
 Global Mold Release Agents Market | 2026-2036
Global Mold Release Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mold Release Agents Market Foresight
Recurring technical service contracts for mold-release formulation optimization is shifting how suppliers capture lifetime value from automotive and aerospace accounts. BASF SE leverages its polymer science depth to anchor long-term supply relationships with tier-one injection molders across Europe. Dow Inc. competes through backward integration into silicone feedstocks, giving it captive supply of the organosilicon building blocks that dominate high-temperature release applications. Shin-Etsu Chemical Co. Ltd. dominates fluorinated release agent niches where extreme chemical resistance commands premium positioning.
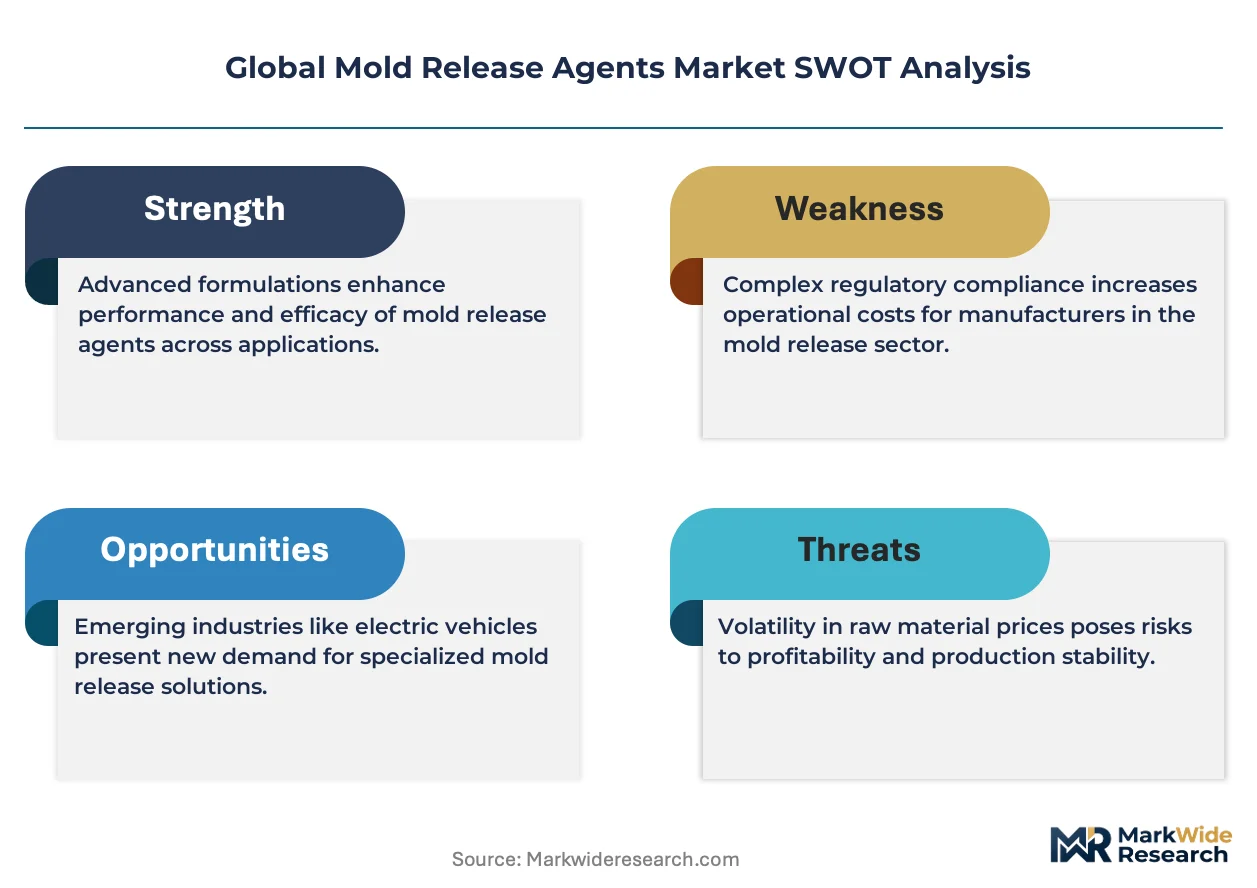
Mold release agents are functional surface treatments applied to mold cavities to prevent adhesion between the mold surface and the finished part, typically comprising carrier fluids, active release polymers such as polydimethylsiloxane or polytetrafluoroethylene, and performance additives that control wetting and cure compatibility. These formulations reduce cycle times, improve surface finish quality, and extend mold life in repeated-use manufacturing environments. Water-based formulations are gaining share from solvent-based alternatives as plant-level VOC compliance costs reshape procurement criteria across metal casting and plastic molding applications. In the end-use dimension, automotive OEMs represent the deepest margin pool due to specification lock-in and validation timelines, while composite fabrication for aerospace manufacturers is registering the fastest application growth as thermoset production rates accelerate.
EPA oversight of hazardous air pollutants and REACH registration requirements for silicone and fluoropolymer chemistries are elevating formulation disclosure burdens and reshaping supplier qualification protocols in the United States and Europe. China's MEE enforcement of GB standards for industrial emissions is pushing domestic foundries toward compliant water-based systems, creating specification convergence across major manufacturing jurisdictions. Stakeholders must monitor regulatory divergence between perfluorinated substance restrictions in Europe and slower-phase timelines elsewhere, as this gap will determine where next-generation bio-based and hybrid release chemistries achieve commercial scale first.
Market Dynamics
Water-based release formulations are compressing solvent-based alternatives as EPA and REACH enforcement elevates plant-level compliance costs across precision molding operations worldwide.
Growth Catalysts
- REACH registration mandates:European chemical disclosure requirements are locking qualified suppliers into long-term automotive OEM supply relationships through validation timelines.
- Composite fabrication:Thermoset production acceleration in aerospace manufacturing is expanding high-temperature release agent consumption.
- China:MEE enforcement of GB emissions standards is pushing domestic foundries toward compliant water-based systems, creating specification convergence.
Market Restraints
- Silicone feedstock concentration:Organosilicon building block supply clusters in East Asia create input cost volatility for high-temperature formulations.
- Perfluorinated substance restrictions:Europe's F-Gas Regulation and evolving PFAS limits create regulatory friction against fluorinated release chemistries.
- Bio-based performance gap:Plant-derived alternatives face technical limitations in extreme chemical resistance applications where PTFE dominates.
Strategic Opportunities
- India:Underpenetrated automotive molding capacity offers white space for water-based formulation suppliers as domestic OEMs scale injection operations.
- Technical service contracts:Recurring mold-release optimization agreements are capturing lifetime value from tier-one accounts.
- Hybrid chemistries:Convergence of silicone durability with bio-based carriers responds to dual sustainability-performance specifications.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in cure-compatible additive design limits R&D throughput at mid-cap suppliers.
- OEM validation timelines:Automotive specification lock-in requires 18-36 month certification cycles before volume procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mold Release Agents Market |
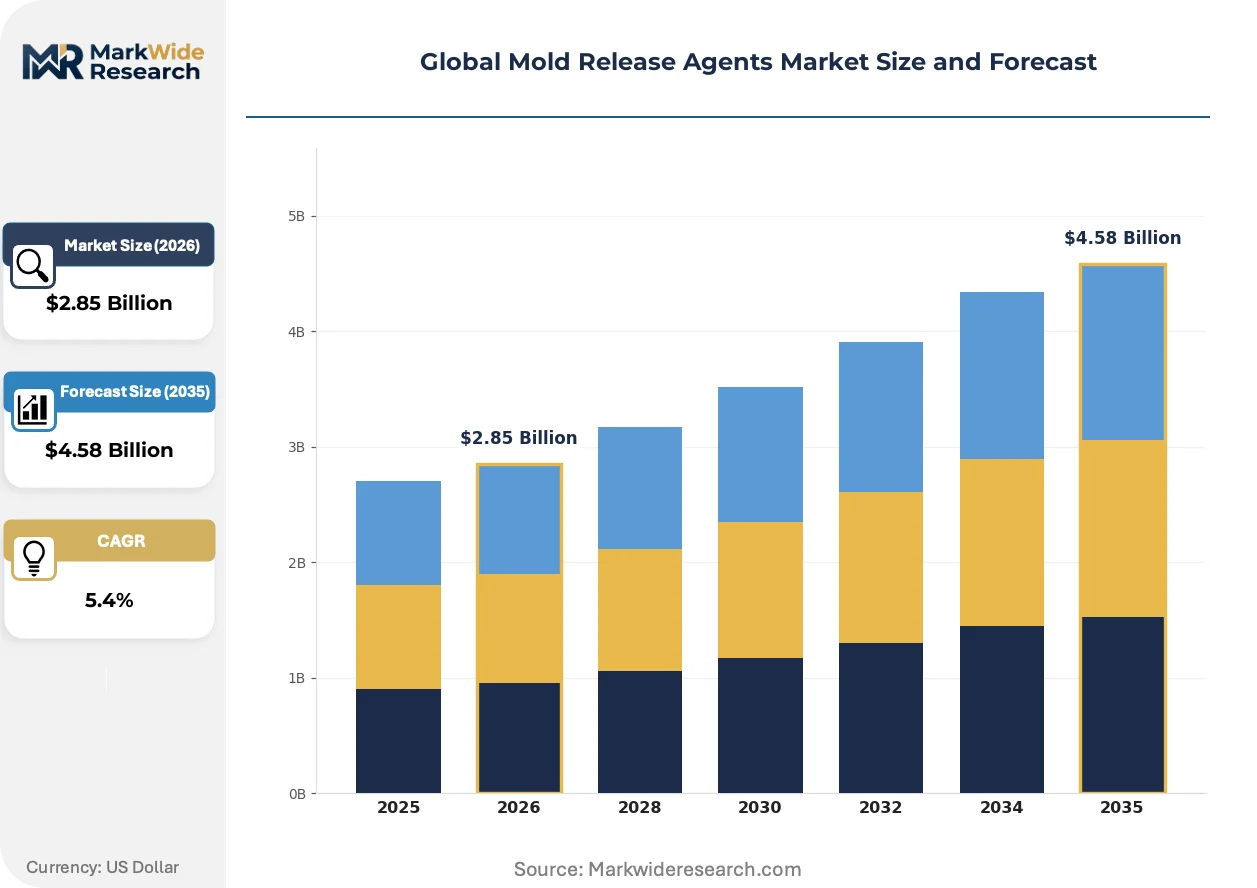
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.58 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Natural, Semi-Synthetic, Water-Based, Solvent-Based Application: Metal Casting, Plastic Molding, Rubber Processing, Composite Fabrication, Concrete Molding End Use Industry: Automotive OEMs, Electrical & Electronics, Aerospace Manufacturers, Marine Builders, Consumer Goods Producers Form: Liquid, Paste, Powder, Spray, Aerosol |
| Companies Covered | Dow Inc., BASF SE, Henkel AG & Co. KGaA, Chem-Trend L.P., Wacker Chemie AG, Shin-Etsu Chemical Co. Ltd., Daikin Industries Ltd., LANXESS Group, Michelman Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mold Release Agents Market Shifts & Advancements
Active unification of release-performance-sustainability specifications is compressing formulation development cycles and reshaping supplier qualification protocols across molding value chains.
Hybrid water-silicone emulsion technology is unifying VOC compliance with high-temperature performance in a single carrier system. Automotive OEMs in Germany and the United States are adopting these formulations at accelerating pace as dual-cure compatibility becomes standard. This convergence is unifying previously separate solvent-based and water-based procurement categories into single-source contracts.
REACH registration requirements for silicone and fluoropolymer chemistries are elevating formulation disclosure burdens across European supply chains. Industrial consequence includes supplier consolidation as smaller compounders exit due to registration cost thresholds. Aerospace composite fabricators are responding by pre-qualifying alternative hybrid chemistries ahead of potential PFAS restrictions.
After-sales service unbundling is separating mold-release optimization from base chemical supply in procurement negotiations. Tier-one injection molders in China and Germany now contract technical service separately, compressing margins on commodity formulations. This pattern is most visible in automotive supply chains where specification engineers retain direct supplier relationships independent of purchasing departments.
Global Mold Release Agents Market Segmentation
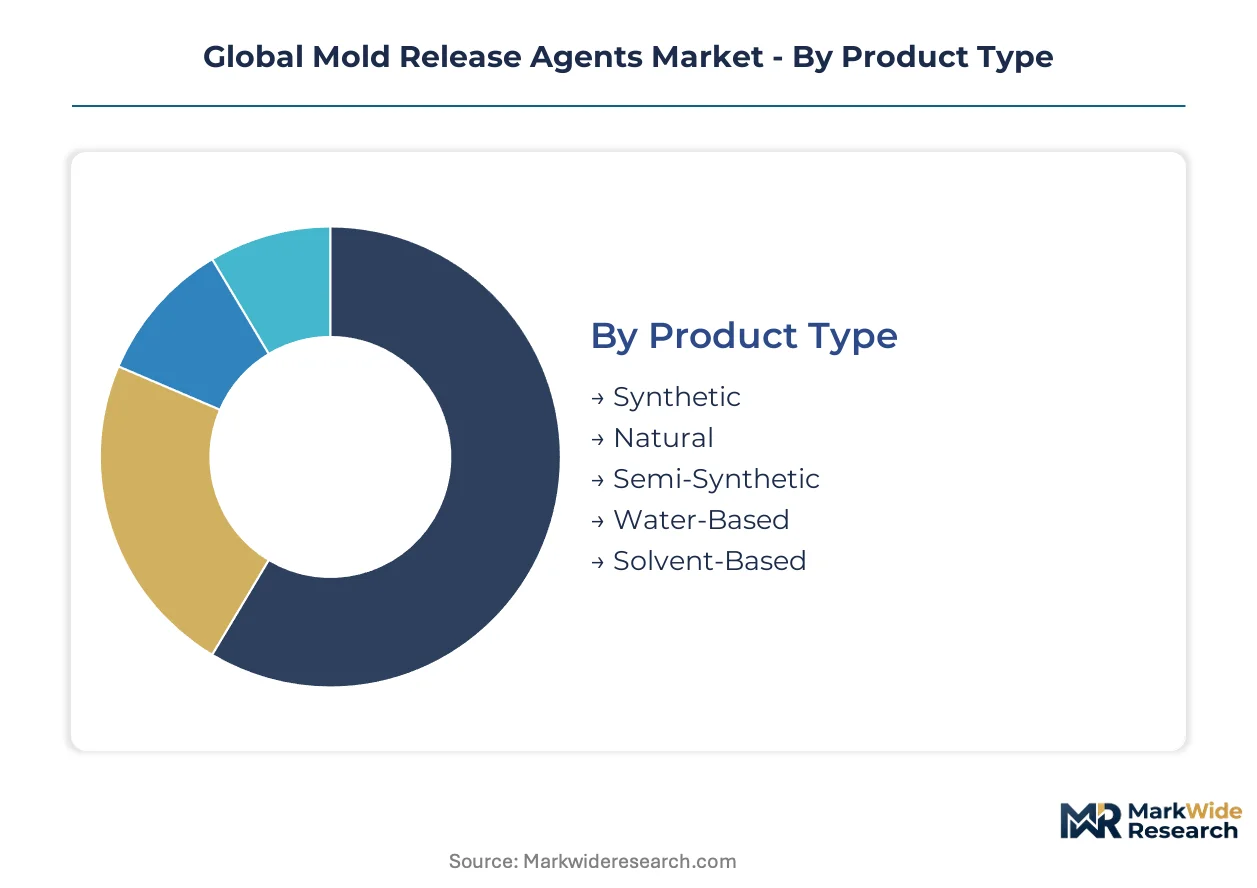
Mold release agents fragment across formulation chemistry, application environment, and delivery format. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier positioning across automotive, aerospace, and industrial molding value chains.
Product Type:
Water-based formulations command volume leadership while fluorinated synthetics capture premium positioning in extreme-temperature niches.
- Water-Based:Emulsion systems using silicone or vegetable oil actives suspended in aqueous carriers dominate procurement in Germany, China, and the United States as EPA, REACH, and MEE enforcement elevates plant-level VOC compliance costs. Tier-one automotive OEMs in Stuttgart and Detroit specify these formulations for injection molding operations where dual-cure compatibility has become standard.
- Synthetic:Petrochemical-derived formulations based on polydimethylsiloxane, mineral oils, and fluoropolymers retain entrenched positions in metal casting and high-temperature thermoset applications where thermal stability exceeds 300°C. Aerospace composite fabricators in Toulouse and Hamburg specify fluorinated synthetics for carbon fiber epoxy pre-preg molding cycles.
- Natural:Vegetable oil and animal fat derivatives serve specialty food-contact and cosmetic packaging molds where synthetic residue restrictions apply.
- Semi-Synthetic:Blended formulations balance cost and performance in mid-tier rubber processing and general industrial molding.
- Solvent-Based:Hydrocarbon-carrier systems retreat to legacy foundry applications and regions with delayed VOC enforcement timelines.
Today's leader: Water-Based. Tomorrow's challenger: Semi-Synthetic hybrid formulations bridging performance and sustainability specifications.
Application:
Process temperature and cycle frequency determine formulation selection across five distinct molding disciplines.
- Plastic Molding:Injection and blow molding operations in automotive supply chains consume the deepest volume pools, with specification lock-in through 18-36 month OEM validation cycles creating durable supplier relationships. Water-based silicones dominate thermoplastic applications while thermoset composites in aerospace drive fluorinated consumption.
- Composite Fabrication:Epoxy and phenolic resin molding for aircraft structures and wind turbine blades registers the steepest expansion trajectory as production rates accelerate at Boeing, Airbus, and their tier suppliers. High-temperature release agents must withstand cure cycles exceeding 180°C without transfer to finished surfaces.
- Metal Casting:Die casting and investment foundries in China's Pearl River Delta and Germany's Baden-Württemberg region specify graphite-based and ceramic-release formulations for aluminum and magnesium alloys.
- Rubber Processing:Tire manufacturing and industrial rubber molding in Southeast Asia and Eastern Europe consume standard silicone emulsions in high-volume extrusion and compression applications.
- Concrete Molding:Construction precast and architectural concrete formwork use biodegradable vegetable oil formulations where environmental runoff restrictions apply.
Plastic Molding anchors current procurement volumes. Composite Fabrication is climbing the fastest as aerospace production rates normalize post-supply-chain disruption.
End Use Industry:
Automotive OEMs concentrate the highest formulation specification density and longest validation timelines.
- Automotive OEMs:Interior, exterior, and powertrain component molding across Volkswagen, Toyota, and General Motors supply chains demands cure-compatible release agents validated for specific resin systems. Specification engineers at tier-one injection molders in Wolfsburg, Nagoya, and Warren retain direct supplier relationships independent of purchasing departments.
- Aerospace Manufacturers:Boeing, Airbus, and their composite tier suppliers pre-qualify alternative hybrid chemistries ahead of potential European PFAS restrictions, creating early-adopter demand for next-generation formulations.
- Electrical & Electronics:Connector housing and enclosure molding for consumer electronics and industrial equipment consumes standard water-based silicones in high-volume Asian manufacturing clusters.
- Marine Builders:Fiberglass hull and deck molding for recreational and commercial vessels uses wax-based and PVA release systems in seasonal production environments.
- Consumer Goods Producers:Food packaging, cosmetic containers, and household product molding prioritize natural and semi-synthetic formulations where brand sustainability commitments influence procurement.
Automotive OEMs define today's premium tier. Aerospace Manufacturers are gaining share fastest as thermoset composite production scales.
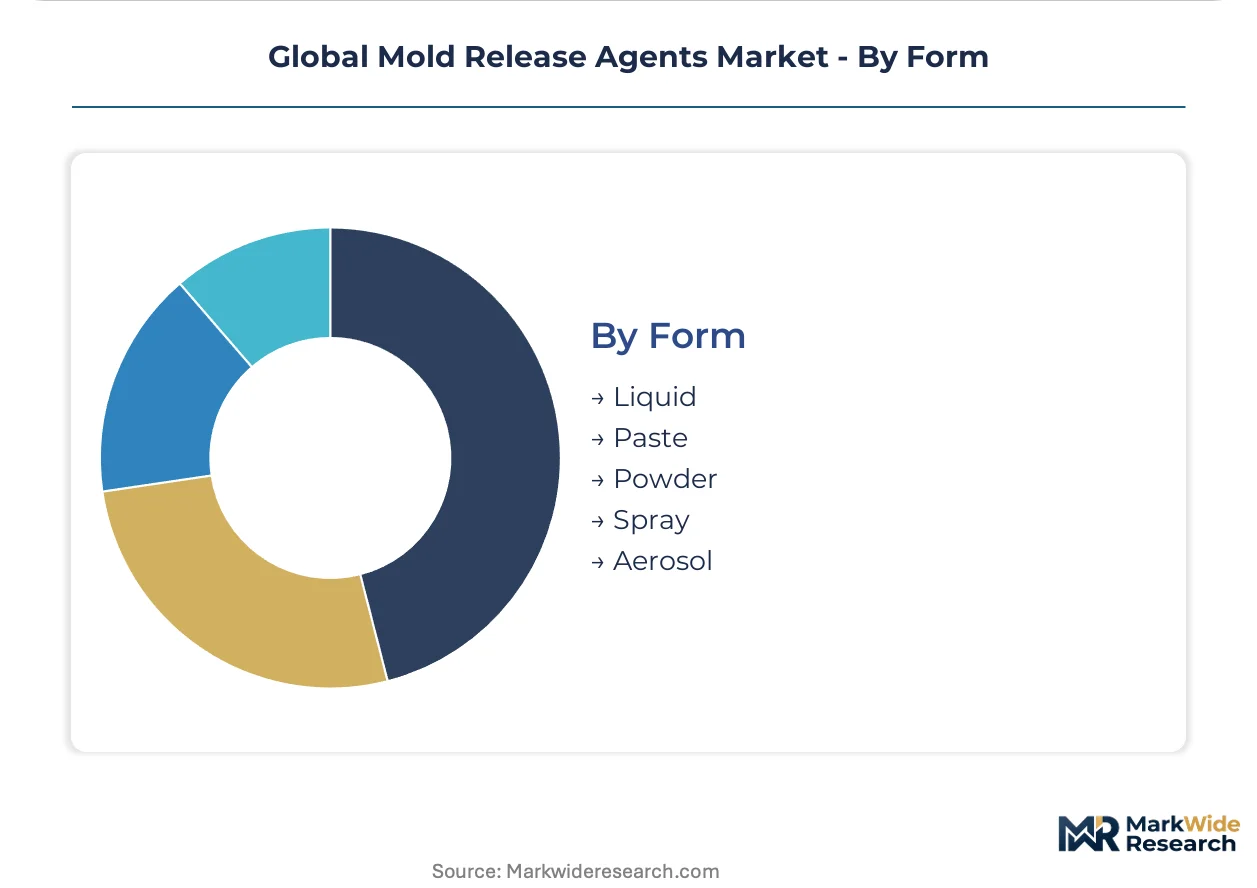
Form:
Delivery format selection tracks automation level, mold complexity, and worker exposure protocols.
- Liquid:Bulk concentrate and ready-to-use formulations dominate automated spray systems in high-volume automotive and electronics molding where robotic application ensures consistent film thickness.
- Spray:Pre-pressurized and pump-spray systems serve manual application in prototype, repair, and small-batch production environments across job shops and toolrooms.
- Paste:High-viscosity brush-applied formulations target complex mold geometries and vertical surfaces where liquid runoff would compromise coverage uniformity.
- Powder:Dry film release agents serve specialty rubber molding and certain metal casting applications where liquid carriers would contaminate processes.
- Aerosol:Portable convenience format retains niche demand in maintenance, repair, and field service applications despite VOC regulatory pressure.
Liquid concentrates lead industrial procurement. Spray systems are expanding most quickly as manual application protocols modernize in emerging manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision molding specification authority while China absorbs the deepest volume pools as domestic foundries modernize under tightening emissions protocols.
United States
Automotive OEMs in Detroit and Warren drive water-based silicone adoption for injection molding operations. EPA enforcement of hazardous air pollutant limits under the Clean Air Act elevates plant-level compliance costs. Tier-one suppliers across Michigan and Ohio now specify dual-cure compatible formulations validated through 18-month certification cycles.
Germany
REACH registration mandates for silicone and fluoropolymer chemistries lock qualified suppliers into durable automotive supply relationships. ECHA disclosure requirements favor compounders with polymer science depth and regulatory affairs capacity. Stuttgart and Wolfsburg anchor specification engineering for Volkswagen and Mercedes-Benz supply chains where mold-release optimization contracts separate from base chemical procurement.
China
Domestic foundries in the Pearl River Delta and Yangtze River Delta convert to water-based systems under MEE enforcement of GB industrial emissions standards. MIIT industrial upgrading programs accelerate specification convergence with European and American procurement criteria. Shenzhen and Suzhou molders now demand technical service contracts unbundled from chemical supply.
Japan
Organosilicon building block production clusters in Nagoya and Osaka create captive feedstock advantages for high-temperature formulation suppliers. METI guidance on sustainable manufacturing pushes hybrid chemistry development. Nagoya-based composite fabricators supply Boeing and Airbus tier networks with pre-qualified alternatives to fluorinated releases.
India
Underpenetrated automotive molding capacity in Maharashtra and Tamil Nadu offers white space for water-based formulation suppliers. BIS standards alignment with REACH frameworks simplifies import qualification for European compounders. Chennai and Pune injection molders scale operations as domestic OEMs expand component sourcing.
Global Mold Release Agents Market Competitive Landscape
Top-tier vendors anchor polymer science and regulatory compliance capabilities, while mid-cap specialists occupy formulation customization niches. The vendor base stratifies across three archetypes: diversified chemical conglomerates with backward integration into silicone feedstocks, fluoropolymer specialists commanding premium positioning in aerospace applications, and regional compounders serving foundry and rubber processing markets. Consolidation pressure intensifies as REACH registration costs and OEM validation timelines favor scaled players with dedicated regulatory affairs functions.
Among diversified chemical conglomerates, Dow Inc. and BASF SE exemplify the integrated archetype through captive supply of organosilicon building blocks and polymer science depth respectively. Shin-Etsu Chemical Co. Ltd. occupies a specialist position in fluorinated release agent niches where extreme chemical resistance commands premium pricing. These three anchors represent distinct competitive vectors: feedstock integration, formulation breadth, and high-performance specialization.
| Leading Market Players |
|---|
| Dow Inc. |
| BASF SE |
| Henkel AG & Co. KGaA |
| Chem-Trend L.P. |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co. Ltd. |
| Daikin Industries Ltd. |
| LANXESS Group |
| Michelman Inc. |
| Others |
Supply & Pricing Matrix
Silicone feedstock price indices in East Asia cascade through formulation tiers, compressing margins on commodity water-based emulsions while fluorinated synthetics retain pricing power through aerospace qualification lock-in.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard water-based silicone emulsions. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered European formulations from domestic Chinese grades and unregistered regional alternatives. Cost compression in the standard tier is intensifying because technical service unbundling allows tier-one molders to source base chemicals separately from optimization contracts. Automotive OEM procurement teams show the highest price sensitivity, while aerospace composite fabricators accept premium positioning for pre-qualified PFAS alternatives.
Supply Chain Analysis
REACH registration and EPA compliance certification gates upstream supply access, favoring compounders with dedicated regulatory affairs functions. Organosilicon building block production clusters in Japan, China, and Germany anchor global formulation supply. Raw material dependencies include methyl chloride, silicon metal, and fluoropolymer resins. Single-source vulnerability concentrates in high-purity silicone feedstocks from Nagoya-Osaka industrial corridors. Distribution runs through authorized distributor networks serving tier-one injection molders with validated logistics protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH registration deadlines and EPA enforcement timelines create durable demand for compliant water-based formulations.
For Market Incumbents: Deploy technical service contract expansion to capture lifetime value from automotive accounts before commodity formulation margins erode further. Backward integration into silicone feedstocks defends cost position against East Asian supply volatility. Consolidation of mid-cap compounders lacking registration capacity removes price-competitive threats in European supply chains. For New Entrants and Emerging Players: Regional distributors in India's Maharashtra and Tamil Nadu automotive corridors offer the most penetrable channel for water-based formulation market entry. BIS standards alignment simplifies import qualification versus full REACH registration burden. White space exists in hybrid chemistry segments where European PFAS restrictions accelerate specification turnover ahead of domestic capacity buildout. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap compounders possessing REACH registration assets and established automotive OEM relationships. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than formulation innovation alone. Watch for ECHA guidance on perfluorinated substance restrictions as the inflection signal determining fluorinated chemistry replacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Feedstocks | Dow Inc.'s captive organosilicon supply anchors cost position in high-temperature release formulations. |
| REACH Registration Completion | ECHA compliance locks qualified suppliers into durable automotive OEM supply relationships through validation timelines. |
| Hybrid Chemistry Development | Convergence of silicone durability with bio-based carriers responds to dual sustainability-performance specifications in Germany. |
| Technical Service Contract Expansion | BASF SE leverages polymer science depth to anchor recurring mold-release optimization agreements separate from chemical supply. |
| Geographic Expansion into India | Underpenetrated automotive molding capacity in Pune and Chennai offers white space for water-based formulation suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at injection molding facilities, procurement leads at tier-one automotive suppliers, technical R&D directors at formulation compounders, and distribution channel partners across Germany, China, and the United States with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA enforcement records. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across formulation chemistry, application environment, and delivery format dimensions.
Historical reference periods anchored the forecast window through the analysis window, with projections built across product type, application, end-use industry, and regional production hub segments. CAGRs derived from segment-level growth rate synthesis incorporating REACH registration timelines, MEE enforcement trajectories in China, and aerospace composite production rate normalization. Industry-specific inputs included silicone feedstock price volatility indices and OEM validation cycle duration benchmarks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA PFAS restriction guidance and MEE emissions standard enforcement intensity. Forecasts reflect assumptions about regulatory convergence across major manufacturing jurisdictions. A model refresh is warranted upon material change in European fluorinated substance restriction timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Sodium Potassium Tartrate Market
Additives
Global Calcium Formate Market
Additives
Global Acidulants Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
Sodium Caprylate Market
Additives
Sodium Stearyl Fumarate Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
Lubricant Additives Market
Additives
Amino Acids Premixes Market
Additives
Global Feed Acidulants Market
Additives
Global Coalescing Agent Market
Additives
Ethoxyquin Market
Additives
Tamarind Gum Derivatives Market
Additives
Plastic Fillers Market
Additives
India Feed Additives Market