
 Asia-Pacific Adhesives and Sealants Market | 2026-2036
Asia-Pacific Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Adhesives and Sealants Market Analysis
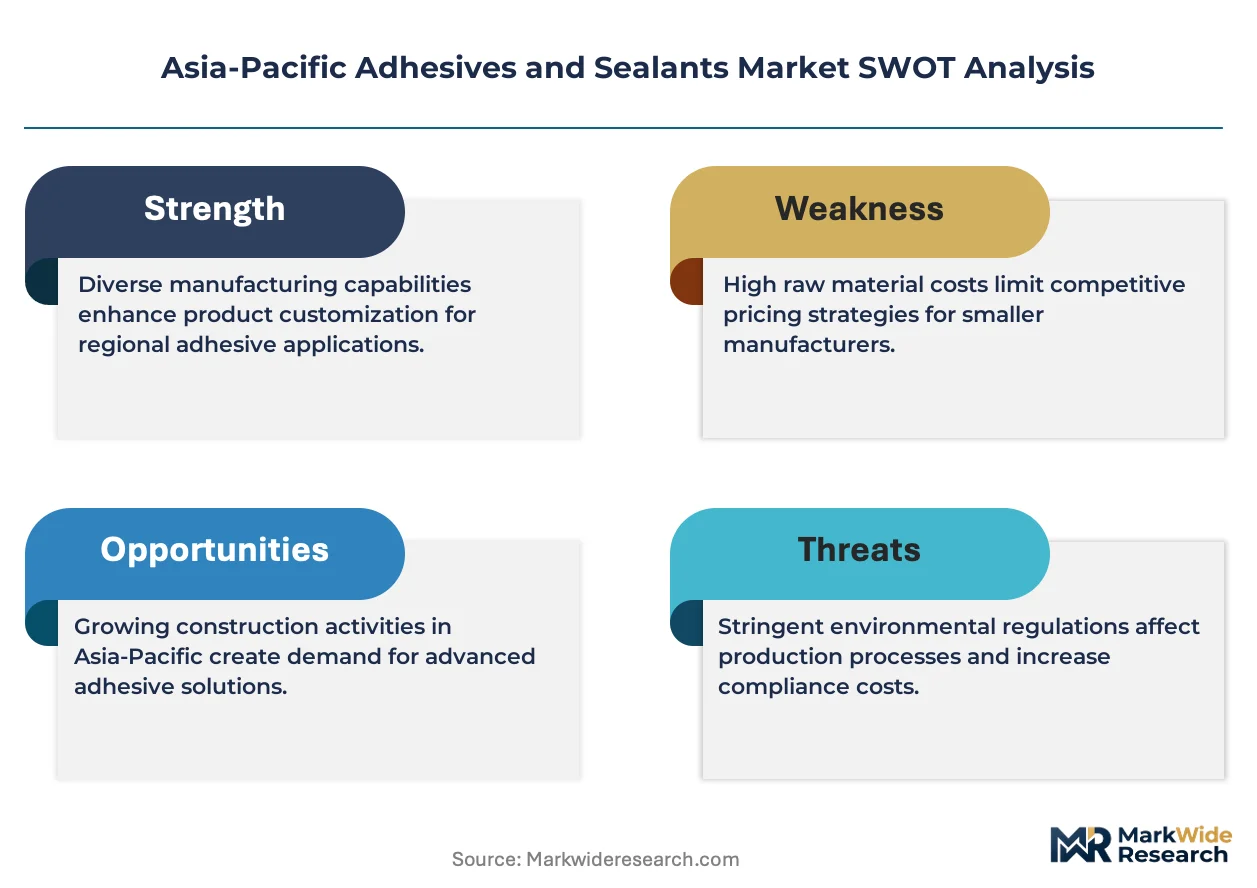
The gap between premium reactive formulations and commodity hot-melt grades is broadening across the Asia-Pacific adhesives and sealants market. Arkema Group leverages its specialty resin portfolio to command positions in electronics-grade acrylic systems. Henkel AG & Co. KGaA anchors construction adhesive supply through localized manufacturing networks in Southeast Asia. Pidilite Industries Limited dominates India's consumer and industrial segments with deep distribution into tier-two cities.
Adhesives and sealants are bonding substances formulated from polymers, tackifiers, and curing agents that create structural or flexible joints between substrates through mechanical interlocking, chemical crosslinking, or surface wetting; silicone variants tolerate temperature swings from minus sixty to plus two hundred degrees Celsius while maintaining elastomeric recovery. Water-based technology leads volume shipments across packaging and furniture applications due to lower volatile organic compound profiles and compliance pressure from environmental authorities. Reactive technology, encompassing epoxy and polyurethane chemistries, captures disproportionate margin pools in automotive lightweighting and electronics miniaturization where cure speed and bond strength determine specification.
China's Ministry of Ecology and Environment enforces GB standards limiting solvent content in industrial coatings and adhesives, redirecting formulation investment toward water-based and hot-melt platforms. India's BIS certification mandates for construction chemicals and automotive components create entry barriers for uncertified imports while privileging domestic manufacturers with testing laboratory relationships. Japan's METI promotes next-generation material standards that reward low-carbon adhesive production processes. Stakeholders must track how evolving VOC thresholds in China, India, and Japan reshape raw material sourcing and capital allocation across the technology matrix.
Market Dynamics
China's GB standards for volatile organic compound emissions are compressing formulation margins while redirecting capital toward water-based and hot-melt platforms across the Asia-Pacific adhesives and sealants market.
Growth Catalysts
- Infrastructure Investment:Southeast Asian governments are channeling funds into transportation and urban development, absorbing structural adhesives for concrete bonding and facade assembly at scale.
- Automotive Lightweighting:Reactive polyurethane and epoxy systems are capturing specification in electric vehicle battery pack assembly across India's western industrial corridor.
- Packaging Sustainability Mandates:Japan's METI low-carbon material standards are accelerating substitution of solvent-based laminating adhesives with bio-based hot-melt alternatives in food and beverage flexible packaging.
Market Restraints
- Petrochemical Feedstock Volatility:Crude-derived polyols and tackifier resins expose formulators to margin compression when naphtha and propylene prices spike.
- Specialty Additive Concentration:Curing agent supply for epoxy systems clusters with Chinese chemical manufacturers, creating single-source vulnerability for regional compounders.
- Cure Speed Limitations:Water-based acrylics remain incompatible with high-speed automotive assembly lines requiring sub-minute fixture times, restricting penetration in OEM body-in-white applications.
Strategic Opportunities
- Vietnam Manufacturing Expansion:Electronics contract manufacturers are relocating final assembly from coastal China, creating demand for ultra-pure silicone and acrylic systems in smartphone and semiconductor packaging.
- Construction Chemical Certification:India's BIS mandatory certification for tile adhesives and waterproofing membranes privileges domestic manufacturers with established testing laboratory relationships.
- UV-Curable Convergence:Hybrid formulations combining UV-initiated cure with moisture-crosslinking are opening specification in medical device assembly where rapid processing meets biocompatibility requirements.
Industry Challenges
- Formulation Chemistry Expertise Gap:Regional compounders struggle to recruit polymer scientists capable of balancing VOC compliance with adhesion performance in water-based automotive grades.
- Multi-Standard Certification Timelines:Exporters to China, India, and Japan must navigate concurrent GB standard, BIS, and JIS testing protocols, extending product launch cycles by twelve to eighteen months.
- Legacy Equipment Retrofit Costs:Converting solvent-based coating lines to hot-melt or water-based application requires capital outlay for drying oven modification and viscosity control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Adhesives and Sealants Market |
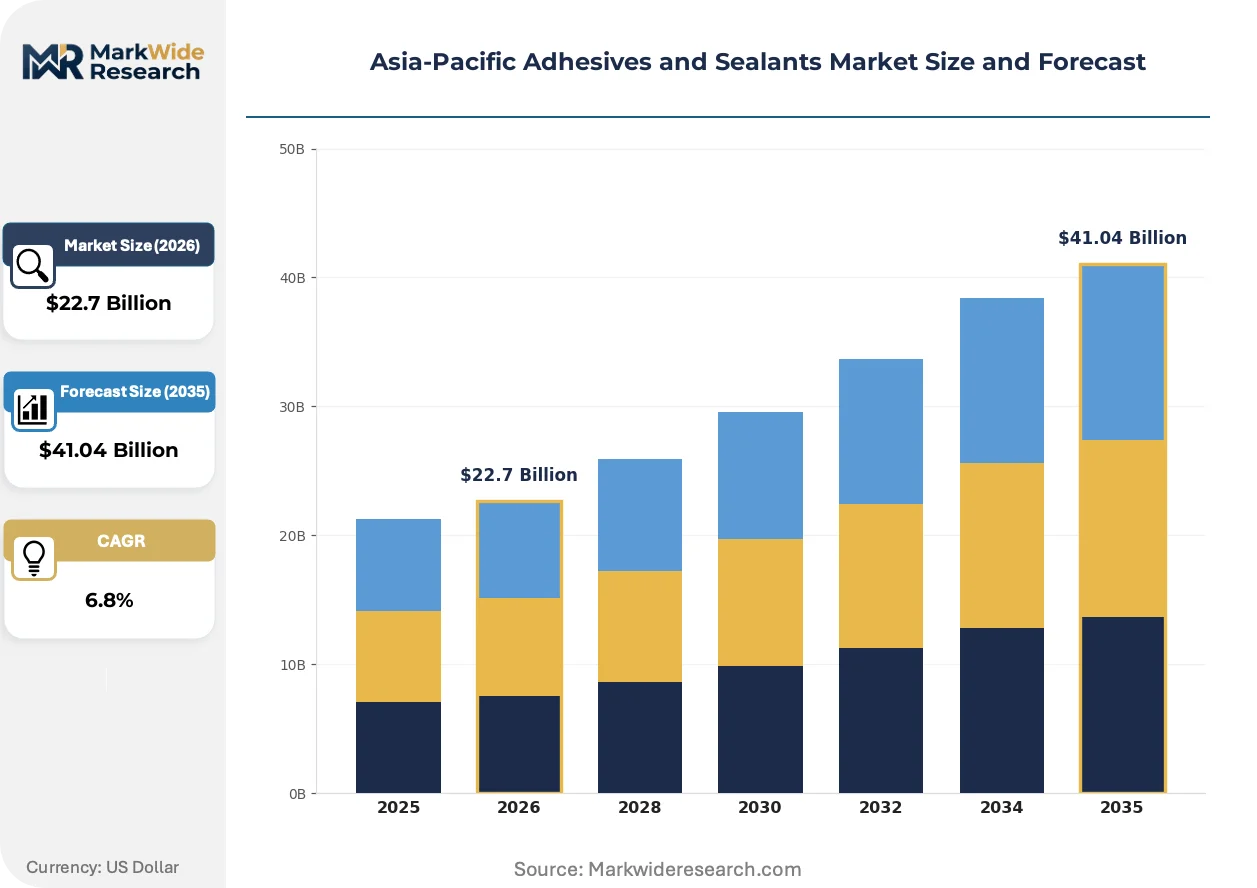
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $41.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Silicone End User: Automotive, Construction, Electronics, Packaging Form: Liquid, Paste, Film, Powder Technology: Water-based, Solvent-based, Hot Melt, Reactive |
| Companies Covered | Arkema Group, Pidilite Industries Limited, 3M Company, Kangda New Materials, Huitian Adhesive, Henkel AG & Co. KGaA, H.B. Fuller Company, ThreeBond Holdings, Sika AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Adhesives and Sealants Market Emerging Trajectories
Formulation chemistry and application technology are converging to resolve the tension between regulatory compliance and performance specifications across Asia-Pacific industrial adhesives.
Reactive hot-melt polyurethane technology is consolidating position in automotive interior lamination and textile bonding applications. Tier-one suppliers in Thailand and Indonesia are adopting these systems to eliminate solvent emissions while maintaining the immediate handling strength required for just-in-time seat assembly. The technology is consolidating market share previously held by two-component solventborne polyurethanes in premium vehicle programs.
China's Ministry of Ecology and Environment enforcement of updated GB standards is eliminating solvent-based formulation options for packaging converters in the Yangtze River Delta industrial belt. Formulators are redirecting R&D investment toward water-based acrylic and hot-melt ethylene vinyl acetate platforms to maintain access to this demand cluster. The policy shift is most acute in flexible food packaging, where residual solvent limits have tightened by forty percent.
Specification authority is migrating from converters to brand-owner sustainability procurement teams in consumer packaged goods. Direct engagement between adhesive suppliers and multinational food and personal care companies is displacing traditional distributor-mediated relationships in South Korea and Australia. This pattern is most visible in premium cosmetics and organic food segments where carbon footprint disclosure requirements penetrate supply chain contracting terms.
Asia-Pacific Adhesives and Sealants Market Segmentation
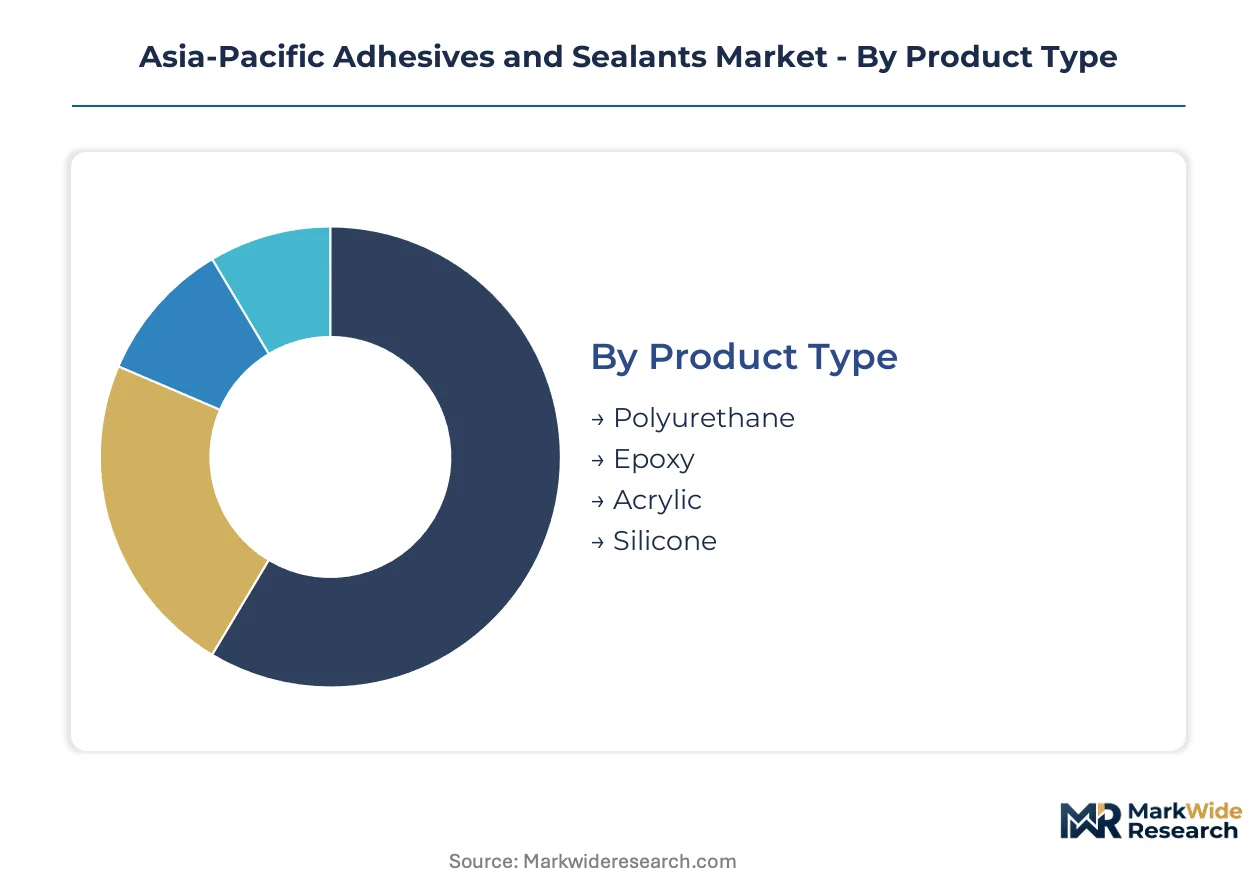
Formulation chemistry, application method, and regulatory compliance intersect across multiple segmentation dimensions in the Asia-Pacific adhesives and sealants market. Understanding how product types map to certification requirements and technology platforms reveals where margin pools concentrate and where capital is redirecting.
Product Type:
China's GB standards and India's BIS certification create divergent compliance burdens across chemistry platforms, with reactive systems facing stricter VOC thresholds than commodity grades.
- Polyurethane:Two-component systems cure through isocyanate-hydroxyl reactions to form elastomeric bonds with excellent impact resistance. Automotive OEMs in Thailand and Indonesia specify reactive polyurethane for interior lamination as solvent-based alternatives face GB standard phase-out.
- Epoxy:Thermosetting resins crosslink through amine or anhydride curing agents to achieve structural load-bearing capacity. Electronics assemblers in Vietnam absorb high-purity grades for semiconductor encapsulation, though curing agent supply concentration with Chinese manufacturers creates vulnerability.
- Acrylic:Water-based emulsions dominate packaging and furniture bonding across India's western industrial corridor, where BIS certification for construction applications privileges domestic formulators with testing relationships.
- Silicone:Elastomeric systems tolerate temperature swings from minus sixty to plus two hundred degrees Celsius while maintaining recovery properties. Medical device manufacturers in Japan specify platinum-cured grades for biocompatibility compliance under METI-promoted standards.
Leading the category by volume: Acrylic. Expanding most quickly: Polyurethane.
End User:
Application intensity varies sharply by sector, with automotive and electronics commanding premium pricing while construction and packaging absorb commodity volumes at scale.
- Automotive:Electric vehicle battery pack assembly in Gujarat and Maharashtra drives specification of reactive systems with sub-minute fixture times. Lightweighting mandates favor structural adhesives over mechanical fasteners in body-in-white applications.
- Construction:Infrastructure investment across Southeast Asia absorbs tile adhesives, waterproofing membranes, and facade bonding systems. India's BIS mandatory certification creates entry barriers for uncertified imports.
- Electronics:Smartphone and semiconductor packaging demand ultra-pure silicone and acrylic systems with ionic contamination controls below fifty parts per billion.
- Packaging:Flexible food and beverage laminating adhesives face China's GB standard solvent content limits, redirecting converters toward water-based acrylic and hot-melt ethylene vinyl acetate platforms.
Dominating volume absorption: Construction. Steepest expansion trajectory: Electronics.
Form:
Physical state determines application equipment requirements and shelf-life logistics, with liquid and paste formats commanding share in automated assembly while film and powder serve specialized niches.
- Liquid:Pumpable systems suit high-speed dispensing equipment in automotive and electronics assembly. Low-viscosity grades penetrate substrate pores for structural bonding in concrete repair applications.
- Paste:Thixotropic formulations resist sag on vertical surfaces during cure, finding specification in tile adhesive and facade assembly across Southeast Asian construction sites.
- Film:Pre-cast adhesive layers enable precise thickness control in aerospace composite lamination and electronics heat sink attachment.
- Powder:Thermoplastic formats melt and flow under heat and pressure, serving textile bonding and woodworking applications where solvent-free processing is mandatory.
Highest shipment volumes: Liquid. Gaining share fastest: Paste.
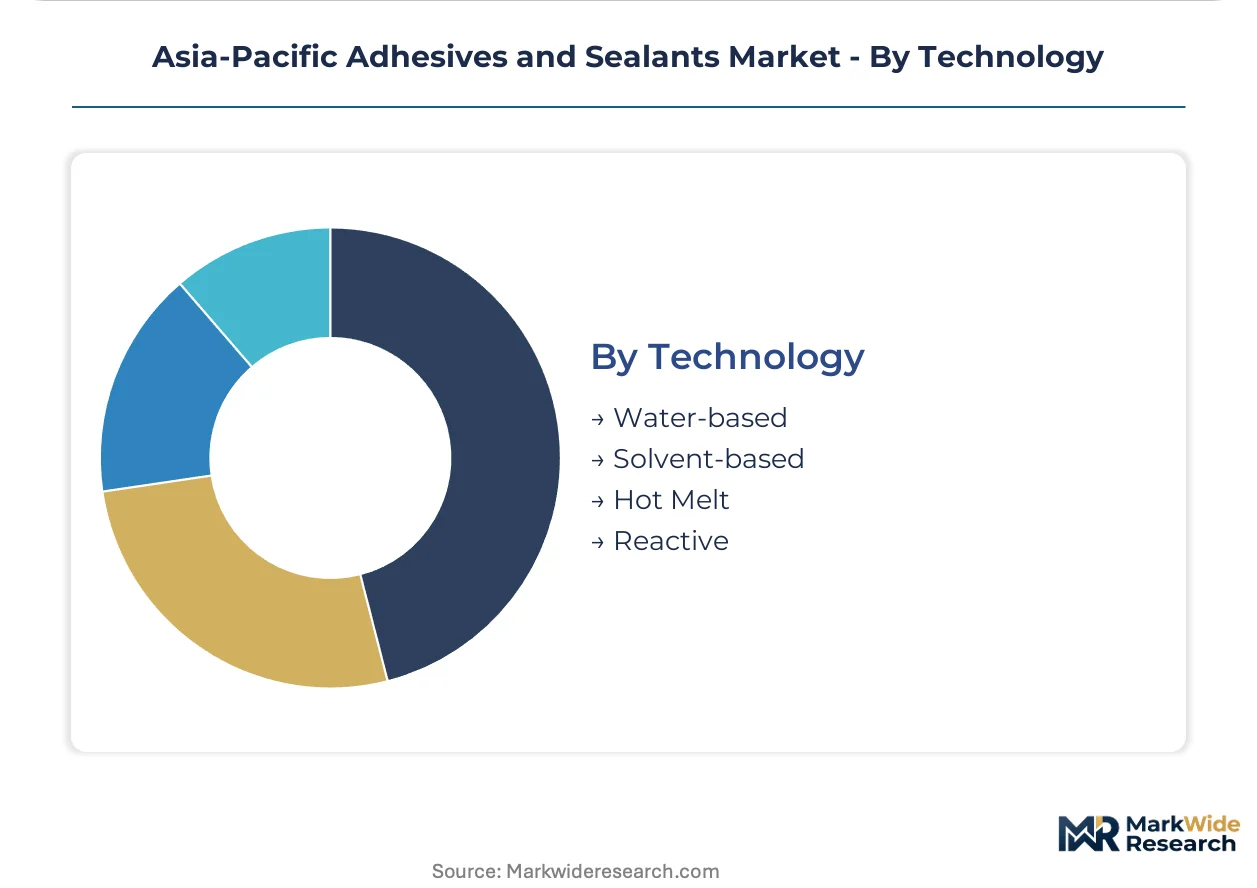
Technology:
Environmental compliance pressure from China's MEE and Japan's METI is compressing solvent-based platforms while elevating water-based and reactive alternatives.
- Water-based:Acrylic and polyurethane dispersions achieve compliance with China's updated GB standards for packaging converters in the Yangtze River Delta. Cure speed limitations restrict penetration in high-speed automotive body-in-white lines.
- Solvent-based:Rapid drying and aggressive substrate wetting retain niche specification in specialty coatings, though China's GB standard enforcement is eliminating options for flexible food packaging.
- Hot Melt:Thermoplastic formulations eliminate cure time entirely, serving just-in-time seat assembly in Thai and Indonesian automotive plants. Bio-based alternatives gain traction under Japan's METI low-carbon material standards.
- Reactive:Epoxy and polyurethane chemistries capture disproportionate margin pools where bond strength and cure speed determine specification. Hybrid UV-moisture systems open medical device applications.
Commanding volume leadership: Water-based. Climbing the fastest: Reactive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta industrial belt anchors Asia-Pacific adhesives demand, where Shanghai-based packaging converters absorb water-based acrylic systems under tightening environmental enforcement. India's western industrial corridor around Gujarat and Maharashtra concentrates automotive OEM activity. Southeast Asian construction markets absorb structural grades for infrastructure buildout.
China
Packaging converters in the Yangtze River Delta absorb water-based acrylic and hot-melt ethylene vinyl acetate platforms as the Ministry of Ecology and Environment enforces updated GB standards limiting solvent content. Shanghai and Suzhou industrial zones redirect formulation investment away from solvent-based laminating adhesives. Electronics assemblers in Shenzhen specify ultra-pure silicone systems for semiconductor packaging.
India
Automotive OEMs cluster around Gujarat and Maharashtra, driving specification of reactive polyurethane systems for electric vehicle battery pack assembly. The Bureau of Indian Standards mandates certification for construction chemicals including tile adhesives and waterproofing membranes. Domestic formulators with testing laboratory relationships in Mumbai and Ahmedabad capture preferential market access.
Japan
Medical device manufacturers specify platinum-cured silicone grades for biocompatibility compliance as METI promotes next-generation material standards rewarding low-carbon production processes. Osaka and Nagoya industrial zones concentrate electronics-grade adhesive demand. Food and beverage brand owners directly engage adhesive suppliers for carbon footprint disclosure compliance.
Thailand
Tier-one automotive suppliers adopt reactive hot-melt polyurethane technology for just-in-time seat assembly, eliminating solvent emissions while maintaining handling strength. Bangkok and Eastern Economic Corridor manufacturing zones absorb construction adhesives for infrastructure development. Japanese and Korean OEMs localize supply chain relationships with regional compounders.
Vietnam
Electronics contract manufacturers relocating final assembly from coastal China create demand for ultra-pure silicone and acrylic systems in smartphone packaging. Ho Chi Minh City and Hanoi industrial zones concentrate foreign direct investment in semiconductor assembly. Formulators establish technical service centers to support ionic contamination controls below fifty parts per billion.
Asia-Pacific Adhesives and Sealants Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the technology certification matrix, with reactive and electronics-grade specialists commanding structural advantages over hot-melt commodity suppliers. The vendor base stratifies into three tiers: multinational chemical conglomerates with integrated resin portfolios, regional specialists with deep distribution networks, and domestic compounders serving price-sensitive construction segments. Dominant competitive moves include backward integration into tackifier resin production and geographic expansion through technical service center establishment.
Among Asia-Pacific-based specialists, Pidilite Industries Limited exemplifies the domestic distribution archetype with penetration into tier-two Indian cities. Arkema Group and Henkel AG & Co. KGaA occupy positions at the premium formulation tier, representing multinational technology leadership across specialty acrylic and construction adhesive segments. These three anchors illustrate how competitive positioning diverges between scale-driven commodity supply and certification-dependent premium specification.
| Leading Market Players |
|---|
| Arkema Group |
| Pidilite Industries Limited |
| 3M Company |
| Kangda New Materials |
| Huitian Adhesive |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| ThreeBond Holdings |
| Sika AG |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap compounders across India and Southeast Asia anchor supply discipline through conservative working capital management, translating into stable contract pricing even when petrochemical feedstocks swing. Their reluctance to expand capacity ahead of confirmed offtake creates periodic tightness in specialty curing agent availability, pushing automotive OEMs toward longer-term volume commitments.
Pricing Analysis
Yield-based pricing anchors premium reactive formulations, where adhesive suppliers capture value proportional to manufacturing throughput gains or defect-rate reduction in customer assembly lines. Three-tier pricing structure across premium, standard, and economy levels separates electronics-grade silicone certified for ionic contamination below fifty parts per billion from commodity hot-melt grades. Price differentiation hinges on BIS certification status in India and GB standard compliance tiers in China. Cost compression in water-based automotive grades is intensifying because formulators absorb R&D overhead to meet cure-speed specifications. Packaging converters in the Yangtze River Delta exhibit highest price sensitivity, while medical device manufacturers in Japan tolerate substantial premiums for biocompatibility-assured platinum-cured silicones.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs in Thailand and Indonesia mandate qualification of at least two curing agent suppliers, mitigating concentration risk with Chinese manufacturers. Geographic supply concentration centers on China for epoxy curing agents and tackifier resins, South Korea for specialty polyols, and Japan for high-purity silicone precursors. Raw material dependencies rest on naphtha-derived polyols, rosin-based tackifiers, and amine functional curing agents. Single-source vulnerability in Chinese curing agent supply creates exposure to export license delays. Distribution runs through authorized technical distributors in tier-one industrial zones, with direct supplier engagement penetrating brand-owner sustainability procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where GB standard enforcement and BIS certification timelines force sub-scale compounders toward exit or acquisition. Margin compression in solvent-based legacy portfolios accelerates the winnowing.
For Market Incumbents: Deepen backward integration into tackifier resin production to insulate margins from rosin and hydrocarbon feedstock volatility. Anchor capacity expansion in Vietnam's electronics manufacturing corridors ahead of smartphone and semiconductor packaging demand migration. Secure dual-source curing agent relationships to neutralize Chinese supply concentration vulnerability. Defend specification authority by embedding technical service teams directly with automotive OEM platform engineers in Gujarat and Maharashtra.
For New Entrants and Emerging Players: UV-curable hybrid formulations offering sub-second cure with moisture-crosslinking backup present a technology-first wedge into medical device assembly, where incumbent response lags biocompatibility certification requirements. White-space concentrates in India's tier-two construction chemical distribution, where Pidilite's dominance leaves gaps in waterproofing membrane technical support. Vietnam's electronics contract manufacturing relocation from coastal China offers the most penetrable geography for ultra-pure silicone qualification. Pursue direct engagement with Japanese METI low-carbon material procurement teams to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic Indian compounders with established BIS testing laboratory relationships in Mumbai and Ahmedabad, where certification backlog creates temporary liquidity pressure. Long-term viability across the next decade rests on water-based and reactive technology transition completion, with solvent-based legacy exposure representing stranded asset risk. Target acquisition archetype: mid-cap regional formulators with 20-40 percent revenue in certified construction chemicals and underinvested R&D infrastructure. Monitor GB standard enforcement intensity in the Yangtze River Delta as inflection indicator for water-based platform demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tackifier Resins | Captive supply of rosin derivatives neutralizes margin compression during naphtha price spikes. |
| Technical Service Center Establishment | Ho Chi Minh City and Hanoi presence supports ionic contamination controls for semiconductor packaging. |
| BIS Certification Investment | Mumbai laboratory relationships unlock preferential access to India's mandatory construction chemical market. |
| Reactive Hot-Melt Capacity Expansion | Thai and Indonesian plants capture automotive interior lamination demand from solvent-based phase-out. |
| UV-Curable Hybrid R&D Program | Medical device assembly applications reward rapid cure speed with biocompatibility compliance. |
Methodological Framework
Document review covered customs and trade databases, SEC 10-K filings from multinational chemical conglomerates, and GB standard enforcement notices from China's Ministry of Ecology and Environment, complemented by interviews with plant managers at Southeast Asian adhesive compounders, procurement leads at Indian automotive OEMs, distribution channel partners across tier-two Indian cities, and technical R&D directors at Japanese silicone formulators. Bottom-up demand modeling triangulated against top-down market sizing from production capacity and utilization disclosures.
Segmentation outputs reflect chemistry platform, end-use industry, physical form, and technology compliance tier across the projection horizon. The analytical framework modeled reactive, water-based, solvent-based, and hot-melt platforms against automotive, construction, electronics, and packaging absorption. CAGRs derived from elasticity-adjusted demand curves incorporating VOC regulatory phase-out schedules and infrastructure investment pipelines. Forecast inputs included electric vehicle battery pack assembly intensity assumptions and flexible food packaging converter migration patterns.
Several conditions sit outside the modeled scope, including sudden tariff reconfigurations on Chinese chemical imports, force majeure disruptions at concentrated curing agent manufacturing sites, and accelerated substitution of adhesive bonding by mechanical fastening in automotive lightweighting. Deviation in GB standard enforcement intensity or BIS certification timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Acrylate Oligomer Market
Adhesives & Sealants
Removable Adhesive Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
United States Adhesives Market
Adhesives & Sealants
United Kingdom Hot-Melt Adhesives Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
Flooring Installation Adhesives Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
Ocular Adhesives and Sealants Market
Adhesives & Sealants
Chemical Anchors Market
Adhesives & Sealants
Dispersion Adhesives Market