
 Global Underfill Material Market | 2026-2036
Global Underfill Material Market Size, Share, and Industry Trends Forecast 2026-2036
Global Underfill Material Market Intelligence
The transition to flip-chip and wafer-level packaging in semiconductor assembly is reconfiguring requirements for thermal and mechanical stress protection. Henkel AG & Co. KGaA leverages its extensive chemical formulation expertise to offer a broad portfolio for diverse applications. NAMICS Corporation specializes in high-performance materials for advanced packaging, particularly for the demanding automotive electronics sector. Meanwhile, Sumitomo Bakelite Co., Ltd. competes through its scale in epoxy resin production and integrated material solutions.
Underfill material is a polymer-based encapsulant, typically an epoxy filled with silica particles, used in semiconductor packaging. It fills the gap between a chip and substrate, absorbing thermal expansion mismatch and protecting solder joints from mechanical shock. While epoxy-based products dominate the material landscape, acrylics are gaining traction in specific niche applications. The capillary flow technology segment holds the largest share, but jet dispense methods are growing faster due to their precision and speed.
Material composition is governed by regulations like the EU's REACH framework and RoHS directive, which restrict hazardous substances. In the United States, EPA guidelines under the TSCA influence chemical precursor sourcing. Additionally, standards from bodies like the IEC in Geneva set reliability and testing protocols for electronic components. Future material development will hinge on balancing higher thermal conductivity requirements with stricter environmental compliance standards.
Market Dynamics
The drive for device miniaturization and higher power density in electronics is the central force shaping the underfill material market. This requires materials with enhanced thermal conductivity, creating a tension between performance gains and compliance with chemical regulations like REACH.
Growth Catalysts
- Advanced Packaging:The adoption of flip-chip and wafer-level packaging in 5G modules and AI accelerators increases the need for underfill to manage thermomechanical stress and dissipate heat.
- Automotive Electrification:Proliferation of ADAS and EV battery management systems, which use numerous microcontrollers, expands the requirement for reliable underfill encapsulants.
- Manufacturing Consolidation:Demand concentrates in semiconductor ecosystems like Taiwan and South Korea, streamlining supply chains and fostering localized material innovation for specific foundry needs.
Market Restraints
- Raw Material Volatility:Prices for high-purity epoxy resins and specialty silica fillers are subject to petrochemical market fluctuations, impacting formulation costs.
- Cure Time Bottlenecks:Traditional capillary underfill processes involve long cure times, limiting throughput in high-volume semiconductor assembly lines.
- Substance Restrictions:The EU's RoHS directive and REACH framework limit specific chemicals, forcing costly reformulation and restricting performance additive options.
Strategic Opportunities
- Bio-based Formulations:Developing underfills from renewable resins meets corporate sustainability goals and appeals to electronics OEMs seeking greener supply chains.
- Jet Dispensing Materials:Formulating materials optimized for high-speed jet dispensing captures share from slower capillary flow methods in advanced packaging applications.
- New Manufacturing Hubs:Establishing supply and technical support in emerging electronics manufacturing centers like Vietnam and India offers first-mover advantages.
Industry Challenges
- Formulation Expertise Scarcity:A shortage of polymer chemists with experience in balancing the thermal, mechanical, and rheological properties required for semiconductor applications exists.
- Complex Reliability Testing:Meeting stringent reliability standards from bodies like the IEC and automotive-specific qualifications requires extensive and time-consuming testing for each new formulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Underfill Material Market |
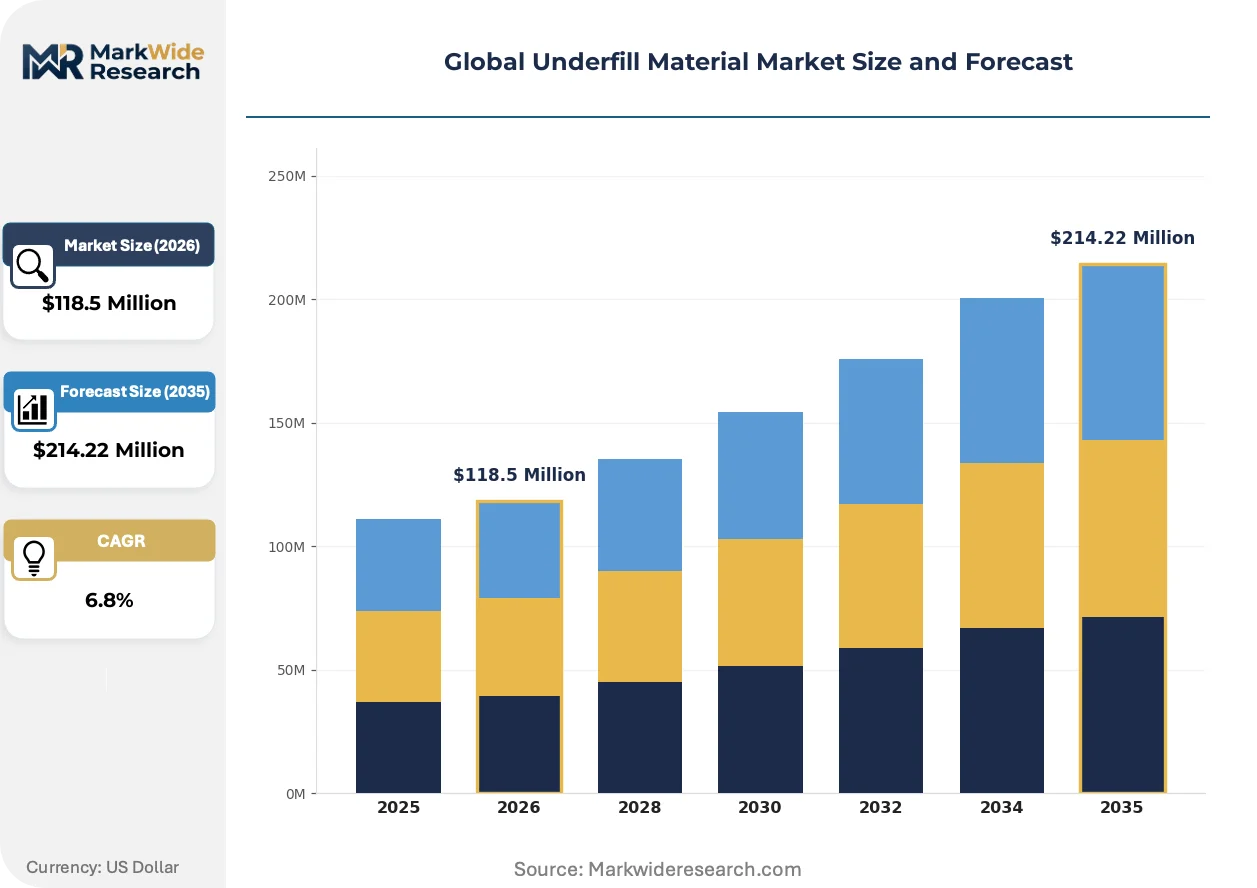
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $214.22 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Silicone, Polyimide, Urethane Technology: Capillary Flow, Vacuum Dispense, Transfer Molding, Jet Dispense, Screen Printing Application: Consumer Electronics, Telecommunications Equipment, Automotive Modules, Industrial Controls, Wearable Devices End User Industry: Semiconductor Packaging, Printed Circuit Board Assembly, Electronic Manufacturing Services, Contract Manufacturing, Original Design Manufacturers |
| Companies Covered | Henkel AG & Co. KGaA, NAMICS Corporation, Won Chemical, H.B. Fuller Company, 3M Company, Sumitomo Bakelite Co., Ltd., Shin-Etsu Chemical Co., Ltd., Showa Denko Materials Co., Ltd., Epoxy Technology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Underfill Material Market Strategic Shifts & Innovations
Material science is converging with process engineering to address the dual challenges of heat dissipation and mechanical integrity in smaller electronic packages. Innovations focus on novel filler materials and dispensing methods that improve both performance and manufacturing efficiency.
Molded Underfill (MUF) is an encapsulant applied during compression molding, forming the package body while simultaneously underfilling the chip. Manufacturers of high-volume components like memory modules are adopting this technology to increase throughput. The assembly process is migrating from a multi-step liquid dispense-and-cure workflow toward a simplified, single-step molding operation.
The US Environmental Protection Agency (EPA) is increasing scrutiny of new chemicals under the Toxic Substances Control Act (TSCA). This extends review timelines and data requirements for novel epoxy precursors or filler additives before they can enter the US market. Material suppliers now often prioritize modifications to existing, TSCA-inventoried chemistries to mitigate regulatory risk and market-entry delays.
Co-development partnerships between material suppliers and semiconductor assembly and test (OSAT) companies are becoming standard practice. This displaces the traditional model of purchasing catalog products with an integrated approach where underfill is tailored for specific jetting platforms. This practice is most pronounced in Taiwan's advanced packaging ecosystem, where custom formulations are required for unique process flows.
Global Underfill Material Market Segmentation
Segmentation within the underfill material market illuminates the diverse functional requirements and application methods that shape product development. Understanding these distinct segments helps identify areas of concentrated demand and technological evolution, guiding strategic investments in material science and process innovation.
Product Type:
The underfill material market segments by product type, showcasing a maturity spectrum from established epoxy formulations to emerging acrylic alternatives.
- Epoxy:This polymer-based encapsulant, often filled with silica particles, forms the traditional backbone of underfill applications. Demand concentrates in flip-chip and wafer-level packaging across South Korea and Taiwan, driven by thermomechanical stress protection requirements.
- Acrylic:These materials are gaining traction in specific niche applications, offering advantages like faster cure times or lower stress profiles. Adoption is expanding in consumer electronics where high throughput and reduced processing times are critical for volume manufacturing.
- Silicone:Known for flexibility and temperature stability, silicone underfills serve applications requiring high-temperature resistance or specific stress relief.
- Polyimide:These high-performance polymers find use in demanding environments due to their excellent thermal stability and chemical resistance in specialized electronic components.
- Urethane:Offering a balance of flexibility and adhesion, urethane underfills are employed in applications where impact resistance and moderate thermal performance are key.
Epoxy handles the majority of throughput; Acrylic is the fastest mover on share.
Technology:
Underfill material technology is defined by application methods, ranging from traditional capillary flow to advanced jet dispensing systems.
- Capillary Flow:This traditional method relies on the underfill material flowing into the chip-to-substrate gap via capillary action after dispense. It dominates high-volume, cost-sensitive semiconductor assembly, particularly in established packaging lines.
- Jet Dispense:Characterized by precision and speed, jet dispensing ejects discrete droplets of underfill, enabling highly accurate placement and faster processing. This technology is crucial for advanced packaging in AI accelerators and 5G modules, where miniaturization is paramount.
- Vacuum Dispense:This technique ensures void-free filling by applying underfill in a vacuum, critical for high-reliability applications and complex package geometries.
- Transfer Molding:Used in molded underfill (MUF) processes, this method integrates encapsulation with package formation, streamlining manufacturing for high-volume memory components.
- Screen Printing:A cost-effective and high-throughput method, screen printing applies underfill to multiple components simultaneously, suitable for certain flip-chip and wafer-level applications.
Capillary flow methods account for the largest volume, while jet dispense offers specialized performance for next-generation devices.
Application:
The segmentation by application highlights diverse end-user requirements, from high-volume consumer devices to mission-critical automotive systems.
- Automotive Modules:Underfill materials protect microcontrollers and sensors in electric vehicles and advanced driver-assistance systems. These applications demand high reliability and thermal stability under harsh operating conditions.
- Consumer Electronics:This segment includes smartphones, laptops, and smart devices, driving demand for underfills that support miniaturization and high-density packaging. Rapid product cycles and cost efficiency influence material selection for these high-volume products.
- Telecommunications Equipment:Underfill protects components in 5G infrastructure, base stations, and network devices, requiring materials with robust thermal management capabilities.
- Industrial Controls:Underfill materials ensure the durability and reliability of electronic components in factory automation, robotics, and power management systems operating in challenging environments.
- Wearable Devices:Miniaturization and flexibility are key drivers in this segment, requiring underfills that offer mechanical protection within compact and often flexible form factors.
Automotive modules impose the strictest reliability standards; consumer electronics drive the largest material volume.
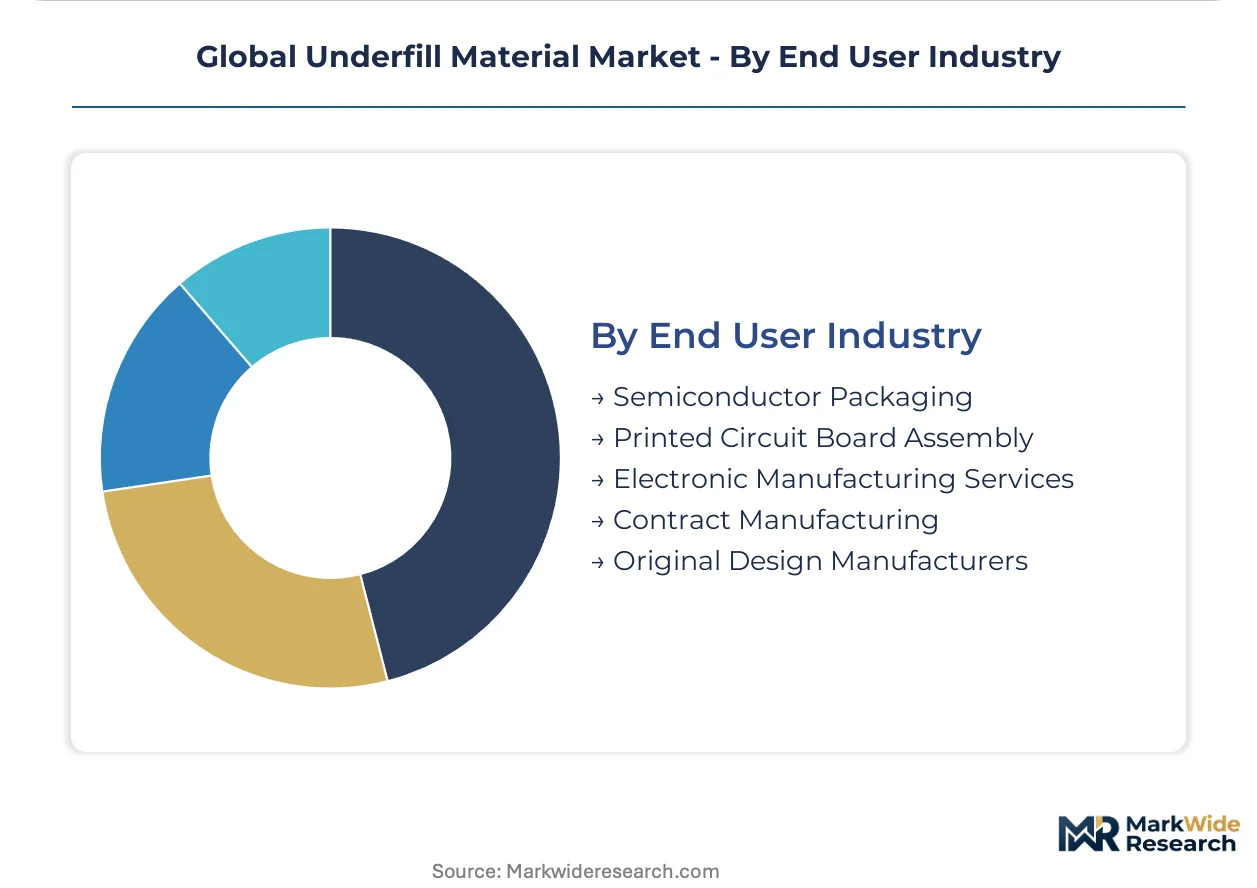
End User Industry:
End-user industry segmentation reveals where supply concentration dictates material specifications, particularly within the semiconductor ecosystem.
- Semiconductor Packaging:This core industry segment integrates underfill materials into advanced packaging architectures like flip-chip and wafer-level packages. It demands materials optimized for thermal dissipation and solder joint protection in high-performance chips.
- Electronic Manufacturing Services:EMS providers assemble, test, and distribute electronic components for original equipment manufacturers. They require versatile underfill solutions that integrate seamlessly into diverse production lines and support various customer specifications.
- Printed Circuit Board Assembly:Underfill materials enhance the mechanical integrity and thermal performance of components mounted on PCBs, particularly in high-density or stress-prone areas.
- Contract Manufacturing:These firms produce goods for other companies, requiring flexible underfill solutions that can adapt to varying product designs and production scales across different industries.
- Original Design Manufacturers:ODMs design and manufacture products that are then rebranded by other companies, necessitating underfill materials that meet specific design and reliability benchmarks for their proprietary designs.
Semiconductor packaging dictates the most advanced material requirements; Electronic Manufacturing Services integrate underfill across the widest range of products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global underfill material market exhibits a complex trade dynamic, with key manufacturing hubs driving significant export volumes of finished electronic goods while simultaneously importing specialized material precursors. This balance influences localized material development and supply chain resilience. Demand for advanced packaging solutions shapes regional market structures.
South Korea
South Korea's robust semiconductor industry drives demand for advanced underfill materials in memory and logic chips. The country's MFDS oversees chemical safety, impacting material formulation and approval processes. The Seoul Capital Area, including cities like Suwon, concentrates R&D and manufacturing for high-performance electronics.
Taiwan
Taiwan, a global leader in foundry services, requires tailored underfill solutions for its advanced packaging ecosystems. Local standards from bodies like BSMI ensure component reliability and material compliance. The Hsinchu Science Park forms a critical cluster for semiconductor manufacturing and underfill material innovation.
United States
Demand for underfill materials in the United States stems from high-performance computing and AI accelerator development. The EPA, under the TSCA, rigorously reviews new chemical substances, influencing material development timelines. Silicon Valley, California, remains a hub for advanced semiconductor design and related material science research.
Germany
Germany's automotive sector, particularly in electric vehicles and ADAS, fuels demand for highly reliable underfill encapsulants. European regulations like REACH and RoHS dictate strict substance restrictions for material suppliers. The Munich and Stuttgart regions host significant automotive electronics manufacturing and material R&D centers.
China
China's expanding domestic electronics production and EV market generate substantial demand for underfill materials. The Ministry of Industry and Information Technology (MIIT) promotes local material innovation through various policy initiatives. The Yangtze River Delta, a major manufacturing base, sees extensive application of underfill in consumer and industrial electronics.
Global Underfill Material Market Key Industry Players
On the supply side, the industry is characterized by a mix of large diversified chemical companies and specialized material formulators. This structure enables both broad-portfolio offerings and niche high-performance solutions. Key strategic archetypes include global chemical giants leveraging scale and agile specialists focusing on advanced packaging. Competitive moves primarily involve strategic partnerships for co-development and targeted capacity expansions.
Global chemical conglomerates like Henkel AG & Co. KGaA exemplify the diversified approach, offering a broad material portfolio for various applications across multiple industries. NAMICS Corporation, a Japan-based specialist, represents companies focused on high-performance materials for advanced packaging, particularly in demanding sectors like automotive electronics and AI accelerators. Sumitomo Bakelite Co., Ltd., also from Japan, occupies a position leveraging extensive epoxy resin production capabilities and integrated material solutions for semiconductor assembly.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| NAMICS Corporation |
| Won Chemical |
| H.B. Fuller Company |
| 3M Company |
| Sumitomo Bakelite Co., Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| Showa Denko Materials Co., Ltd. |
| Epoxy Technology, Inc. |
| Others |
Cost & Logistics Intelligence
Raw material volatility for high-purity epoxy resins determines both pricing tier spreads and the geographic shape of the underfill material supply chain. Petrochemical market fluctuations directly influence material costs, impacting end-product pricing and procurement strategies.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for underfill materials. Price differentiation hinges on customization levels for specific jetting platforms and stringent IEC or automotive-specific certification requirements. Upward pricing pressure stems from the high R&D investment for advanced packaging solutions and volatile raw material costs. Consumer electronics manufacturers exhibit the highest price sensitivity, while automotive module producers prioritize performance and reliability over cost.
Supply Chain Analysis
Export control regimes and intellectual property protections limit the flow of advanced underfill material formulations, concentrating supply. Supply for specialized underfill materials primarily concentrates in Taiwan, South Korea, and Japan, where advanced packaging ecosystems reside. The industry relies on high-purity epoxy resins and specialty silica fillers, creating single-source vulnerability for niche applications. Distribution runs through direct sales channels to semiconductor packaging companies and Electronic Manufacturing Services providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The underfill material market is experiencing a buyer-power shift driven by the consolidation of electronics manufacturing centers in Taiwan and South Korea. This demand concentration enables large OSATs to exert greater influence over material specifications and pricing.
For Market Incumbents: Harden core market positions by deepening co-development partnerships with major OSATs in Taiwan's advanced packaging ecosystem. Invest in R&D for higher thermal conductivity materials to counter the threat from emerging acrylic alternatives. Expand specialized production capacity in South Korea, focusing on materials compliant with evolving EU REACH and RoHS regulations.
For New Entrants and Emerging Players: Pursue niche opportunities in jet dispensing materials optimized for high-speed advanced packaging applications. Target emerging electronics manufacturing centers like Vietnam and India, establishing early supply and technical support infrastructure. Develop bio-based underfill formulations to meet corporate sustainability goals of electronics OEMs. Offer tailored solutions that address specific regional process flows and regulatory requirements.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized material formulators with deep chemical formulation expertise. Long-term viability extends over the next decade, driven by sustained demand from electric vehicles and AI accelerators. Acquisition targets should focus on agile specialists developing high-performance materials for advanced packaging. Increased M&A activity in thermal management material science will signal market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-development with OSATs | Tailors underfill solutions for unique process flows in Taiwan's advanced packaging ecosystem. |
| Capacity Expansion in Asia | Secures supply chains and supports localized material innovation in South Korea's electronics manufacturing centers. |
| Bio-based Material R&D | Addresses stricter environmental compliance standards and appeals to electronics OEMs seeking greener supply chains. |
| Jet Dispense Optimization | Captures market share from slower capillary flow methods in advanced packaging applications for AI accelerators. |
| Regulatory Compliance Investment | Navigates complex frameworks like EU REACH and US TSCA, ensuring market access for novel epoxy precursors. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews to gather granular market insights. Interviews included polymer chemists, OSAT procurement managers, automotive electronics engineers, and regulatory compliance officers. Secondary validation leveraged IEC standards, EPA guidelines, and petrochemical market reports. This data was triangulated using both bottom-up and top-down approaches to ensure robust market sizing.
The analytical framework was calibrated against historical market performance and projected growth drivers over the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional electronics manufacturing concentration. CAGRs were derived from industry-specific inputs like semiconductor fabrication capacity and EV production volumes.
Sensitivities concentrate around unforeseen regulatory changes, particularly US TSCA and EU REACH updates, and raw material price fluctuations. Forecasts reflect documented assumptions regarding technological advancements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Spain Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesives for EV Battery Modules Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
Contact Cement Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Chemical Anchors Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
Ocular Adhesives and Sealants Market