
 Acrylate Market | 2026-2036
Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylate Market Intelligence
The divergence in capital investment for propylene oxidation technology is unwinding the historical cost advantages of large-scale producers. BASF SE leverages its integrated Verbund production system to maintain cost leadership in key regions like Germany and China. In contrast, Arkema Group differentiates through a focus on specialty acrylic polymers and downstream derivatives for high-performance applications. The Dow Chemical Company competes on a global scale by utilizing its vast feedstock access and extensive distribution network across multiple continents.
Acrylates are a family of esters derived from acrylic acid, functioning as reactive monomers in polymerization. Their key characteristic is a vinyl group adjacent to a carboxyl group, which facilitates chain-growth polymerization to form acrylic polymers. These polymers are valued for their clarity, weather resistance, and adhesive properties. The product landscape is dominated by bulk monomers like Butyl Acrylate and 2-Ethylhexyl Acrylate. Within applications, the Coatings and Adhesives & Sealants segments constitute the largest share of consumption, primarily for the construction and automotive sectors.
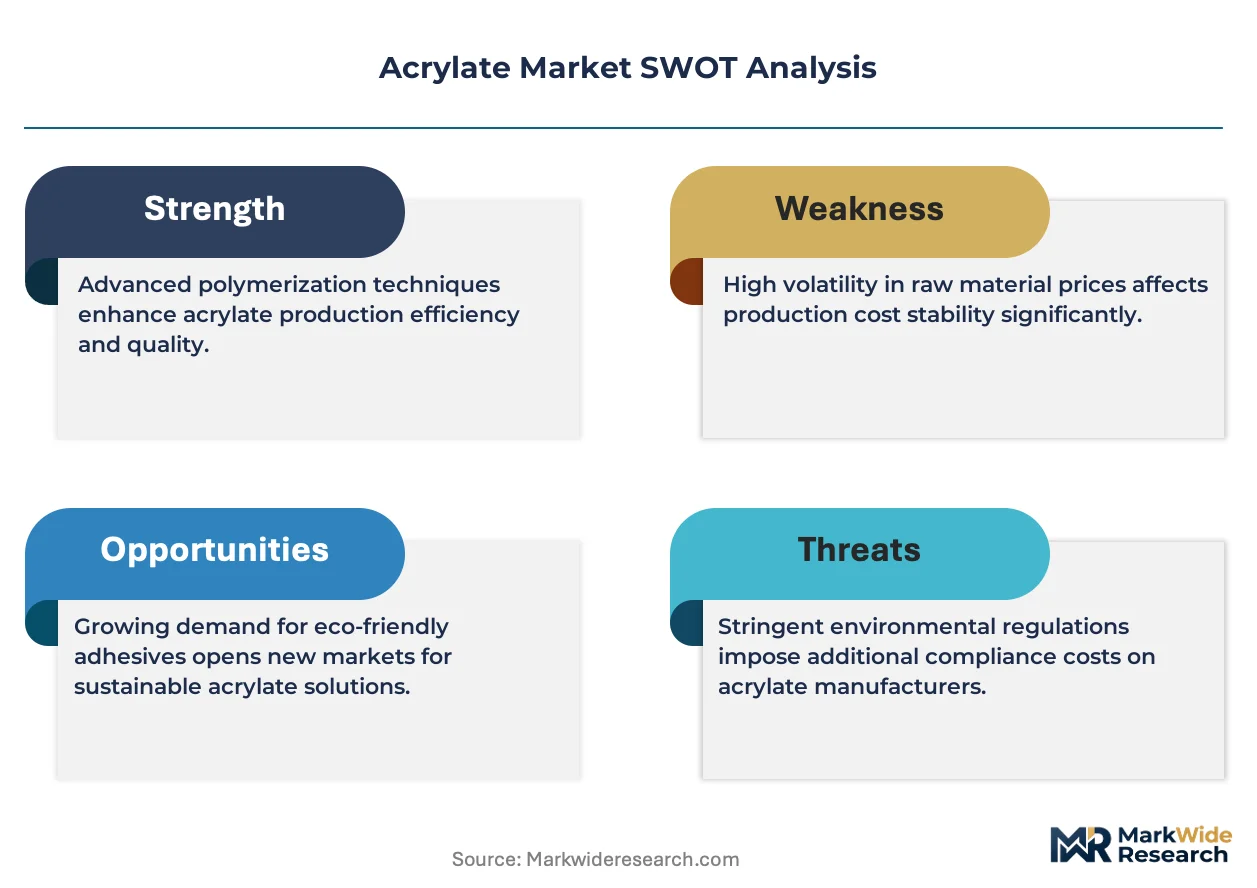
Regulatory frameworks from Europe's ECHA under REACH and the US EPA's rules on volatile organic compounds (VOCs) actively shape product formulation. In parallel, China's Ministry of Ecology and Environment (MEE) imposes strict standards on industrial emissions from chemical plants. The industry's strategic direction now hinges on the successful commercialization of bio-based acrylic acid and the expansion of waterborne systems to meet tightening environmental mandates.
Market Dynamics
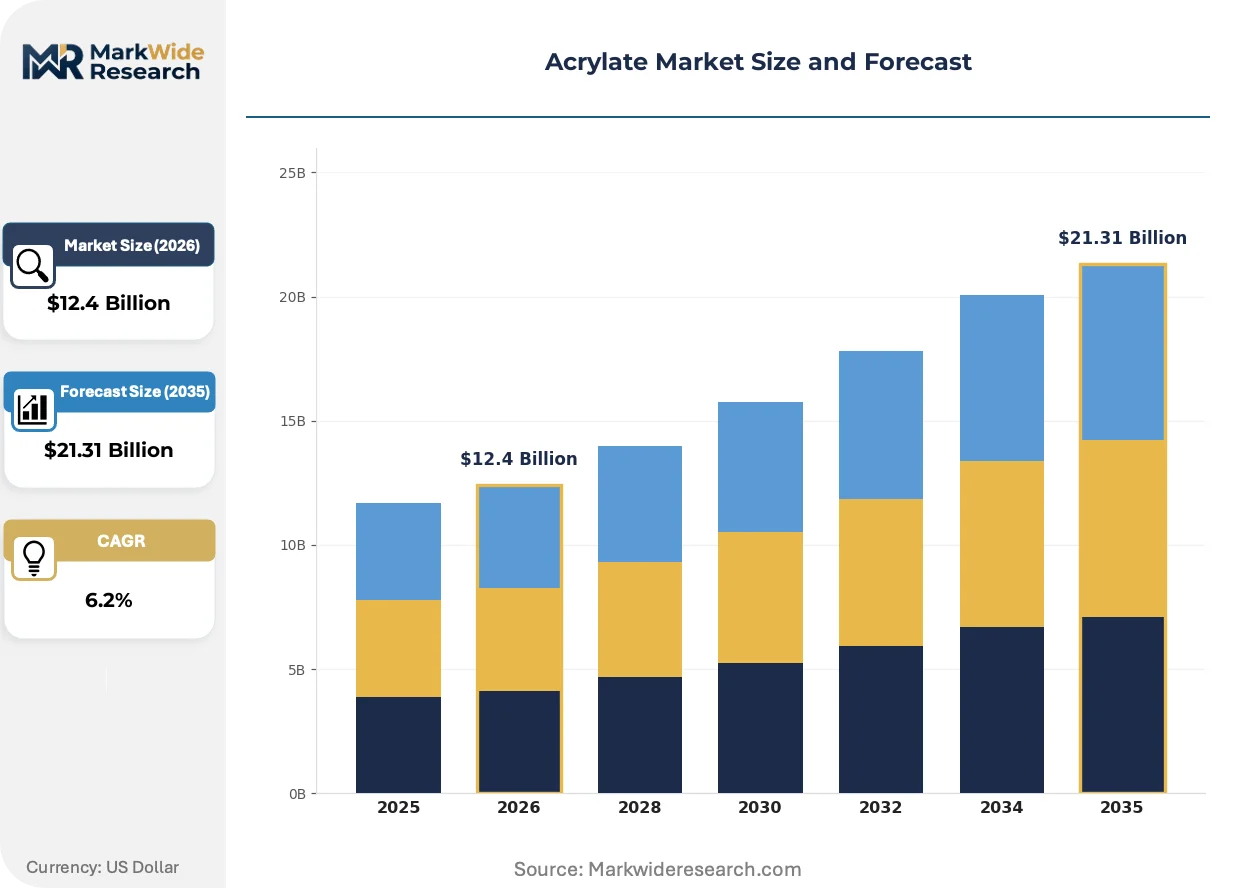
The market's central dynamic is the tension between volatile propylene feedstock costs and intensifying global environmental mandates. Regulations from Europe's ECHA and China's MEE are forcing a strategic pivot towards sustainable, low-VOC formulations, altering historical production economics.
Growth Catalysts
- Architectural Coatings Expansion:Rapid urbanization and infrastructure projects in countries like India and Brazil fuel demand for acrylic-based paints and coatings due to their durability and weather resistance.
- Automotive Lightweighting:The automotive industry's push for lighter vehicles increases the use of acrylic adhesives and composites as alternatives to mechanical fasteners and heavier materials.
- REACH Regulation Evolution:European Union chemical safety rules under REACH actively encourage innovation in waterborne and high-solid acrylate systems, creating new product categories with lower environmental impact.
Market Restraints
- Feedstock Price Volatility:The acrylate value chain is highly exposed to price fluctuations in its primary feedstock, propylene, which can compress margins for non-integrated producers.
- Substitution from Polyurethanes:In high-stress applications within industrial coatings and sealants, polyurethane systems present a significant performance-based substitution threat to traditional acrylics.
- Regulatory Compliance Burden:The high cost and technical data requirements for registering new acrylate substances under frameworks like the US EPA's TSCA create barriers to entry.
Strategic Opportunities
- Bio-Based Feedstocks:The development and scaling of bio-based acrylic acid from renewable sources like glycerin or sugars presents a major opportunity to decarbonize the value chain.
- 3D Printing Resins:Acrylate photopolymers are finding new, high-value applications as foundational materials for UV-curable resins used in stereolithography (SLA) and digital light processing (DLP) 3D printing.
- Expansion in Southeast Asia:Growing manufacturing bases in Vietnam and Indonesia offer significant greenfield opportunities for acrylate consumption in textiles, packaging, and electronics assembly.
Industry Challenges
- Capital-Intensive Production:The construction of new, efficient propylene oxidation and esterification facilities requires substantial capital investment, limiting the entry of smaller competitors.
- Process Safety Management:Managing the hazards associated with the handling of highly reactive and flammable acrylate monomers demands rigorous adherence to process safety protocols, such as those outlined by OSHA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylate Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $21.31 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methyl Acrylate, Ethyl Acrylate, Butyl Acrylate, 2-Ethylhexyl Acrylate, Octyl Acrylate Application: Adhesives & Sealants, Coatings, Textile Finishing, Plastics Modification, Paints End User Industry: Construction, Automotive Tier-1 Suppliers, Packaging, Electronics Manufacturing, Consumer Goods Technology: Free Radical Polymerization, Emulsion Polymerization, Suspension Polymerization, Solution Polymerization, UV Polymerization |
| Companies Covered | BASF SE, The Dow Chemical Company, Nippon Shokubai Co., Ltd., Arkema Group, LG Chem Ltd., Mitsubishi Chemical Corporation, Evonik Industries, Sasol Limited, Formosa Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylate Market Strategic Shifts & Innovations
A dual focus on environmental compliance and material functionality defines the current innovation cycle for acrylates. This pushes development beyond bulk monomers toward specialized polymers that solve specific end-use challenges while meeting stricter regulatory standards.
Advanced UV-curable acrylate systems provide rapid, low-energy polymerization for industrial processes. The electronics and medical device sectors are steadily adopting these formulations for precision bonding and coating applications. This technology is miniaturizing the physical space required for curing equipment on production lines, enabling more compact and efficient manufacturing operations.
European Union regulations under REACH mandate comprehensive safety data for all chemical substances, including acrylate monomers. This forces producers to invest heavily in toxicological testing and risk assessment, directly impacting R&D budgets. The specialty acrylates segment is most affected, accelerating a shift to waterborne systems to reduce exposure profiles and compliance burdens.
Consolidated procurement practices in key end-use industries are shifting buying criteria from simple cost-per-ton to total performance value. The traditional model of purchasing bulk monomers is being supplemented by demand for tailored polymer solutions that guarantee specific outcomes like adhesion strength or UV resistance. This trend is most visible within the automotive OEM supply chains in Germany and Japan.
Acrylate Market Segmentation
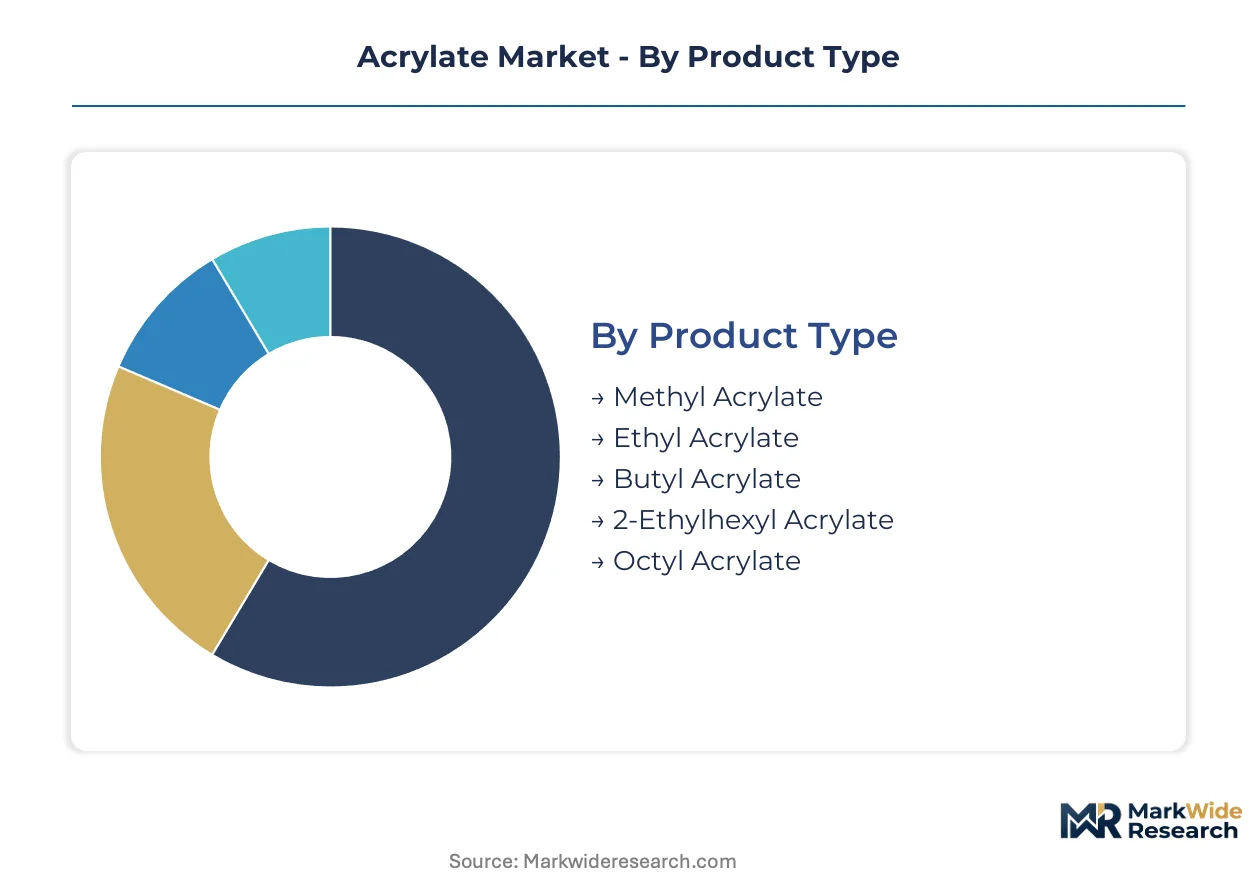
Segmentation analysis reveals the diverse characteristics and applications defining the acrylate market landscape. Understanding these segments is crucial for identifying targeted growth strategies and navigating the complex interplay of feedstock dynamics, regulatory pressures, and end-use demand. This detailed breakdown illuminates where value creation and innovation are most concentrated.
Product Type:
Regulatory frameworks from Europe's ECHA and the US EPA significantly influence formulation requirements across different acrylate product types, driving innovation in low-VOC alternatives.
- Butyl Acrylate:A primary bulk monomer, Butyl Acrylate is widely used for its flexibility and weather resistance in polymer emulsions for coatings and adhesives. Demand concentrates in China's construction sector, driven by extensive infrastructure development.
- 2-Ethylhexyl Acrylate:This acrylate monomer provides excellent low-temperature flexibility and adhesion, valuable for pressure-sensitive adhesives and sealants. Usage is strong in the automotive industry in Germany, where high-performance bonding solutions are critical.
- Methyl Acrylate:Used as a building block for various polymers, Methyl Acrylate finds application in textile and leather finishes due to its hardness.
- Ethyl Acrylate:Ethyl Acrylate is a key component in emulsion polymers, offering good adhesion and flexibility for paints and non-woven fabrics.
- Octyl Acrylate:Valued for its hydrophobicity and low glass transition temperature, Octyl Acrylate is employed in specialty pressure-sensitive adhesives.
Butyl Acrylate handles the majority of throughput; 2-Ethylhexyl Acrylate is the fastest mover on share.
Application:
Volume concentration dictates the competitive landscape across acrylate applications, with established sectors absorbing the largest quantities of acrylic monomers and polymers.
- Coatings:This segment represents the largest consumption share, utilizing acrylates for durability, weather resistance, and color retention in architectural and industrial paints. The construction sector in India drives significant demand for acrylic coatings.
- Adhesives & Sealants:Acrylates provide strong bonding, flexibility, and UV resistance for various adhesive and sealant formulations, crucial for construction and automotive assembly. Automotive OEM supply chains in Japan increasingly specify acrylate-based adhesives for lightweighting.
- Textile Finishing:Acrylates enhance fabric properties, providing improved hand feel, durability, and wrinkle resistance in manufacturing.
- Plastics Modification:Acrylate polymers are incorporated into plastics to improve impact strength, weatherability, and processing characteristics.
- Paints:Acrylate-based paints offer superior adhesion, gloss retention, and environmental benefits, particularly in waterborne formulations.
Coatings and Adhesives & Sealants represent mature segments, while Plastics Modification exhibits expanding most quickly.
End User Industry:
Specific end-user industries drive demand for acrylates based on unique performance requirements and evolving material specifications.
- Construction:This industry is a primary consumer of acrylates for paints, coatings, adhesives, and sealants, valuing durability and weather resistance. Rapid urbanization in Brazil fuels substantial demand for acrylate products in new building projects.
- Automotive Tier-1 Suppliers:These suppliers integrate acrylate-based materials into components for lightweighting, bonding, and protective coatings, meeting stringent performance standards. The push for electric vehicles in Germany increases acrylate adhesive use for battery pack assembly.
- Packaging:Acrylates are used in packaging for flexible films, laminates, and adhesive tapes, offering barrier properties and printability.
- Electronics Manufacturing:Acrylate photopolymers find application in printed circuit boards, displays, and encapsulants due to precision curing.
- Consumer Goods:This segment utilizes acrylates in various products, including personal care items, household paints, and durable goods.
The Construction and Automotive sectors remain strategically important; Electronics Manufacturing is climbing the fastest due to technological advancements.
Technology:
Innovation focus within polymerization technologies is shifting towards processes offering greater efficiency, lower environmental impact, and enhanced polymer performance.
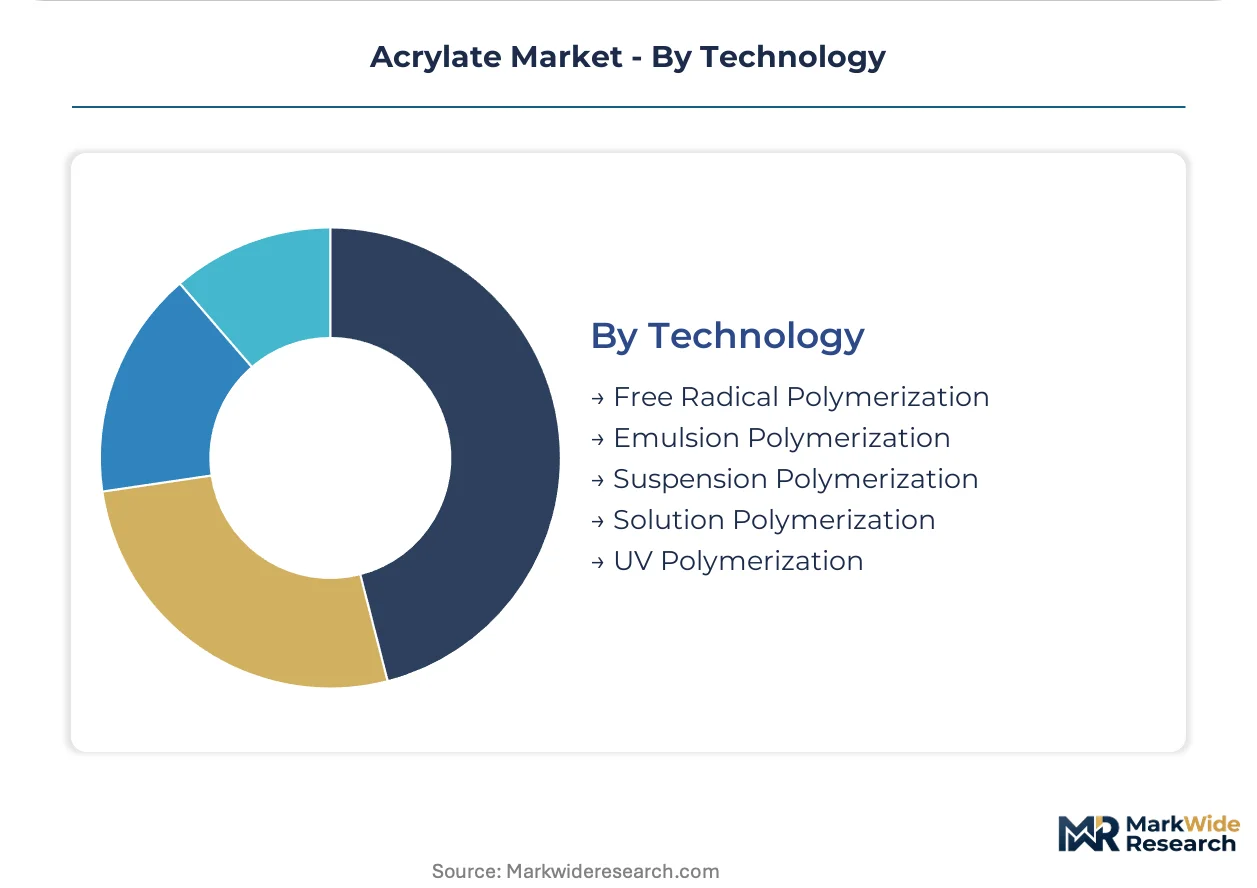
- UV Polymerization:This rapid, low-energy curing technology utilizes acrylate photopolymers for precision bonding and coating in electronics and medical devices. Its miniaturization capabilities are valuable for compact manufacturing lines in South Korea's electronics industry.
- Free Radical Polymerization:A fundamental and versatile method, Free Radical Polymerization is widely employed for producing bulk acrylate monomers and polymers for various industrial applications. This technology remains the backbone for large-scale production facilities in China.
- Emulsion Polymerization:This water-based method produces polymer dispersions, crucial for low-VOC paints, adhesives, and textile finishes, aligning with environmental mandates.
- Suspension Polymerization:Used for producing spherical polymer beads, Suspension Polymerization finds applications in ion-exchange resins and specialized coatings.
- Solution Polymerization:This technique creates polymers dissolved in a solvent, suitable for specific coating and adhesive formulations requiring precise molecular weight control.
Free Radical Polymerization maintains its foundational role, while UV Polymerization exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power within the acrylate market shows asymmetry, with China benefiting from extensive manufacturing scale while European producers face higher compliance costs. This divergence influences investment decisions and supply chain resilience across continents. Feedstock availability and regulatory pressures shape regional market dynamics.
China
Demand for acrylate polymers in China stems from its vast manufacturing and construction industries. China's Ministry of Ecology and Environment (MEE) imposes strict standards on industrial emissions from chemical plants. Large-scale production facilities in the Yangtze River Delta continue to drive bulk acrylate monomer output.
Germany
Germany's automotive sector and high-performance applications generate significant demand for specialty acrylic polymers. European Union chemical safety rules under REACH actively encourage innovation in waterborne acrylate systems. Automotive OEM supply chains in Bavaria increasingly specify acrylate-based adhesives for lightweighting initiatives.
India
Rapid urbanization and infrastructure projects in India fuel substantial demand for acrylic-based paints and coatings. The Bureau of Indian Standards (BIS) guides product quality and safety for construction materials. Construction activities in major metropolitan areas like Mumbai drive significant consumption of acrylic coatings.
Brazil
Brazilian construction sector growth and expanding consumer goods manufacturing elevate acrylate consumption. ANVISA, the national health surveillance agency, regulates chemical product safety and usage. New building projects in São Paulo fuel substantial demand for acrylate products.
United States
The United States industrial coatings and adhesives sectors consistently require acrylate monomers for diverse applications. The US EPA's rules on volatile organic compounds (VOCs) actively shape product formulation. Chemical manufacturing hubs along the Gulf Coast remain critical for acrylate production.
Acrylate Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the acrylate market. The market exhibits a tiered structure, with large, integrated chemical conglomerates coexisting with specialized polymer producers. Strategic archetypes include diversified chemical giants, specialty chemical innovators, and regional bulk manufacturers. Dominant competitive moves involve capacity expansions in Asia and strategic partnerships for bio-based feedstock development.
Diversified chemical giants, such as Germany-based BASF SE, anchor the market through extensive production capabilities and integrated supply chains. Arkema Group, a France-based specialty chemical producer, exemplifies differentiation through a focus on high-performance acrylic polymers and downstream derivatives. The Dow Chemical Company, a US-based multinational, leverages its vast feedstock access and extensive distribution networks to compete on a global scale. These players represent the varied approaches to market penetration and value creation.
| Leading Market Players |
|---|
| BASF SE |
| The Dow Chemical Company |
| Nippon Shokubai Co., Ltd. |
| Arkema Group |
| LG Chem Ltd. |
| Mitsubishi Chemical Corporation |
| Evonik Industries |
| Sasol Limited |
| Formosa Plastics Corporation |
Cost & Logistics Intelligence
European Union chemical safety rules under REACH gate both supply qualification and price differentiation for acrylate products. These regulations necessitate innovation in low-VOC formulations, impacting production costs.
Pricing Analysis
Configured-to-order acrylate solutions command a premium over standard, bulk monomer pricing. The dominant pricing structure is contract-based long-term off-take for large industrial buyers, supplemented by spot market transactions for smaller volumes. Price differentiation stems from product purity grades and the level of technical support provided for specialized applications. Pricing softness for commodity acrylates reflects volatile propylene feedstock costs. Construction sector buyers often exhibit high price sensitivity, while electronics manufacturing demands performance over cost.
Supply Chain Analysis
Inventory levels for acrylate monomers often fluctuate with lead times for propylene, a critical feedstock. Geographic supply concentrates heavily in China due to vast production capacities and along the US Gulf Coast. The acrylate value chain relies on propylene and acrylic acid. Commodity price volatility for these petrochemical inputs presents a significant structural supply chain risk. Distribution runs primarily through specialized chemical distributors and direct sales to large industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acrylate market is poised for a cyclical recovery, driven by renewed global industrial activity post-pandemic. Infrastructure spending and manufacturing expansion are boosting demand for acrylic polymers.
For Market Incumbents:
Fortify core market positions through continuous process optimization and strategic capacity expansions in Asia. This counters the threat of margin compression from volatile feedstock costs and emerging regional competitors. Invest heavily in R&D for bio-based acrylic acid to meet tightening environmental mandates. Deepen vertical integration into key raw material production to enhance cost leadership.
For New Entrants and Emerging Players:
Lead with specialized, high-performance acrylate formulations for niche applications like 3D printing resins. The electronics manufacturing sector in South Korea presents a penetrable segment for UV-curable acrylate photopolymers. Focus on developing waterborne systems to align with strict VOC regulations. A go-to-market angle involves direct technical collaboration with OEM design teams.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upwards across specialty acrylate production, signaling long-term market viability. The market offers attractive returns over a five-to-ten year window, especially in high-growth application areas. Target acquisition archetypes include specialized polymer producers with advanced UV-curable or bio-based technology portfolios. A key signal to watch is the successful commercialization of new bio-based acrylic acid production facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expand production facilities in Southeast Asia to meet regional construction and electronics demand. |
| Green Manufacturing Transition | Invest in processes for bio-based acrylic acid to comply with global environmental mandates. |
| Long-term Supply Agreement | Secure stable propylene feedstock through long-term contracts to mitigate price volatility. |
| Joint Venture | Partner with technology firms to develop advanced UV-curable resins for 3D printing applications. |
| R&D for Waterborne Systems | Prioritize research into low-VOC waterborne acrylate formulations for architectural coatings. |
Research Approach
A spread of perspectives from plant managers, procurement leads at OEMs, and R&D directors converged on the working assumptions for acrylate market dynamics. This involved extensive primary interviews with industry stakeholders, validated by secondary research. Secondary sources included customs data, Cefic reports, and SEC 10-K filings from major chemical producers. A robust bottom-up and top-down triangulation approach ensured data accuracy and consistency.
Segmentation dimensions modeled included product type, application, end-user industry, technology, and regional production hubs. The analytical framework projected market growth across the modeling period without specific year references. Compound annual growth rates were derived from historical trends and anticipated shifts in demand patterns. Key forecast inputs included urbanization rates in emerging markets and automotive lightweighting trends.
The analysis sits within stated boundaries; outcomes outside major geopolitical shifts or unforeseen technological breakthroughs would require recalibration. Forecasts reflect assumptions regarding feedstock stability and regulatory enforcement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
Anti-Seize Compounds Market
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
Timber Laminating Adhesives Market
Adhesives & Sealants
Elastomeric Adhesive Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
Bio-Based Adhesive and Sealant Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
Solvent-Borne Adhesives Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Europe Waterborne Adhesives Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
Global Glass Bonding Adhesive Market
Adhesives & Sealants
Vietnam Construction Chemicals Market