
 Australia Adhesives Market | 2026-2036
Australia Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Adhesives Market Outlook
Australia's National Environment Protection Measure for Air Quality is recalibrating the cost-of-entry calculus for adhesive suppliers seeking federal project eligibility. Henkel AG & Co. KGaA leverages its global R&D network to localize low-VOC formulations that meet state-level procurement thresholds. Sika AG anchors its position through vertical integration into construction-sector distribution, while Bostik Australia Pty Ltd competes aggressively in the retail renovation channel with specialized polyurethane lines.
Adhesives are non-metallic substances applied to substrate surfaces that develop structural or semi-structural bonding through chemical curing, mechanical interlocking, or diffusion mechanisms, with tensile shear strengths ranging from flexible sealants to rigid epoxy systems exceeding structural engineering thresholds. Their primary industrial purpose spans permanent assembly, temporary fixation, sealing, and surface protection across manufacturing and construction workflows. Water-based formulations now lead volume share in Australia's regulatory environment, while reactive systems command premium positioning in automotive and electronics applications where cure speed and thermal resistance determine specification wins. Hot melt segments sustain growth in packaging automation lines serving food and beverage distribution networks.
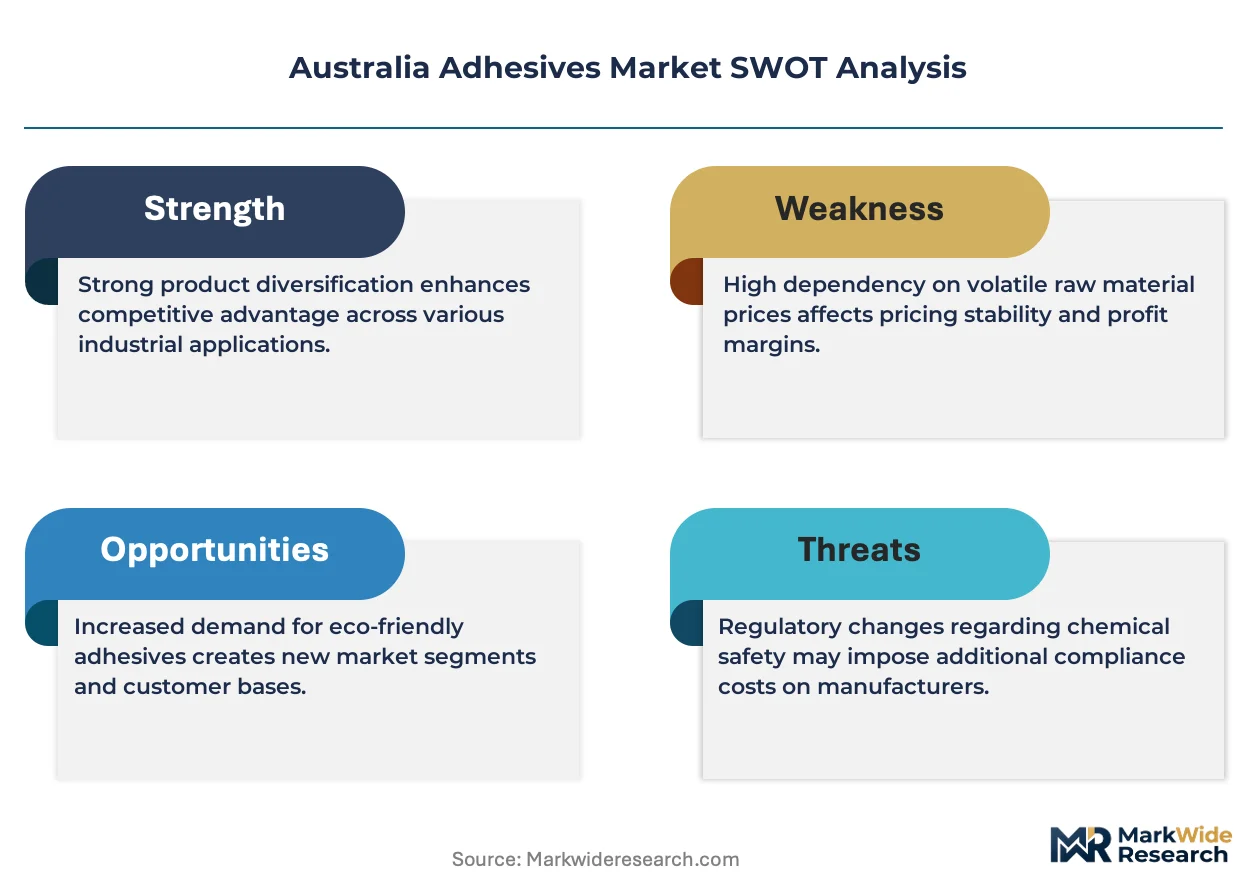
TGA chemical substance assessments intersect with NICNAS industrial chemical registration requirements to govern adhesive ingredient safety and import compliance, while state-level EPA jurisdictions enforce VOC emission limits that directly shape product formulation roadmaps. WELS labeling and Green Star building certification create dual pressure points that elevate water-based and bio-sourced adhesive specifications in commercial construction tenders. Stakeholders must monitor the convergence of federal procurement standards with state EPA enforcement intensity to anticipate which formulation platforms will retain project eligibility across Australia's fragmented regulatory landscape.
Market Dynamics
Tightening VOC emission protocols under Australia's National Environment Protection Measure are recalibrating formulation priorities, redirecting procurement specifications toward water-based and low-emission chemistries across federal and state-level construction tenders.
Growth Catalysts
- Green Star building certification:Commercial construction projects in Sydney and Melbourne now mandate adhesives meeting sustainability benchmarks, accelerating specification of bio-sourced and water-based systems in high-rise developments.
- Transport manufacturing corridor expansion:Victoria's automotive and rail assembly clusters are driving reactive adhesive demand where cure speed and thermal resistance determine engineering approvals.
- WELS water efficiency labeling:This federal scheme redirects industrial procurement toward formulations with reduced water intensity, particularly in New South Wales infrastructure pipelines.
Market Restraints
- Petrochemical feedstock volatility:Epoxy and polyurethane resin costs fluctuate with crude oil derivatives, compressing margin stability for formulators serving price-sensitive renovation channels.
- Import concentration risk:Specialty monomer and catalyst supplies concentrate through Asian manufacturing hubs, exposing Australian blenders to shipping disruption and currency exposure.
- Cure speed limitations in ambient conditions:Water-based systems face performance gaps in cold-weather construction across Tasmania and southern Victoria, restricting seasonal application windows.
Strategic Opportunities
- Queensland mining infrastructure renewal:Heavy equipment maintenance and conveyor system assembly in the Bowen Basin create demand for high-shear structural bonding systems currently underpenetrated versus construction.
- Food packaging automation:Hot melt segments serving beverage distribution networks in Adelaide and Perth offer expansion as line speeds increase and substrate diversity broadens.
- Digital specification platforms:Building information modeling integration enables adhesive suppliers to embed performance data directly into architect workflows, shortening tender qualification cycles.
Industry Challenges
- Formulation chemist scarcity:NICNAS registration complexity and TGA substance assessment requirements demand specialized regulatory affairs capacity that mid-size blenders struggle to retain.
- Multi-jurisdiction compliance timelines:State EPA enforcement intensity varies between New South Wales, Victoria, and Queensland, forcing parallel certification tracks for national product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Adhesives Market |
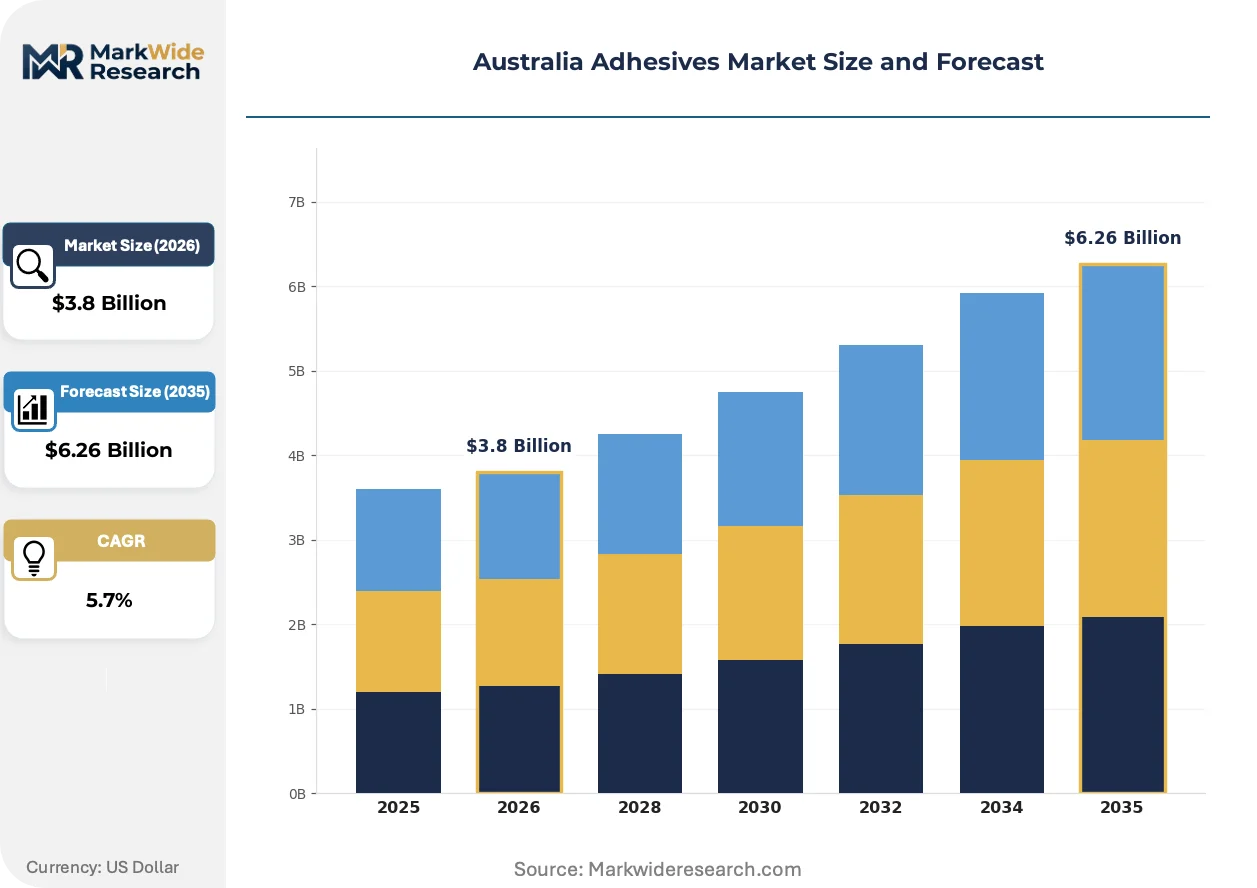
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Construction, Automotive, Electronics, Packaging Type: Polyurethane, Epoxy, Acrylic, Silicone End User: Manufacturing, Retail, Aerospace, Healthcare Formulation: Water-based, Solvent-based, Hot Melt, Reactive |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, H.B. Fuller Company, Selleys, Bostik Australia Pty Ltd, DuluxGroup Ltd., Arkema Group, AVERY DENNISON CORPORATION, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Adhesives Market Strategic Shifts
Formulation science and procurement digitization are converging to compress product development cycles and reshape how adhesive performance data reaches specification decision-makers.
Hybrid water-based polyurethane-acrylic systems is consolidating category boundaries between construction sealants and structural adhesives. Major infrastructure contractors in Sydney's commercial pipeline are specifying these platforms for curtain wall assembly, accelerating displacement of solvent-borne alternatives. The technology is consolidating supplier tiers as regional blenders without hybrid R&D capability lose access to federal project eligibility.
Australia's National Environment Protection Measure for Air Quality is tightening VOC thresholds for interior-grade products used in schools and healthcare facilities. This regulatory pressure forces reformulation of legacy acrylic and contact cements, elevating compliance costs for importers without local technical service infrastructure. New South Wales and Victoria state EPAs are enforcing these limits most aggressively, creating geographic variation in product availability.
Direct specification relationships between adhesive formulators and tier-one construction contractors are displacing traditional distributor-mediated procurement in major infrastructure tenders. Engineering firms managing Melbourne's transport manufacturing corridor now require supplier technical sign-off on structural bonding designs, compressing the role of merchant distributors. This pattern concentrates most visibly in commercial developments exceeding AUD 100 million contract value where liability exposure drives direct vendor accountability.
Australia Adhesives Market Segmentation
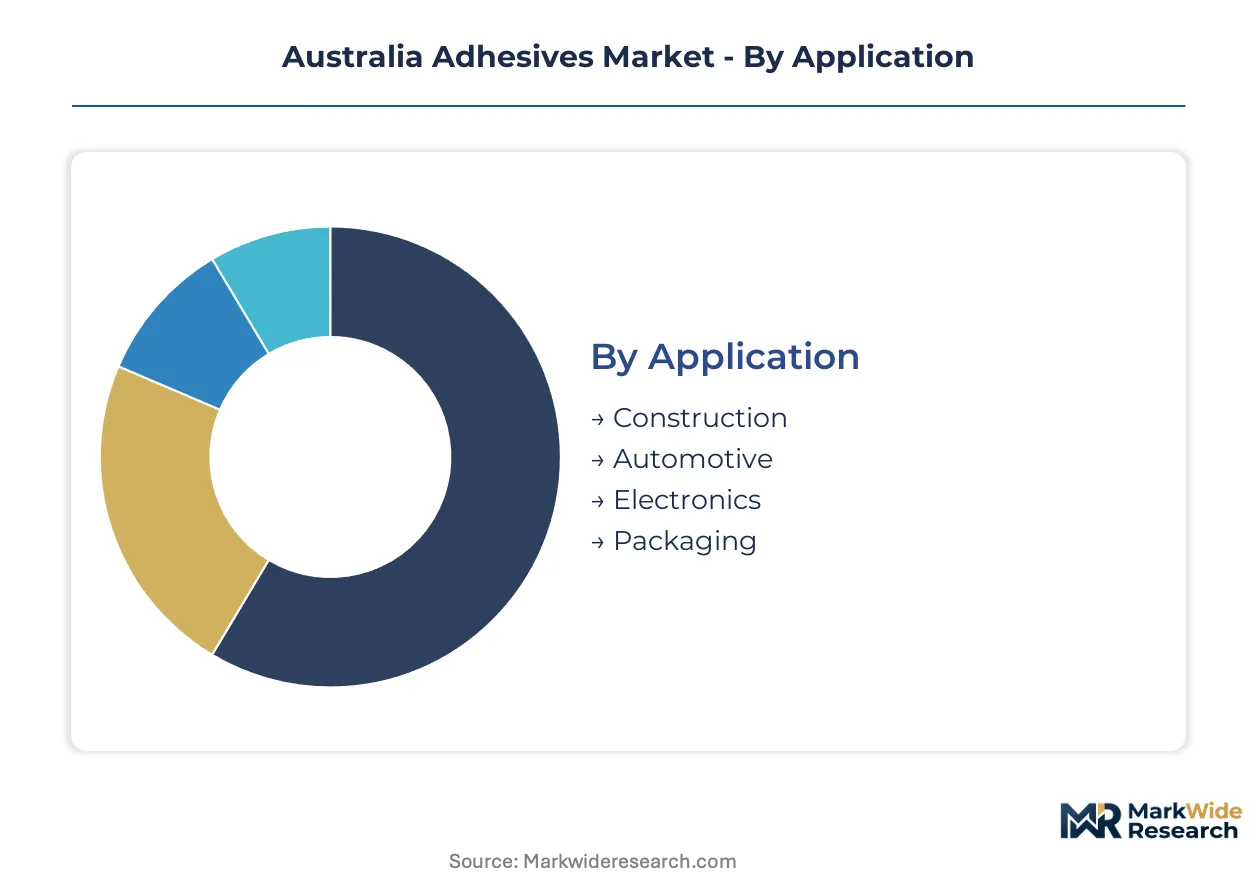
Adhesive specification in Australia fragments across formulation chemistry, application environment, and end-user procurement protocols. Each segmentation axis carries distinct regulatory burdens and margin profiles that determine supplier positioning strategies.
Application:
Construction and automotive segments face divergent approval pathways under TGA substance assessments versus state-level EPA VOC enforcement.
- Construction:Structural bonding systems for curtain wall assembly and concrete anchoring dominate procurement volumes across New South Wales and Victoria infrastructure pipelines. Sydney's commercial high-rise developments and Melbourne's transport manufacturing corridor drive specification of hybrid polyurethane-acrylic platforms that satisfy Green Star certification thresholds.
- Automotive:Reactive adhesive systems cure through polymerization mechanisms delivering thermal resistance and shear strength for powertrain assembly and interior trim bonding. Victoria's automotive clusters prioritize cure speed and engineering approval workflows over cost minimization, creating premium positioning for suppliers with localized technical service infrastructure.
- Electronics:Miniaturized device assembly demands precision dispensing compatibility and ionic purity compliance for circuit board protection.
- Packaging:Hot melt segments serve food and beverage distribution automation lines in Adelaide and Perth where line speed and substrate diversity determine specification.
Leading the category by volume: Construction. Expanding most quickly: Automotive.
Type:
Chemistry selection maps directly to performance tier and project eligibility under Australia's tightening emission protocols.
- Polyurethane:Two-part systems cure through isocyanate-hydroxyl reactions forming elastomeric bonds with exceptional impact resistance. Bostik Australia Pty Ltd competes aggressively in retail renovation channels with specialized polyurethane lines targeting DIY and contractor segments across Queensland mining infrastructure maintenance.
- Epoxy:Thermosetting resins crosslink through amine curing agents delivering rigid structural bonds exceeding engineering thresholds for heavy equipment and conveyor system assembly. Epoxy formulations face margin compression from petrochemical feedstock volatility affecting crude oil derivative costs.
- Acrylic:Legacy contact cements and pressure-sensitive systems require reformulation under National Environment Protection Measure VOC thresholds for interior-grade products.
- Silicone:RTV systems dominate sealing applications where thermal cycling resistance and UV stability determine specification in exterior glazing assemblies.
Highest margin capture: Epoxy. Steepest reformulation pressure: Acrylic.
End User:
Procurement sophistication varies from centralized manufacturing technical sign-off to distributed retail channel price sensitivity.
- Manufacturing:Tier-one construction contractors and transport assemblers demand direct supplier relationships with embedded performance data in building information modeling workflows. Engineering firms managing projects exceeding AUD 100 million contract value require vendor technical accountability compressing traditional distributor roles.
- Retail:Renovation channel procurement concentrates through merchant distributors where polyurethane line availability and point-of-sale technical support determine shelf positioning.
- Aerospace:Specialized structural bonding for composite airframe assembly demands traceable batch certification and TGA-aligned substance safety documentation.
- Healthcare:Interior-grade adhesive specifications for schools and medical facilities face aggressive VOC enforcement under New South Wales and Victoria state EPA jurisdictions.
Most concentrated buying power: Manufacturing. Most price-sensitive volume: Retail.
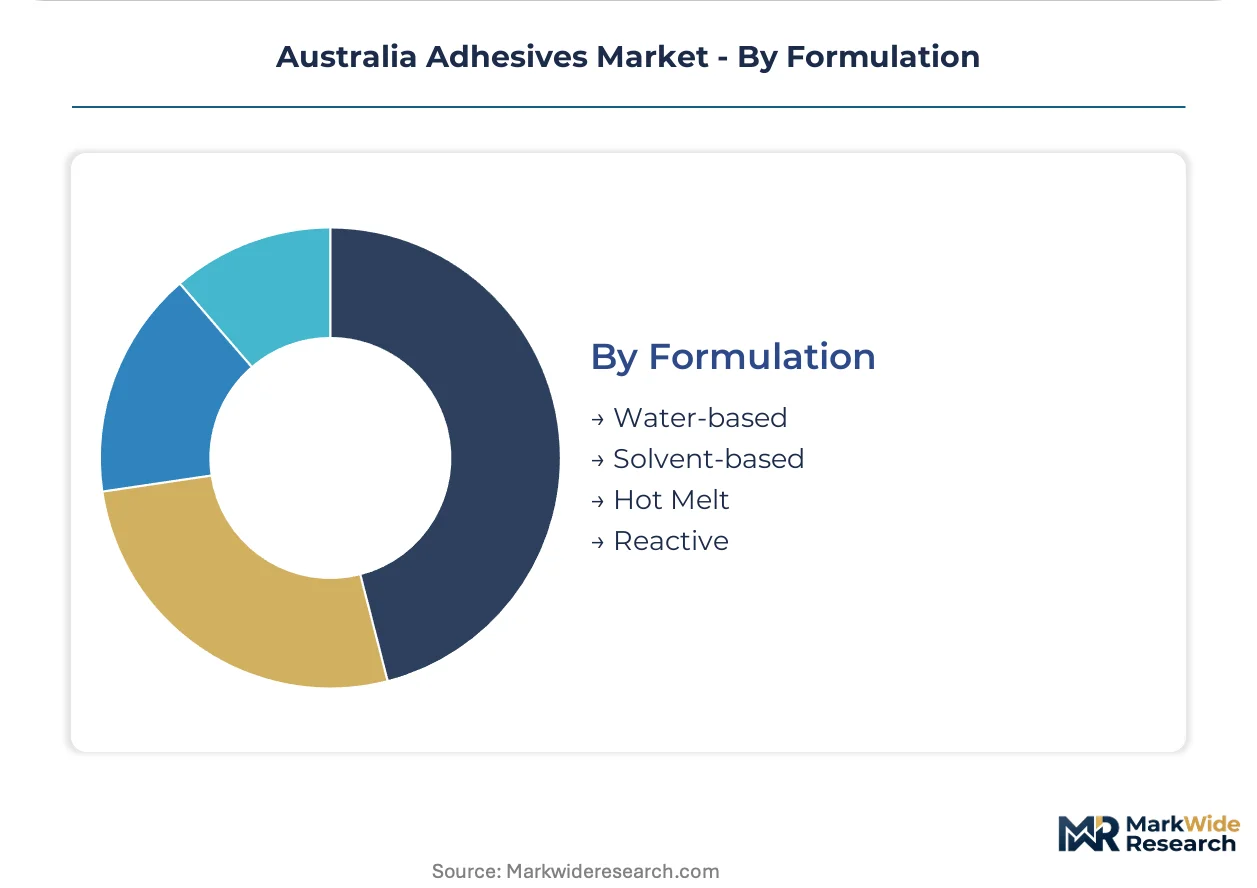
Formulation:
Water-based and reactive platforms now split the market between regulatory compliance and performance-critical applications.
- Water-based:Acrylic and polyurethane dispersions carry reduced solvent content satisfying WELS labeling requirements and Green Star procurement benchmarks. These systems face performance gaps in cold-weather construction across Tasmania and southern Victoria restricting seasonal application windows.
- Reactive:Two-component epoxy and polyurethane systems cure through chemical reaction delivering structural strength and thermal resistance for automotive and electronics applications where engineering approval determines specification wins.
- Solvent-based:Legacy formulations face displacement under National Environment Protection Measure tightening except where ambient cure speed requirements override emission constraints.
- Hot Melt:Thermoplastic adhesives solidify on cooling serving packaging automation lines with rapid bond formation and substrate versatility for food and beverage distribution networks.
Gaining share fastest: Water-based. Premium positioning: Reactive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Sydney's Aerotropolis and Special Activation Precincts are concentrating adhesive-intensive manufacturing and logistics investment through targeted infrastructure allowances and streamlined planning approvals.
New South Wales
Sydney's commercial high-rise pipeline and Parramatta's civic precinct renewal are specifying hybrid polyurethane-acrylic structural bonding systems. The state's EPA enforces National Environment Protection Measure VOC thresholds most aggressively for interior-grade products in schools and healthcare facilities. Green Star certification mandates in Barangaroo and Central Station precincts are accelerating water-based adhesive procurement.
Victoria
Melbourne's transport manufacturing corridor drives reactive adhesive demand for rail assembly and automotive powertrain bonding where cure speed determines engineering approvals. WorkSafe Victoria aligns with state EPA protocols on industrial chemical exposure limits affecting formulation facility licensing. Geelong's advanced manufacturing zone and Dandenong's assembly clusters anchor technical service infrastructure for specification-intensive applications.
Queensland
Bowen Basin mining infrastructure renewal creates underpenetrated demand for high-shear structural bonding in heavy equipment maintenance and conveyor system assembly. The state's EPA maintains less stringent VOC enforcement timelines than southern jurisdictions, preserving solvent-based product availability. Brisbane's urban renewal and Gold Coast commercial development concentrate construction adhesive procurement through merchant distribution networks.
Western Australia
Perth's food and beverage distribution automation lines sustain hot melt segment growth as packaging line speeds increase. The state's environmental regulator applies National Environment Protection Measure thresholds with modified compliance timelines reflecting remote supply chain realities. Kwinana's industrial zone and Pilbara resource project maintenance generate episodic demand for epoxy structural systems in bulk material handling equipment.
South Australia
Adelaide's packaging automation sector and emerging defense manufacturing precinct specify adhesives where substrate diversity and rapid bond formation matter. EPA South Australia coordinates with federal NICNAS requirements for industrial chemical registration without duplicative state-level substance assessments. Edinburgh's defense technology park and Osborne's naval shipbuilding hub are developing specialized bonding specifications for composite assembly.
Australia Adhesives Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where scale-driven procurement consolidation coexists with specification-intensive technical service differentiation. Market concentration is moderate, with multinational chemical groups holding federal project eligibility advantages through localized R&D infrastructure while regional blenders retain renovation channel access. Three archetypes dominate: global integrated chemical conglomerates with captive resin supply, construction-specialized technical formulators with direct contractor relationships, and retail-channel distributors with private-label blending capacity. Competitive dynamics center on backward integration into specialty monomer supply and digital specification platform deployment to compress tender qualification cycles.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA and Sika AG exemplify contrasting strategic positions. Henkel's KGaA structure reflects European corporate governance traditions while anchoring a position through global R&D network localization. Sika AG's Swiss-listed status and construction-sector specialization represent the focused technical formulator archetype. Bostik Australia Pty Ltd occupies a distinct tier as a regional operating subsidiary with concentrated retail renovation channel presence. These three entities collectively illustrate the competitive spectrum from global scale to regional execution without implying specific market share positions or strategic priorities.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| H.B. Fuller Company |
| Selleys |
| Bostik Australia Pty Ltd |
| DuluxGroup Ltd. |
| Arkema Group |
| AVERY DENNISON CORPORATION |
| Others |
Value Chain & Pricing Dynamics
Australia's National Environment Protection Measure for Air Quality gates qualified supply and premium-tier pricing access by mandating low-VOC formulation compliance for federal project eligibility. Formulators meeting state EPA thresholds in New South Wales and Victoria command pricing premiums from tier-one construction contractors, while non-compliant blenders face margin compression in renovation channels.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning, particularly for reactive epoxy and polyurethane systems serving Victoria's automotive assembly clusters where cure speed determines engineering approvals. Three-tier pricing structure across premium, standard, and economy levels separates Green Star-certified hybrid formulations from commodity water-based alternatives and legacy solvent-borne inventory. Price differentiation hinges on certification grade and technical service bundling, with NICNAS-registered suppliers capturing margin from healthcare and education sector procurement. Cost compression in solvent-based tiers is intensifying because of feedstock volatility and import concentration risk, while retail renovation channels remain most price-sensitive versus manufacturing segments prioritizing performance guarantees.
Supply Chain Analysis
Reverse-logistics flows for adhesive packaging and expired inventory return concentrate compliance burdens on Australian blenders managing NICNAS substance tracking requirements. Geographic supply concentration centers on China, South Korea, and Germany for specialty isocyanates, epoxy resins, and catalyst systems that Australian formulators draw from for localized blending operations. Raw material dependencies rest on crude oil derivatives, titanium dioxide pigments, and silane coupling agents subject to currency exposure and shipping disruption risks. Single-source vulnerability from Asian manufacturing hubs threatens continuity for reactive system monomers. Distribution runs through construction-sector merchant distributors and direct technical service relationships with tier-one contractors, with the latter compressing traditional channel roles in projects exceeding AUD 100 million contract value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as tightening VOC enforcement under the National Environment Protection Measure forces regional blenders without hybrid R&D capability toward exit or acquisition.
For Market Incumbents: Deploy backward integration into specialty monomer supply to secure margin stability against petrochemical feedstock volatility threatening epoxy and polyurethane resin costs. Henkel AG and Sika AG exemplify this lever through captive resin networks and construction-sector distribution control. Acquire regional blenders in Queensland and Western Australia to preempt new entrant positioning in underpenetrated mining infrastructure and food packaging automation segments. Certification investment in Green Star-aligned hybrid formulations defends federal project eligibility against emerging low-VOC specialists. For New Entrants and Emerging Players: Merchant distributors with private-label blending capacity offer the fastest channel to shelf positioning in retail renovation segments where Bostik Australia currently dominates polyurethane line availability. Target Queensland's Bowen Basin mining infrastructure renewal for high-shear structural bonding systems currently underpenetrated versus construction applications, where less stringent EPA timelines preserve solvent-based product windows. Digital specification platform partnerships with building information modeling workflows enable tender qualification compression without legacy distributor relationships. For Investors and Strategic Acquirers: State EPA enforcement intensity divergence between New South Wales, Victoria, and Queensland is the leading indicator that multi-jurisdiction compliance capability will determine acquisition premiums. Five-to-ten year viability favors technical formulators with localized R&D infrastructure and direct contractor relationships over pure distribution plays. Target acquisition archetype: mid-size hybrid R&D blenders with NICNAS registration capacity and Green Star certification track records. Monitor National Environment Protection Measure threshold tightening announcements for interior-grade products as the signal for accelerated solvent-based displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomer Supply | Captive resin production insulates margin stability from crude oil derivative volatility affecting epoxy and polyurethane costs. |
| Green Manufacturing Transition | Water-based and bio-sourced formulation platforms secure federal project eligibility under tightening National Environment Protection Measure thresholds. |
| Long-term Supply Agreement | Fixed-price contracts with Asian manufacturing hubs reduce currency exposure for isocyanate and catalyst imports. |
| Joint Venture | Partnerships with building information modeling platform providers embed performance data into architect specification workflows. |
| Capacity Expansion | Regional blending facilities in Queensland and Western Australia capture mining infrastructure and packaging automation demand. |
Study Parameters
Document review covered customs and trade data, Australian Bureau of Statistics construction activity indices, NICNAS chemical registration databases, and state EPA enforcement records, complemented by interviews with adhesive formulation chemists, procurement leads at tier-one construction contractors, distribution channel partners, and technical R&D directors at multinational chemical groups. Bottom-up volume modeling triangulated against top-down construction spend allocation and automotive production forecasts.
Cross-referencing historical import volumes with industry panel input established baseline demand patterns across the projection horizon. Segmentation dimensions modeled include formulation chemistry, application environment, end-user procurement sophistication, and regional regulatory enforcement intensity. CAGRs derived from elasticity-adjusted construction and manufacturing output projections, with WELS labeling adoption curves and Green Star certification penetration serving as adhesive-specific demand modifiers.
Caveats apply where National Environment Protection Measure threshold acceleration, petrochemical feedstock price spikes, or shipping disruption through Asian manufacturing hubs could materially shift the outlook. Practitioners should monitor state EPA enforcement divergence and hybrid water-based polyurethane-acrylic displacement rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Cyanoacrylate Adhesives Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
South America Acrylic Adhesives Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
Waterproof Tapes Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
Dimethylaminoethyl Acrylate Market
Adhesives & Sealants
India Adhesives Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market