
 South America Polyurethane (PU) Adhesives Market | 2026-2036
South America Polyurethane (PU) Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
South America Polyurethane (PU) Adhesives Market Analytics
Project finance for specialty chemical tolling facilities is fragmenting competitive access across Brazil and Argentina. Henkel AG & Co. KGaA leverages its regional formulation network to supply construction-grade PU adhesives to Brazilian contractors. Dow anchors its position through backward integration into polyol feedstock production at its local manufacturing complex. Sika AG competes by specializing in high-performance flexible formulations for infrastructure expansion projects.
South America polyurethane adhesives are thermosetting polymers formed from polyol and isocyanate reactions, cured through moisture, heat, or catalyst activation to achieve bond strengths exceeding 2,000 psi on substrates including concrete, metal, and engineered wood. Their primary industrial purpose centers on structural bonding where flexibility, impact resistance, and gap-filling capability outperform epoxy or acrylic alternatives. Single component systems dominate volume consumption in construction applications due to simplified on-site application and reduced labor training requirements. Water-based formulations represent the fastest-expanding product category as Brazilian footwear manufacturers and Argentine furniture exporters reformulate to meet tightening workplace exposure limits. Flexible formulation grades command margin premiums in automotive seating and interior trim assembly where vibration damping properties determine specification approval.
Brazil's ANVISA regulates workplace chemical exposure thresholds while Argentina's Secretariat of Industry enforces labeling and import registration protocols for adhesive raw materials. REACH-aligned substance restrictions from European trading partners indirectly shape export-compliant product development across regional manufacturers. Stakeholders must monitor pending Mercosur chemical harmonization proposals and pre-position formulation registrations before bilateral technical barriers consolidate into unified bloc standards.
Market Dynamics
Brazil's ANVISA and Argentina's chemical regulators are tightening VOC emission thresholds for industrial adhesives, forcing converters to abandon solvent-based systems and rebuild formulation capabilities around water-borne and hot-melt PU chemistries.
Growth Catalysts
- Automotive lightweighting mandates:Brazilian and Argentine OEMs are expanding bonded assembly lines to replace mechanical fasteners, driving specification-grade PU adhesive demand for structural bonding applications.
- REACH-aligned export compliance:European trading partners enforce substance restrictions on imported finished goods, compelling regional footwear and furniture manufacturers to reformulate with compliant PU systems.
- São Paulo industrial corridor concentration:Domestic toll manufacturers cluster around Brazil's footwear and furniture production hubs, reducing logistics costs and technical service response times for formulated adhesive supply.
Market Restraints
- Isocyanate feedstock volatility:MDI and TDI prices fluctuate with global petrochemical cycles, compressing margin visibility for regional formulators lacking backward integration into polyol production.
- Import dependency for specialty additives:Catalysts, surfactants, and chain extenders concentrate supply risk with Asian and European specialty chemical producers, exposing Brazilian converters to currency and shipping cost swings.
- Cure speed limitations in humid climates:Single-component moisture-cure systems face extended tack-free times during Brazil's rainy season, limiting productivity in construction applications versus faster-setting epoxy alternatives.
Strategic Opportunities
- Argentine furniture export corridor:Buenos Aires province manufacturers serving North American retailers present untapped demand for low-VOC, high-heat-resistance PU adhesives meeting CARB Phase II standards.
- Mercosur chemical harmonization:Pending unified bloc standards will streamline cross-border formulation registrations, enabling toll manufacturers to scale production across Brazil, Argentina, Paraguay, and Uruguay without redundant compliance costs.
- Hybrid PUR-hot melt systems:Convergence of reactive polyurethane technology with conventional hot-melt application equipment opens retrofit opportunities in Argentine automotive seating plants seeking energy-efficient bonding processes.
Industry Challenges
- Formulation chemist scarcity:Brazilian technical universities produce limited graduates with isocyanate handling and reactive polymer design expertise, forcing manufacturers to recruit from European or North American talent pools.
- ANVISA registration timelines:New adhesive substance approvals require 18-24 month toxicological review cycles, delaying product launches and locking inventory positions ahead of regulatory certainty.
- Legacy equipment incompatibility:Water-based PU systems demand stainless steel storage and heated transfer lines incompatible with existing solvent-based infrastructure at small and mid-sized converter facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Polyurethane (PU) Adhesives Market |
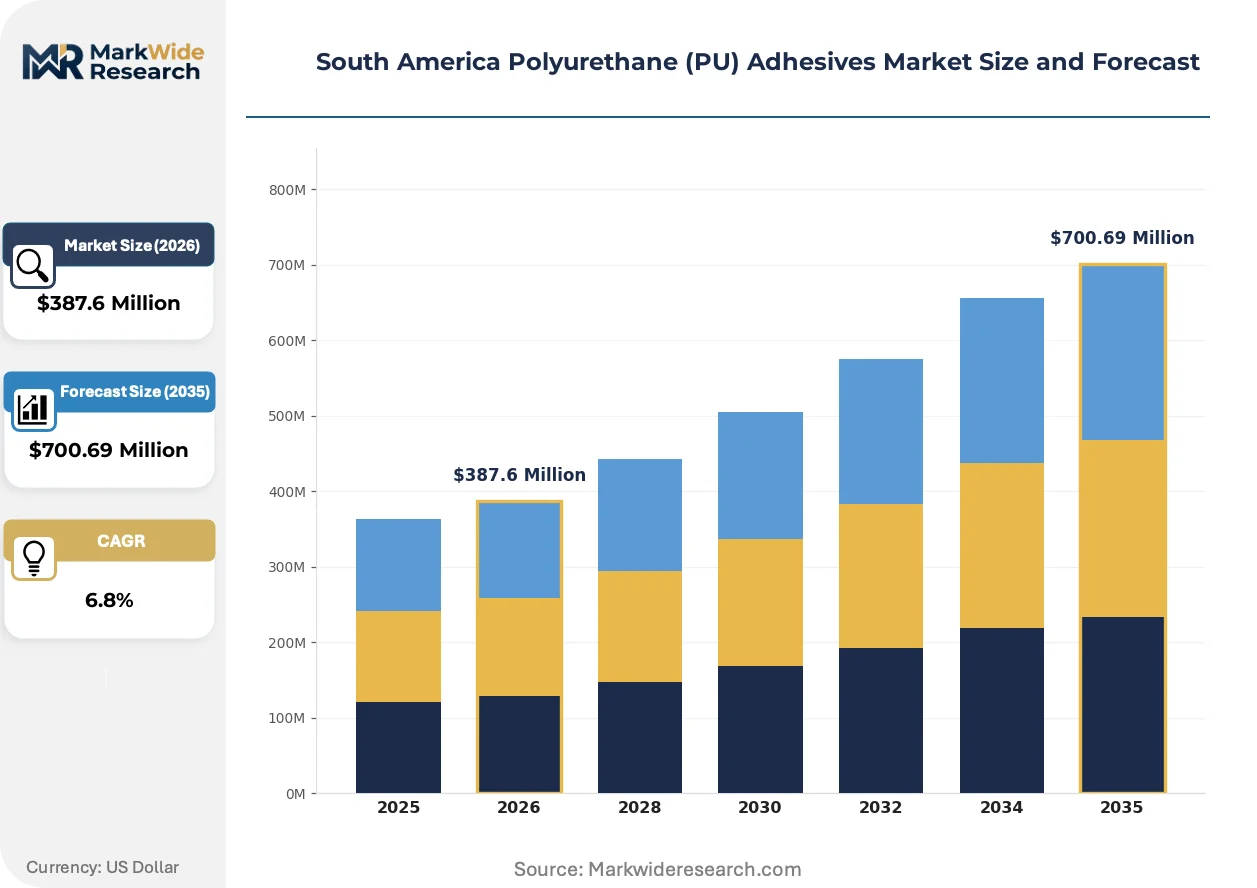
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Component, Multi Component, Water-Based, Solvent-Based Application: Construction, Automotive, Footwear, Furniture Formulation: Flexible, Rigid, High Performance, Low Viscosity End User: OEMs, Manufacturers, Contractors, Retailers |
| Companies Covered | 3M, Arkema Group, Dow, H.B. Fuller, Henkel AG & Co. KGaA, Sika AG, Huntsman International LLC, Avery Dennison Corporation, Covestro AG, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Polyurethane (PU) Adhesives Market Evolving Landscape
Reactive hot-melt polyurethane technology is penetrating South American automotive and furniture assembly lines, displacing conventional EVA and PO-based systems with superior heat resistance and structural integrity.
Two-component water-borne PU systems are rendering obsolete solvent-borne contact adhesives in Brazilian footwear manufacturing. São Paulo state tanneries and assembly plants adopted these systems between 2022 and 2024 to meet ANVISA workplace exposure limits. The shift compresses volatile organic compound emissions by over ninety percent while maintaining the peel strength specifications required for leather-rubber bonding.
Argentina's Secretariat of Industry enacted mandatory GHS-aligned labeling and import registration protocols for adhesive raw materials in 2023. The regulation forces toll manufacturers to requalify supply chains and document substance volumes for cross-border shipments. Brazilian exporters to Argentina now pre-register formulations with Buenos Aires customs authorities to avoid port detention and demurrage costs.
Consolidated procurement by multinational automotive Tier 1 suppliers is displacing fragmented spot purchasing across Brazilian OEM supply chains. Magna, Faurecia, and Lear Corporation now specify approved adhesive suppliers through global framework agreements, bypassing regional distributor networks. This concentration is most visible in São Paulo state's ABC automotive cluster, where local formulators compete for technical qualification rather than price leadership.
South America Polyurethane (PU) Adhesives Market Segmentation
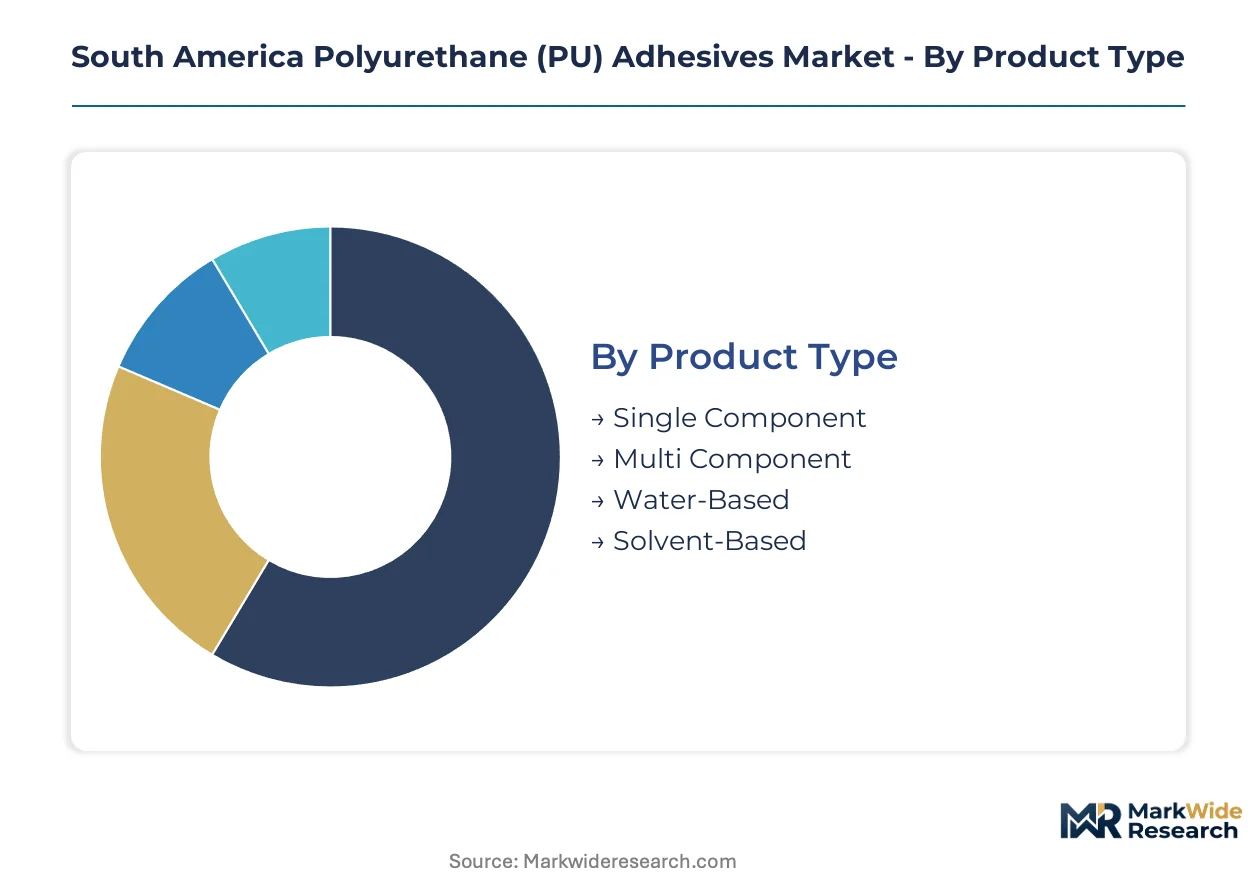
Polyurethane adhesive purchasing patterns diverge sharply across formulation chemistry and end-use specifications. Brazilian and Argentine buyers prioritize cure speed and VOC compliance over price in regulated applications, while spot markets reward volume flexibility in commodity construction grades.
Product Type:
Single-component systems turn inventory fastest in construction spot markets, while water-based formulations require longer qualification cycles but lock in multi-year supply agreements.
- Single Component:Moisture-cure and heat-activated systems dominate Brazilian construction sites where labor training is minimal. São Paulo contractors specify these grades for tilt-up concrete panel bonding to compress installation schedules during dry season windows.
- Water-Based:Emulsion PU systems carry ANVISA-compliant toxicity profiles that footwear manufacturers in Franca and Nova Serrana now mandate. Argentine furniture exporters to California adopt these formulations to satisfy CARB Phase II emission thresholds without sacrificing heat resistance.
- Multi Component:Two-part systems enable precise pot-life control for automotive structural bonding at Brazilian OEM plants.
- Solvent-Based:Declining share concentrates in legacy furniture repair and aftermarket automotive applications where regulatory enforcement remains uneven.
Single Component dominates installed base. Water-Based is where expansion concentrates.
Application:
Automotive and construction applications absorb the highest absolute volumes, yet footwear and furniture segments drive the most frequent formulation reformulation cycles as export compliance standards tighten.
- Construction:Structural bonding of insulated metal panels and engineered wood I-joists consumes bulk PU adhesive volumes across Brazil's residential and commercial building sectors. Argentine infrastructure projects specify flexible formulations for bridge deck waterproofing membranes that must accommodate thermal cycling.
- Footwear:Leather-rubber sole attachment in São Paulo state tanneries demands peel strengths exceeding leather substrate failure points. Water-borne systems displaced solvent contact adhesives here between 2022 and 2024, cutting VOC emissions while maintaining bonding integrity.
- Automotive:OEMs in São Paulo's ABC cluster specify PU adhesives for lightweighting initiatives replacing welded and riveted joints.
- Furniture:Buenos Aires province manufacturers serving North American retailers require low-VOC, high-heat-resistance grades for upholstered frame assembly.
Construction commands the largest volume position. Footwear exhibits the steepest expansion trajectory as regulatory deadlines force system conversions.
Formulation:
Flexible grades carry margin premiums in vibration-critical applications, while rigid formulations compete on price in static structural bonding where epoxy alternatives threaten substitution.
- Flexible:Elastomeric PU adhesives absorb dynamic loads in automotive seating assembly and building expansion joints. Brazilian bus manufacturers specify these grades for floor panel bonding to reduce noise transmission and improve crash energy management.
- High Performance:Engineered formulations for extreme temperature cycling and chemical exposure command specification control in Argentine oilfield equipment manufacturing and Brazilian chemical processing infrastructure.
- Rigid:High-modulus systems serve static load-bearing applications in engineered wood and composite panel fabrication.
- Low Viscosity:Penetrating grades enable thin-film bonding of porous substrates in furniture veneer and automotive trim applications.
Flexible formulations anchor premium pricing tiers. High Performance segments are gaining share fastest as infrastructure specifications tighten.
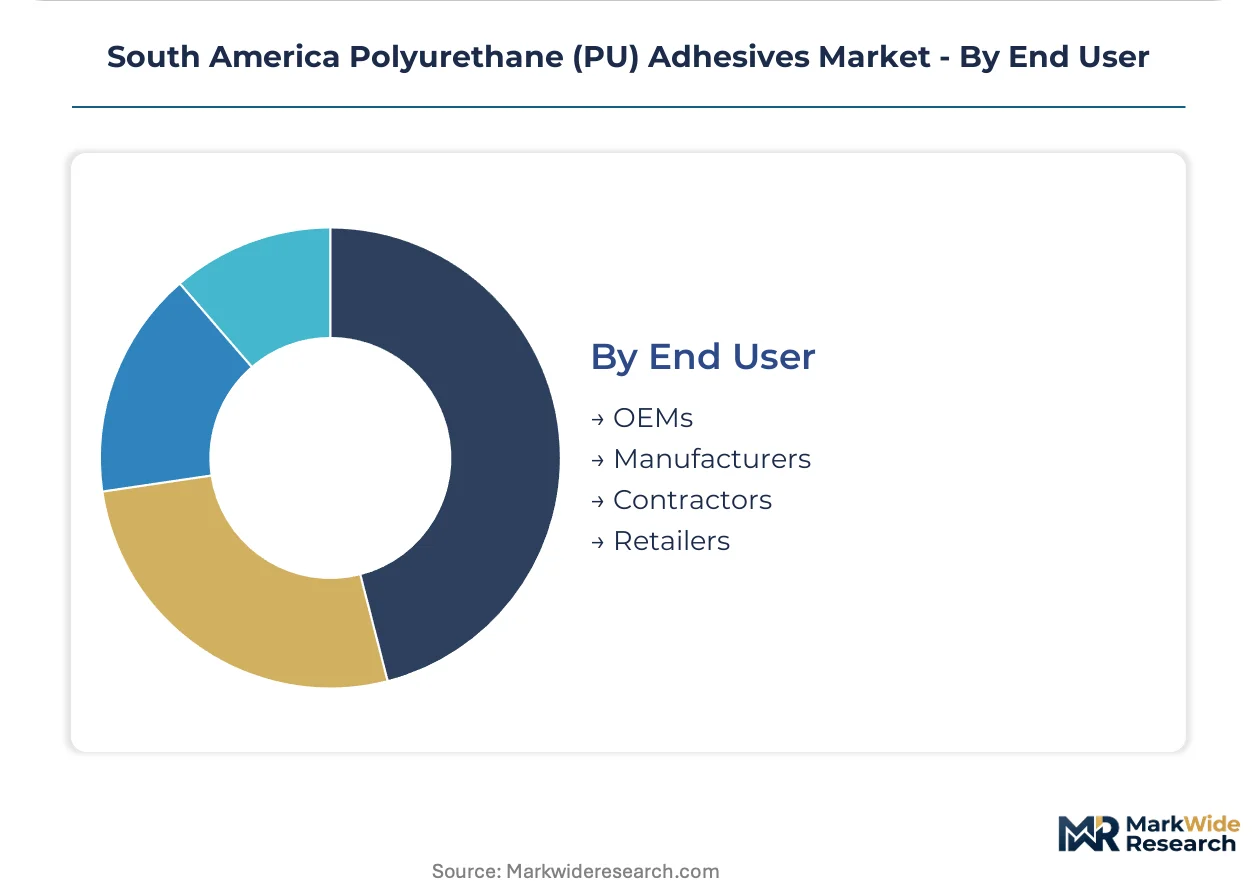
End User:
OEMs and multinational manufacturers consolidate procurement through global framework agreements, while contractors and retailers fragment purchasing across spot markets and distributor networks.
- OEMs:Magna, Faurecia, and Lear Corporation specify approved adhesive suppliers through centralized technical qualification programs. These agreements bypass regional distributors and lock volume commitments to qualified Brazilian formulators with IATF certification.
- Manufacturers:Mid-sized footwear and furniture producers in São Paulo and Buenos Aires provinces rely on toll manufacturers for customized formulation blending and technical service support.
- Contractors:Construction applicators purchase through distributor networks with price-sensitive spot buying patterns.
- Retailers:Small-volume hardware and aftermarket channels stock commodity-grade single-component systems for DIY and repair applications.
OEMs dominate specification control. Manufacturers represent the most dynamic expansion segment as export compliance requirements multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for specialty additives concentrates supply risk with Asian and European producers, while Brazilian and Argentine formulators seek to rebalance trade flows through regional toll manufacturing partnerships and backward integration into polyol production.
Brazil
Automotive OEMs in São Paulo's ABC cluster expand bonded assembly lines to reduce vehicle weight and improve crash performance. ANVISA tightens VOC emission standards for industrial adhesives, pushing converters toward water-based PU systems. The São Paulo industrial corridor concentrates demand, where footwear and furniture clusters source formulated adhesives from domestic toll manufacturers.
Argentina
Buenos Aires province furniture manufacturers serving North American retailers drive specification-grade demand for low-VOC, high-heat-resistance adhesives. The Secretariat of Industry enforces GHS-aligned labeling and import registration protocols for adhesive raw materials. Automotive seating plants in Córdoba province evaluate hybrid PUR-hot melt systems for energy-efficient bonding process retrofits.
Chile
Infrastructure expansion projects in Santiago and Valparaíso specify flexible PU formulations for bridge deck waterproofing membranes that accommodate thermal cycling. The national chemical regulator monitors REACH-aligned substance restrictions from European trading partners. Mining equipment manufacturers in Antofagasta region adopt high-performance grades for extreme temperature and chemical exposure applications.
Colombia
Construction activity in Bogotá and Medellín absorbs bulk volumes of single-component moisture-cure systems for tilt-up concrete panel bonding. The national environmental authority implements workplace chemical exposure thresholds modeled on Brazilian ANVISA standards. Coffee processing and agricultural equipment fabricators in the Coffee Triangle region source rigid formulations for composite panel fabrication.
Peru
Lima-based contractors purchase construction-grade PU adhesives through distributor networks with price-sensitive spot buying patterns. The national health authority develops chemical registration protocols for imported adhesive formulations. Mining infrastructure projects in the Andean region specify high-performance grades for ore processing equipment assembly.
South America Polyurethane (PU) Adhesives Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling feedstock access and formulation IP. The vendor base consolidates around three strategic tiers: multinational chemical conglomerates with backward integration into polyol production, regional toll manufacturers with customized blending capabilities, and specialized distributors serving spot construction markets. Competitive moves concentrate on capacity expansion in water-based formulation lines and strategic partnerships to secure isocyanate supply agreements.
Among the multinational chemical conglomerates, Dow anchors its position through backward integration into polyol feedstock production at its local manufacturing complex. Henkel AG & Co. KGaA leverages its regional formulation network to supply construction-grade PU adhesives. Sika AG occupies a position specializing in high-performance flexible formulations for infrastructure expansion projects.
| Leading Market Players |
|---|
| 3M |
| Arkema Group |
| Dow |
| H.B. Fuller |
| Henkel AG & Co. KGaA |
| Sika AG |
| Huntsman International LLC |
| Avery Dennison Corporation |
| Covestro AG |
| Others |
Value Network & Pricing Analysis
Chinese and German specialty chemical producers dominate catalyst and surfactant supply, concentrating margin capture upstream while Brazilian toll manufacturers compete on formulation service premiums downstream. This concentration forces regional converters to absorb currency volatility and shipping cost swings, compressing blended margins at the formulation tier.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—IATF-automotive versus commodity construction—and volume scale with annual offtake commitments. Cost compression in standard grades is intensifying because MDI and TDI feedstock volatility transfers directly from Asian petrochemical cycles. Contractors and small retailers exhibit highest price sensitivity, while multinational OEMs prioritize technical qualification over unit cost.
Supply Chain Analysis
Domestic toll manufacturers in Brazil's São Paulo industrial corridor and Buenos Aires province hold formulation capacity for customized blending. Raw material dependencies center on MDI isocyanates from China and Germany, polyol feedstocks from Dow's local complex, and specialty additives from European producers. Single-source vulnerability concentrates in catalyst supply from Asian producers. Distribution runs through authorized distributor networks for construction spot markets and direct technical service agreements for OEM accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based formulation mandates are disrupting competitive positioning, creating acquisition opportunities for converters with ANVISA pre-registered product lines. This regulatory inflection compresses legacy solvent-based capacity values while premiumizing compliant formulation assets.
For Market Incumbents: Build certification moats through IATF automotive qualification and ANVISA substance pre-registration. Secure long-term isocyanate supply agreements with Asian producers to buffer feedstock volatility. Acquire distressed solvent-based toll manufacturers in São Paulo state to convert capacity toward water-based lines before regulatory deadlines harden. For New Entrants and Emerging Players: Argentine furniture exporters to California represent underpenetrated demand for CARB Phase II-compliant, high-heat-resistance grades. Target hybrid PUR-hot melt retrofits in Córdoba automotive seating plants seeking energy-efficient bonding processes. Enter through technical partnership with established Brazilian toll manufacturers rather than greenfield capacity. For Investors and Strategic Acquirers: Capital is best deployed toward water-based formulation specialists with ANVISA registration pipelines and established OEM technical service relationships. Long-term viability favors assets positioned for Mercosur chemical harmonization and unified bloc standard compliance. Monitor ANVISA registration approval timelines as the signal for competitive capacity availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Dow's captive feedstock supply anchors margin stability against MDI price cycles. |
| Water-Based Formulation Capacity Expansion | ANVISA-compliant lines capture footwear and furniture contract migrations from solvent systems. |
| Long-Term Isocyanate Supply Agreement | Fixed-price contracts with Chinese producers reduce currency exposure for Brazilian toll manufacturers. |
| Joint Venture with Regional Toll Manufacturer | Partnerships accelerate ANVISA registration access and technical service footprint in São Paulo corridor. |
| Hybrid PUR-Hot Melt Technology Licensing | Energy-efficient bonding systems penetrate Argentine automotive seating retrofit opportunities. |
Research Methodology
Cross-validation between primary interviews with plant managers at Brazilian toll manufacturers and secondary customs trade data anchors the qualitative findings. Procurement leads at automotive OEMs, distribution channel partners in São Paulo and Buenos Aires, and technical R&D directors at multinational chemical suppliers provided operational perspective. Secondary sources include ANVISA registration databases, SEC 10-K filings of listed chemical conglomerates, and ACC regional production reports. Bottom-up volume estimates from end-use consumption patterns were reconciled with top-down capacity assessments across the analysis window.
Calibration against historical price series and regulatory implementation timelines shaped the projection framework. Segmentation dimensions modeled include formulation chemistry, application end-use, flexibility grade, and regional production hub. CAGRs were derived from regression analysis of volume growth rates against macroeconomic drivers and regulatory phase-in schedules. Feedstock price elasticity and OEM content-per-vehicle assumptions for automotive lightweighting served as industry-specific forecast inputs throughout the modeling period.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian chemical conglomerates or accelerated Mercosur harmonization would shift outcomes. Quarterly review of ANVISA registration approval velocities and MDI import price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Asia-Pacific Laminated Adhesives Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Global Construction Adhesives and Sealants Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Floor Adhesive Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Global MS Polymer Adhesives Market
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
EMEA Epoxy Adhesives Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
De-Seamable Adhesives Market
Adhesives & Sealants
UV-Curable Adhesives Market