
 Floor Tile Adhesive Market | 2026-2036
Floor Tile Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Tile Adhesive Market Analytics
Commercial contractors are bifurcating demand away from traditional residential installers as hospitality and retail fit-out projects specify higher-performance systems. Sika AG leverages its European formulation expertise to dominate specification-driven commercial channels. Mapei S.p.A. sustains manufacturing scale across multiple continents through vertically integrated raw material sourcing. Pidilite Industries anchors the South Asian contractor segment with localized distribution networks and technical service support.
Floor tile adhesive comprises cementitious, polymer-modified, or resin-based compounds formulated to bond ceramic, porcelain, stone, and glass tiles to substrates, with open time, shear strength, and deformability as critical performance parameters. Thin-set formulations occupy the largest volume share due to cost efficiency across standard residential and light commercial applications, while epoxy systems command premium positioning in industrial and wet-environment installations where chemical resistance and zero water absorption prove mandatory. Water-based technology leads environmental compliance trajectories as regulatory pressure on solvent emissions intensifies across developed markets.
REACH in Europe and EPA regulations in the United States constrain solvent-based adhesive formulations, redirecting R&D investment toward low-VOC and zero-emission product platforms. India's BIS certification requirements for construction chemicals create formal quality barriers that favor organized manufacturers over unregulated regional suppliers. ISO 13007 tile adhesive standards govern international trade and product classification, influencing procurement specifications for multinational construction firms. Stakeholders must monitor evolving regional chemical restrictions and certification harmonization to align product portfolios with diverging compliance timelines.
Market Dynamics
Water-based adhesive formulations are capturing specification share from solvent-based systems as REACH and EPA emission limits harden compliance thresholds across manufacturing footprints. This compositional pivot is redrawing raw material procurement patterns and reformulation investment priorities for compounders serving construction end-uses.
Growth Catalysts
- India's Housing for All schemes:Government-subsidized residential construction in Maharashtra and Karnataka corridors is accelerating bulk procurement of cementitious thin-set adhesives by state-appointed contractors.
- REACH VOC phase-down:ECHA's tightening volatile organic compound limits are forcing specification upgrades in commercial hospitality fit-outs across Germany, France, and the Netherlands.
- Large-format porcelain tiles:The shift toward 1200mm x 2400mm slab dimensions in premium residential kitchens is demanding polymer-modified adhesives with enhanced deformability and extended open time.
Market Restraints
- Portland cement price volatility:Energy-intensive clinker production costs in China and Vietnam are transmitting input cost instability to cementitious adhesive margins.
- Specialty polymer supply concentration:Redispersible polymer powder production clusters in Germany and South Korea create geographic concentration risk for modified adhesive compounders.
- Epoxy system curing limitations:Temperature-sensitive cure kinetics restrict year-round application of high-performance resin adhesives in Nordic and Alpine climates.
Strategic Opportunities
- Indonesia's Trans-Java infrastructure corridor:Railway and metro station construction is creating specification demand for rapid-setting adhesives in high-traffic commercial environments.
- Biopolymer binder convergence:Bio-based polyurethane and modified starch technologies are opening pathways to zero-petroleum formulations for LEED-certified projects.
- E-commerce technical distribution:Digital procurement platforms with embedded substrate-matching algorithms are capturing contractor specification research phases ahead of traditional distributor relationships.
Industry Challenges
- ISO 13007 certification timelines:Extended third-party testing protocols for C2TES1 classification are delaying product launches and freezing working capital in qualification pipelines.
- Substrate moisture assessment skill gaps:Inadequate field training on calcium carbide testing and relative humidity measurement is causing bond failure callbacks and warranty disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Tile Adhesive Market |
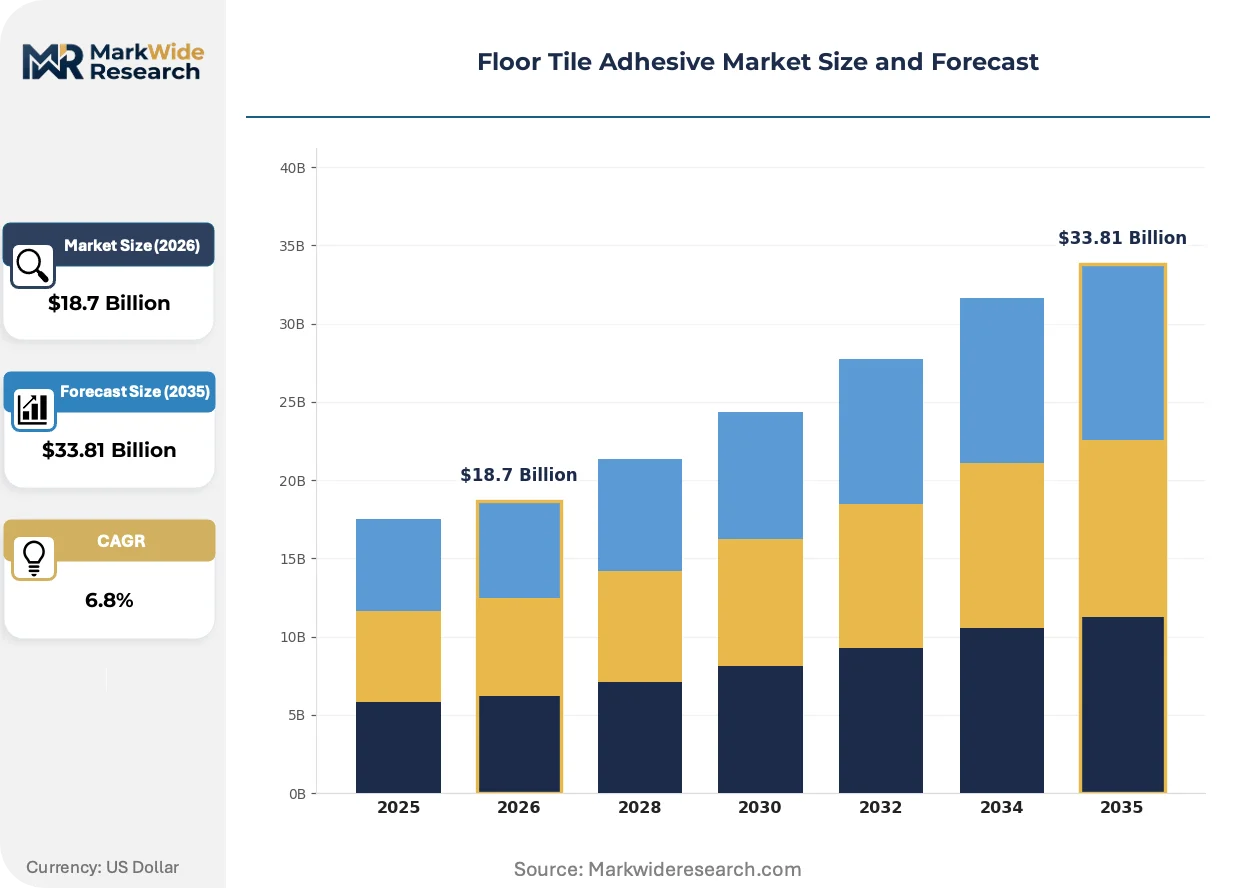
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-set, Medium Bed, Epoxy, Pressure Sensitive Application: Residential, Commercial, Industrial, Institutional Technology: Water-Based, Solvent-Based, Hybrid, Pre-Mixed End User: Contractors, DIY Enthusiasts, Architects, Designers |
| Companies Covered | Henkel AG, Sika AG, H.B. Fuller, Arkema, Mapei S.p.A., Wacker Chemie AG, 3M, Laticrete International, Pidilite Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Tile Adhesive Market Evolving Landscape
Reformulation chemistry and digital specification tools are compressing the traditional product-to-application feedback loop. Manufacturers now embed performance data directly into procurement platforms while advancing bio-based binder technologies.
Hybrid polymer-cement adhesives with enhanced flexibility and reduced shrinkage are supplanting conventional unmodified thin-set mortars in porcelain slab installations. Commercial contractors in hospitality and healthcare verticals are specifying these systems for substrates with elevated deflection. The shift is compressing demand for economy-grade cementitious products in specification-driven channels.
EPA's National Emission Standards for Hazardous Air Pollutants for industrial adhesives manufacturing are tightening methylene chloride and perchloroethylene discharge limits. U.S. compounders are retooling production lines to capture and recycle solvent streams or convert entirely to aqueous processing. Water-based epoxy and acrylic systems are capturing share in industrial flooring segments previously dominated by solvent-cure formulations.
Specification decisions are migrating from distributor showrooms to mobile substrate-diagnostic applications that algorithmically match adhesive class to project conditions. Large commercial contractors in the United Kingdom and Australia are adopting these digital tools to standardize field procurement and reduce specification errors. The shift is compressing the influence of traditional distributor technical representatives in early-stage project phases.
Floor Tile Adhesive Market Segmentation
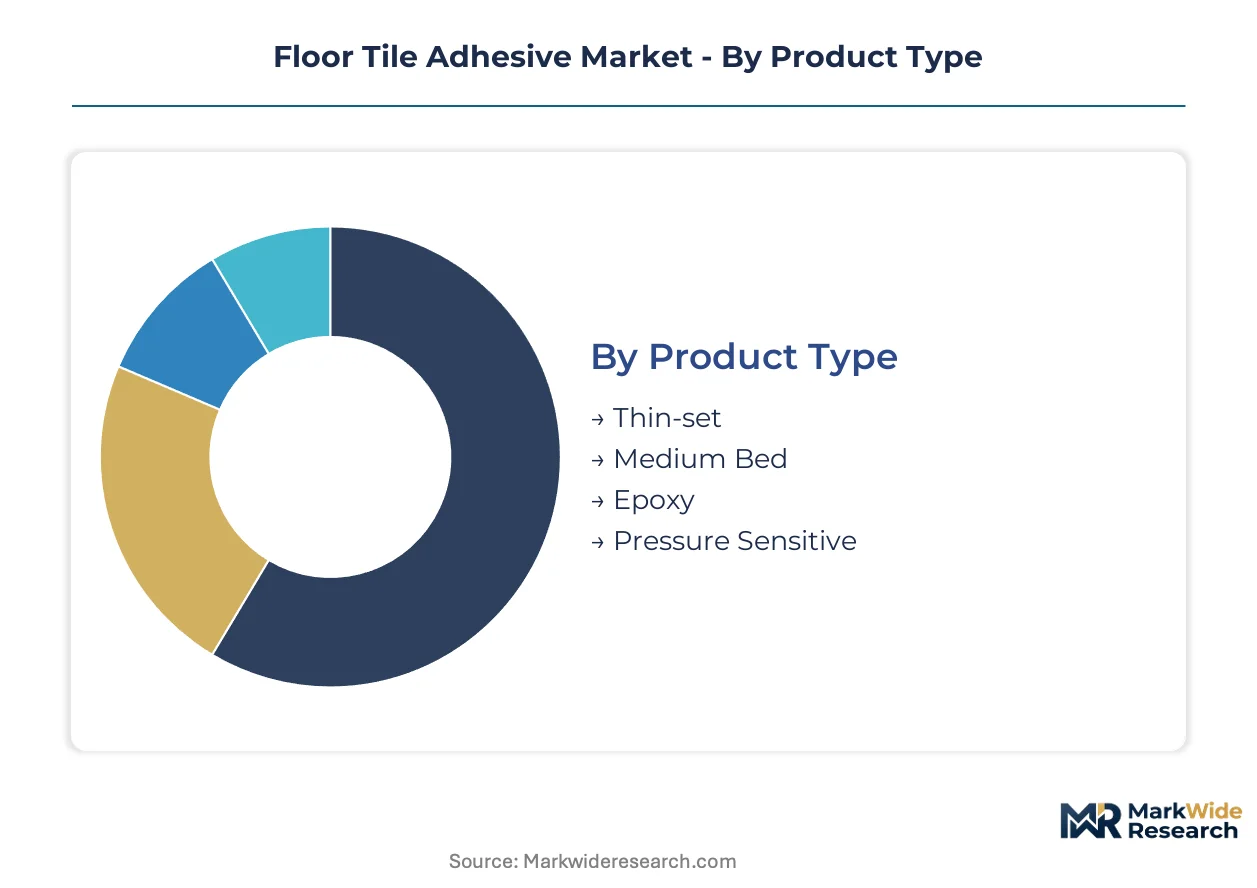
Segmentation in floor tile adhesives reveals how specification authority, substrate complexity, and regulatory pressure fragment procurement patterns across construction channels. Understanding these divides exposes where formulation investments concentrate and which customer types drive premium pricing.
Product Type:
Channel flow diverges sharply: thin-set and medium bed formulations dominate distributor and big-box retail, while epoxy systems route through specification-driven commercial distributors and direct contractor sales.
- Thin-set:Cementitious or polymer-modified powders mixed on-site deliver cost-efficient bonding for standard ceramic and porcelain installations. Demand concentrates in India's Housing for All corridors where state contractors bulk-procure economy-grade bags for high-volume residential tiling.
- Epoxy:Two-part resin systems cure to zero water absorption and complete chemical resistance. Industrial flooring contractors in Germany and the Netherlands specify these for pharmaceutical cleanrooms and food processing facilities where REACH VOC limits have eliminated solvent alternatives.
- Medium Bed:Thicker-bed formulations accommodate uneven substrates and large-format tiles without lippage. Preferred by commercial contractors for hospitality lobby installations.
- Pressure Sensitive:Peel-and-stick systems for vinyl and carpet tile applications in rapid-turnover retail fit-outs. Limited penetration in wet-area specifications.
By volume, thin-set leads. By growth pace, epoxy is climbing the fastest.
Application:
Margin structures invert across these segments: residential runs on price-competitive distributor brands, while commercial and institutional command specification premiums through certified installer networks.
- Residential:Kitchen and bathroom renovations drive recurring demand, with polymer-modified systems gaining share for porcelain slab installations. Urban India's apartment upgrades and Maharashtra's affordable housing schemes concentrate procurement volume.
- Commercial:Hospitality, retail, and office fit-outs specify high-performance systems with extended open times and deformability. ECHA's REACH phase-down is redirecting German and French hospitality projects toward water-based epoxies.
- Industrial:Chemical resistance and thermal cycling tolerance dominate specifications. Food processing plants in the Netherlands and automotive facilities in Germany anchor demand.
- Institutional:Healthcare and education projects require antimicrobial additives and rapid-setting formulations to minimize facility downtime. UK's NHS hospital refurbishments specify ISO 13007-certified systems.
Residential captures the largest volume share. Commercial delivers the steepest margin expansion.
Technology:
Environmental compliance timelines are fragmenting technology adoption: water-based systems capture specification share in regulated markets while solvent-based persists where enforcement lags.
- Water-Based:Acrylic and polyurethane dispersions eliminate VOC emissions during application. EPA's National Emission Standards and REACH restrictions are accelerating U.S. and European conversion from solvent systems.
- Solvent-Based:Rapid initial tack and moisture tolerance sustain niche demand in unregulated regional markets and cold-climate applications. Facing structural decline in developed economies.
- Hybrid:Silane-modified polymer systems combine moisture curing with water-based cleanup. Gaining traction in Nordic climates where temperature-sensitive cure kinetics limit pure epoxy use.
- Pre-Mixed:Bucket-dispensed pastes eliminate on-site mixing errors and accelerate DIY installation. Australian and UK retail channels report strongest uptake among homeowner renovators.
Water-based formulations dominate new specification. Hybrid technology is gaining share fastest in climate-constrained geographies.
End User:
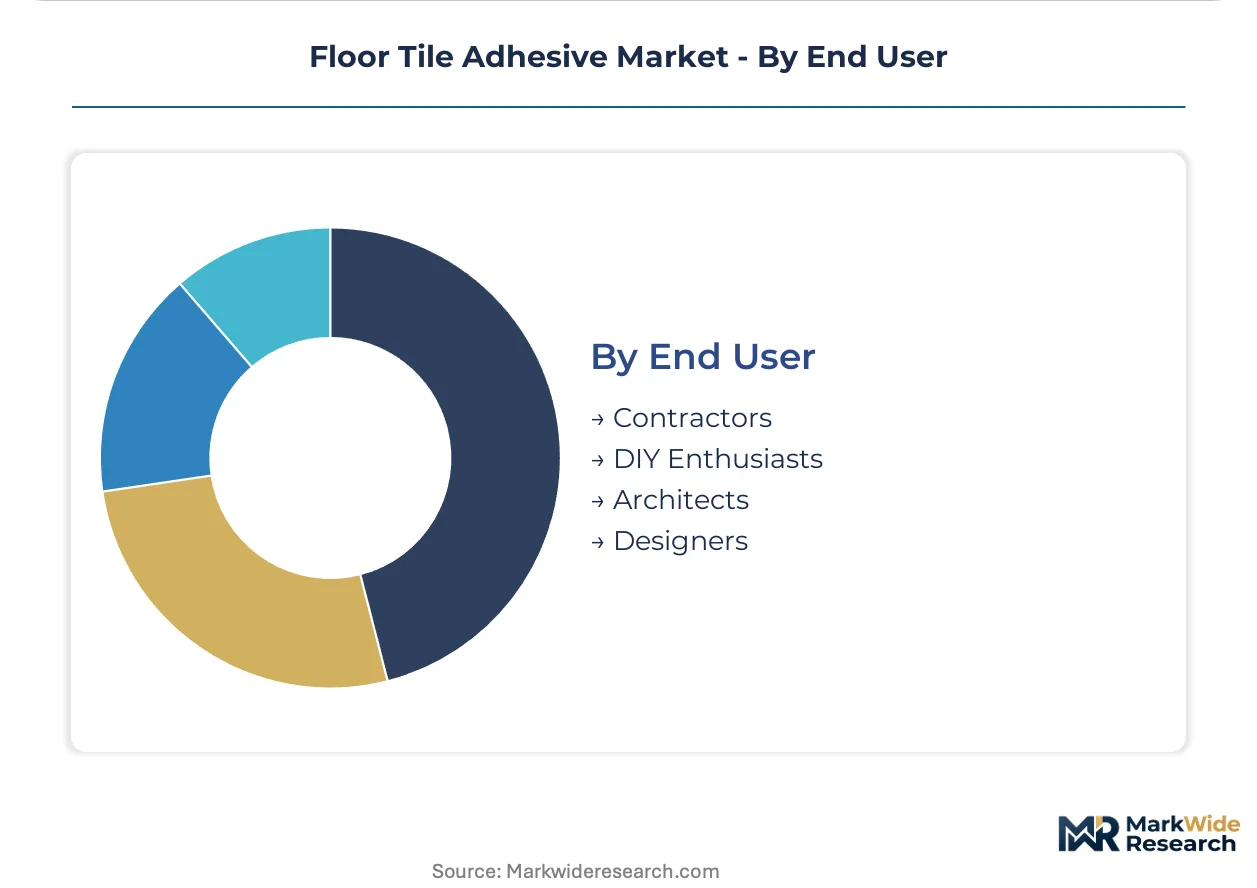
Specification authority cascades differently: architects and designers set performance requirements early, contractors control procurement volume, and DIY enthusiasts drive retail format innovation.
- Contractors:Commercial tiling specialists and residential installation crews purchase through distributor accounts with volume pricing and technical support. India's organized contractor segment favors localized brands with field service networks.
- DIY Enthusiasts:Home improvement retailers capture this segment with pre-mixed, ready-to-use formulations and substrate-matching mobile applications. UK and Australian digital procurement platforms embed algorithmic specification tools.
- Architects:Specification writers in commercial and institutional channels mandate performance classifications under ISO 13007. German and Dutch hospitality projects increasingly require C2TES1-certified deformable adhesives.
- Designers:Interior design consultants influence premium residential and boutique commercial selections, prioritizing aesthetic compatibility with large-format porcelain and natural stone.
Contractors move the highest volume. Architects are pulling specification toward certified performance tiers most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German adhesive compounders export polymer-modified thin-set formulations to Dutch and French commercial contractors, establishing a Rhine-Ruhr-to-Randstad trade corridor that channels high-performance products into hospitality fit-out projects.
United States
Residential renovation contractors in Florida and California drive bulk procurement of cementitious adhesives for kitchen and bathroom upgrades. EPA's National Emission Standards for Hazardous Air Pollutants compel manufacturers toward water-based epoxy systems. Dallas-Fort Worth distribution hubs consolidate inventory for Sun Belt construction activity.
Germany
Commercial hospitality projects in Berlin and Munich specify deformable adhesives for large-format porcelain installations. ECHA's REACH phase-down on volatile organic compounds eliminates solvent-based alternatives from specification lists. The Rhine-Ruhr industrial cluster houses redispersible polymer powder production for modified adhesive compounders.
India
Maharashtra and Karnataka state contractors bulk-procure economy-grade thin-set adhesives under Housing for All schemes. BIS certification requirements for construction chemicals create quality barriers favoring organized manufacturers over unregulated regional suppliers. Mumbai-Pune corridor distributors anchor technical service networks for organized contractor segments.
Netherlands
Food processing facility upgrades in Rotterdam and Eindhoven demand zero water absorption epoxy systems. REACH compliance timelines accelerate conversion from solvent-cure formulations in industrial flooring segments. Amsterdam specification consultants influence adhesive selection for healthcare and institutional projects requiring ISO 13007 certification.
Indonesia
Trans-Java railway and metro station construction creates demand for rapid-setting adhesives in high-traffic commercial environments. National infrastructure procurement guidelines favor certified construction chemical suppliers. Jakarta-Bandung corridor contractors specify polymer-modified systems for large-format tile installations in transit hubs.
Floor Tile Adhesive Market Competitive Landscape
Listed leaders compete with private specialists across formulation expertise and geographic reach, producing a tiered structure where scale-driven multinationals anchor premium commercial channels while regional compounders capture price-sensitive residential volume. Three archetypes dominate: European formulation specialists with REACH-compliant water-based platforms, Asian manufacturers leveraging localized raw material sourcing, and integrated chemical conglomerates with captive polymer supply. Competitive moves concentrate on backward integration into redispersible polymer powder production and digital specification platform partnerships with commercial contractors.
Within the European specialist tier, Sika AG and Mapei S.p.A. exemplify formulation-driven positioning, while Pidilite Industries anchors South Asian market presence through localized distribution density. Henkel AG occupies a position among diversified chemical conglomerates with adhesive portfolios spanning construction end-uses. These three entities represent distinct competitive vectors: Sika AG through specification authority in commercial hospitality, Mapei S.p.A. through manufacturing scale across multiple continents, and Pidilite Industries through field service networks in emerging market corridors.
| Leading Market Players |
|---|
| Henkel AG |
| Sika AG |
| H.B. Fuller |
| Arkema |
| Mapei S.p.A. |
| Wacker Chemie AG |
| 3M |
| Laticrete International |
| Pidilite Industries |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between redispersible polymer powder producers and European adhesive compounders lock in feedstock access and stabilize input cost visibility across multi-year procurement cycles. These arrangements insulate formulation specialists from Portland cement volatility while exposing them to polymer supply concentration risk in Germany and South Korea.
Pricing Analysis
Water-based versus solvent-based versus next-generation hybrid formulations command widening price spreads as REACH and EPA compliance timelines diverge. Three-tier pricing structure across premium polymer-modified, standard cementitious, and economy-grade thin-set levels stratifies procurement budgets. Cost compression in economy-grade bags intensifies because Indian state contractors bulk-procure under Housing for All schemes. Residential renovators in Florida and California exhibit highest price sensitivity; pharmaceutical cleanroom contractors in the Netherlands show least.
Supply Chain Analysis
Just-in-time inventory strategies dominate European and North American distributor networks, while Indian and Indonesian contractors prefer strategic stockpiles to buffer monsoon-season logistics disruptions. Redispersible polymer powder production clusters in Germany and South Korea; Portland cement sourcing concentrates in China and Vietnam. Single-source vulnerability in specialty polymer feedstocks threatens formulation continuity. Distribution runs through regional distributor networks with embedded technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floor tile adhesive procurement is migrating toward platform-mediated specification, where digital substrate-matching algorithms displace traditional distributor relationships and reshape how performance data flows from manufacturer to installer.
For Market Incumbents: Consolidate backward integration into redispersible polymer powder production to escape German and South Korean supply concentration. Deepen certification investment toward ISO 13007 C2TES1 classification to defend specification authority against emerging hybrid-formulation specialists. Lock in long-term offtake with Mumbai-Pune corridor distributors to anchor India's organized contractor segment. For New Entrants and Emerging Players: ISO 13007 fast-track certification opens procurement access to UK NHS hospital refurbishments and Dutch food processing facility upgrades. White-space concentrates in Indonesia's Trans-Java infrastructure corridor, where national procurement guidelines favor certified suppliers but local technical service networks remain underdeveloped. Go-to-market through e-commerce platforms with embedded substrate-diagnostic algorithms captures contractor research phases ahead of incumbent distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward formulation specialists with captive polymer supply and REACH-compliant water-based platforms. Five-to-ten-year viability hinges on regulatory compliance trajectory rather than volume scale alone. Acquisition targets should demonstrate ISO 13007 certification pipelines and established specification relationships with hospitality and healthcare verticals. Watch for inflection when EPA enforcement tightens methylene chloride discharge limits in industrial adhesive manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive redispersible powder supply insulates Sika AG and Mapei S.p.A. from German-South Korean concentration risk. |
| ISO 13007 C2TES1 Certification Investment | Deformable adhesive classification unlocks German hospitality and UK healthcare specification channels. |
| Digital Platform Partnership | Substrate-matching algorithms in UK and Australian procurement platforms compress distributor influence. |
| Biopolymer Binder R&D | Bio-based polyurethane pathways position compounders for LEED-certified project capture. |
| Regional Distribution Expansion | Mumbai-Pune technical service networks anchor Pidilite Industries' contractor loyalty in India's Housing for All corridors. |
Research Methodology
Initial hypotheses were tested against primary input from commercial tiling contractors, specification consultants, adhesive compounder R&D directors, and construction chemical procurement managers at state housing agencies, then refined through secondary validation. Trade data from Indian customs authorities, ECHA REACH registration databases, SEC 10-K filings from listed chemical conglomerates, and ISO 13007 certification registries anchored quantitative baselines. Bottom-up volume estimates triangulated against top-down construction spending allocations.
Variance decomposition across product type, application vertical, technology platform, and end-user specification authority shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro construction indicators. Redispersible polymer powder capacity utilization rates and Portland cement price indices fed industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained government housing scheme funding or accelerated REACH enforcement timelines would require recalibration. Forecasts reflect assumptions on regulatory compliance trajectories and construction material substitution elasticities. Revision becomes warranted when EPA National Emission Standards enforcement intensity crosses thresholds that trigger solvent-based formulation obsolescence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
South Africa Sealants Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
Asia-Pacific Flock Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Market