
 Global Sealants Market | 2026-2036
Global Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sealants Market Outlook
Aerospace assembly is consolidating its position as the fastest-expanding end-use vertical for high-performance sealants, displacing traditional construction primacy in premium product tiers. Sika AG leverages its European formulation heritage to dominate structural bonding applications for commercial aircraft programs. Dow sustains technology leadership through advanced silicone chemistry platforms serving semiconductor packaging and electric vehicle battery enclosures. Henkel AG & Co. KGaA anchors its competitive position via automotive OEM qualification programs that lock in multi-year supply agreements across German and Chinese manufacturing clusters.
Sealants are polymeric materials formulated to fill gaps, block fluid transmission, and maintain adhesion under thermal cycling, vibration, or chemical exposure, typically specified by elongation at break, Shore A hardness, and cure time parameters. Silicone formulations command the highest margin pools due to temperature resistance requirements in electronics and aerospace, while polyurethane competes aggressively on construction volume through faster cure profiles and paint compatibility. Acrylic segments occupy the retail and DIY channel where contractors and homeowners prioritize water-based cleanup and lower per-unit cost, though butyl maintains captive demand in automotive damping applications where outgassing specifications are stringent.
EPA VOC regulations in the United States restrict solvent content in architectural sealants, while REACH compliance in Europe mandates disclosure of Substances of Very High Concern in imported formulations. China's GB standards administered by SAMR establish localized testing protocols that foreign suppliers must navigate for market access. Stakeholders must monitor evolving carbon border adjustment mechanisms and bio-based feedstock certification schemes that will reshape raw material sourcing decisions and regional manufacturing footprints.
Market Dynamics
Silicone chemistry platforms are commanding premium positioning as aerospace and electric vehicle manufacturers impose thermal cycling specifications that polyurethane and acrylic formulations cannot satisfy. REACH disclosure mandates and EPA VOC restrictions are simultaneously compressing solvent-based capacity while rewarding compliant producers with locked-in supply relationships.
Growth Catalysts
- EU Green Deal compliance deadlines:European OEMs are accelerating solvent-free procurement specifications ahead of carbon border adjustment implementation. German automotive assembly lines now require bio-based content verification for structural bonding tenders.
- Semiconductor packaging thermal management:Advanced silicone formulations enable higher power density in chip enclosures. Taiwan and South Korean foundries are qualifying next-generation encapsulants for 3D stacking architectures.
- China's eastern coastal manufacturing clusters:Integrated bonding operations in Jiangsu and Guangdong provinces are consolidating multi-step adhesive-sealant workflows. Electronics contract manufacturers specify single-supplier solutions to reduce qualification overhead.
Market Restraints
- Siloxane raw material concentration:Four chemical conglomerates control over three-quarters of global silane monomer supply. Any disruption at Rotterdam or Singapore shipping hubs propagates through aerospace and electronics value chains within weeks.
- REACH Substances of Very High Concern disclosure:Importers face 18-month notification timelines and testing costs exceeding standard formulation development budgets. Smaller Asian exporters are withdrawing from European tenders rather than navigating ECHA compliance.
- Hot-melt pressure-sensitive adhesives:These substitutes capture automotive interior assembly where temperature exposure remains moderate. Japanese tier-one suppliers have shifted damping pad specifications toward thermal-bonding films.
Strategic Opportunities
- India's automotive component corridor:Tamil Nadu and Gujarat manufacturing zones lack qualified local sealant formulators. PLI scheme beneficiaries require imported bonding solutions for electric powertrain assembly.
- UV-LED cure convergence with robotics:Automotive OEMs in Stuttgart and Wolfsburg are piloting in-line curing stations that compress cycle times from hours to minutes. Equipment suppliers and chemical formulators must co-develop integrated systems.
- SAMR bio-based certification pathway:China's national standards administration is finalizing renewable content testing protocols. Early movers with verified supply chains will secure preferred supplier status for state-owned enterprise tenders.
Industry Challenges
- Formulation chemist scarcity:European universities have shuttered polymer synthesis programs. BASF and Evonik now operate captive training academies to replace retiring technical staff.
- Dual aerospace-automotive qualification timelines:Boeing and Airbus certification cycles run 24-36 months concurrent with automotive PPAP requirements. Shared service laboratories face capacity constraints managing parallel approval tracks.
- Legacy solvent-based inventory stranding:Distributors in Southern Europe hold aging stock that fails impending VOC thresholds. Write-down pressures are forcing channel consolidation ahead of regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sealants Market |
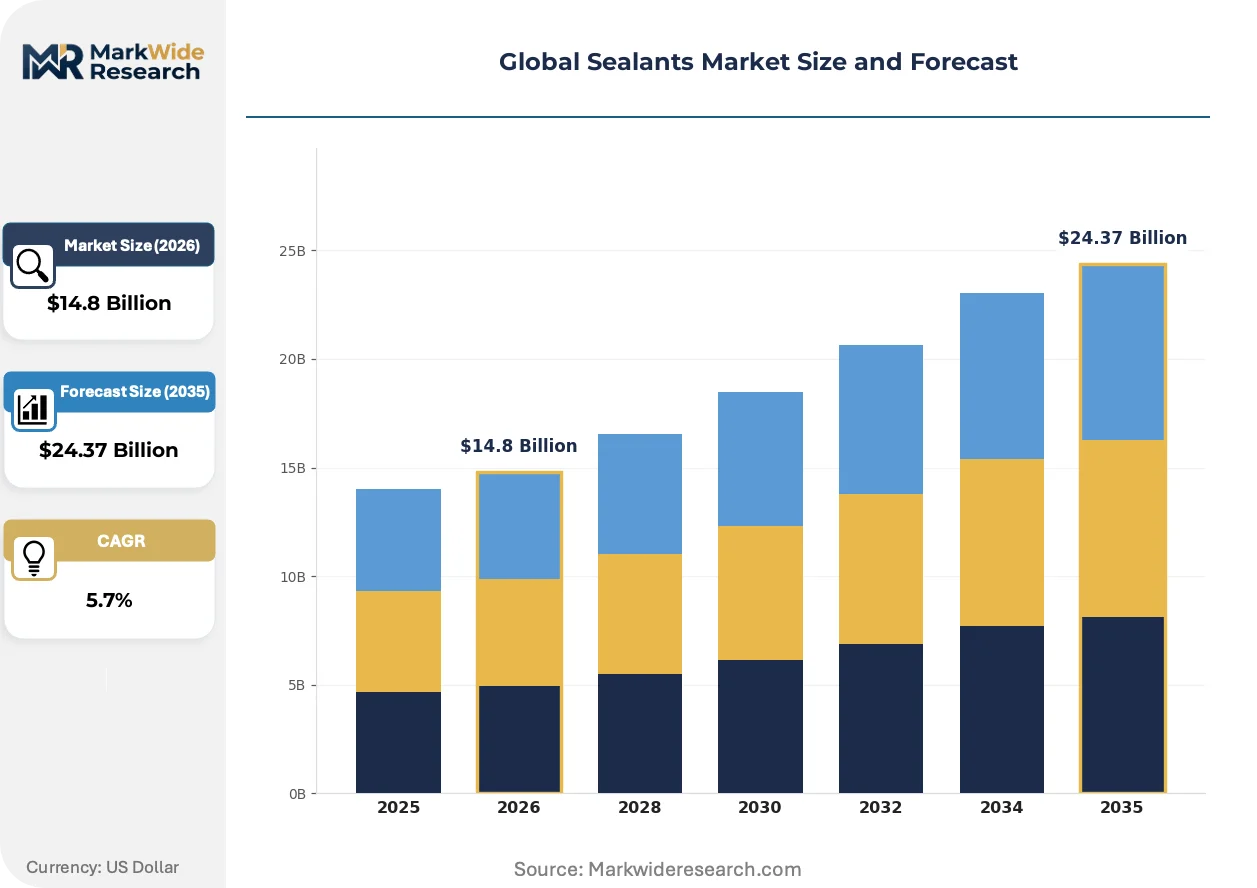
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Acrylic, Butyl Application: Construction, Automotive, Aerospace, Electronics End User: Manufacturers, Contractors, Homeowners, Retailers Distribution Channel: Online, Wholesale, Direct Sales, Retail |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, 3M, Dow, H.B. Fuller Company, Arkema Group, Huntsman, Illinois Tool Works Inc, RPM International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sealants Market Strategic Shifts
Thermal management requirements are fragmenting specification standards across end-use verticals. Manufacturers now optimize for narrow performance envelopes rather than universal formulations.
Two-part addition-cure silicones with platinum catalyst systems enable fuel cell stack sealing at sustained temperatures above standard automotive specifications. Hyundai and Toyota powertrain engineers are specifying these materials for next-generation hydrogen vehicle production. The technology is expanding into stationary energy storage enclosures where thermal runaway containment has become a non-negotiable design parameter.
EPA architectural sealant VOC limits now restrict solvent content to 250 grams per liter in commercial construction applications. Formulators have reformulated with silane-terminated polyether backbones that achieve comparable adhesion without aromatic diluents. California Air Resources Board enforcement in Los Angeles and San Francisco metropolitan areas is driving national product line standardization.
Automotive OEMs now unbundle material supply from application equipment and technical service contracts. Tier-one suppliers in Germany's Rhine-Ruhr region are selecting sealant vendors based on per-vehicle bonding cost rather than per-kilogram pricing. This purchasing recalibration favors integrated solution providers with robotic dispensing partnerships over commodity chemical distributors.
Global Sealants Market Segmentation
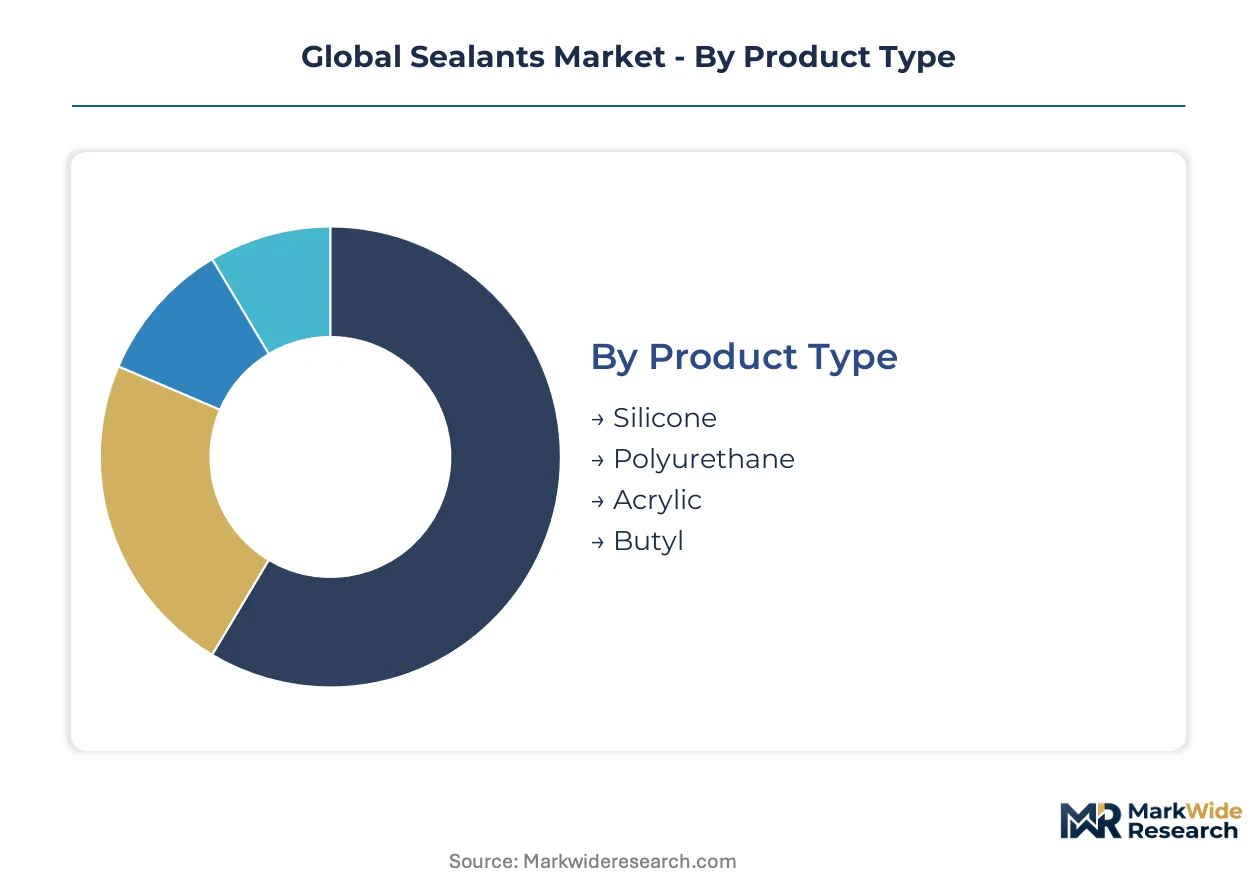
Sealant procurement patterns diverge sharply across chemistry platforms and end-use verticals. Specification standards, cure requirements, and regulatory exposure create distinct buying behaviors that suppliers must navigate separately.
Product Type:
Buyers in this category differentiate primarily by thermal tolerance needs and paint compatibility trade-offs.
- Silicone:Cross-linked polydimethylsiloxane networks withstand sustained temperatures exceeding 200°C without degradation. Aerospace fuel cell sealing and electric vehicle battery enclosures in Germany and China now specify platinum-cured addition systems for thermal cycling resilience.
- Polyurethane:Isocyanate-terminated prepolymers cure through atmospheric moisture to form elastomeric seals with Shore A hardness tunable from 15 to 90. Construction contractors in Spain and Italy favor these formulations for facade sealing where rapid handling and paint adhesion matter more than temperature extremes.
- Acrylic:Water-based emulsions serve DIY homeowners and small contractors through retail channels requiring soap-and-water cleanup.
- Butyl:Isobutylene-isoprene copolymers deliver ultra-low gas permeability for automotive damping pads where outgassing specifications exclude silicones.
Volume sits with Polyurethane; growth tilts toward Silicone.
Application:
End-use selection hinges on qualification timelines and performance certification requirements rather than unit economics alone.
- Construction:Joint sealing for commercial facades and residential fenestration consumes bulk volume through project-based procurement. EPA VOC limits and California Air Resources Board enforcement are eliminating solvent-bearing formulations from US specifications.
- Automotive:Powertrain, body-in-white, and interior assembly applications demand PPAP qualification cycles spanning 12-18 months. German OEMs in Stuttgart and Wolfsburg now unbundle material supply from robotic dispensing equipment contracts.
- Aerospace:Fuel-efficient airframe programs in France and Germany specify structural bonding silicones with 24-36 month certification horizons concurrent with Airbus and Boeing requirements.
- Electronics:Semiconductor packaging and display bonding in Taiwan and South Korea require ultra-pure encapsulants with ionic contamination below 10 ppm.
Construction commands current volume; electronics and aerospace are climbing the fastest.
End User:
Purchasing sophistication and technical service requirements separate buyers across this dimension.
- Manufacturers:Integrated bonding operations in China's Jiangsu and Guangdong provinces consolidate multi-step adhesive-sealant workflows under single-supplier agreements to reduce qualification overhead.
- Contractors:Commercial construction specialists in Los Angeles and San Francisco metropolitan areas face California Air Resources Board enforcement that restricts product choice to low-VOC compliant inventories.
- Homeowners:Retail channel purchasers prioritize water-based cleanup and per-unit cost over performance specifications.
- Retailers:Distributors in Southern Europe hold aging solvent-based stock facing write-down pressures from impending EU Green Deal thresholds.
Manufacturers dominate volume; contractors are gaining share fastest as project specifications tighten.
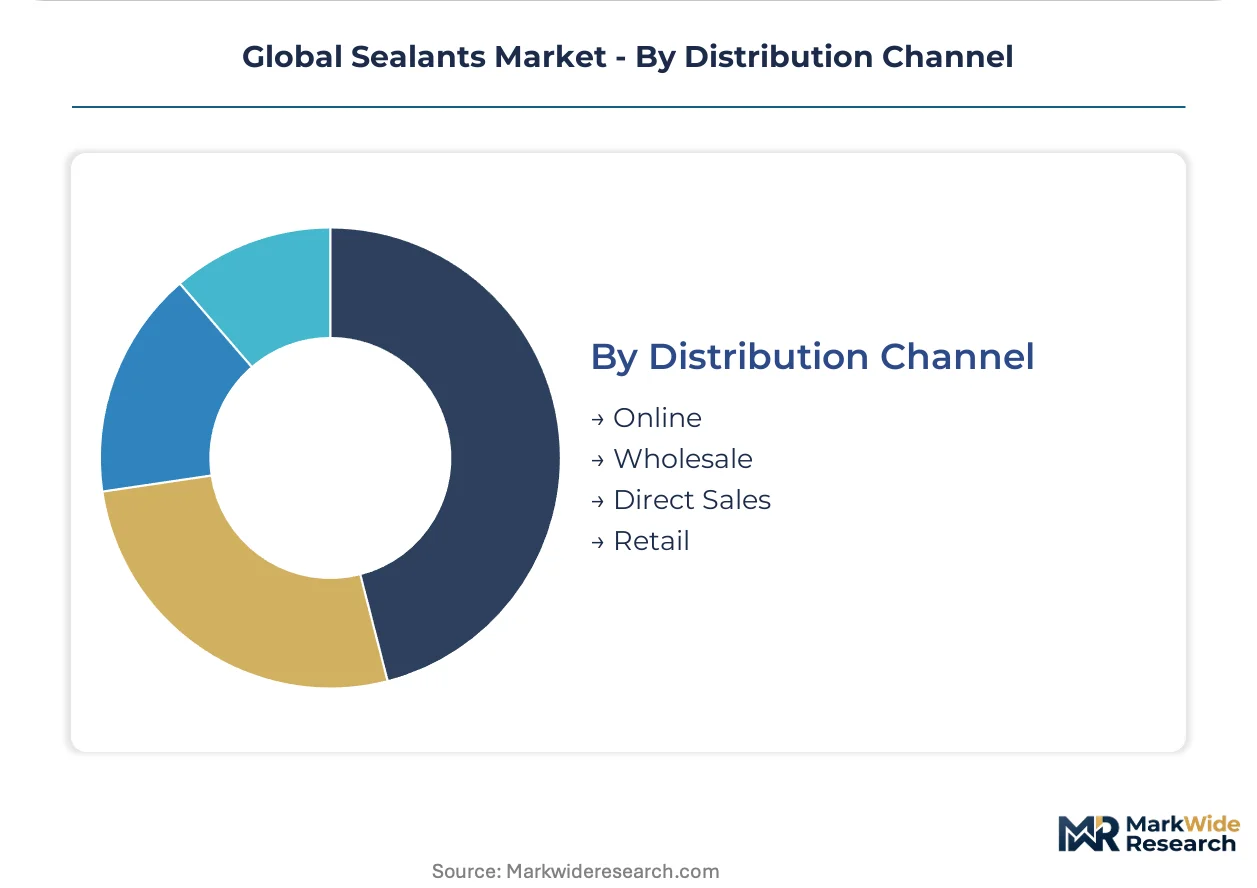
Distribution Channel:
Channel selection reflects order size predictability and technical support intensity requirements.
- Online:E-commerce platforms serve small contractors and maintenance departments with standardized SKUs and next-day logistics.
- Wholesale:Regional distributors in the Rhine-Ruhr region maintain local inventory for German automotive tier-one suppliers requiring just-in-time delivery.
- Direct Sales:Aerospace and electronics manufacturers negotiate multi-year supply agreements with dedicated technical service teams.
- Retail:Home improvement chains stock acrylic and silicone cartridges for homeowner DIY applications.
Wholesale holds current volume; direct sales are expanding most quickly as OEMs consolidate supplier bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province's free-trade zones and bonded logistics parks concentrate electronics contract manufacturing that drives sealant procurement intensity. German automotive OEMs and French aerospace assemblers anchor European demand through qualification-heavy supply agreements. China's eastern coastal manufacturing clusters absorb volume through integrated bonding operations that consolidate multi-step workflows.
China
Jiangsu and Guangdong provinces host electronics contract manufacturers operating integrated bonding operations that specify single-supplier solutions. SAMR administers GB standards establishing localized testing protocols that foreign suppliers must navigate for market access. Shanghai and Shenzhen metropolitan areas concentrate automotive OEM facilities and semiconductor packaging operations that qualify next-generation silicone encapsulants.
Germany
Stuttgart and Wolfsburg automotive OEMs unbundle material supply from robotic dispensing equipment contracts based on per-vehicle bonding cost metrics. EU Green Deal compliance deadlines accelerate solvent-free procurement specifications ahead of carbon border adjustment implementation. The Rhine-Ruhr region maintains wholesale distribution infrastructure serving tier-one suppliers requiring just-in-time delivery.
United States
EPA VOC regulations restrict solvent content in architectural sealants to 250 grams per liter in commercial construction applications. California Air Resources Board enforcement in Los Angeles and San Francisco metropolitan areas drives national product line standardization toward low-VOC formulations. Aerospace manufacturers in Washington State and California expand silicone sealant procurement for fuel-efficient airframe assembly programs.
France
Airbus supply chains in Toulouse and Nantes specify structural bonding silicones with 24-36 month certification horizons concurrent with Boeing requirements. REACH compliance mandates disclosure of Substances of Very High Concern in imported formulations. The Île-de-France region concentrates headquarters operations for formulators serving both aerospace and automotive qualification tracks.
India
Tamil Nadu and Gujarat manufacturing zones lack qualified local sealant formulators, creating import dependency for electric powertrain assembly. PLI scheme beneficiaries require imported bonding solutions as domestic capacity remains underdeveloped. Automotive component corridors around Chennai and Ahmedabad attract multinational suppliers establishing technical service presence.
Global Sealants Market Competitive Environment
Top-tier vendors anchor premium qualification-intensive segments, while mid-scale formulators compete on construction volume and regional distribution reach. The vendor base separates into three distinct tiers: multinational chemical conglomerates with captive silicone chemistry platforms, European heritage specialists with aerospace-automotive dual qualifications, and regional distributors holding aging solvent-based inventories facing write-down pressures. Two dominant competitive moves are reshaping positioning: M&A activity consolidating formulation capabilities under integrated solution providers, and strategic partnerships between chemical suppliers and robotic dispensing equipment vendors.
Among European heritage specialists, Sika AG and Henkel AG & Co. KGaA exemplify the dual-qualification archetype spanning aerospace structural bonding and automotive OEM supply agreements. Dow occupies a position representing multinational chemical conglomerates with advanced silicone chemistry platforms. These three anchors illustrate how competitive positioning fragments across chemistry specialization, qualification timeline intensity, and geographic manufacturing footprint rather than converging on uniform scale metrics.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| 3M |
| Dow |
| H.B. Fuller Company |
| Arkema Group |
| Huntsman |
| Illinois Tool Works Inc |
| RPM International Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap European formulators, anchored in Germany's Rhine-Ruhr industrial belt, maintain pricing discipline through captive technical service relationships that lock automotive OEMs into multi-year contracts. Their supply behavior centers on just-in-time raw material sourcing from Rotterdam and Singapore shipping hubs, while pricing power reflects qualification timeline premiums that commodity distributors cannot replicate.
Pricing Analysis
Short lead-time premiums dominate aerospace and electronics procurement, where 24-36 month certification cycles create captive demand for qualified inventory. Three-tier pricing structure across aerospace-qualified, automotive-PPAP, and construction-grade tiers reflects certification investment recovery. Price differentiation hinges on thermal cycling performance specifications and REACH compliance documentation depth. Cost compression in construction-grade polyurethane runs through spot siloxane purchasing. DIY homeowners exhibit highest price sensitivity; semiconductor foundries show least.
Supply Chain Analysis
Returns and refurbishment flows remain minimal in sealant supply chains due to single-use application nature and cure chemistry irreversibility. Manufacturing concentrates in Germany, China, and the United States, with formulation plants clustered near automotive OEM and aerospace assembly corridors. Raw material dependencies draw from silane monomer production controlled by four chemical conglomerates, isocyanate prepolymer streams, and platinum catalyst supply. Single-source vulnerability at Rotterdam and Singapore shipping hubs propagates disruption within weeks. Distribution runs through wholesale regional networks for construction, direct sales for aerospace and electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH Substances of Very High Concern disclosure mandates erect barrier-to-entry moats favoring incumbents with dedicated ECHA navigation capabilities.
For Market Incumbents: Lock in multi-year supply agreements with Chinese electronics contract manufacturers before SAMR bio-based certification pathways finalize. Deepen captive siloxane sourcing through backward integration into monomer supply or long-term offtake contracts with Rotterdam hub operators. Counter hot-melt pressure-sensitive adhesive substitution in automotive interiors by bundling robotic dispensing equipment with technical service contracts.
For New Entrants and Emerging Players: UV-LED cure chemistry platforms offer technology-first wedge into automotive assembly lines in Stuttgart and Wolfsburg piloting in-line curing stations. White-space targets include India's Tamil Nadu and Gujarat automotive component corridors lacking qualified local formulators. Most penetrable segment is electric powertrain assembly for PLI scheme beneficiaries. Go-to-market angle should emphasize per-vehicle bonding cost metrics rather than per-kilogram pricing.
For Investors and Strategic Acquirers: Distressed-cycle entries favor European heritage specialists with dual aerospace-automotive qualifications in Germany and France facing legacy solvent-based inventory stranding. Long-term viability favors formulators with verified bio-based supply chains and SAMR certification readiness. Acquisition target archetype includes mid-scale European distributors with aging stock write-down pressures but intact automotive OEM relationships. Signal to watch is carbon border adjustment implementation timing accelerating solvent-free procurement specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomer Supply | Captive raw material security insulates margin pressure from Rotterdam hub disruptions. |
| Long-term Supply Agreement with SAMR-Certified Bio-based Feedstock Suppliers | Preferred supplier status for Chinese state-owned enterprise tenders locks eastern coastal volume. |
| Joint Venture with Robotic Dispensing Equipment Vendors | Integrated per-vehicle bonding solutions displace commodity chemical distributors in German automotive. |
| Green Manufacturing Transition to Solvent-free Formulations | EU Green Deal compliance ahead of carbon border adjustment secures locked-in European OEM relationships. |
| Capacity Expansion in India's Tamil Nadu Automotive Corridor | Technical service proximity to PLI scheme beneficiaries captures electric powertrain assembly demand. |
Study Parameters
Independent corroboration across plant managers at German and Chinese formulation facilities, procurement leads at automotive tier-one suppliers, and distribution channel partners in Southern Europe underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical conglomerates, and SAMR GB standards documentation. Bottom-up volume estimates from end-use application sizing and top-down cross-checks against regional production data establish analytical rigor.
Rate-of-change decomposition across chemistry platform adoption curves, end-use vertical growth differentials, and regional regulatory implementation timelines structures the forecast framework. Segmentation dimensions modeled include silicone-polyurethane-acrylic-butyl chemistry tiers, construction-automotive-aerospace-electronics end-use applications, and manufacturer-contractor-homeowner-retailer buyer archetypes. CAGRs derive from elasticity-adjusted demand projections and supply-side capacity constraints. Industry-specific inputs incorporate semiconductor packaging thermal management specifications and automotive PPAP qualification cycle durations.
Several conditions sit outside the modeled scope, including force majeure disruptions at Singapore or Rotterdam shipping hubs, unilateral REACH substance list expansions, and breakthrough cure chemistry technologies. Forecasts reflect documented assumptions about regulatory implementation pacing and OEM procurement specification stability. Practitioners should monitor carbon border adjustment mechanism announcements, SAMR bio-based certification protocol finalization, and hot-melt adhesive substitution rates in automotive interior assembly for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market
Adhesives & Sealants
Removable Adhesive Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
Rubber Repair Adhesives Market
Adhesives & Sealants
Asia-Pacific Waterborne Adhesives Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market