
 Synthetic and Bio-Based PMMA Polymethyl Methacrylate Size Market | 2026-2036
Synthetic and Bio-Based PMMA Polymethyl Methacrylate Size Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic and Bio-Based PMMA Polymethyl Methacrylate Size Market Insights
Buyer concentration among automotive OEMs and tier-one suppliers is pivoting toward fewer large-scale contracts with dedicated resin partners. Evonik Industries leverages its backward integration into methyl methacrylate monomer supply to secure cost advantages across European optical sheet markets. Mitsubishi Chemical Group anchors its position through captive production of high-purity cast PMMA for electronics manufacturers in East Asia. Arkema differentiates via specialty co-polymer grades that serve medical device and aerospace specifications where standard homopolymer falls short.
Synthetic and bio-based PMMA denotes thermoplastic acrylic resins produced through radical polymerization of methyl methacrylate monomer, with bio-based variants substituting petrochemical feedstocks with renewable carbon sources such as biomass-derived methacrylic acid; the material transmits visible light, resists UV degradation, and machines to tight tolerances for precision optical and structural applications. Cast PMMA retains dominance in optical lens and display applications where surface clarity and thickness uniformity command premium pricing. Extruded PMMA competes aggressively in construction panel and signage markets where throughput economics outweigh optical perfection. Bio-based PMMA occupies a nascent but strategically defended niche as brand owners in consumer goods and packaging seek scope-three emissions reductions without sacrificing acrylic performance.
REACH registration requirements in Europe, EPA Toxic Substances Control Act oversight in the United States, and China's GB standards for plastic building materials collectively shape monomer sourcing, additive restrictions, and recyclate incorporation mandates across the value chain. ECHA's evolving restrictions on methacrylate workplace exposure are forcing reformulation investments that favor producers with integrated toxicology and regulatory affairs capabilities. Stakeholders must monitor bio-based certification scheme fragmentation and polymer-to-polymer recycling pathway economics to anticipate which feedstock and form factor positions will sustain margin capture.
Market Dynamics
Automotive OEMs consolidating their supplier base around dedicated resin partners are compressing procurement cycles and forcing mid-scale PMMA producers to choose between capitulation on margin or exit from optical-grade segments entirely.
Growth Catalysts
- Lightweight glazing mandates:NHTSA fuel economy standards in the United States are accelerating PMMA substitution for glass in panoramic roof systems and side windows.
- REACH monomer purity escalation:ECHA's tightening methacrylate workplace exposure limits are advantaging producers with integrated toxicology capabilities and captive monomer supply.
- Display panel investment waves:South Korean and Chinese electronics manufacturers are expanding optical sheet offtake for quantum-dot enhancement films and mini-LED diffusion plates.
Market Restraints
- MMA feedstock volatility:Acetone cyanohydrin route economics swing with natural gas and ammonia input costs, squeezing margin predictability for non-integrated sheet extruders.
- East Asian supply concentration:Mitsubishi Chemical Group and Chi Mei Corporation control over sixty percent of global cast sheet capacity, creating single-source vulnerability for European optical component buyers.
- Polycarbonate substitution in automotive:Covestro and SABIC are pushing improved scratch-resistant PC grades that threaten PMMA's position in headlamp lenses and exterior trim.
Strategic Opportunities
- India construction panel penetration:BIS certification harmonization with ISO 7823 is lowering import barriers for extruded PMMA in commercial building facades and metro station cladding.
- Polymer-to-polymer recycling pathways:Pyrolysis-based MMA recovery from end-of-life acrylic is approaching cost parity with virgin monomer, enabling circular product lines for brand-conscious consumer goods.
- EU Green Deal bio-based quotas:Mass balance certification under ISCC PLUS is creating premium positioning for producers sourcing methacrylic acid from biomass fermentation.
Industry Challenges
- Optical metrology talent scarcity:Cast sheet production requires technicians capable of maintaining thickness uniformity within fifty microns across two-meter widths, a skill set concentrated in aging workforces in Germany and Japan.
- Multi-standard certification complexity:Medical device PMMA must simultaneously satisfy FDA 21 CFR 177.1010, ISO 10993 biocompatibility, and EU MDR traceability requirements, extending qualification timelines to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic and Bio-Based PMMA Polymethyl Methacrylate Size Market |
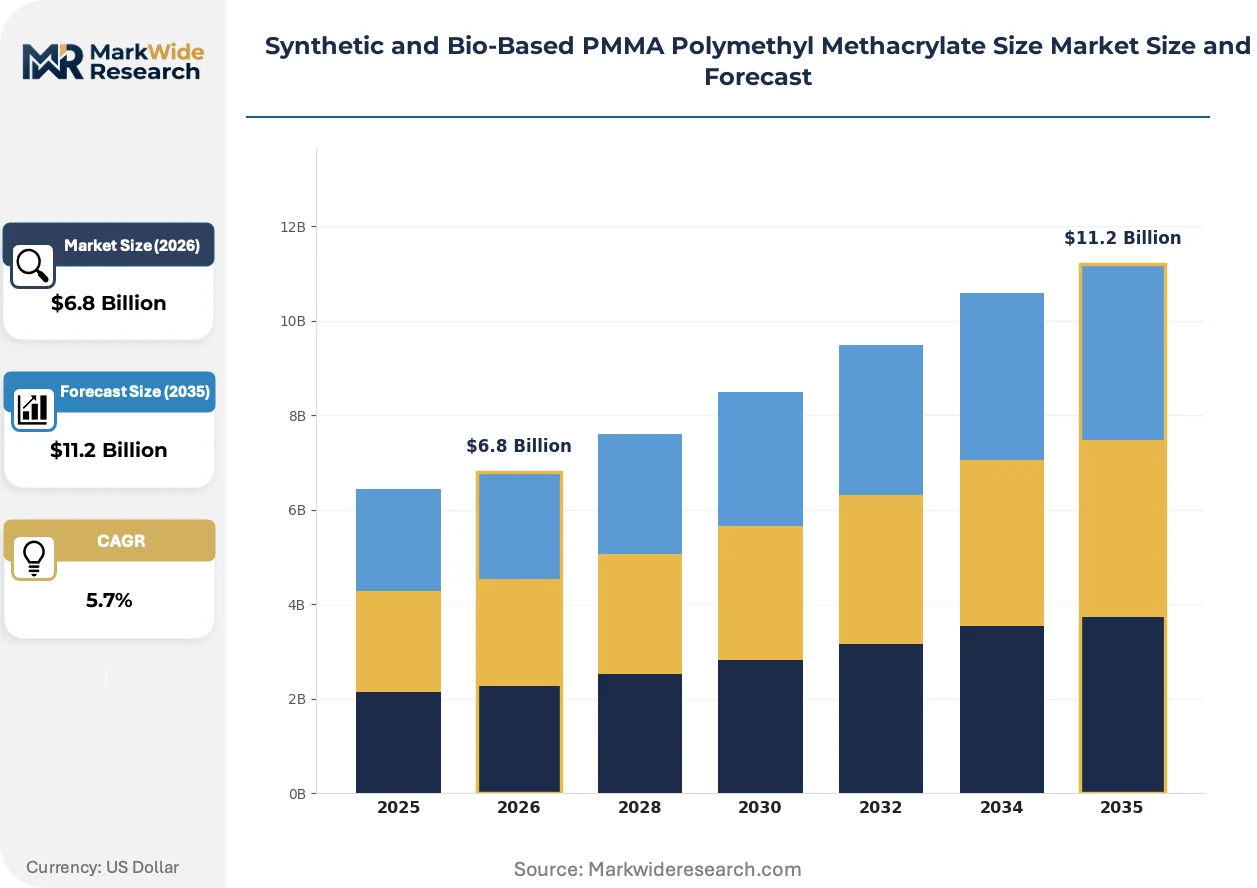
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast PMMA, Extruded PMMA, Block PMMA, Bio-Based PMMA, Co-Polymer PMMA Application: Optical Lenses, Automotive Components, Electronics Housing, Construction Panels, Decorative Items End User Industry: Consumer Goods, Transportation, Electronics Manufacturing, Building Materials, Packaging Form: Sheets, Rods, Pellets, Powders, Films |
| Companies Covered | Evonik Industries, Arkema, Mitsubishi Chemical Group, Röhm, Sumitomo Chemical, CHIMEI Corporation, Trinseo, LG Chem, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic and Bio-Based PMMA Polymethyl Methacrylate Size Market Trends and Innovations
Continuous processing technologies and regulatory carbon accounting are converging to redefine how PMMA producers compete on cost, compliance, and circularity credentials across automotive, electronics, and medical verticals.
Advanced reactive extrusion systems that polymerize MMA monomer in-line with compounding are rewriting throughput economics for commodity-grade sheet. Construction panel manufacturers in China and Turkey are adopting these lines to bypass batch cast bottlenecks. The technology is compressing capital recovery periods from seven years toward four, forcing traditional cast producers to defend optical purity as their sole differentiation.
ECHA's 2023 restriction proposal on methacrylate dermal sensitizers is tightening formulation freedom for medical and dental PMMA grades. Manufacturers must now document alternative crosslinking chemistries or absorb costly personal protective equipment mandates for downstream processors. German and Swiss dental prosthetics suppliers are accelerating qualification of methacrylate-reduced co-polymers to preempt supply disruption.
Automotive tier-one suppliers are unbundling material specification from fabrication, appointing resin partners as co-designers rather than commodity vendors. BMW and Mercedes-Benz glazing procurement teams now embed PMMA producers in early-stage vehicle architecture decisions. This pattern is most pronounced in Bavaria and Stuttgart engineering corridors, where optical simulation capabilities determine contract awards before volume commitments crystallize.
Synthetic and Bio-Based PMMA Polymethyl Methacrylate Size Market Segmentation
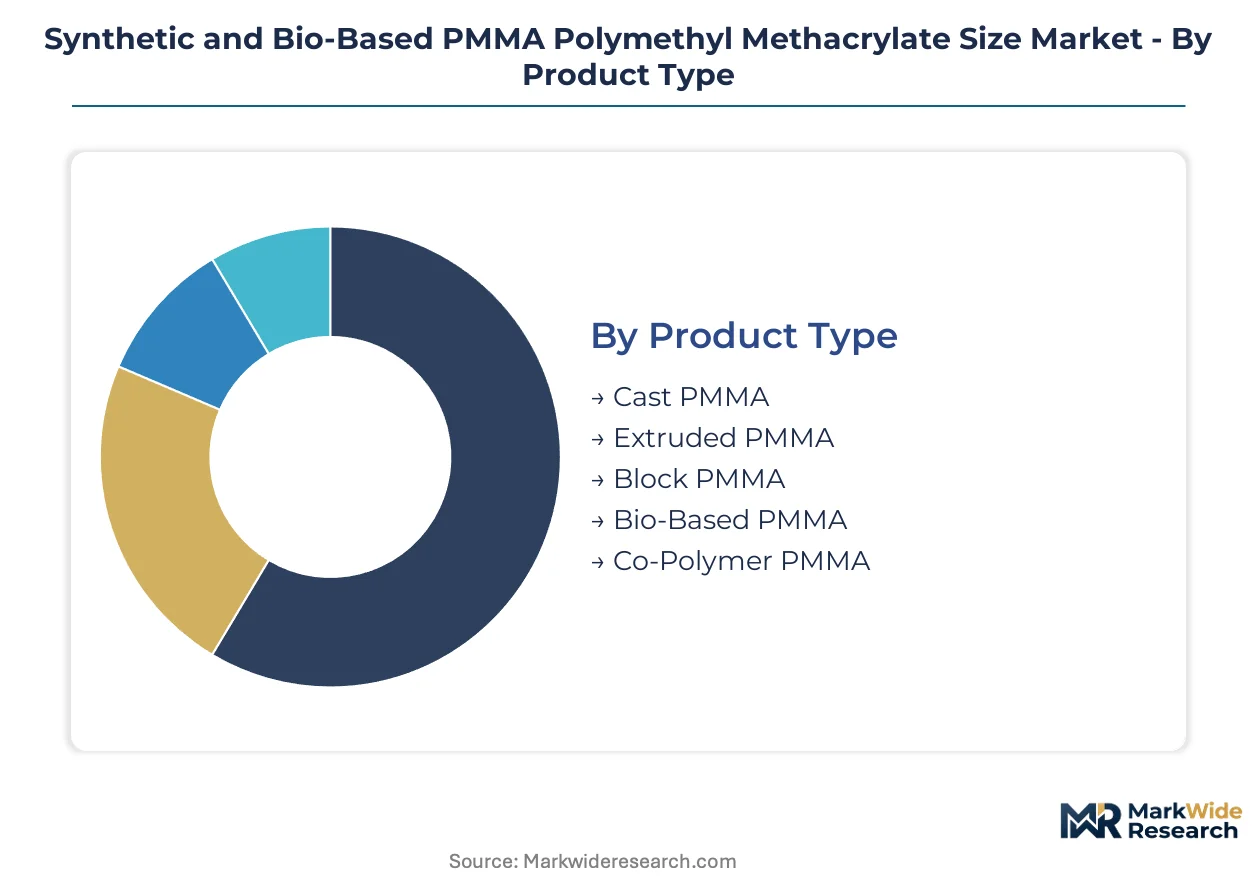
PMMA procurement decisions hinge on optical clarity requirements versus throughput economics, with automotive OEMs and electronics manufacturers driving divergent specification priorities across product types and forms. Understanding segment-level trade-offs between cast purity, extrusion speed, and bio-based certification status determines supplier positioning and margin capture.
Product Type:
Buyers select product types based on surface finish tolerance and lot-to-lot consistency requirements, with optical applications commanding premium validation protocols.
- Cast PMMA:Manufactured via cell casting between glass plates, delivering superior optical clarity and thickness uniformity within fifty microns. Demand concentrates in German and Japanese precision optics clusters where lens manufacturers require birefringence-free substrates for camera modules and medical imaging. REACH monomer purity mandates favor producers with integrated toxicology capabilities.
- Extruded PMMA:Produced through continuous melt extrusion, offering higher throughput and lower unit costs at modest optical compromise. Construction panel buyers in China and Turkey prioritize sheet width consistency over haze specifications, driving adoption of reactive extrusion systems that compress capital recovery timelines.
- Block PMMA:Solid cast blocks machined to custom dimensions for dental prosthetics and aircraft interior components. Swiss and German dental suppliers dominate offtake.
- Bio-Based PMMA:Derived from biomass fermentation routes to methacrylic acid, maintaining petrochemical-equivalent performance. EU Green Deal mass balance certification under ISCC PLUS creates premium positioning for brand owners targeting scope-three emissions reductions.
- Co-Polymer PMMA:Engineered with alternative acrylate monomers to enhance impact resistance or chemical compatibility. Medical device and aerospace specifications in France and Switzerland drive qualification of methacrylate-reduced grades ahead of ECHA dermal sensitizer restrictions.
Volume sits with extruded grades; growth tilts toward bio-based variants.
Application:
Application selection tracks end-use durability requirements and regulatory exposure, with exterior automotive and implantable medical representing opposite ends of the validation spectrum.
- Optical Lenses:Camera module lenses, eyeglass blanks, and LED light guides demanding transmission rates above ninety-two percent. South Korean and Chinese display panel manufacturers are expanding offtake for quantum-dot enhancement films and mini-LED diffusion plates.
- Automotive Components:Panoramic roof systems, side windows, and headlamp lenses where NHTSA fuel economy standards accelerate PMMA substitution for glass. BMW and Mercedes-Benz glazing teams now embed resin partners in early-stage vehicle architecture decisions.
- Electronics Housing:Tablet screens, smartphone covers, and monitor bezels requiring scratch resistance and dimensional stability. Japanese electronics assemblers specify high-purity cast grades for premium device segments.
- Construction Panels:Commercial building facades, metro station cladding, and interior partitions where UV weathering resistance outweighs optical perfection. BIS certification harmonization with ISO 7823 is lowering import barriers for Indian infrastructure projects.
- Decorative Items:Retail displays, furniture accents, and architectural features leveraging acrylic's thermoformability and color stability. Italian and Spanish design houses drive seasonal demand fluctuations.
Automotive glazing commands the steepest expansion trajectory; construction panels anchor current volume.
End User Industry:
Industry verticals impose distinct certification burdens, with medical and aerospace buyers extending qualification timelines to eighteen months while consumer goods prioritize speed-to-market.
- Consumer Goods:Cosmetic packaging, premium stationery, and lifestyle products where brand aesthetics drive material selection. Bio-based certification supports sustainability messaging for European and North American brand owners.
- Transportation:Automotive OEMs and tier-one suppliers consolidating procurement around dedicated resin partners with optical simulation capabilities. German engineering corridors in Bavaria and Stuttgart concentrate specification authority.
- Electronics Manufacturing:Display panel fabricators and device assemblers requiring cleanroom-compatible resin handling and lot traceability. East Asian supply concentration creates single-source vulnerability for European component buyers.
- Building Materials:Commercial developers and public infrastructure agencies specifying fire-rated and impact-resistant grades. Turkish and Chinese construction panel manufacturers are adopting continuous extrusion to bypass batch cast bottlenecks.
- Packaging:Premium food and beverage containers leveraging PMMA's clarity and barrier properties. FDA 21 CFR 177.1010 compliance distinguishes qualified suppliers.
Electronics manufacturing captures premium pricing; building materials drive volume scale.
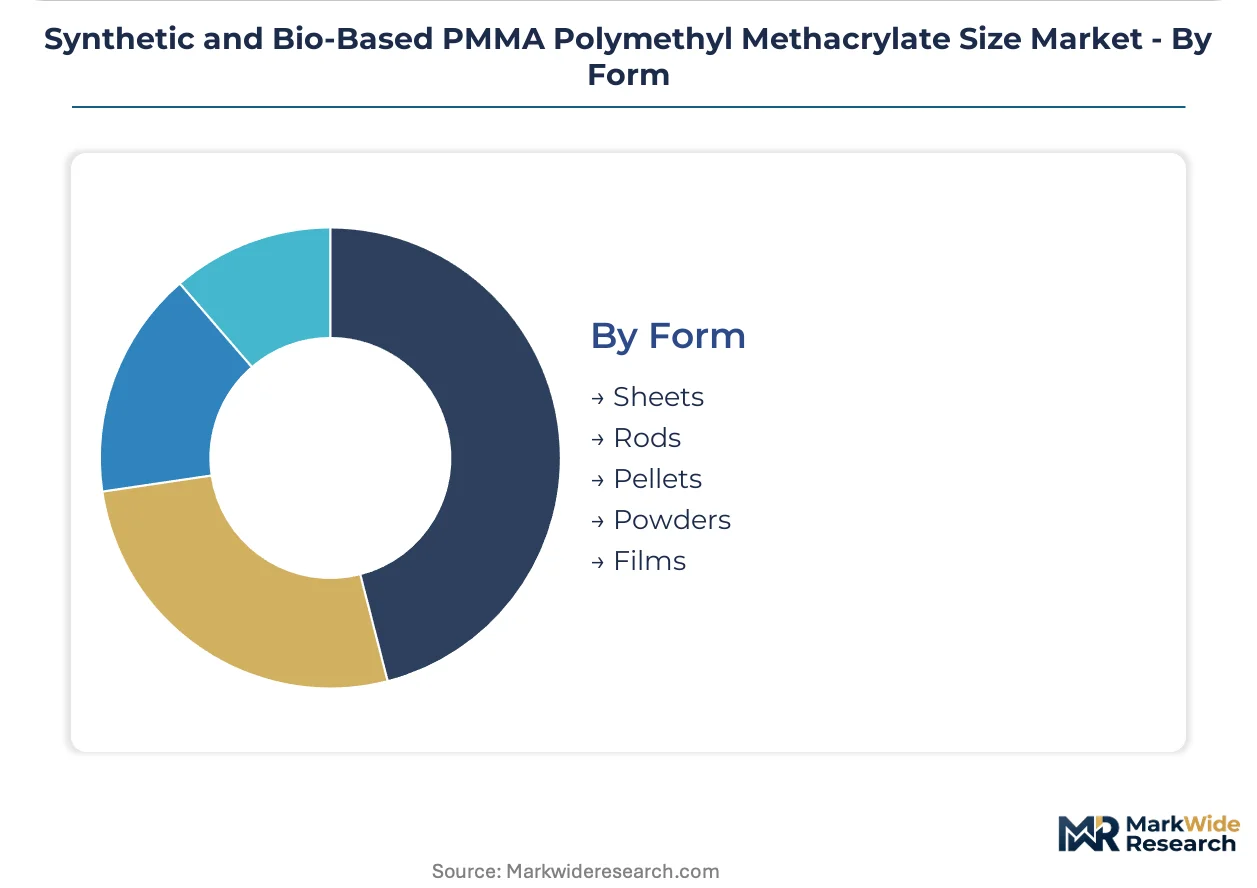
Form:
Form factor selection determines downstream processing economics, with sheet and pellet formats dominating distinct value chain positions.
- Sheets:Flat stock ranging from two to twenty-five millimeters thickness, supplied in standard or cut-to-size dimensions. Extruded sheets serve signage and construction; cast sheets command optical applications.
- Rods:Solid cylindrical stock for machining custom components in dental labs and prototyping shops. German and Swiss precision machining clusters sustain niche demand.
- Pellets:Injection molding feedstock for electronics housings and automotive interior trim. Compounding flexibility allows color and additive customization.
- Powders:Fine particulate for solvent casting, coating formulations, and dental acrylic mixing. Particle size distribution determines dissolution kinetics.
- Films:Thin-gauge rolls for display stack lamination and protective overlays. Japanese and South Korean electronics manufacturers specify optical-grade film for quantum-dot applications.
Pellets and sheets divide volume leadership; films are climbing fastest on display technology investment waves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Methyl methacrylate monomer production clusters in Germany, China, and the United States anchor regional supply architectures. Each concentration shapes downstream PMMA procurement patterns and regulatory compliance burdens.
Germany
Automotive glazing specifications from BMW and Mercedes-Benz drive optical-grade cast sheet demand. ECHA's REACH monomer purity mandates force reformulation investments across the Rhine-Ruhr and Bavarian chemical corridors. The Stuttgart engineering cluster embeds resin partners in early-stage vehicle architecture decisions.
China
Display panel manufacturers in the Yangtze River Delta expand optical sheet offtake for quantum-dot films and mini-LED diffusion plates. GB standards for plastic building materials tighten additive restrictions and recyclate incorporation requirements. Construction panel producers in Guangdong adopt reactive extrusion systems to bypass batch cast bottlenecks.
United States
NHTSA fuel economy standards accelerate PMMA substitution for glass in panoramic roof systems and side windows. EPA Toxic Substances Control Act oversight shapes monomer sourcing protocols for domestic extruders. Texas and Louisiana host integrated MMA production serving Gulf Coast sheet manufacturers.
Japan
Electronics assemblers specify high-purity cast grades for premium device segments requiring cleanroom-compatible resin handling. METI guidelines on carbon accounting pressure suppliers toward mass balance certification. The Kanto region concentrates precision optics clusters demanding birefringence-free substrates.
South Korea
Samsung and LG Display procurement teams drive quantum-dot enhancement film specifications. MFDS oversight of medical device materials extends qualification timelines for dental prosthetics suppliers. The Gumi electronics corridor anchors optical sheet conversion capacity.
Synthetic and Bio-Based PMMA Polymethyl Methacrylate Size Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and circular recycling pathways. The vendor base splits between integrated petrochemical conglomerates with captive monomer supply and specialized optical sheet converters. Three archetypes dominate: backward-integrated monomer producers, precision cast specialists, and reactive extrusion adopters. Competitive moves concentrate on strategic partnerships with automotive OEMs and portfolio diversification into medical-grade co-polymers.
Within the integrated chemical conglomerate tier, Evonik Industries and Mitsubishi Chemical Group exemplify producers leveraging upstream control over methyl methacrylate supply to secure cost positions in optical markets. Arkema occupies a specialty co-polymer position where methacrylate-reduced grades serve medical and aerospace specifications ahead of tightening ECHA dermal sensitizer restrictions. These three anchors represent divergent strategic vectors: European regulatory compliance leadership, East Asian display panel supply dominance, and French specialty materials differentiation.
| Leading Market Players |
|---|
| Evonik Industries |
| Arkema |
| Mitsubishi Chemical Group |
| Röhm |
| Sumitomo Chemical |
| CHIMEI Corporation |
| Trinseo |
| LG Chem |
| SABIC |
| Others |
Pricing and Supply Chain Analysis
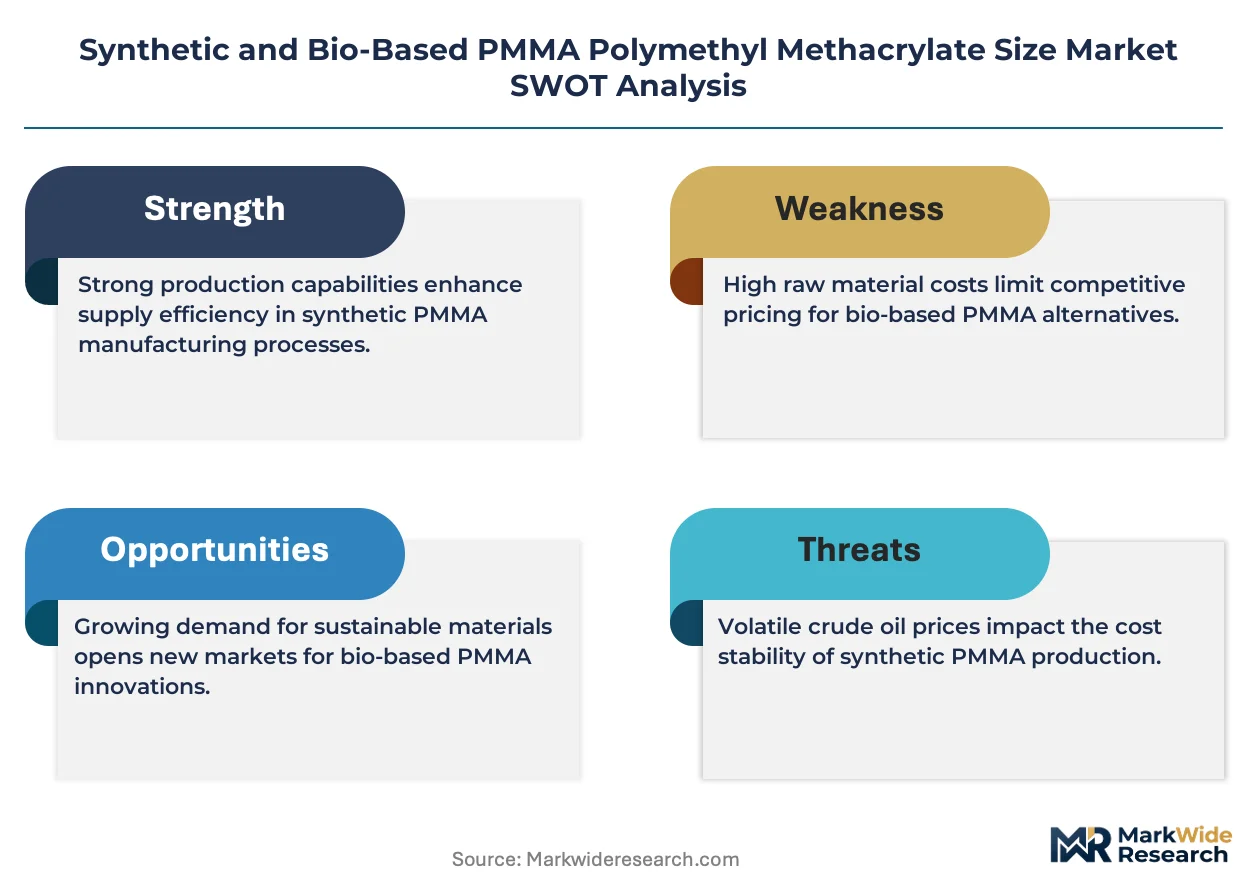
Acetone cyanohydrin spot pricing volatility cascades through PMMA value chains, compressing margin buffers for non-integrated sheet extruders while rewarding producers with captive methyl methacrylate supply. NHTSA fuel economy mandates amplify automotive procurement volumes, yet REACH monomer purity escalation forces reformulation investments that stratify pricing tiers between compliant integrated producers and exposed converters.
Pricing Analysis
Warranty and technical service bundling separates optical-grade cast sheet contracts from commodity extrusion transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with medical device PMMA commanding substantial premiums for FDA 21 CFR 177.1010 compliance. Cost compression in construction panel grades intensifies because Turkish and Chinese reactive extrusion adopters bypass batch cast bottlenecks. Construction panel buyers exhibit highest price sensitivity; medical device OEMs demonstrate least.
Supply Chain Analysis
India's BIS certification harmonization with ISO 7823 and China's GB standards for plastic building materials are reshaping sourcing patterns for regional extruders. Methyl methacrylate production clusters in Germany, China, and the United States anchor global resin supply. Feedstock dependencies center on acetone, hydrogen cyanide, and ammonia inputs. Single-source vulnerability concentrates in East Asian cast sheet capacity controlled by Mitsubishi Chemical Group and Chi Mei Corporation. Distribution runs through direct mill relationships for automotive OEMs and tier-one suppliers, with construction panels flowing via regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA's tightening methacrylate workplace exposure limits erect barrier-to-entry moats for producers with integrated toxicology capabilities. Regulatory qualification timelines extending to eighteen months for medical device grades protect incumbent positions against fast-follower encroachment.
For Market Incumbents: Hedge polycarbonate substitution threats from Covestro and SABIC by accelerating co-polymer qualification for aerospace and medical specifications ahead of ECHA dermal sensitizer restrictions. Deepen backward integration into methyl methacrylate monomer supply to secure cost advantages against acetone cyanohydrin route volatility. Prioritize optical simulation capability investments in Bavarian and Stuttgart engineering corridors where BMW and Mercedes-Benz embed resin partners in early-stage vehicle architecture decisions. For New Entrants and Emerging Players: Automotive tier-one suppliers represent the most penetrable channel partner type for specialty co-polymer entrants seeking qualification pathways outside East Asian supply concentration. Target India's construction panel segment where BIS certification harmonization lowers import barriers for extruded PMMA in commercial building facades and metro station cladding. Pursue mass balance certification under ISCC PLUS as the go-to-market angle for brand owners seeking scope-three emissions reductions without sacrificing acrylic performance. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision cast specialists with aging optical metrology workforces in Germany and Japan, where capability scarcity sustains premium positioning. Long-term viability hinges on polymer-to-polymer recycling pathway economics approaching cost parity with virgin monomer. Watch pyrolysis-based MMA recovery technology maturation as the inflection signal determining which feedstock positions sustain margin capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MMA Monomer | Evonik Industries leverages captive supply to defend optical sheet margins against feedstock volatility. |
| Co-Polymer Grade Qualification | Arkema's methacrylate-reduced grades preempt ECHA dermal sensitizer restrictions in medical and aerospace. |
| Reactive Extrusion System Adoption | Turkish and Chinese construction panel producers compress capital recovery periods toward four years. |
| ISCC PLUS Mass Balance Certification | EU Green Deal bio-based quotas create premium positioning for biomass-derived methacrylic acid routes. |
| Optical Simulation Capability Investment | BMW and Mercedes-Benz procurement teams embed certified resin partners in early-stage glazing decisions. |
Research Methodology
Document review covered trade customs data, SEC 10-K filings, and ECHA regulatory submissions, complemented by interviews with plant managers at integrated chemical conglomerates, procurement leads at automotive tier-one suppliers, technical R&D directors at optical sheet converters, and distribution channel partners across European and Asian markets. Bottom-up demand modeling triangulated against top-down supply capacity assessments.
Segment-level volume and value trajectories emerged from disaggregation across product type, application, end-use industry, and form factor dimensions. CAGRs derived from regression analysis of historical price-volume relationships and forward projection of regulatory-driven specification shifts. Key inputs included NHTSA fuel economy standard stringency curves and display panel investment waves from South Korean and Chinese electronics manufacturers.
Caveats apply where ECHA methacrylate restriction finalization, pyrolysis recycling cost parity achievement, or polycarbonate scratch-resistance breakthroughs could materially shift the outlook. Forecasts reflect assumptions around monomer purity compliance timelines and bio-based certification scheme harmonization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Brazil Bioplastics Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
Starch Blended Biodegradable Polymer Market
Bioplastics
North America Bioplastics Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Biobased Biodegradable Plastics Market
Bioplastics
Biodegradable Insulated Panel Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
US Bioplastics Market