
 Correction Fluid and Tape Market | 2026-2036
Correction Fluid and Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Correction Fluid and Tape Market Insights
The capital-intensity divergence between automated tape extrusion lines and manual fluid blending operations is redrawing competitive boundaries in correction supplies. 3M Company leverages its polymer science infrastructure to sustain premium positioning in precision film substrates. Tombow Pencil Co., Ltd. anchors its competitiveness through integrated manufacturing in Japan, controlling quality from adhesive formulation to final spooling. Pilot Corporation differentiates via refillable system architectures that reduce per-use material intensity for institutional buyers.
Correction fluid and tape comprise error-concealment products applied to paper surfaces to mask handwritten or printed mistakes before re-entry. Correction fluid typically suspends titanium dioxide pigment in a volatile solvent carrier that dries to an opaque film, while correction tape deposits a dry, tear-resistant polymer layer through a pressure-fed dispenser mechanism. Correction tape leads product type demand in office environments due to immediate dry-time and no-odor performance, while water-based formulations represent the fastest-growing material category as institutions phase out aromatic solvents. Eco-friendly packaging commands emerging margin pools as procurement policies at educational districts and corporate facilities embed sustainability criteria into supplier scorecards.
EPA oversight of volatile organic compound emissions shapes solvent selection in U.S.-manufactured correction fluids, while REACH registration requirements in Europe restrict certain halogenated compounds previously common in quick-dry formulations. Japan's Ministry of Economy, Trade and Industry (METI) promotes reduced-waste stationery standards that incentivize refillable tape designs and concentrated fluid formats. Stakeholders must monitor how fragmented national chemical regulations fragment formulation platforms and whether centralized testing investments can unlock multi-jurisdiction product registration economies.
Market Dynamics
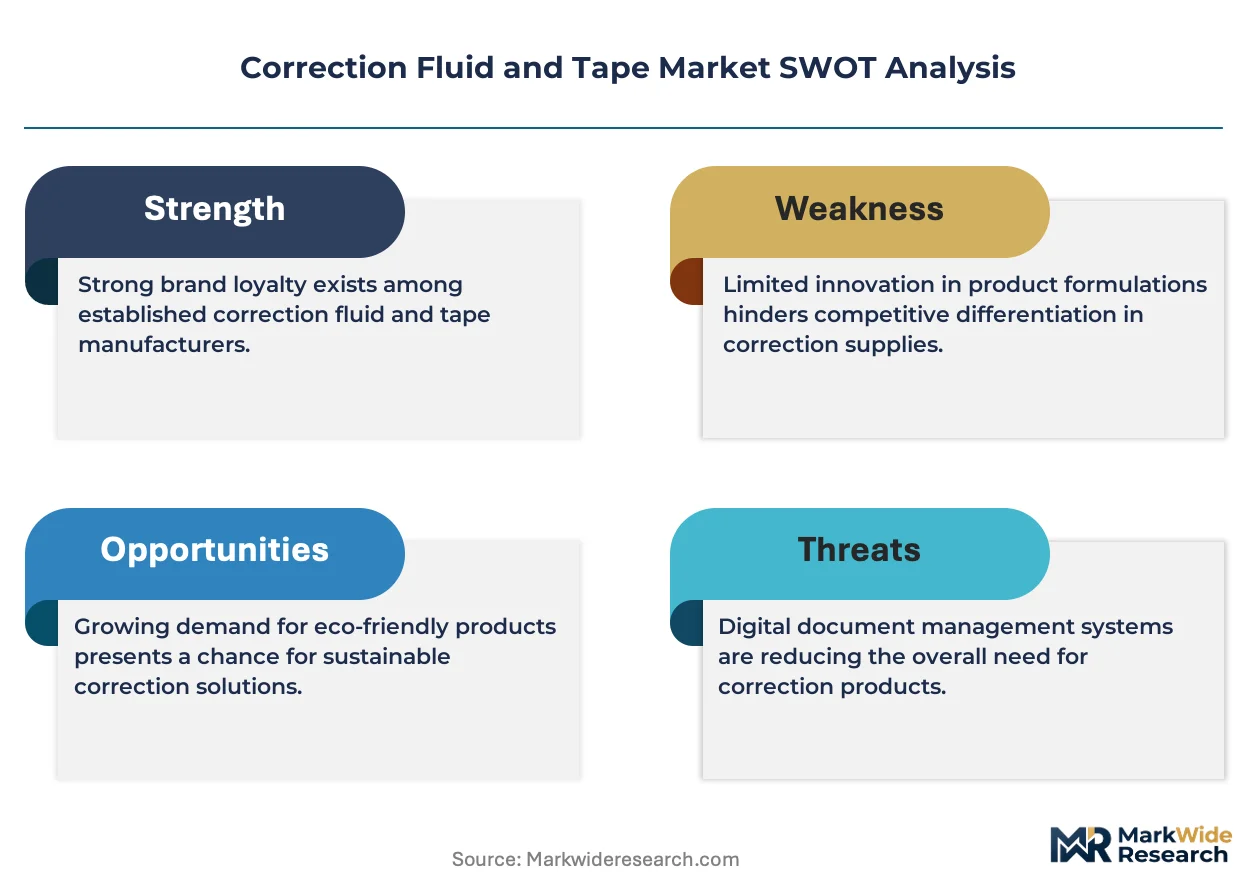
The correction fluid and tape market is experiencing fundamental restructuring as water-based solvent formulations displace aromatic hydrocarbon systems under chemical safety mandates from EPA and REACH. This compositional pivot demands reformulation investment while opening premium positioning for compliant manufacturers.
Growth Catalysts
- REACH chemical registration:European ECHA requirements for solvent disclosure are accelerating R&D investment in bio-derived carrier fluids, creating first-mover advantages for compliant suppliers.
- Educational procurement centralization:School district bulk purchasing programs in India and Vietnam are standardizing correction tape specifications and expanding volume commitments.
- Titanium dioxide recovery:Pigment recycling infrastructure in Japan is lowering input costs for domestic fluid manufacturers through closed-loop processing partnerships.
Market Restraints
- Petrochemical volatility:Acrylic polymer feedstock prices fluctuate with crude oil indices, compressing tape extrusion margins unpredictably.
- Single-source concentration:Precision dispenser spring mechanisms rely on three Japanese component suppliers, creating vulnerability to localized disruption.
- Digital substitution:Tablet-based learning platforms and electronic document workflows in South Korean schools are reducing physical correction product consumption.
Strategic Opportunities
- Indonesia domestic production:Local manufacturing incentives under the country's industrial upgrading program offer tariff advantages for regional supply.
- Refillable system architecture:Modular tape cartridge designs align with Japan METI waste-reduction standards and command institutional premium pricing.
- E-commerce direct fulfillment:Stationery subscription services bypass traditional wholesale distributors and capture recurring revenue streams.
Industry Challenges
- Formulation chemist scarcity:Expertise in volatile organic compound compliance testing is concentrated among aging specialists in European regulatory consultancies.
- Multi-jurisdiction registration:Simultaneous EPA pre-manufacture notification and REACH dossier preparation extends product launch timelines substantially.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Correction Fluid and Tape Market |
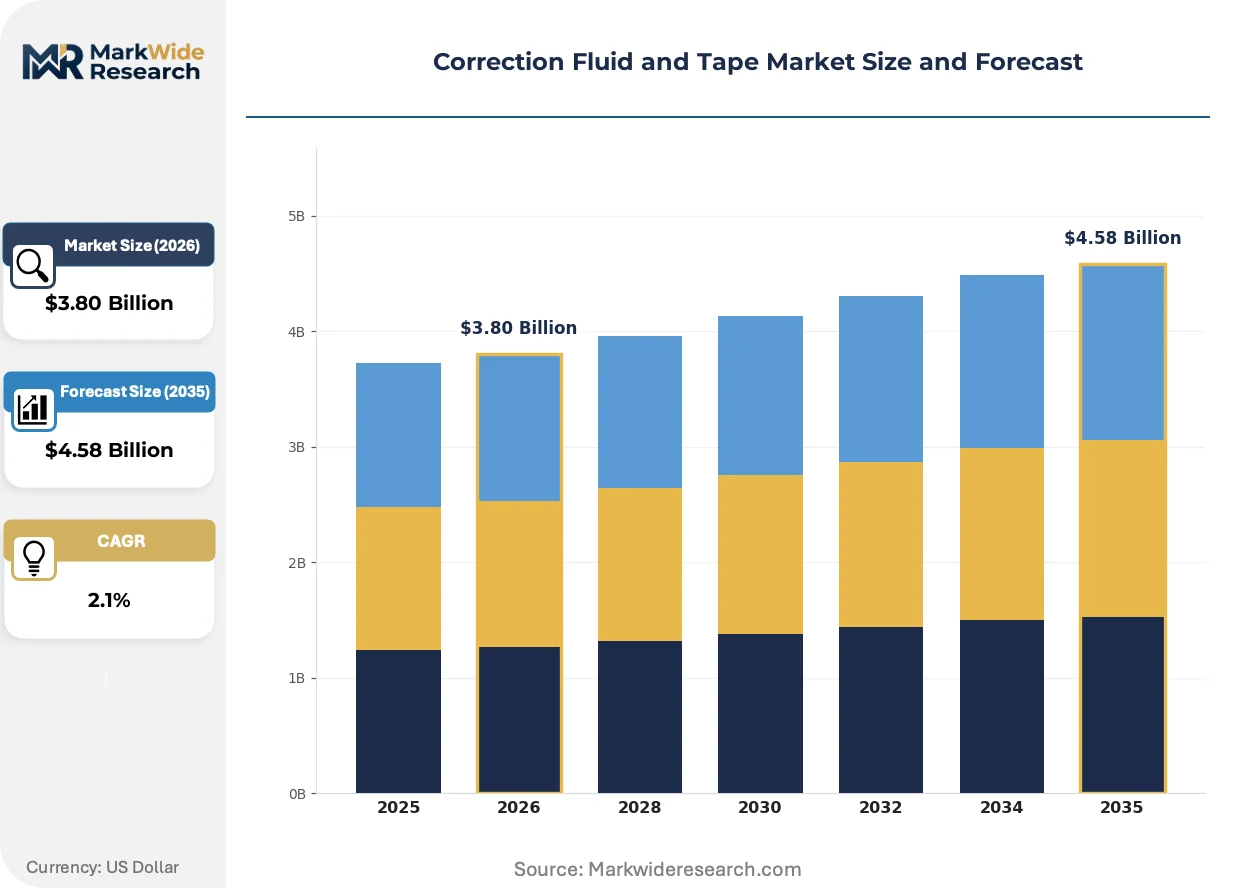
| Market Size in 2026 | $3.80 Billion |
| Market Size in 2035 | $4.58 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Correction Fluid, Correction Tape, Correction Pen, Marker Application: Office Use, School Supplies, Art and Craft, DIY Projects Material: Water-based, Oil-based, Acrylic, Latex Packaging Type: Bulk Packaging, Retail Packaging, Eco-friendly Packaging, Refillable Containers |
| Companies Covered | 3M Company, BIC Group, Tombow Pencil Co., Ltd., Pentel Co., Ltd., Faber-Castell AG, KOKUYO, Pilot Corporation, ACCO Brands, Avery Dennison, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Correction Fluid and Tape Market Trends and Innovations
Active transformation in correction supplies centers on material science advancement, regulatory chemistry evolution, and institutional procurement restructuring. These intersecting developments are compressing traditional product lifecycles while creating new competitive differentiation vectors.
Water-based emulsion technology is decomposing the long-standing dominance of solvent-borne correction fluids. K-12 school districts in California and New York are mandating low-VOC supplies for indoor air quality compliance, forcing manufacturers to rebuild formulation platforms from feedstock selection through drying kinetics. The structural consequence is compressing margins on legacy aromatic products while enabling premium pricing for compliant alternatives.
REACH authorization requirements for halogenated solvents are reshaping European formulation portfolios. Industrial consequence includes accelerated phase-out of trichloroethylene-based quick-dry fluids and substitution with acetate ester carriers. German and French office supply distributors are responding by consolidating supplier relationships around REACH-registered manufacturers with established dossier compliance.
Institutional buyers are consolidating stationery procurement through centralized digital platforms. Amazon Business and specialized educational supply marketplaces are displacing traditional wholesale relationships for U.S. school districts and corporate facilities. This channel shift is most visible in Texas and Florida, where state-level purchasing cooperatives have migrated to e-procurement systems with sustainability scoring embedded in supplier selection algorithms.
Correction Fluid and Tape Market Segmentation
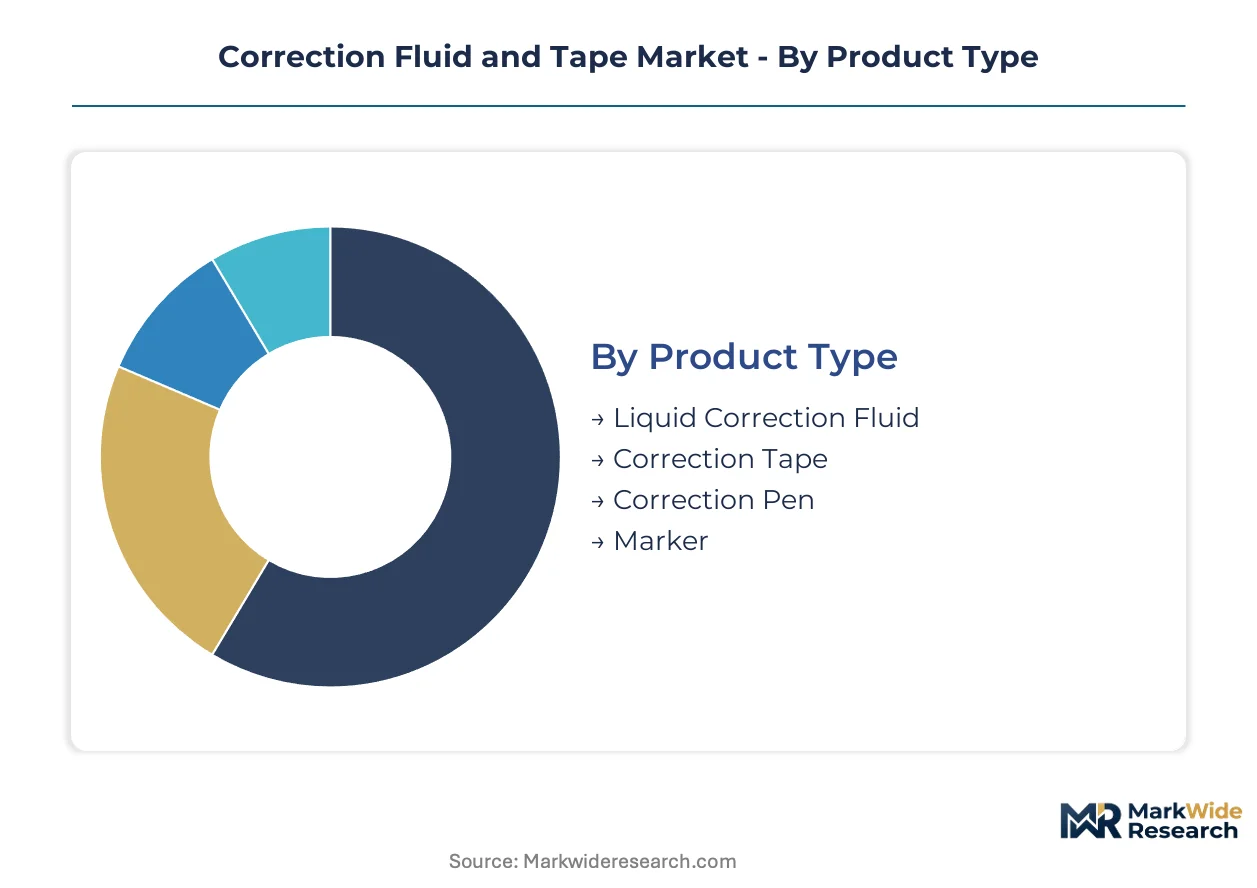
Correction supplies fragment across formulation chemistry, application environment, and institutional procurement requirements. Each segmentation axis carries distinct margin profiles and regulatory exposure that reshape supplier strategy.
Product Type:
Liquid correction fluid dominates domestic manufacturing in Japan and Germany, while correction tape capacity concentrates in Southeast Asian export hubs serving North American educational procurement.
- Liquid Correction Fluid:Suspends titanium dioxide in volatile or water-based carriers to create opaque coverage over handwritten errors. Demand concentrates in European art supply channels where precision brush application matters, though EPA VOC restrictions are forcing solvent reformulation investments.
- Correction Tape:Deposits dry polymer film through pressure-fed dispensers with immediate dry-time and zero odor emission. Japanese institutional buyers drive specification standards here, with refillable architectures capturing premium positioning under METI waste-reduction guidelines.
- Correction Pen:Combines fluid reservoir with fine-point applicator for targeted error concealment.
- Marker:Broad-surface coverage format with felt-tip delivery, common in industrial document correction settings.
Correction tape holds the largest share; momentum sits with liquid correction fluid as water-based formulations displace legacy solvent systems.
Application:
Cost tier separation runs deepest here — bulk institutional contracts compress margins in school supplies while specialized art channels sustain premium pricing.
- Office Use:Corporate procurement platforms standardize on tape formats for immediate usability and indoor air quality compliance. German and French facility managers increasingly embed sustainability scoring into supplier selection algorithms.
- School Supplies:District-level bulk purchasing in India and Vietnam drives volume concentration, with centralized digital procurement displacing traditional wholesale relationships. California and New York K-12 mandates for low-VOC supplies are forcing manufacturer reformulation.
- Art and Craft:Precision application requirements sustain smaller-batch fluid production with specialized pigment loading.
- DIY Projects:Consumer retail channel with sporadic demand patterns and higher price elasticity.
School supplies generate the highest volume throughput; art and craft commands the steepest expansion trajectory as hobbyist spending climbs.
Material:
Supply concentration in acrylic polymer feedstock creates margin vulnerability when crude indices fluctuate, while water-based emulsion R&D investment is redrawing competitive boundaries.
- Water-based:Emulsion technology using bio-derived carriers that eliminate aromatic hydrocarbon exposure. REACH ECHA registration requirements for solvent disclosure are accelerating compliant supplier advantages across European distribution.
- Acrylic:Thermoplastic polymer film substrate in tape construction with tear-resistant mechanical properties. Japanese precision dispenser manufacturing relies on three component suppliers, creating localized disruption risk.
- Oil-based:Legacy solvent-borne formulations facing phased reduction under EPA pre-manufacture notification requirements.
- Latex:Natural rubber-derived binder systems with limited commercial penetration.
Acrylic dominates tape substrate supply; water-based formulations are gaining share fastest as institutional procurement policies embed chemical safety criteria.
Packaging Type:
Customer type divergence separates institutional buyers demanding bulk formats from sustainability-focused procurement officers prioritizing circular packaging architectures.
- Refillable Containers:Modular cartridge designs align with Japan METI reduced-waste stationery standards and command recurring revenue streams through replacement component sales.
- Eco-friendly Packaging:Post-consumer recycled content and biodegradable materials respond to procurement policy evolution at U.S. educational districts and corporate facilities.
- Bulk Packaging:Institutional volume formats for school district and government supply contracts.
- Retail Packaging:Individual unit presentation for consumer channel distribution.
Retail packaging holds current volume leadership; refillable containers are climbing the fastest as regulatory incentives reshape institutional specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal concentrated tape production in Southeast Asian manufacturing hubs offsetting fluid formulation expertise retained in Japan and Germany. Import dependence for precision dispenser components creates vulnerability in North American supply chains.
United States
Corporate facility managers drive tape specification for indoor air quality compliance. EPA pre-manufacture notification requirements extend reformulation timelines for solvent-borne fluids. Texas and Florida state purchasing cooperatives have migrated to e-procurement systems with embedded sustainability scoring.
Japan
METI reduced-waste stationery standards incentivize refillable tape architectures in institutional procurement. Domestic manufacturers control quality from adhesive formulation through final spooling. Precision dispenser spring mechanisms rely on three component suppliers clustered in Nagoya and Osaka industrial zones.
Germany
REACH authorization requirements accelerate phase-out of halogenated solvents in quick-dry formulations. Office supply distributors consolidate supplier relationships around ECHA-registered manufacturers. Art supply channels in Berlin and Munich sustain smaller-batch fluid production with specialized pigment loading.
India
School district bulk purchasing programs standardize correction tape specifications and expand volume commitments. BIS quality standards for stationery products reshape import substitution dynamics. Domestic production scales in Maharashtra and Gujarat manufacturing corridors serving educational procurement.
Vietnam
Centralized digital procurement platforms displace traditional wholesale relationships for educational supply. Industrial upgrading incentives attract regional tape extrusion capacity. Ho Chi Minh City and Hanoi clusters process acrylic polymer feedstock for export-oriented manufacturing.
Correction Fluid and Tape Market Competitive Landscape
Concentration sits with diversified stationery conglomerates controlling integrated manufacturing from raw material through finished goods. Three strategic archetypes dominate: polymer science specialists leveraging film substrate expertise, integrated Japanese manufacturers with captive adhesive formulation, and refillable system architects capturing institutional premium. Competitive moves center on backward integration into titanium dioxide pigment supply and geographic expansion into Indonesian domestic production zones.
Within the polymer science tier, 3M Company represents substrate innovation capabilities. Among integrated Japanese manufacturers, Tombow Pencil Co., Ltd. and Pilot Corporation exemplify quality control from formulation through final assembly. These three anchors occupy positions spanning premium film technology, manufacturing integration, and refillable system architecture respectively.
| Leading Market Players |
|---|
| 3M Company |
| BIC Group |
| Tombow Pencil Co., Ltd. |
| Pentel Co., Ltd. |
| Faber-Castell AG |
| KOKUYO |
| Pilot Corporation |
| ACCO Brands |
| Avery Dennison |
| Others |
Pricing and Supply Chain Analysis
Water-based emulsion chemistry displacing aromatic hydrocarbon formulations is redrawing supply geography toward Japan and Germany while compressing margins on legacy solvent products and enabling premium capture for REACH-registered alternatives. This substitution dynamic concentrates high-value fluid manufacturing in regulatory-compliant zones while pushing commodity tape extrusion toward Southeast Asian cost basins.
Pricing Analysis
The customization-premium spread separates standard correction tape from refillable modular architectures that command institutional pricing under Japan METI waste-reduction guidelines. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier and volume scale, with bulk educational procurement compressing margins while specialized art channels sustain premium positioning. Pricing pressure stems from petrochemical volatility in acrylic polymer feedstock, with margins tightening unpredictably when crude indices fluctuate. School district buyers exhibit highest price sensitivity, whereas corporate facility managers prioritize indoor air quality compliance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Southeast Asian manufacturing hubs to North American educational procurement channels hinge on container availability through the Shanghai-Los Angeles trade lane. Tape production concentrates in Vietnam, Indonesia, and Thailand, while fluid formulation expertise clusters in Japan and Germany. Raw material dependencies encompass titanium dioxide pigment, acrylic polymer substrates, and precision dispenser spring mechanisms. Single-source concentration among three Japanese component suppliers creates localized disruption vulnerability. Distribution runs through Amazon Business and specialized educational supply marketplaces that displace traditional wholesale relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to educational procurement normalization following pandemic-era digital substitution shocks. Institutional stationery budgets are rebounding as physical classroom activity resumes across Asian manufacturing hubs.
For Market Incumbents: Fortify backward integration into titanium dioxide pigment supply to offset feedstock volatility exposure. Deepen captive production of precision dispenser components in Nagoya and Osaka industrial zones to mitigate single-source concentration risk. Prioritize REACH dossier maintenance and EPA pre-manufacture notification compliance to defend institutional contract eligibility against emerging regional challengers.
For New Entrants and Emerging Players: Differentiate on refillable system architecture aligned with Japan METI reduced-waste standards to capture premium positioning in institutional procurement. Target Indonesia domestic production zones under industrial upgrading incentives for tariff-advantaged regional supply. Penetrate through e-commerce direct fulfillment and stationery subscription services that bypass entrenched wholesale distributor relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with polymer science specialists holding film substrate expertise but lacking integrated adhesive formulation capabilities. Long-term viability favors manufacturers with multi-jurisdiction chemical registration economies and refillable platform architectures. Watch for inflection signals in BIS quality standard enforcement reshaping Indian import substitution dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Supply | Captive titanium dioxide processing lowers input cost volatility for fluid manufacturers. |
| Refillable System Architecture Development | Modular cartridge designs command METI-compliant institutional premium pricing. |
| REACH Dossier Compliance Investment | ECHA-registered status unlocks consolidated supplier relationships with German distributors. |
| Indonesia Domestic Production Establishment | Tariff advantages under industrial upgrading program strengthen regional supply positioning. |
| E-commerce Direct Fulfillment Launch | Subscription services capture recurring revenue streams bypassing wholesale intermediaries. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from stationery conglomerates, and BIS quality standard documentation. Primary interviews encompassed procurement officers at U.S. K-12 school districts, plant managers at Japanese tape manufacturing facilities, regulatory affairs specialists at European chemical consultancies, and category buyers at Amazon Business. Secondary validation drew from EPA pre-manufacture notification records, ECHA REACH registration databases, and METI reduced-waste stationery guidelines. Bottom-up volume modeling triangulated against top-down market sizing across formulation chemistry and application segments.
Segmentation dimensions modeled include product type, application environment, material chemistry, and packaging format across the projection horizon. CAGRs were derived from demand elasticity analysis tied to educational procurement cycles and regulatory phase-in timelines. Industry-specific forecast inputs encompassed titanium dioxide price indices, acrylic polymer feedstock volatility bands, and digital substitution penetration rates in South Korean schools.
Forecasts assume regulatory continuity in EPA VOC enforcement, REACH authorization requirements, and METI waste-reduction standards; material policy shifts would require re-modeling of solvent formulation investment returns and refillable system adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Mexico Adhesives Market
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
Global Adhesion Barrier Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
South America Contact Adhesives Market
Adhesives & Sealants
Tissue Adhesives Market
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Europe Construction Adhesives Market
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
Gasket and Seal Material Market
Adhesives & Sealants
Industrial Wood Adhesives Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market