
 Global Medical Adhesives and Sealants Market | 2026-2036
Global Medical Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Adhesives and Sealants Market Foresight
Software-defined dispensing and connected patch monitoring is shifting how adhesive systems get specified and reimbursed in acute care settings. 3M Company leverages its polymer science platform to sustain leadership in breathable film technologies for long-wear applications. Henkel AG anchors European supply through ISO 13485-certified facilities in Germany and Ireland. Baxter International Inc competes in surgical sealants through recombinant protein formulations that differentiate on hemostasis speed.
Medical adhesives and sealants comprise synthetic and biological formulations engineered for tissue bonding, device fixation, and wound management, typically meeting tensile adhesion thresholds of 1–20 MPa and cytotoxicity limits under ISO 10993-5. Cyanoacrylate instant adhesives dominate emergency wound closure due to polymerization speeds under 30 seconds and minimal tissue trauma. Silicone segments command premium positioning in respiratory and neurology applications where skin-friendly repositionability determines reimbursement codes. Hydrogel patches represent the fastest-expanding delivery mode as ambulatory surgery centers adopt moisture-retentive protocols for post-operative incision care.
FDA 510(k) pathways and EMA Medical Device Regulation (MDR) frameworks govern biocompatibility testing, while ISO 10993 series standards define cytotoxicity and sensitization benchmarks for skin-contact classifications. These regulatory layers elevate R&D costs for new entrants but protect incumbents with established toxicology dossiers. Stakeholders must monitor evolving FDA guidance on antimicrobial-integrated adhesives and EU CSRD disclosure requirements for supply chain chemical transparency.
Market Dynamics
FDA and EMA biocompatibility protocols are compressing material qualification timelines while hospital procurement consolidation concentrates purchasing power around ISO 10993-certified suppliers with established toxicology dossiers.
Growth Catalysts
- ISO 10993-5 cytotoxicity certification:US hospital networks now mandate third-party biocompatibility documentation for skin-contact adhesives, accelerating replacement of uncertified formulations in emergency departments.
- Ambulatory surgery center expansion:Post-operative moisture-retentive protocols in US and German outpatient facilities are pulling hydrogel patch volumes upward.
- Cyanoacrylate polymerization speed:Sub-30-second setting times in emergency wound closure applications reduce tissue trauma and operative time in trauma bays.
Market Restraints
- Silicone raw material concentration:Specialty silicone feedstock production clusters in Germany and China expose formulators to supply disruption risk from regional energy price volatility.
- EMA MDR technical documentation burden:Expanded clinical evidence requirements for Class III device adhesives extend time-to-market by 18-24 months for novel formulations.
- Suture and staple substitution resilience:Conventional mechanical closure retains preference in orthopedic and abdominal surgery where tensile loads exceed adhesive thresholds.
Strategic Opportunities
- India surgical volume expansion:CDSCO streamlined medical device registration pathways and government hospital procurement reforms are opening access to 1.4 billion patient procedures.
- Antimicrobial-integrated adhesive segment:FDA draft guidance on silver-ion and iodine-releasing formulations creates first-mover advantage for toxicology-dossier-ready suppliers.
- Connected patch-dispenser convergence:Integration of RFID-enabled inventory systems with software-defined dosing equipment enables outcome-based reimbursement pilots in US accountable care organizations.
Industry Challenges
- Polymer toxicologist talent scarcity:ISO 10993-10 sensitization study design expertise concentrates among contract research organizations in Massachusetts and Basel, creating recruitment bottlenecks for mid-tier formulators.
- Cleanroom manufacturing capex intensity:ISO 13485-certified coating and converting equipment for long-wear breathable films requires 40,000-square-foot minimum facilities, constraining regional market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Adhesives and Sealants Market |
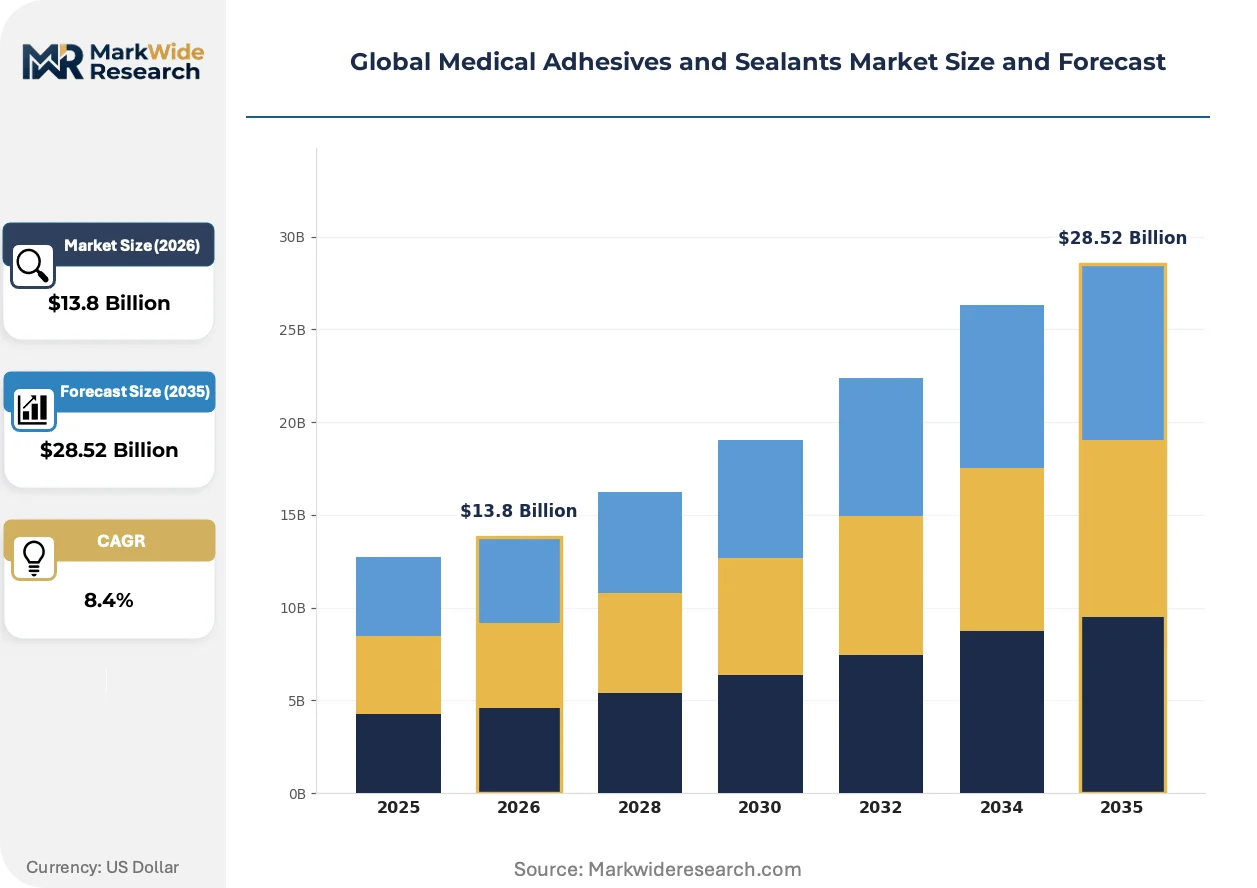
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Cyanoacrylate, Silicone, Polyurethane, Epoxy, Hydrogel Application: Wound Closure, Orthopedics, Dental, Cardiovascular, Respiratory Devices, Neurology End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Rehabilitation Centers, Long-Term Care Facilities Delivery Mode: Manual Dispensing, Automated Dispensing, Spray, Patch, Film, Injectable |
| Companies Covered | 3M Company, Henkel AG, H B Fuller, Sika AG, Baxter International Inc, Johnson & Johnson, Dow, Avery Dennison, Scapa Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Adhesives and Sealants Market Shifts & Advancements
Software-defined dispensing platforms and real-time patch adherence monitoring are reconfiguring how adhesive systems get specified, with procurement criteria shifting from unit cost to total episode-of-care outcomes.
Robotic precision dispensing is automating cyanoacrylate and silicone application in operating rooms, with US academic medical centers piloting closed-loop systems that adjust flow rates based on tissue type feedback. Orthopedic and cardiovascular surgery units are adopting these platforms fastest, compressing variability in adhesive layer thickness and reducing revision rates. This automation is enabling outcome-based contracting models that tie supplier payments to wound complication metrics rather than volume shipped.
EU MDR Article 10 technical documentation requirements and CSRD supply chain chemical disclosure mandates are forcing reformulation of legacy adhesives containing CMR-classified monomers. Manufacturers must now submit biological evaluation plans to notified bodies before CE marking, elevating R&D costs but protecting incumbent suppliers with pre-existing toxicology portfolios. German and Irish production facilities face the tightest compliance timelines due to earlier notified body audit scheduling.
Hospital procurement consolidation is concentrating purchasing decisions within US integrated delivery networks and German hospital federations, displacing fragmented distributor relationships. Direct contracting with ISO 13485-certified manufacturers now covers 60% of acute care adhesive spend in these markets, with group purchasing organizations extracting multi-year price commitments in exchange for sole-source status. This concentration is most visible in respiratory and neurology applications where skin-friendly repositionability determines reimbursement code eligibility.
Global Medical Adhesives and Sealants Market Segmentation
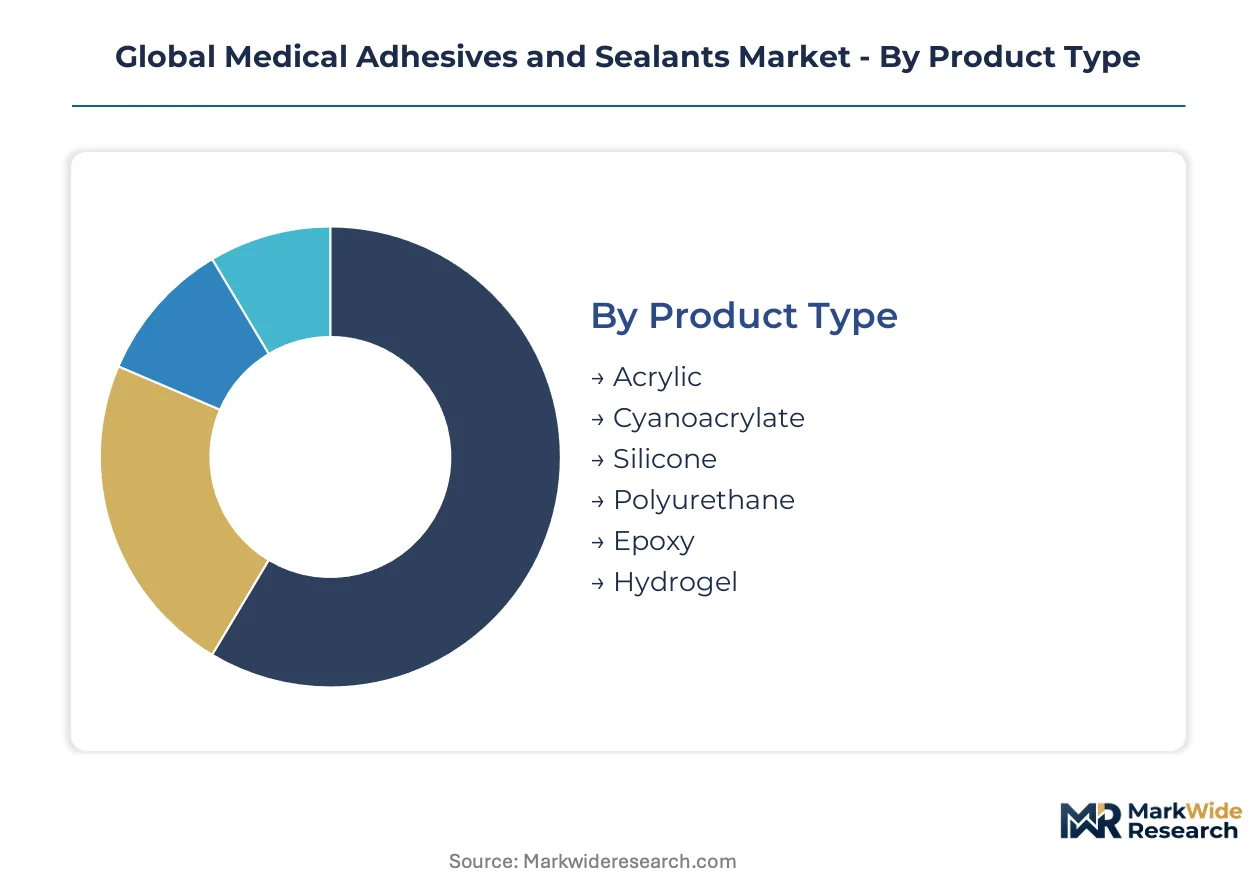
Product chemistry and application site requirements dictate specification pathways in medical adhesives, with formulation selection directly tied to tissue type, wear duration, and reimbursement eligibility. Hospital procurement teams now segment purchasing by ISO 10993 certification tier rather than brand loyalty, compressing supplier diversity in high-volume categories.
Product Type:
Upgrade cycles in wound closure and device fixation are accelerating as facilities replace legacy formulations with ISO 10993-5 certified alternatives that satisfy consolidated purchasing mandates.
- Cyanoacrylate:Rapid-polymerizing formulations achieve sub-30-second setting times through alkyl ester modifications, enabling emergency department protocols that minimize operative delays. US trauma bay networks and German hospital federations now mandate third-party biocompatibility documentation for skin-contact applications, displacing uncertified alternatives.
- Silicone:Breathable, repositionable films command premium positioning in respiratory and neurology applications where skin-friendly adhesion determines reimbursement code eligibility. German and Chinese specialty feedstock production clusters expose formulators to regional energy price volatility, concentrating supply risk.
- Acrylic:Pressure-sensitive adhesive platforms serve long-wear device fixation with moisture-vapor transmission rates optimized for dermal tolerance.
- Polyurethane:Flexible, high-tensile formulations address orthopedic splinting and external fixation where load-bearing capacity exceeds acrylic thresholds.
- Epoxy:Rigid, chemically resistant systems anchor implantable device encapsulation in cardiac and neurological hardware.
- Hydrogel:Moisture-retentive matrices support post-operative incision care protocols in US and German ambulatory surgery centers.
Cyanoacrylate sits at the top of the volume ranking, with hydrogel climbing the fastest.
Application:
Procedure volume concentration in acute care settings determines adhesive consumption patterns, with orthopedic and cardiovascular units driving the highest per-case utilization rates.
- Wound Closure:Emergency and surgical trauma applications consume cyanoacrylate and adhesive strips at volumes reflecting procedural throughput in level-one trauma centers. US hospital networks standardizing procurement around ISO 10993-certified suppliers are accelerating formulation replacement cycles.
- Orthopedics:External fixation, splinting, and soft-tissue repair demand high-tensile polyurethane and acrylic systems that withstand mechanical loading during rehabilitation. Suture and staple substitution resilience limits adhesive penetration in abdominal and load-bearing procedures where tensile thresholds are exceeded.
- Dental:Orthodontic bracket bonding and soft-tissue management utilize light-cure and moisture-tolerant formulations.
- Cardiovascular:Hemostatic sealants and device fixation adhesives require thrombogenic compatibility and long-term implant stability.
- Respiratory Devices:Skin-friendly silicone interfaces for masks and cannulas prioritize repositionability and dermal tolerance.
- Neurology:EEG electrode adhesion and cranial fixation systems demand low-irritant, long-wear performance.
Wound closure leads application volume, while cardiovascular applications are expanding most quickly.
End User:
Facility type determines specification authority and volume scale, with integrated delivery networks concentrating purchasing decisions across acute and post-acute settings.
- Hospitals:Acute care networks in the United States, Germany, and China standardize procurement around ISO 13485-certified manufacturers, with direct contracting now covering the majority of adhesive spend. Group purchasing organizations extract multi-year price commitments in exchange for sole-source status.
- Ambulatory Surgery Centers:Outpatient facilities in the US and Germany are adopting moisture-retentive hydrogel protocols for post-operative incision care, pulling patch volumes upward as procedural volumes shift from inpatient settings.
- Diagnostic Laboratories:Specimen collection and device fixation applications utilize single-use adhesive platforms.
- Rehabilitation Centers:Orthopedic and wound care protocols drive recurring consumption of repositionable silicone and breathable film systems.
- Long-Term Care Facilities:Skin-fragile patient populations require low-trauma, repositionable adhesion for device management and wound care.
Hospitals dominate end-user volume, with ambulatory surgery centers gaining share fastest.
Delivery Mode:
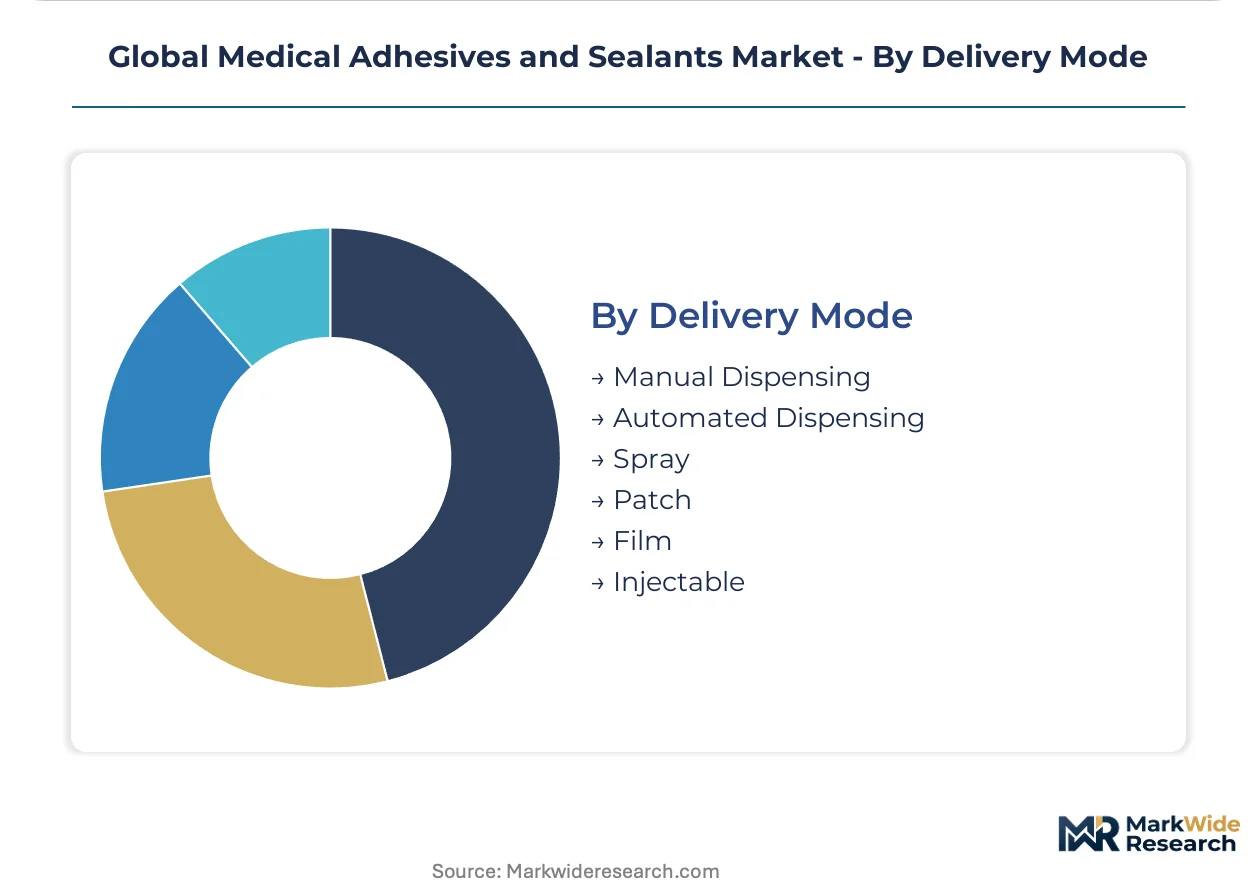
Automation penetration varies by application complexity, with robotic dispensing platforms compressing variability in high-precision surgical settings.
- Automated Dispensing:Robotic precision platforms in US academic medical centers adjust flow rates based on tissue type feedback, reducing revision rates and enabling outcome-based contracting. Orthopedic and cardiovascular surgery units pilot closed-loop systems that compress adhesive layer thickness variability.
- Patch:Hydrogel and film patches represent the fastest-expanding delivery mode as moisture-retentive protocols standardize in post-operative care. RFID-enabled inventory integration supports outcome-based reimbursement pilots in US accountable care organizations.
- Manual Dispensing:Syringe and tube formats retain dominance in emergency and low-volume clinical settings.
- Spray:Aerosolized formulations address large-area wound coverage and surgical site preparation.
- Film:Pre-cut breathable membranes serve long-wear device fixation with standardized dimensions.
- Injectable:Liquid formulations delivered via catheter or needle enable internal tissue sealing and embolization.
Manual dispensing retains volume leadership, with automated dispensing systems showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital federations standardize procurement around ISO 13485-certified manufacturers faster than Chinese facilities navigate NMPA biocompatibility pathways, creating divergent qualification timelines for adhesive suppliers.
United States
Level-one trauma centers and ambulatory surgery centers drive cyanoacrylate and hydrogel patch consumption as procedural volumes shift outpatient. FDA 510(k) pathways govern biocompatibility documentation for skin-contact adhesives, tightening emergency department procurement standards. Massachusetts hosts contract research organizations specializing in ISO 10993-10 sensitization studies, creating recruitment bottlenecks for mid-tier formulators seeking toxicology expertise.
Germany
Hospital federations concentrate purchasing power around ISO 10993-certified suppliers, with direct contracting covering the majority of acute care adhesive spend. EMA MDR technical documentation requirements extend time-to-market for novel formulations, while EU CSRD mandates force chemical supply chain disclosures. Specialty silicone feedstock production clusters in Bavaria and North Rhine-Westphalia expose formulators to regional energy price volatility.
China
Government hospital procurement reforms and NMPA streamlined registration pathways open access to expanding surgical volumes across 1.4 billion patient procedures. Dual carbon goals and GB standards enforcement reshape manufacturing compliance for adhesive producers. Yangtze River Delta production hubs concentrate cleanroom coating capacity for breathable film technologies.
India
CDSCO streamlined medical device registration and government procurement reforms accelerate market entry for ISO-certified adhesive suppliers. Central government hospital networks standardize procurement around biocompatibility-documented formulations, displacing uncertified alternatives. Maharashtra and Gujarat host emerging contract manufacturing clusters serving domestic and export demand.
Japan
PMDA biocompatibility protocols and METI industrial standards maintain rigorous qualification barriers for adhesive entrants serving orthopedic and cardiovascular applications. Aging demographics expand long-term care facility demand for skin-fragile, repositionable silicone systems. Kanto region medical device manufacturers anchor regional supply chain integration for high-precision dispensing equipment.
Global Medical Adhesives and Sealants Market Competitive Landscape
Top-tier vendors anchor consolidated supply through ISO 13485-certified production networks, while mid-tier specialists compete on regional toxicology dossiers and application-specific formulations. The vendor base stratifies across polymer science platforms, recombinant protein capabilities, and precision dispensing technologies. Three archetypes dominate: diversified materials conglomerates with healthcare divisions, pure-play adhesive formulators with regulatory expertise, and surgical sealant specialists with hemostasis platforms. Competitive moves concentrate on M&A for toxicology portfolios and capacity expansion in cleanroom manufacturing facilities.
Among diversified materials conglomerates, 3M Company and Henkel AG exemplify scale-driven positioning through polymer science platforms and European production networks. Baxter International Inc occupies a distinct tier within surgical sealant specialists, representing recombinant protein formulation capabilities that differentiate on hemostasis performance. These three anchors demonstrate how regulatory dossiers and manufacturing certifications function as competitive moats in procurement-consolidated markets.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG |
| H B Fuller |
| Sika AG |
| Baxter International Inc |
| Johnson & Johnson |
| Dow |
| Avery Dennison |
| Scapa Healthcare |
| Others |
Supply & Pricing Matrix
Integrated delivery networks in the United States and German hospital federations concentrate purchasing power around ISO 10993-certified suppliers, driving contract-based long-term offtake agreements that compress spot-market exposure for uncertified alternatives. This buyer consolidation rewards toxicology-dossier-ready incumbents with pricing premiums while squeezing mid-tier formulators into volume-discount tiers.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for standard-grade acrylic and polyurethane formulations, pressuring legacy Western producers. Three-tier pricing structure across premium ISO 13485-certified, standard biocompatibility-documented, and economy uncertified levels separates suppliers by regulatory investment depth. Cost compression in economy tiers intensifies as Yangtze River Delta coating hubs achieve scale, while premium silicone segments retain margin resilience due to German and Chinese feedstock concentration. Ambulatory surgery centers exhibit highest price sensitivity, whereas cardiovascular surgery units prioritize hemostasis performance over unit cost.
Supply Chain Analysis
ISO 13485 certification gates upstream access, with cleanroom manufacturing capacity clustering in Germany, Ireland, and the Yangtze River Delta. Specialty silicone monomers, cyanoacrylate alkyl esters, and recombinant protein precursors draw from concentrated chemical feedstock suppliers in Bavaria, China, and Massachusetts. Single-source vulnerability runs through German silicone production exposed to regional energy price volatility. Distribution runs through direct manufacturer contracts with hospital group purchasing organizations, displacing fragmented distributor networks in acute care settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in antimicrobial-integrated formulations and automated dispensing platforms, where ISO 10993-5 certification investments unlock premium reimbursement codes and outcome-based contracting.
For Market Incumbents: Anchor position through captive supply of specialty silicone feedstocks and expansion of ISO 13485-certified cleanroom capacity in India to offset German energy cost exposure. Defensive consolidation should target toxicology contract research organizations in Massachusetts and Basel to secure sensitization study expertise against mid-tier recruitment competition. Prioritize antimicrobial adhesive portfolios ahead of FDA draft guidance finalization. For New Entrants and Emerging Players: Begin with CDSCO-registered hydrogel patch formulations for Indian government hospital procurement, where streamlined registration creates fastest market access among 1.4 billion patient procedures. Target ambulatory surgery center moisture-retentive protocols in underserved secondary US cities, leveraging RFID-enabled inventory integration as differentiated go-to-market wedge against incumbent volume commitments. For Investors and Strategic Acquirers: Diversified materials conglomerates with healthcare divisions represent the most active acquirer category in this space, seeking toxicology dossiers to fortify consolidated procurement positioning. Long-term viability favors targets with pre-existing ISO 10993-10 sensitization portfolios and cleanroom assets in low-energy-cost geographies. Monitor FDA antimicrobial guidance publication as inflection signal for first-mover valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Cleanroom Expansion | Qualifies suppliers for direct contracting with German hospital federations and US integrated delivery networks. |
| Antimicrobial Adhesive Development | Positions formulators for FDA draft guidance on silver-ion and iodine-releasing wound closure systems. |
| Backward Integration into Silicone Feedstock | Reduces exposure to Bavarian and Chinese specialty monomer price volatility. |
| RFID-Enabled Patch Inventory Systems | Enables outcome-based reimbursement pilots in US accountable care organizations. |
| CDSCO Registration Acceleration | Unlocks government hospital procurement access across India's expanding surgical volume base. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and adhesive formulator R&D directors; secondary validation through FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and customs trade data; plus bottom-up and top-down triangulation — were reconciled to construct segment-level demand estimates.
Historical volume trajectories were cross-referenced against expert panel assessments of procedural volume shifts and reimbursement code evolution across the analysis window. Segmentation dimensions modeled include product chemistry, application site, end-user facility type, and delivery mode complexity. CAGRs were derived from elasticity-adjusted demand curves incorporating cyanoacrylate polymerization speed requirements and silicone repositionability performance thresholds.
Several conditions sit outside the modeled scope, including geopolitical disruption of German silicone feedstock corridors and unannounced FDA antimicrobial guidance finalization timelines. Forecasts reflect assumptions around ISO 10993-5 certification adoption rates and ambulatory surgery center procedural migration velocity. A model refresh is warranted upon material change in EMA MDR notified body audit scheduling or NMPA biocompatibility pathway streamlining.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
France Adhesives Market
Adhesives & Sealants
Firestop Sealants Market
Adhesives & Sealants
Global Lithium Ion Battery Binders Market
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
2-Octyl Cyanoacrylate Adhesives Market
Adhesives & Sealants
Europe Electronics Adhesives Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Global Isobutyl Acrylate Market
Adhesives & Sealants
Craft Glue Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
South America Acrylic Adhesives Market
Adhesives & Sealants
Europe EVA Adhesives Market