
 Iron Flow Battery Market | 2026-2036
Iron Flow Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Iron Flow Battery Market Intelligence
Higher-purity electrolyte formulations is rotating the market toward longer-duration energy storage applications with improved performance guarantees. This shift benefits specialized producers capable of delivering consistent, high-grade materials. ESS Tech, Inc. leverages its proprietary all-iron chemistry to target utility-scale projects in North America and Europe. Meanwhile, VRB Energy specializes in vanadium-based systems, creating a distinct technology pathway within the broader flow battery landscape.
An iron flow battery is a rechargeable electrochemical cell that stores energy in liquid electrolytes containing dissolved iron salts. The system operates by pumping these electrolytes from external tanks through a stack of electrochemical cells where the redox reactions occur. Its primary purpose is providing long-duration energy storage, decoupled from power capacity, which is ideal for grid-level services. Grid Energy Storage applications represent the dominant segment, driven by large utility-scale deployments. The Renewable Integration application is expanding rapidly as intermittent solar and wind power sources require stabilization.
Incentive structures like the US Inflation Reduction Act (IRA) and China's dual carbon goals directly subsidize large-scale battery installations. Concurrently, EU Green Deal policies are creating market-pull for non-lithium storage technologies to enhance grid stability and energy independence. These regulatory frameworks establish clear demand signals for long-duration storage. Stakeholders must now decide between securing long-term electrolyte supply chains or investing in alternative, more abundant chemistries.
Market Dynamics
The central force shaping the iron flow battery market is the strategic alignment of national energy security policies with long-duration storage mandates. This creates concentrated demand in regions like China and the United States, compelling a global race to secure supply chains for high-purity electrolytes and key system components.
Growth Catalysts
- Policy Frameworks:The US Inflation Reduction Act provides substantial tax credits for domestic energy storage projects, directly accelerating utility-scale iron flow battery deployments for grid stabilization and renewable energy integration.
- National Energy Targets:China's dual carbon goals necessitate massive investment in long-duration storage infrastructure to balance its rapidly expanding intermittent wind and solar generation capacity, creating a large, state-supported market.
- Electrolyte Advancement:The development of higher-purity electrolyte formulations enhances battery performance, cycle life, and operational safety, allowing manufacturers to offer improved performance guarantees for demanding grid-level services.
Market Restraints
- System Energy Density:Iron flow batteries exhibit lower energy density compared to lithium-ion technologies, making them less suitable for applications with significant physical space constraints, such as urban or mobile installations.
- Supply Chain Concentration:The production of high-purity iron salts and other critical electrolyte components is geographically concentrated, posing a supply chain vulnerability and price volatility risk for manufacturers in other regions.
- Upfront Capital Cost:The initial capital expenditure for large-scale iron flow battery systems, including tanks, pumps, and control systems, remains a significant barrier for some project developers despite a lower lifetime cost.
Strategic Opportunities
- Emerging Market Penetration:Countries like India and Australia, with ambitious renewable energy targets and grid stability challenges, represent significant untapped markets for long-duration storage solutions beyond lithium-ion.
- Industrial Co-location:There is a growing opportunity to deploy iron flow batteries at large industrial facilities to manage peak electricity demand, reduce energy costs, and provide ancillary grid services.
- European Energy Independence:The EU Green Deal's emphasis on non-lithium, non-cobalt storage technologies to enhance grid sovereignty and reduce reliance on external supply chains creates a direct market-pull for iron flow systems.
Industry Challenges
- System Integration Complexity:Integrating large-scale flow battery systems with existing grid infrastructure and utility control software requires specialized expertise, and a lack of standardization across vendors can complicate deployment.
- Specialized Talent Scarcity:A shortage of electrochemists and power systems engineers with experience in flow battery technology hinders research, development, and the operational management of large-scale projects.
- Manufacturing Scale-Up:The high capital investment needed to build and automate manufacturing facilities for cell stacks, membranes, and electrolytes at a scale sufficient to meet projected demand is a challenge for many vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron Flow Battery Market |
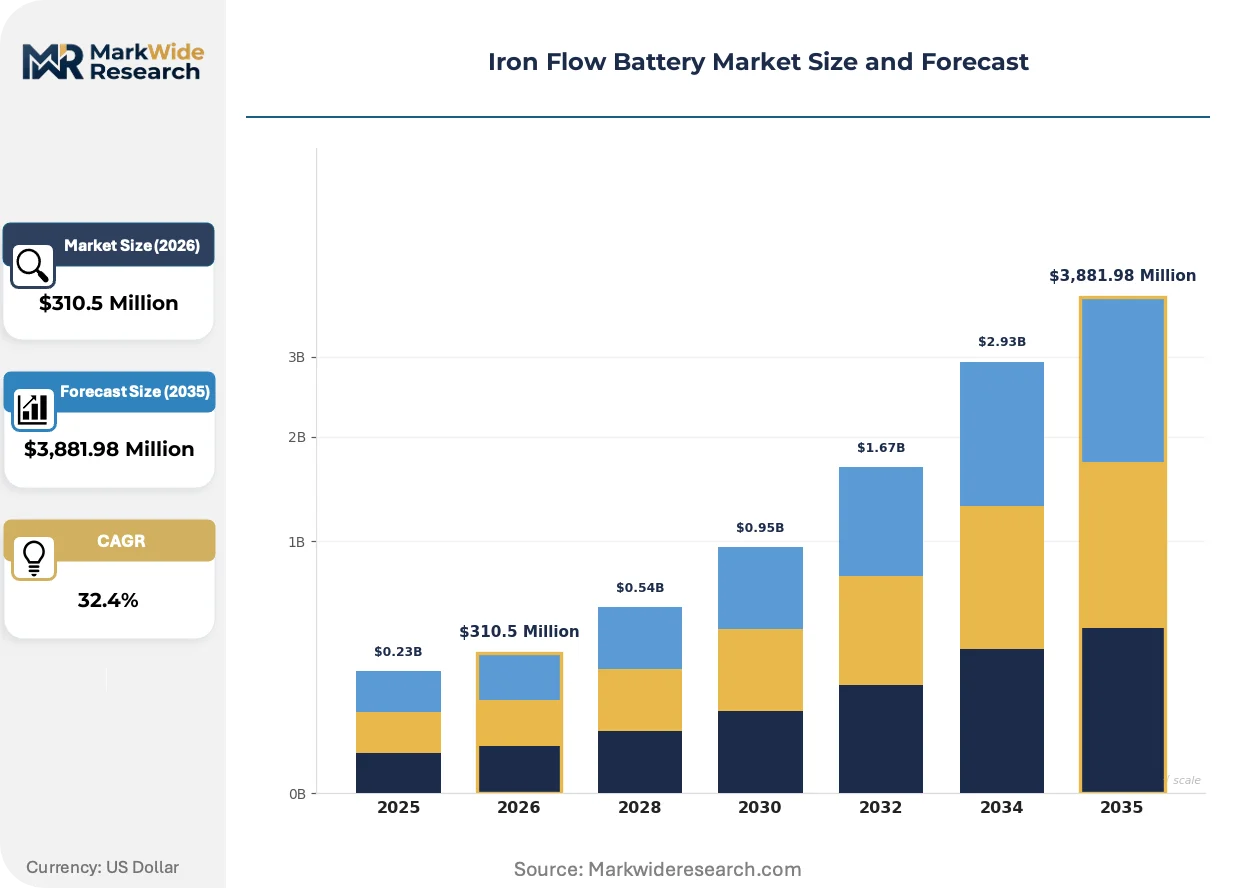
| Market Size in 2026 | $310.5 Million |
| Market Size in 2035 | $3,881.98 Million |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vanadium Redox, Zinc Bromine, Iron-Chromium, Polysulfide Bromide Application: Grid Energy Storage, Renewable Integration, Backup Power, Microgrid Systems, Industrial Facilities Deployment: Utility-Scale, Commercial, Residential, Remote Installations End User: Energy Providers, Independent Power Producers, Data Centers, Telecommunications, Agriculture |
| Companies Covered | Australian Vanadium Limited, Flux XII, Inc., ESS Tech, Inc., VRB Energy, Invinity Energy Systems, Flo, Bushveld Energy, Primus Power, Carbo Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron Flow Battery Market Strategic Shifts & Innovations
The market's evolution reflects a pivot from experimental technology to a critical grid infrastructure asset. This transition is driven by a convergence of material science breakthroughs in electrolyte chemistry and supportive government policies mandating long-duration energy storage. System designs are now prioritizing modularity and long-term performance guarantees.
Higher-purity electrolyte formulations are a key innovation that improves cycle life and reduces performance degradation over time. Utility-scale grid operators are adopting these advanced chemistries for new long-duration storage projects requiring high reliability. This advancement is bifurcating the market between premium, high-performance systems for critical grid applications and standard-grade systems for less demanding industrial use cases.
China's national policies, particularly its dual carbon goals, mandate significant deployments of non-lithium long-duration energy storage. This top-down directive creates large-scale, state-backed demand for technologies including iron flow batteries. Provincial governments are most affected, now competing to attract battery manufacturing investments and develop local supply chains to meet centrally planned grid stabilization targets.
A notable shift from outright capital purchase to long-term Energy Storage as a Service (ESaaS) contracts is gaining traction among end-users. This model allows utilities and industrial customers to avoid large upfront investments by paying a recurring fee for guaranteed capacity and availability. The trend is most visible in North America and Europe, where sophisticated project financing and third-party asset ownership models are well-established.
Iron Flow Battery Market Segmentation
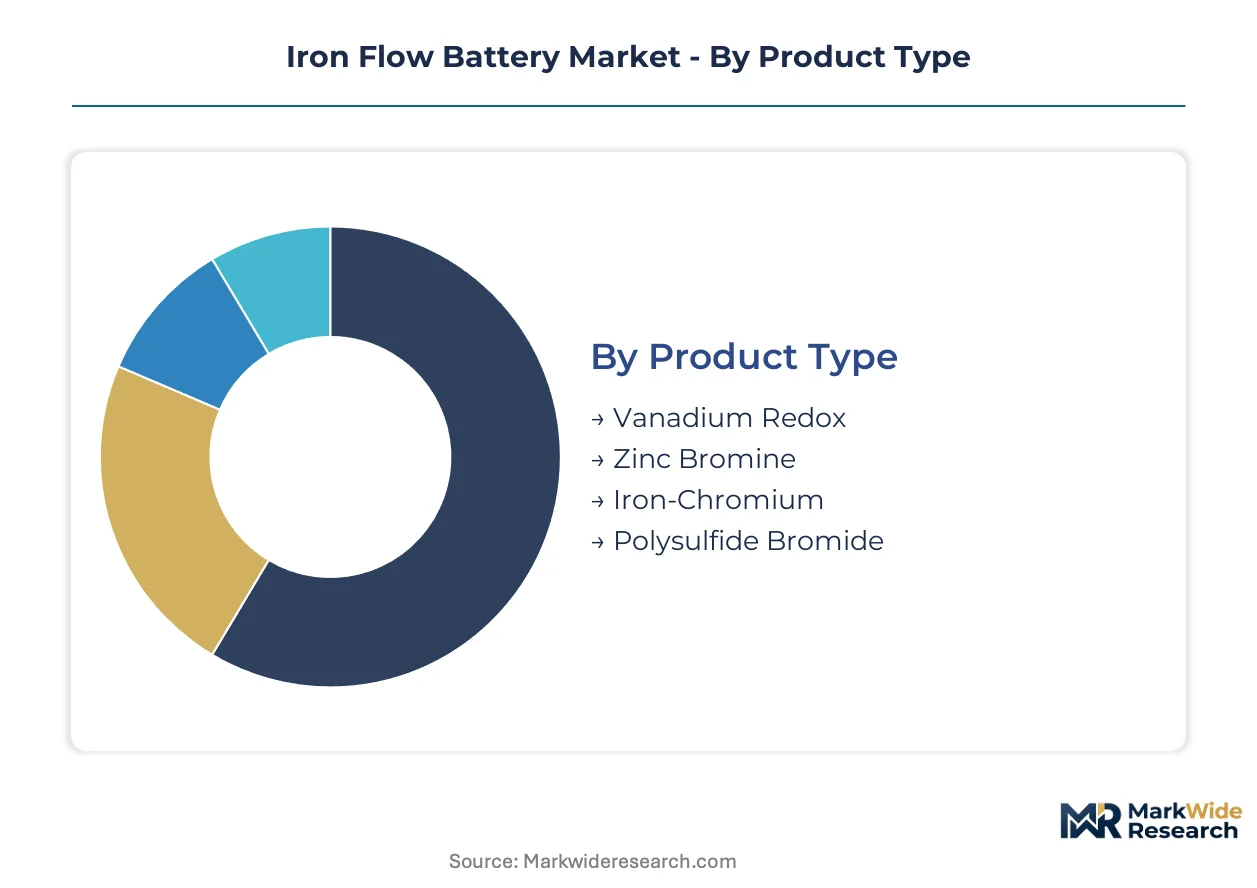
The iron flow battery market exhibits diverse operational characteristics and end-user requirements, necessitating clear segmentation for strategic analysis. Understanding these distinct segments helps manufacturers tailor product development and deployment strategies effectively.
Product Type:
Margin pools within the product type segment are largely influenced by electrolyte purity and manufacturing complexity.
- Vanadium Redox:These systems utilize vanadium ions in different oxidation states for energy storage, known for their long cycle life and high efficiency. Demand concentrates in large-scale grid storage projects in China, driven by the need for stable, long-duration power delivery for renewable energy integration.
- Iron-Chromium:Iron-chromium flow batteries employ iron and chromium redox couples, offering a cost-effective alternative with abundant material availability. Utility-scale deployments in North America increasingly adopt this chemistry, seeking lower-cost, non-vanadium options for grid stabilization under the US Inflation Reduction Act.
- Zinc Bromine:These batteries use zinc and bromine electrolytes, providing high energy density suitable for specific grid support applications.
- Polysulfide Bromide:Polysulfide bromide systems leverage sulfur and bromine chemistries, explored for their potential in long-duration storage due to low material costs.
The dominant share belongs to Vanadium Redox, while Iron-Chromium is closing the gap fastest.
Application:
Application segments reflect distinct operational profiles, ranging from continuous power supply to intermittent energy balancing.
- Grid Energy Storage:These applications involve large-scale battery systems connected to the electrical grid, providing services like peak shaving, load shifting, and frequency regulation. Utility deployments in the United States and Europe drive significant demand, aiming to enhance grid stability and reliability for national energy security.
- Renewable Integration:This segment focuses on storing excess energy from intermittent sources like solar and wind, discharging it when generation is low or demand is high. China's ambitious dual carbon goals create substantial demand for these systems, balancing its rapidly expanding wind and solar generation capacity.
- Backup Power:Iron flow batteries provide reliable, long-duration power during outages for critical infrastructure like hospitals.
- Microgrid Systems:These systems integrate storage into localized grids, enhancing resilience and energy independence for communities or industrial sites.
- Industrial Facilities:Large industrial sites use flow batteries for demand charge management and ensuring continuous operations during grid fluctuations.
Grid Energy Storage commands the largest volume, with Renewable Integration expanding most quickly.
Deployment:
Deployment models vary significantly by scale and complexity, influencing system design and installation requirements.
- Utility-Scale:These deployments involve very large battery systems, often exceeding several megawatts, directly connected to the transmission or distribution grid. Projects in Australia and India are adopting utility-scale iron flow batteries to stabilize their grids and integrate vast renewable energy resources.
- Commercial:Commercial deployments involve systems installed at businesses, factories, or campuses to manage energy costs, provide backup, or support local grid services. European enterprises are increasingly implementing commercial systems to optimize energy consumption and participate in demand response programs, aligning with EU Green Deal policies.
- Residential:Smaller systems designed for home use, providing backup power or optimizing self-consumption of rooftop solar generation.
- Remote Installations:These deployments serve off-grid locations or isolated communities, offering reliable power where grid access is limited.
Utility-Scale deployments dominate the market, while Commercial applications are gaining share fastest.
End User:
End-user segments exhibit diverse needs for energy resilience and cost optimization, driving specific battery technology requirements.
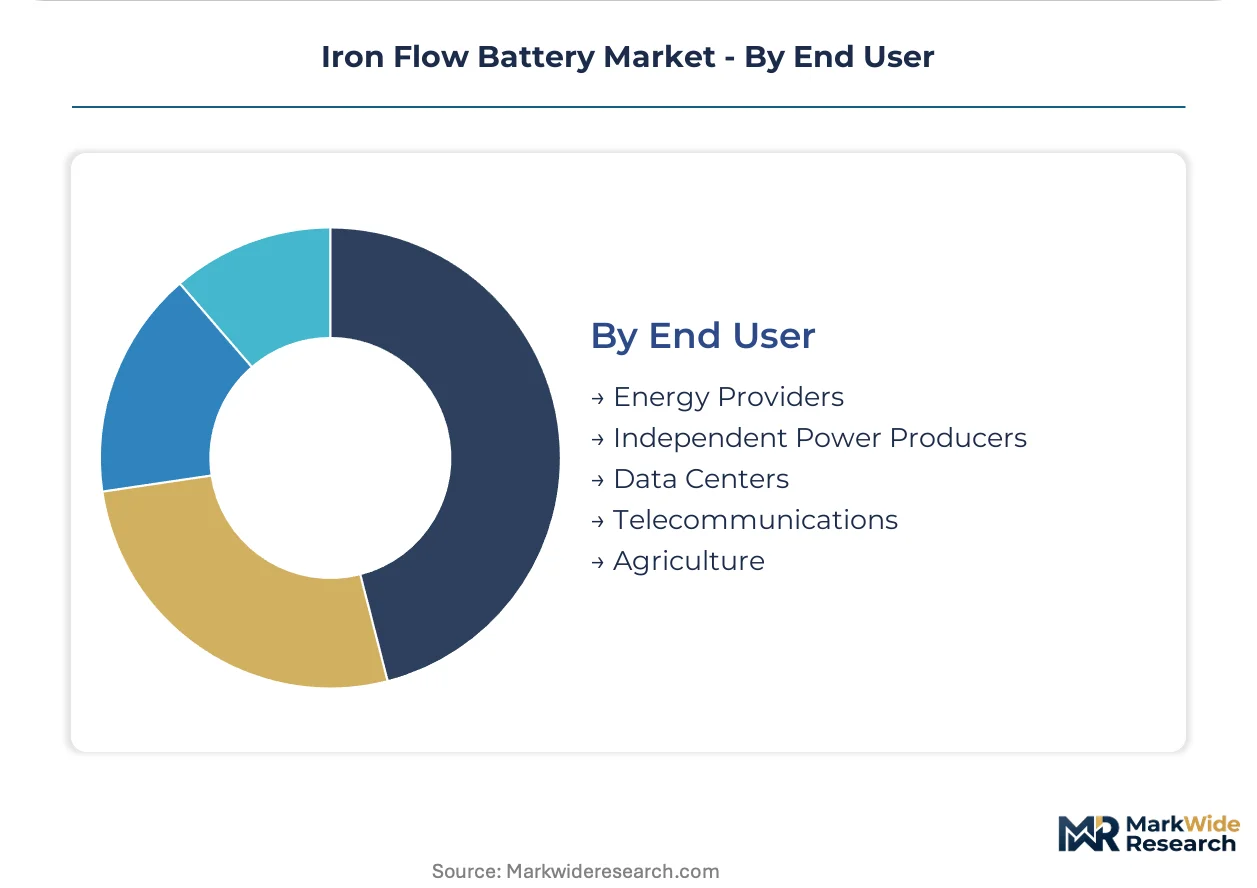
- Energy Providers:These entities, including utilities and grid operators, deploy iron flow batteries to manage grid stability, integrate renewables, and defer transmission upgrades. State-owned energy companies in China are major consumers, fulfilling national mandates for long-duration storage to meet dual carbon goals.
- Independent Power Producers:IPPs develop and operate power generation facilities, integrating storage to enhance project economics, firm renewable output, and participate in energy markets. North American IPPs are leveraging tax credits from the US Inflation Reduction Act to co-locate iron flow batteries with new solar and wind farms.
- Data Centers:Critical facilities requiring uninterrupted power supply, utilizing flow batteries for backup and peak load management.
- Telecommunications:Infrastructure relies on robust backup power solutions to ensure continuous operation of communication networks.
- Agriculture:Farms use energy storage to power irrigation systems, cold storage, and other operations, especially in remote areas or with renewable integration.
Energy Providers represent the largest customer base, with Independent Power Producers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The iron flow battery market exhibits varying regional dynamics, with some nations driving significant domestic demand while others develop supply capabilities. This creates a complex interplay of technology transfer and material sourcing across international borders. Strategic investments in local manufacturing are emerging to mitigate supply chain vulnerabilities.
United States
The United States drives demand for iron flow batteries through grid stabilization and renewable energy integration initiatives. The US Inflation Reduction Act provides substantial tax credits for domestic energy storage projects. Utility-scale deployments are concentrating in regions like California and Texas, supporting large-scale renewable energy facilities.
China
China's dual carbon goals necessitate massive investment in long-duration storage infrastructure, creating substantial demand. National policies mandate significant deployments of non-lithium energy storage technologies. Provincial governments in areas like the Yangtze River Delta are actively attracting battery manufacturing investments and developing local supply chains.
India
India faces ambitious renewable energy targets and significant grid stability challenges, creating a strong market for long-duration storage. Government initiatives promote grid modernization and energy independence across the country. Utility-scale projects are gaining traction in states such as Gujarat and Rajasthan, integrating solar and wind power.
Australia
Australia pursues aggressive integration of vast renewable energy resources, necessitating robust grid stabilization solutions. National Energy Market reforms support large-scale storage projects to enhance grid reliability. Utility-scale deployments are prevalent in South Australia and Queensland, balancing intermittent solar and wind generation.
Germany
Germany prioritizes enhancing grid stability and energy independence, aligning with EU Green Deal policies. National energy transition policies encourage the adoption of non-lithium storage technologies for grid services. Research and development hubs in Bavaria and North Rhine-Westphalia are exploring advanced flow battery chemistries.
Iron Flow Battery Market Key Industry Players
Concentration sits with specialized flow battery manufacturers focused on proprietary chemistries and system integration. The market also includes diversified energy storage providers expanding their portfolios to include long-duration solutions. Key competitive moves involve significant capacity expansion to meet escalating demand. Strategic partnerships with utilities and project developers are also prevalent across the industry.
Among specialized flow battery developers, ESS Tech, Inc. represents a North American player leveraging proprietary all-iron chemistry for utility-scale projects. VRB Energy, a Canada-based entity, exemplifies a focus on vanadium-based systems, positioning itself within the broader flow battery landscape. Invinity Energy Systems, a UK-headquartered firm, also sits within the vanadium redox flow battery segment, emphasizing long-duration grid applications.
| Leading Market Players |
|---|
| Australian Vanadium Limited |
| Flux XII, Inc. |
| ESS Tech, Inc. |
| VRB Energy |
| Invinity Energy Systems |
| Flo |
| Bushveld Energy |
| Primus Power |
| Carbo Energy |
| Others |
Cost & Logistics Intelligence
Long-term Energy Storage as a Service (ESaaS) contracts lock in both supply access and price visibility for utility and industrial customers. This model mitigates upfront capital expenditure barriers, fostering market stability for iron flow battery deployments.
Pricing Analysis
Utility-scale project developers anchor project-based pricing, often incorporating long-term performance guarantees. Price differentiation stems from electrolyte purity and system customization for specific grid services. Pricing softness emerges from the high upfront capital cost of large-scale systems, despite lower lifetime operational expenses. Commercial and microgrid operators exhibit higher price sensitivity compared to national energy providers.
Supply Chain Analysis
Strategic stockpiling of critical components and electrolytes characterizes the iron flow battery supply chain due to geopolitical sensitivities. Geographic supply concentration for high-purity iron salts and specialized membranes resides primarily in China and a few European producers. Raw material dependencies include iron, chromium, and vanadium, depending on the specific chemistry. Supply chain concentration creates a risk of price volatility. Distribution runs through direct sales to energy providers and specialized EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The iron flow battery market presents a fragmentation opportunity, driven by diverse long-duration storage mandates creating specialized niches across geographies and applications.
For Market Incumbents: Compound existing technology leadership through targeted research and development in advanced electrolyte chemistries. Secure long-term electrolyte supply chains to mitigate raw material price volatility, a persistent threat. Invest in certification processes for grid integration to counter potential competitive pressure from alternative long-duration storage technologies. Expand manufacturing capacity in strategic regions like North America and Europe.
For New Entrants and Emerging Players: Differentiate on system integration simplicity and modularity to address the complexity challenge for grid operators. Target industrial co-location projects in Europe, where energy independence policies create strong market pull for non-lithium solutions. Implement Energy Storage as a Service (ESaaS) models as a go-to-market angle, reducing upfront investment barriers for commercial customers. Focus on regions with less established lithium-ion infrastructure.
For Investors and Strategic Acquirers: Specialized electrolyte manufacturers represent compelling acquisition targets due to their proprietary formulations and supply chain control. The long-term viability of iron flow batteries, spanning a 5-10 year window, rests on sustained policy support and performance improvements. The signal to watch is the successful completion and operational validation of multiple gigawatt-hour scale projects in challenging grid environments.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meet escalating demand from utility-scale projects in China and the United States. |
| Long-term Supply Agreements | Secure high-purity electrolyte access for manufacturers and reduce raw material risk. |
| Technology Licensing | Accelerate adoption of advanced iron-flow chemistries globally, particularly in emerging markets. |
| System Integration Partnerships | Streamline deployment for grid operators and independent power producers in North America. |
| ESaaS Model Development | Reduce upfront capital barriers for commercial facilities and microgrid developers. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary data validation. Primary research involved conversations with utility planning officers, electrochemists, project developers, and government energy officials. This was triangulated with secondary sources including IEA reports, US EIA data, company financial statements, and academic publications, employing both bottom-up and top-down approaches.
Across the analysis window, the forecasting framework integrated quantitative and qualitative data inputs. Segmentation dimensions modeled included product type, application, deployment, end-user, and regional policy environment. Compound annual growth rates were derived through a proprietary analytical model, incorporating industry-specific forecast inputs such as national energy transition targets and electrolyte performance improvements.
Material uncertainties — unforeseen technological breakthroughs or abrupt policy shifts — sit outside the modeled envelope, as forecasts reflect assumptions about market evolution. Revision becomes warranted when sustained shifts in raw material costs or the global pace of grid modernization occur.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
United Kingdom SLI Battery Market
Batteries
Romania Rechargeable Battery Market
Batteries
South America Battery Cell Market
Batteries
Dry Cell Battery Market
Batteries
Lithium-Based Battery Charger Market
Batteries
3D-Printed Battery Market
Batteries
South Africa Battery Market
Batteries
Middle East and Africa Battery Market
Batteries
South America Primary Battery Market
Batteries
Military Battery Market
Batteries
India SLI Battery Market
Batteries
Smart Diagnostic Battery Charger Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
South Asia Battery Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market
Batteries
Tubular Batteries Market