
 Tubular Batteries Market | 2026-2036
Tubular Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Tubular Batteries Market Insights
India's PLI scheme for advanced chemistry cell manufacturing is consolidating procurement preferences toward domestically certified tubular battery suppliers. Exide Industries Limited leverages its vertically integrated lead smelting operations to sustain cost competitiveness in flooded tubular segments. Amara Raja Batteries Limited anchors its position through dense distribution across South India's telecom tower networks. Tata Power competes by bundling tubular battery storage with its solar rooftop installations.
Tubular batteries employ lead-acid chemistry with positive active material cast into cylindrical gauntlets, enabling deep-cycle endurance exceeding 1,500 cycles at 80% depth of discharge. These cells serve primarily as stationary storage for backup power and renewable energy integration where capital cost sensitivity outweighs energy density requirements. The flooded product type dominates volume in price-sensitive emerging markets, while gel variants command margin premiums in telecom applications requiring minimal maintenance. Advanced lead-accid technology leads the technology segment by installed base, though lithium-ion alternatives are displacing it in premium grid-support deployments.
India's BIS mandates cycle-life testing and corrosion resistance standards that filter out low-tier imports. The EU's REACH and RoHS frameworks restrict lead content thresholds and recycling documentation for batteries entering European supply chains. Stakeholders must monitor how carbon-border adjustment mechanisms reshape cost structures for lead-acid versus lithium-ion procurement decisions.
Market Dynamics
India's PLI scheme for advanced chemistry cell manufacturing is redirecting procurement flows toward domestically certified tubular battery suppliers, compressing import-dependent supply chains and elevating BIS-compliant domestic producers.
Growth Catalysts
- Telecom infrastructure expansion:India's tower operators are scaling backup power deployments across South India's dense network corridors, creating sustained demand for deep-cycle tubular storage.
- BIS certification tightening:India's Bureau of Indian Standards mandates now enforce cycle-life testing and corrosion resistance standards that filter out low-tier imports and elevate certified domestic production.
- Renewable energy bundling:Solar rooftop integrators are pairing tubular battery systems with photovoltaic installations, extending product reach into residential and commercial segments.
Market Restraints
- Lead price volatility:Raw material input costs for lead-acid chemistry fluctuate with global smelter output and scrap recycling rates, compressing margin predictability for flooded tubular manufacturers.
- Lithium-ion substitution:Premium grid-support deployments are migrating to lithium-ion alternatives where energy density and cycle efficiency outweigh capital cost sensitivity.
- EU REACH compliance friction:European recycling documentation requirements and lead content thresholds create administrative barriers for exporters targeting continental supply chains.
Strategic Opportunities
- Industrial corridor densification:Manufacturing clusters around Chennai and Pune present concentrated demand for stationary backup power in automotive and electronics production facilities.
- Gel variant premiumization:Minimal-maintenance gel tubular batteries command margin premiums in telecom applications where site access costs exceed product price differentials.
- Carbon-border mechanism positioning:Early alignment with emerging carbon-accounting frameworks creates competitive insulation against future import tariff adjustments favoring low-carbon battery chemistries.
Industry Challenges
- Smelter environmental compliance:Lead-acid battery manufacturers face intensifying MEE oversight on smelting operations, requiring capital deployment toward emission control and wastewater treatment systems.
- Skill scarcity in electrochemical engineering:Deep-cycle battery design expertise concentrates among retiring technical specialists, constraining R&D velocity for next-generation tubular architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tubular Batteries Market |
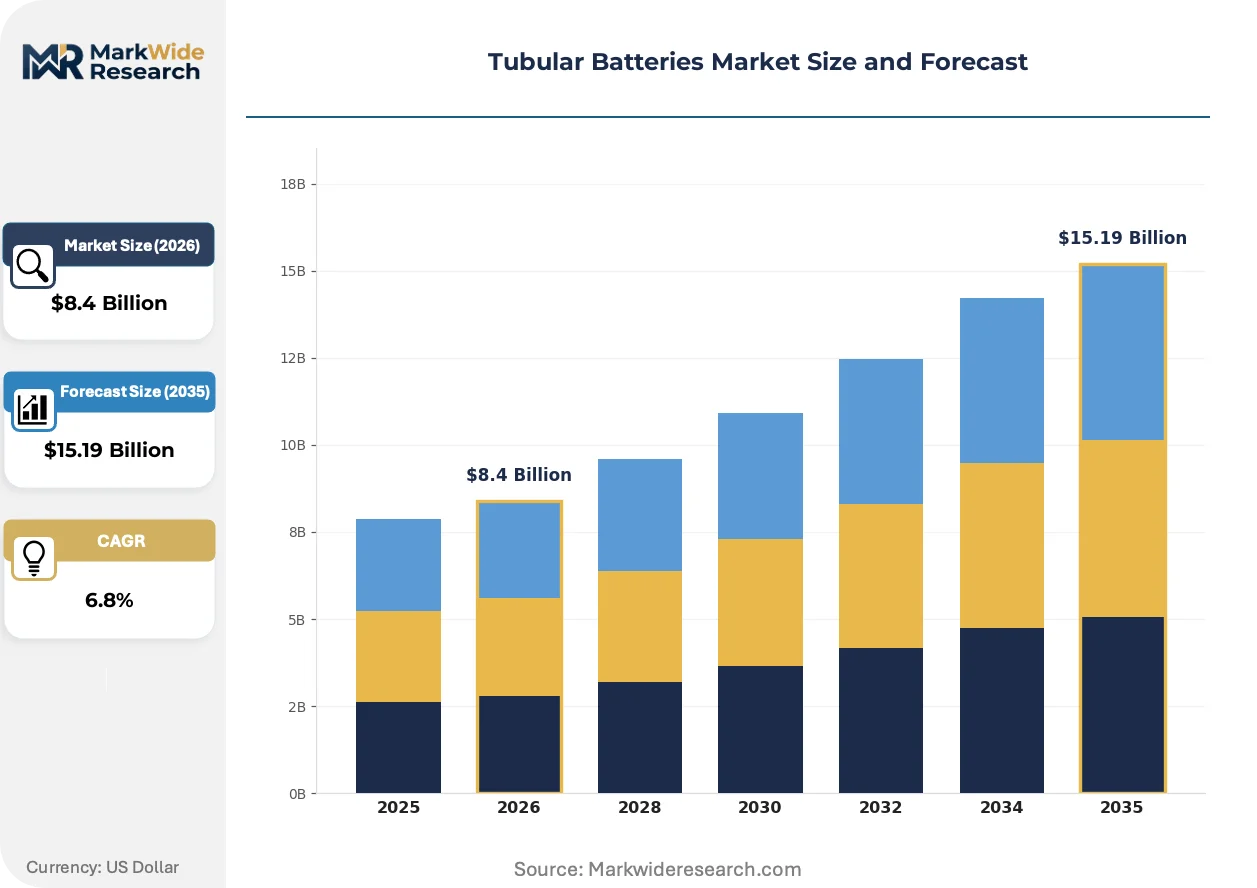
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Gel, Flooded, Sealed End User: Telecom, Renewable Energy, Residential, Industrial Application: Off-Grid, Backup Power, Load Shifting, Grid Support Technology: Advanced Lead-Acid, Lithium-Ion, Sodium-Nickel Chloride, Others |
| Companies Covered | Tata Power, Sonnenschein, Exide Industries Limited, East Penn Manufacturing Company, Trojan Battery Company, Amara Raja Batteries Limited, HBL Power Systems Limited, Crown Battery Manufacturing Company, Luminous Power Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tubular Batteries Market Trends and Innovations
Active material engineering and regulatory carbon-accounting are converging to reshape competitive positioning in stationary storage, with chemistry optimization and supply-chain traceability emerging as primary differentiation vectors.
Carbon-enhanced lead oxide formulations are integrating into positive plate manufacturing, extending cycle endurance beyond conventional cast-iron spine designs. Telecom operators with remote tower portfolios are adopting these formulations fastest, recognizing total-cost-of-ownership advantages over standard flooded alternatives. This material transition is integrating deep-cycle performance benchmarks previously associated with premium gel variants into mid-tier product lines.
India's BIS cycle-life certification protocols are tightening test-stringency thresholds for stationary battery qualification. Domestic manufacturers with captive lead smelting and in-house gauntlet casting capabilities absorb compliance costs more efficiently than import-reliant competitors. The flooded tubular segment bears the heaviest adaptation burden, as existing product lines require reformulation to meet corrosion-resistance mandates.
Telecom tower operators are consolidating vendor relationships around integrated power-service contracts that bundle battery supply with installation and lifecycle maintenance. Traditional equipment distributors lose relevance as direct procurement channels between tower companies and certified manufacturers strengthen. This channel compression is most pronounced in Maharashtra and Tamil Nadu, where tower density supports dedicated logistics infrastructure for battery replacement cycles.
Tubular Batteries Market Segmentation
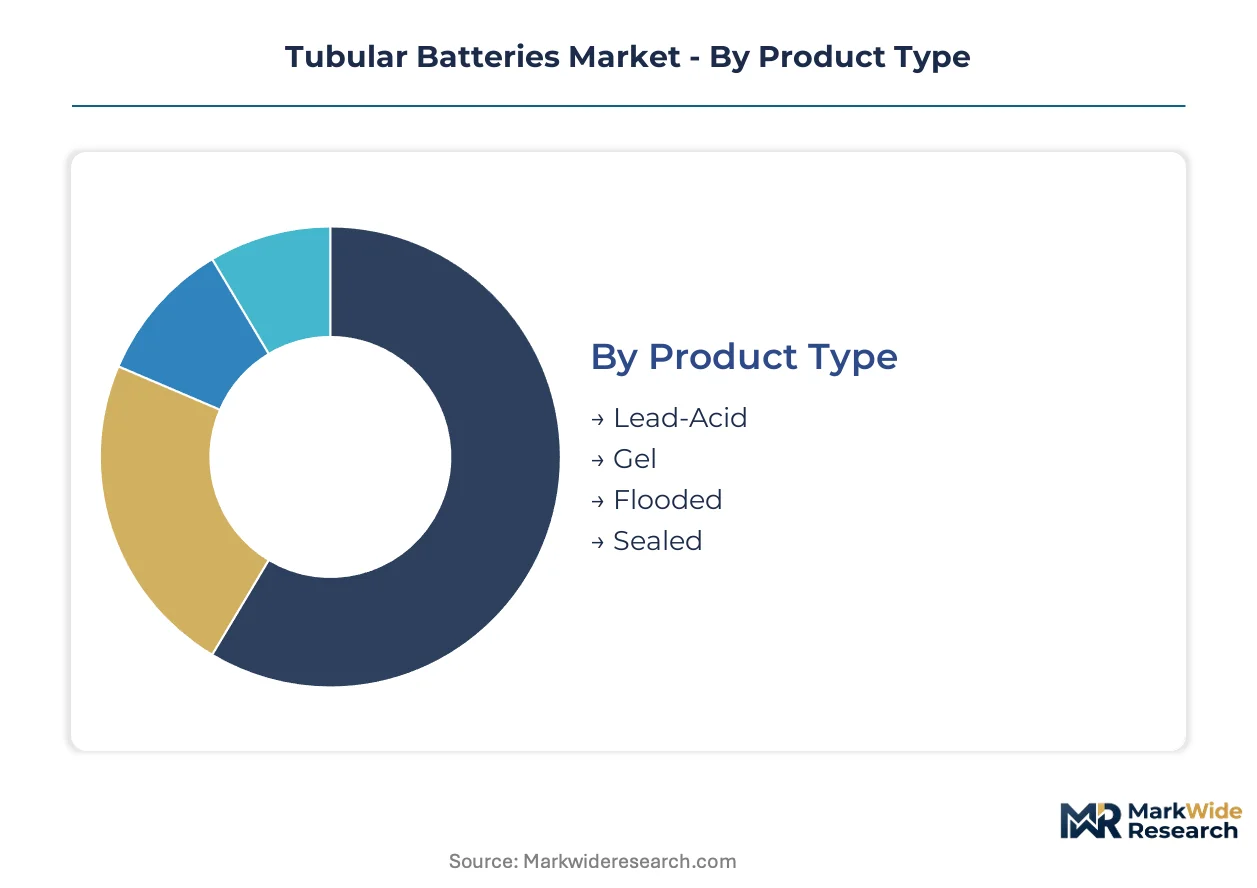
Segmentation in tubular batteries reveals divergent profit pools across chemistry formats and deployment contexts. Product type splits between maintenance-intensive flooded systems and premium gel variants, while end-use concentration in telecom backup power shapes volume allocation.
Product Type:
Flooded tubular batteries dominate unit volume in price-sensitive emerging markets, while gel variants extract margin premiums where site access costs justify maintenance minimization.
- Flooded:Positive active material cast into cylindrical gauntlets around lead-antimony spines enables deep-cycle endurance exceeding 1,500 cycles at 80% depth of discharge. India's industrial corridors around Chennai and Pune concentrate demand for these cost-optimized systems in automotive and electronics production facilities where capital sensitivity outweighs maintenance burden.
- Gel:Electrolyte immobilized in silica-based thixotropic gel eliminates stratification and reduces watering requirements. Telecom tower operators across South India adopt these variants fastest where helicopter or rope-access site visits exceed battery price differentials, recognizing total-cost-of-ownership advantages in remote portfolios.
- Lead-Acid:Conventional flooded lead-acid chemistry with cast-iron spine tubular construction serves price-sensitive backup power installations.
- Sealed:Valve-regulated recombinant designs prevent electrolyte spillage for indoor or restricted-access deployments.
Today's leader: Flooded. Tomorrow's challenger: Gel.
End User:
Telecom infrastructure anchors procurement volume, while renewable energy bundling opens residential and commercial expansion corridors.
- Telecom:Tower operators scaling backup power deployments across Maharashtra and Tamil Nadu drive sustained demand for deep-cycle tubular storage. India's TRAI mandates on network uptime reliability compress vendor selection toward BIS-certified manufacturers with dedicated logistics infrastructure for replacement cycles.
- Renewable Energy:Solar rooftop integrators pair tubular battery systems with photovoltaic installations, extending product reach beyond traditional industrial buyers. Tata Power bundles storage with residential solar deployments, creating integrated procurement channels that bypass traditional equipment distributors.
- Industrial:Manufacturing clusters require stationary backup for process continuity in automotive and electronics production.
- Residential:Grid-tied solar adopters in urban centers seek cost-optimized storage for evening load coverage.
Telecom commands current volume. Renewable energy is climbing the fastest.
Application:
Backup power absorbs majority capacity, while grid support applications face lithium-ion displacement pressure.
- Backup Power:Uninterruptible supply for critical infrastructure spans telecom towers, manufacturing facilities, and commercial buildings. BIS cycle-life certification protocols tighten test-stringency thresholds, filtering low-tier imports and elevating domestic manufacturers with captive lead smelting capabilities.
- Off-Grid:Remote installations without grid connectivity rely on tubular batteries for solar-diesel hybrid systems. Rural electrification programs in India's underserved districts concentrate procurement toward flooded variants with lowest capital cost per kilowatt-hour.
- Load Shifting:Time-of-use arbitrage for commercial consumers with demand-charge exposure.
- Grid Support:Frequency regulation and ancillary services migrate toward lithium-ion alternatives where energy density and cycle efficiency outweigh capital cost sensitivity.
Backup power retains installed base dominance. Off-grid shows steepest expansion trajectory.
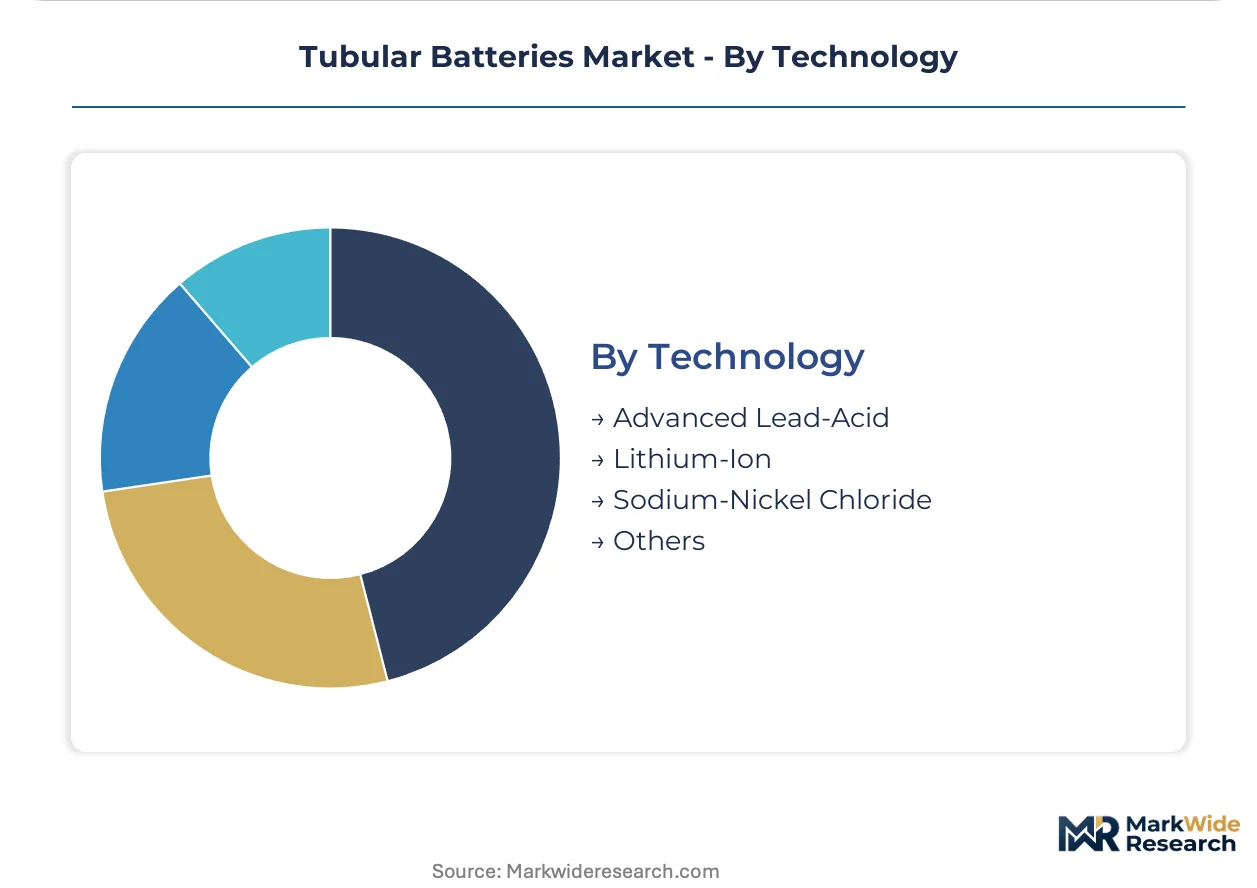
Technology:
Advanced lead-acid chemistry defends position through cost structure, while sodium-nickel chloride occupies niche high-temperature applications.
- Advanced Lead-Acid:Carbon-enhanced lead oxide formulations integrate into positive plate manufacturing, extending cycle endurance beyond conventional designs. Domestic manufacturers with in-house gauntlet casting absorb BIS compliance costs more efficiently than import-reliant competitors.
- Lithium-Ion:Premium grid-support deployments migrate to this chemistry where energy density and cycle efficiency outweigh capital cost sensitivity, displacing tubular alternatives in frequency regulation applications.
- Sodium-Nickel Chloride:High-temperature molten salt chemistry serves specialized industrial backup with extreme temperature tolerance.
- Others:Emerging chemistries including flow batteries and solid-state prototypes occupy pre-commercial demonstration phases.
Advanced lead-acid holds current share. Lithium-ion is gaining share fastest in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochemical engineering talent concentrates in India's industrial corridors, where lead-acid battery design expertise anchors manufacturing scale for stationary storage applications.
India
Telecom tower operators across Maharashtra and Tamil Nadu drive procurement volume for deep-cycle tubular storage systems. BIS cycle-life certification protocols enforce corrosion-resistance standards that filter low-tier imports and elevate domestic manufacturers with captive lead smelting. Manufacturing clusters around Chennai and Pune concentrate demand for flooded tubular systems in automotive and electronics production facilities.
United States
Data center operators and telecom infrastructure providers sustain demand for gel tubular variants in remote backup power deployments. EPA oversight on lead smelter emissions intensifies compliance costs for domestic manufacturers, compressing margins on flooded product lines. Industrial corridors across Texas and the Midwest anchor stationary battery procurement for manufacturing continuity applications.
Germany
Renewable energy integrators and industrial automation facilities drive adoption of advanced lead-acid tubular systems for load-shifting applications. REACH documentation requirements and RoHS lead-content thresholds create administrative barriers for battery exporters targeting continental supply chains. Manufacturing clusters in Bavaria and Baden-Württemberg concentrate demand for maintenance-minimized gel variants in precision production environments.
China
Telecom infrastructure expansion and rural electrification programs sustain volume demand for cost-optimized flooded tubular batteries. MEE oversight on smelting operations intensifies environmental compliance requirements, forcing capital deployment toward emission control systems. Manufacturing corridors in Guangdong and Jiangsu provinces anchor production scale for both domestic consumption and export markets.
Brazil
Off-grid solar installations and telecom backup deployments drive procurement for deep-cycle tubular storage in underserved districts. ANVISA and environmental agency oversight on lead processing operations elevates compliance costs for domestic assemblers reliant on imported components. Industrial zones around São Paulo and Minas Gerais concentrate demand for stationary backup power in mining and manufacturing operations.
Tubular Batteries Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the tubular battery landscape, with integrated smelting operations conferring cost advantages in flooded segments while specialized engineering houses capture margin in gel variants. The vendor base stratifies across three tiers: multinational battery conglomerates with captive lead supply, regional specialists with dense distribution networks, and contract assemblers serving price-sensitive replacement markets. Dominant competitive moves include backward integration into lead smelting to secure raw material cost structures, and bundling battery supply with lifecycle maintenance contracts to compress traditional distribution channels.
Within the integrated-manufacturer tier, Exide Industries Limited and Amara Raja Batteries Limited exemplify archetypes that anchor competitive positioning through captive production capabilities and geographic concentration. HBL Power Systems Limited occupies a specialist position focused on engineered power solutions. These named entities represent patterns visible across the competitive set rather than exhaustive enumeration of market participants.
| Leading Market Players |
|---|
| Tata Power |
| Sonnenschein |
| Exide Industries Limited |
| East Penn Manufacturing Company |
| Trojan Battery Company |
| Amara Raja Batteries Limited |
| HBL Power Systems Limited |
| Crown Battery Manufacturing Company |
| Luminous Power Technologies |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists with captive lead smelting operations in India anchor supply discipline through backward integration into raw material production, converting BIS certification mandates into pricing power over import-dependent competitors while absorbing cycle-life testing compliance costs more efficiently than fragmented assemblers.
Pricing Analysis
Bundled power-service contracts versus unbundled equipment-only sales split the pricing landscape, with integrated lifecycle maintenance packages commanding premiums in telecom tower deployments where site access costs exceed battery price differentials. Three-tier pricing structure across premium gel, certified flooded, and economy flooded levels differentiates by corrosion-resistance grade and BIS compliance tier. Pricing pressure stems from lithium-ion substitution in grid-support applications, compressing margins for standard flooded tubular manufacturers. Industrial procurement teams in automotive corridors exhibit highest price sensitivity, while remote telecom operators prioritize total-cost-of-ownership over upfront capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with lead concentrate supply from Australia, Peru, and China, where smelter output fluctuations transmit directly into raw material input costs for positive plate manufacturing. The tubular battery supply chain draws from lead-antimony alloy feedstock, silica gel precursors, and polyethylene gauntlet materials, with logistics chokepoints concentrated in Indian port infrastructure handling imported lead concentrate. Distribution runs through direct procurement channels between tower companies and certified manufacturers, compressing traditional equipment distributors in Maharashtra and Tamil Nadu.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through carbon-enhanced lead oxide formulation shifts that extend cycle endurance into premium performance tiers without full gel chemistry cost structures.
For Market Incumbents: Deploy captive smelter retrofit investments to absorb intensifying MEE emission control mandates before compliance deadlines filter smaller competitors. Anchor channel control through exclusive lifecycle maintenance contracts with telecom tower operators in South India, defending against lithium-ion displacement in grid-support segments by bundling tubular storage with solar rooftop installations. For New Entrants and Emerging Players: Begin with gel variant specialization targeting remote telecom portfolios where helicopter-access site visits justify maintenance-minimization premiums. Penetrate renewable energy bundling channels through direct partnerships with solar integrators in residential and commercial segments, bypassing traditional distributor networks that incumbent players dominate. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with dense distribution networks but lacking captive lead supply, presenting consolidation targets for integrated manufacturers seeking geographic expansion. Long-term viability hinges on carbon-border adjustment mechanism alignment favoring low-carbon battery chemistries. Watch BIS certification enforcement intensity as inflection signal for import compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Smelting | Captive raw material supply insulates Exide Industries and Amara Raja from global lead price volatility. |
| Gel Variant Premiumization | Minimal-maintenance formulations extract margin premiums from telecom operators with remote tower portfolios. |
| Carbon-Enhanced Lead Oxide Adoption | Advanced positive plate formulations extend cycle endurance beyond conventional cast-iron spine designs. |
| Direct Channel Compression | Integrated power-service contracts between manufacturers and tower companies displace traditional distributors. |
| BIS Certification Pre-Positioning | Early compliance with tightening cycle-life and corrosion-resistance standards filters import-dependent competitors. |
Research Methodology
Direct dialogue with lead-acid battery plant managers, telecom tower procurement officers, solar integrator technical directors, and BIS certification auditors grounded qualitative findings, cross-referenced against customs trade data on lead concentrate imports, TRAI network uptime compliance filings, SEC disclosures from listed battery manufacturers, and industrial corridor energy demand projections. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring across the analysis window.
Installed base forecasts by product type, end-use sector, and regional production cluster emerged from elasticity modeling of telecom infrastructure expansion rates, renewable energy bundling adoption curves, and industrial backup power replacement cycles. CAGRs derived from regression analysis of historical lead-acid deployment patterns against lithium-ion substitution thresholds, with BIS regulatory phase-in schedules and PLI scheme procurement preferences as structural inputs.
Several conditions sit outside the modeled scope, including unannounced carbon-border adjustment mechanism implementation dates, sudden lead price spike events from smelter supply disruptions, and accelerated lithium-ion cost parity breakthroughs in stationary storage. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
DMC for Battery Market
Batteries
India SLI Battery Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market
Batteries
Power Tool Batteries Market
Batteries
Indonesia Battery Market
Batteries
North Africa Battery Market
Batteries
Battery Materials Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
Inverter Battery Market
Batteries
South Asia Battery Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
Yacht Battery Market
Batteries
Middle East and Africa Battery Market
Batteries
Southeast Asia Battery Market