
 South Asia Battery Market | 2026-2036
South Asia Battery Market Size, Share, and Industry Trends Forecast 2026-2036
South Asia Battery Market Analytics
India's PLI scheme for advanced chemistry cells is rebalancing the cost-of-entry calculus for foreign manufacturers seeking domestic assembly footholds. Exide Industries Limited anchors its position through deep distribution across India's aftermarket automotive channel. BYD Co. Ltd leverages its blade-cell architecture to compete in electric bus tenders across Bangladesh and Nepal. Samsung SDI Co. Ltd specializes in high-nickel cathode formulations for premium two-wheeler electrification programs.
South Asia batteries encompass electrochemical energy storage devices ranging from lead-acid flooded units with specific gravities near 1.280 to solid-state lithium-metal prototypes exceeding 400 Wh/kg, engineered to convert stored chemical potential into direct-current electrical output for motive, stationary, and portable applications. Lithium-ion chemistry leads product-type value generation as cell costs decline and energy density thresholds improve, while lead-acid retains volume dominance in India's uninterruptible power supply and conventional automotive starter segments. The electric vehicles application category commands the fastest expansion trajectory, though grid storage systems for solar-diesel hybrid microgrids in rural Bangladesh and Sri Lanka represent an emerging margin pool with distinct performance specifications.
India's BIS certification mandates and the CEA's technical standards for grid-connected storage are tightening product compliance requirements across the subcontinent. Sri Lanka's Sustainable Energy Authority and Bangladesh's power division impose parallel import and safety protocols that shape market access conditions for regional suppliers. Stakeholders must monitor how India's Bureau of Energy Efficiency labeling norms and evolving state-level electric vehicle policies redistribute manufacturing incentives and procurement preferences across the South Asian battery value chain.
Market Dynamics
India's PLI scheme for advanced chemistry cells is compressing import dependency and forcing foreign cell makers to localize electrode coating and final assembly operations within Tamil Nadu and Gujarat industrial corridors.
Growth Catalysts
- CEA Grid Storage Standards:India's Central Electricity Authority mandates for grid-connected battery systems are creating certified demand pools for lithium-ion installations in renewable hybrid projects.
- Two-wheeler electrification:Bangladesh and Sri Lanka are expanding fleet electrification programs for last-mile delivery motorcycles, pulling in high-nickel cathode cell procurement.
- Blade-cell architecture:Structural battery pack designs are reducing thermal management complexity and enabling faster assembly for electric bus tenders across Nepal.
Market Restraints
- Lithium carbonate volatility:Raw material input costs for cathode active materials swing with Chilean and Australian spodumene concentrate contract pricing.
- East Asian supply concentration:Separator film and electrolyte salt production clusters in South Korea and Japan create single-source vulnerability for South Asian pack assemblers.
- Lead-acid substitution ceiling:Flooded lead-acid batteries retain cost advantage in India's automotive starter segment below 15% price parity with lithium-ion.
Strategic Opportunities
- Rural Bangladesh microgrids:Solar-diesel hybrid installations in off-grid districts present uncaptured margin pools for long-cycle-life storage chemistry.
- BIS certification arbitrage:Foreign manufacturers achieving Bureau of Indian Standards accreditation gain preferential access to state electric vehicle procurement tenders.
- Solid-state convergence:Sulfide electrolyte research programs at Indian Institutes of Technology are converging with polymer separator advances from domestic materials startups.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell design and formation protocol expertise concentrates in Bangalore and Chennai, constraining pack assembly scale-up in secondary cities.
- BIS testing timeline compression:Certification cycles for new cell form factors stretch 14-18 months, delaying product launches for emerging electric three-wheeler OEMs.
- Legacy lead-acid infrastructure stranding:Existing smelter and distribution networks resist write-downs as lithium-ion volumes accelerate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Asia Battery Market |
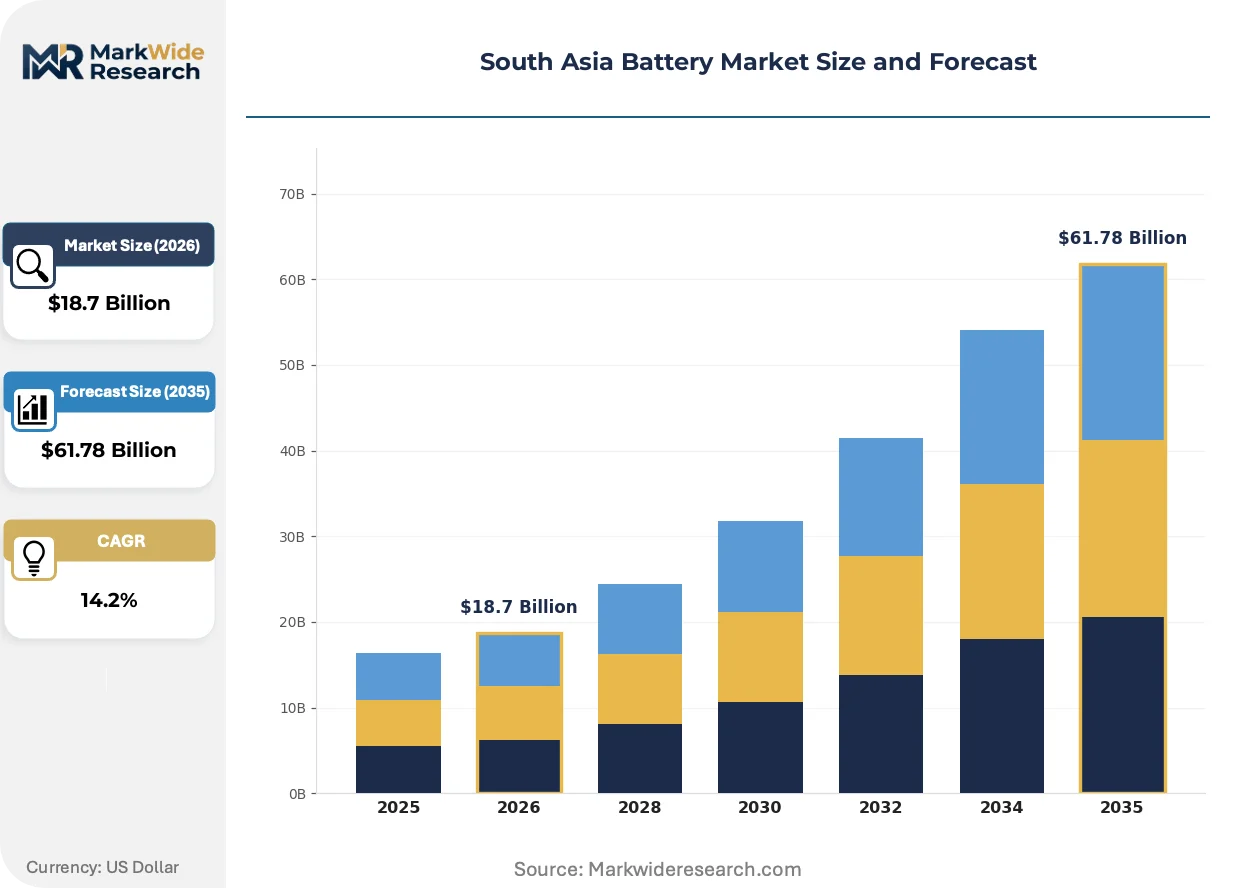
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-acid, Lithium-ion, Nickel-cadmium, Sodium-sulfur End User: Automotive, Consumer Electronics, Renewable Energy, Industrial Application: Electric Vehicles, UPS Systems, Grid Storage, Power Tools Technology: Rechargeable, Flow Batteries, Solid-state, Fuel Cells |
| Companies Covered | GS Yuasa Corporation, Panasonic Corporation, BYD Co. Ltd, Leoch International Technology Limited, C&D Technologies Inc., Exide Industries Limited, Samsung SDI Co. Ltd, Amara Raja Batteries Ltd, LG Chem Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Asia Battery Market Evolving Landscape
Sodium-ion chemistry is disrupting cost curves for entry-level electric mobility. Regulatory pressure on cell safety is tightening testing protocols. Procurement patterns are consolidating around certified suppliers with localized assembly.
Lithium iron phosphate cathode formulations are integrating into electric three-wheeler and low-speed electric vehicle battery packs across India's Tier-2 cities. Fleet operators in Ahmedabad and Lucknow specify these cells for thermal stability during monsoon humidity cycles. The chemistry is integrating cost structures that undercut nickel-manganese-cobalt alternatives by 20-25% at pack level.
BIS certification mandates for lithium-ion cells are tightening product compliance requirements across India's value chain. The Bureau's IS 16046 standards now require abuse testing and cycle-life documentation that foreign suppliers must replicate at domestic testing facilities. Tamil Nadu-based pack assemblers are responding by pre-qualifying cell sources with existing BIS accreditation.
Fleet procurement is consolidating around long-term service contracts with guaranteed cycle-life performance. Electric bus operators in Dhaka and Kathmandu now specify battery-as-a-service arrangements that unbundle cell replacement risk from vehicle capital cost. This shift is most visible in municipal tender documents across Bangladesh's power division procurement channels.
South Asia Battery Market Segmentation
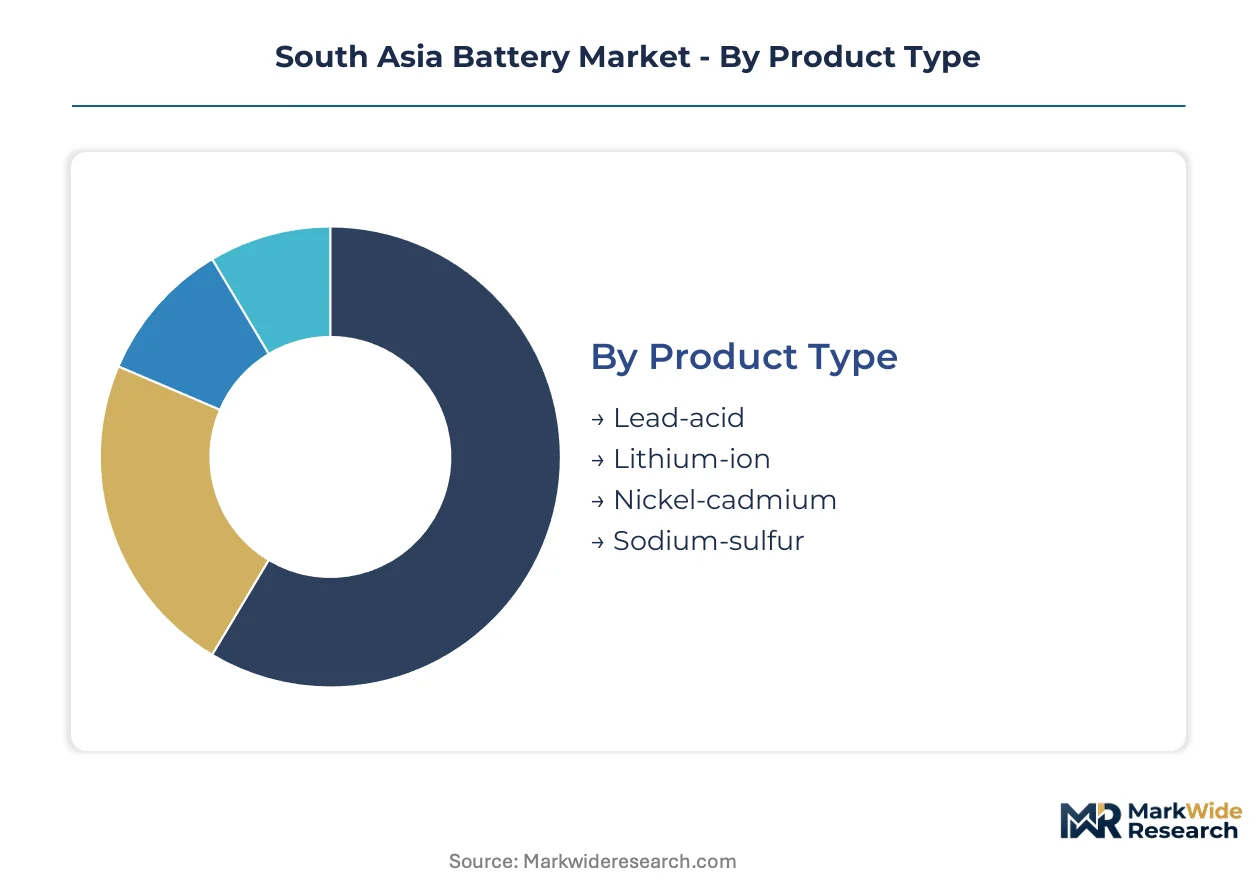
South Asia's battery market fragments across chemistry, end-use, and technology dimensions, each carrying distinct certification burdens from BIS, CEA, and national energy authorities. Segment-specific compliance timelines and localization requirements reshape procurement patterns for cell manufacturers and pack assemblers across India, Bangladesh, and Sri Lanka.
Product Type:
BIS certification mandates under IS 16046 apply differentially across chemistries, with lithium-ion facing the most stringent abuse-testing protocols while lead-acid operates under legacy automotive standards.
- Lithium-ion:Cathode formulations span LFP for thermal stability in monsoon climates and high-nickel NMC for premium two-wheeler density targets. Tamil Nadu and Gujarat industrial corridors concentrate electrode coating and final assembly operations driven by India's PLI scheme localization requirements.
- Lead-acid:Flooded units with specific gravities near 1.280 dominate India's automotive starter and UPS segments. Bangladesh and Sri Lanka maintain import tariff structures that protect regional smelter networks from Chinese price competition.
- Nickel-cadmium:Industrial alkaline cells serve railway signaling and aviation backup applications requiring extreme temperature resilience.
- Sodium-sulfur:High-temperature molten salt chemistry targets grid-scale installations with discharge durations exceeding six hours.
Leading the category by volume: Lead-acid. Growing fastest: Lithium-ion.
End User:
Cost tier stratification separates premium certified supply for automotive OEMs from economy-tier aftermarket channels serving consumer and industrial segments.
- Automotive:Electric bus tenders across Dhaka and Kathmandu specify battery-as-a-service contracts that unbundle cell replacement risk from vehicle capital cost. Fleet procurement consolidates around long-term cycle-life guarantees.
- Renewable Energy:Solar-diesel hybrid microgrids in rural Bangladesh demand long-cycle-life storage chemistry with distinct performance specifications from urban grid-tied installations.
- Consumer Electronics:Smartphone and laptop battery packs require BIS accreditation for import clearance into Indian distribution channels.
- Industrial:Forklift motive power and telecom tower backup systems specify deep-cycle durability standards.
Highest margin concentration: Renewable Energy. Steepest volume expansion: Automotive.
Application:
Geography drives specification divergence, with monsoon humidity cycles in coastal India and Bangladesh demanding enhanced thermal management compared to drier interior markets.
- Electric Vehicles:Two-wheeler electrification programs in Bangladesh and Sri Lanka pull high-nickel cathode procurement for last-mile delivery motorcycles. Ahmedabad and Lucknow fleet operators specify LFP alternatives for cost advantages.
- Grid Storage:CEA technical standards for grid-connected systems create certified demand pools for lithium-ion installations in renewable hybrid projects across India's industrial corridors.
- UPS Systems:Flooded lead-acid retains dominance in India's conventional automotive starter segment below price parity thresholds with lithium-ion alternatives.
- Power Tools:Cylindrical cell formats serve cordless construction equipment with high discharge rate requirements.
Fastest share gain: Electric Vehicles. Most mature installed base: UPS Systems.
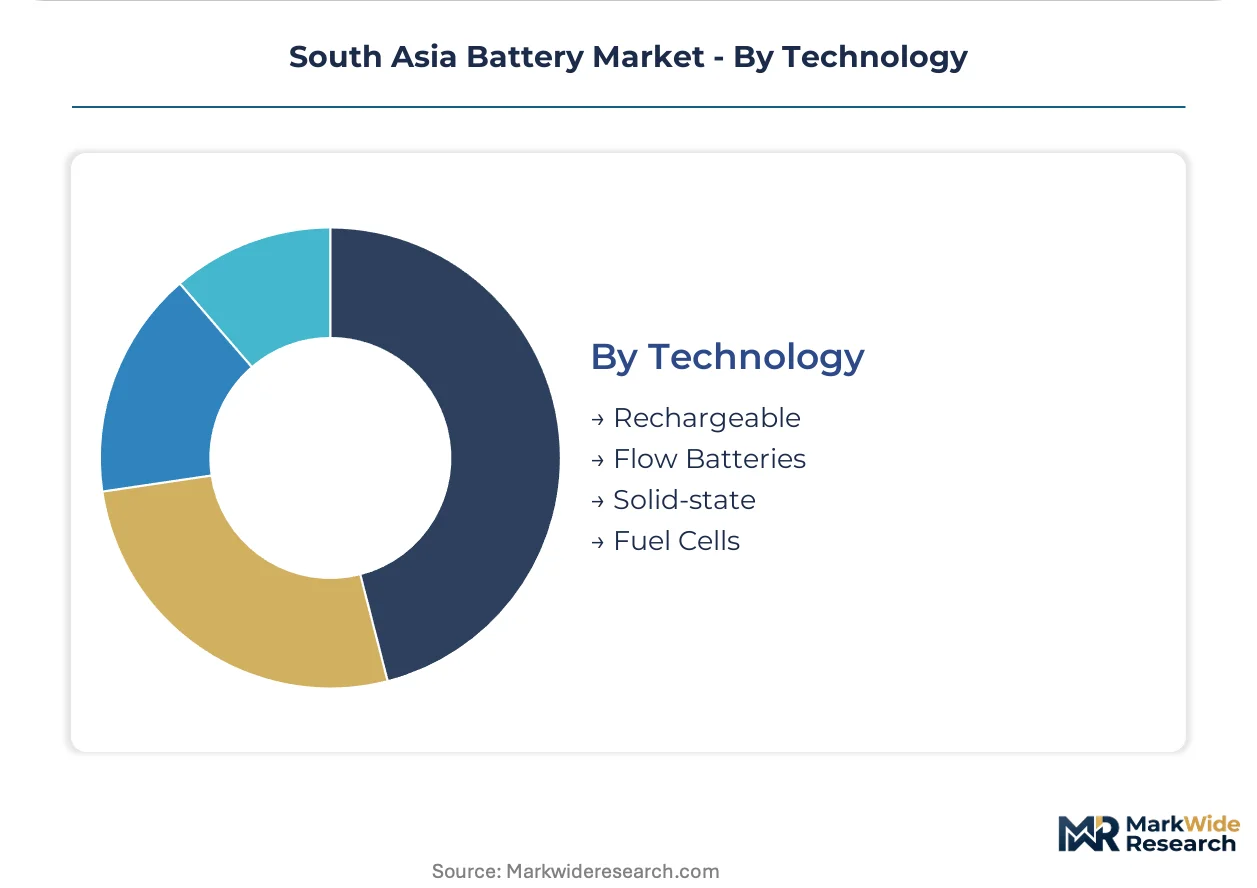
Technology:
Supply concentration for separator film and electrolyte salt in East Asian production clusters creates single-source vulnerability for South Asian pack assemblers across all technology tiers.
- Rechargeable:Intercalation chemistry dominates commercial deployment with established formation protocols and recycling infrastructure.
- Solid-state:Sulfide electrolyte research at Indian Institutes of Technology converges with polymer separator advances from domestic materials startups, targeting energy density thresholds exceeding 400 Wh/kg.
- Flow Batteries:Vanadium redox systems serve long-duration grid storage with decoupled power and energy scaling.
- Fuel Cells:Hydrogen proton-exchange membrane technology targets heavy-duty trucking segments beyond battery-economic range limits.
Current production dominance: Rechargeable. Emerging technology priority: Solid-state.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for battery storage concentrates most densely in India's industrial corridors, with Bangladesh and Sri Lanka emerging as secondary growth poles for electric mobility and rural microgrid applications.
India
Electric vehicle procurement from Tamil Nadu and Gujarat manufacturing hubs drives lithium-ion cell demand. The PLI scheme for advanced chemistry cells mandates localization of electrode coating and final assembly operations. Tamil Nadu's Sriperumbudur industrial belt hosts pack assembly facilities serving domestic automotive OEMs and export markets.
Bangladesh
Last-mile delivery motorcycle electrification programs pull high-nickel cathode cell procurement into Dhaka and Chittagong logistics corridors. The country's power division imposes parallel import and safety protocols shaping market access for regional suppliers. Solar-diesel hybrid microgrids in rural off-grid districts present uncaptured margin pools for long-cycle-life storage chemistry.
Sri Lanka
Fleet electrification for three-wheeler taxis and urban delivery vehicles generates concentrated demand in Colombo and its periphery. The Sustainable Energy Authority maintains certification requirements for grid-connected storage systems. Katunayake export processing zone hosts assembly operations for consumer electronics battery packs requiring BIS-aligned accreditation.
Nepal
Electric bus tenders in Kathmandu Valley specify battery-as-a-service arrangements unbundling cell replacement risk from vehicle capital cost. Municipal procurement channels consolidate around long-term cycle-life guarantees. Bhaktapur industrial corridor attracts pack integrators serving cross-border logistics operators.
Pakistan
Automotive starter battery replacement cycles sustain lead-acid volume in Karachi-Lahore distribution channels. Import tariff structures protect regional smelter networks from Chinese price competition. Faisalabad's engineering goods cluster hosts aftermarket battery assembly serving commercial vehicle fleets.
South Asia Battery Market Competitive Landscape
East Asian producers anchor the premium cell tier; Indian and Southeast Asian specialists hold assembly and aftermarket positions. Market structure shows moderate consolidation at cell level with fragmented pack integration and distribution layers. Three archetypes dominate: vertically integrated chemistry developers, licensed electrode coaters, and pure-play pack assemblers. Capacity expansion and strategic technology licensing represent the dominant competitive vectors reshaping participant positioning.
Within the integrated chemistry tier, GS Yuasa Corporation and Panasonic Corporation exemplify Japanese-origin multinationals with established formation protocol expertise. BYD Co. Ltd occupies a distinct position bridging cell architecture innovation with downstream vehicle integration. These three entities represent contrasting geographic origins—Japan and China—while sharing scale-driven manufacturing archetypes.
| Leading Market Players |
|---|
| GS Yuasa Corporation |
| Panasonic Corporation |
| BYD Co. Ltd |
| Leoch International Technology Limited |
| C&D Technologies Inc. |
| Exide Industries Limited |
| Samsung SDI Co. Ltd |
| Amara Raja Batteries Ltd |
| LG Chem Ltd |
| Others |
Value Network & Pricing Analysis
Blade-cell architecture adoption across Nepal's electric bus tenders is compressing pack assembly costs while simultaneously concentrating procurement leverage among integrators with localized electrode coating capabilities in Tamil Nadu and Gujarat. This production-method transition feeds back into supply choices as fleet operators demand battery-as-a-service contracts that unbundle cell replacement risk from upfront capital outlays.
Pricing Analysis
Volume concentrates in lead-acid automotive starter and UPS segments while margins pool in lithium-ion grid storage and electric mobility applications. Three-tier pricing structure across premium certified, standard BIS-compliant, and economy non-certified levels separates automotive OEM supply from aftermarket channels. Price differentiation hinges on Bureau of Indian Standards accreditation status and guaranteed cycle-life performance in service contracts. Cost compression in entry-level lithium iron phosphate packs is intensifying because Ahmedabad and Lucknow fleet operators specify these cells for 20-25% pack-level savings over nickel-manganese-cobalt alternatives. Aftermarket automotive channels exhibit highest price sensitivity; grid-connected renewable hybrid projects show lowest sensitivity due to long-term offtake security.
Supply Chain Analysis
Reverse-logistics flows for end-of-life lead-acid batteries sustain regional smelter networks in Bangladesh and Pakistan through formal collection channels that protect against Chinese price competition. Raw material dependencies draw from Chilean and Australian spodumene concentrate for lithium carbonate, South Korean and Japanese separator film production, and domestic electrode coating capacity in Tamil Nadu. Single-source vulnerability concentrates in East Asian electrolyte salt and separator supply. Distribution runs through Exide Industries and Amara Raja's deep aftermarket automotive channels in India, supplemented by cross-border logistics operators in Nepal's Bhaktapur corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's Bureau of Indian Standards certification mandates under IS 16046 erect a cost-of-compliance barrier that rewards accredited domestic testing investment and penalizes import-dependent suppliers. This regulatory moat consolidates procurement preference around pre-qualified cell sources with existing BIS accreditation.
For Market Incumbents: To counter sodium-ion chemistry disruption in entry-level electric mobility, Exide Industries and Amara Raja Batteries should deepen backward integration into electrode coating operations within Gujarat's industrial corridors while accelerating BIS pre-qualification of high-nickel cathode cell sources for premium two-wheeler programs. Channel control through existing aftermarket distribution networks remains essential for defending automotive starter segment position against lithium-ion substitution. For New Entrants and Emerging Players: Rural Bangladesh microgrid operators represent an underserved buyer archetype with uncaptured margin pools for long-cycle-life storage chemistry distinct from urban grid-tied specifications. Solar-diesel hybrid installations in off-grid districts offer the most penetrable application segment. A go-to-market angle anchored in battery-as-a-service arrangements with guaranteed cycle-life performance unbundles cell replacement risk and accelerates procurement decisions. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by East Asian cell manufacturers seeking localized assembly footholds to satisfy India's PLI scheme localization requirements. Long-term viability across the analysis window favors vertically integrated pack assemblers with captive electrode coating capacity and existing BIS accreditation. The signal to watch is CEA grid storage standard revisions that expand certified demand pools for lithium-ion installations in renewable hybrid projects.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Coating | PLI scheme localization mandates in Tamil Nadu and Gujarat compress import dependency for accredited manufacturers. |
| BIS Certification Pre-Qualification | IS 16046 accreditation unlocks preferential access to state electric vehicle procurement tenders across India. |
| Battery-as-a-Service Contract Structuring | Dhaka and Kathmandu municipal tenders now specify unbundled cell replacement risk from vehicle capital cost. |
| Sodium-Ion Chemistry Scale-Up | Entry-level electric mobility cost curves disrupt 20-25% below LFP alternatives in Tier-2 Indian cities. |
| Rural Microgrid Storage Deployment | Solar-diesel hybrid installations in Bangladesh's off-grid districts demand distinct long-cycle-life specifications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with cell formation protocol engineers, pack assembly facility managers, state electric vehicle policy officers, and fleet procurement directors at municipal transport authorities. Bureau of Indian Standards certification documentation, Central Electricity Authority grid storage technical standards, and Bangladesh Power Division import protocols provided regulatory validation. Bottom-up cell production estimates and top-down electric vehicle fleet deployment targets were reconciled through iterative triangulation.
Data-stream reconciliation across chemistry-specific cost curves, localization incentive structures, and end-use procurement patterns shaped the analytical framework. Segmentation dimensions modeled include cathode formulation tier, end-use application, certification status, and regional industrial corridor concentration. CAGRs were derived from installed base replacement cycles and fleet electrification program timelines. Lithium carbonate contract pricing volatility and PLI scheme uptake rates served as key forecast sensitivity inputs throughout the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to East Asian supply concentration risks and raw material input cost swings. Practitioners should monitor CEA standard revision timelines and state-level electric vehicle policy redistributions for early signals of procurement preference shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery-Powered Riveter Market
Batteries
Custom Battery Pack Market
Batteries
South America Battery Cell Market
Batteries
Battery Light Towers Market
Batteries
Taiwan Battery Market
Batteries
Aluminum Wire Battery Market
Batteries
Australia Battery Market
Batteries
Vietnam Battery Market
Batteries
Global Marine Battery Market
Batteries
North America Industrial Battery Market
Batteries
Marine Powerboat Battery Market
Batteries
Southeast Asia Battery Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
India Rechargeable Battery Market
Batteries
High Voltage Battery Market
Batteries
Sodium-Ion Battery Electrolyte Market