
 North America Electric Vehicle Battery Electrolyte Market | 2026-2036
North America Electric Vehicle Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle Battery Electrolyte Market Insights
Canada's emerging battery materials corridor is reshaping North American electrolyte sourcing geography. BASF Corporation leverages its integrated chemical production network to anchor regional lithium salt supply. LG Chem Ltd. competes through captive cathode-electrolyte alignment in US Midwest manufacturing. Mitsubishi Chemical Group specializes in high-purity carbonate solvents for premium cell formulations.
Electric vehicle battery electrolyte constitutes an ionically conductive medium, typically comprising lithium salts dissolved in organic carbonate solvents, that facilitates lithium-ion transport between anode and cathode during charge and discharge cycles. Liquid electrolyte formulations currently dominate commercial production due to established manufacturing scalability and cost structure, though solid polymer electrolyte represents the fastest-growing technology segment as OEMs pursue higher energy density targets with reduced thermal runaway risk. Sodium-ion technology applications are expanding within commercial vehicle segments where energy density requirements trade off against material cost and supply security considerations.
The US Environmental Protection Agency tailpipe emission standards and the Inflation Reduction Act domestic content provisions collectively reshape product qualification requirements and manufacturing location decisions for electrolyte suppliers. Transport Canada and Health Canada coordinate battery safety standards that influence electrolyte formulation specifications for vehicles operating across the US-Canada border. Stakeholders must monitor evolving critical mineral sourcing rules and their cascading impact on electrolyte additive qualification and regional supply chain configuration.
Market Dynamics
The Inflation Reduction Act's domestic content provisions are forcing electrolyte suppliers to relocate manufacturing capacity to the US Great Lakes corridor, restructuring North American supply geography around Michigan and Ohio battery megafactories.
Growth Catalysts
- EPA tailpipe emission standards:The US Environmental Protection Agency's tightened vehicle emission rules are mandating accelerated EV adoption across passenger and commercial fleets, expanding addressable demand for high-voltage battery electrolyte formulations.
- Solid polymer electrolyte technology:OEM pursuit of higher energy density targets with reduced thermal runaway risk is pulling investment toward next-generation solid-state cell architectures and their specialized ionic conductor requirements.
- Canada's battery materials corridor:Quebec and Ontario's integrated mining-refining-manufacturing clusters are attracting electrolyte precursor investments that reduce trans-Pacific supply dependencies for North American cell producers.
Market Restraints
- Lithium carbonate price volatility:Concentrated South American and Australian spodumene supply exposes electrolyte cost structures to extraction bottlenecks and battery-grade lithium salt contract repricing cycles.
- Fluoroethylene carbonate import concentration:Asian specialty chemical producers dominate high-purity electrolyte additive supply, creating single-source vulnerability for North American formulators seeking USMCA qualifying content ratios.
- Liquid electrolyte flammability ceiling:Established carbonate solvent formulations carry inherent thermal runaway limitations that constrain pack-level energy density gains regardless of cathode chemistry advances.
Strategic Opportunities
- Sodium-ion commercial vehicle penetration:Lower energy density tolerance in urban delivery and school bus fleets creates electrolyte formulation openings using abundant sodium salts rather than lithium-dependent chemistries.
- Mexico nearshoring expansion:Baja California and Nuevo León manufacturing zones offer tariff-advantaged production bases for electrolyte suppliers serving US Southwest battery assembly plants under USMCA rules of origin.
- Transport Canada-EPA regulatory alignment:Harmonized cross-border battery safety standards are simplifying formulation qualification for suppliers seeking unified product approvals across the US-Canada automotive corridor.
Industry Challenges
- Electrolyte additive toxicology assessment:Health Canada's PMRA and the US EPA are tightening novel chemical substance review timelines, delaying commercialization of next-generation flame retardant and high-voltage stabilizer compounds.
- Dry electrode coating integration:Emerging solvent-free electrode manufacturing processes require electrolyte wetting property recalibration, forcing reformulation investments that strain R&D bandwidth at mid-scale suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle Battery Electrolyte Market |
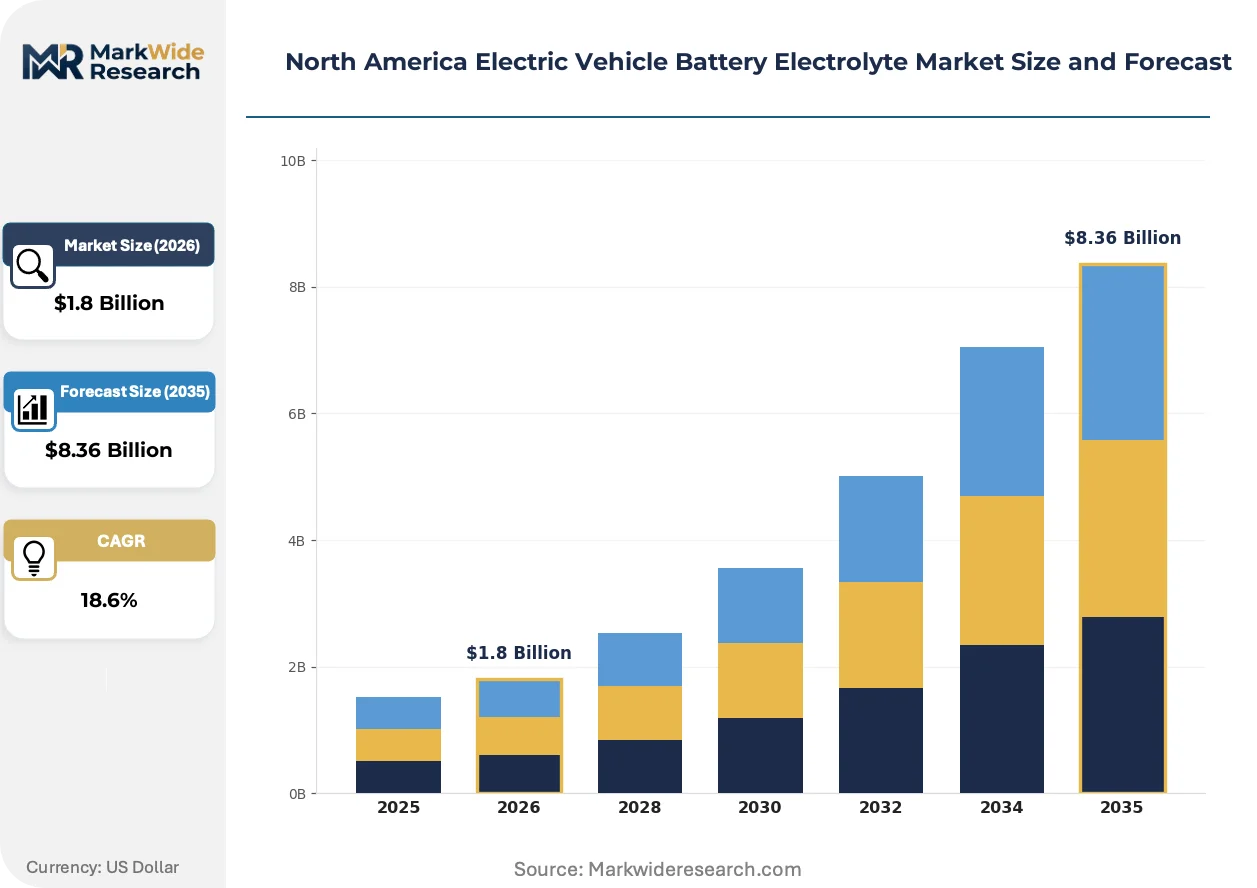
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Electrolyte, Gel Polymer Electrolyte, Solid Polymer Electrolyte, Ionic Liquid Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Low-Speed Vehicles Technology: Lithium-Ion, Lithium Polymer, Sodium-Ion, Redox Flow End User: Manufacturers, OEMs, Aftermarket Suppliers, Research Institutions |
| Companies Covered | 3M Company, BASF Corporation, Mitsubishi Chemical Group, Targray Technology International Inc, NEI Corporation, UBE Corporation, LG Chem Ltd., American Elements, Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle Battery Electrolyte Market Trends and Innovations
Solid-state electrolyte architectures are virtualizing conventional liquid formulation supply chains, while regulatory chemistry disclosure requirements and OEM captive production strategies are compressing merchant electrolyte margins.
Localized lithium hexafluorophosphate synthesis is virtualizing traditional Asian import dependencies for North American cell producers. BASF Corporation and emerging domestic suppliers are commissioning integrated salt-solvent production trains in Louisiana and Texas chemical corridors. This captive precursor capability is compressing working capital requirements for electrolyte blenders and reducing exposure to spot lithium salt volatility.
The US Inflation Reduction Act's critical mineral and battery component content thresholds are restructuring qualification protocols for electrolyte suppliers seeking federal tax credit eligibility. Transport Canada and the EPA are coordinating aligned substance disclosure frameworks that reduce redundant testing burdens for cross-border product registrations. Formulators serving the integrated US-Canada automotive supply chain are consolidating product lines around harmonized additive packages.
Long-term offtake contracting is displacing spot market purchasing as the dominant procurement mode for electrolyte volume commitments. Battery OEMs in Michigan and Ohio are negotiating five-to-seven-year supply agreements with floor-price protections and dedicated capacity reservations. This contract concentration is most visible in the Great Lakes manufacturing corridor, where new cell gigafactories require supply security for ramping production schedules.
North America Electric Vehicle Battery Electrolyte Market Segmentation
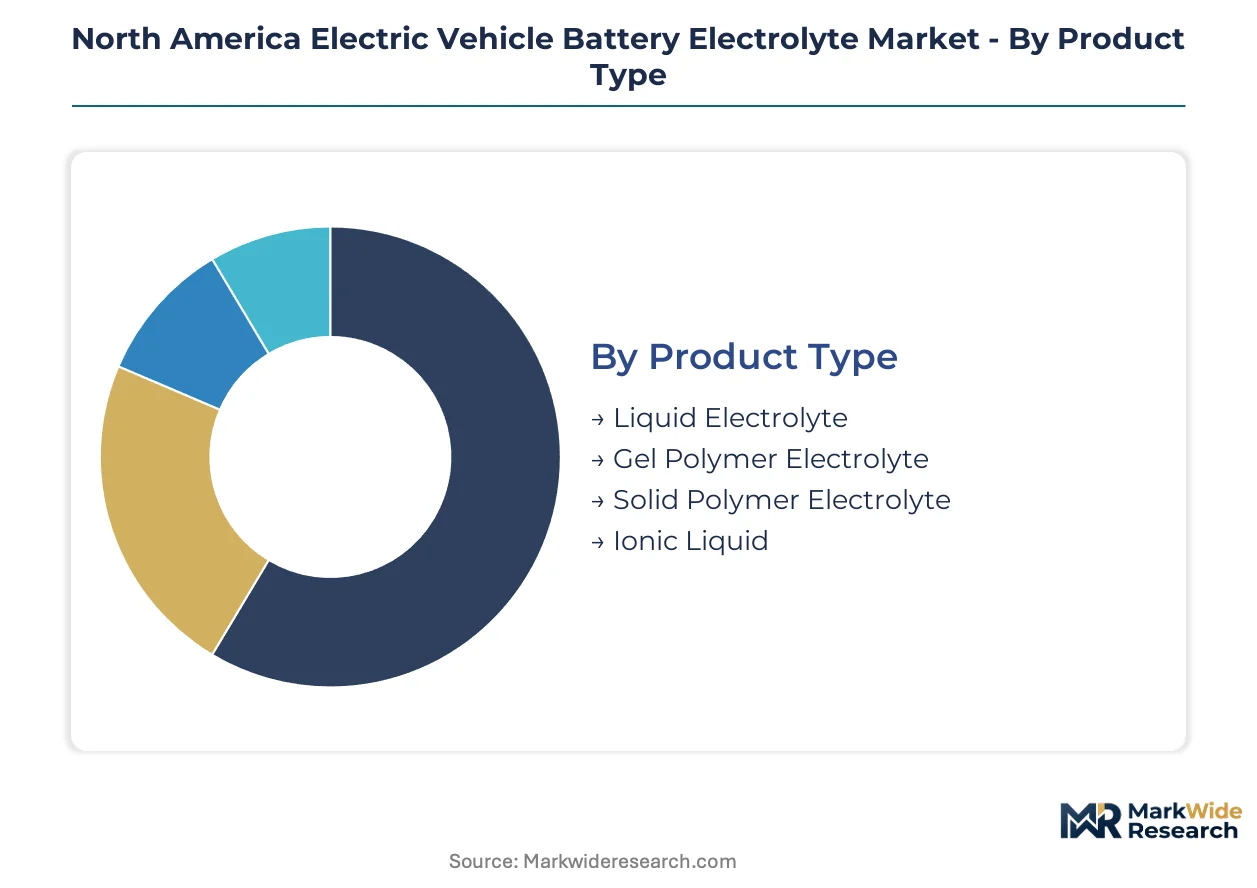
Electrolyte formulation specifications diverge sharply across cell architectures and vehicle platforms, forcing suppliers to maintain parallel production lines with distinct additive packages and purity grades. Segmentation discipline separates volume-driven commodity blends from specialty formulations commanding technical premiums.
Product Type:
After-sales service intensity escalates from liquid to solid-state formats, with gel and solid polymer electrolytes requiring specialized diagnostic equipment and cell replacement protocols rather than routine maintenance.
- Liquid Electrolyte:Lithium hexafluorophosphate dissolved in ethylene carbonate and dimethyl carbonate mixtures constitutes the incumbent formulation. Michigan and Ohio cell gigafactories consume the majority of North American volume for cylindrical and prismatic cell assembly. Established supply chains and blending infrastructure protect cost positions against emerging alternatives.
- Solid Polymer Electrolyte:Dry ion-conductive polymer matrices eliminate flammable solvents and enable lithium-metal anode compatibility. OEMs in the US Great Lakes corridor pilot solid-state packs for premium passenger segments where energy density targets exceed 400 Wh/kg. Manufacturing scale-up challenges constrain near-term volume.
- Gel Polymer Electrolyte:Semi-solid formulations bridge liquid conductivity with polymer mechanical stability.
- Ionic Liquid:Non-flammable molten salt electrolytes operate across extended temperature ranges.
By volume, liquid electrolyte leads. By growth pace, solid polymer electrolyte is ahead.
Application:
Cost tier stratification separates passenger vehicle formulations—optimized for cycle life and fast-charge capability—from commercial vehicle blends prioritizing calendar life and thermal tolerance.
- Passenger Vehicles:High-voltage pack architectures above 800V drive electrolyte additive innovation for high-voltage stability. US EPA tailpipe standards accelerate OEM procurement across Michigan, Ohio, and Tennessee battery assembly corridors. Formulators compete on flame retardant packages and low-temperature conductivity specifications.
- Commercial Vehicles:Heavy-duty cycle profiles demand enhanced thermal management and extended calendar life. School bus and urban delivery fleets in California and Quebec adopt sodium-ion compatible electrolytes where energy density requirements trade against material cost. Duty cycle severity justifies premium additive loadings.
- Two-Wheelers:Compact pack geometries favor gel polymer formats with simplified cell sealing.
- Low-Speed Vehicles:Price-sensitive neighborhood electric vehicle segments drive commodity electrolyte sourcing.
Passenger vehicles dominate absolute volume. Commercial vehicles are climbing the fastest as fleet electrification mandates tighten.
Technology:
Customer type segmentation maps electrolyte R&D investment intensity, with lithium-ion commanding mainstream manufacturing resources and sodium-ion attracting venture-backed pilot production.
- Lithium-Ion:Nickel-manganese-cobalt and lithium-iron-phosphate cathode pairings dictate distinct electrolyte additive strategies. The US Inflation Reduction Act's critical mineral thresholds redirect supplier qualification toward North American lithium salt sourcing. BASF Corporation and domestic blenders commission integrated precursor capacity in Louisiana chemical corridors.
- Sodium-Ion:Abundant sodium salt feedstocks reduce supply security risk for commercial vehicle and stationary storage applications. Quebec mining-refining clusters evaluate sodium sulfate conversion to battery-grade precursors. Energy density limitations constrain passenger vehicle penetration.
- Lithium Polymer:Pouch cell architectures favor gel electrolyte formats with flexible packaging compatibility.
- Redox Flow:Aqueous electrolyte systems serve grid-scale storage with decoupled power-energy scaling.
Lithium-ion retains volume leadership. Sodium-ion is gaining share fastest as raw material cost pressures intensify.
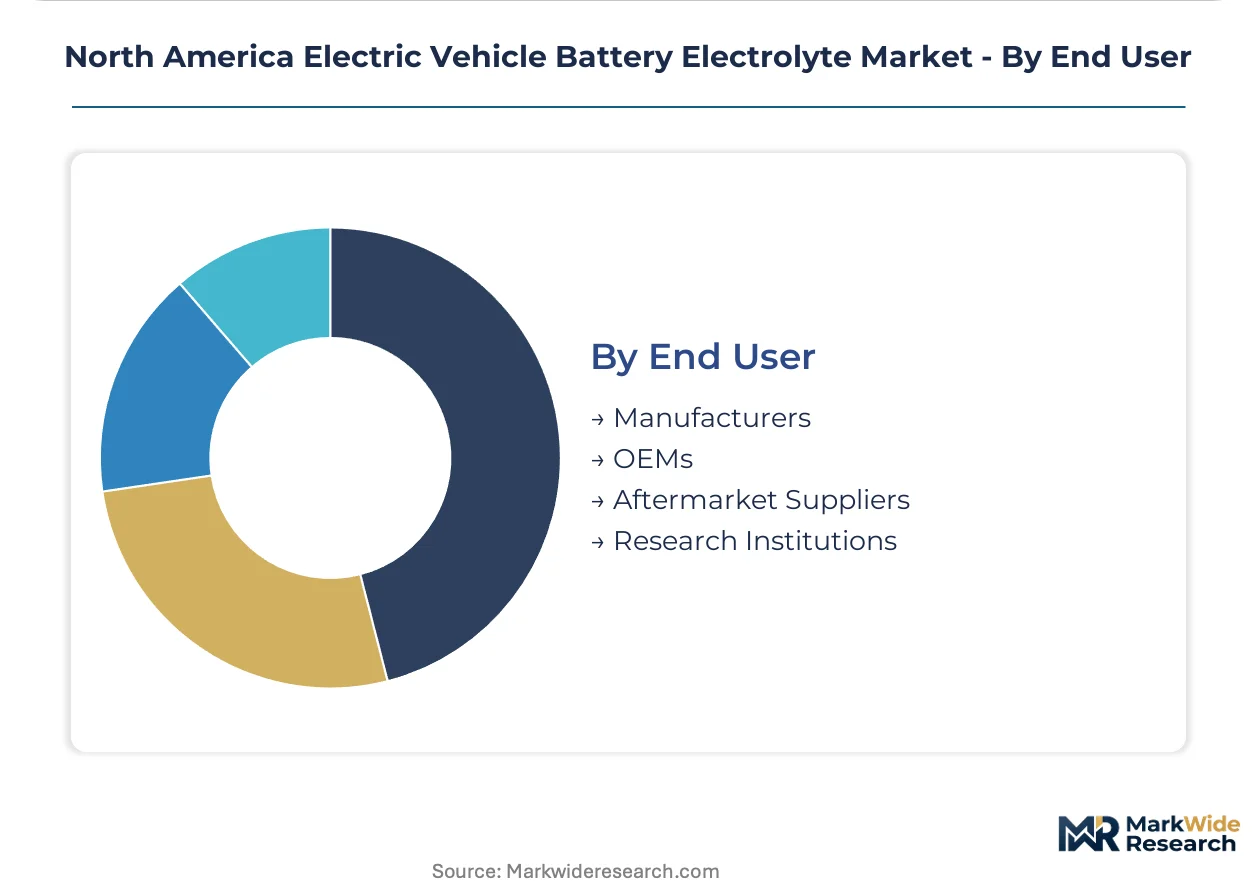
End User:
Supply concentration varies sharply across end-user tiers, with OEM captive production displacing merchant sales in high-volume battery manufacturing corridors.
- OEMs:Vertically integrated cell producers in Michigan and Ohio negotiate long-term offtake contracts with floor-price protections. Dedicated capacity reservations and formulation co-development agreements lock in supply security for ramping gigafactory schedules. Transport Canada-EPA regulatory alignment simplifies cross-border product registration.
- Manufacturers:Independent cell producers source merchant electrolyte blends with shorter contract horizons and spot market exposure.
- Aftermarket Suppliers:Replacement pack rebuilders require compatible electrolyte formulations for legacy vehicle servicing.
- Research Institutions:National laboratories and university consortia pilot novel ionic conductors and solid-state architectures.
OEMs command the largest volume commitments. Research institutions are expanding fastest as solid-state development programs multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrolyte production capacity clusters along the US-Canada automotive corridor, with Michigan and Ohio cell gigafactories driving demand concentration. Mexico's nearshoring zones and Quebec's mining-refining integration complete the North American supply triangle.
United States
Michigan and Ohio battery megafactories consume the majority of regional electrolyte volume for cylindrical and prismatic cell assembly. The US Inflation Reduction Act's domestic content thresholds redirect supplier qualification toward Louisiana and Texas chemical corridor production. BASF Corporation anchors integrated lithium salt-solvent manufacturing in these Gulf Coast clusters.
Canada
Quebec and Ontario's integrated mining-refining-manufacturing clusters attract electrolyte precursor investments that reduce trans-Pacific supply dependencies. Transport Canada and Health Canada coordinate battery safety standards that influence electrolyte formulation specifications for cross-border vehicle operations. The country's battery materials corridor is reshaping North American electrolyte sourcing geography.
Mexico
Baja California and Nuevo León manufacturing zones offer tariff-advantaged production bases for electrolyte suppliers serving US Southwest battery assembly plants. USMCA rules of origin compliance positions Mexican blending facilities for duty-free access to American OEM procurement channels. Nearshoring momentum is accelerating as suppliers seek to bypass Pacific logistics constraints.
North America Electric Vehicle Battery Electrolyte Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in salt, solvent, and additive supply. The vendor base organizes around three archetypes: integrated chemical conglomerates with captive precursor networks, Asian battery material specialists with captive cathode-electrolyte alignment, and regional blenders dependent on merchant salt sourcing. Competitive moves concentrate on backward integration into lithium hexafluorophosphate synthesis and long-term offtake contracting with floor-price protections.
Within the integrated chemical tier, BASF Corporation exemplifies the conglomerate archetype through its Louisiana-Texas production network. LG Chem Ltd. occupies a position representing Asian battery material specialists with Midwest manufacturing alignment. Mitsubishi Chemical Group anchors the high-purity carbonate solvent specialization segment. These three players illustrate divergent strategic postures: captive precursor control, cathode-electrolyte integration, and premium formulation focus.
| Leading Market Players |
|---|
| 3M Company |
| BASF Corporation |
| Mitsubishi Chemical Group |
| Targray Technology International Inc |
| NEI Corporation |
| UBE Corporation |
| LG Chem Ltd. |
| American Elements |
| Umicore |
| Others |
Pricing and Supply Chain Analysis
The US Gulf Coast chemical corridor anchors North American lithium hexafluorophosphate capacity, concentrating upstream salt synthesis in Louisiana and Texas. This geographic clustering grants integrated producers leverage over merchant blenders dependent on spot market sourcing, compressing margins for non-captive suppliers while stabilizing input costs for backward-integrated formulators.
Pricing Analysis
The US Inflation Reduction Act dictates the pricing tier structure across North American electrolyte supply. Battery-grade lithium salt certification tiers separate premium formulations qualifying for federal tax credits from standard blends lacking domestic content compliance. Cost compression in merchant-grade liquid electrolyte is intensifying because OEM captive production displaces spot purchasing. Independent cell producers exhibit the highest price sensitivity, while vertically integrated OEMs prioritize supply security over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Asian specialty chemical producers sustain fluoroethylene carbonate import flows into North American blending operations. The supply chain draws from South American lithium brine operations, Australian spodumene concentrates, and East Asian high-purity carbonate solvent refineries. Single-source vulnerability concentrates in specialty additive supply from Korean and Japanese producers. Distribution runs through dedicated tanker networks serving Michigan and Ohio battery megafactories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American electrolyte demand is entering a cyclical upswing driven by IRA-mandated domestic content thresholds accelerating OEM procurement timelines.
For Market Incumbents: Harden captive lithium salt production positions through Louisiana and Texas chemical corridor capacity additions. Secure long-term offtake contracts with floor-price protections against spot lithium carbonate volatility. Defend formulation know-how through EPA-aligned additive qualification pipelines that delay competitor certification timelines. For New Entrants and Emerging Players: Establish a beachhead in sodium-ion electrolyte formulations for commercial vehicle segments where energy density tolerances permit lower-cost chemistry. Target Quebec's battery materials corridor for precursor integration advantages. Lead with Transport Canada-EPA harmonized product registrations that unlock cross-border qualification efficiency. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors solid-state electrolyte specialists with lithium-metal anode compatibility. The five-to-ten year window rewards platforms bridging liquid formulation revenue with solid polymer R&D pipelines. Watch solid-state pilot production timelines at Michigan OEM facilities as the inflection signal for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Salt Synthesis | BASF Corporation's Louisiana production train reduces working capital exposure for Great Lakes blenders. |
| Long-Term Supply Agreement with Floor-Price Protection | Five-to-seven-year contracts with Michigan OEMs lock in capacity reservations for ramping gigafactory schedules. |
| Cross-Border Regulatory Harmonization Investment | Transport Canada-EPA aligned additive packages consolidate product lines for unified North American registration. |
| Solid-State Electrolyte Pilot Production Scale-Up | OEM energy density targets above 400 Wh/kg pull investment toward dry polymer matrix manufacturing. |
| Mexico Nearshoring Manufacturing Footprint | Baja California blending facilities secure USMCA duty-free access to Southwest US battery assembly plants. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with electrolyte procurement managers at Michigan and Ohio cell producers, Louisiana plant operations directors, and Transport Canada regulatory affairs specialists; and secondary validation against US EPA filing databases, SEC 10-K disclosures from integrated chemical conglomerates, and customs trade records tracking lithium salt import flows. Bottom-up volume estimates from individual gigafactory consumption profiles were triangulated against top-down market sizing derived from vehicle production forecasts and battery pack chemistry mix assumptions.
Forecast inputs span liquid, solid polymer, and gel electrolyte product categories across passenger vehicle, commercial vehicle, and two-wheeler applications, with lithium-ion, sodium-ion, and lithium polymer technology disaggregation. Modeled CAGRs reflect segment-level growth rate differentials applied across the projection horizon. Industry-specific inputs include IRA domestic content threshold compliance rates, solid-state pilot production announcement timelines, and Quebec mining-refining cluster development milestones.
Stress conditions across lithium carbonate price bands, fluoroethylene carbonate import disruption scenarios, and solid-state technology substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and OEM electrification commitment durability. Macroeconomic contraction, critical mineral sourcing rule revision, or solid-state manufacturing breakthrough would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Solar Containers Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
United States Electric Vehicle Battery Separator Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Lithium-Ion Battery Housing Cases Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Asia Pacific Electric Vehicle Battery Separator Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
France Electric Vehicle Battery Separator Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
Battery Swap-Ready Pack Systems for Urban Fleets Market