
 ASEAN Countries Electric Vehicle Battery Electrolyte Market | 2026-2036
ASEAN Countries Electric Vehicle Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Countries Electric Vehicle Battery Electrolyte Market Insights
The divergence between premium solid-state formulations and commodity liquid electrolyte grades is realigning procurement strategies across ASEAN cell plants. CATL leverages its integrated supply chain to sustain cost leadership in Thailand's expanding production base. Samsung SDI anchors premium positioning through high-voltage electrolyte specialization for Southeast Asian OEM programs. BYD competes aggressively on volume scale, extending its captive demand from Indonesia's growing electric bus and passenger vehicle assembly.
ASEAN Countries Electric Vehicle Battery Electrolyte encompasses ion-conducting media—typically lithium hexafluorophosphate dissolved in carbonate solvents—that enable lithium-ion charge transfer between anode and cathode during cycling, with conductivity parameters generally ranging from 4 to 10 mS/cm at room temperature. Liquid electrolyte still dominates installed capacity across Thai and Indonesian cell lines, though solid-state electrolyte represents the fastest-growing technology category as regional producers pilot next-generation architectures. Polymer electrolyte occupies a niche in flexible-format applications for tropical climate two-wheelers, where thermal stability requirements differ from automotive-grade specifications.
Thailand's Board of Investment EV incentive packages and Indonesia's downstream mineral processing regulations are tightening local content thresholds, forcing electrolyte suppliers to establish domestic blending or precursor operations. BIS-equivalent standards in emerging ASEAN jurisdictions, alongside ESG disclosure requirements modeled on EU Battery Regulation frameworks, are raising qualification barriers for imported formulations. Stakeholders must monitor how Indonesia's nickel refining quotas and Thailand's carbon border preparation timelines reshape electrolyte chemistry roadmaps and regional manufacturing commitments.
Market Dynamics
Thailand's Board of Investment EV incentive packages and Indonesia's downstream mineral processing regulations are forcing electrolyte suppliers to establish domestic blending operations, fundamentally restructuring regional supply chain geography around local content thresholds rather than import efficiency.
Growth Catalysts
- Thailand's BOI EV incentive framework:Tax holidays and import duty exemptions for battery component manufacturing are pulling electrolyte blenders into the Eastern Economic Corridor industrial zone.
- Indonesian nickel-to-cell integration:Downstream mineral processing mandates are creating captive demand for electrolyte precursors refined from domestic laterite ore deposits.
- High-voltage electrolyte chemistry:Nickel-rich cathode adoption in ASEAN passenger vehicle programs requires advanced additive packages with enhanced oxidation stability.
Market Restraints
- Lithium hexafluorophosphate supply concentration:Precursor manufacturing clusters in China's Hunan and Hubei provinces create single-source vulnerability for ASEAN blenders.
- Fluoroethylene carbonate cost volatility:This high-purity solvent constitutes 35-45% of liquid electrolyte material cost and tracks fluorochemical feedstock availability.
- Solid-state electrolyte technical immaturity:Sulfide-based ceramic conductivity degradation at tropical humidity levels delays regional manufacturing feasibility.
Strategic Opportunities
- Vietnam's emerging cell assembly base:VinFast's expanding battery production creates uncontracted electrolyte demand outside established Thai-Indonesian supply relationships.
- Two-wheeler polymer electrolyte niche:Flexible-format solid polymer systems address thermal management constraints in Southeast Asian scooter electrification programs.
- EU Battery Regulation alignment:Carbon footprint disclosure and recycled content mandates are creating first-mover advantage for ASEAN suppliers with ESG-certified production.
Industry Challenges
- Electrolyte formulator talent scarcity:ASEAN universities lack specialized programs in non-aqueous electrochemistry, forcing reliance on expatriate technical leadership.
- BIS-equivalent certification timelines:Emerging national standards bodies in Vietnam and the Philippines lack testing infrastructure, extending product qualification cycles.
- Legacy automotive supplier integration:Japanese tier-one battery management system vendors resist chemistry changes that invalidate existing thermal runaway models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Countries Electric Vehicle Battery Electrolyte Market |
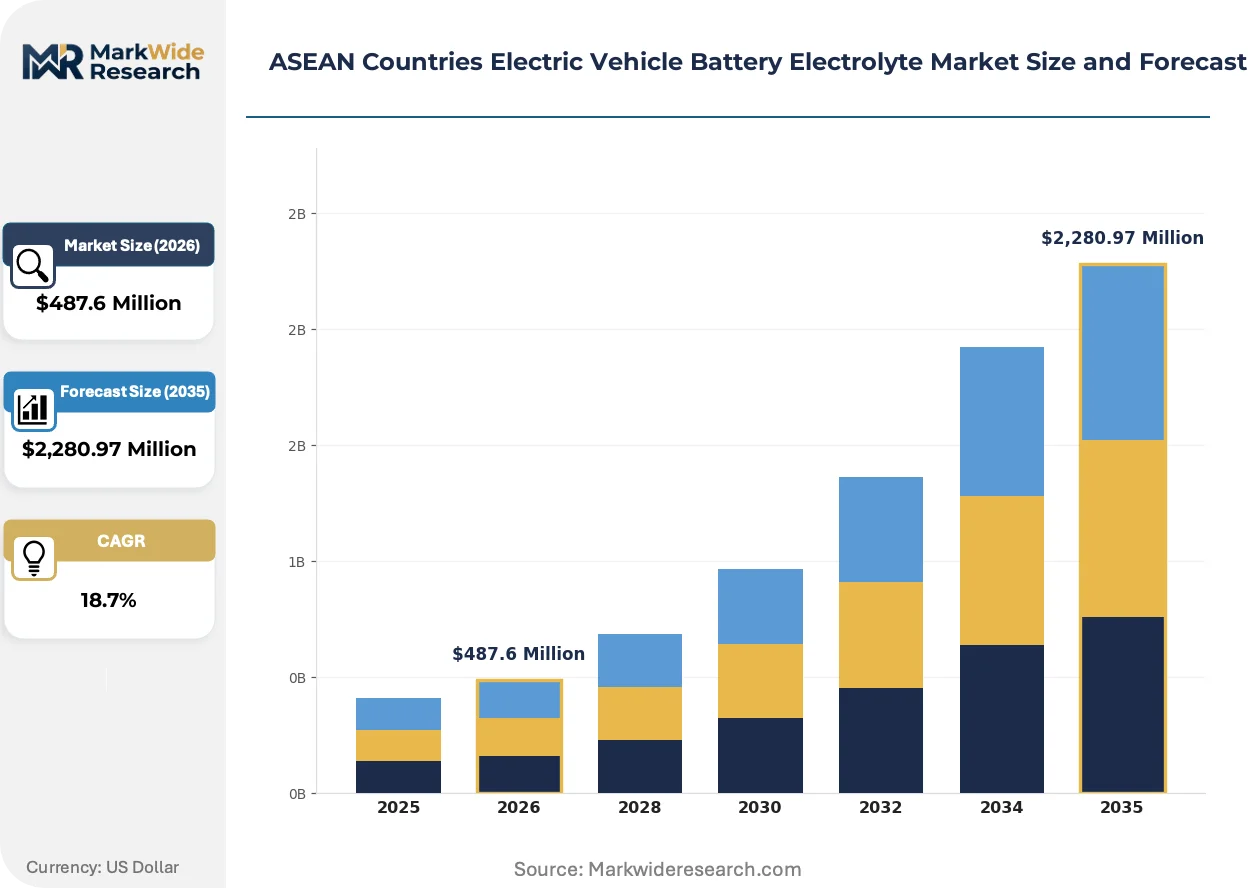
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,280.97 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Electrolyte, Gel Electrolyte, Polymer Electrolyte, Solid-State Electrolyte Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Buses End User: OEM Manufacturers, Aftermarket, Electric Fleets, Government Transport Technology: Lithium-Ion, Solid-State, Flow Battery, Nickel-Metal Hydride |
| Companies Covered | Samsung SDI Co. Ltd., Contemporary Amperex Technology Co. Ltd. (CATL), LG Energy Solution Ltd., GS Yuasa Corporation, Panasonic Holdings Corporation, BYD Company Ltd., SK Innovation Co. Ltd., SVOLT Energy Technology Co. Ltd., LiRON LIB Power Pte Ltd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Countries Electric Vehicle Battery Electrolyte Market Trends and Innovations
Electrolyte formulation strategy across ASEAN cell plants is pivoting from commodity liquid systems toward differentiated high-voltage and solid-state architectures, with supplier qualification criteria now embedding carbon intensity and mineral traceability requirements alongside performance metrics.
Localized electrolyte blending is overtaking centralized Asian supply as the dominant procurement model for Thai and Indonesian cell manufacturers. CATL and Samsung SDI are requiring their formulation partners to establish domestic compounding facilities within 200 kilometers of electrode coating lines. This geographic compression eliminates cross-border hazardous material transport complexity while satisfying emerging local content thresholds for national EV subsidy eligibility.
Indonesia's downstream mineral processing regulations are mandating that nickel-derived battery materials achieve specified domestic value-add thresholds before export or integration into cell manufacturing. These rules are accelerating precursor salt crystallization and solvent purification investments within the country's industrial parks. Electrolyte suppliers without captive lithium hexafluorophosphate or fluoroethylene carbonate production face exclusion from integrated nickel-to-cell project offtake agreements.
Fleet operators and energy storage developers are consolidating electrolyte procurement under long-term chemistry roadmaps rather than spot formulations. This behavioral shift compresses supplier switching flexibility and rewards formulators with demonstrated R&D pipelines spanning three to five cell generations. Thailand's electric bus operators and Indonesia's utility-scale storage integrators are most visibly adopting this roadmap-based contracting approach, locking in electrolyte specifications that align with their projected cell technology transitions.
ASEAN Countries Electric Vehicle Battery Electrolyte Market Segmentation
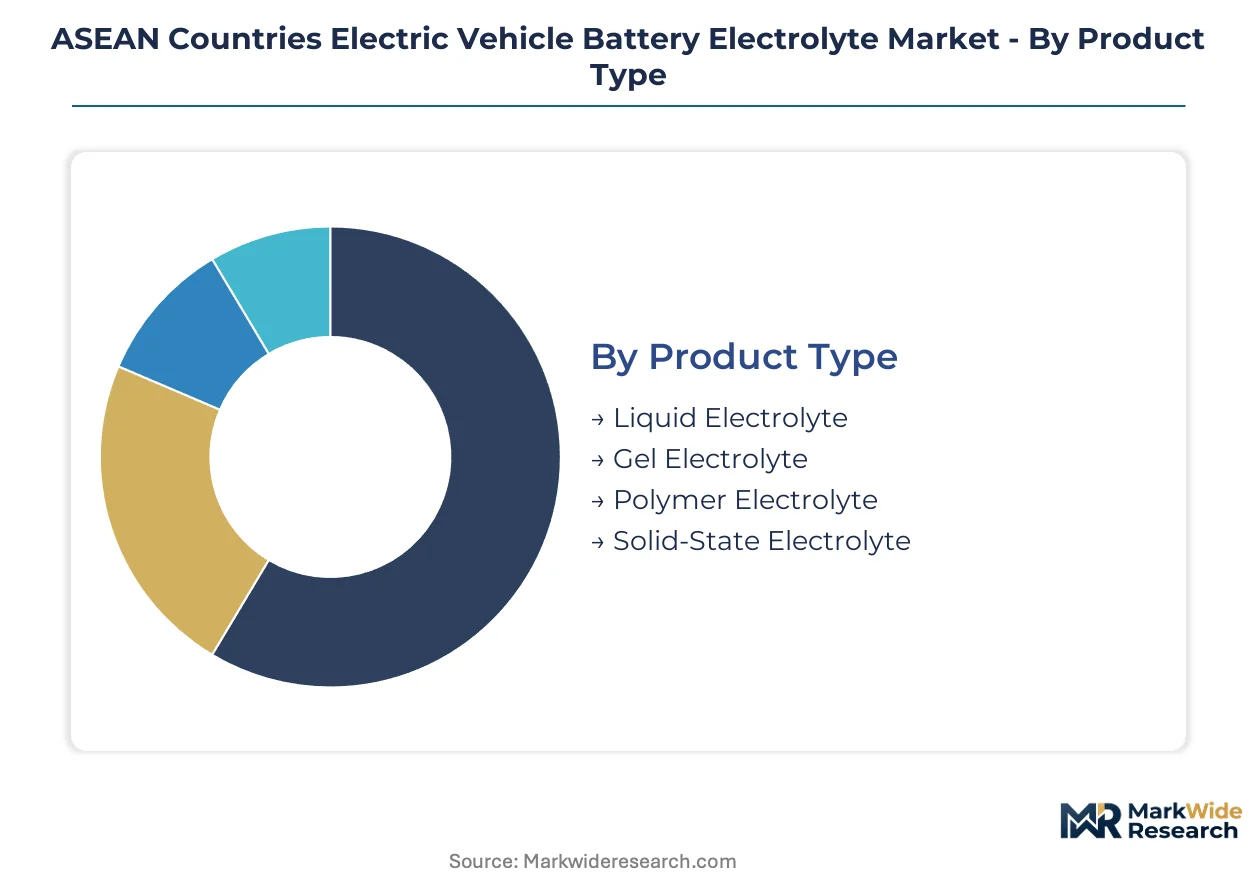
Electrolyte procurement patterns across ASEAN cell plants diverge sharply by product chemistry, vehicle application, and end-user contracting behavior. Each segmentation axis carries distinct qualification burdens, margin profiles, and supply chain configurations that reshape supplier competitive positioning.
Product Type:
Certification requirements stratify across electrolyte formats, with liquid systems facing established BIS-equivalent protocols while solid-state architectures confront evolving safety frameworks without harmonized regional standards.
- Liquid Electrolyte:Lithium hexafluorophosphate dissolved in carbonate solvent blends dominates Thai and Indonesian cell line installations. Passenger vehicle programs in Thailand's Eastern Economic Corridor absorb the bulk of procurement volume, constrained by fluoroethylene carbonate cost volatility and precursor import dependency.
- Solid-State Electrolyte:Sulfide-based ceramic and oxide thin-film architectures enable nickel-rich cathode compatibility at elevated voltages. Pilot production lines in Indonesian integrated nickel-to-cell projects are testing these formulations, though tropical humidity degradation delays manufacturing scale-up.
- Polymer Electrolyte:Flexible-format solid polymer systems serve Southeast Asian scooter electrification programs where thermal management requirements differ from automotive specifications.
- Gel Electrolyte:Semi-solid matrices occupy niche applications in electric bus modules requiring enhanced leak resistance under vibration stress.
Liquid Electrolyte sits at the top of the volume ranking, with Solid-State Electrolyte climbing the fastest.
Application:
Vehicle electrification programs across ASEAN concentrate procurement in passenger segments, though commercial and fleet applications are diverging toward specialized electrolyte specifications with extended cycle life requirements.
- Passenger Vehicles:Nickel-rich cathode adoption in Thai and Indonesian OEM programs drives demand for high-voltage electrolyte additive packages with enhanced oxidation stability. Indonesia's domestic content thresholds and Thailand's BOI incentive frameworks reshape supplier qualification criteria for this segment.
- Electric Buses:Fleet operators in Bangkok and Jakarta are consolidating procurement under long-term chemistry roadmaps rather than spot formulations, locking in electrolyte specifications that align with projected cell technology transitions over three to five generations.
- Two-Wheelers:Polymer electrolyte systems address thermal stability constraints in tropical climate scooter electrification programs across Vietnam and the Philippines.
- Commercial Vehicles:Heavy-duty logistics electrification in Indonesian mining corridors and Thai industrial zones requires electrolyte formulations optimized for high-C-rate cycling durability.
Passenger Vehicles command the largest procurement volumes, while Electric Buses are expanding most quickly.
End User:
Contracting behavior diverges between integrated cell manufacturers with captive demand and independent fleet operators seeking chemistry roadmap alignment.
- OEM Manufacturers:CATL, Samsung SDI, and BYD are requiring formulation partners to establish domestic compounding facilities within 200 kilometers of electrode coating lines, eliminating cross-border hazardous material transport complexity.
- Electric Fleets:Bus operators and energy storage developers are adopting roadmap-based contracting that compresses supplier switching flexibility and rewards formulators with demonstrated R&D pipelines spanning multiple cell generations.
- Government Transport:State-owned transit authorities in Thailand and Indonesia are embedding local content thresholds and ESG disclosure requirements into procurement specifications.
- Aftermarket:Replacement electrolyte demand remains minimal given cell-level sealed architectures, though diagnostic and refurbishment services are emerging in Vietnamese and Philippine urban centers.
OEM Manufacturers represent the dominant demand source, with Electric Fleets gaining share fastest through consolidated long-term agreements.
Technology:
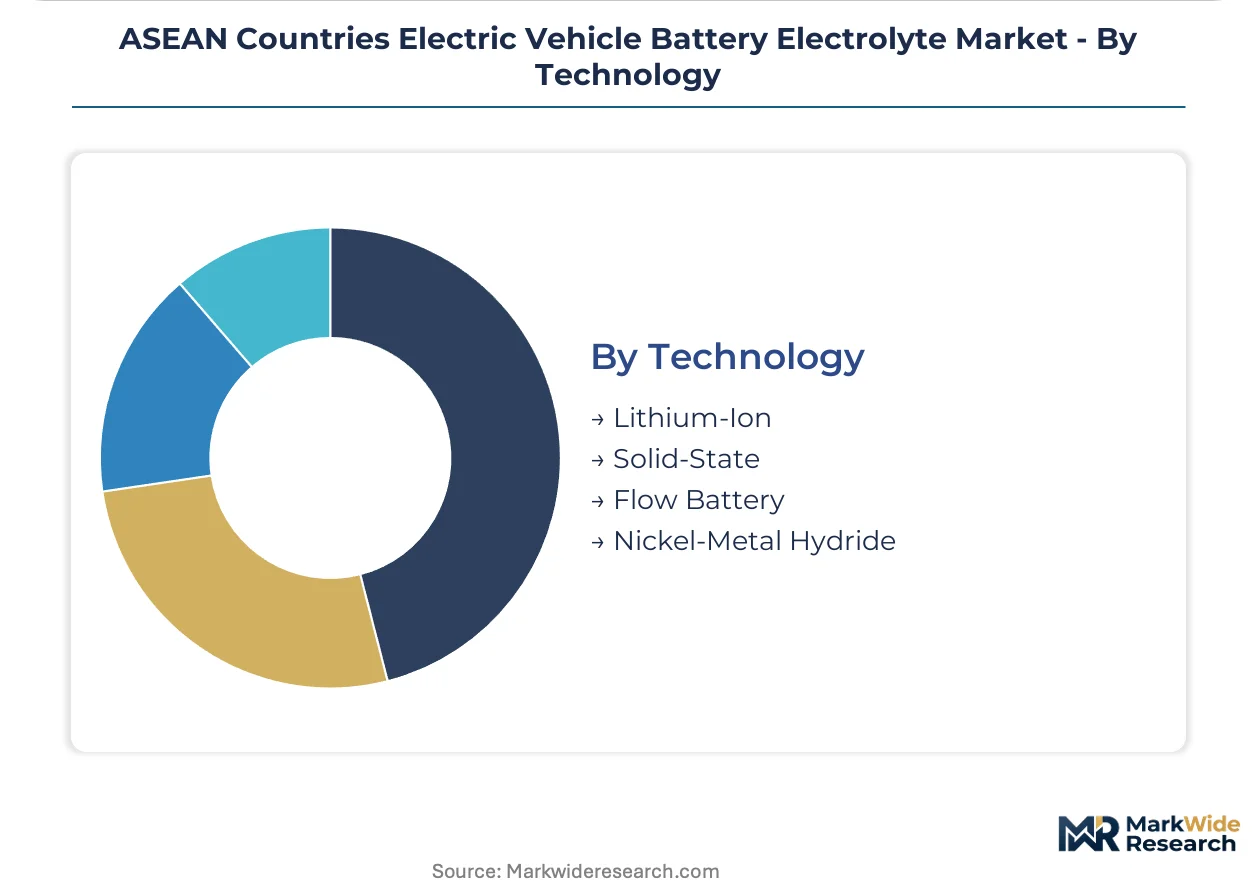
Cell chemistry roadmaps determine electrolyte conductivity requirements, with lithium-ion systems facing incremental optimization pressures while solid-state architectures require entirely new ion-conducting media formulations.
- Lithium-Ion:Liquid and gel electrolyte systems with conductivity parameters ranging from 4 to 10 mS/cm at room temperature serve the installed base across Thai and Indonesian production lines. High-voltage additive packages are becoming mandatory for nickel-rich cathode compatibility.
- Solid-State:Ceramic and glass-ceramic electrolytes eliminate flammability risks while enabling lithium metal anode integration. Regional producers are piloting these architectures, though manufacturing feasibility remains constrained by tropical humidity exposure.
- Flow Battery:Aqueous electrolyte systems for stationary energy storage applications occupy a distinct procurement channel with separate supply chain configurations from automotive-grade non-aqueous formulations.
- Nickel-Metal Hydride:Legacy hybrid vehicle programs in Thai automotive assembly plants sustain residual demand for alkaline electrolyte systems with established recycling infrastructure.
Lithium-Ion maintains volume leadership, with Solid-State posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrolyte formulator talent pools concentrate in Thailand's Eastern Economic Corridor and Indonesia's nickel processing zones, with emerging technical capabilities in Vietnam and the Philippines reshaping regional supply chain geography.
Thailand
Passenger vehicle electrification and BOI tax incentives pull electrolyte blenders toward Rayong and Chonburi industrial zones. Thailand's Board of Investment EV incentive packages mandate local content thresholds for battery component manufacturing. CATL and Samsung SDI compounding facilities within 200 kilometers of electrode coating lines are consolidating procurement around domestic blending operations.
Indonesia
Downstream mineral processing regulations create captive demand for electrolyte precursors refined from domestic laterite ore deposits. Indonesia's nickel-to-cell integration mandates require specified domestic value-add thresholds before battery materials enter cell manufacturing. Integrated industrial parks in Morowali and Weda Bay are accelerating precursor salt crystallization investments.
Vietnam
VinFast's expanding battery production generates uncontracted electrolyte demand outside established Thai-Indonesian supply relationships. Vietnam's national standards body lacks BIS-equivalent testing infrastructure, extending product qualification cycles for imported formulations. Ho Chi Minh City and Hai Phong industrial corridors are emerging as alternative cell assembly locations.
Singapore
Specialized electrochemistry R&D capabilities and regional headquarters functions attract electrolyte suppliers seeking Southeast Asian coordination centers. Singapore's ESG disclosure frameworks and carbon border preparation timelines align with EU Battery Regulation compliance requirements. Jurong Island chemical processing infrastructure supports high-purity solvent purification for regional distribution.
Philippines
Two-wheeler electrification programs in Metro Manila and Cebu create niche demand for polymer electrolyte systems with tropical climate thermal stability. The country's emerging national standards body faces certification infrastructure gaps similar to Vietnam. Batangas and Laguna industrial zones are piloting flexible-format battery assembly for scooter applications.
ASEAN Countries Electric Vehicle Battery Electrolyte Market Competitive Landscape
Top-tier vendors anchor integrated cell manufacturer supply chains, while mid-tier blenders compete on localization speed and regulatory compliance. The vendor base stratifies around captive demand relationships with CATL, Samsung SDI, and BYD versus independent formulators serving fleet operators. Three archetypes dominate: integrated chemical conglomerates with precursor production, specialized electrolyte blenders with formulation IP, and cell manufacturer captive operations. Capacity expansion into domestic compounding facilities and strategic partnerships with nickel refiners represent the dominant competitive moves reshaping regional positioning.
Within the integrated chemical tier, Samsung SDI Co. Ltd. and Contemporary Amperex Technology Co. Ltd. exemplify formulators leveraging captive demand from electrode coating lines. LG Energy Solution Ltd. occupies a position bridging premium high-voltage specialization with volume scale. BYD Company Ltd. represents the scale-driven archetype extending captive supply into Indonesia's electric bus and passenger vehicle assembly base. These three companies anchor distinct competitive vectors: premium chemistry, integrated supply chain control, and volume manufacturing.
| Leading Market Players |
|---|
| Samsung SDI Co. Ltd. |
| Contemporary Amperex Technology Co. Ltd. (CATL) |
| LG Energy Solution Ltd. |
| GS Yuasa Corporation |
| Panasonic Holdings Corporation |
| BYD Company Ltd. |
| SK Innovation Co. Ltd. |
| SVOLT Energy Technology Co. Ltd. |
| LiRON LIB Power Pte Ltd |
| Others |
Pricing and Supply Chain Analysis
OEM manufacturers with captive electrode coating lines command pricing leverage through consolidated procurement volumes, compressing electrolyte formulators into contract-based long-term offtake structures that embed volume-commitment discounts and local content compliance premiums.
Pricing Analysis
Bundled precursor-plus-solvent procurement dominates Thai and Indonesian cell plants, while unbundled spot purchases persist for specialty additive packages. Three-tier pricing structure across high-voltage, automotive-standard, and two-wheeler economy levels reflects certification grade and volume scale differentiation. Cost compression in liquid electrolyte grades is intensifying because fluoroethylene carbonate feedstock volatility feeds through to blenders. Fleet operators exhibit highest price sensitivity due to roadmap-based contracting, while premium high-voltage specialists maintain pricing power through oxidation stability IP.
Supply Chain Analysis
Single-source vulnerability sits with lithium hexafluorophosphate precursor clusters in China's Hunan and Hubei provinces, exposing ASEAN blenders to crystallization capacity constraints and export licensing unpredictability. Electrolyte formulation draws from carbonate solvent purification in South Korea and Japan alongside domestic blending investments in Thailand's Eastern Economic Corridor and Indonesia's Morowali industrial zone. Tariff exposure on fluorochemical feedstocks threatens margin structures for non-integrated formulators. Distribution runs through hazardous material logistics networks anchored at Jurong Island chemical terminals with regional hub-and-spoke configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN electrolyte procurement functions as a regulatory compounder, with Indonesia's downstream mineral processing mandates and Thailand's BOI local content thresholds multiplying qualification complexity for suppliers seeking integrated project offtake.
For Market Incumbents: Cement captive supply relationships through backward integration into precursor salt crystallization within 200 kilometers of electrode coating lines, insulating against emerging Vietnamese blenders competing on localization speed. Defend high-voltage formulation IP through accelerated additive package patent filings before BIS-equivalent standards harmonization erodes technical differentiation. For New Entrants and Emerging Players: Thailand's BOI tax holiday extensions in Rayong and Chonburi provinces open a window for independent blenders to establish domestic compounding facilities ahead of tightened local content enforcement. Target Vietnam's uncontracted VinFast supply relationships as the most penetrable demand pool, entering through polymer electrolyte specialization for tropical climate two-wheeler applications with lower certification barriers. For Investors and Strategic Acquirers: Integrated nickel-to-cell project developers are the most active acquirer in this space, seeking captive electrolyte capabilities to satisfy domestic value-add thresholds. Mid-tier formulators with demonstrated R&D pipelines spanning solid-state architectures represent prime acquisition targets. Monitor Indonesia's nickel refining quota announcements as the critical inflection signal for precursor investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Blending Facility Establishment | Thailand's BOI incentives reward Rayong-Chonburi compounding investments with tax holiday eligibility. |
| Precursor Salt Crystallization Integration | Indonesia's downstream regulations mandate domestic lithium hexafluorophosphate production for nickel-to-cell project participation. |
| High-Voltage Additive Package Development | Nickel-rich cathode adoption in Thai passenger vehicle programs requires enhanced oxidation stability formulations. |
| Solid-State Electrolyte Pilot Production | Tropical humidity degradation challenges position first-movers with sulfide ceramic manufacturing expertise. |
| ESG-Certified Production Certification | EU Battery Regulation alignment creates qualification advantage for carbon footprint disclosure compliance. |
Research Methodology
Multiple input streams — electrolyte procurement managers at Thai and Indonesian cell plants, technical R&D directors at formulation houses, hazardous material logistics coordinators, and national standards body officials — were reconciled against customs trade records, BOI incentive disclosure filings, and nickel downstream processing permit databases. Bottom-up electrolyte volume estimates from individual production line configurations were cross-validated against top-down cell manufacturing capacity announcements across the analysis window.
Historical capacity utilization patterns were cross-referenced against expert panel assessments of solid-state manufacturing feasibility timelines. Segmentation modeling incorporated product chemistry tiers, vehicle application classes, end-user contracting behaviors, and technology roadmaps spanning lithium-ion through emerging ceramic architectures. CAGRs were derived from elasticity-adjusted demand projections anchored to national EV penetration targets and industrial park investment commitments.
Revisions become necessary when Indonesia's nickel refining quotas shift, Thailand's carbon border preparation accelerates, or solid-state electrolyte humidity degradation solutions achieve manufacturing scale. Forecasts reflect documented assumptions about local content threshold enforcement timing and precursor import licensing continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
USA Forklift Battery Market
Batteries
Battery Plate Market
Batteries
Lithium Marine Battery Market
Batteries
N-Type Battery Market
Batteries
Non-Rechargeable Battery Market
Batteries
Vanadium Redox Flow Batteries (VRFB) Market
Batteries
Forklift Battery Rental Market
Batteries
Molten Salt Battery Market
Batteries
India Lead-Acid Battery Market
Batteries
Secondary Battery Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Automotive Starting Battery Market
Batteries
Portable Battery Pack Market
Batteries
Battery Voltage Recorder Market
Batteries
Zinc-Manganese Oxide Batteries Market
Batteries
Myanmar Battery Market