
 Romania Rechargeable Battery Market | 2026-2036
Romania Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Romania Rechargeable Battery Market Insights
Aftermarket battery refurbishment revenue is tilting toward original equipment manufacturers as cell diagnostics and second-life grading capabilities become proprietary advantages. LG Energy Solution leverages its electrode formulation R&D to sustain premium positioning in Romanian electric vehicle supply chains. Samsung SDI anchors the consumer electronics segment through direct relationships with smartphone assemblers operating in Timișoara's industrial zone. Prime Batteries competes on localized assembly and shorter logistics loops for industrial backup power customers.
Romania rechargeable batteries are electrochemical storage devices designed for multiple charge-discharge cycles, typically employing lithium cobalt oxide, nickel manganese cobalt, or lead-dioxide chemistries with nominal voltages ranging from 1.2V to 3.7V per cell depending on chemistry, and they serve to decouple energy generation from consumption across mobility, portable electronics, and grid stabilization applications. Lithium-ion occupies the dominant margin pool as energy density requirements intensify across automotive and renewable energy end users. Lead-acid retains structural relevance in UPS systems and industrial starter applications where cost-per-kilowatt-hour and cold-crank performance outweigh weight considerations. Electric vehicle application growth is concentrating procurement leverage among original equipment manufacturers seeking long-term offtake agreements with cell producers.
Romania's national regulatory framework operates under EU REACH compliance for chemical substance registration, CE marking for product safety conformity, and the EU Battery Regulation establishing recycled content mandates and due diligence requirements for raw material sourcing. BIS-equivalent standards through the country's national standardization body govern domestic product certification timelines and testing protocols for grid-connected storage installations. Stakeholders must monitor how forthcoming EU Battery Regulation delegated acts on carbon footprint declarations reshape supplier qualification criteria and procurement specifications for Romanian distribution channels.
Market Dynamics
The EU Battery Regulation's recycled content mandates are forcing Romanian distributors to requalify their supplier base ahead of 2027 compliance deadlines, compressing procurement timelines and elevating cell traceability to a competitive differentiator.
Growth Catalysts
- EU Green Deal alignment:Romania's fossil-dependent mobility phase-out accelerates lithium-ion procurement for Bucharest's expanding electric bus fleet. Municipal operators now specify EU-manufactured cells to satisfy carbon footprint disclosure requirements.
- Industrial UPS demand:Ploiești's manufacturing corridor drives concentrated lead-acid and nickel-metal hydride consumption for backup power systems. Data center operators prioritize localized assembly to minimize logistics disruption.
- F-Gas Regulation phase-out:Cold chain logistics operators replace diesel auxiliary units with battery-electric refrigeration, creating new demand nodes for medium-voltage lithium packs in Timișoara's distribution hubs.
Market Restraints
- Cobalt supply concentration:Romanian cell assemblers face input cost volatility from DRC-dominant cobalt mining, with limited near-term substitution pathways for high-nickel cathode formulations.
- CE marking complexity:Extended product safety conformity timelines delay grid-connected storage installations, particularly for residential solar-plus-storage configurations requiring BIS-equivalent national certification.
- Lead-acid substitution ceiling:Industrial starter applications in automotive manufacturing resist lithium migration due to cold-crank performance requirements below minus twenty degrees Celsius.
Strategic Opportunities
- Second-life battery grading:Bucharest's emerging electric vehicle aftermarket creates white space for proprietary cell diagnostics capabilities, with original equipment manufacturers capturing refurbishment revenue through controlled distribution.
- Cluj-Napoca charging infrastructure:Underpenetrated fast-charging corridors along Transylvania's highway network present deployment opportunities for integrated battery storage systems managing grid peak demand.
- EU Battery Regulation delegated acts:Forthcoming carbon footprint declaration rules will reshape supplier qualification criteria, rewarding early movers with established due diligence documentation for Romanian distribution channels.
Industry Challenges
- Electrochemical engineering talent scarcity:Domestic universities produce insufficient battery management system specialists, forcing assemblers to recruit from Poland's established lithium-ion manufacturing clusters.
- REACH compliance documentation:Chemical substance registration requirements for imported electrolyte formulations extend procurement lead times, particularly for sodium-ion alternatives seeking market entry.
- Legacy grid integration:Distribution network operators in Moldova and Dobrogea regions lack standardized interconnection protocols for behind-the-meter storage, delaying commercial and industrial project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania Rechargeable Battery Market |
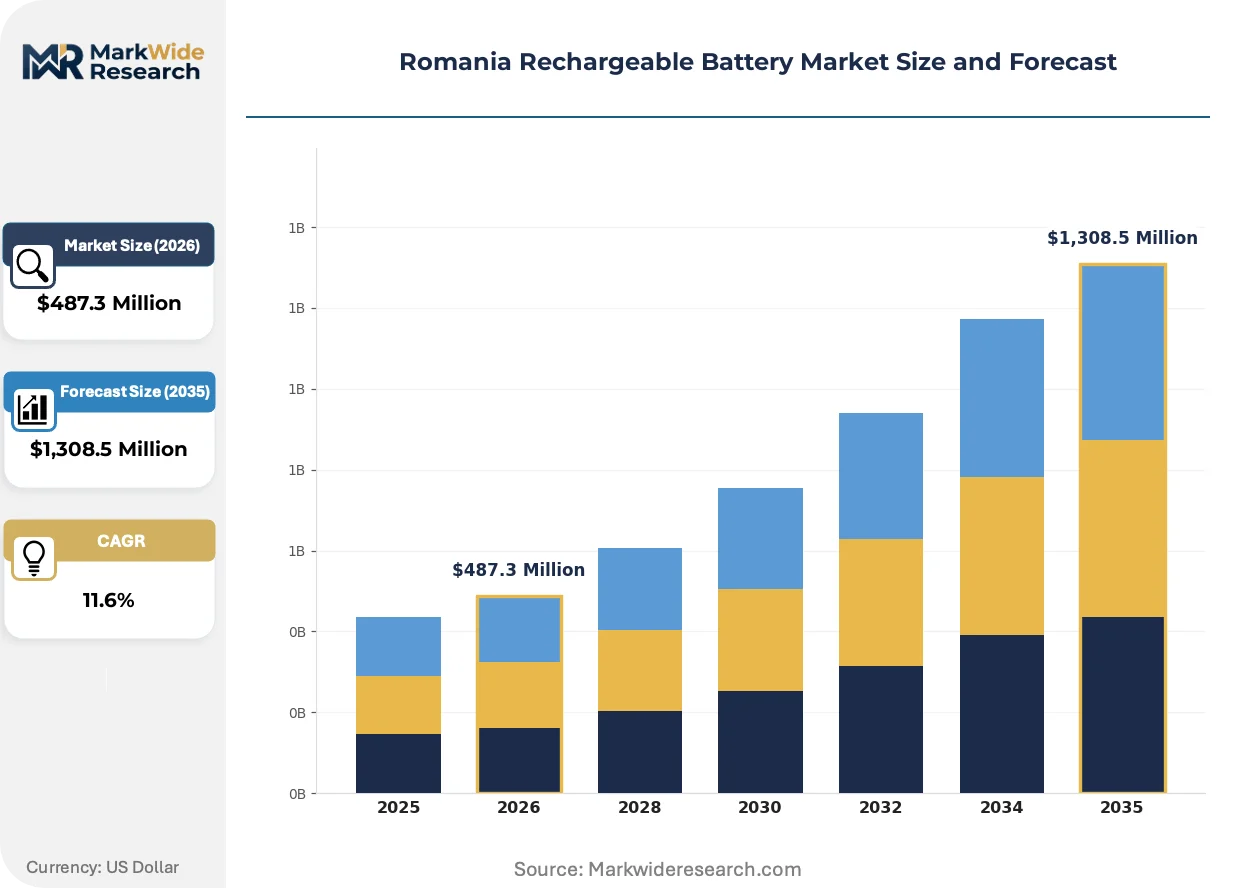
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Metal Hydride, Lead-Acid, Lithium Polymer End User: Consumer Electronics, Automotive, Industrial, Renewable Energy Application: Smartphones, Electric Vehicles, Power Tools, UPS Systems Distribution Channel: Online Retail, Wholesale, Direct Sales, Third-Party Retail |
| Companies Covered | LG Energy Solution, CATL, Samsung SDI, Panasonic, Varta, Exide Technologies, Johnson Controls, Prime Batteries, Electrica, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania Rechargeable Battery Market Trends and Innovations
Solid-state electrolyte research is compressing conventional liquid-cell design cycles, while Romanian industrial buyers increasingly specify performance guarantees tied to residual capacity thresholds rather than calendar life alone.
Sodium-ion cathode chemistry is hybridizing energy storage procurement specifications across Romania's renewable integration projects. Grid-scale developers in Dobrogea's wind corridor now evaluate sodium-ion alongside lithium iron phosphate for four-hour duration applications. The technology's elimination of cobalt and nickel is compressing due diligence timelines for EU Battery Regulation compliance.
REACH delegated acts on recycled content verification are restructuring supplier documentation requirements for Romanian importers. Cell manufacturers must now provide batch-level material provenance records to satisfy ECHA audit protocols. Industrial buyers in Ploiești's manufacturing zone are responding by consolidating procurement around vertically integrated European producers with captive recycling capabilities.
Fleet operators across Bucharest and Cluj-Napoca are compressing battery replacement cycles from eight years to five years, driven by residual value guarantees from leasing providers. This behavioral shift is displacing outright purchase models in municipal electric bus procurement. The trend concentrates most visibly in transport authorities managing over fifty vehicles, where scale justifies performance-based service contracts.
Romania Rechargeable Battery Market Segmentation
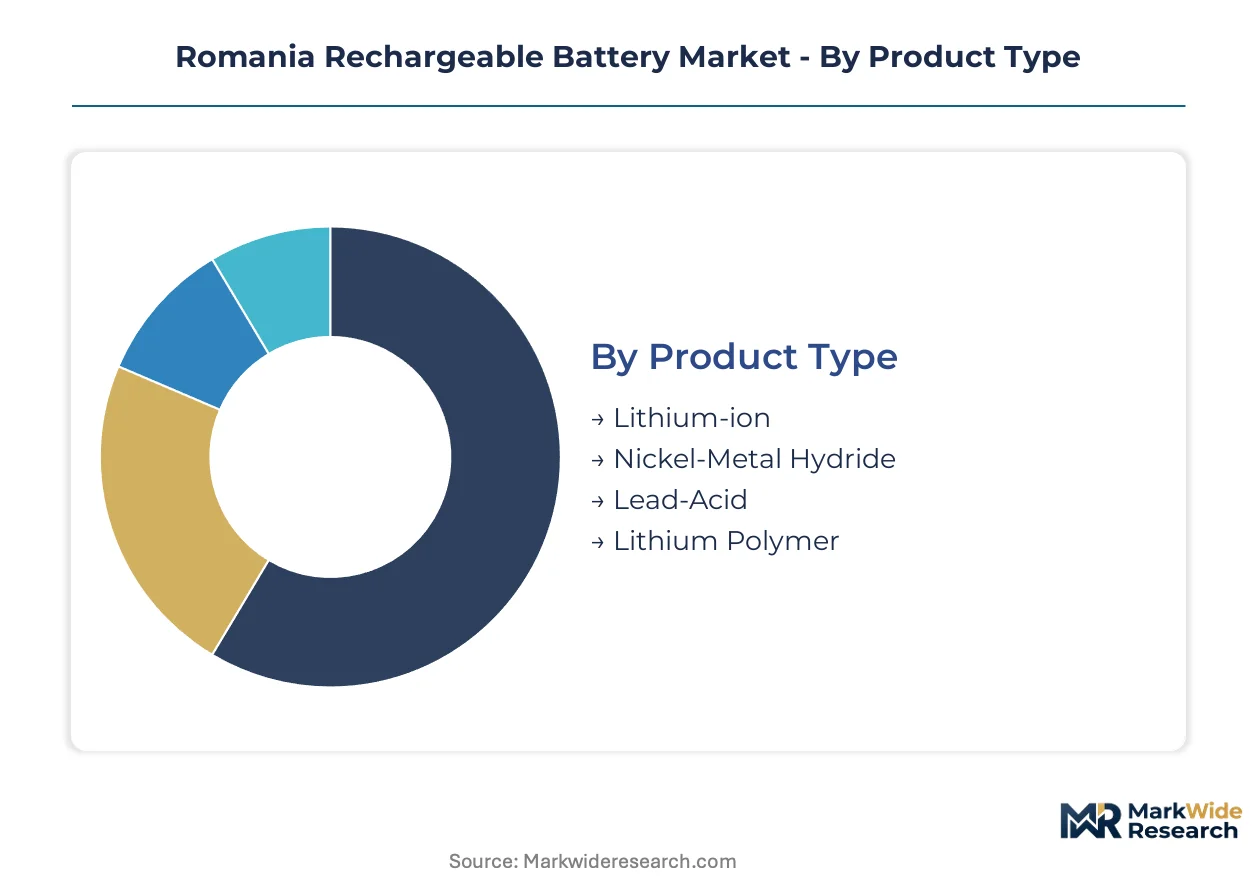
Romania's rechargeable battery market fragments across four distinct dimensions. Each segmentation layer reveals divergent margin structures and procurement behaviors. Understanding these splits is essential for positioning against EU Battery Regulation compliance deadlines.
Product Type:
Cost tier determines supplier qualification intensity and carbon footprint disclosure burden across Romanian distribution channels.
- Lithium-ion:Cells employ layered oxide cathodes with graphite anodes, achieving 250-300 Wh/kg energy density. Bucharest's electric bus operators now mandate EU-manufactured packs to satisfy emerging carbon declaration requirements. Cold-crank limitations below minus twenty degrees Celsius constrain penetration in automotive starter applications.
- Lead-Acid:Flooded and VRLA configurations dominate Ploiești's industrial UPS corridor where cost-per-kilowatt-hour outweighs weight considerations. Data center operators prioritize localized assembly to minimize logistics disruption from regional supply shocks.
- Nickel-Metal Hydride:Rare-earth hydride anodes deliver stable voltage curves for power tool applications requiring sustained discharge rates. Timișoara's manufacturing zone sustains modest demand from cordless equipment assemblers.
- Lithium Polymer:Pouch-cell architectures enable form-factor flexibility for wearable electronics and drone applications. Consumer electronics distributors in Cluj-Napoca source primarily from Asian contract manufacturers.
Lithium-ion commands the established base. The steepest expansion runs through lead-acid substitution in grid-scale buffering applications.
End User:
Application maturity separates price-sensitive commodity procurement from performance-guaranteed service contracts.
- Automotive:Original equipment manufacturers concentrate procurement leverage through long-term offtake agreements with cell producers. Bucharest's municipal fleet operators specify residual capacity thresholds rather than calendar life alone.
- Industrial:Manufacturing corridors in Ploiești and Timișoara drive concentrated demand for backup power systems. UPS deployments prioritize localized assembly to satisfy just-in-time inventory requirements.
- Consumer Electronics:Smartphone assemblers operating in Timișoara's industrial zone source through direct relationships with tier-one cell producers. Margins compress toward logistics efficiency and customs clearance speed.
- Renewable Energy:Grid-scale developers in Dobrogea's wind corridor evaluate sodium-ion alongside lithium iron phosphate for four-hour duration applications. Interconnection protocol gaps in Moldova and Dobrogea regions delay project commissioning.
Industrial applications anchor current procurement volumes. Automotive electrification is climbing the fastest as municipal fleet specifications tighten.
Application:
Volume concentration varies sharply between consumer replacement cycles and industrial capital expenditure timelines.
- Electric Vehicles:Battery-electric buses and commercial vans dominate Bucharest and Cluj-Napoca procurement. Fleet operators compress replacement cycles from eight years to five years through performance-based leasing structures.
- UPS Systems:Data centers and manufacturing facilities in Ploiești specify valve-regulated lead-acid for short-duration backup. Lithium-ion penetration remains limited by upfront capital cost differentials.
- Smartphones:Pouch-cell lithium polymer supplies Timișoara's electronics assembly cluster. Specifications prioritize energy density over cycle life given eighteen-month consumer replacement patterns.
- Power Tools:Cordless equipment manufacturers source nickel-metal hydride and lithium-ion cylindrical cells. Professional-grade segments demand rapid-charge compatibility.
UPS systems represent the installed base anchor. Electric vehicle integration is gaining share fastest as charging infrastructure scales.
Distribution Channel:
Customer type and order scale determine margin capture and traceability documentation burden.
- Direct Sales:Original equipment manufacturers negotiate multi-year offtake agreements with cell producers for automotive and industrial volumes. Contracts incorporate EU Battery Regulation recycled content mandates.
- Wholesale:Regional distributors serve Ploiești's manufacturing corridor with consolidated lead-acid and nickel-metal hydride inventories. REACH compliance documentation extends procurement lead times for imported electrolyte formulations.
- Online Retail:Consumer electronics replacement batteries move through marketplace platforms with minimal technical support. CE marking complexity delays grid-connected storage listings.
- Third-Party Retail:Electronics specialty stores in Bucharest and Cluj-Napoca stock smartphone and power tool batteries. Staff technical knowledge varies widely across retail networks.
Direct sales capture the premium tier. Wholesale channels are expanding most quickly as industrial procurement consolidates around fewer qualified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Romania's rechargeable battery consumption tilts toward industrial backup and municipal electrification, diverging from Western European patterns where passenger EVs dominate procurement volumes. The country's manufacturing corridors and public transit fleets absorb cell output differently than household-driven markets.
Bucharest-Ilfov
The capital region concentrates Romania's electric bus fleet expansion, with municipal operators procuring lithium-ion packs for over fifty-vehicle deployments. EU Green Deal alignment drives specifications toward EU-manufactured cells with carbon footprint disclosures. Charging infrastructure scaling along Bucharest's ring road creates demand nodes for grid-connected storage systems managing peak demand.
Cluj-Napoca
Transylvania's largest metro anchors commercial van electrification and underpenetrated fast-charging corridor development. The F-Gas Regulation phase-out accelerates battery-electric refrigeration adoption among cold chain logistics operators. Highway network gaps present deployment opportunities for integrated storage systems buffering grid interconnection.
Ploiești
The Prahova Valley manufacturing corridor sustains concentrated lead-acid and nickel-metal hydride demand for industrial UPS systems. Data center operators prioritize localized assembly to minimize logistics disruption from regional supply shocks. Valve-regulated lead-acid configurations dominate short-duration backup specifications despite lithium-ion cost compression.
Timișoara
The Banat industrial zone hosts smartphone assemblers sourcing pouch-cell lithium polymer through direct tier-one producer relationships. Cordless equipment manufacturers in the region consume cylindrical nickel-metal hydride and lithium-ion cells for professional-grade power tools. Consumer electronics margins compress toward customs clearance speed and logistics efficiency.
Dobrogea
The Black Sea wind corridor drives grid-scale storage evaluation, with developers comparing sodium-ion against lithium iron phosphate for four-hour duration applications. Legacy distribution network infrastructure lacks standardized interconnection protocols for behind-the-meter installations. EU Battery Regulation recycled content mandates restructure procurement qualification timelines for regional developers.
Romania Rechargeable Battery Market Competitive Landscape
Capability concentration sits with electrode formulation specialists; scale advantage sits with integrated cell producers commanding multi-year automotive offtake agreements. The vendor base stratifies across three tiers: premium technology licensors, mid-cap regional assemblers, and commodity traders serving replacement markets. Strategic moves center on backward integration into cathode active material production and captive recycling capabilities to satisfy REACH compliance documentation requirements.
Within the premium technology tier, LG Energy Solution and Samsung SDI occupy positions defined by proprietary R&D assets and direct OEM relationships. CATL anchors the scale-driven end with manufacturing footprints serving European distribution channels. Prime Batteries exemplifies the regional assembler archetype competing on localized logistics loops and shorter procurement timelines for industrial backup power customers in Romania's manufacturing corridors.
| Leading Market Players |
|---|
| LG Energy Solution |
| CATL |
| Samsung SDI |
| Panasonic |
| Varta |
| Exide Technologies |
| Johnson Controls |
| Prime Batteries |
| Electrica |
| Others |
Pricing and Supply Chain Analysis
Cobalt supply concentration from the Democratic Republic of Congo compresses both margin structures and procurement timelines across Romanian cell assemblers, forcing a bifurcation between long-term offtake contracts that secure input stability and spot-market exposure that amplifies price volatility for smaller distributors.
Pricing Analysis
Long-term offtake agreements dominate procurement between original equipment manufacturers and tier-one cell producers, insulating automotive volumes from commodity swings while spot-market transactions govern replacement battery channels. Price differentiation rests on carbon footprint certification tiers under the EU Battery Regulation and volume scale, with EU-manufactured cells commanding premiums over Asian imports. Cost compression in the consumer electronics tier intensifies as pouch-cell specifications standardize around energy density benchmarks. Industrial UPS buyers exhibit lowest price sensitivity due to downtime cost exposure, whereas smartphone assemblers prioritize logistics efficiency over unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for Romanian distributors navigating electrode active material procurement. Manufacturing concentration centers on China, South Korea, and Japan for cathode precursors and separator membranes, with Romanian assemblers drawing from Polish and Hungarian conversion facilities for final pack integration. Raw material dependencies tether the market to Chilean lithium brine, Indonesian nickel matte, and DRC cobalt hydroxide. Distribution runs through direct sales channels for automotive volumes and consolidated wholesale networks serving Ploiești's industrial corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery lifecycle management services are expanding faster than hardware sales as Bucharest's electric bus operators shift from outright purchase to performance-based leasing structures with residual value guarantees.
For Market Incumbents: Entrench position through backward integration into cathode active material production and captive recycling capabilities that satisfy REACH compliance documentation requirements. Secure multi-year offtake agreements with municipal fleet operators before EU Battery Regulation carbon footprint declarations reshape supplier qualification criteria. Counter sodium-ion substitution threats by emphasizing energy density advantages in cold-crank applications below minus twenty degrees Celsius. For New Entrants and Emerging Players: Establish a beachhead in second-life battery grading services for Bucharest's emerging electric vehicle aftermarket, where proprietary cell diagnostics capabilities remain undersupplied. Target Cluj-Napoca's underpenetrated fast-charging corridor for integrated battery storage systems managing grid peak demand. Pursue project-based contracting with data center operators in Ploiești seeking localized assembly to minimize logistics disruption. For Investors and Strategic Acquirers: Regional assemblers with established due diligence documentation and vertical integration into recycling present the most defensible acquisition profile across the analysis window. Mid-cap specialists commanding captive cathode material supply and EU Battery Regulation compliance infrastructure offer the strongest long-term viability framing. Monitor delegated act publication timelines on carbon footprint declarations as the critical inflection signal for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Active Material | Captive supply of nickel manganese cobalt precursors insulates Romanian assemblers from DRC cobalt volatility. |
| EU Battery Regulation Compliance Investment | Early carbon footprint documentation secures preferred supplier status with Bucharest municipal fleet operators. |
| Second-Life Battery Grading Capability | Proprietary diagnostics capture refurbishment revenue from electric bus aftermarket displacement cycles. |
| Localized Assembly Footprint Expansion | Ploiești manufacturing corridor proximity minimizes logistics disruption for industrial UPS customers. |
| Sodium-Ion Technology Evaluation Partnership | Dobrogea wind corridor developers assess four-hour duration applications against lithium iron phosphate benchmarks. |
Research Methodology
Desk research of EU regulatory filings, customs trade databases, and cell producer sustainability disclosures preceded structured interviews with procurement directors at Romanian automotive OEMs, battery management system engineers, industrial UPS facility managers, and renewable energy project developers. Primary fieldwork combined with secondary validation against ECHA REACH registration data, CE marking certification records, and national grid operator interconnection protocols. Bottom-up volume estimates from segment-level procurement patterns were triangulated against top-down market sizing derived from EU Green Deal implementation timelines.
Assumptions around EU Battery Regulation delegated act publication schedules, cobalt substitution pathway feasibility, and charging infrastructure deployment rates were held fixed across base-case scenarios while stress-tested against accelerated sodium-ion adoption and extended lead-acid substitution ceilings. The analytical framework modeled product type, end user, application, and distribution channel dimensions across the projection horizon. CAGRs were derived from logistic growth curve fitting to historical procurement volumes and policy-mandated fleet electrification targets. Forecast inputs incorporated electric bus fleet expansion schedules and industrial UPS replacement cycles.
Stress conditions across cobalt price volatility bands, REACH compliance timeline extensions, and grid interconnection protocol standardization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about EU regulatory enforcement consistency and raw material supply chain continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Europe Lead-Acid Battery Market
Batteries
Automotive AGM Battery Market
Batteries
North America Lead Acid Battery Market
Batteries
Micro Mobility Battery PACK Market
Batteries
Zinc-Ion Battery Cells Market
Batteries
Battery Swapping Market
Batteries
Middle-East Battery Market
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
Battery Coolant-Antifreeze Refractometer Market
Batteries
FORTELION Battery Module Market
Batteries
Second-Life Automotive Battery Module Systems Market
Batteries
Middle East and Africa Battery Market
Batteries
Vietnam Battery Market
Batteries
Industrial Backup Battery Market
Batteries
Portable Battery Market
Batteries
Global Primary Cells Market