
 Smart Diagnostic Battery Charger Market | 2026-2036
Smart Diagnostic Battery Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Diagnostic Battery Charger Market Insights
China is tilting toward domestic production of high-frequency charging systems for lithium-ion and lead-acid battery diagnostics. Schneider Electric leverages its European industrial channel network to sustain service contracts across factory automation sites. Robert Bosch anchors its position through backward integration into power semiconductor modules that govern pulse repair algorithms. CTEK Holding specializes in marine and outdoor applications where salt corrosion resistance commands premium positioning.
A smart diagnostic battery charger integrates microprocessor-controlled circuitry with voltage sensing, temperature compensation, and automated fault detection to restore battery capacity while preventing overcharge damage. These systems typically operate across input ranges of 110-240V AC and deliver multi-stage charging profiles at 6V, 12V, or 24V outputs for lead-acid, AGM, gel, and lithium-ion chemistries. Stationary chargers occupy the largest revenue pool in industrial and commercial installations where uptime requirements justify capital expenditure. Portable chargers represent the fastest-expanding category as field service technicians and recreational vehicle owners prioritize mobility. Microprocessor-controlled technology leads unit shipments due to its programmable adaptability across battery chemistries and operating conditions.
The EU Battery Regulation and CE marking requirements enforce traceable state-of-health documentation for industrial batteries, directly stimulating replacement demand for diagnostic-capable chargers. The EPA's Energy Star specifications and China's GB standards for electromagnetic compatibility constrain product design while creating compliance barriers for unqualified entrants. Stakeholders must monitor how solid-state battery commercialization alters charging protocols and whether pulse repair technology retains relevance as battery architectures evolve.
Market Dynamics
Automotive fleet electrification is forcing a wholesale replacement of conventional charging infrastructure with microprocessor-controlled diagnostic systems capable of managing heterogeneous battery chemistries across mixed fleets.
Growth Catalysts
- EU Battery Regulation:State-of-health documentation mandates for industrial batteries sold in member states compel facility operators to upgrade to diagnostic-capable charging systems.
- EV infrastructure buildouts:Germany, China, and the United States are deploying high-frequency charging networks that integrate battery health monitoring as a standard feature.
- Pulse repair algorithms:Semiconductor-controlled pulse technology extends lead-acid battery service life in heavy-duty applications, reducing total cost of ownership for logistics operators.
Market Restraints
- Power semiconductor supply concentration:IGBT and MOSFET sourcing depends heavily on East Asian foundry capacity, creating input cost volatility for charger manufacturers.
- GB standards compliance:China's electromagnetic compatibility certification requirements impose design constraints and testing timelines that delay market entry for non-domestic suppliers.
- Solid-state battery substitution:Next-generation battery architectures with fundamentally different charging protocols threaten to obsolete pulse repair and multi-stage charging technologies.
Strategic Opportunities
- Marine and outdoor segments:Salt corrosion-resistant diagnostic chargers command premium pricing in coastal and offshore applications where equipment reliability is safety-critical.
- Field service mobility:Portable diagnostic units are penetrating recreational vehicle and remote maintenance markets previously served by basic trickle chargers.
- CE marking convergence:The EU's traceability requirements for industrial batteries create a regulatory tailwind for integrated charger-diagnostic systems that automate documentation workflows.
Industry Challenges
- Firmware engineering talent:The shortage of embedded systems developers with battery chemistry expertise constrains product development cycles for adaptive charging algorithms.
- Multi-chemistry certification:Validating safe operation across lead-acid, AGM, gel, and lithium-ion chemistries extends testing timelines and regulatory filing costs.
- Legacy fleet integration:Retrofitting diagnostic chargers into existing material handling and ground support equipment requires custom harnessing and voltage compatibility solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Diagnostic Battery Charger Market |
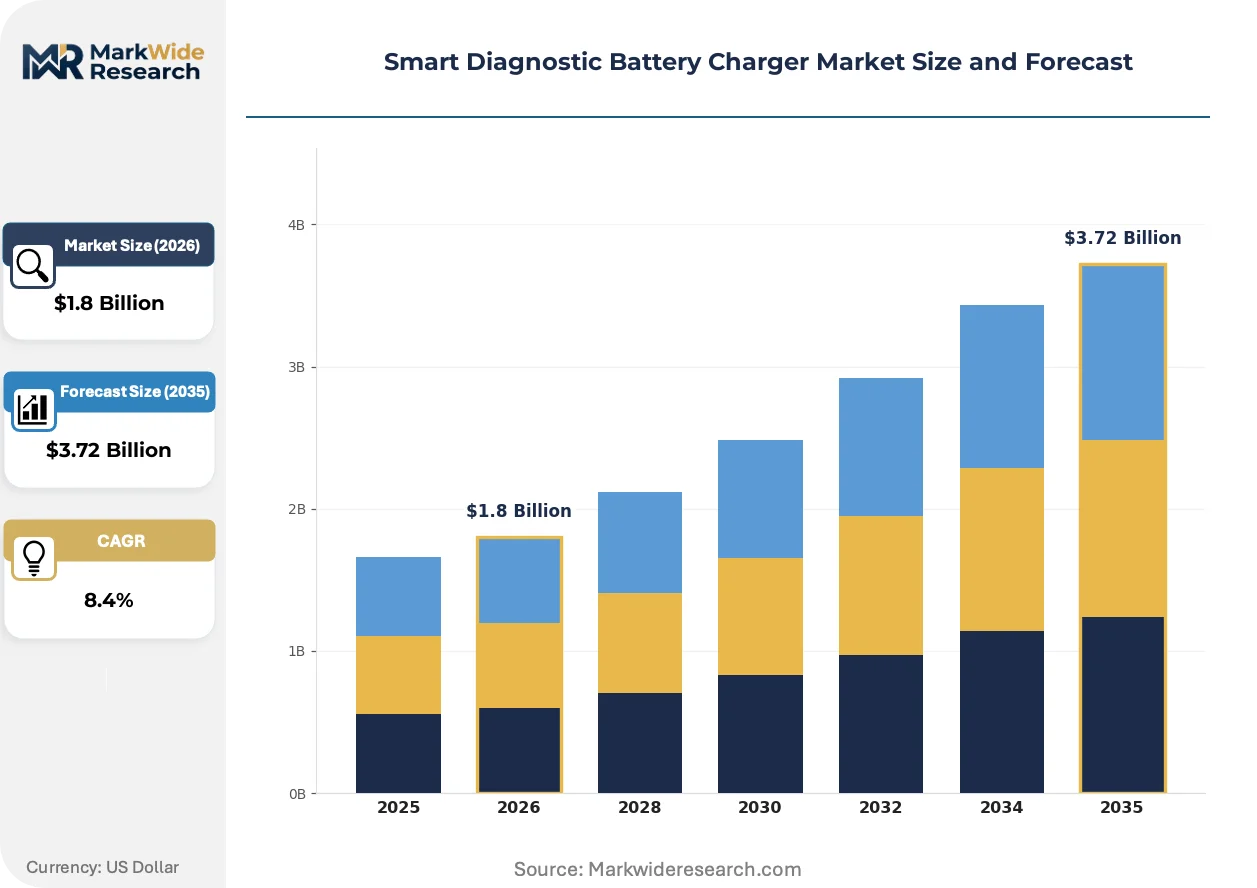
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Chargers, Stationary Chargers, Solar Chargers, Multi-Step Chargers Technology: Microprocessor Controlled, Smart Technology, Automatic Voltage Regulation, Pulse Repair Technology End User: Automotive, Marine, Aerospace, Industrial Equipment Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Panasonic Corporation, Eaton Corporation, Schneider Electric, BYD Company Ltd., Qualcomm Technologies, Delta Electronics, Samsung Electronics, CTEK Holding, Robert Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Diagnostic Battery Charger Market Trends and Innovations
Adaptive charging intelligence is displacing fixed-voltage charging across industrial and commercial installations, with software-defined battery management emerging as the primary axis of product differentiation.
Microprocessor-controlled circuitry with real-time impedance spectroscopy is digitizing battery state estimation, replacing analog voltage threshold detection. Material handling fleet operators in Germany are deploying these systems at scale to optimize charging windows around shift patterns. The technology is digitizing maintenance scheduling by predicting capacity fade before it triggers equipment downtime.
REACH substance restrictions and RoHS compliance deadlines are forcing redesigns of power electronics assemblies to eliminate restricted solder materials and capacitor chemistries. Industrial charger manufacturers must requalify thermal management systems under revised safety margins. The stationary charger segment faces the most acute retooling pressure as these units carry the longest certification legacy.
Service contract unbundling is fragmenting procurement decisions between capital equipment buyers and aftermarket service providers. Factory automation sites in China are separating charger hardware acquisition from predictive maintenance subscriptions, creating channel conflict between OEM direct sales and distributor service networks. This pattern is most visible in automotive tier-one supplier facilities where total cost of ownership analysis now dominates vendor selection.
Smart Diagnostic Battery Charger Market Segmentation
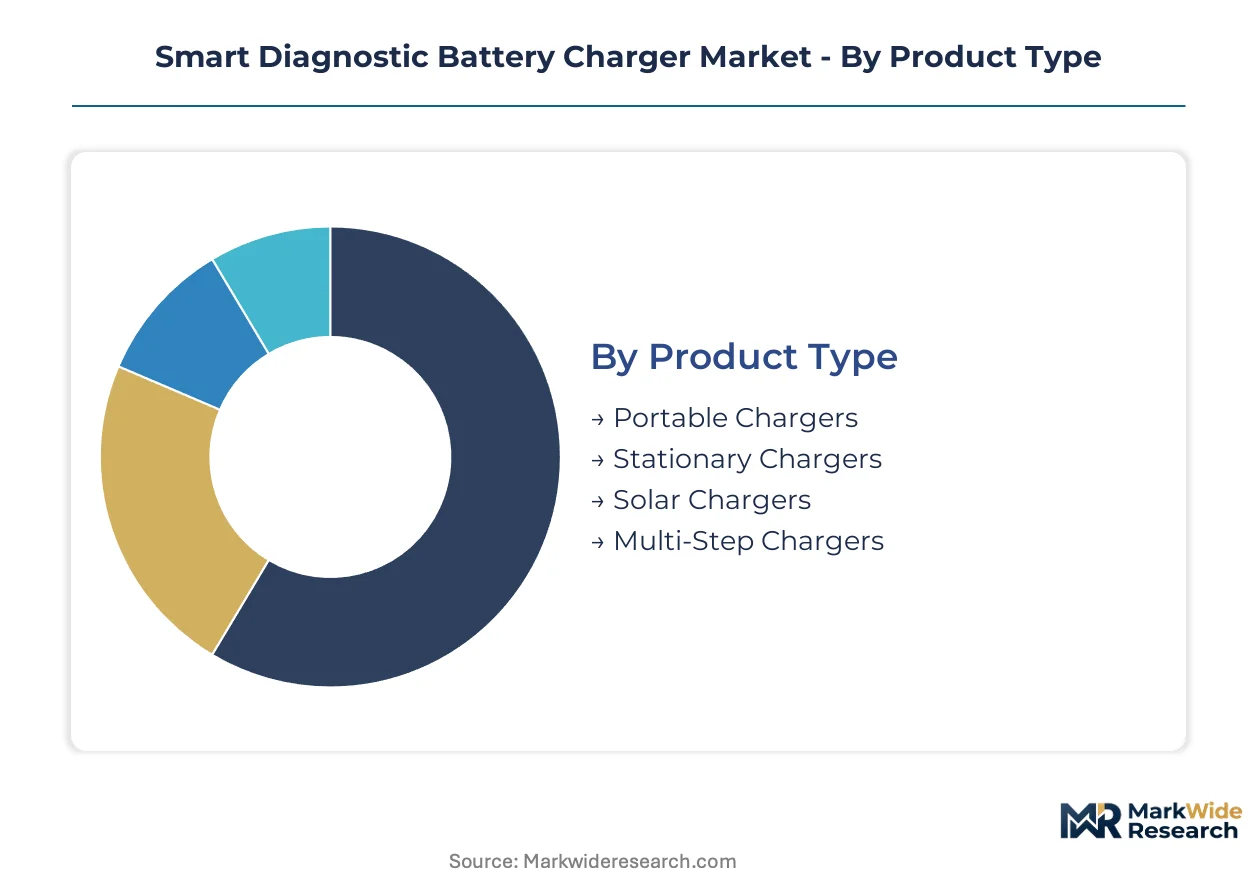
Segmentation in the smart diagnostic battery charger market determines service contract structures and replacement cycle timing. Procurement patterns diverge sharply between capital-intensive stationary installations and mobility-dependent portable units.
Product Type:
After-sales-service intensity varies dramatically across product types, with stationary systems demanding multi-year maintenance contracts while portable units rely on warranty replacement programs.
- Stationary Chargers:Fixed-installation units with integrated cooling systems and ethernet connectivity for fleet management software integration. German automotive manufacturers deploy these at scale for production line battery conditioning, where predictive maintenance subscriptions now exceed hardware margins. CE marking and EU Battery Regulation traceability requirements favor these systems for industrial compliance automation.
- Portable Chargers:Compact units with IP-rated enclosures and vehicle-mounted configurations. Field service technicians in the United States and recreational vehicle owners in coastal China drive procurement, prioritizing lithium-ion compatibility and rapid charging profiles over diagnostic depth.
- Solar Chargers:Photovoltaic-input systems with maximum power point tracking for off-grid applications.
- Multi-Step Chargers:Programmable units delivering bulk, absorption, and float stages for lead-acid longevity.
By volume, Portable Chargers leads. By growth pace, Stationary Chargers is ahead.
Technology:
Cost tier stratification separates premium adaptive systems from basic voltage-regulated alternatives, with firmware licensing fees creating recurring revenue differentiation.
- Microprocessor Controlled:Software-defined charging profiles with real-time impedance spectroscopy and temperature compensation algorithms. These systems dominate German material handling fleet retrofits, where shift-pattern optimization and capacity fade prediction justify capital expenditure. The EU Battery Regulation's state-of-health documentation mandates directly stimulate replacement demand for these units.
- Pulse Repair Technology:Semiconductor-controlled desulfation circuits that extend lead-acid service life through high-frequency pulse sequences. Logistics operators in heavy-duty applications favor these for total cost of ownership reduction, though solid-state battery commercialization threatens protocol relevance.
- Smart Technology:Bluetooth-enabled units with mobile application diagnostics and over-the-air firmware updates.
- Automatic Voltage Regulation:Analog-digital hybrid systems maintaining constant output despite input fluctuation.
Microprocessor Controlled commands the revenue pool. Pulse Repair Technology faces substitution pressure from next-generation battery architectures.
End User:
Application-specific certification requirements fragment vendor qualification, with marine salt corrosion standards and aerospace DO-160G testing creating distinct competitive moats.
- Automotive:Fleet electrification and mixed-chemistry management requirements. OEM service centers and independent repair shops in Germany and the United States are replacing conventional infrastructure with diagnostic-capable systems. The EPA's Energy Star specifications constrain standby power consumption while stimulating efficiency-driven procurement.
- Marine:Salt corrosion-resistant enclosures and vibration-hardened electronics for coastal and offshore deployment. CTEK Holding and specialized Nordic manufacturers command premium positioning where equipment reliability is safety-critical.
- Industrial Equipment:Factory automation and material handling integration with SCADA connectivity.
- Aerospace:Ground support equipment with DO-160G electromagnetic compatibility certification.
Automotive generates the largest order volume. Marine sustains the highest average selling prices.
Distribution Channel:
Customer type bifurcation separates enterprise procurement through direct sales from consumer and small commercial acquisition via retail channels.
- Direct Sales:Long-term service contracts and predictive maintenance subscriptions bundled with hardware. Factory automation sites in China are unbundling these arrangements, creating channel conflict between OEM direct sales and distributor service networks.
- Distributors:Regional inventory stocking with technical support capabilities for installer networks.
- Online Retail:E-commerce platforms with specification comparison tools and consumer review aggregation.
- Offline Retail:Automotive parts chains and marine supply stores with counter service and immediate fulfillment.
Direct Sales captures the enterprise value pool. Online Retail is climbing the fastest in unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian semiconductor foundries supply the power electronics that govern pulse repair algorithms and microprocessor-controlled charging profiles. German automotive manufacturers and Chinese industrial automation sites absorb the highest volumes of diagnostic-capable systems. Regulatory mandates in the European Union and electromagnetic compatibility standards in China reshape procurement specifications across these demand centers.
China
Industrial automation investments in the Yangtze River Delta and Pearl River Delta drive procurement of high-frequency charging systems for lithium-ion and lead-acid battery diagnostics. GB standards for electromagnetic compatibility constrain product design while creating compliance barriers for non-domestic suppliers. Factory automation sites in Shenzhen and Shanghai are unbundling hardware acquisition from predictive maintenance subscriptions.
Germany
Automotive fleet electrification and material handling fleet retrofits force replacement of conventional charging infrastructure with microprocessor-controlled diagnostic systems. The EU Battery Regulation mandates state-of-health monitoring for industrial batteries sold in member states. Production line battery conditioning operations in Stuttgart and Wolfsburg deploy stationary chargers with predictive maintenance subscriptions exceeding hardware margins.
United States
EPA Energy Star specifications constrain standby power consumption while stimulating efficiency-driven procurement from OEM service centers and independent repair shops. EV infrastructure buildouts integrate battery health monitoring as a standard feature. Field service technicians in Texas and California drive portable diagnostic unit penetration into recreational vehicle and remote maintenance markets.
Japan
METI industrial policy supports factory automation and battery management system integration across automotive and electronics manufacturing clusters. JIS standards govern electromagnetic compatibility certification for industrial equipment. Precision manufacturing sites in Nagoya and Osaka prioritize adaptive charging intelligence with real-time impedance spectroscopy for digitized maintenance scheduling.
South Korea
Heavy investment in EV battery manufacturing and semiconductor fabrication creates downstream demand for diagnostic charging systems with multi-chemistry certification. MFDS-equivalent industrial safety frameworks and KTL certification requirements shape product qualification timelines. Battery conditioning facilities in Gyeonggi Province and Ulsan deploy high-frequency charging networks for heterogeneous fleet management.
Smart Diagnostic Battery Charger Market Competitive Landscape
Industrial conglomerates and specialized charging system manufacturers split the market into consolidated enterprise segments and fragmented specialty niches. Tier-one automotive suppliers and factory automation OEMs favor direct procurement relationships with full-solution providers capable of bundling predictive maintenance subscriptions. Three strategic archetypes dominate: diversified industrial electronics conglomerates with captive semiconductor supply, pure-play battery management specialists with marine and outdoor positioning, and Asian electronics manufacturers leveraging component cost advantages. Competitive intensity centers on backward integration into power semiconductor modules and geographic expansion through regional distributor service networks.
Within the diversified industrial tier, Schneider Electric and Robert Bosch exemplify full-solution positioning through European industrial channel networks and in-house power electronics capabilities. CTEK Holding occupies a specialist position where salt corrosion resistance and marine application expertise command premium pricing. Panasonic Corporation and Samsung Electronics represent the Asian electronics manufacturing archetype with scale advantages in component sourcing. These five entities collectively illustrate the strategic segmentation between integrated conglomerates, application specialists, and volume manufacturers that defines competitive dynamics in diagnostic charging systems.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Eaton Corporation |
| Schneider Electric |
| BYD Company Ltd. |
| Qualcomm Technologies |
| Delta Electronics |
| Samsung Electronics |
| CTEK Holding |
| Robert Bosch |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor shapes cost dynamics across the smart diagnostic battery charger market, with container rate volatility feeding directly into landed cost differentiation between East Asian volume manufacturers and European full-solution providers. Supply concentration in Taiwan and South Korean foundry capacity concentrates pricing power among semiconductor-integrated OEMs, while GB standards compliance costs create tiered entry barriers that stratify procurement options for industrial buyers.
Pricing Analysis
EU Battery Regulation dictates the pricing tier structure across industrial procurement, with CE marking and state-of-health documentation mandates separating premium subscription-bundled systems from basic hardware-only alternatives. Price differentiation rests on certification grade and predictive maintenance bundling, with factory automation sites in Germany least sensitive to upfront capital expenditure and Southeast Asian commercial buyers most responsive to per-unit transactional pricing. Cost compression in the portable charger segment is intensifying because lithium-ion compatibility requirements force firmware licensing fees that erode margin at volume scale.
Supply Chain Analysis
TSMC, Samsung Foundry, and SMIC anchor contract manufacturing concentration for the power semiconductor modules governing pulse repair algorithms and microprocessor-controlled charging profiles. Geographic supply concentration centers on Taiwan, South Korea, and China for IGBT and MOSFET sourcing, with raw material dependencies spanning silicon wafers, rare earth magnetic materials, and RoHS-compliant solder alloys. Single-source vulnerability in East Asian foundry capacity creates supply chain risk that charger manufacturers mitigate through dual qualification programs. Distribution runs through direct sales for enterprise fleet operators and regional distributors for field service and recreational vehicle segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined battery management is shifting this market toward platform-economics dynamics, with firmware subscription revenues and predictive maintenance ecosystems displacing transactional hardware procurement as the primary value capture mechanism.
For Market Incumbents: Pre-empt solid-state battery protocol obsolescence by accelerating backward integration into adaptive charging ASICs capable of over-the-air algorithm updates. Secure captive semiconductor supply through foundry partnerships in Taiwan and South Korea before capacity allocation tightens. Defend service contract margins by unbundling hardware from predictive maintenance subscriptions only in markets where distributor technical support networks are already entrenched.
For New Entrants and Emerging Players: Marine and outdoor applications in coastal China and Nordic markets represent the most penetrable entry point, with salt corrosion-resistant IP-rated enclosures commanding premium positioning where CTEK Holding lacks localized service presence. Portable diagnostic units for recreational vehicle owners in the United States offer secondary white-space opportunity, with lithium-ion rapid-charging compatibility as the decisive specification. A channel partnership with industrial distributor networks in Germany bypasses direct sales qualification timelines.
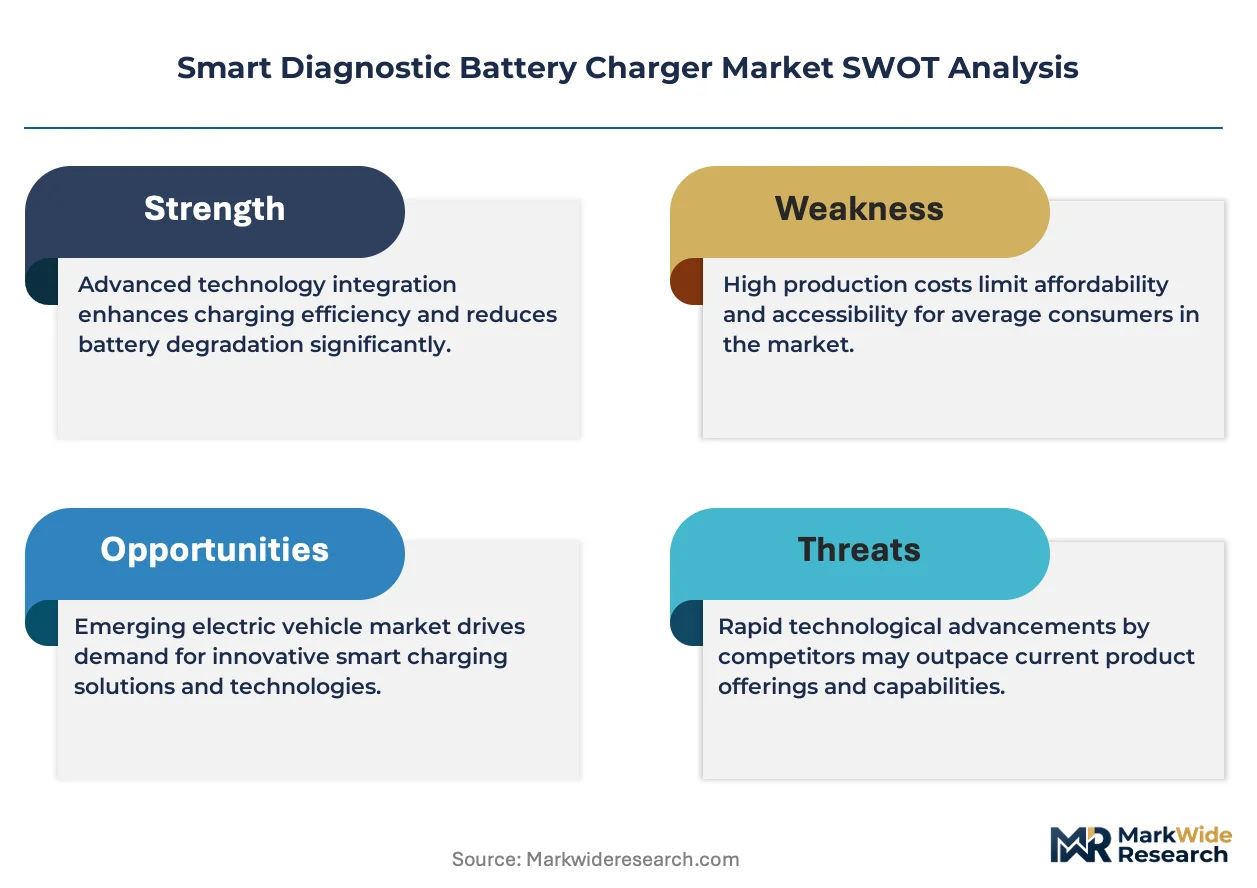
For Investors and Strategic Acquirers: Pure-play battery management specialists with embedded systems firmware libraries and marine application certifications present the most attractive acquisition archetype for platform consolidation plays. Long-term viability hinges on adaptive charging intelligence capabilities that transcend chemistry-specific obsolescence risk. Monitor solid-state battery commercialization timelines at automotive OEM pilot programs as the critical inflection signal for pulse repair technology relevance.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Semiconductors | Captive IGBT supply from TSMC or Samsung Foundry insulates margin from foundry allocation volatility. |
| Software-Defined Charging Platform Launch | Over-the-air firmware updates transform hardware vendors into recurring-revenue battery management service providers. |
| Marine Certification Investment | Salt corrosion resistance and DO-160G testing create defensible premium positioning in offshore safety-critical applications. |
| Predictive Maintenance Subscription Unbundling | Separating hardware from service contracts in Chinese factory automation sites captures total cost of ownership procurement shifts. |
| Multi-Chemistry Certification Acceleration | Simultaneous UL, CE, and GB validation for lead-acid, AGM, gel, and lithium-ion chemistries compresses regulatory filing timelines. |
Research Methodology
The analysis maps stationary chargers, portable chargers, pulse repair technology, and microprocessor-controlled systems, each validated through procurement directors at automotive fleet operators, embedded systems engineers at charging OEMs, and aftermarket service managers at industrial distributor networks. Primary interview intelligence triangulates against customs trade data for power semiconductor imports, SEC 10-K filings from diversified industrial conglomerates, and EU Battery Regulation implementation guidance from ECHA. Bottom-up unit shipment estimates from regional distributor networks reconcile with top-down addressable market sizing derived from EV infrastructure deployment databases and material handling fleet electrification announcements.
Fixed assumptions across the modeling period include sustained EU Battery Regulation enforcement, continued East Asian foundry dominance in power electronics, and gradual solid-state battery pilot deployment without mass-market substitution. Segmentation dimensions span product type, technology architecture, end-use application, and distribution channel, with CAGRs derived from regression analysis of historical replacement cycle timing and regulatory mandate implementation schedules. Forecast inputs incorporate automotive production line battery conditioning capacity expansion in Germany and industrial automation investment trajectories in the Yangtze River Delta.
Practitioners should monitor foundry capacity allocation shifts, solid-state battery chemistry announcements from automotive OEMs, and REACH substance restriction updates for early signals requiring forecast revision. Quarterly review of semiconductor spot pricing, EU Battery Regulation delegated act clarifications, and GB standards electromagnetic compatibility testing backlog is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
Watch Battery Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market
Batteries
Electric Battery Market
Batteries
Vanadium Redox Batteries Market
Batteries
AAA Battery Market
Batteries
USA Forklift Battery Market
Batteries
Battery Cell Market
Batteries
Global Primary Cells Market
Batteries
Forklift Battery Charger Market
Batteries
SLI Battery Market
Batteries
Asia-Pacific NMC Battery Pack Market
Batteries
Norway Rechargeable Battery Market
Batteries
Smart Battery Market
Batteries
Non-Rechargeable Battery Market
Batteries
Marine Powerboat Battery Market