
 India SLI Battery Market | 2026-2036
India SLI Battery Market Size, Share, and Industry Trends Forecast 2026-2036
India SLI Battery Market Insights
Domestic lead-acid recyclers in Gujarat and Tamil Nadu is restructuring raw material flows for India's SLI battery value chain. Exide Industries Ltd leverages captive smelting capacity to control lead costs across its manufacturing network. Amara Raja Energy & Mobility Limited anchors southern India distribution through dense dealer networks in Andhra Pradesh and Telangana. TATA AutoComp GY Batteries Pvt. Ltd. competes on OEM supply relationships with domestic passenger vehicle assemblers.
An SLI (Starting, Lighting, Ignition) battery delivers short-duration high-current bursts to crank internal combustion engines, typically employing lead-acid chemistry with six two-volt cells submerged in sulfuric acid electrolyte for reliable cold-cranking performance. The device supplies stabilized direct current to onboard electronics during alternator downtime. Lead-Acid chemistry dominates installed base due to recyclability and established supply chains, though Start-Stop technology segments are gaining traction as fuel-efficiency regulations tighten. Aftermarket channels carry higher margin pools than OEM supply, while Fleet Operators represent a concentrated demand segment with predictable replacement cycles.
BIS mandates cranking performance benchmarks and environmental disposal protocols for automotive batteries sold in India. CEA guidelines intersect with state-level pollution control requirements for lead smelter emissions near manufacturing clusters. The PLI scheme for advanced chemistry cells is reshaping investment incentives, though lead-acid SLI formats remain outside direct subsidy scope. Stakeholders must monitor how BIS aligns with evolving UN ECE battery standards and whether lithium-ion cost curves penetrate two-wheeler SLI replacement demand.
Market Dynamics
BIS certification mandates and commercial fleet expansion are restructuring competitive positioning in India's SLI battery value chain. Lead-acid chemistry faces selective displacement as start-stop technology penetrates fuel-efficiency segments.
Growth Catalysts
- Commercial Vehicle Fleet Expansion:Logistics operators in Maharashtra and Gujarat are compressing replacement cycles for heavy-duty SLI units. Predictable maintenance schedules generate stable aftermarket demand pools.
- BIS Certification Tightening:The Bureau of Indian Standards is mandating stricter cranking performance benchmarks and environmental disposal protocols. Compliance requirements are filtering out informal assemblers and consolidating certified manufacturer market presence.
- Start-Stop Technology Penetration:Enhanced flooded battery and absorbed glass mat formats are gaining traction in passenger vehicle OEM specifications. Fuel-efficiency regulations are accelerating chemistry upgrades beyond conventional flooded lead-acid designs.
Market Restraints
- Lead Price Volatility:Raw material costs fluctuate with London Metal Exchange pricing and domestic smelter capacity constraints. Captive smelting operations in Gujarat and Tamil Nadu partially insulate integrated manufacturers from spot market swings.
- Lithium-Ion Substitution Threat:Declining lithium-ion cost curves are penetrating two-wheeler SLI replacement demand. Electric two-wheeler adoption in Karnataka and Tamil Nadu is compressing addressable market for traditional lead-acid starter batteries.
- Supply Concentration Risk:Lead smelter emissions regulations under CEA guidelines and state pollution control board mandates are constraining secondary lead availability. Manufacturing clusters near Pune and Chennai face input bottlenecks during regulatory enforcement cycles.
Strategic Opportunities
- Start-Stop Technology White Space:AGM and EFB formats remain underpenetrated in India's passenger vehicle aftermarket. Technical upgrade paths from conventional flooded batteries create margin expansion potential for certified suppliers.
- Recycling Infrastructure Investment:Extended producer responsibility frameworks under BIS environmental protocols are incentivizing closed-loop lead recovery. Integrated smelter-battery operations in Tamil Nadu and Gujarat capture value from end-of-life collection networks.
- Dealer Network Digitization:Dense aftermarket channels in Andhra Pradesh and Telangana are adopting inventory management platforms. Route-to-market efficiency gains compress working capital cycles for regional distributors.
Industry Challenges
- Skilled Technician Scarcity:Start-stop battery installation and diagnostics require specialized training beyond conventional SLI servicing. Technical institutes in Maharashtra and Karnataka are lagging curriculum updates for AGM and EFB handling protocols.
- Certification Timeline Compression:BIS laboratory testing queues and documentation requirements are extending product launch cycles. Manufacturers face working capital lockup during multi-month approval processes for new battery specifications.
- Reverse Logistics Complexity:Lead-acid battery collection and smelter coordination require hazardous material handling permits. State-level transport regulations create friction in interstate movement of spent batteries to recycling facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India SLI Battery Market |
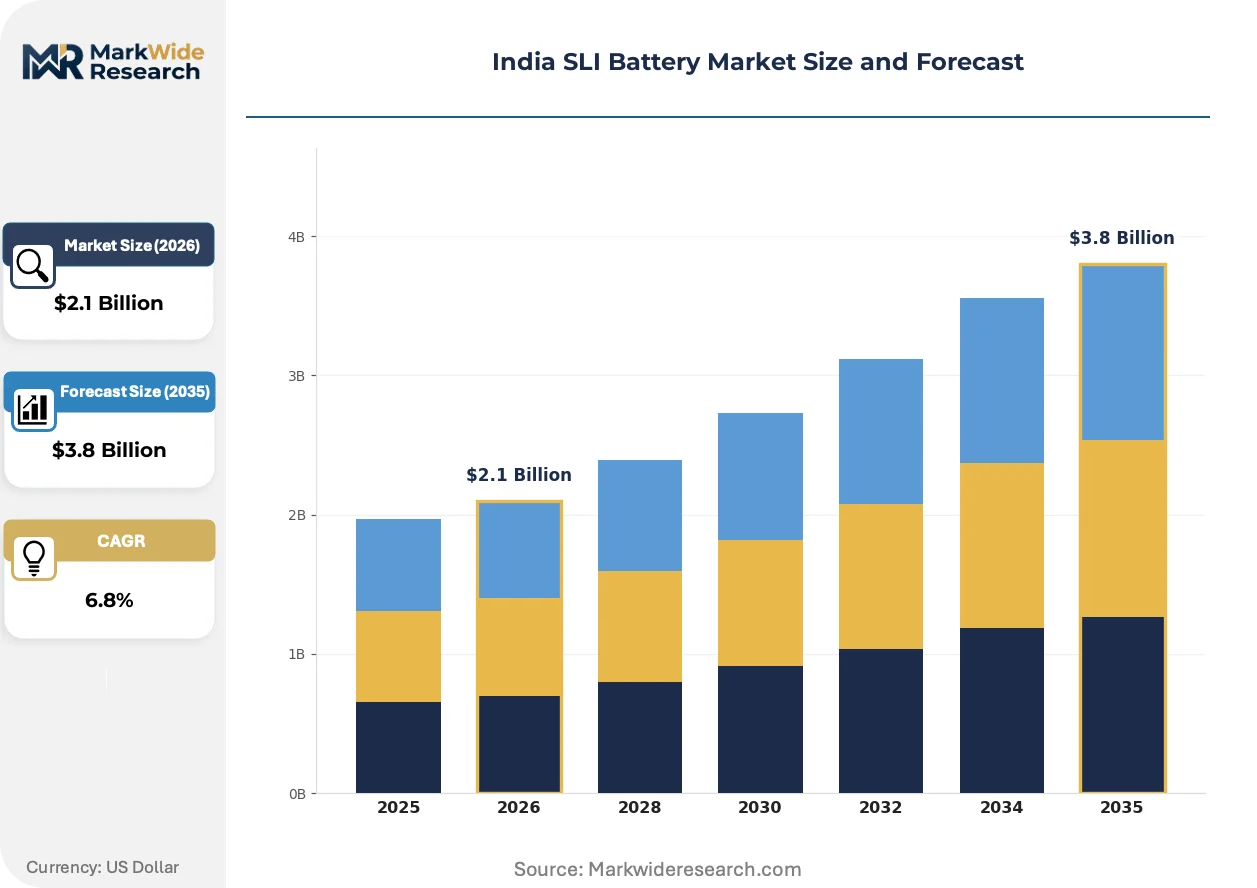
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Absorbent Glass Mat Application: Automotive, Motorcycles, Commercial Vehicles, Marine Technology: Conventional, Start-Stop, Enhanced Flooded Battery, Gel End User: Aftermarket, OEMs, Fleet Operators, Retail |
| Companies Covered | Exide Industries Ltd, Amara Raja Energy & Mobility Limited, Luminous Power Technologies Pvt. Ltd., TATA AutoComp GY Batteries Pvt. Ltd., HBL Power Systems Ltd, TATA Green Batteries, Clarios, EnerSys, GS Yuasa Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India SLI Battery Market Trends and Innovations
Start-stop technology integration and digital distribution platforms are converging to reshape India's SLI battery competitive landscape. Regulatory pressure on fuel efficiency and emissions is accelerating product format evolution beyond conventional lead-acid designs.
Absorbed glass mat technology is converging with enhanced flooded battery formats to serve start-stop vehicle architectures. Passenger vehicle OEMs in Maharashtra are specifying dual-purpose designs that tolerate deeper cycling than traditional starter batteries. The technology convergence is compressing margins for conventional flooded battery assemblers unable to upgrade manufacturing lines.
BIS environmental disposal protocols are intersecting with state pollution control board enforcement to tighten lead smelter emissions standards. Manufacturing clusters near Pune and Chennai are investing in scrubber upgrades and effluent treatment capacity. The regulatory shift is most acute for secondary lead recyclers in Tamil Nadu facing consolidated compliance deadlines.
Fleet operators are unbundling battery procurement from vehicle acquisition to optimize lifecycle costs. Logistics companies in Gujarat and Karnataka are negotiating direct supply agreements with certified manufacturers, bypassing traditional multi-tier distribution. This procurement restructuring is most visible in long-haul trucking segments where predictable replacement schedules enable volume contracting.
India SLI Battery Market Segmentation
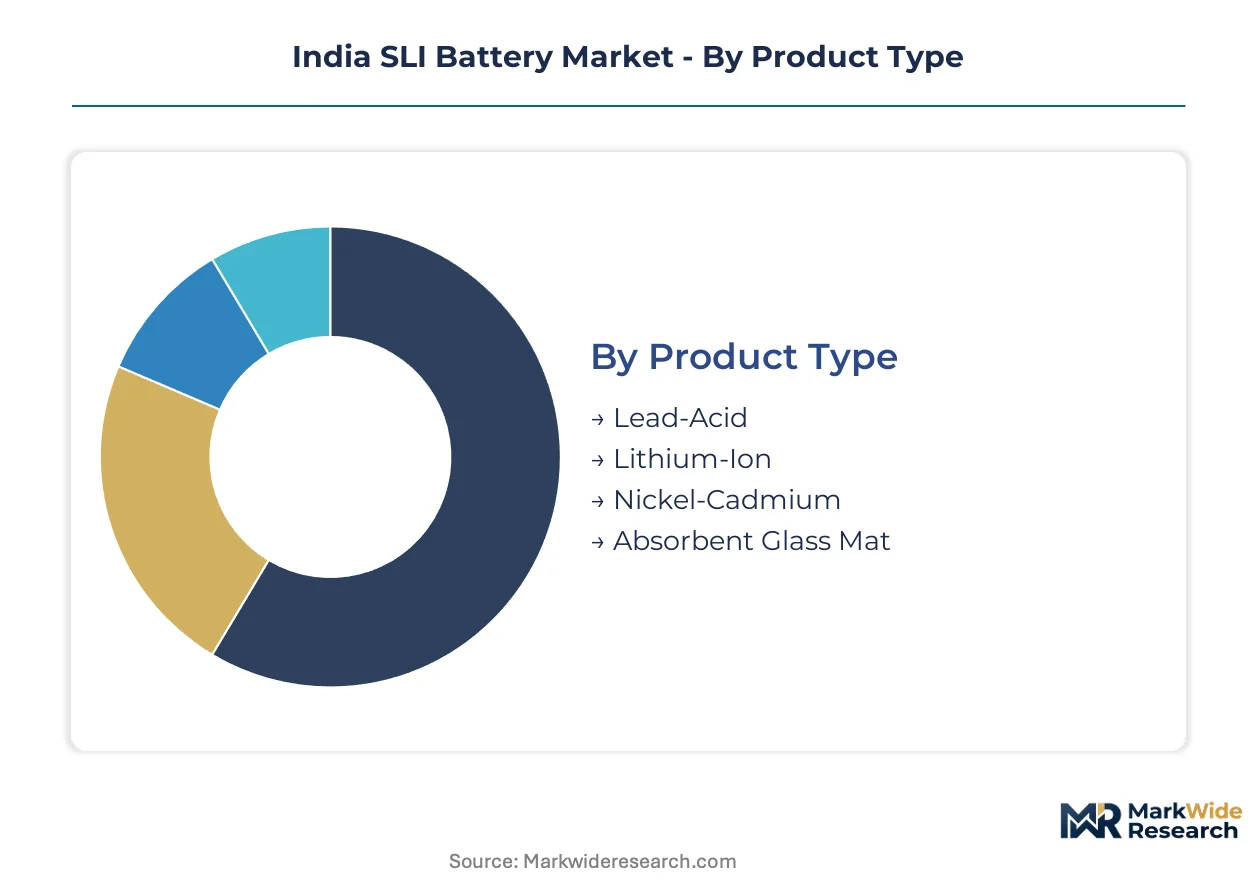
Segmentation in India's SLI battery market reveals how BIS certification burdens and application-specific performance requirements fragment competitive positioning. Chemistry choices, technology formats, and channel strategies each carry distinct regulatory compliance costs and margin profiles.
Product Type:
BIS mandates diverge sharply across chemistries, with lead-acid formats facing established testing protocols while lithium-ion variants navigate evolving safety standards under CEA guidelines.
- Lead-Acid:Flooded lead-acid cells with sulfuric acid electrolyte dominate installed base due to recyclability and Gujarat-Tamil Nadu smelter network proximity. Maharashtra commercial vehicle fleets generate concentrated replacement demand through compressed maintenance cycles.
- Lithium-Ion:Lithium iron phosphate and NMC chemistries penetrate two-wheeler SLI applications as Karnataka electric vehicle adoption accelerates. BIS safety testing queues and thermal runaway documentation requirements extend certification timelines beyond lead-acid benchmarks.
- Nickel-Cadmium:Sintered plate construction tolerates extreme temperature cycling for defense and railway auxiliary applications. Limited civilian demand concentrates in Tamil Nadu industrial zones with legacy infrastructure compatibility requirements.
- Absorbent Glass Mat:Fiberglass mat separators enable vibration resistance and faster recharge rates for start-stop architectures. Pune passenger vehicle OEMs specify AGM for fuel-efficiency compliance in premium model segments.
Lead-Acid sits at the top of the volume ranking, with Lithium-Ion climbing the fastest.
Application:
Replacement cycle predictability varies dramatically across vehicle classes, restructuring procurement patterns and margin capture opportunities.
- Automotive:Passenger vehicle SLI demand splits between OEM specification and aftermarket replacement, with start-stop technology penetration deepening in Maharashtra manufacturing corridors. Warranty periods and dealer network density shape regional competitive dynamics.
- Motorcycles:Two-wheeler batteries face lithium-ion displacement pressure as Tamil Nadu and Karnataka electric scooter adoption compresses addressable lead-acid market. Price sensitivity dominates procurement with minimal brand loyalty in unorganized retail channels.
- Commercial Vehicles:Heavy-duty trucking fleets in Gujarat negotiate direct manufacturer contracts bypassing distribution tiers. Predictable highway mileage generates stable volume contracting with 18-24 month replacement visibility.
- Marine:Deep-cycle dual-purpose designs serve fishing vessel auxiliary power in Kerala and Gujarat coastal zones. Salt corrosion resistance and vibration tolerance specifications exceed automotive SLI requirements.
Automotive commands the largest revenue pool, though Commercial Vehicles deliver the most predictable margin structure.
Technology:
Manufacturing capex requirements and technical training gaps create tiered competitive barriers across technology generations.
- Conventional:Flooded lead-acid with liquid electrolyte remains the cost floor for price-sensitive motorcycle and entry automotive segments. Margin compression intensifies as BIS environmental disposal protocols raise compliance costs for informal assemblers.
- Start-Stop:Dual-purpose designs tolerate deeper cycling for engine-off coasting and regenerative braking capture. OEM specifications from Pune passenger vehicle assemblers are accelerating chemistry upgrade requirements.
- Enhanced Flooded Battery:Improved plate alloys and separator designs bridge conventional and AGM performance at moderate cost premiums. EFB formats gain traction in mid-market automotive segments where full AGM conversion costs encounter resistance.
- Gel:Silica-thickened electrolyte eliminates spillage for tilted installation angles in marine and recreational vehicle applications. Limited volume constrains domestic manufacturing scale, sustaining import dependence for specialized demand.
Conventional technology retains volume leadership, while Start-Stop formats gain share fastest through OEM specification mandates.
End User:
Channel structure determines working capital intensity and technical service requirements, with fleet direct procurement compressing traditional distribution margins.
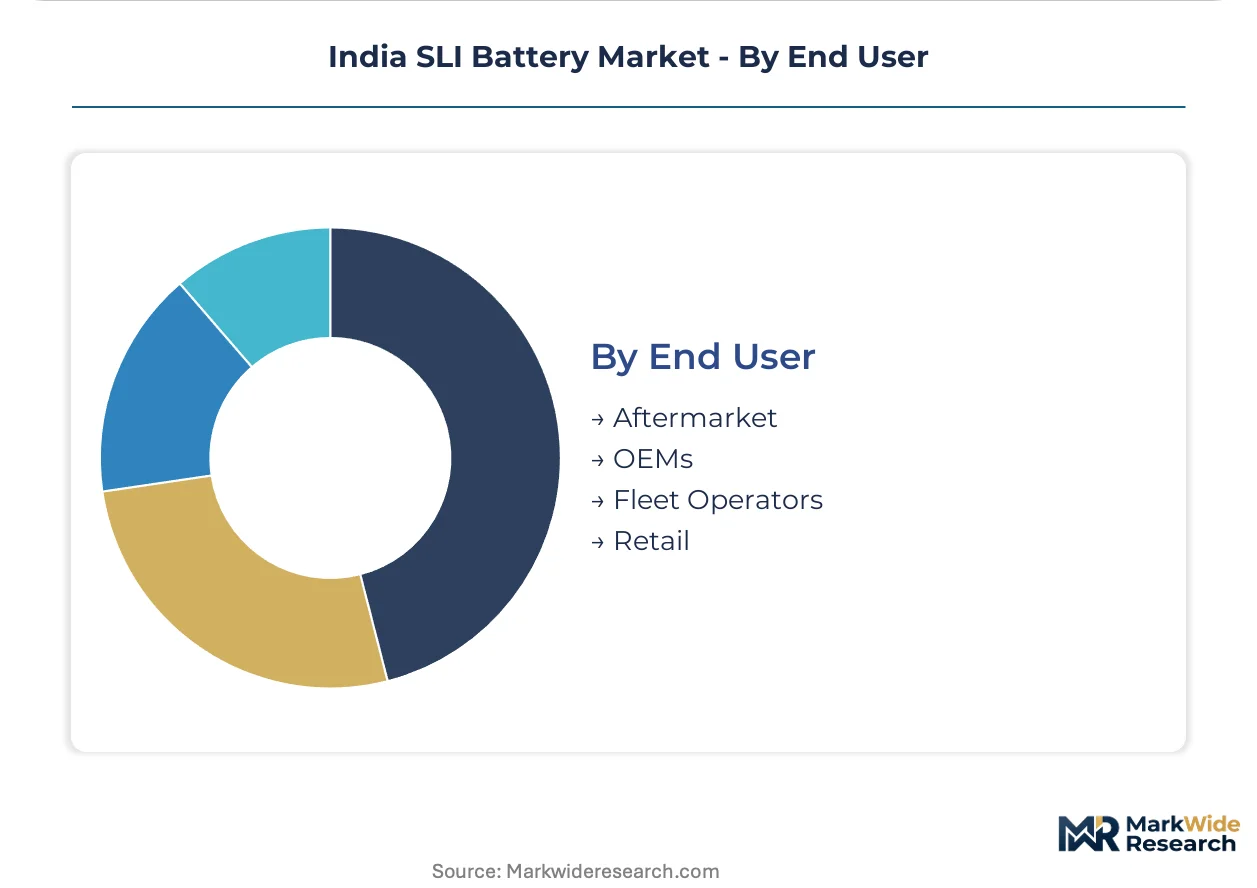
- Aftermarket:Dense dealer networks in Andhra Pradesh and Telangana carry higher margin pools than OEM supply, though inventory financing costs strain regional distributors. Digitization of route-to-market platforms is compressing working capital cycles.
- OEMs:Passenger vehicle assemblers in Maharashtra specify battery formats during platform development, locking in multi-year supply agreements. Technical collaboration on start-stop integration creates switching costs for qualified suppliers.
- Fleet Operators:Logistics companies in Gujarat and Karnataka unbundle battery procurement from vehicle acquisition to optimize lifecycle costs. Volume contracting and predictable replacement schedules enable manufacturer-direct relationships.
- Retail:Unorganized two-wheeler battery replacement channels in Tamil Nadu and Karnataka face lithium-ion substitution pressure. Price transparency from digital platforms is eroding traditional markup structures.
Aftermarket channels capture the widest margin spread, with Fleet Operators restructuring procurement fastest toward direct supply models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's SLI battery demand clusters diverge sharply from China's coastal manufacturing dominance, with production gravity centering on western and southern industrial corridors rather than export-oriented zones.
Maharashtra
Passenger vehicle OEMs around Pune and Chakan specify start-stop battery formats for fuel-efficiency compliance. BIS cranking performance mandates filter supplier qualification for these assembly lines. The Pune-Chakan automotive corridor concentrates technical collaboration between battery makers and vehicle assemblers on AGM integration.
Gujarat
Heavy-duty trucking fleets negotiate direct manufacturer contracts bypassing distribution tiers. CEA guidelines on lead smelter emissions intersect with state pollution control board enforcement near manufacturing clusters. Captive smelting operations in Gujarat partially insulate integrated producers from London Metal Exchange price swings.
Tamil Nadu
Secondary lead recyclers face consolidated compliance deadlines under tightening environmental protocols. The PLI scheme for advanced chemistry cells redirects investment incentives away from lead-acid formats. Chennai-area manufacturing clusters confront input bottlenecks during regulatory enforcement cycles on smelter emissions.
Karnataka
Electric two-wheeler adoption in Bengaluru compresses addressable market for traditional lead-acid starter batteries. State-level transport regulations create friction in interstate movement of spent batteries to recycling facilities. Technical institutes lag curriculum updates for AGM and EFB handling protocols.
Andhra Pradesh and Telangana
Dense aftermarket dealer networks carry higher margin pools than OEM supply channels. Digitization of route-to-market platforms compresses working capital cycles for regional distributors. Unorganized retail channels face price transparency pressure from battery procurement platforms.
India SLI Battery Market Competitive Landscape
Gujarat and Tamil Nadu producers anchor one tier; Maharashtra and Karnataka specialists hold aftermarket and OEM specification positions respectively. The vendor base consolidates around integrated smelter-battery operations and dense distribution networks. Three archetypes dominate: captive lead producers controlling raw material costs, dealer-network specialists capturing aftermarket margin, and OEM-integrated suppliers locking in platform development cycles. Competitive moves concentrate on recycling infrastructure investment and start-stop technology line upgrades.
Within the integrated producer tier, Exide Industries Ltd and Amara Raja Energy & Mobility Limited exemplify divergent geographic strategies. Exide anchors western India manufacturing through captive smelting capacity, while Amara Raja occupies a position in southern distribution density. TATA AutoComp GY Batteries Pvt. Ltd. sits within the OEM-integrated specialist category, representing the vehicle assembler affiliate model. These three patterns—captive raw material control, route-to-market depth, and assembler alignment—structure competitive positioning across the value chain.
| Leading Market Players |
|---|
| Exide Industries Ltd |
| Amara Raja Energy & Mobility Limited |
| Luminous Power Technologies Pvt. Ltd. |
| TATA AutoComp GY Batteries Pvt. Ltd. |
| HBL Power Systems Ltd |
| TATA Green Batteries |
| Clarios |
| EnerSys |
| GS Yuasa Corporation |
| Others |
Pricing and Supply Chain Analysis
BIS environmental disposal protocols gate qualified supply access and premium-tier pricing power in India's SLI battery market. Compliance investments filter informal assemblers from certified manufacturer tiers, concentrating margin capture among integrated producers with captive smelting and end-of-life collection networks.
Pricing Analysis
Capacity additions in Tamil Nadu and Gujarat are reshaping price floors for lead-acid formats as captive smelter operations compress raw material costs for integrated manufacturers. Pricing stratifies across AGM-EFB premium tiers, BIS-certified standard segments, and unorganized economy channels where price sensitivity concentrates in two-wheeler replacement demand. Cost compression in conventional flooded batteries intensifies as lithium-ion substitution pressure penetrates Karnataka electric two-wheeler markets. Fleet operators in Maharashtra and Gujarat exhibit lowest price sensitivity due to lifecycle contracting, while unorganized retail channels in Tamil Nadu face margin erosion from digital price transparency.
Supply Chain Analysis
BIS certification and CEA smelter emissions standards gate qualified supplier participation, concentrating manufacturing among integrated producers with environmental compliance infrastructure. Lead supply draws from domestic secondary smelters in Gujarat and Tamil Nadu, with primary lead imports supplementing raw material requirements during regulatory enforcement cycles. Manufacturing inputs hinge on sulfuric acid electrolyte, fiberglass mat separators for AGM formats, and specialized plate alloys for EFB designs. Single-source vulnerability concentrates in secondary lead availability during state pollution control board enforcement actions. Distribution runs through dense dealer networks in Andhra Pradesh and Telangana for aftermarket coverage, with direct manufacturer contracts serving Gujarat fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's SLI battery market compounds steadily as commercial vehicle fleet expansion generates predictable replacement demand pools with compressed maintenance cycles.
For Market Incumbents: Cement smelter-battery integration advantages by expanding captive lead recovery capacity in Tamil Nadu and Gujarat ahead of consolidated BIS environmental deadlines. Defend aftermarket margin pools through dealer network digitization in Andhra Pradesh and Telangana, countering direct procurement restructuring by logistics fleet operators. Prioritize AGM-EFB line upgrades to capture start-stop specification mandates from Pune passenger vehicle OEMs. For New Entrants and Emerging Players: Enter via start-stop technology white space in India's passenger vehicle aftermarket, where AGM and EFB formats remain underpenetrated relative to OEM specification penetration. Target marine and commercial vehicle auxiliary power segments in Kerala and Gujarat coastal zones, where deep-cycle dual-purpose designs face limited domestic manufacturing scale. Pursue fleet direct contracting models bypassing traditional distribution tiers, leveraging predictable replacement visibility in long-haul trucking segments. For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket distributors with dense dealer networks because BIS certification barriers and working capital intensity fragment competitive positioning across state-level markets. Acquisition targets include southern India distribution specialists with route-to-market control in Andhra Pradesh and Telangana, and secondary lead recyclers with environmental compliance infrastructure in Tamil Nadu. Watch lithium-ion cost curve progression in two-wheeler SLI replacement as the signal for lead-acid demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Recycling Infrastructure Investment | Extended producer responsibility under BIS protocols rewards closed-loop lead recovery in Tamil Nadu and Gujarat smelter networks. |
| Start-Stop Technology Line Upgrade | AGM and EFB manufacturing capacity captures fuel-efficiency specification mandates from Pune passenger vehicle OEMs. |
| Fleet Direct Supply Agreement | Volume contracting with Gujarat logistics operators bypasses distribution margin compression in traditional aftermarket channels. |
| Dealer Network Digitization | Inventory management platforms compress working capital cycles for regional distributors in Andhra Pradesh and Telangana. |
| Technical Training Partnership | AGM-EFB handling curriculum development addresses skilled technician scarcity in Maharashtra and Karnataka service networks. |
Research Methodology
Direct dialogue with battery manufacturing executives, aftermarket distribution heads, fleet procurement managers, and lead smelter operations directors grounded qualitative insights in operational reality. Secondary validation drew from BIS certification databases, CEA emissions compliance records, vehicle production statistics, and customs trade data for lead and battery imports. Bottom-up channel sizing triangulated against top-down macroeconomic drivers across the projection horizon.
Segmentation outputs reflect chemistry choices, technology formats, application classes, and channel structures modeled throughout the forecast period. CAGRs were derived from replacement cycle analysis, fleet expansion trajectories, and regulatory compliance cost pass-through assumptions. Industry-specific inputs included BIS laboratory testing queue durations, state-level pollution control enforcement patterns, and lithium-ion substitution elasticity in two-wheeler markets.
Inputs from BIS certification records and CEA smelter compliance filings were available through the study window; gaps in informal assembler production estimates introduce uncertainty bands in economy-tier volume projections. Forecasts reflect documented assumptions on regulatory timeline adherence and technology substitution rates. A model refresh is warranted upon material change in PLI scheme scope for advanced chemistry cells or consolidated BIS-UN ECE alignment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
Submarine Batteries Market
Batteries
Japan Mobile Battery Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
Yacht Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Forklift Battery Market
Batteries
South America Consumer Battery Market
Batteries
South America Battery Cell Market
Batteries
Battery Light Towers Market
Batteries
Myanmar Battery Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
Global Industrial Lead Acid Battery Market
Batteries
Battery Separators Market
Batteries
South Africa Battery Market