
 Middle-East and North Africa Rechargeable Battery Market | 2026-2036
Middle-East and North Africa Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and North Africa Rechargeable Battery Market Insights
Morocco is narrowing its dependence on imported cells through industrial zone development around Tangier and Kenitra. BYD Company Ltd leverages integrated cell-to-pack manufacturing to serve African utility-scale tenders. Panasonic Holdings Corporation anchors premium cylindrical cell supply for Gulf consumer electronics OEMs. Samsung SDI competes on high-nickel chemistry roadmaps tailored to Middle Eastern thermal conditions.
Rechargeable batteries in the Middle-East and North Africa region are electrochemical energy storage devices designed for multiple discharge-recharge cycles, typically employing lithium-ion cells with nickel-manganese-cobalt or lithium-iron-phosphate cathodes operating between 2.5V and 4.2V per cell, primarily deployed to buffer intermittent renewable generation and power electrified transport. The lithium-ion product category dominates procurement volumes across utility and mobility applications, while lead acid retains cost-sensitive industrial equipment installations. Energy Storage Systems application demand is accelerating fastest as Gulf utilities procure four-hour duration battery plants to firm solar output.
Saudi SFDA and UAE MOHAP enforce transport and stationary storage safety protocols that restrict uncertified pack imports, while Morocco's national regulator applies CE-aligned technical standards for grid-connected installations. Egypt's CEA and Israel's national standards body are drafting capacity market rules that will mandate frequency response capabilities from new battery assets. Stakeholders must track which certification pathway—European CE marking, Chinese GB standards, or emerging Gulf technical regulations—each national procurement authority will recognize for upcoming tenders.
Market Dynamics
Gulf Cooperation Council oil-to-electric transition programs are compressing procurement timelines for utility-scale battery storage, forcing suppliers to pre-certify packs against divergent national safety protocols before tender participation.
Growth Catalysts
- SFDA Transport Safety Mandates:Saudi Arabia's tightened import protocols for lithium-ion cells are filtering out uncertified suppliers and consolidating procurement around pre-qualified pack assemblers with in-country testing facilities.
- Solar-Plus-Storage Auctions:Abu Dhabi's renewable energy procurement authority is embedding four-hour duration battery requirements into every utility-scale solar tender, creating dedicated demand corridors for lithium-iron-phosphate suppliers.
- EV Charging Infrastructure Rollouts:Dubai's network expansion is absorbing high-nickel cylindrical cells for fast-charging stations, pulling cell volumes away from consumer electronics channels.
Market Restraints
- Cobalt and Lithium Price Volatility:Raw material input swings are compressing cell assembler margins and forcing pass-through clauses into long-term offtake contracts with Gulf utilities.
- East Asian Cell Supply Concentration:Overwhelming dependence on Chinese and Korean cell production creates single-source vulnerability for Moroccan and Egyptian pack integrators lacking backward integration.
- CE Marking Recognition Gaps:Divergent acceptance of European certification versus emerging Gulf technical regulations is fragmenting compliance pathways and delaying project financial close.
Strategic Opportunities
- Industrial Zone Development:Morocco's Tangier and Kenitra manufacturing corridors offer tariff-advantaged cell-to-pack assembly for African utility tenders and European re-export.
- Frequency Response Mandates:Egypt's CEA draft capacity market rules will require grid-connected batteries to deliver ancillary services, opening technical specification premiums for advanced battery management systems.
- Second-Life Automotive Packs:Retired electric vehicle batteries from UAE fleets are hybridizing into stationary storage applications for commercial and industrial behind-the-meter installations.
Industry Challenges
- Thermal Management Engineering Shortage:Gulf utilities lack sufficient local talent to design battery enclosures for ambient temperatures exceeding 45°C, forcing reliance on foreign engineering contractors.
- Multi-Certification Timeline Compression:Pack suppliers must simultaneously pursue SFDA, MOHAP, and CE-aligned approvals to serve fragmented procurement authorities, stretching quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and North Africa Rechargeable Battery Market |
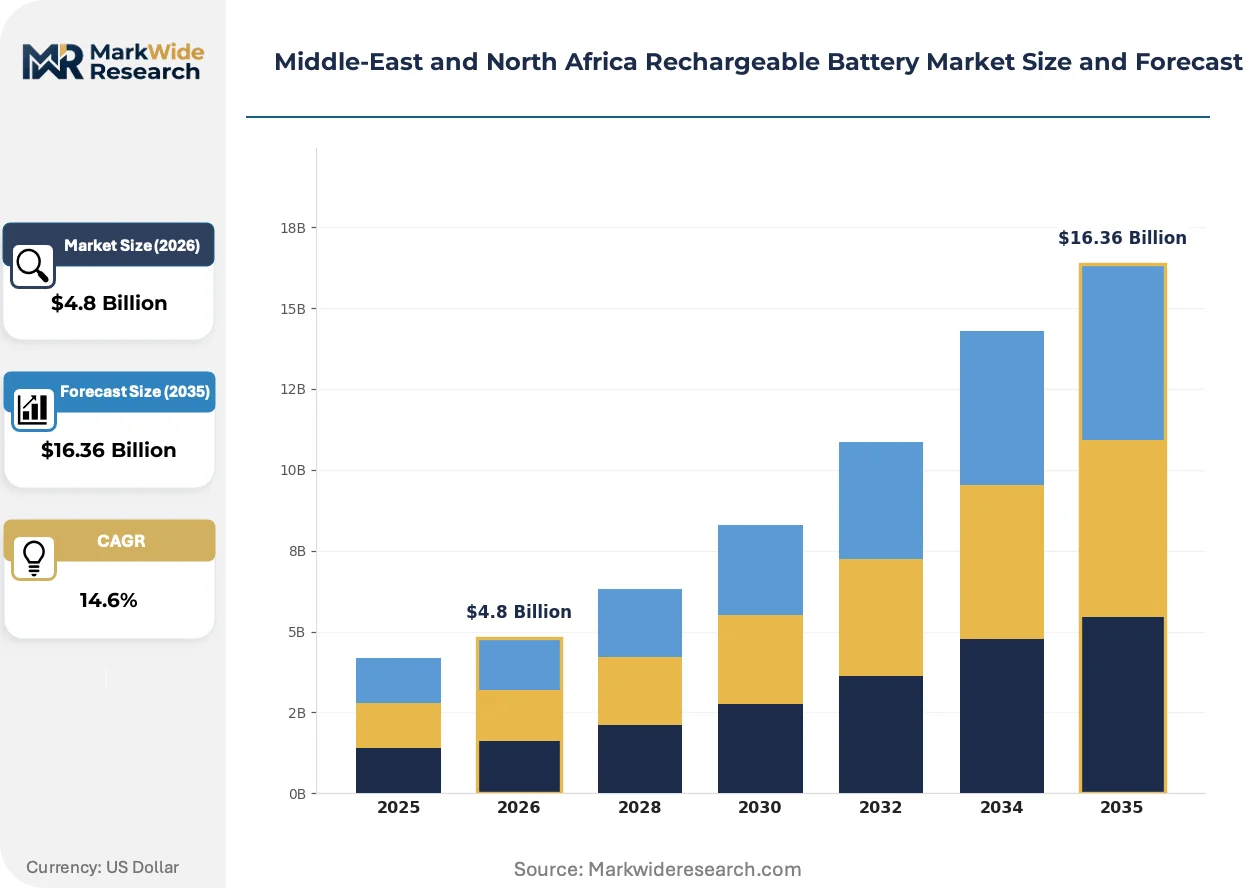
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead Acid, Sodium-ion End User: Consumer Electronics, Automotive, Renewable Energy, Industrial Equipment Technology: Battery Management Systems, Fast Charging, Thermal Management, Energy Density Enhancements Application: Electric Vehicles, Power Tools, Energy Storage Systems, Mobile Devices |
| Companies Covered | BYD Company Ltd, Panasonic Holdings Corporation, Exide Industries Ltd, EnerSys, Middle East Battery Company (MEBCO), Duracell Inc., LG Chem, Contemporary Amperex Technology Co., Limited, Samsung SDI, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and North Africa Rechargeable Battery Market Trends and Innovations
Cell chemistry roadmaps and procurement contracting models are diverging across the Middle-East and North Africa region as thermal conditions and regulatory fragmentation force localized adaptation.
Sodium-ion cathode formulations are hybridizing with conventional lithium-ion production lines as Moroccan and Algerian developers seek chemistry-agnostic pack architectures that can switch cell suppliers without enclosure redesign. North African solar developers are piloting sodium-ion banks for six-hour duration storage where energy density penalties matter less than thermal stability. This hybridizing approach is compressing the technology lock-in that previously favored established lithium-iron-phosphate supply relationships.
MOHAP stationary storage safety protocols in the UAE are mandating gas detection and suppression systems inside every containerized battery plant, forcing pack integrators to redesign thermal runaway containment architectures. The industrial consequence is a bifurcation between Gulf-certified premium enclosures and standard international offerings. Utility-scale procurement in Abu Dhabi and Dubai is most affected, with developers absorbing 12-18 month certification timelines into project schedules.
Long-term service agreements are unbundling from initial hardware supply as Gulf utilities seek operational risk transfer to cell suppliers. Procurement teams in Saudi Arabia and Qatar are negotiating availability-based contracts where suppliers guarantee round-trip efficiency degradation curves. This shift is most visible in the Emirates, where Dubai's utility is piloting ten-year service wraps on its 2024 battery plant awards.
Middle-East and North Africa Rechargeable Battery Market Segmentation
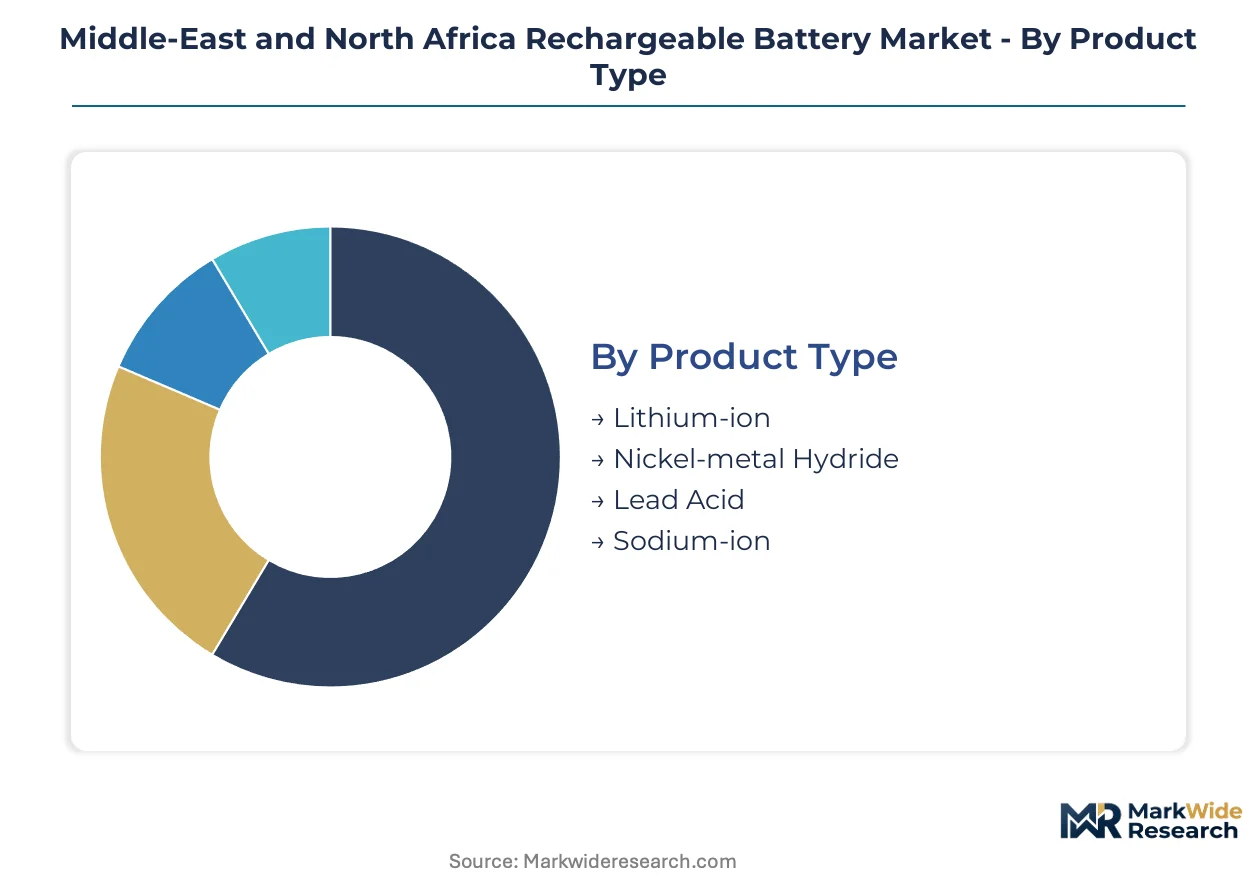
Segmentation reveals how divergent thermal conditions, regulatory fragmentation, and oil-to-electric transition timelines are splitting procurement requirements across the Middle-East and North Africa rechargeable battery market. Each dimension captures distinct technical specifications, certification burdens, and customer contracting preferences that suppliers must navigate simultaneously.
Product Type:
Use-case spectrum spans high-energy-density mobility applications to cost-tolerant stationary installations, with chemistry selection driven by ambient temperature tolerance and cycle life requirements.
- Lithium-ion:Nickel-manganese-cobalt and lithium-iron-phosphate cathodes dominate procurement volumes across Gulf utility-scale solar-plus-storage tenders and UAE electric vehicle charging infrastructure. Abu Dhabi's four-hour duration mandates and Dubai's fast-charging station rollouts are absorbing cylindrical and prismatic formats with enhanced thermal management.
- Lead Acid:Flooded and valve-regulated designs retain industrial equipment installations in Egyptian manufacturing zones and Moroccan phosphate mining operations where capital constraints override energy density requirements. Cost-sensitive procurement favors established supply chains with minimal certification overhead.
- Nickel-metal Hydride:Hybrid electric vehicle battery packs in Saudi Arabia's emerging domestic automotive assembly sector utilize this chemistry for moderate-temperature reliability.
- Sodium-ion:Moroccan and Algerian developers are piloting six-hour duration solar storage banks where thermal stability outweighs energy density penalties, enabling supplier-switching flexibility without enclosure redesign.
Established volume favors lithium-ion; emerging adoption favors sodium-ion.
End User:
Customer-type concentration varies by national industrial policy, with state-led procurement dominating utility-scale deployments and private investment driving consumer channels.
- Automotive:Gulf Cooperation Council oil-to-electric transition programs are compressing procurement timelines for electric vehicle fleets, with Saudi Arabia's domestic manufacturing incentives and UAE charging network mandates creating dedicated demand corridors for high-nickel cylindrical cells.
- Renewable Energy:Abu Dhabi's solar-plus-storage auctions and Morocco's Noor Ouarzazate complex extensions are embedding battery requirements into every utility-scale tender, pulling lithium-iron-phosphate volumes for four-to-six-hour duration plants.
- Consumer Electronics:Premium cylindrical cell demand from Gulf consumer electronics OEMs concentrates in Panasonic and Samsung SDI supply relationships.
- Industrial Equipment:Egyptian cement and steel producers are procuring lead-acid traction batteries for forklift fleets and backup power systems.
Procurement scale favors automotive; policy tailwinds favor renewable energy.
Technology:
Margin structure across technology tiers reflects engineering intensity, with thermal management commanding premium pricing in Gulf ambient conditions exceeding 45°C.
- Thermal Management:Active liquid cooling and phase-change material systems are mandatory for UAE MOHAP-certified containerized battery plants, with gas detection and suppression integration adding 12-18 month certification timelines. Gulf utilities rely on foreign engineering contractors due to local talent scarcity.
- Battery Management Systems:Egypt's CEA draft capacity market rules are mandating frequency response capabilities, opening specification premiums for advanced state-of-charge algorithms and predictive degradation modeling.
- Fast Charging:Dubai's EV charging infrastructure rollout is absorbing high-power cell formats capable of 350kW sustained output.
- Energy Density Enhancements:Silicon-anode and high-nickel cathode roadmaps from Korean and Chinese cell suppliers are penetrating Gulf premium mobility applications.
Compliance burden favors thermal management; technical differentiation favors battery management systems.
Application:
Application maturity splits between established consumer channels and rapidly scaling utility and mobility deployments.
- Energy Storage Systems:Four-hour duration requirements in Abu Dhabi and Dubai utility tenders are creating the steepest expansion trajectory across the region, with Saudi SFDA safety mandates filtering procurement toward pre-qualified pack assemblers with in-country testing facilities.
- Electric Vehicles:Fleet electrification programs across Saudi Arabia, UAE, and Qatar are absorbing high-nickel cylindrical and prismatic cells, with second-life automotive packs hybridizing into UAE commercial and industrial behind-the-meter installations.
- Mobile Devices:Premium cylindrical cell supply for Gulf consumer electronics OEMs retains established Panasonic and Samsung SDI relationships.
- Power Tools:Moroccan and Egyptian construction sectors are procuring nickel-metal hydride and entry lithium-ion packs for cordless equipment.
Utility-scale procurement favors energy storage systems; fleet transition momentum favors electric vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell assembly concentrates in East Asian manufacturing clusters, yet Gulf utilities are forcing localization through pre-qualification requirements. Moroccan industrial zones and UAE testing facilities are emerging as regional nodes for pack integration and certification.
Saudi Arabia
Domestic EV fleet procurement and grid-scale storage tenders are absorbing cylindrical and prismatic cell volumes. The SFDA enforces transport safety mandates that filter uncertified pack imports. Riyadh and the Eastern Province host pre-qualified assemblers with in-country thermal testing capabilities.
United Arab Emirates
Dubai's fast-charging network expansion and Abu Dhabi's solar-plus-storage auctions are creating dedicated procurement channels. MOHAP mandates gas detection and suppression systems for containerized plants. Jebel Ali industrial corridors concentrate pack integration facilities serving Gulf re-export.
Morocco
Noor Ouarzazate complex extensions and African utility tenders are embedding four-to-six-hour battery requirements. National regulators apply CE-aligned technical standards for grid-connected installations. Tangier and Kenitra manufacturing corridors offer tariff-advantaged cell-to-pack assembly.
Egypt
Cement and steel producers procure lead-acid traction batteries for industrial fleets while renewable developers await capacity market finalization. The CEA drafts rules mandating frequency response capabilities from new battery assets. Suez Canal Economic Zone clusters are attracting pack integrators serving North African tenders.
Israel
Grid modernization and behind-the-meter commercial storage are driving lithium-ion procurement. The national standards body is drafting capacity market rules aligned with European frequency response norms. Tel Aviv metropolitan clusters concentrate battery management system engineering talent.
Middle-East and North Africa Rechargeable Battery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on chemistry and thermal management. The supplier base organizes around three archetypes: integrated cell-to-pack manufacturers, premium cylindrical cell producers, and regional pack assemblers with certification expertise. Consolidation pressures favor pre-qualified suppliers with multi-jurisdiction approval capabilities. Competitive moves center on backward integration into cell production and geographic expansion through industrial zone partnerships.
Within the integrated manufacturing tier, BYD Company Ltd and Contemporary Amperex Technology Co., Limited represent scale-driven platform players with captive cell supply. Panasonic Holdings Corporation and Samsung SDI occupy positions as premium cylindrical specialists serving Gulf consumer electronics and mobility OEMs. Among regional pack integrators, Middle East Battery Company exemplifies the certification-focused archetype with established SFDA and MOHAP testing relationships.
| Leading Market Players |
|---|
| BYD Company Ltd |
| Panasonic Holdings Corporation |
| Exide Industries Ltd |
| EnerSys |
| Middle East Battery Company (MEBCO) |
| Duracell Inc. |
| LG Chem |
| Contemporary Amperex Technology Co., Limited |
| Samsung SDI |
| Others |
Pricing and Supply Chain Analysis
Jebel Ali port freight corridors from East Asian cell manufacturing clusters to Gulf pack integrators impose cost dynamics that amplify supply-side concentration into downstream price stratification across certification tiers.
Pricing Analysis
SFDA transport safety mandates dictate the pricing tier structure across Saudi procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates MOHAP-certified containerized plants with gas suppression integration from uncertified imports and industrial lead-acid alternatives. Price differentiation hinges on certification grade and after-sales service bundling, with Gulf utilities absorbing twelve-to-eighteen-month compliance timelines into project costs. Cost compression in standard-tier lithium-iron-phosphate packs is intensifying because raw material pass-through clauses force cell assemblers to absorb cobalt and lithium volatility.
Supply Chain Analysis
Tariff exposure between China and Morocco dominates supply chain risk calculus for North African pack integrators. Cell supply concentrates in China, South Korea, and Japan, with Moroccan and Egyptian assemblers lacking backward integration into cathode active material production. Raw material dependencies rest on lithium carbonate, nickel sulfate, and cobalt hydroxide feedstocks from Chilean and Indonesian extraction. Single-source vulnerability pervades the cell-to-pack transition for regional integrators. Distribution runs through Jebel Ali re-export hubs serving Gulf Cooperation Council utilities and Tangier manufacturing corridors targeting African tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity where ten-year availability-based contracts with guaranteed round-trip efficiency degradation curves are expanding faster than standalone hardware procurement across Emirates utility tenders.
For Market Incumbents: Entrench pre-qualified status with SFDA and MOHAP through in-country thermal testing facilities in Riyadh and Dubai. Deepen backward integration into cell production to offset East Asian supply concentration risks. Defend against sodium-ion substitution in Moroccan six-hour duration pilots by anchoring lithium-iron-phosphate relationships with Noor Ouarzazate complex developers. For New Entrants and Emerging Players: Build out certification expertise as a standalone service layer for Egyptian and Algerian developers awaiting capacity market finalization. Target second-life automotive pack hybridization for UAE commercial and industrial behind-the-meter installations as the most penetrable white space. Pursue joint-venture structures with Tangier industrial zone authorities to access tariff-advantaged cell-to-pack assembly for African utility tenders. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional pack integrators with multi-jurisdiction certification capabilities over pure cell manufacturers facing chemistry-transition risks. Long-term viability hinges on service revenue attachment rates and operational risk transfer contract penetration. Monitor Egypt CEA capacity market rule finalization as the signal indicating frequency response capability premiums and battery management system valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Investment | Pre-qualifies pack assemblers for Saudi utility-scale tenders filtering uncertified imports. |
| Backward Integration into Cathode Production | Reduces single-source vulnerability for Moroccan integrators serving African tenders. |
| Service Agreement Unbundling | Captures ten-year availability-based revenue streams from Dubai utility pilot programs. |
| Tangier Industrial Zone Partnership | Unlocks tariff-advantaged assembly for European re-export and African utility procurement. |
| Sodium-Ion Pilot Deployment | Positions Algerian developers for supplier-switching flexibility without enclosure redesign costs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, utility procurement disclosures, and regulatory filing databases. Primary interviews engaged utility planning officers at Gulf Cooperation Council state utilities, IPP project developers active in Abu Dhabi solar-plus-storage auctions, EPC contractors with MOHAP certification experience, and cell supplier commercial directors with regional tender participation. Secondary validation drew from SFDA transport safety protocol amendments, MOHAP stationary storage technical regulations, Egypt CEA capacity market consultation papers, and Morocco Noor Ouarzazate complex extension documentation. Bottom-up project pipeline aggregation was triangulated against top-down macroeconomic scenario modeling.
Forecast inputs span product type chemistry roadmaps, end-user procurement channel concentration, technology tier thermal management requirements, and application duration specifications across the analysis window. Segmentation dimensions modeled include lithium-ion versus sodium-ion chemistry adoption curves, automotive versus renewable energy versus industrial equipment end-use splits, and Gulf versus North African regulatory framework clusters. CAGRs were derived from installed base growth trajectories and replacement cycle assumptions. Industry-specific inputs incorporated Gulf ambient temperature derating factors and frequency response capability mandate adoption curves.
Stress conditions across cobalt-lithium price volatility bands, SFDA certification timeline extensions, and Egypt CEA rule finalization delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding oil-to-electric transition program execution rates and industrial zone development timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Iron Salt Battery Market
Batteries
Battery Plate Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
Lithium-Based Battery Charger Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
Europe Industrial Battery Market
Batteries
Rechargeable Coin Cell Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Zinc Carbon Battery Market
Batteries
Myanmar Battery Market
Batteries
South Africa Battery Market
Batteries
Asia Power Tool Batteries Market
Batteries
China Electric Vehicle Vrla Batteries Market
Batteries
Lithium-Fluorinated Graphite Batteries Market