
 Military Battery Market | 2026-2036
Military Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Military Battery Market Intelligence
Software-defined battery management is repositioning what defense primes deliver to end users, shifting contracts from hardware-only procurements to integrated power-as-a-service agreements. EnerSys leverages its North American manufacturing footprint to anchor Pentagon supply security mandates. Saft specializes in high-reliability lithium-thionyl chloride architectures for extended mission profiles in contested logistics environments.
A military battery is an electrochemical energy storage device engineered to deliver specified voltage, current, and cycle life under extreme thermal, mechanical, and electromagnetic conditions, typically employing lithium-ion, nickel-metal hydride, or specialized chemistry formulations sealed to MIL-STD-810 environmental standards; its primary purpose is to power mission-critical electronics, propulsion, and weapon systems when grid access is impossible or denied. Lithium-ion chemistry dominates procurement for its energy density advantage in unmanned vehicles and dismounted soldier systems, while silver zinc retains priority in naval torpedo and submarine applications where volumetric efficiency outweighs cost. Lead acid maintains residual presence in vehicle starting and stationary backup roles despite weight penalties, as legacy platform retrofit cycles extend replacement timelines.
US DoD acquisition officers, NATO standardization offices, and the Defense Logistics Agency jointly enforce battery qualification protocols that restrict market access to vendors meeting MIL-PRF-32052 or STANAG specifications. The EU Green Deal's emerging critical raw materials framework will tighten cobalt and lithium sourcing disclosures for European defense contractors. Stakeholders must monitor how export control expansions around advanced cell technologies reshape supplier eligibility across allied procurement networks.
Market Dynamics
The US Defense Production Act's lithium supply chain mandates are forcing prime contractors to requalify domestic cell sources, creating a bifurcation between Pentagon-compliant and export-oriented production lines. This regulatory pressure is compressing vendor qualification timelines while elevating capital requirements for market participation.
Growth Catalysts
- Unmanned vehicle fleet expansion:Autonomous ground and aerial platforms require high-cycle lithium-ion packs that legacy lead-acid architectures cannot support. The US Army's Robotic Combat Vehicle program exemplifies this demand inflection.
- MIL-PRF-32052 qualification pathways:Standardized testing protocols reduce vendor onboarding friction for NATO interoperable systems. The Defense Logistics Agency has streamlined certification for solid-state cell architectures.
- Contested logistics doctrine:Extended mission profiles without resupply are driving energy density requirements beyond 300 Wh/kg in dismounted soldier power systems.
Market Restraints
- Cobalt and lithium price volatility:Cathode material costs swing with DRC mining output and Chilean brine processing capacity, compressing cell manufacturer margins.
- Single-source dependency for separator films:Japanese and South Korean suppliers control 70% of military-grade ceramic-coated separator production.
- Solid-state electrolyte manufacturing yields:Sulfide-based ceramic processing remains below commercial scale thresholds, limiting next-generation cell availability.
Strategic Opportunities
- Software-defined battery management integration:AI-enabled state-of-health prediction enables power-as-a-service contracts, shifting revenue from hardware sales to operational availability guarantees.
- EU Green Deal critical raw materials framework:Battery passport requirements create first-mover advantage for European contractors with transparent cobalt and lithium sourcing.
- Undersea and arctic warfare applications:Silver-zinc chemistry retains dominance in torpedo propulsion where pressure tolerance and low-temperature performance outweigh cost penalties.
Industry Challenges
- Electrochemical engineer talent scarcity:Military cell design requires hybrid expertise in solid-state physics and MIL-STD-810 environmental testing that university programs rarely combine.
- Dual-use export control navigation:The Wassenaar Arrangement's advanced battery technology annex complicates cross-border collaboration on next-generation chemistries.
- Legacy platform retrofit integration:24V and 28V bus architectures in fielded vehicles constrain voltage migration paths for higher-energy lithium-ion substitutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Battery Market |
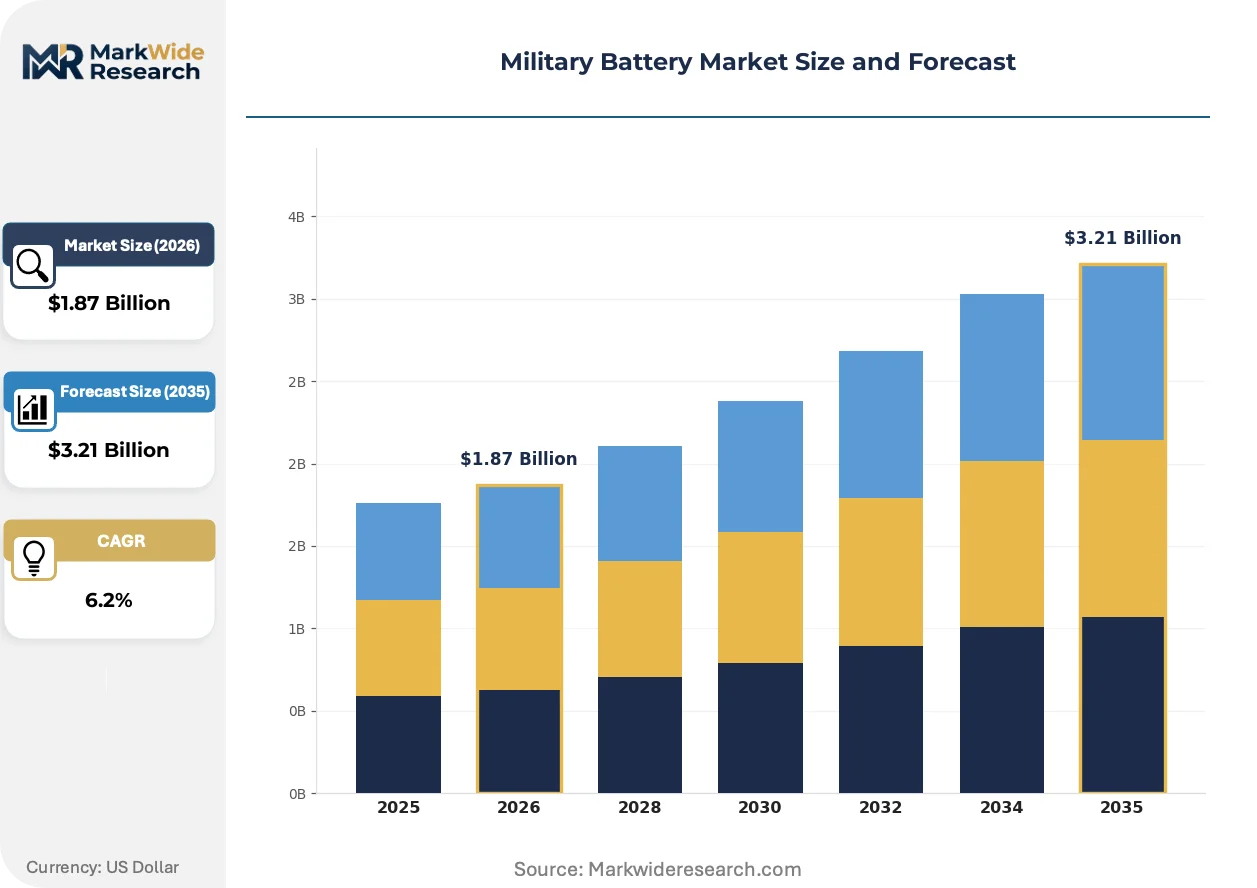
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $3.21 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead Acid, Silver Zinc, Alkaline Application: Communication Equipment, Surveillance Systems, Weapon Systems, Unmanned Vehicles, Navigation Devices Deployment: Land Operations, Aerial Missions, Naval Operations, Space Systems End User: Defense Contractors, Military Forces, Government Agencies, Tactical Units |
| Companies Covered | GS Yuasa Corporation, Bren-Tronics, EnerSys, Panasonic Holdings Corporation, Exide Technologies, Saft, Ultralife Corporation, LG Energy Solution, EaglePicher Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Battery Market Strategic Shifts & Innovations
Silicon-anode chemistries and solid-state architectures are overtaking conventional graphite-based lithium-ion in defense procurement specifications. These material shifts are compressing qualification cycles while enabling mission profiles previously impossible with legacy energy storage.
Silicon nanowire anode formulations are overtaking graphite in dismounted soldier power systems. The US Army's Soldier Power program has accelerated adoption timelines from 18 to 9 months for field trials. This chemistry is compressing pack mass by 30% while maintaining cycle life under MIL-STD-810 thermal shock protocols.
REACH and the EU Green Deal's battery passport requirements are mandating full supply chain disclosure for cobalt, lithium, and nickel sourcing. European defense primes must now document extraction sites and carbon intensity metrics to qualify for NATO procurement frameworks. Contractors are responding by securing offtake agreements with certified African and Australian mining operations rather than spot-market purchasing.
Outcome-based power service contracts are displacing unit hardware sales in unmanned vehicle programs. The US Navy's Medium Unmanned Surface Vehicle program now specifies energy availability per mission hour rather than battery pack procurement. This model concentrates vendor risk on cell degradation performance while transferring operational flexibility to fleet managers.
Military Battery Market Segmentation
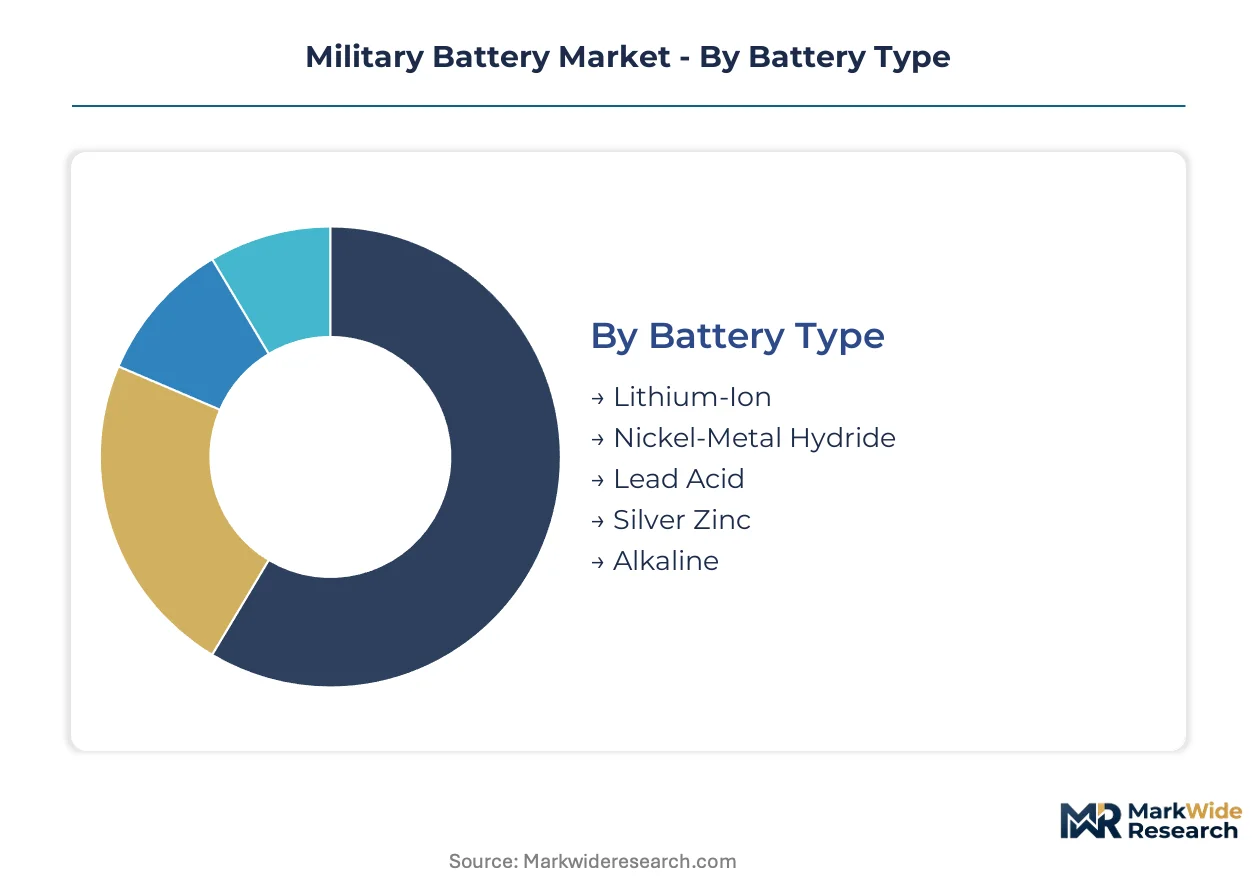
Military battery procurement diverges sharply between standalone power systems and embedded architectures. Commanders specify voltage buses, thermal envelopes, and cycle life thresholds that reshape how segments compete for program dollars.
Battery Type:
Integration depth separates chemistry families—lithium-ion and silver zinc embed deeply into platform designs, while alkaline and lead acid remain field-swappable commodities.
- Lithium-Ion:Graphite-silicon composite anodes paired with nickel-cobalt-aluminum cathodes deliver 250-300 Wh/kg under MIL-STD-810 shock protocols. The US Army's dismounted soldier programs and all unmanned vehicle procurements specify this chemistry exclusively due to energy density mandates for contested logistics.
- Silver Zinc:Silver oxide cathodes and zinc anodes achieve 150 Wh/kg with exceptional volumetric efficiency and zero thermal runaway risk. Naval torpedo propulsion and submarine emergency systems demand this chemistry where pressure tolerance at depth outweighs cost premiums.
- Nickel-Metal Hydride:Rare-earth lanthanide alloys store hydrogen at intermediate energy densities for legacy vehicle starting applications requiring cold-crank reliability without lithium thermal management.
- Lead Acid:Spongy lead negative plates and lead dioxide positive plates in sulfuric acid electrolyte persist in stationary backup and tactical vehicle starting roles where 24V bus compatibility trumps mass penalties.
- Alkaline:Zinc-manganese dioxide cells with potassium hydroxide electrolyte serve as disposable power for short-duration tactical electronics where recharging infrastructure is unavailable.
Volume placements concentrate in Lithium-Ion; the faster expansion belongs to Silver Zinc.
Application:
Platform electrification intensity varies—unmanned vehicles and weapon systems demand embedded battery engineering, while communication gear tolerates modular swap-in designs.
- Unmanned Vehicles:High-cycle lithium-ion packs with 500+ deep-discharge cycles power autonomous ground and aerial platforms. The US Navy's Medium Unmanned Surface Vehicle program specifies energy availability contracts rather than hardware procurement, shifting vendor risk to degradation performance.
- Weapon Systems:Pulse-power architectures discharge 100C rates for directed energy weapons and electromagnetic railgun capacitors. Thermal management systems must dissipate 40°C temperature spikes during firing sequences.
- Communication Equipment:Man-portable radios and satellite terminals prioritize standard form factors over energy density, accepting commercial 18650 cell configurations with military-grade sealing.
- Surveillance Systems:Extended-duration sensor arrays in unattended ground sensors favor lithium-thionyl chloride primary cells with 10-year shelf life.
- Navigation Devices:GPS receivers and inertial measurement units require stable voltage output across -40°C to +71°C operational envelopes.
Procurement volume clusters in Communication Equipment; Unmanned Vehicles are climbing the fastest.
Deployment:
Environmental severity escalates from land to space—each domain imposes distinct thermal, pressure, and radiation constraints on cell selection.
- Land Operations:Dismounted soldier power and ground vehicle systems face dust intrusion, vibration, and temperature cycling. The US Army's Soldier Power program has compressed field trial timelines for silicon-anode chemistries.
- Aerial Missions:Fixed-wing and rotary platforms demand gravimetric energy density above 200 Wh/kg with altitude depressurization tolerance. Unmanned aerial systems prioritize mass reduction for endurance extension.
- Naval Operations:Submerged pressure vessels and surface ship corrosion environments require hermetic sealing and salt-fog resistance. Silver-zinc dominates torpedo propulsion.
- Space Systems:Radiation-hardened lithium-ion with ceramic electrolyte separators withstand Van Allen belt exposure and vacuum outgassing constraints for satellite bus power.
Contract awards concentrate in Land Operations; Space Systems show steepest expansion trajectory.
End User:
Procurement authority fragmentation shapes specification authority—tactical units demand rapid fielding while defense contractors control platform integration decisions.
- Defense Contractors:Lockheed Martin, Raytheon, and Northrop Grumman specify battery subsystems for weapon platforms, driving qualification requirements through MIL-PRF-32052 pathways.
- Military Forces:Service branches issue operational requirements for soldier-worn power and vehicle starting, with the Defense Logistics Agency managing consolidated purchasing.
- Government Agencies:DARPA and national laboratories fund advanced chemistry development through Broad Agency Announcements.
- Tactical Units:Special operations formations procure rapid-fielding solutions outside standard acquisition timelines, favoring commercial-off-the-shelf lithium-ion with military packaging.
Spending authority concentrates in Defense Contractors; Tactical Units are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian cell manufacturing corridors while procurement authority clusters in North American and European defense ministries. This geographic split shapes qualification requirements and supply chain security mandates.
United States
Pentagon procurement drives lithium-ion demand for unmanned vehicles and dismounted soldier systems under contested logistics doctrine. The Defense Production Act mandates domestic supply chain requalification, compressing vendor onboarding timelines. Arizona and Nevada host emerging cathode material processing facilities serving prime contractors.
China
Cell manufacturing scale dominates global supply, though export control restrictions limit military-grade electrolyte and separator access. The country's national industrial regulator enforces dual-use technology transfer protocols. Jiangsu and Fujian provinces concentrate military-qualified production lines subject to Wassenaar Arrangement scrutiny.
Germany
Rheinmetall and Diehl Defence specify battery subsystems for NATO interoperable platforms, driving MIL-PRF-32052 adoption across European procurement. The EU Green Deal's battery passport requirements mandate cobalt and lithium sourcing disclosure. Bavaria hosts solid-state electrolyte research clusters advancing sulfide-based ceramic processing.
Japan
Industrial policy under METI prioritizes separator film and electrolyte salt production for allied defense supply security. Ceramic-coated separator manufacturing concentrates in Osaka and Kyoto industrial corridors. Domestic cell producers face capacity allocation tensions between automotive and defense qualification pathways.
South Korea
LG Energy Solution and Samsung SDI anchor military-grade cylindrical cell production for NATO unmanned vehicle programs. The MFDS regulates dual-use battery technology exports through strategic item classification. Gyeonggi Province hosts cathode active material plants subject to US Defense Production Act compliance audits.
Military Battery Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the military battery value chain. The market structure bifurcates between integrated cell manufacturers owning electrode coating and winding assets, and system integrators packaging commercial cells into MIL-STD-810 compliant enclosures. Three archetypes dominate: vertically integrated chemistry developers, modular pack assemblers, and software-enabled power service providers. Capacity expansion and strategic partnerships constitute the primary competitive moves, as qualification timelines and capital requirements elevate barriers to organic entry.
Within the integrated chemistry tier, GS Yuasa Corporation and Saft exemplify producers with in-house electrode formulation and military qualification track records. EnerSys anchors the North American manufacturing footprint, positioning its production lines for Pentagon supply security mandates. These three occupy positions spanning Asian, European, and North American regulatory jurisdictions, reflecting the geographic fragmentation of defense procurement authority.
| Leading Market Players |
|---|
| GS Yuasa Corporation |
| Bren-Tronics |
| EnerSys |
| Panasonic Holdings Corporation |
| Exide Technologies |
| Saft |
| Ultralife Corporation |
| LG Energy Solution |
| EaglePicher Technologies |
| Others |
Cost & Logistics Intelligence
Electrochemical engineer scarcity in the southwestern United States widens labor-cost spreads between premium MIL-PRF-32052 qualified packs and commodity-standard alternatives, compressing margins for mid-tier assemblers unable to absorb certification overhead.
Pricing Analysis
Margin tightening in standard-tier lithium-ion packs reflects cobalt price volatility from DRC mining disruptions and Chilean brine processing constraints. Three-tier pricing structure across premium, standard, and economy levels separates solid-state prototypes from graphite-silicon composites and legacy lead-acid field replacements. Price differentiation hinges on MIL-STD-810 qualification depth and volume scale. Tactical units exhibit highest price sensitivity due to rapid-fielding budget constraints, while defense contractors prioritize availability guarantees over unit cost.
Supply Chain Analysis
MIL-PRF-32052 qualification gating restricts separator film sourcing to Japanese and South Korean ceramic-coated producers, concentrating supply chain leverage in Osaka and Kyoto industrial corridors. Raw material dependencies center on DRC cobalt, Chilean lithium carbonate, and Australian spodumene concentrates. Single-source vulnerability for military-grade electrolyte salts creates tariff exposure under Wassenaar Arrangement dual-use controls. Distribution runs through Defense Logistics Agency consolidated purchasing with prime contractor subsystem integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state electrolyte manufacturing yield bottlenecks prop pricing power for qualified incumbents, constraining supply elasticity across the projection horizon.
For Market Incumbents: Anticipate cobalt supply disclosure mandates under EU Green Deal battery passport requirements by securing offtake agreements with certified African and Australian mining operations. Deepen backward integration into cathode active material processing in Arizona and Nevada to satisfy Defense Production Act domestic content thresholds. Prioritize AI-enabled battery management software development to capture power-as-a-service contract expansion in unmanned vehicle programs. For New Entrants and Emerging Players: Direct-to-defense-prime digital channels bypass traditional DLA procurement queues for rapid-fielding tactical unit contracts. White-space opportunity concentrates in soldier-worn silicon-anode power systems where US Army field trial timelines have compressed from 18 to 9 months. Target special operations procurement channels with commercial-off-the-shelf lithium-ion cells repackaged to MIL-STD-810 environmental specifications. For Investors and Strategic Acquirers: Re-rating potential sits with modular pack assemblers possessing software-defined battery management capabilities given the US Navy's shift to energy availability contracting. Long-term viability favors vendors with dual-use technology licenses spanning defense and grid-scale storage applications. Monitor solid-state electrolyte yield breakthroughs as inflection signal for next-generation cell manufacturing scale.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Cathode Material Processing | Arizona and Nevada facilities satisfy Defense Production Act supply security mandates for Pentagon procurement. |
| Software-Defined Battery Management Integration | AI-enabled state-of-health prediction enables power-as-a-service contracts shifting vendor risk to degradation performance. |
| Certified Raw Material Offtake Agreements | Documented cobalt and lithium sourcing secures EU Green Deal battery passport compliance for NATO interoperability. |
| Solid-State Electrolyte Manufacturing Scale-Up | Sulfide-based ceramic processing advancement unlocks energy density thresholds for contested logistics mission profiles. |
| Defense Logistics Agency Channel Partnership | Consolidated purchasing access reduces customer acquisition friction for unmanned vehicle program qualification. |
Research Approach
Document review covered Defense Production Act implementation guidance, MIL-PRF-32052 qualification protocols, and EU Green Deal critical raw materials framework documentation, complemented by interviews with electrochemical engineering directors at prime contractors, DLA procurement officers, and solid-state research leads at national laboratories. Secondary validation drew from SEC filings of listed battery manufacturers, customs trade data on lithium and cobalt imports, and FERC filings for grid-scale storage project pipelines. Bottom-up cell production estimates and top-down defense procurement budget analysis were triangulated.
Historical shipment data was cross-referenced against expert panel input from NATO standardization offices and service branch power system program managers. Segmentation modeling spanned chemistry family, platform application, deployment domain, and end-user procurement authority across the analysis window. CAGRs were derived from volume-weighted average growth trajectories incorporating unmanned vehicle fleet expansion rates and soldier system modernization cycle timing. Forecast inputs included contested logistics doctrine adoption curves and solid-state manufacturing yield improvement assumptions.
Inputs from Defense Logistics Agency contract award databases and prime contractor subcontractor disclosures were available through the study window; gaps in classified program specifications introduce uncertainty bands around directed energy weapon pulse-power demand estimates. Forecasts reflect documented assumptions regarding lithium supply chain requalification timelines and Wassenaar Arrangement control list revisions. A model refresh is warranted upon material change in solid-state electrolyte commercial yield thresholds or Defense Production Act geographic sourcing requirement expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Solid-State Car Battery Market
Batteries
Nimh Battery Market
Batteries
Stretchable Battery Market
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
Europe Industrial Battery Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
Lead Acid Battery Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Vanadium Redox Batteries Market
Batteries
Lithium-Based Battery Charger Market
Batteries
Proton Battery Market
Batteries
India Rechargeable Battery Market
Batteries
Battery Diagnostics and Repair Market
Batteries
Rear Rack Battery Market
Batteries
Lead Carbon Battery Market
Batteries
South America Primary Battery Market