
 Lithium Carbon Monofluoride Battery Market | 2026-2036
Lithium Carbon Monofluoride Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Carbon Monofluoride Battery Market Insights
Defense contractors and aerospace integrators are unwinding their historical reliance on silver oxide and alkaline reserve power systems, redirecting procurement specifications toward lithium carbon monofluoride cells for extended shelf-life missions. Panasonic leverages its vertically integrated fluoropolymer supply chain to dominate cylindrical cell formats for implantable medical applications. EaglePicher anchors long-cycle defense contracts through domestic U.S. manufacturing and ITAR-compliant production lines. Tadiran Batteries specializes in hermetic glass-to-metal seal technologies that sustain performance across extreme thermal cycling ranges.
Lithium carbon monofluoride batteries employ a cathode composed of carbon monofluoride (CFx, where x typically ranges 0.9 to 1.2) paired with a lithium metal anode, delivering nominal voltages near 2.8 V and specific energies exceeding 700 Wh/kg depending on discharge rate and cathode stoichiometry. These electrochemical systems serve applications demanding decade-scale storage stability without maintenance, including munitions fuzing, oceanographic sensors, and cardiac rhythm management devices. Primary Lithium cells command the dominant revenue share given their irreversible chemistry aligns with single-use military and medical deployment models, while Specialty Lithium variants capture expanding margin pools in downhole drilling and subsea instrumentation where custom form factors justify premium pricing. The Application dimension shows Medical Devices outpacing Automotive Systems in absolute growth as neurostimulation and drug delivery implants multiply.
FDA device classification rules and EU MDR technical documentation requirements shape electrode material biocompatibility testing protocols, while REACH restrictions on per- and polyfluoroalkyl substances are pressuring CFx precursor sourcing strategies. Japan's METI administers industrial battery safety standards through JIS C 8715 that govern transport and handling of lithium primary cells in densely populated manufacturing corridors. Stakeholders must monitor evolving fluorochemical regulatory thresholds across multiple jurisdictions while calibrating cathode stoichiometry investments against emerging solid-state alternatives.
Market Dynamics
Defense procurement offices across NATO member states are retiring silver oxide specifications for munitions fuzing and emergency beacon systems, redirecting multi-year contracts toward lithium carbon monofluoride chemistries that deliver shelf lives exceeding twenty years without voltage degradation.
Growth Catalysts
- EU Battery Regulation traceability mandates:Material passport requirements for fluorinated compounds are accelerating qualified supplier consolidation among medical device OEMs seeking REACH-compliant CFx cathode sources.
- Japan and South Korea precision manufacturing clusters:Deepened subcontracting networks for implantable neurostimulators and oceanographic sensors are concentrating demand for hermetic cylindrical cell formats.
- Cardiac rhythm management device multiplication:FDA 510(k) clearance pathways for next-generation pacemakers and drug delivery pumps are expanding addressable volumes for primary lithium cells with decade-scale stability.
Market Restraints
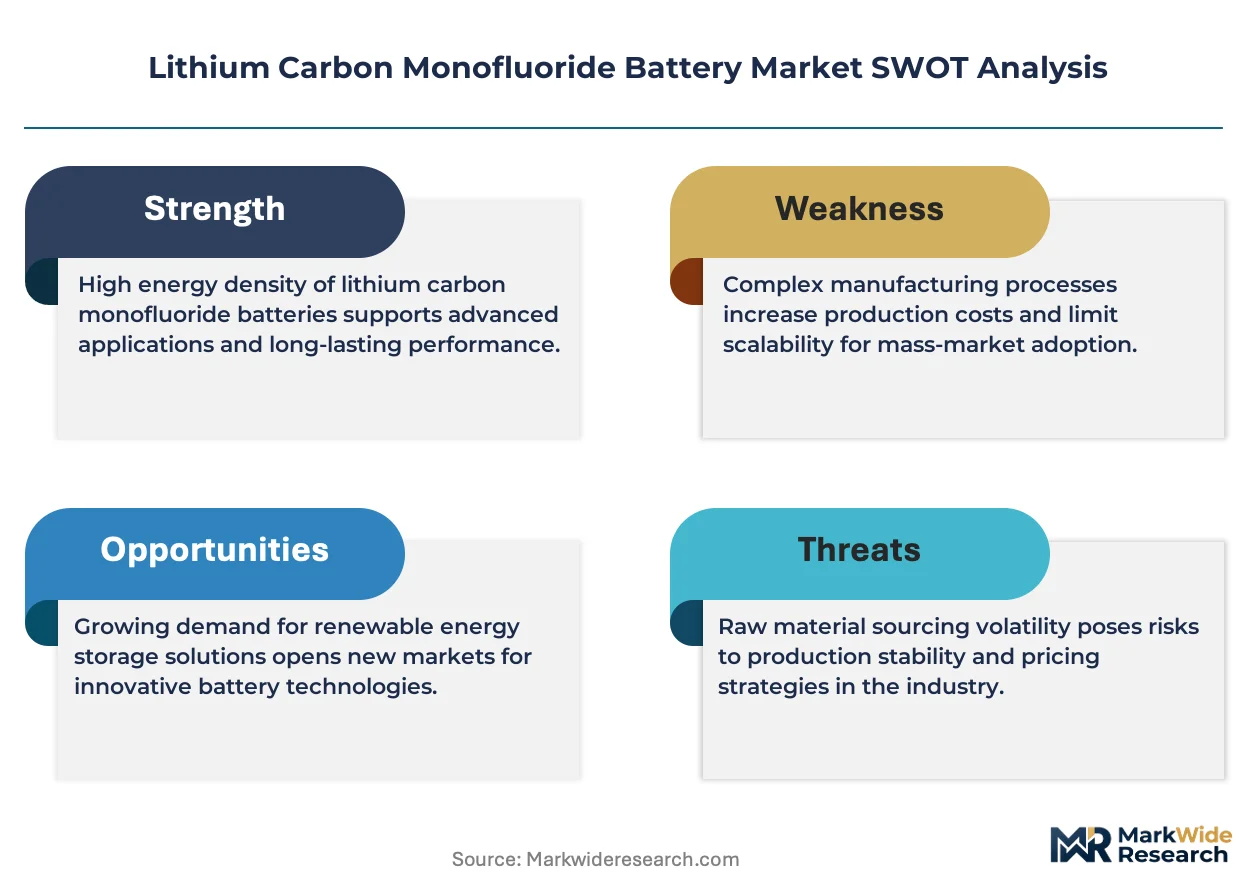
- Fluoropolymer precursor cost volatility:Feedstock concentration among Japanese and Chinese fluorochemical producers creates input price exposure for cathode material fabricators.
- Substitution threat from solid-state lithium metal:Emerging thin-film solid electrolyte architectures promise comparable energy density with rechargeable economics, pressuring irreversible primary cell positioning in premium medical applications.
- ITAR and EAR export control friction:U.S. State Department licensing requirements for defense-grade battery systems constrain supplier diversification for allied nation munitions programs.
Strategic Opportunities
- Downhole drilling instrumentation in Permian and North Sea basins:Custom form factor contracts for high-temperature lithium primary cells command margin premiums above standard cylindrical configurations.
- Japan METI industrial battery safety standard harmonization:JIS C 8715 alignment with UN 38.3 transport protocols reduces certification burden for manufacturers serving dense East Asian manufacturing corridors.
- Convergence of wireless power harvesting with ultra-low-power microcontrollers:Hybrid energy architectures combining CFx cells with thermoelectric or piezoelectric scavenging extend operational life in unattended subsea sensor networks.
Industry Challenges
- Hermetic glass-to-metal seal engineering talent scarcity:Specialized metallurgists capable of sustaining helium leak rates below 1×10⁻⁸ atm-cc/s across thermal cycling ranges command compensation premiums that compress contract margins.
- FDA biocompatibility testing timeline compression:ISO 10993 cytotoxicity and sensitization studies for electrode materials in implantable configurations extend product qualification cycles by eighteen to thirty-six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Carbon Monofluoride Battery Market |
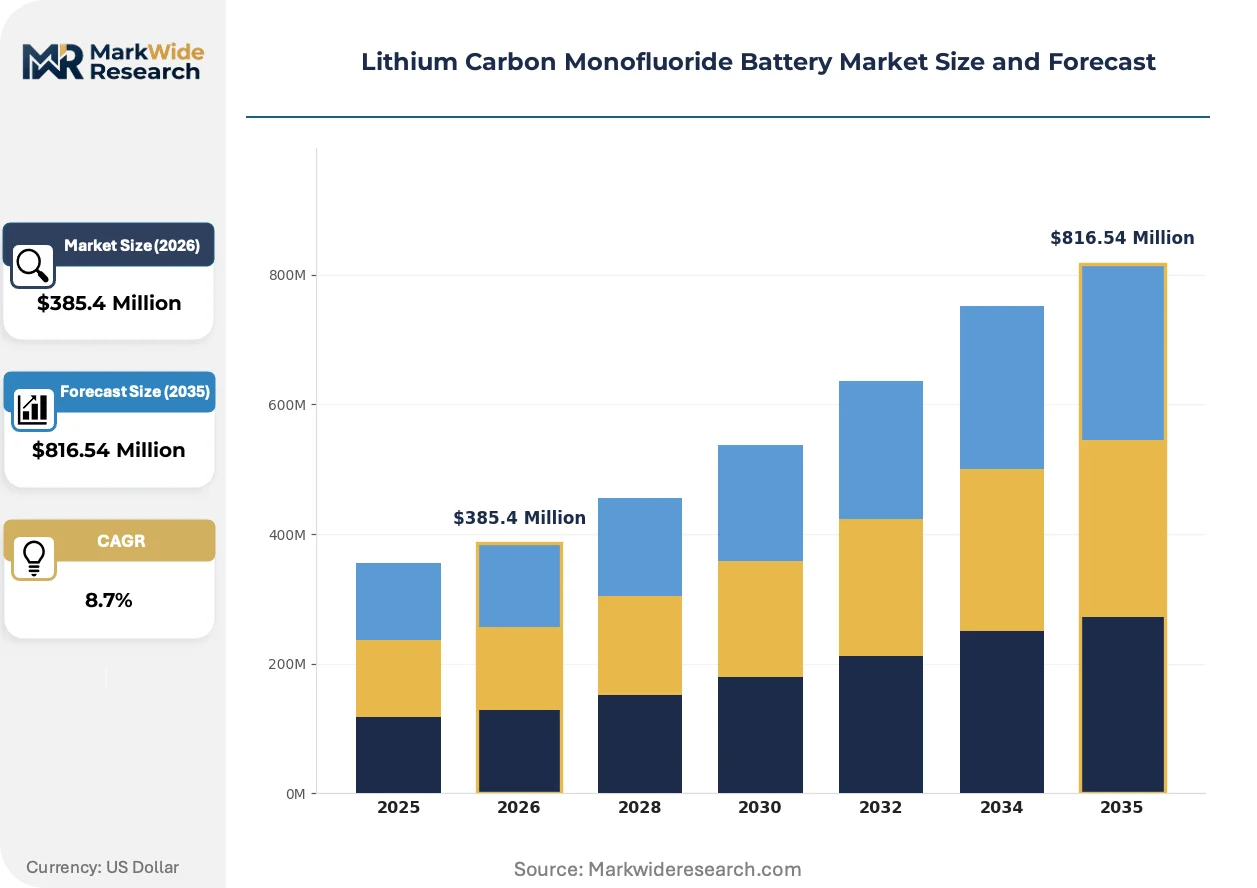
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Lithium, Rechargeable Lithium, Specialty Lithium, Lithium Ion Application: Consumer Electronics, Automotive Systems, Medical Devices, Industrial Equipment End User: Retail Consumers, OEMs, Manufacturers, Research Institutions Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Panasonic, STMicroelectronics, Dantona Industries, EaglePicher, Daikin, Tadiran Batteries, Saft, Toshiba Corporation, Duracell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Carbon Monofluoride Battery Market Trends and Innovations
Cathode stoichiometry optimization and cell format diversification are fragmenting the historically uniform CFx battery landscape into application-specific variants with divergent performance profiles and regulatory pathways.
Carbon monofluoride cathode formulations with variable fluorination levels (CF₀.₉ to CF₁.₂) are bifurcating into two distinct product branches. Munitions and aerospace integrators specify high-fluorination CF₁.₁–CF₁.₂ variants maximizing specific energy for single-discharge missions. Medical device OEMs prioritize CF₀.₉–CF₁.₀ stoichiometries that moderate voltage delay and improve pulse capability for neurostimulation applications. This technical divergence is compressing cross-application procurement standardization.
REACH restrictions on per- and polyfluoroalkyl substances are tightening precursor sourcing requirements for European medical device manufacturers. ECHA substance evaluation protocols now require full supply chain disclosure for fluorinated graphite feedstocks used in CFx synthesis. German and French battery assemblers are responding by qualifying alternative fluorination processes and securing long-term offtake agreements with Japanese fluoropolymer suppliers ahead of anticipated regulatory thresholds.
Defense procurement offices are consolidating battery purchasing through centralized NATO supply agreements rather than national stockpiling. This buyer concentration is displacing fragmented national tender processes with multi-year framework contracts specifying performance-based reliability metrics. The shift is most visible in U.S. and United Kingdom munitions programs, where prime contractors now source cells through qualified supplier lists managed by Defense Logistics Agency and Defence Equipment and Support respectively.
Lithium Carbon Monofluoride Battery Market Segmentation
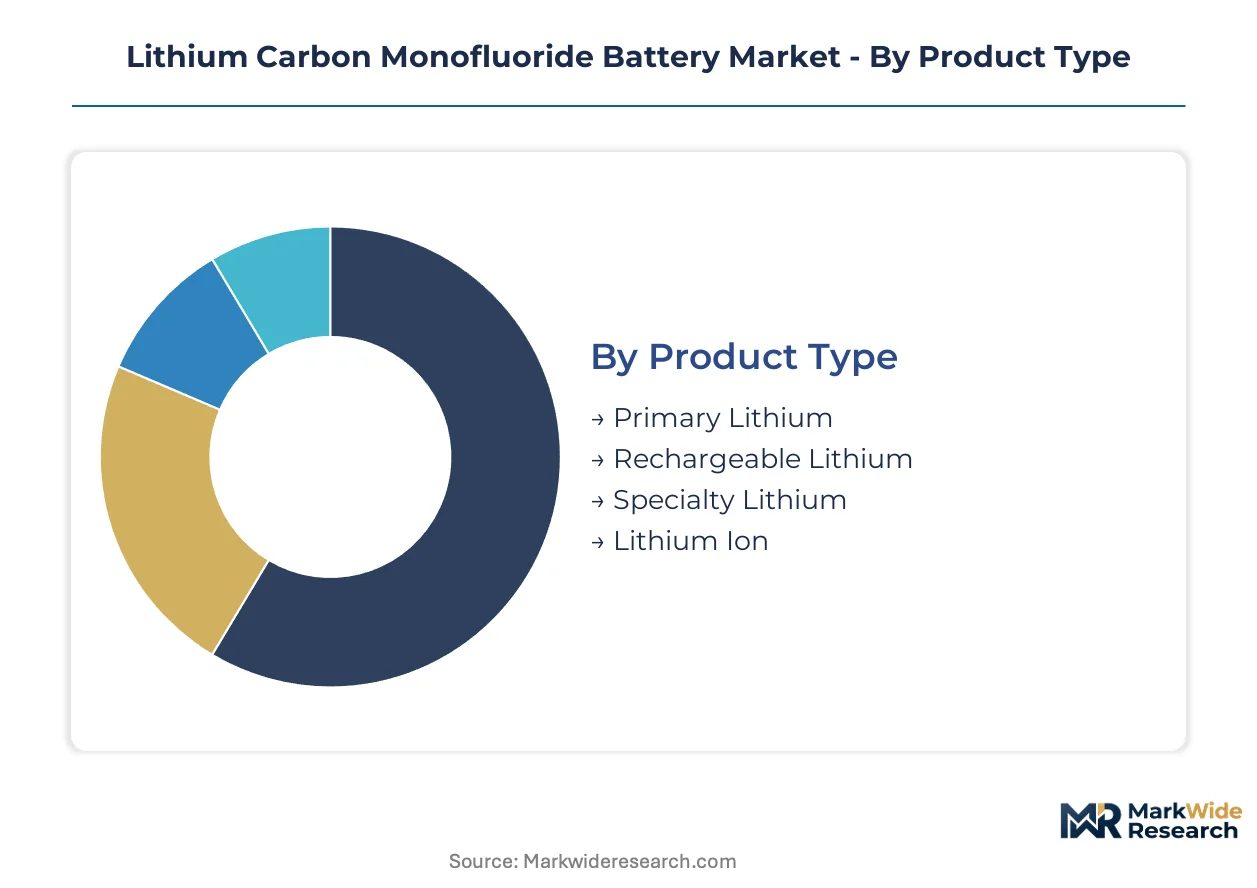
Lithium carbon monofluoride battery procurement fragments across irreversible primary systems, rechargeable architectures, and application-specific formats. Each segment faces distinct substitution pressures from solid-state alternatives and competing lithium chemistries that reshape supplier positioning.
Product Type:
Rechargeable lithium variants confront the most acute substitution threat as thin-film solid electrolyte architectures promise comparable energy density with cycle life economics.
- Primary Lithium:Irreversible electrochemistry employing lithium metal anodes and CFx cathodes delivers nominal voltages near 2.8 V with specific energies exceeding 700 Wh/kg. Defense munitions fuzing and oceanographic sensor networks in Japan and South Korea concentrate procurement for decade-scale storage stability without maintenance.
- Rechargeable Lithium:Secondary cell architectures with lithium metal or alloy anodes paired with intercalation cathodes enable multiple discharge cycles. Medical device OEMs in Germany and France are evaluating these systems against primary cells for neurostimulation applications where rechargeable economics could displace single-use models.
- Specialty Lithium:Custom form factor cells engineered for extreme temperature or pressure environments command premium pricing in downhole drilling instrumentation.
- Lithium Ion:Intercalation-based chemistry with graphite anodes and metal oxide cathodes serves as the benchmark substitution threat across consumer and industrial applications.
Primary lithium anchors the volume base while specialty lithium gains share at the steepest rate.
Application:
Medical device procurement stratifies across FDA 510(k) clearance pathways and EU MDR technical documentation requirements that shape electrode material qualification timelines.
- Medical Devices:Cardiac rhythm management implants, neurostimulators, and drug delivery pumps demand hermetic glass-to-metal seals sustaining helium leak rates below 1×10⁻⁸ atm-cc/s. FDA biocompatibility testing under ISO 10993 extends qualification cycles by eighteen to thirty-six months for electrode materials.
- Automotive Systems:Emergency beacon and telematics backup power applications specify extended shelf-life cells for collision event data recorders. U.S. NHTSA regulations and EU vehicle type-approval frameworks govern transport and handling requirements.
- Consumer Electronics:Memory backup and real-time clock functions in precision instruments specify compact cylindrical formats.
- Industrial Equipment:Subsea instrumentation and pipeline monitoring systems in the North Sea and Permian Basin deploy custom configurations.
Medical devices command the highest margin pool while industrial equipment expands most quickly.
End User:
OEM procurement consolidation through qualified supplier lists is displacing fragmented national tender processes with multi-year framework contracts.
- OEMs:Defense prime contractors and medical device manufacturers source cells through Defense Logistics Agency qualified supplier lists and centralized NATO supply agreements. Performance-based reliability metrics now govern multi-year contracts in U.S. and United Kingdom munitions programs.
- Manufacturers:Battery assemblers in East Asian manufacturing corridors face REACH precursor sourcing pressure and JIS C 8715 safety standard compliance requirements.
- Research Institutions:Oceanographic and aerospace laboratories specify custom prototypes for extreme environment validation.
- Retail Consumers:Limited direct procurement given the specialized nature of CFx chemistry applications.
OEMs dominate contract value while manufacturers absorb the steepest regulatory compliance burden.
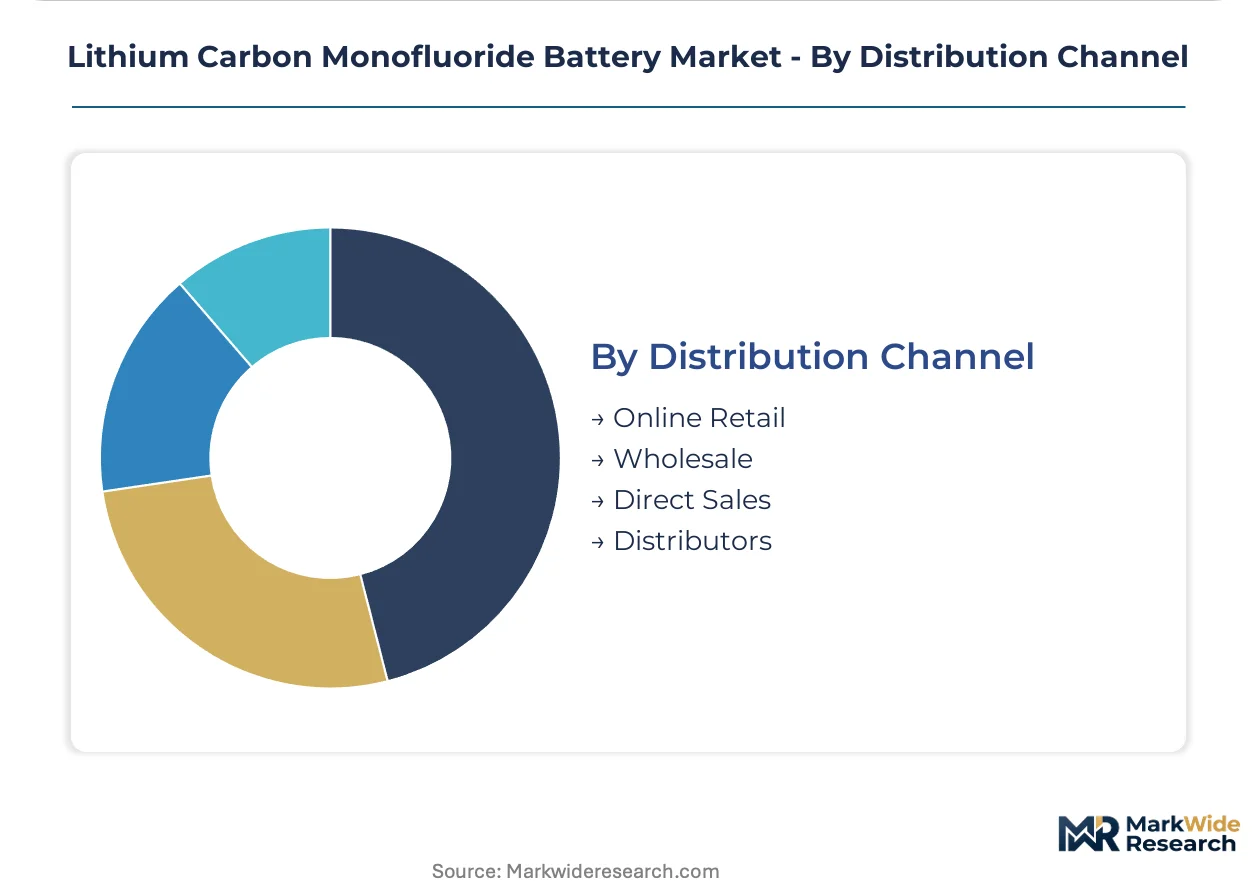
Distribution Channel:
ITAR and EAR export controls constrain supplier diversification for defense-grade systems, channeling procurement toward compliant distribution pathways.
- Direct Sales:Long-cycle defense contracts and medical device supply agreements route through manufacturer-direct relationships with ITAR-compliant production lines. EaglePicher and Tadiran Batteries anchor this channel through domestic U.S. manufacturing and hermetic seal expertise.
- Distributors:Authorized industrial distributors serve qualified supplier list requirements for NATO member state procurement offices.
- Wholesale:Bulk procurement for standard cylindrical formats in industrial instrumentation.
- Online Retail:Limited penetration given certification and handling requirements for lithium primary cells.
Direct sales captures the highest contract value while distributors serve the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles and Long Beach complex anchors North American lithium primary cell logistics, handling fluoropolymer precursors and finished battery shipments for defense and medical OEMs across the Pacific Rim trade corridor.
United States
Defense Logistics Agency procurement consolidation for munitions fuzing and emergency beacon systems drives demand concentration. ITAR compliance requirements and EAR export controls shape supplier qualification pathways for allied nation contracts. EaglePicher maintains ITAR-compliant production lines in domestic manufacturing corridors serving NATO framework agreements.
Japan
METI administers JIS C 8715 industrial battery safety standards governing transport and handling in densely populated manufacturing zones. Precision electronics subcontracting networks for implantable neurostimulators concentrate demand in the Kanto and Kansai industrial belts. Panasonic leverages vertically integrated fluoropolymer supply chains for cylindrical cell formats.
Germany
REACH restrictions on per- and polyfluoroalkyl substances pressure CFx precursor sourcing strategies for medical device OEMs. ECHA substance evaluation protocols now mandate full supply chain disclosure for fluorinated graphite feedstocks. Battery assemblers in Bavaria and Baden-Württemberg qualify alternative fluorination processes ahead of anticipated regulatory thresholds.
South Korea
Oceanographic sensor networks and subsea instrumentation programs multiply procurement for hermetic cylindrical cells with decade-scale stability. MFDS medical device regulations align with EU MDR technical documentation requirements for implantable applications. Manufacturing clusters in the Seoul Capital Area and Busan-Ulsan corridor deepen subcontracting relationships with Japanese fluorochemical suppliers.
United Kingdom
Defence Equipment and Support centralized procurement displaces fragmented national tender processes with multi-year framework contracts. Performance-based reliability metrics govern prime contractor sourcing for munitions programs. Hermetic glass-to-metal seal engineering capabilities concentrate in specialized metallurgy firms serving aerospace integrators.
Lithium Carbon Monofluoride Battery Market Competitive Landscape
Concentration sits with diversified electronics conglomerates and defense-specialized battery fabricators. The vendor base separates into three tiers: vertically integrated Japanese industrial groups controlling fluoropolymer supply chains, U.S.-based ITAR-compliant defense contractors anchoring long-cycle munitions contracts, and European specialists in hermetic sealing technologies. Competitive moves center on strategic partnerships with medical device OEMs and capacity expansion in East Asian manufacturing corridors.
Among Japanese industrial groups, Panasonic and Toshiba Corporation exemplify the vertically integrated archetype with captive fluorochemical supply chains. EaglePicher occupies a position within the U.S. defense-contractor tier, representing ITAR-compliant domestic manufacturing capabilities. Tadiran Batteries sits within the hermetic sealing specialist category, anchoring expertise in glass-to-metal seal technologies for extreme environment applications.
| Leading Market Players |
|---|
| Panasonic |
| STMicroelectronics |
| Dantona Industries |
| EaglePicher |
| Daikin |
| Tadiran Batteries |
| Saft |
| Toshiba Corporation |
| Duracell |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Japanese fluoropolymer producers and European medical device OEMs lock in cathode material access while anchoring price visibility against REACH regulatory volatility. These contracts insulate qualified suppliers from spot-market fluorochemical swings but concentrate procurement power among vertically integrated incumbents.
Pricing Analysis
Volume-discount tiering separates ITAR-certified defense contracts from standard industrial procurement, with hermetic glass-to-metal seal certification commanding substantial premiums over unqualified cylindrical formats. Price differentiation hinges on JIS C 8715 safety compliance and FDA biocompatibility testing completion, with German battery assemblers absorbing the steepest cost compression from ECHA substance disclosure mandates. Defense prime contractors exhibit lowest price sensitivity given mission-critical reliability requirements, while consumer electronics memory backup applications face persistent margin pressure from lithium-ion substitution.
Supply Chain Analysis
Inbound logistics costs through the Port of Los Angeles and Long Beach complex fluctuate with Pacific Rim container availability, directly impacting fluoropolymer precursor landed costs for domestic U.S. defense contractors. Manufacturing concentration in Japan, South Korea, and China feeds from fluorinated graphite feedstock dependencies and lithium metal anode supply. Single-source vulnerability concentrates in Japanese fluorochemical producers, while distribution runs through ITAR-compliant direct sales channels for munitions programs and authorized industrial distributors for medical OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized metallurgists capable of sustaining sub-atmospheric helium leak rates represent the critical capability gap constraining contract margins and qualification timelines across defense and medical applications.
For Market Incumbents: Shield long-cycle defense relationships through accelerated ITAR production line certification and captive fluoropolymer supply arrangements that neutralize REACH precursor volatility. Solid-state lithium metal architectures threaten irreversible primary cell positioning in premium neurostimulation applications, necessitating strategic R&D allocation toward hybrid energy architectures combining CFx cells with wireless power harvesting. For New Entrants and Emerging Players: Differentiate on custom form factor engineering for downhole drilling instrumentation in Permian and North Sea basins, where high-temperature performance specifications justify premium positioning absent from commoditized cylindrical markets. Target oceanographic sensor networks through hermetic sealing partnerships with established Japanese subcontractors, leveraging JIS C 8715 alignment to compress certification burden. For Investors and Strategic Acquirers: Capital is best deployed toward hermetic glass-to-metal seal specialists with proven thermal cycling performance and existing qualified supplier list relationships, as these assets anchor irreplaceable positioning across decade-scale storage applications. The long-term viability window favors acquisition targets with demonstrated FDA 510(k) pathway experience and EU MDR technical documentation capabilities. Monitor solid-state thin-film electrolyte commercialization timelines as the critical inflection signal for primary lithium obsolescence risk in rechargeable-addressable medical segments.| Strategic Initiative | Industry Significance |
|---|---|
| Hermetic Glass-to-Metal Seal Capacity Expansion | Addresses helium leak rate engineering scarcity constraining cardiac implant qualification timelines. |
| Backward Integration into Fluoropolymer Precursors | Mitigates REACH disclosure pressure and Japanese feedstock concentration for European assemblers. |
| FDA 510(k) Dual Submission Pathway | Accelerates neurostimulator and drug delivery pump electrode material approvals against solid-state substitution. |
| Defense Logistics Agency Qualified Supplier List Entry | Unlocks multi-year NATO framework contracts displacing fragmented national tender processes. |
| Hybrid Energy Architecture Development | Combines CFx cells with thermoelectric scavenging for unattended subsea sensor network extension. |
Research Methodology
A standing panel of defense procurement officers, biomedical engineers at cardiac device OEMs, fluoropolymer plant managers, and hermetic seal metallurgists provided ongoing calibration against secondary validation from FDA 510(k) filings, ECHA substance evaluation protocols, JIS C 8715 safety standards, and SEC disclosures from diversified battery manufacturers. Bottom-up cell format demand modeling and top-down fluorochemical feedstock supply analysis were cross-referenced for triangulation.
Consistency checks validated volume and value outputs against UN 38.3 transport certification databases and Defense Logistics Agency qualified supplier list expansions across the projection horizon. Segmentation dimensions modeled include product type irreversibility, application-specific hermetic requirements, end-user procurement consolidation patterns, and geographic regulatory cluster alignment. CAGRs were derived from defense contract award trajectories and medical device implant procedure growth curves, with cathode stoichiometry investment cycles and solid-state patent filing velocity serving as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained NATO munitions procurement continuity, REACH regulatory threshold stability, and hermetic seal engineering pipeline replenishment would require recalibration. Forecasts reflect documented assumptions regarding fluoropolymer precursor supply concentration and thin-film solid electrolyte commercialization timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Seawater Battery Market
Batteries
Middle-East Battery Market
Batteries
South Korea Rechargeable Battery Market
Batteries
Deep Cycle Battery Market
Batteries
Marine Low-Voltage Battery Market
Batteries
Yacht Battery Market
Batteries
Breathing Battery Market
Batteries
Residential Battery Market
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market
Batteries
North Africa Battery Market
Batteries
Tubular Batteries Market
Batteries
Iron Salt Battery Market
Batteries
Advanced Batteries Market
Batteries
Middle East Rechargeable Battery Market
Batteries
Printed Batteries Market