
 Middle East and Africa Battery Market | 2026-2036
Middle East and Africa Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Battery Market Foresight
North African cell assembly capacity is shifting toward lithium-ion formats as Morocco and Egypt attract component suppliers with free-zone incentives. Exide Industries Ltd anchors its regional position through lead-acid dominance in automotive aftermarket channels across East Africa. Saft Groupe S.A. specializes in industrial nickel-cadmium systems for oil and gas installations in the Gulf. First National Battery Pty Ltd leverages its Southern African manufacturing footprint to compete in heavy-duty mining and commercial vehicle segments.
A battery is an electrochemical device comprising cathode, anode, electrolyte, and separator materials that converts stored chemical energy into electrical energy through reversible redox reactions, with energy density ranging from 30 Wh/kg for lead-acid formulations to over 250 Wh/kg for advanced lithium-ion chemistries. Its primary commercial purpose is to provide portable, backup, or cyclic power across transportation, electronics, and stationary infrastructure applications. Lithium-ion systems command the fastest expansion trajectory across the Middle East and Africa Battery Market as utility-scale solar pairing and electric bus pilots multiply. Lead-acid formats retain volume leadership in automotive starter and shallow-cycle industrial roles due to established recycling networks and lower upfront capital requirements. The above 1000Ah capacity tier captures concentrated margin pools from grid-scale energy storage systems and telecom backup installations.
Saudi Arabia's dual carbon goals and South Africa's NERSA licensing framework are reshaping procurement standards for grid-connected battery assets, while EMA-equivalent technical committees in the GCC coordinate thermal runaway testing protocols for imported lithium-ion packs. Compliance with these overlapping regimes determines market access eligibility for international suppliers and shapes local assembly investment timelines. Stakeholders must monitor how divergent certification requirements between Gulf standardization bodies and sub-Saharan national regulators affect cross-border supply chain configuration and warranty liability structures.
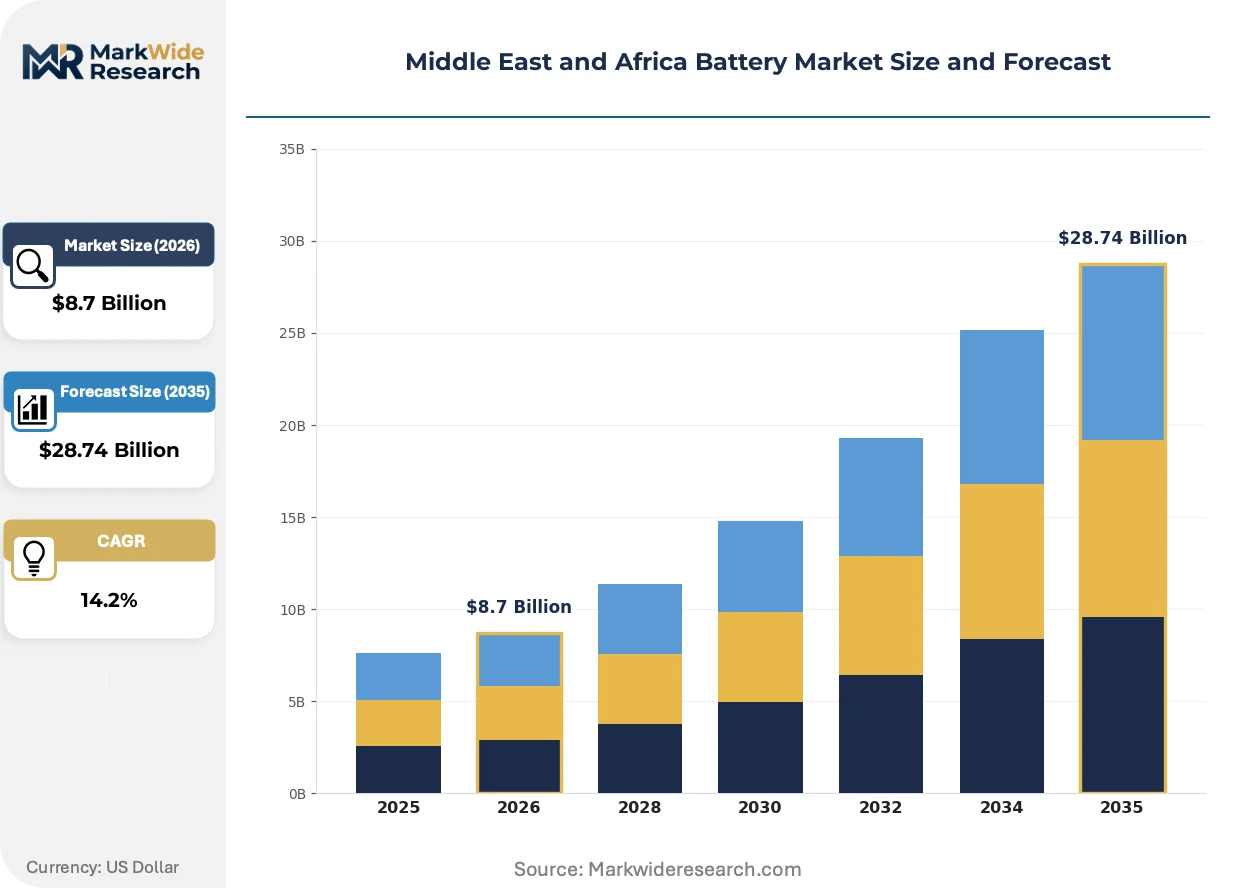
Market Dynamics
Grid intermittency from renewable assets across South Africa and Saudi Arabia is forcing procurement timelines to compress, tightening local content requirements and accelerating certification demands for imported lithium-ion packs.
Growth Catalysts
- Dual carbon targets:Saudi Arabia's domestic manufacturing mandates and Morocco's green hydrogen export strategies are pulling battery assembly investment into North African free zones.
- NERSA licensing:South Africa's energy regulator has streamlined grid-connected storage approvals, enabling utility-scale solar-plus-storage procurement at pace.
- Electric mobility pilots:GCC urban transit authorities are accelerating electric bus fleet trials, creating anchored demand for high-cycle lithium-ion chemistries.
Market Restraints
- Lithium carbonate volatility:Cathode material costs swing with Chilean and Australian concentrate supply, compressing margin predictability for regional assemblers.
- Cell import concentration:Pack producers across the Middle East and Africa depend on East Asian cell supply, exposing projects to shipping bottlenecks and currency mismatch.
- Thermal runaway testing gaps:EMA-equivalent GCC committees lack harmonized protocols with sub-Saharan national regulators, fragmenting certification pathways.
Strategic Opportunities
- Egyptian free-zone expansion:Component suppliers are relocating winding and electrolyte filling operations to Suez Canal Economic Zone to capture African market access.
- Telecom tower backup:Tower operators across Nigeria and Kenya are replacing diesel gensets with lithium-iron-phosphate systems, opening shallow-cycle volume.
- Green hydrogen storage:Moroccan electrolyzer projects require multi-hour battery buffering, creating demand for above-1000Ah capacity tiers.
Industry Challenges
- Electrochemical engineering talent:Cell characterization and pack thermal management expertise concentrates in South African and UAE technical institutes, creating recruitment bottlenecks for new entrants.
- Legacy lead-acid infrastructure:Established recycling networks and service channels for flooded batteries slow lithium-ion aftermarket penetration in East African commercial vehicle segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Battery Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead-Acid, Nickel-Cadmium, Flow Battery End User: Automotive, Consumer Electronics, Industrial, Renewable Energy Technology: Energy Storage Systems, Battery Management Systems, Electric Vehicle Batteries, Portable Batteries Capacity: Below 50Ah, 50Ah to 200Ah, 200Ah to 1000Ah, Above 1000Ah |
| Companies Covered | Middle East Battery Company (MEBCO), Exide Industries Ltd, First National Battery Pty Ltd, EnerSys, Amara Raja Batteries Ltd, Saft Groupe S.A., C&D Technologies Inc., East Penn Manufacturing Co. Inc., Leoch International Technology Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Battery Market Shifts & Advancements
Technology convergence and regulatory coordination are compressing product development cycles across the Middle East and Africa battery value chain, with implications for assembly localization and procurement models.
Solid-state electrolyte research is unifying safety and energy density targets previously traded off in liquid-electrolyte lithium-ion systems. Saudi industrial research centers are piloting sulfide-based ceramic separators for grid storage applications. This unifying trajectory is compressing the competitive window for incumbent liquid-electrolyte pack assemblers.
GCC standardization bodies are coordinating thermal runaway testing protocols for imported lithium-ion packs, narrowing the gap between Gulf and European safety benchmarks. Industrial pack importers must now submit to extended abuse testing before market entry. Telecom and oil and gas backup segments are responding by pre-qualifying suppliers against emerging regional standards.
Utility procurement is compressing vendor qualification timelines from 18 months to 9 months as renewable developers race to meet Saudi and South African grid connection deadlines. Engineering-procurement-construction contractors are displacing traditional distributor channels for projects above 10MWh. This compression is most visible in the GCC corridor where state-backed developers bundle storage with solar independent power producer tenders.
Middle East and Africa Battery Market Segmentation
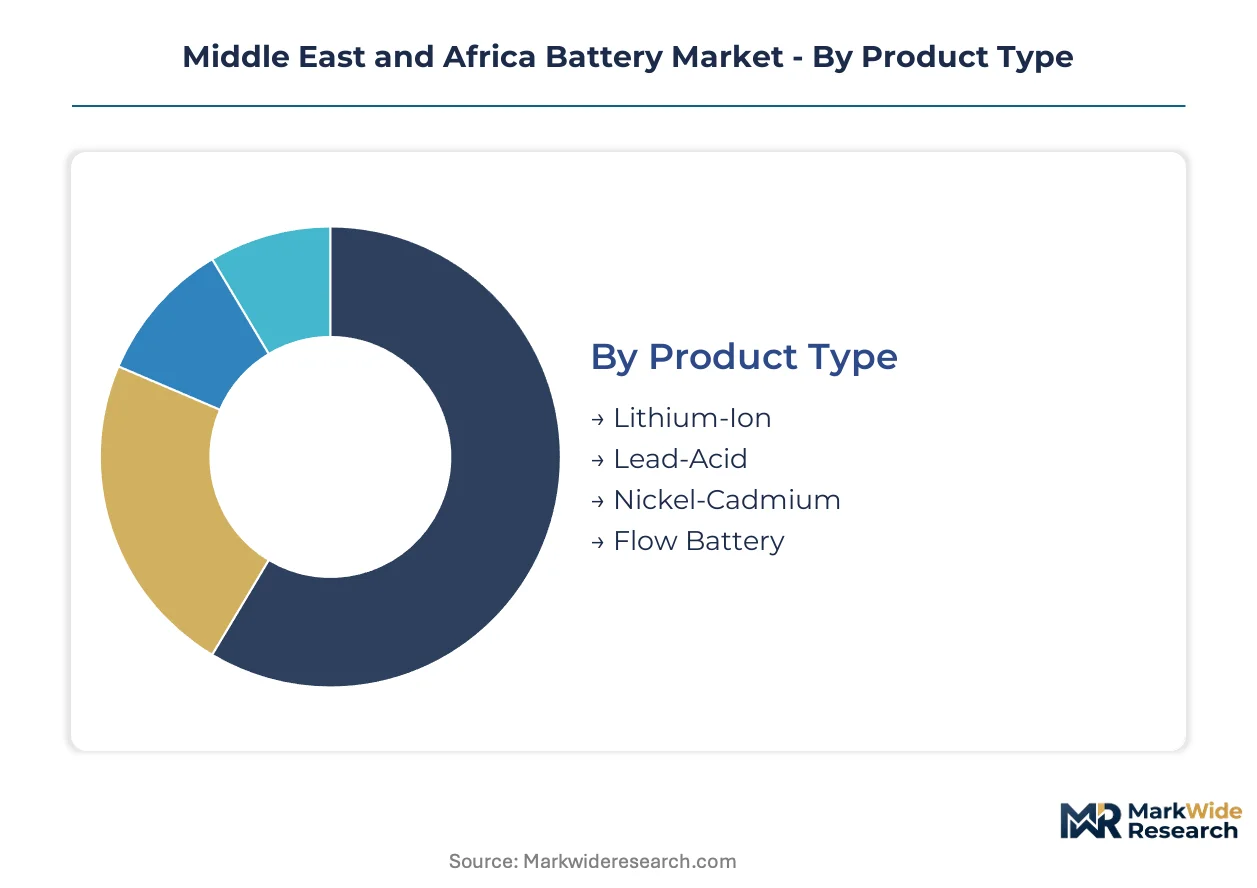
Segmentation in the Middle East and Africa Battery Market reveals how divergent certification requirements and local content mandates reshape procurement patterns across electrochemical formats. Understanding these divisions exposes where margin pools concentrate and which technology tiers face regulatory friction.
Product Type:
Lithium-ion packs require GCC thermal runaway testing and NERSA grid-connection approvals, while lead-acid formats navigate established recycling compliance regimes with lighter regulatory burden.
- Lithium-Ion:Advanced cathode-anode architectures with liquid or solid-state electrolyte configurations deliver energy densities exceeding 250 Wh/kg. Demand concentrates in Saudi utility-scale solar pairing and UAE electric bus pilots, where procurement timelines compress under dual carbon mandates. GCC standardization bodies now mandate extended abuse testing before market entry, extending vendor qualification cycles.
- Lead-Acid:Flooded and valve-regulated designs utilizing sulfuric acid electrolyte and lead dioxide cathodes remain entrenched in automotive starter applications. East African commercial vehicle channels favor this format due to established recycling networks and lower capital requirements, though lithium-ion aftermarket penetration is gradually displacing volume in premium segments.
- Nickel-Cadmium:Industrial sintered plate configurations tolerate extreme temperature cycling for oil and gas backup installations across the Gulf.
- Flow Battery:Vanadium redox and zinc-bromine chemistries target multi-hour grid buffering for Moroccan green hydrogen electrolyzer projects.
Lead-Acid sits at the top of the volume ranking, with Lithium-Ion climbing the fastest.
End User:
Cost tier differentiation separates premium industrial applications from price-sensitive consumer segments, with certification complexity scaling upward for grid-connected assets.
- Automotive:Starter-lighting-ignition batteries dominate aftermarket replacement cycles, while electric mobility pilots in GCC urban transit authorities create anchored demand for high-cycle lithium-ion chemistries. South African heavy-duty mining fleets sustain demand for deep-cycle formats.
- Consumer Electronics:Cylindrical and prismatic lithium-ion cells power portable devices across North African retail channels, with Egyptian free-zone assembly capturing regional distribution advantages.
- Industrial:Telecom tower operators across Nigeria and Kenya are replacing diesel gensets with lithium-iron-phosphate systems, opening shallow-cycle volume pools. Oil and gas installations in the Gulf require nickel-cadmium resilience for extreme temperature environments.
- Renewable Energy:Utility-scale solar-plus-storage procurement accelerates across South Africa under streamlined NERSA licensing, while Saudi state-backed developers bundle storage with independent power producer tenders above 10MWh.
Automotive commands the deepest volume base, with Renewable Energy expanding most quickly.
Technology:
Application-specific requirements determine whether battery management sophistication or raw cell supply dominates procurement decisions.
- Energy Storage Systems:Containerized lithium-ion configurations with integrated power conversion and thermal management target grid-scale deployment. Above-1000Ah capacity tiers capture concentrated margins from Saudi and Moroccan utility projects requiring multi-hour buffering.
- Battery Management Systems:Cell balancing, state-of-charge estimation, and thermal monitoring electronics differentiate pack performance and warranty terms. South African and UAE technical institutes concentrate electrochemical engineering talent for this layer.
- Electric Vehicle Batteries:High-nickel cathode formulations and silicon-anode innovations target GCC electric bus fleet trials, with procurement compressing from 18-month to 9-month vendor qualification timelines.
- Portable Batteries:Compact lithium-polymer and cylindrical formats serve consumer and light industrial mobility needs through established distributor channels.
Portable Batteries retains the widest shipment base, with Energy Storage Systems gaining share fastest.
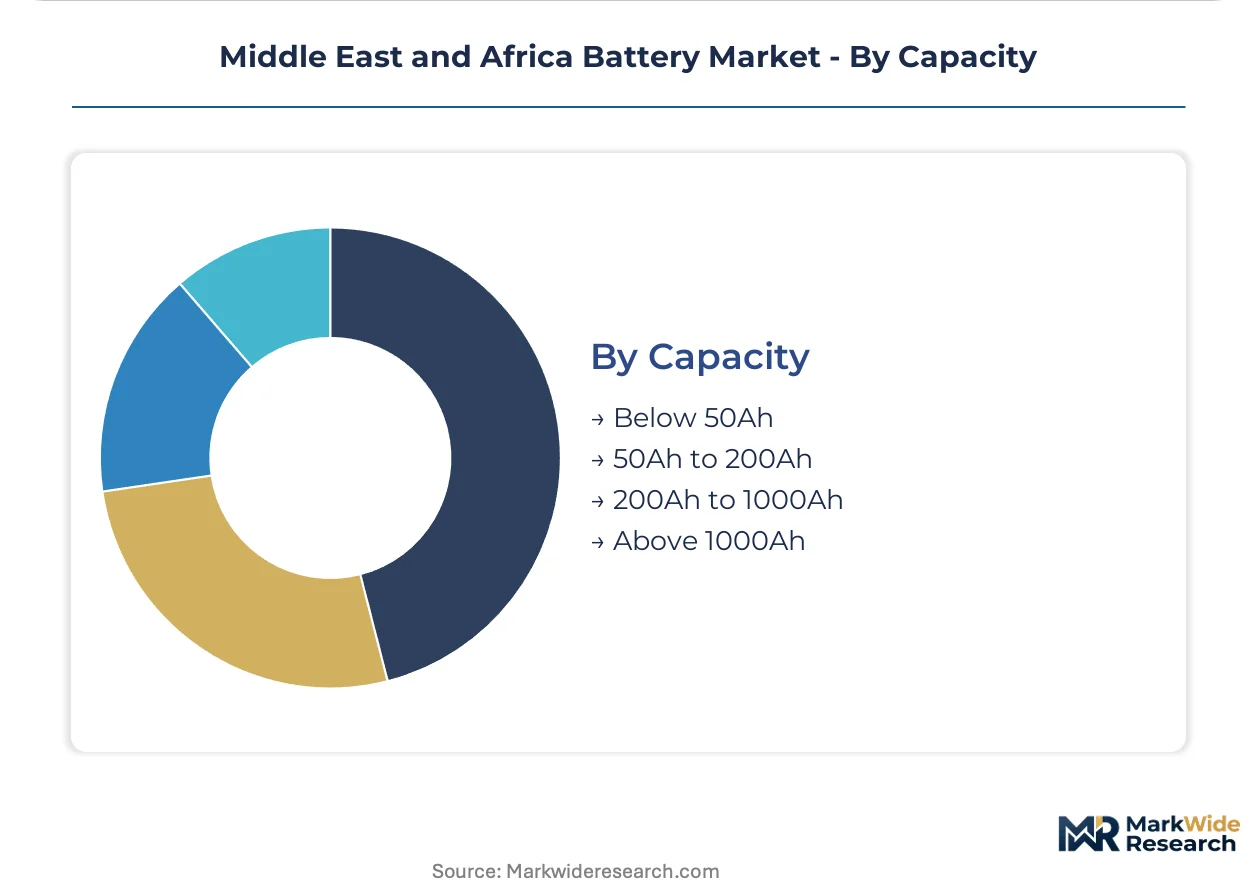
Capacity:
Volume scale inversely correlates with margin concentration, as sub-50Ah commoditization contrasts with above-1000Ah engineering intensity.
- Below 50Ah:Consumer electronics and automotive starter applications drive high-volume, lower-margin production with standardized form factors.
- 50Ah to 200Ah:Commercial vehicle and light industrial stationary applications occupy this mid-tier, with lead-acid and lithium-iron-phosphate formats competing on total cost of ownership.
- 200Ah to 1000Ah:C&I rooftop solar and telecom backup installations favor this range, where Egyptian free-zone component suppliers are relocating winding and electrolyte filling operations.
- Above 1000Ah:Grid-scale energy storage systems and large-format telecom backup capture the steepest margin pools. Moroccan electrolyzer projects and Saudi utility tenders concentrate procurement here, with engineering-procurement-construction contractors displacing traditional distributor channels.
Below 50Ah dominates shipment volumes, with Above 1000Ah showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's state-backed procurement outpaces South Africa's private-sector-driven deployment, yet both markets face converging certification bottlenecks for imported lithium-ion packs.
Saudi Arabia
Utility-scale solar-plus-storage tenders dominate procurement, with the national utility bundling battery assets into independent power producer agreements. The Saudi Standards, Metrology and Quality Organization mandates thermal runaway testing for all grid-connected lithium-ion systems. Industrial clusters in Jubail and Yanbu host emerging pack assembly operations serving Gulf Cooperation Council export markets.
South Africa
Renewable developers accelerate storage deployment to stabilize grid intermittency from wind and solar assets, particularly in the Northern Cape renewable energy zone. The National Energy Regulator of South Africa streamlined licensing frameworks for grid-connected battery assets. Manufacturing concentration in Gauteng province supplies heavy-duty mining and commercial vehicle segments with deep-cycle formats.
United Arab Emirates
Electric bus fleet trials in Dubai and Abu Dhabi create anchored demand for high-cycle lithium-ion chemistries. The Emirates Authority for Standardization and Metrology coordinates abuse testing protocols with Gulf standardization bodies. Jebel Ali free-zone assemblers import cells from East Asian suppliers for regional redistribution.
Morocco
Green hydrogen export strategies pull multi-hour battery buffering demand for electrolyzer projects in the Tangier-Mediterranean industrial zone. Moroccan regulators align technical standards with European benchmarks to facilitate cross-border equipment certification. Component suppliers relocate winding operations to Casablanca-Settat region to capture African market access.
Egypt
Telecom tower operators across the Nile Delta replace diesel gensets with lithium-iron-phosphate backup systems. The Suez Canal Economic Zone offers free-zone incentives for electrolyte filling and cell winding operations. Cairo-based distributors serve North African retail channels with prismatic lithium-ion formats assembled in Egyptian industrial parks.
Middle East and Africa Battery Market Competitive Landscape
East Asian cell producers anchor the upstream supply tier; regional pack assemblers and aftermarket distributors hold downstream positions. Market structure fragments across import-dependent pack producers, legacy lead-acid specialists, and emerging lithium-ion integrators. Three archetypes dominate: Gulf-based utility contractors, Southern African mining suppliers, and North African free-zone assemblers. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure cell supply agreements.
Within the regional pack assembly tier, Middle East Battery Company and First National Battery exemplify geographically anchored specialists serving distinct sub-markets. Exide Industries occupies a position spanning automotive aftermarket channels across multiple East African countries. These three companies represent the spectrum from Gulf utility-focused contractors to Southern African mining equipment suppliers.
| Leading Market Players |
|---|
| Middle East Battery Company (MEBCO) |
| Exide Industries Ltd |
| First National Battery Pty Ltd |
| EnerSys |
| Amara Raja Batteries Ltd |
| Saft Groupe S.A. |
| C&D Technologies Inc. |
| East Penn Manufacturing Co. Inc. |
| Leoch International Technology Ltd. |
| Others |
Supply & Pricing Matrix
Cell characterization expertise concentration in South African and UAE technical institutes widens labor-cost differentials between premium engineering-intensive packs and commodity-assembled formats, compressing margin spreads at the mid-tier.
Pricing Analysis
Capacity additions in Egyptian free zones are reshaping price floors for sub-200Ah lithium-iron-phosphate systems serving telecom backup. Three-tier pricing structure across premium certified, standard certified, and uncertified economy levels separates grid-connected utility assets from commercial vehicle replacements. Cost compression in the standard tier intensifies because Jebel Ali assemblers compete on cell import arbitrage. Tower operators across Nigeria exhibit highest price sensitivity, while Saudi state-backed developers prioritize thermal runaway certification over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with East Asian cathode active material suppliers feeding North African winding operations. Cell supply concentrates in China, South Korea, and Japan, while electrolyte salt production rests on Chilean and Australian lithium concentrate. Shipping bottlenecks through the Suez Canal expose projects to logistics chokepoint risk. Distribution runs through Cairo-based distributors for North African retail channels and engineering-procurement-construction contractors for GCC utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where Saudi dual carbon mandates and South African NERSA licensing acceleration compound procurement velocity for certified suppliers.
For Market Incumbents: Anticipate margin compression from Egyptian free-zone entrants by securing captive cathode supply agreements with East Asian producers. Invest in GCC thermal runaway pre-certification to compress vendor qualification timelines below nine months. Defend against solid-state electrolyte disruption by anchoring utility relationships through long-term service contracts.
For New Entrants and Emerging Players: NERSA licensing streamlining in South Africa opens a window for grid-connected storage specialists lacking Gulf market presence. Target telecom tower backup across Kenya and Nigeria as the most penetrable segment given diesel displacement mandates. Enter through Egyptian free-zone assembly partnerships to capture North African distribution access without direct cell manufacturing investment.
For Investors and Strategic Acquirers: Gulf-based engineering-procurement-construction contractors are the most active acquirer in this space, consolidating pack assembly capabilities to bundle storage with solar independent power producer tenders. Five-to-ten-year viability favors specialists with thermal management engineering depth and pre-qualified GCC certification status. Watch Moroccan electrolyzer project procurement timelines as the inflection signal for above-1000Ah capacity tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Supply | Captive lithium carbonate sourcing insulates Saudi assemblers from Chilean concentrate volatility. |
| GCC Thermal Runaway Pre-Certification | Early compliance with SASO mandates compresses vendor qualification timelines for grid-connected projects. |
| Egyptian Free-Zone Assembly Expansion | Suez Canal Economic Zone incentives capture North African telecom backup demand from Dubai redistributors. |
| Telecom Tower Diesel Displacement Partnerships | Lithium-iron-phosphate system supply contracts with Nigerian tower operators anchor shallow-cycle volume. |
| Solid-State Electrolyte Pilot Investment | Sulfide-based ceramic separator research at Saudi industrial centers unifies safety and energy density targets. |
Research Methodology
Bottom-up renewable energy project modeling reconciled against top-down cell import tracking forms the analytical core of this study. Primary interviews with utility planning officers, EPC contractors, tower operator procurement leads, and electrochemical engineering institute directors combined with secondary validation from customs records, NERSA licensing databases, and GCC standardization body filings. Top-down triangulation against IEA renewable deployment reports and FERC-equivalent grid connection disclosures validates bottom-up project aggregation.
Input-output matrices map cathode material flows through pack assembly to end-use deployment across electrochemical format, capacity tier, application segment, and regulatory jurisdiction dimensions. CAGRs derive from segment-level unit economics and procurement timeline compression factors. Forecast inputs incorporate lithium carbonate spot price trajectories and GCC local content mandate evolution across the projection horizon.
Revisions become necessary when East Asian cell supply disruptions, Suez Canal logistics interruptions, or divergence between Gulf and sub-Saharan thermal runaway protocols materialize. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
North Europe Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
48 Volt Battery System Market
Batteries
Electric Battery Market
Batteries
Electrolyte Solutions for Li-Ion Batteries Market
Batteries
Denmark Rechargeable Battery Market
Batteries
Semi-Solid Flow Battery Market
Batteries
Primary Lithium Battery Market
Batteries
Lead Carbon Battery Market
Batteries
Stretchable Battery Market
Batteries
Global Bio Compatible Battery Market
Batteries
India Lead-Acid Battery Market
Batteries
West Europe Battery Market
Batteries
Low Temperature Battery Market
Batteries
Aluminum Based Battery Market
Batteries
Forklift Battery Rental Market