
 Lithium-Based Battery Charger Market | 2026-2036
Lithium-Based Battery Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Based Battery Charger Market Insights
Direct-to-fleet distribution is reconfiguring how lithium-based battery charger manufacturers reach commercial buyers. Panasonic leverages its vertical integration into power electronics to sustain pricing power across automotive charging contracts. NOCO competes aggressively in the consumer segment through retail channel control and brand strength in portable jump-starter ecosystems. XTAR specializes in precision charging circuits for high-drain lithium-ion cells, occupying a defensible niche in flashlight and photography markets.
A lithium-based battery charger is an electrochemical energy restoration device engineered to deliver controlled voltage and current profiles—typically 3.6V to 4.2V per cell for Li-ion chemistries—while monitoring temperature thresholds and charge termination criteria to prevent dendrite formation or thermal runaway. Its primary purpose is to safely replenish rechargeable lithium-ion and lithium-polymer cells across consumer, automotive, and industrial applications where energy density and cycle life are critical. Smart charger architectures now dominate product development roadmaps, integrating microcontroller-based battery management systems that adjust charging curves in real time. Fast charger deployment for electric vehicles represents the fastest-growing end-user segment, though home use applications retain the largest installed base volume. Wired charging technology still anchors the majority of revenue, while wireless charging protocols are gaining traction in consumer electronics and sealed industrial environments.
The EU Battery Regulation and CE marking requirements under the EU Green Deal are reshaping charger efficiency mandates and recyclability disclosures for products entering European markets. In the United States, the Department of Energy and NHTSA influence automotive charging standards through efficiency benchmarking and vehicle safety integration protocols. China's SAMR enforces GB/T compatibility standards that determine market access for both domestic and imported charging equipment. Stakeholders must monitor how divergent certification regimes between major economies affect product platform standardization and manufacturing cost structures.
Market Dynamics
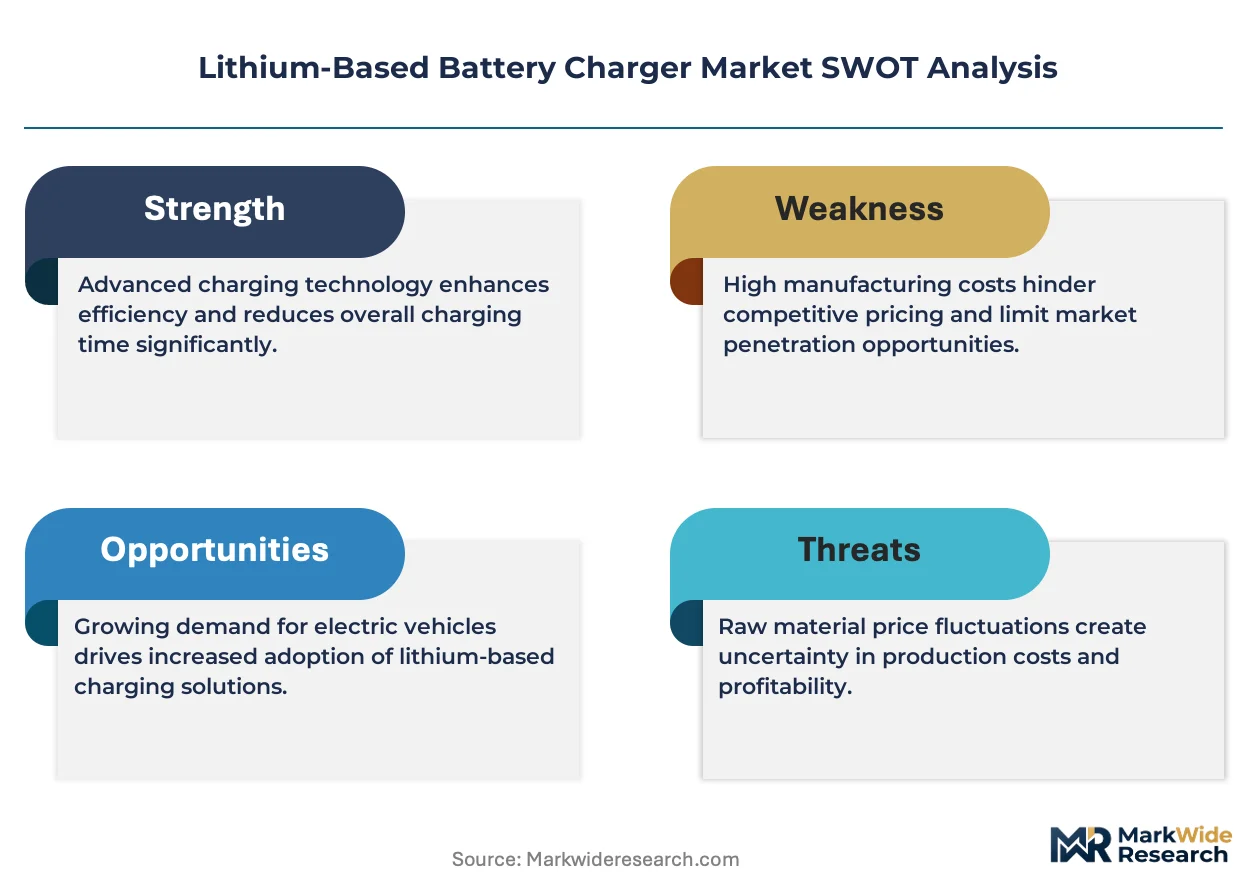
Fast-charging infrastructure deployment for electric vehicle fleets is compressing development cycles and forcing power electronics manufacturers to recalibrate thermal management architectures around silicon carbide substrates.
Growth Catalysts
- EU Battery Regulation compliance deadlines:Charger efficiency mandates under the EU Green Deal are compelling manufacturers to redesign conversion circuits, creating replacement demand across European installed bases.
- China's Guangdong manufacturing corridor concentration:Vertical integration of magnetic component suppliers with final assembly operations is shortening lead times for high-wattage charger modules.
- Silicon carbide MOSFET adoption:Wide-bandgap semiconductors are enabling 350kW+ charging stations while reducing thermal losses, accelerating fleet operator procurement timelines.
Market Restraints
- Neodymium and ferrite magnet supply concentration:Rare earth processing capacity in China's Jiangsu province creates input cost volatility for inductor manufacturers serving automotive charger contracts.
- GB/T standard interoperability friction:SAMR certification requirements for imported equipment create timeline uncertainty for European and North American suppliers entering Chinese markets.
- Legacy lead-acid charger substitution ceiling:Industrial forklift and marine applications retain substantial lead-acid installed bases where lithium charger retrofits face capital budget resistance.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic cell manufacturing incentives are creating parallel demand for matching charger infrastructure across Tamil Nadu and Gujarat industrial zones.
- Wireless charging protocol convergence:Qi and proprietary inductive standards are merging in sealed industrial environments where connector contamination risks dominate maintenance costs.
- Second-life battery integration:Stationary energy storage systems using retired EV cells require bidirectional charging architectures that incumbent suppliers have underdeveloped.
Industry Challenges
- Power electronics talent scarcity:Shortages of engineers with silicon carbide gate driver design experience are extending R&D timelines for next-generation fast charger platforms.
- Multi-jurisdiction certification complexity:Simultaneous CE marking, UL listing, and GB/T testing requirements are fragmenting product development resources across regional variants.
- Automotive OEM qualification cycles:Tier-1 supplier approval processes for onboard charger modules extend 18-24 months, compressing margin recovery windows before technology refresh.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Based Battery Charger Market |
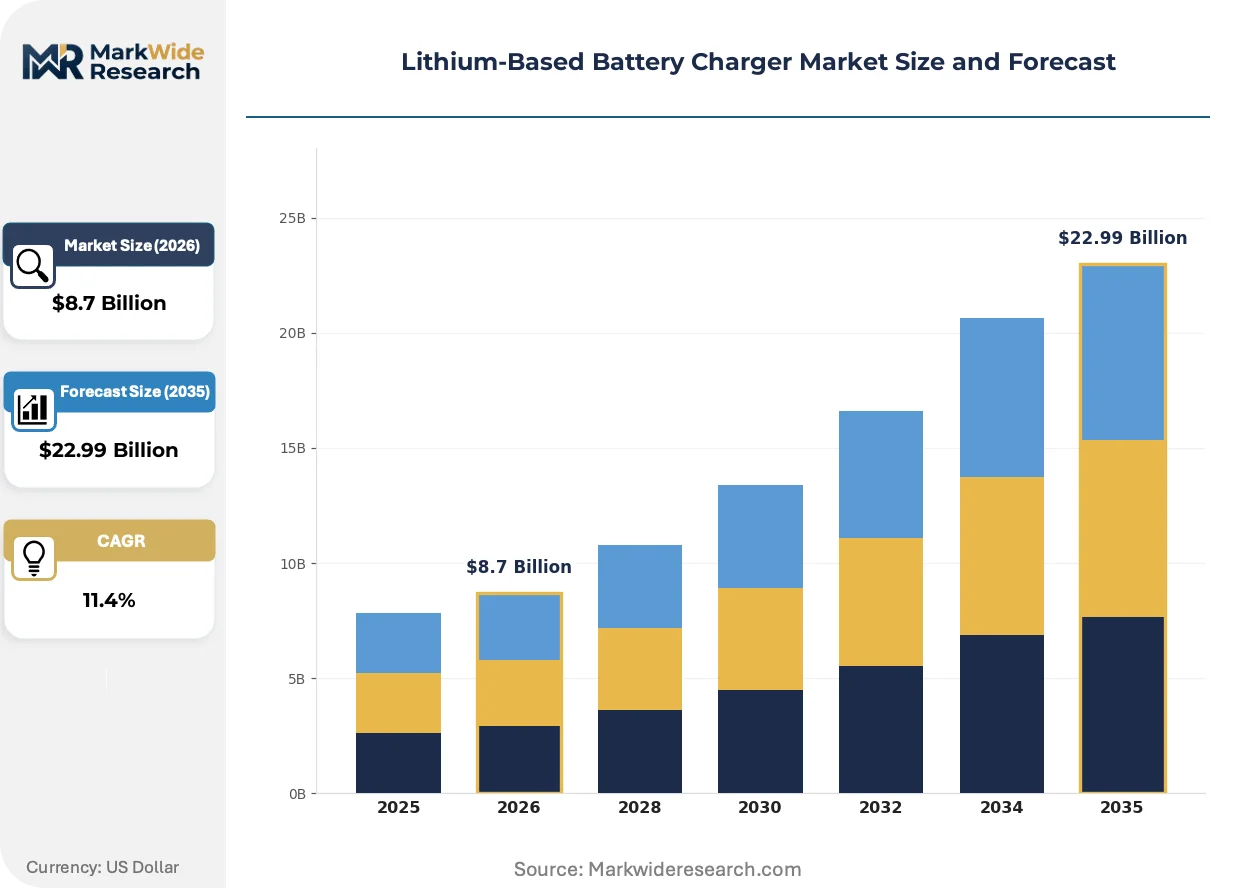
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fast Charger, Standard Charger, Solar Charger, Smart Charger End User: Consumer Electronics, Electric Vehicles, Industrial Equipment, Renewable Energy Systems Technology: Wired Charging, Wireless Charging, Adaptive Charging, Battery Management Systems Application: Home Use, Commercial Use, Automotive Charging, Portable Devices |
| Companies Covered | Panasonic, NOCO, CTEK, Energizer, EBL, La Crosse Technology, Optima Digital, Nitecore, XTAR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Based Battery Charger Market Trends and Innovations
Silicon carbide power semiconductors are restructuring competitive advantage around thermal performance rather than cost-per-watt metrics. Three converging developments are reshaping product roadmaps.
Silicon carbide MOSFETs and Schottky diodes are collapsing the thermal management overhead that constrained fast charger power density. Fleet operators in Germany and California are specifying 350kW+ stations for depot charging, forcing incumbent silicon IGBT designs into obsolescence. The technology is collapsing physical footprint requirements for multi-port charging hubs, enabling constrained urban site deployment.
REACH substance restrictions and RoHS recast directives are tightening disclosure requirements for power electronics sold into European markets. Manufacturers must now document full material content for magnetic components and conformal coatings, adding compliance overhead. Automotive charger suppliers with European assembly operations are restructuring supplier qualification protocols to preempt SVHC substitution risks.
Fleet operators are consolidating charging infrastructure procurement under direct manufacturer contracts, bypassing traditional electrical distributor channels. This channel compression is most visible in North American logistics and last-mile delivery verticals where total cost of ownership models dominate capital allocation. Service bundling and uptime guarantees are displacing equipment-only transactions in commercial segments.
Lithium-Based Battery Charger Market Segmentation
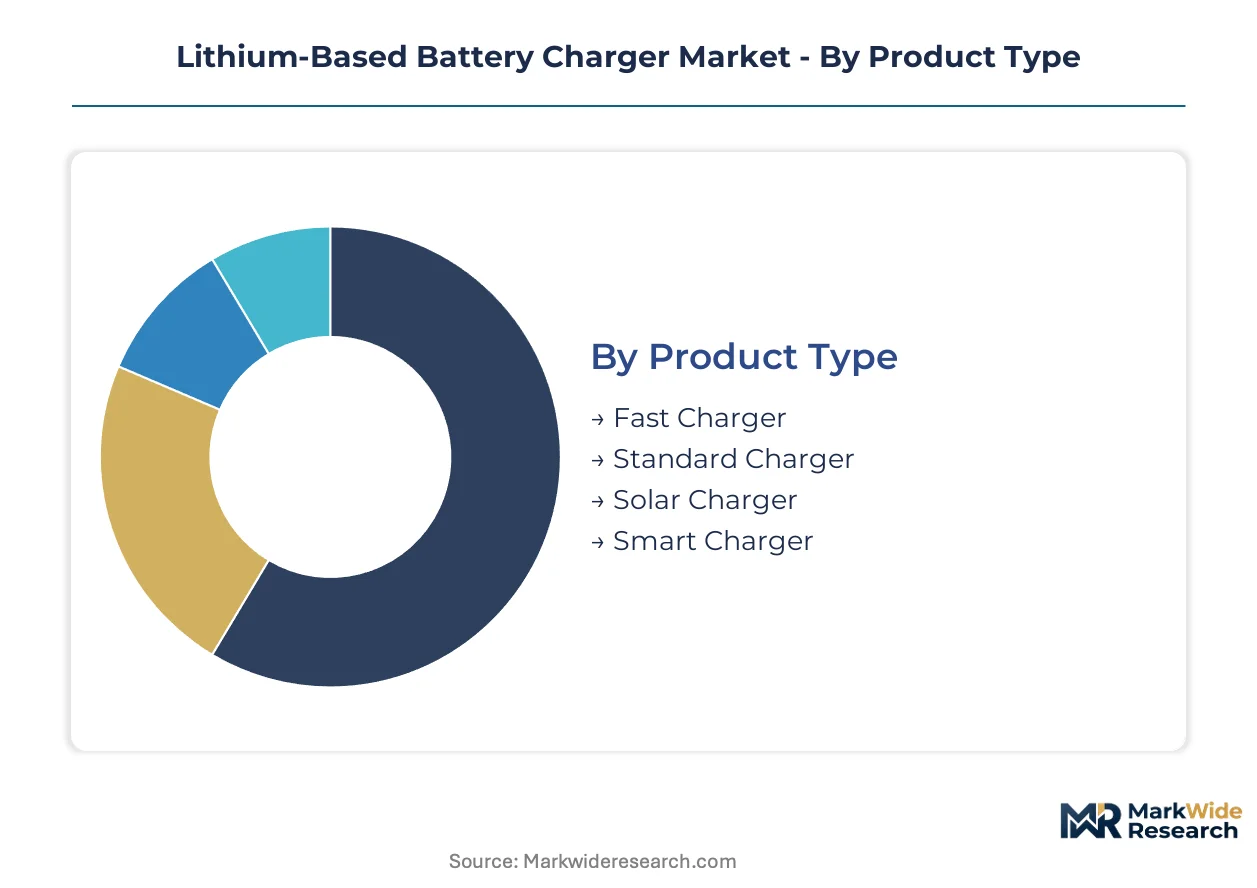
Segmentation in the lithium-based battery charger market exposes divergent replacement cycles and margin profiles across product architectures. Fast charger modules for electric vehicle fleets turn over every 7-10 years under heavy utilization, while consumer smart chargers cycle faster at 3-5 years as protocol standards evolve. Understanding these cadence differences shapes inventory planning and R&D resource allocation for manufacturers serving multiple verticals.
Product Type:
Cycle times vary dramatically across charger categories, with automotive-grade fast chargers engineered for decade-long service lives while consumer solar chargers face 2-3 year replacement windows in outdoor deployments.
- Fast Charger:High-wattage architectures delivering 150kW to 350kW+ for electric vehicle depot charging, built around silicon carbide power stages and liquid-cooled thermal management. Demand concentrates with German and Californian fleet operators specifying 350kW+ stations as battery capacities exceed 100kWh, though neodymium magnet supply constraints in China's Jiangsu province create input cost volatility for inductor manufacturers.
- Smart Charger:Microcontroller-based units with real-time voltage and temperature monitoring, cell balancing, and adaptive charge curve adjustment for lithium-ion and lithium-polymer chemistries. Procurement is accelerating among photography and flashlight enthusiasts in Guangdong's manufacturing corridor where precision charging circuits protect high-drain cell investments.
- Standard Charger:Fixed-profile charging circuits for consumer electronics and light industrial applications with basic CC-CV termination.
- Solar Charger:MPPT-equipped outdoor units for off-grid and portable power applications with wide input voltage tolerance.
Fast charger anchors the volume base while smart charger gains share at the steepest rate.
End User:
Cost tier differentiation separates capital-intensive automotive contracts from high-volume consumer electronics procurement, with industrial equipment occupying a middle tier of price-performance optimization.
- Electric Vehicles:Onboard and offboard charging systems for passenger cars, commercial trucks, and bus fleets, subject to NHTSA safety integration protocols in the United States and GB/T compatibility mandates from China's SAMR. German and Californian fleet operators are consolidating procurement under direct manufacturer contracts, bypassing traditional electrical distributor channels.
- Consumer Electronics:Chargers for smartphones, laptops, tablets, and wearables where Qi wireless protocols are merging with proprietary inductive standards in sealed environments.
- Industrial Equipment:Forklift, marine, and material handling chargers where lead-acid substitution faces capital budget resistance despite lithium's cycle life advantages.
- Renewable Energy Systems:Bidirectional chargers for stationary storage using retired EV cells, requiring architectures that incumbent suppliers have underdeveloped.
Consumer electronics sustains the widest installed base while electric vehicle charging climbs the fastest.
Technology:
Application requirements dictate technology selection, with wired architectures dominating where connector access is routine and wireless gaining ground where contamination risks drive maintenance costs.
- Wired Charging:Conductive power delivery through USB-C, proprietary barrel connectors, and high-current automotive interfaces, still anchoring the majority of revenue across all end-use segments.
- Wireless Charging:Inductive and resonant power transfer for consumer electronics and sealed industrial environments, with protocol convergence between Qi and proprietary standards reducing fragmentation.
- Adaptive Charging:Dynamic current and voltage adjustment based on cell state-of-health, temperature, and charge history.
- Battery Management Systems:Integrated monitoring and protection circuits that communicate with charger controllers to optimize charge profiles and prevent thermal runaway.
Wired charging holds the dominant revenue position while wireless charging expands most quickly in industrial sealing applications.
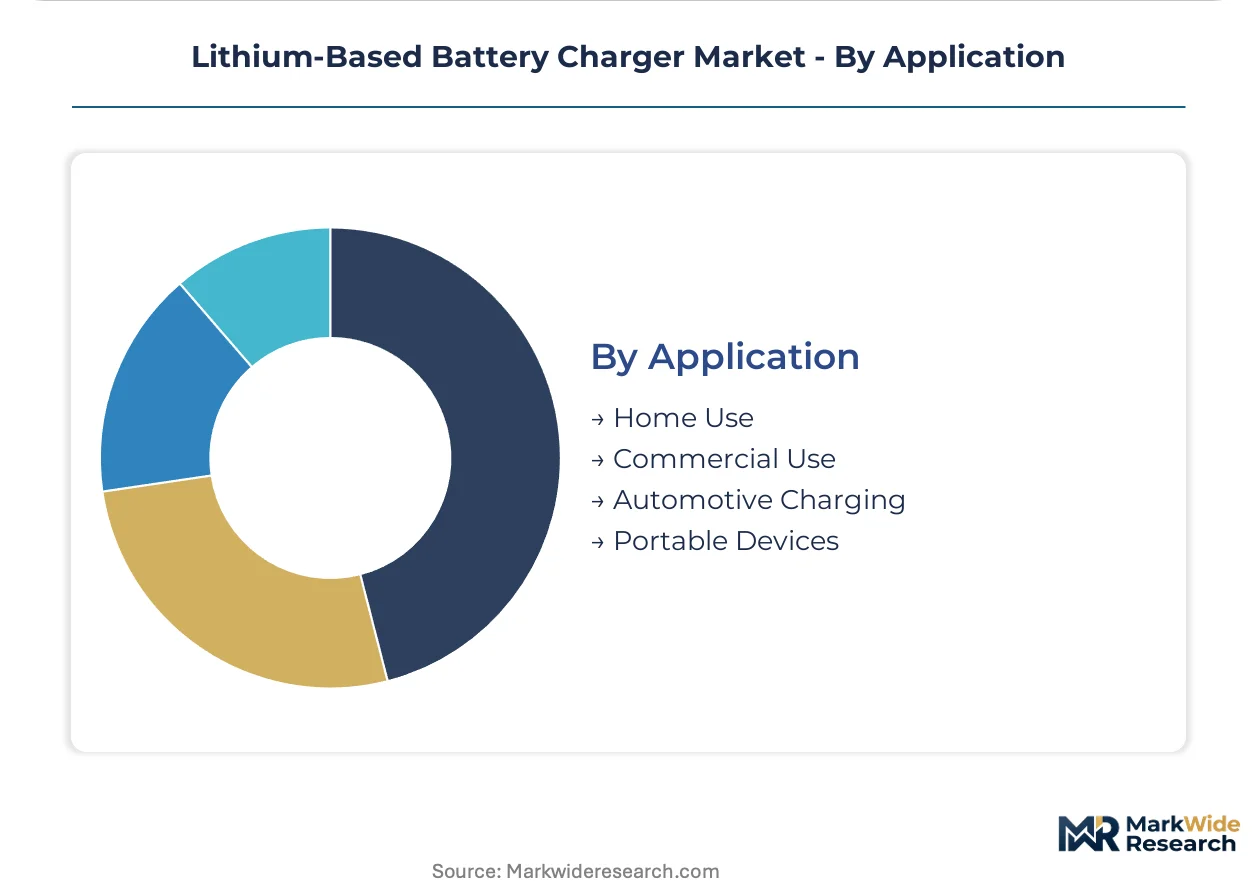
Application:
Customer type segmentation reveals divergent purchasing behaviors, with home users prioritizing convenience and commercial buyers emphasizing total cost of ownership and uptime guarantees.
- Automotive Charging:Depot, public, and residential infrastructure for electric vehicle energy replenishment, where 18-24 month OEM qualification cycles compress margin recovery windows before technology refresh.
- Home Use:Residential chargers for personal electronics and electric vehicles, retaining the largest installed base volume across all product categories.
- Commercial Use:Multi-port charging hubs for retail, hospitality, and workplace environments where footprint constraints favor collapsed physical designs enabled by silicon carbide substrates.
- Portable Devices:Mobile power solutions for field operations, emergency services, and outdoor recreation.
Home use maintains the broadest penetration while automotive charging shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's grid interconnect capacity underwrites Europe's role in electric vehicle charging infrastructure, while China's ultra-high voltage transmission corridors power the Guangdong manufacturing belt. India's western freight corridors and Germany's autobahn charging network anchor regional demand clusters.
United States
Californian fleet operators are consolidating depot charging procurement under direct manufacturer contracts for 350kW+ silicon carbide stations. NHTSA safety integration protocols and DOE efficiency benchmarking shape automotive charger qualification timelines. The Pacific Northwest hosts concentrated engineering talent for power electronics design.
Germany
Automotive OEMs are specifying liquid-cooled fast charger architectures for heavy-duty electric truck depots along the autobahn freight network. The EU Battery Regulation and CE marking requirements under the EU Green Deal mandate charger efficiency disclosures and recyclability documentation. Bavaria's industrial corridor hosts tier-1 supplier qualification centers for onboard charger modules.
China
Guangdong's manufacturing corridor has consolidated magnetic component suppliers with final assembly operations, shortening lead times for high-wattage charger modules. SAMR enforces GB/T compatibility standards that determine market access for imported charging equipment. Jiangsu province's rare earth processing capacity supplies neodymium magnets for automotive charger inductors.
India
Tamil Nadu and Gujarat industrial zones are scaling charger infrastructure to match domestic cell manufacturing incentives under the PLI scheme for advanced chemistry cells. The Central Electricity Authority influences grid interconnection standards for high-power charging stations. Maharashtra's automotive clusters are emerging as procurement centers for fleet electrification.
Japan
Chubu and Kansai regions maintain precision manufacturing capabilities for microcontroller-based battery management systems in smart chargers. METI oversees technical standards for bidirectional charging architectures integrating retired EV cells into stationary storage. Tokyo's metropolitan area drives consumer electronics charger demand with protocol evolution toward wireless inductive standards.
Lithium-Based Battery Charger Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in magnetic and semiconductor supply. The vendor base stratifies across three tiers: automotive-grade fast charger manufacturers with 18-24 month OEM qualification cycles, consumer electronics specialists with 2-3 year product refresh cadences, and industrial equipment suppliers bridging lead-acid substitution markets. Two dominant competitive moves are reshaping positioning: silicon carbide MOSFET adoption collapsing thermal management footprints, and direct-to-fleet distribution bypassing traditional electrical distributor channels.
Among Japanese electronics conglomerates, Panasonic exemplifies the vertically integrated platform archetype with captive power electronics production. Chinese precision charging specialists occupy defensible niches—XTAR anchors the high-drain lithium-ion cell segment for flashlight and photography markets. American consumer brands including NOCO represent retail channel control strategies in portable power ecosystems.
| Leading Market Players |
|---|
| Panasonic |
| NOCO |
| CTEK |
| Energizer |
| EBL |
| La Crosse Technology |
| Optima Digital |
| Nitecore |
| XTAR |
| Others |
Pricing and Supply Chain Analysis
The Port of Rotterdam's container throughput cost dynamics amplify pricing power for silicon carbide substrate suppliers concentrated in China's Guangdong corridor, compressing margins for European fast charger assemblers while enabling three-tier pricing stratification across automotive certification grades.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts for 350kW+ fast charger modules, with automotive OEMs extracting steeper concessions than fleet operators due to qualification cycle leverage. Price differentiation hinges on GB/T certification tier and silicon carbide MOSFET integration depth, with UL-listed automotive-grade units commanding premiums over industrial forklift retrofits. Cost compression in consumer smart chargers intensifies as Guangdong manufacturers consolidate magnetic component supply, squeezing photography and flashlight segment margins. Fleet operators show least price sensitivity due to total cost of ownership modeling, while residential home-use buyers prioritize unit economics over performance specifications.
Supply Chain Analysis
Upstream neodymium and ferrite magnet feedstock draws from China's Jiangsu province rare earth processing capacity, with silicon carbide wafer supply anchored in Japan and the United States. Raw material dependencies center on wide-bandgap semiconductor substrates, high-temperature magnetic cores, and liquid-cooled thermal interface materials. Single-source vulnerability in Jiangsu's rare earth refining creates input cost volatility for automotive inductor manufacturers. Distribution runs through direct-to-fleet manufacturer contracts in North America and tier-1 supplier qualification centers in Germany, bypassing traditional electrical distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, with silicon carbide fast charger deployment for electric vehicle fleets representing penetration tailwinds that will sustain double-digit expansion across the projection horizon.
For Market Incumbents: Build certification moats around simultaneous CE marking, UL listing, and GB/T compliance to preempt multi-jurisdiction testing fragmentation that extends rival R&D timelines. Secure captive supply of silicon carbide MOSFETs through backward integration into power electronics or long-term offtake agreements with Japanese substrate suppliers, insulating against wide-bandgap semiconductor allocation constraints that threaten automotive contract fulfillment. For New Entrants and Emerging Players: Pursue India's Tamil Nadu and Gujarat industrial zones where PLI scheme incentives for advanced chemistry cells create parallel charger infrastructure demand with limited incumbent penetration. Target second-life battery integration architectures for stationary storage systems, a bidirectional charging segment where established suppliers maintain underdeveloped product roadmaps. Lead with service-bundled uptime guarantees rather than equipment-only transactions to differentiate in fleet operator procurement. For Investors and Strategic Acquirers: Component specialists with silicon carbide gate driver design capabilities represent the most defensible acquisition archetype amid power electronics talent scarcity that extends development timelines. Long-term viability over a five-to-ten-year window rests on positioning for wireless charging protocol convergence in sealed industrial environments. Monitor GB/T standard interoperability friction as the inflection signal—resolution would unlock Chinese market access for European and North American equipment suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide MOSFET Integration | Enables 350kW+ charging stations while collapsing thermal management footprints for urban depot deployment. |
| Direct-to-Fleet Distribution Buildout | Bypasses electrical distributor channels where German and Californian logistics operators consolidate procurement. |
| Multi-Jurisdiction Certification Investment | Preempts CE marking, UL listing, and GB/T testing fragmentation that fragments product development resources. |
| Second-Life Battery Architecture Development | Captures bidirectional charging demand from stationary storage systems using retired EV cells. |
| Wireless Charging Protocol Convergence | Addresses connector contamination risks in sealed industrial environments where maintenance costs dominate. |
Research Methodology
Desk research of customs trade data, SEC filings from power electronics suppliers, and SAMR certification registries preceded structured interviews with Tier 1 automotive procurement directors, fleet charging infrastructure managers, and magnetic component manufacturing heads. Bottom-up shipment triangulation across fast charger module production volumes was cross-validated against top-down automotive OEM platform deployment schedules. Primary fieldwork with silicon carbide substrate suppliers and thermal management system designers informed technology adoption curve assumptions.
Fixed assumptions around EU Battery Regulation compliance deadlines and China's GB/T interoperability requirements anchored the analytical framework across the projection horizon, with silicon carbide adoption rates and fleet electrification penetration modeled as variable sensitivities. Segmentation dimensions included charger product architecture, end-use vertical, wired versus wireless technology protocol, and geographic regulatory cluster. CAGRs were derived from installed base replacement cycles and new deployment run-rates rather than extrapolated trend fitting. Forecast inputs incorporated neodymium magnet supply constraints from Jiangsu province and power electronics engineering talent availability.
Macroeconomic conditions sit as an overlay; deviation in electric vehicle sales trajectories, rare earth export restrictions, or semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and technology cost curves. Cross-checking against IEA electric vehicle outlook data and customs records for wide-bandgap semiconductor trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
Nanicl Battery Market
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
Nickel-Based Battery Charger Market
Batteries
Automotive Start-Stop Battery Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Global Industrial Lead Acid Battery Market
Batteries
Military Battery Market
Batteries
Electric Battery Market
Batteries
Sodium-Air Battery Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Portable Battery Powered Products Market
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market
Batteries
Global Electric Scooter Batteries Market
Batteries
South America Micro Battery Market
Batteries
Iron-Chromium Flow Battery Market