
 South America Primary Battery Market | 2026-2036
South America Primary Battery Market Size, Share, and Industry Trends Forecast 2026-2036
South America Primary Battery Market Analytics
Argentina's import substitution framework is rebalancing the competitive landscape for foreign battery suppliers. Duracell Inc. leverages its established distribution network to sustain shelf presence across Argentine supermarkets and electronics retailers. Energizer Holdings Inc. anchors its regional competitiveness through specialized alkaline formulations targeting tropical humidity conditions. Panasonic Corporation differentiates via lithium primary cell production serving Brazilian medical device OEMs.
Primary batteries are non-rechargeable electrochemical cells delivering single-use energy through irreversible redox reactions, typically employing zinc-manganese dioxide, lithium-thionyl chloride, or lithium-iron disulfide chemistries with nominal voltages ranging from 1.5V to 3.6V and shelf lives extending 5-10 years under controlled storage. These devices power critical applications where charging infrastructure proves impractical or reliability demands preclude secondary cell failure modes. Alkaline products dominate household and consumer electronics channels through cost-performance parity, while lithium chemistries command premium positioning in medical devices and industrial equipment requiring stable discharge profiles under extreme temperatures. Zinc-carbon variants retain volume in price-sensitive rural markets across Paraguay and Bolivia despite accelerating alkaline substitution in urban centers.
Brazil's ANVISA medical device regulations mandate traceable battery performance documentation for implantable and patient-contact equipment, elevating compliance costs for non-specialized suppliers. Argentina's national production incentives and Brazil's INMETRO certification requirements for consumer goods collectively shape product registration timelines and local testing obligations. Stakeholders must monitor evolving mercury-content restrictions under Mercosur environmental protocols and anticipate lithium supply chain disclosure mandates affecting cross-border procurement strategies.
Market Dynamics
Argentina's import substitution regulations are compressing margins for foreign battery suppliers while accelerating local assembly investments across the Southern Cone. This structural pressure is redrawing competitive boundaries between established multinationals and emerging domestic producers.
Growth Catalysts
- ANVISA medical device traceability mandates:Brazilian implantable equipment manufacturers now require documented lithium primary cell performance records, creating specialized demand for certified suppliers.
- Lithium-thionyl chloride chemistry adoption:Industrial equipment operators in São Paulo's manufacturing corridor are specifying these cells for extreme temperature reliability in remote monitoring applications.
- Southeastern Brazil industrial clustering:Dense concentrations of medical device OEMs and automotive electronics plants in Minas Gerais generate contiguous procurement volumes for primary cell distributors.
Market Restraints
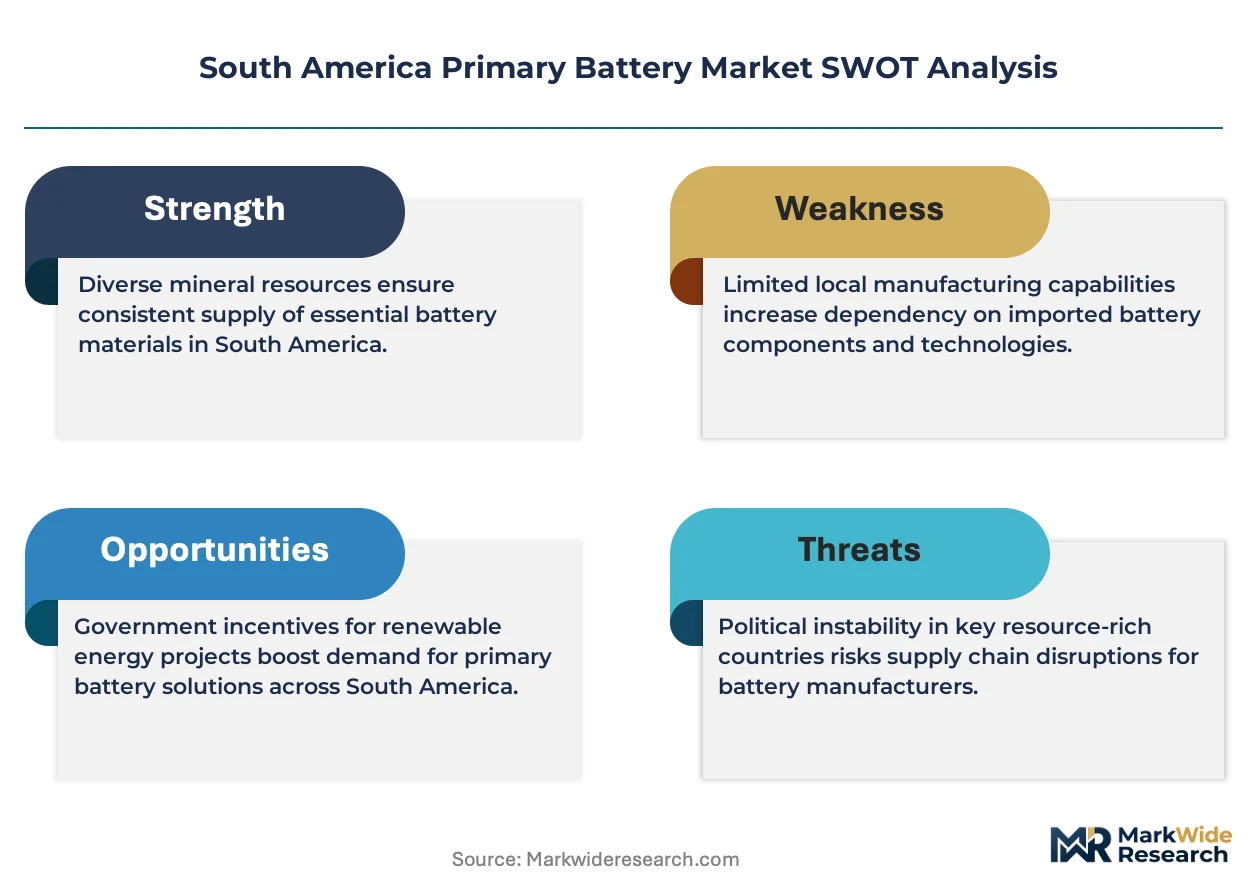
- Lithium raw material supply concentration:Chilean and Argentine brine operations control regional carbonate feedstock, exposing assemblers to upstream price volatility and export quota fluctuations.
- INMETRO certification timelines:Brazil's mandatory consumer goods testing extends product registration cycles by eight to fourteen months, freezing working capital in pre-revenue inventory.
- Alkaline substitution of zinc-carbon:Cost-performance parity in urban retail channels is eroding the rural price-sensitive segment that historically sustained volume producers.
Strategic Opportunities
- Paraguayan and Bolivian rural electrification gaps:Off-grid healthcare posts and agricultural telemetry in these markets still rely on primary cell backup where charging infrastructure remains absent.
- Mercosur environmental protocol harmonization:Emerging mercury-content restrictions will disqualify non-compliant imports, opening shelf space for certified regional manufacturers.
- Direct-to-industrial distributor models:Bypassing traditional retail wholesale layers lets suppliers capture margin from Brazilian medical device OEMs with predictable volume contracts.
Industry Challenges
- Electrochemical engineering talent scarcity:Brazil and Argentina produce limited graduates with lithium cell design expertise, forcing assemblers to import technical leadership or accept longer development cycles.
- Cross-border logistics reconfiguration:Argentine import substitution rules disrupt established supply chains, requiring foreign suppliers to establish local legal entities and bonded warehousing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Primary Battery Market |
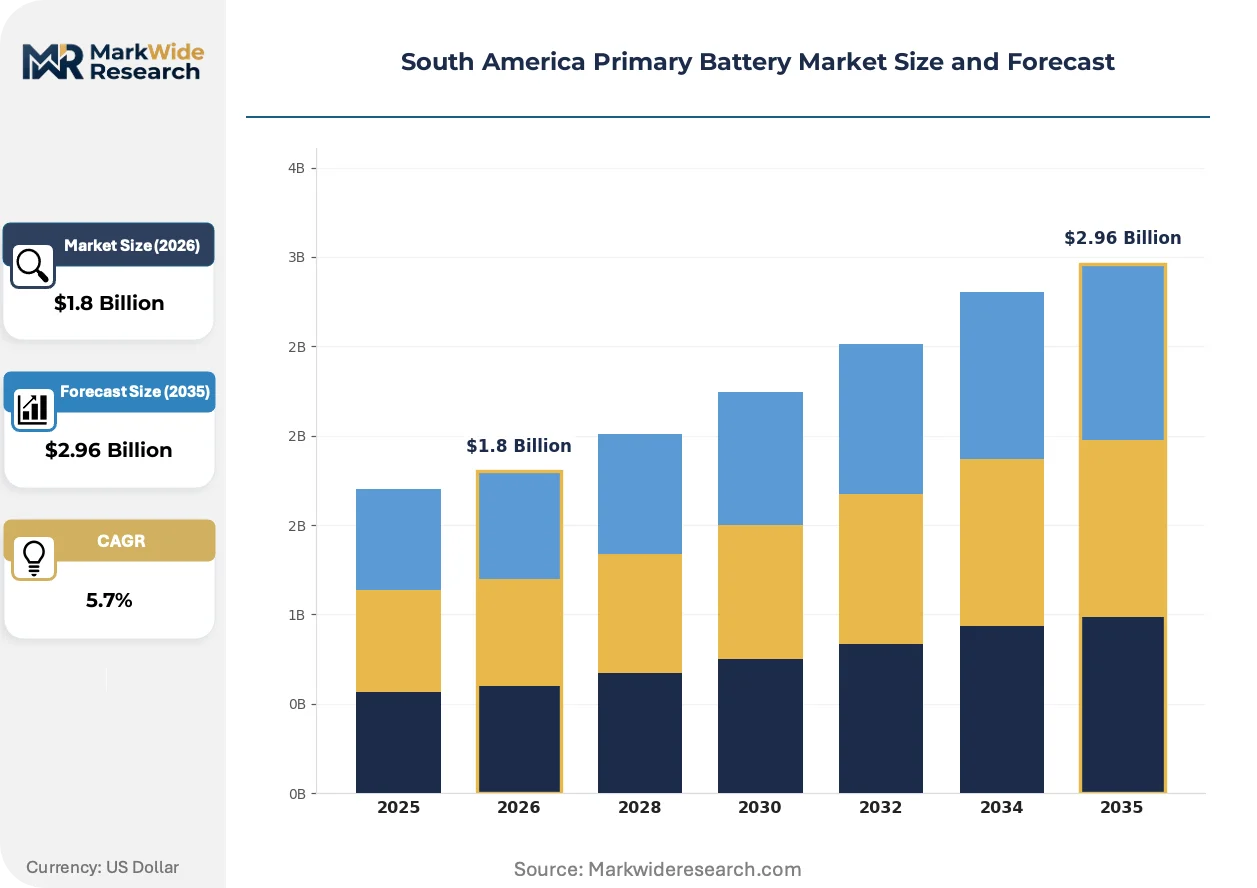
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline, Lithium, Zinc-Carbon, Lithium-Ion Application: Consumer Electronics, Automotive, Industrial Equipment, Medical Devices Sales Channel: Online Retailers, Supermarkets, Wholesale Distributors, Electronics Stores End User: Households, Enterprises, Educational Institutions, Government Agencies |
| Companies Covered | Duracell Inc., Energizer Holdings Inc., Panasonic Corporation, Saft Groupe SA, Camelion Battery Co. Ltd, GP Batteries International Ltd., EaglePicher Technologies, Gold Peak Industries Limited, Integer Holdings Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Primary Battery Market Evolving Landscape
Lithium primary cell architectures are advancing through chemistry refinements and packaging miniaturization, reshaping competitive differentiation in medical and industrial segments. These developments are compressing the performance gap between premium and standard tiers while raising compliance thresholds.
Lithium-iron disulfide cylindrical formats are converging with hermetic sealing techniques originally developed for implantable medical applications. Brazilian cardiac device manufacturers are specifying these configurations for next-generation pacemakers and neurostimulators. This convergence is collapsing the traditional separation between consumer-grade and medical-grade cell production lines, forcing suppliers to dual-certify facilities.
Mercosur's advancing mercury-content restrictions are eliminating zinc-carbon formulations from formal retail channels across Argentina, Brazil, and Uruguay. Industrial buyers must now validate alkaline or lithium alternatives for legacy equipment designed around older voltage profiles. Medical device OEMs in São Paulo are responding fastest, locking in multi-year supply agreements before compliance deadlines tighten.
Hospital procurement consortia in Brazil's southeastern states are consolidating primary battery purchasing through centralized tender platforms, displacing fragmented distributor relationships. These pooled contracts favor suppliers with ANVISA-registered documentation and regional warehousing capacity. The concentration is most visible in Minas Gerais, where three healthcare networks now coordinate implantable device power source acquisitions.
South America Primary Battery Market Segmentation
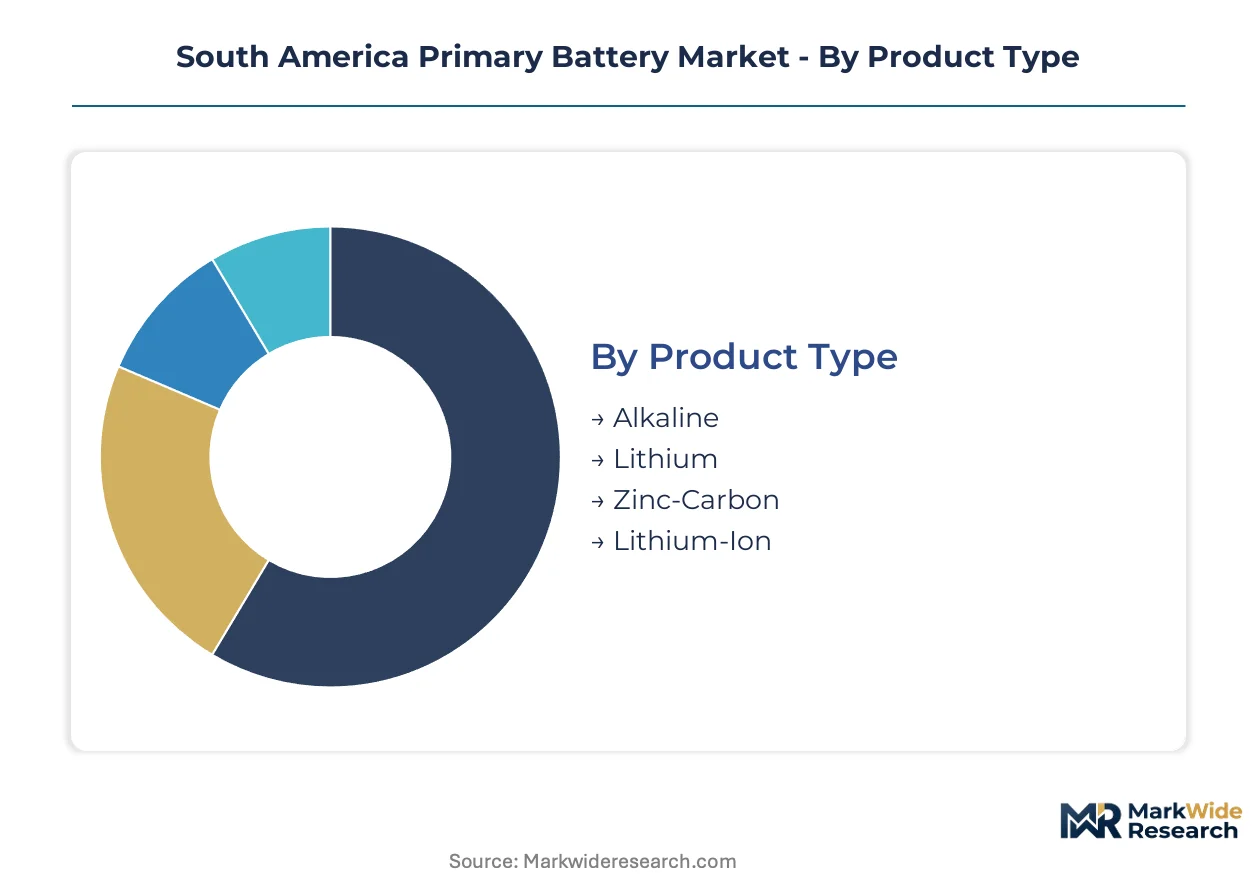
Primary battery segmentation across South America reflects divergent performance requirements between commodity household consumption and precision industrial applications. Chemistry selection and channel configuration determine margin capture, with lithium formulations commanding premium positioning in Brazilian medical corridors while alkaline products dominate volume through Argentine retail networks.
Product Type:
Volume concentrates in alkaline and zinc-carbon chemistries serving price-sensitive retail channels, while premium lithium cells capture specialized industrial and medical demand with documented performance traceability.
- Alkaline:Zinc-manganese dioxide chemistry delivers 1.5V nominal output with shelf stability extending five to seven years under controlled storage. Brazilian supermarkets and electronics retailers in São Paulo's urban corridor move the highest volumes, though Argentine import substitution regulations are compressing margins for foreign-branded alkaline imports and accelerating local assembly investments.
- Lithium:Lithium-thionyl chloride and lithium-iron disulfide formulations provide 3.6V and 1.5V outputs respectively with decade-plus shelf lives and stable discharge across extreme temperatures. ANVISA-traceable lithium cells are concentrating procurement from Brazilian cardiac device manufacturers in Minas Gerais, where implantable equipment OEMs now require documented performance records for patient-contact applications.
- Zinc-Carbon:Legacy Leclanché cell construction retains foothold in Paraguayan and Bolivian rural markets where price sensitivity outweighs alkaline's superior cost-per-hour performance, though Mercosur mercury-content restrictions are progressively disqualifying these formulations from formal retail channels.
- Lithium-Ion:Rechargeable chemistry inclusion reflects category boundary blurring in distributor catalogs, with Brazilian industrial buyers occasionally specifying lithium-ion backup for remote telemetry equipment despite primary cell dominance in true disposable applications.
Mature deployment sits with alkaline products. Newer deployment is concentrated in lithium-thionyl chloride cells for industrial reliability applications.
Application:
Customer requirements fragment sharply between consumer convenience priorities and industrial compliance obligations, with medical device specifications imposing the most stringent chemistry and documentation standards.
- Consumer Electronics:Remote controls, flashlights, and portable radios drive alkaline volume through Argentine supermarkets and Brazilian electronics retailers. São Paulo's dense urban population sustains the highest per-capita consumption rates, though substitution toward rechargeable alternatives is eroding growth in premium household segments.
- Medical Devices:Implantable cardiac equipment and neurostimulators demand lithium-iron disulfide cylindrical formats with hermetic sealing and ANVISA-registered documentation. Brazilian hospital procurement consortia in Minas Gerais are consolidating purchasing through centralized tender platforms that favor suppliers with regional warehousing and traceable batch records.
- Automotive:Keyless entry fobs, tire pressure monitors, and emergency beacon backup power represent steady demand concentrated in São Paulo's automotive electronics manufacturing cluster, where tier suppliers specify lithium primary cells for extreme temperature reliability.
- Industrial Equipment:Remote monitoring sensors and agricultural telemetry in Paraguayan and Bolivian off-grid locations specify lithium-thionyl chloride for decade-long deployment without maintenance access, creating specialized demand outside urban retail channels.
Procurement concentration is highest in medical devices. Volume expansion is climbing the fastest in industrial equipment as telemetry deployment spreads.
Sales Channel:
Channel selection determines working capital intensity and margin capture, with direct industrial relationships offering superior returns compared to fragmented retail wholesale layers.
- Supermarkets:Argentine and Brazilian mass-market retail chains sustain alkaline volume through impulse purchase placement and promotional bundling, though shelf space consolidation is favoring established brands with established distribution infrastructure.
- Wholesale Distributors:Traditional layer serving rural electronics retailers and small industrial buyers across the Southern Cone, facing margin compression as direct-to-industrial models bypass intermediary markups.
- Electronics Stores:Urban specialty retailers in São Paulo and Buenos Aires capture premium lithium sales for high-drain devices, with staff expertise influencing chemistry selection toward higher-margin products.
- Online Retailers:E-commerce penetration remains below North American benchmarks, though Brazilian marketplace platforms are gaining traction for bulk alkaline purchases and hard-to-source lithium formats for industrial buyers.
Established volume flows through supermarkets. Emerging deployment is concentrating in direct distributor relationships with Brazilian medical device OEMs.
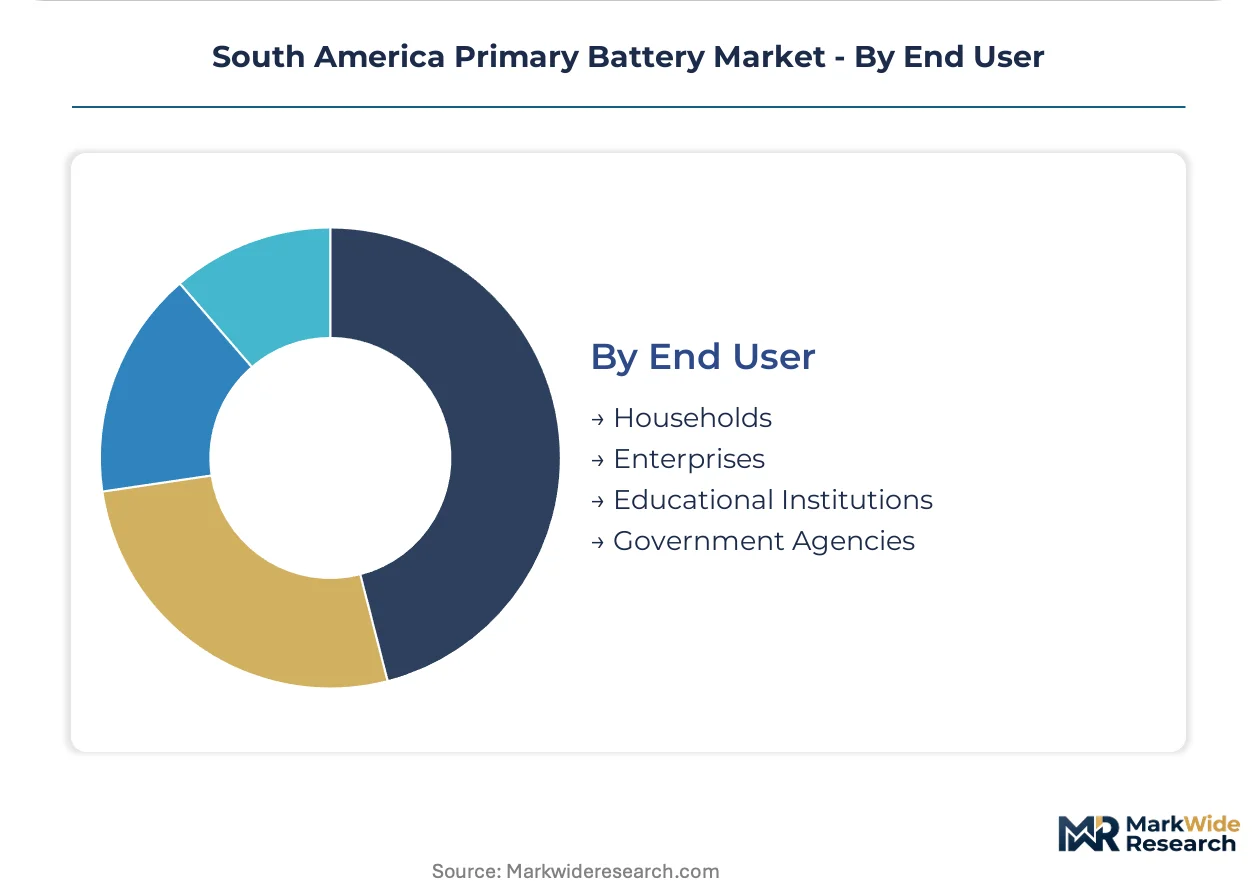
End User:
User type dictates specification rigor and contract structure, with enterprise and government procurement imposing compliance documentation that household consumption bypasses entirely.
- Households:Price-sensitive alkaline consumption dominates, with Brazilian urban households showing accelerating preference for bulk purchasing through wholesale clubs and online platforms.
- Enterprises:Brazilian medical device manufacturers and industrial equipment operators specify certified lithium cells with multi-year supply agreements, locking in volume commitments ahead of Mercosur compliance deadlines.
- Government Agencies:Hospital procurement consortia and rural electrification programs in Paraguay and Bolivia represent concentrated volume with extended tender cycles and local content preferences.
- Educational Institutions:Laboratory equipment and emergency communication backup in Argentine universities generates intermittent demand for specialized lithium formats with documentation requirements.
Volume concentration remains with households. Specification intensity is expanding most quickly in enterprise procurement as traceability mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone incentives anchor Brazil's battery assembly concentration. Argentine import substitution rules redirect foreign supplier strategies toward local legal entities. Chilean lithium brine operations feed regional carbonate supply chains.
Brazil
ANVISA traceability mandates for implantable medical equipment drive lithium primary cell procurement from certified suppliers. INMETRO certification requirements extend consumer goods registration timelines. São Paulo and Minas Gerais industrial corridors concentrate medical device OEMs and automotive electronics manufacturers specifying lithium-thionyl chloride for extreme temperature reliability.
Argentina
Updated import substitution regulations favor local battery assembly operations over finished cell imports. National production incentives compress margins for foreign suppliers while accelerating domestic manufacturing investments. Buenos Aires and Córdoba retail networks sustain alkaline volume through supermarket and electronics store channels.
Chile
Atacama Desert brine operations control regional lithium carbonate feedstock for primary cell cathode materials. Export quota fluctuations expose downstream assemblers to upstream price volatility. Santiago-based distributors coordinate cross-border supply to Brazilian and Argentine battery manufacturers.
Paraguay
Rural electrification gaps sustain zinc-carbon demand for off-grid healthcare posts and agricultural telemetry. Price-sensitive consumption in informal retail channels resists alkaline substitution. Asunción wholesale distributors serve remote agricultural regions where charging infrastructure remains absent.
Bolivia
Uyuni salt flat lithium reserves remain underdeveloped relative to regional supply needs. Government procurement for rural health programs generates intermittent primary battery demand. Santa Cruz and La Paz electronics retailers bridge urban-rural distribution for legacy zinc-carbon formats.
South America Primary Battery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across chemistry tiers. Market structure consolidates around established brands with distribution infrastructure and certified production lines. Three archetypes dominate: multinational consumer brands with retail shelf presence, industrial specialists with medical-grade certifications, and regional assemblers leveraging local content rules. Competitive moves concentrate on direct-to-industrial distributor models and ANVISA-registered facility investments.
Among multinational consumer brands, Duracell Inc. and Energizer Holdings Inc. occupy positions shaped by supermarket and electronics retail channel access. Panasonic Corporation exemplifies the industrial-medical specialist archetype through lithium primary cell production serving Brazilian device OEMs. These three names anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Duracell Inc. |
| Energizer Holdings Inc. |
| Panasonic Corporation |
| Saft Groupe SA |
| Camelion Battery Co. Ltd |
| GP Batteries International Ltd. |
| EaglePicher Technologies |
| Gold Peak Industries Limited |
| Integer Holdings Corporation |
| Others |
Value Network & Pricing Analysis
Lithium carbonate feedstock from Chilean and Argentine brine operations flows through cathode material processing before reaching cell assemblers, with upstream concentration translating into tiered pricing power across Brazilian medical-grade and Argentine retail-grade battery markets.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations, with Brazilian medical device OEMs paying marked-up rates for ANVISA-traceable lithium cells against eight-to-fourteen-month INMETRO registration timelines that freeze working capital. Three-tier pricing structure across premium, standard, and economy levels separates certified medical-grade lithium from industrial alkaline and rural zinc-carbon segments. Cost compression in Argentine alkaline imports is intensifying because import substitution regulations force foreign suppliers into local assembly partnerships. Household consumers in Paraguayan and Bolivian rural markets exhibit highest price sensitivity, while Brazilian cardiac device manufacturers show lowest sensitivity due to compliance mandates.
Supply Chain Analysis
Regional distribution centers in São Paulo and Buenos Aires anchor hub-and-spoke patterns serving southeastern Brazil's industrial corridor and Argentina's retail networks. Chilean brine extraction and Chinese cathode processing feed regional cell assembly, with Brazilian and Argentine manufacturing hubs drawing from upstream carbonate supply. Single-source vulnerability sits with Chilean export quota fluctuations that expose downstream assemblers to feedstock disruption. Distribution runs through bonded warehousing arrangements mandated by Argentine import substitution rules, with direct-to-industrial models bypassing traditional wholesale layers for medical device OEM procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into lithium carbonate sourcing and cathode material production is becoming the decisive competitive lever, with players securing upstream positions insulating margin structures from Chilean export volatility.
For Market Incumbents: Hedge against Argentine import substitution disruption by establishing local legal entities and bonded warehousing before regulatory deadlines tighten. Secure multi-year supply agreements with Brazilian hospital procurement consortia in Minas Gais to lock in volume commitments ahead of Mercosur mercury-content compliance deadlines. Backward integration into lithium brine offtake or cathode material partnerships addresses upstream price volatility threatening standard-tier margins. For New Entrants and Emerging Players: Launch via direct-to-industrial distributor models targeting Brazilian medical device OEMs with ANVISA-registered documentation and regional warehousing capacity. Paraguayan and Bolivian rural electrification gaps represent the most penetrable white-space, with off-grid healthcare posts and agricultural telemetry requiring primary cell backup where charging infrastructure remains absent. Position around lithium-thionyl chloride reliability for extreme temperature industrial applications in São Paulo's manufacturing corridor. For Investors and Strategic Acquirers: Argentine domestic assembly license issuance accelerating is the leading indicator that local content rules are reshaping competitive boundaries and creating acquisition targets among distressed foreign suppliers. Five-to-ten-year viability favors regional assemblers with certified production lines and established distributor relationships over pure import-dependent models. Watch for Chilean export quota tightening as the signal that upstream carbonate scarcity is transferring pricing power to integrated players.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Certification Investment | Enables procurement from Brazilian cardiac device OEMs requiring traceable batch documentation. |
| Local Assembly Partnership | Satisfies Argentine import substitution regulations while compressing foreign supplier margins. |
| Lithium Carbonate offtake Agreement | Secures upstream feedstock from Chilean brine operations against export quota volatility. |
| Direct-to-Industrial Distribution | Bypasses wholesale markups to capture margin from Brazilian medical device volume contracts. |
| Hermetic Sealing Capability Buildout | Supports lithium-iron disulfide production for next-generation implantable pacemakers and neurostimulators. |
Research Methodology
Multi-period observation of lithium carbonate pricing volatility, ANVISA registration timelines, and Argentine import substitution enforcement anchored the trend analysis, supplemented by interviews with Brazilian medical device procurement managers, Argentine battery assemblers, Chilean brine operation executives, Paraguayan rural healthcare administrators, and Bolivian electronics distributors. Secondary validation drew from ANVISA regulatory filings, INMETRO certification databases, Mercosur environmental protocol drafts, Chilean export statistics, and Brazilian hospital procurement consortium tender records. Bottom-up cell demand modeling and top-down macroeconomic triangulation cross-checked volume projections.
Input-output matrices mapped lithium-thionyl chloride and lithium-iron disulfide demand across medical device, automotive electronics, and industrial telemetry applications, with chemistry-specific growth rates derived from segment-level procurement intensity and replacement cycle analysis. Segmentation dimensions included product chemistry tier, end-use application rigor, sales channel structure, and end-user specification intensity. Forecast inputs incorporated INMETRO certification backlog estimates and Mercosur compliance deadline phasing.
Chilean export quota policy shifts, Argentine regulatory enforcement variance, and Brazilian hospital procurement consolidation pace are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding lithium carbonate supply continuity and Mercosur environmental protocol implementation timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
FORTELION Battery Module Market
Batteries
South America Rechargeable Battery Market
Batteries
Global Industrial Lead Acid Battery Market
Batteries
Deep Cycle Battery Market
Batteries
North America Lead Acid Battery Market
Batteries
Printable Battery Market
Batteries
West Africa Battery Market
Batteries
Alkaline Battery Market
Batteries
India Micro Batteries Market
Batteries
Japan Battery Market
Batteries
Behind-The-Meter (BTM) Battery Market
Batteries
Stretchable Battery Market
Batteries
Europe Industrial Battery Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
Solid Electrolyte Market
Batteries
Consumer Battery Market