
 Dry Cell Battery Market | 2026-2036
Dry Cell Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Cell Battery Market Insights
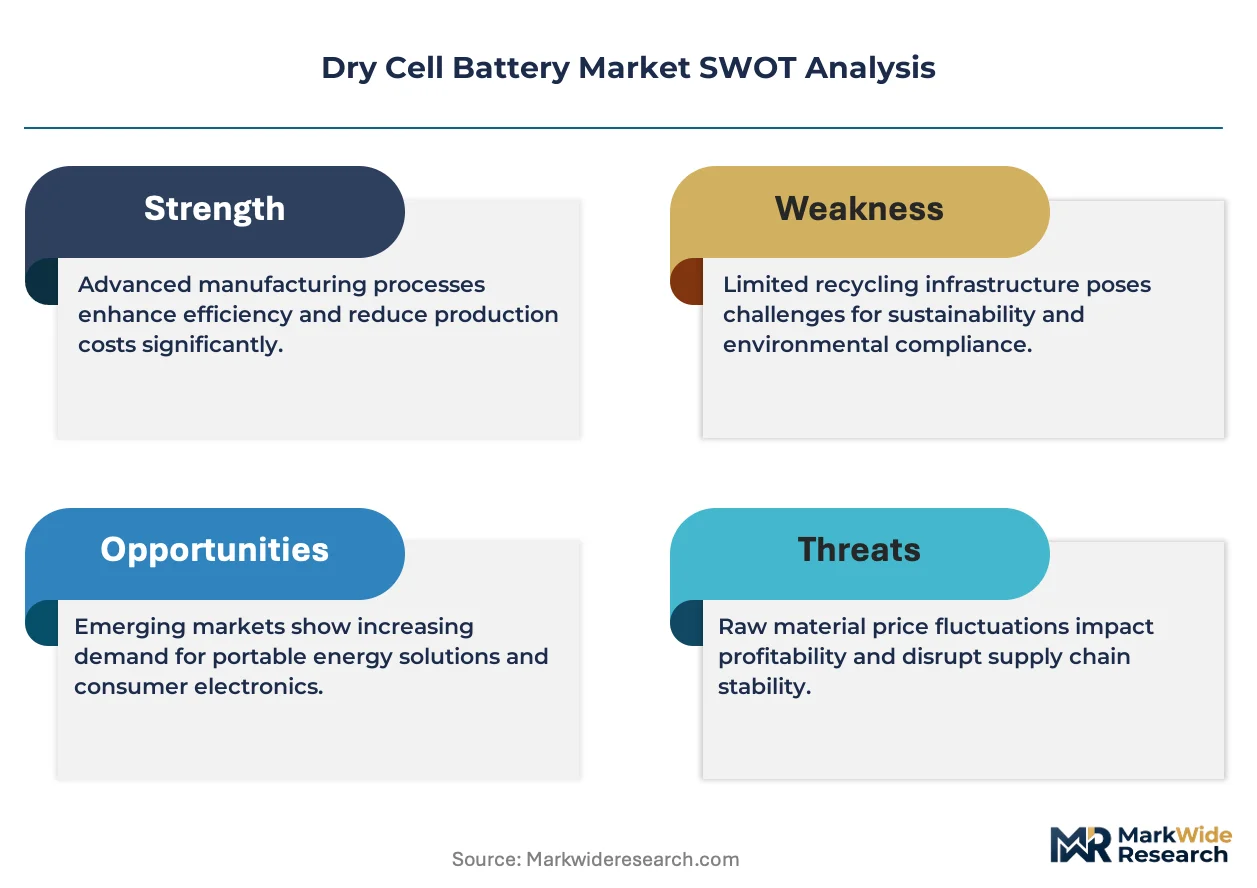
Subscription-based battery replacement programs for enterprise and medical device fleets is broadening recurring revenue streams beyond unit sales. Duracell leverages its retail shelf dominance and brand equity to sustain premium positioning in alkaline segments across North American and European mass-market channels. Energizer Holdings anchors its portfolio through specialized lithium primary cells for industrial IoT and critical medical applications where leakage resistance commands technical preference.
A dry cell battery is an electrochemical cell with a paste electrolyte rather than free liquid, typically employing zinc as an anode and manganese dioxide as a cathode with an aqueous or alkaline electrolyte immobilized in a separator matrix, designed to deliver portable DC power without spillage risk. The alkaline product type occupies the margin-rich core of consumer replacement cycles, while zinc-carbon retains volume leadership in price-sensitive emerging markets; lithium primary variants represent the fastest-growing chemistry for connected sensors and remote monitoring equipment. Application concentration in medical devices concentrates demand for stable discharge curves and extended shelf lives, whereas consumer electronics sustains the highest absolute unit throughput across retail distribution channels.
The EU Battery Regulation and REACH framework enforce cadmium and mercury thresholds while mandating recycled content disclosures, compelling reformulation of legacy chemistries and documentation burdens on importers. In the United States, EPA hazardous waste classifications and California's DTSC universal waste rules govern end-of-life collection logistics and retailer take-back obligations. China's SAMR and GB standards set dimensional and safety baselines for cells entering industrial supply chains. Stakeholders must monitor evolving extended producer responsibility schemes and chemistry-specific substance restrictions to anticipate compliance-driven product redesign cycles and regional sourcing realignments.
Market Dynamics
The EU Battery Regulation's substance restrictions and recyclability mandates are forcing chemistry reformulations across alkaline and zinc-carbon supply chains, while India's rural electrification gaps sustain bulk consumption of legacy formats.
Growth Catalysts
- Portable medical device expansion:Long-life primary cells power remote patient monitoring equipment and implantable sensors where leakage resistance and stable discharge curves are non-negotiable.
- REACH framework enforcement:ECHA's cadmium and mercury thresholds accelerate substitution toward mercury-free alkaline formulations and improved separator technologies.
- Industrial IoT sensor deployment:Lithium primary chemistry captures demand from connected asset tracking and environmental monitoring nodes requiring decade-long field lifespans.
Market Restraints
- Zinc price volatility:Anode material cost swings compress margins for zinc-carbon producers serving price-sensitive emerging market segments.
- Secondary cell substitution:Rechargeable lithium-ion formats displace primary cells in consumer electronics and power tools, eroding replacement cycle frequency.
- Collection infrastructure gaps:EU extended producer responsibility schemes impose documentation burdens on importers lacking established reverse logistics networks.
Strategic Opportunities
- Subscription fleet replacement:Enterprise and medical device operators seek recurring revenue models beyond unit sales through managed battery refresh programs.
- India's rural electrification:Uneven grid access sustains demand for bulk alkaline and zinc-carbon cells in Tier-2 and Tier-3 cities.
- CE marking convergence:Harmonized EU safety standards reduce certification fragmentation for manufacturers targeting multiple member state markets.
Industry Challenges
- Recyclability compliance timelines:EU Battery Regulation's recycled content disclosure mandates strain legacy supply chains lacking verified material provenance systems.
- Electrochemical engineering talent scarcity:Formulation chemists with paste electrolyte and separator matrix expertise face competition from battery sectors commanding premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Cell Battery Market |
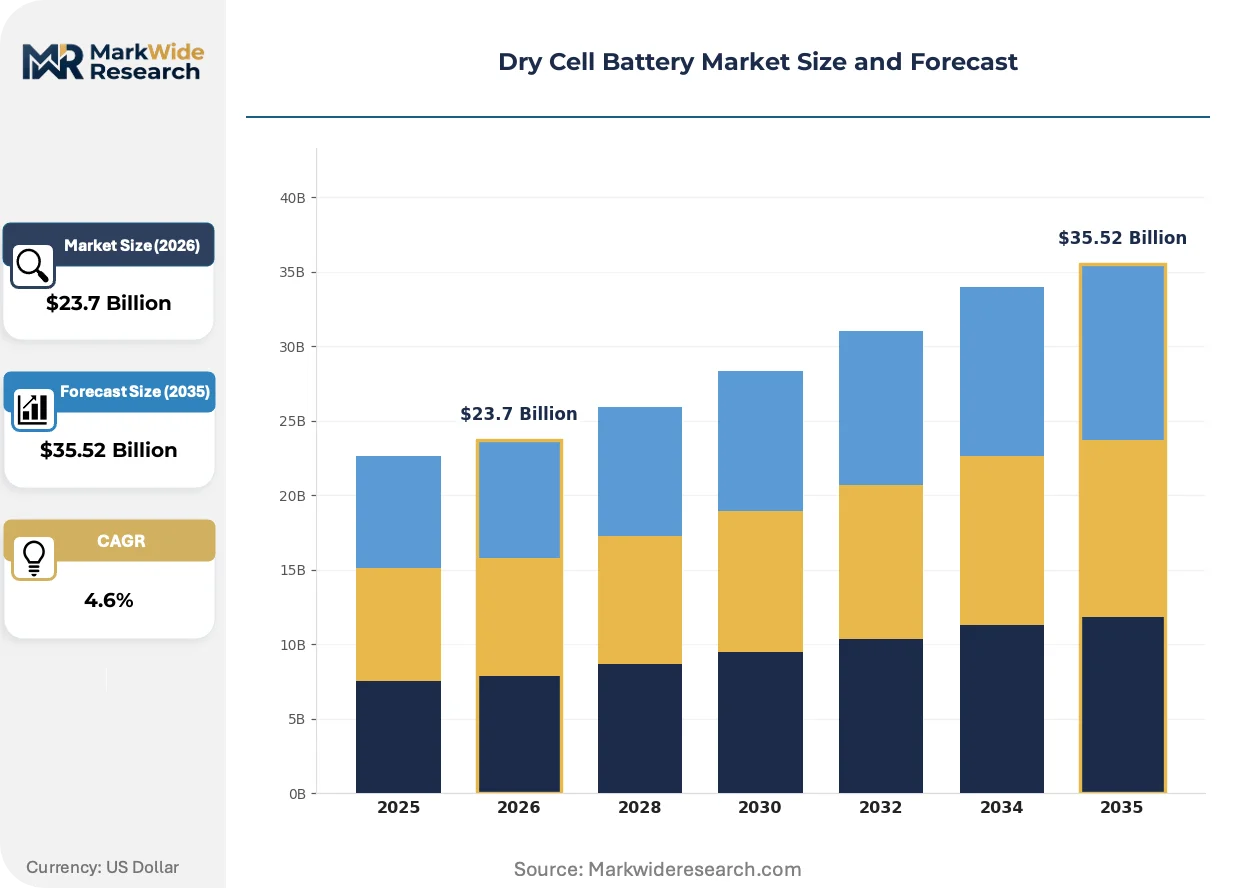
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $35.52 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline, Zinc-Carbon, Lithium-Ion, Rechargeable Application: Consumer Electronics, Medical Devices, Automotive, Toys End User: Households, Industries, Retailers, Manufacturers Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Distributors |
| Companies Covered | Duracell (Berkshire Hathaway), Fujitsu, Energizer Holdings, Tenpower, Rayovac, Panasonic, Eveready Industries, GP Batteries, Tadiran Batteries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Cell Battery Market Trends and Innovations
Electrochemical architectures are converging with digital infrastructure demands, reshaping how primary cells are specified, procured, and retired across industrial and medical value chains.
Lithium iron disulfide chemistry is integrating into high-drain medical and IoT applications through its superior energy density and cold-weather performance. Cardiac monitoring device manufacturers and cold-chain logistics operators are standardizing on this format for mission-critical deployments. The technology is integrating technical preference hierarchies that previously favored alkaline, compressing incumbent chemistry margins in premium segments.
REACH substance restrictions are tightening cadmium thresholds across battery categories entering EU industrial supply chains. ECHA's enforcement mechanisms now require pre-market notification for novel electrolyte additives, extending product development cycles. Medical device importers are responding by dual-sourcing mercury-free formulations from qualified Asian contract manufacturers.
Enterprise procurement is consolidating around outcome-based fleet management contracts rather than spot purchasing of replacement cells. Industrial sensor network operators in Germany and the Netherlands are unbundling hardware acquisition from energy service provisioning. This shift concentrates buyer power with specialized distributors capable of integrating inventory management with regulatory documentation.
Dry Cell Battery Market Segmentation
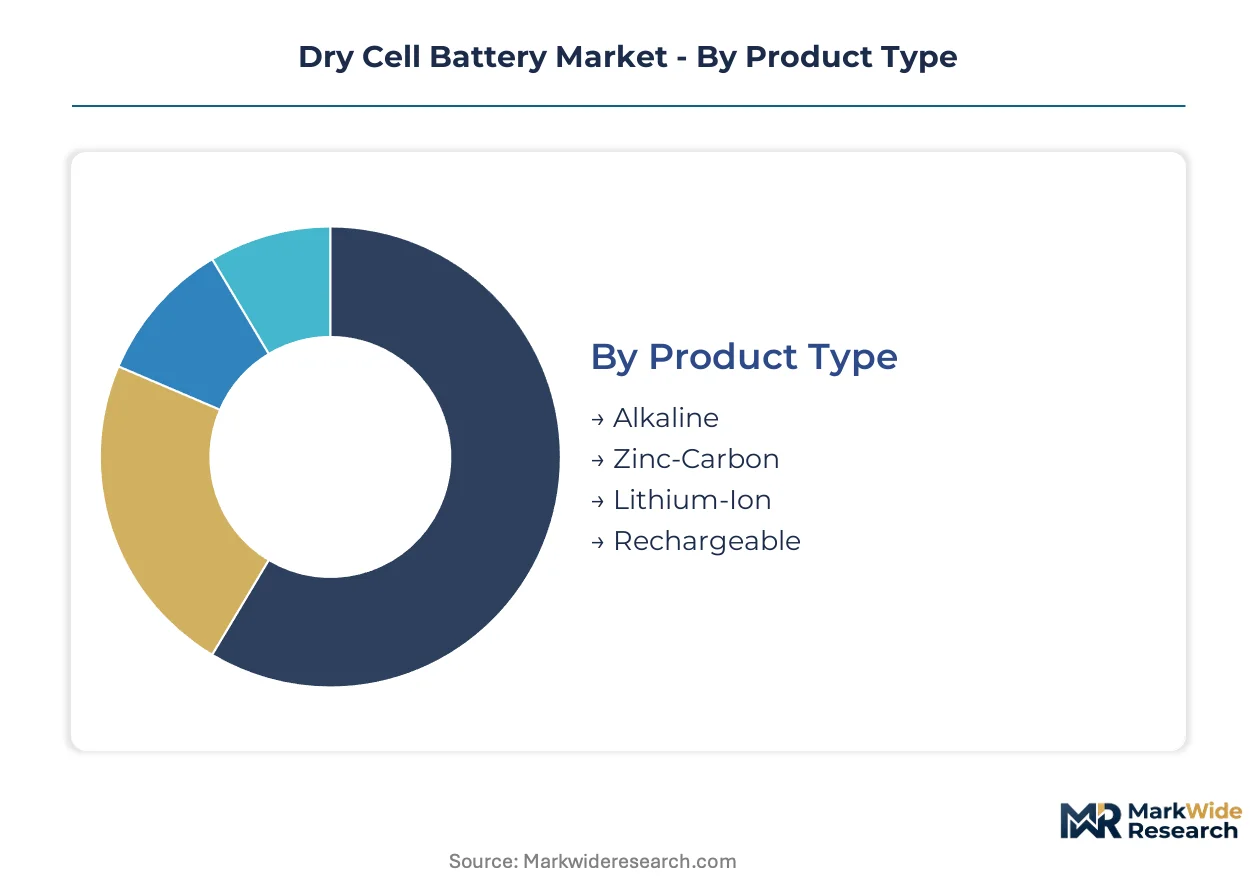
Dry cell battery procurement patterns diverge sharply across chemistry types and use cases, with replacement cycle frequency and performance thresholds dicting segment profitability. Understanding these divides reveals where margin concentrates versus where volume flows.
Product Type:
Upgrade decisions hinge on whether devices tolerate recharge cycles or demand sealed primary power, with chemistry selection locking in shelf life and discharge characteristics.
- Alkaline:Manganese dioxide cathode paired with zinc anode in potassium hydroxide electrolyte delivers stable voltage output across moderate drain rates. Demand clusters in North American and European consumer replacement cycles where leakage resistance justifies premium shelf positioning against zinc-carbon alternatives.
- Zinc-Carbon:Leclanché cell construction with ammonium chloride electrolyte paste occupies the price-sensitive core of rural electrification markets. India's Tier-2 and Tier-3 cities sustain bulk procurement for flashlights and basic radios where unit economics outweigh energy density requirements.
- Lithium-Ion:Rechargeable intercalation chemistry captures consumer electronics and power tool applications where cycle life economics displace primary cell replacement regimes.
- Rechargeable:Nickel-metal hydride and lithium-ion formats serve institutional buyers with managed fleet refresh programs, compressing spot purchasing volumes in enterprise channels.
Zinc-carbon sits at the top of the volume ranking, with lithium primary chemistry climbing the fastest in medical and IoT deployments.
Application:
End-use specifications fragment procurement into safety-critical versus discretionary consumption pools with divergent price elasticity and regulatory exposure.
- Consumer Electronics:Remote controls, wireless peripherals, and portable audio equipment generate the highest absolute unit throughput across retail distribution. Replacement cycles compress as device obsolescence outpaces cell exhaustion, sustaining steady demand despite rechargeable encroachment in high-drain categories.
- Medical Devices:Implantable sensors, cardiac monitors, and drug delivery pumps mandate primary lithium formulations with decade-long shelf stability. FDA and EMA device approvals lock in qualified cell suppliers, creating sticky procurement relationships resistant to spot price competition.
- Automotive:Key fobs, tire pressure monitors, and emergency beacons specify wide-temperature-range lithium primary cells for under-hood reliability.
- Toys:Seasonal demand surges around holiday purchasing windows concentrate alkaline volume in mass-market retail channels with high promotional intensity.
Consumer electronics commands absolute unit leadership, while medical devices expand most quickly on remote patient monitoring adoption.
End User:
Procurement sophistication separates price-takers from outcome-based buyers, with contract structure determining margin capture.
- Households:Spot purchasing at retail dominates, with brand equity and shelf visibility driving selection in low-involvement replacement decisions.
- Industries:Sensor network operators and logistics fleets consolidate procurement through managed service contracts bundling hardware, installation, and refresh logistics.
- Retailers:Private label sourcing and category management decisions determine shelf allocation between premium branded and value-positioned alternatives.
- Manufacturers:Original equipment integration contracts specify qualified cell suppliers during device design phases, locking in multi-year supply agreements.
Households generate the highest transaction frequency, with industrial buyers gaining share fastest through fleet consolidation.
Distribution Channel:
Channel selection reflects purchase urgency and lot size requirements, with digital penetration reshaping replenishment patterns.
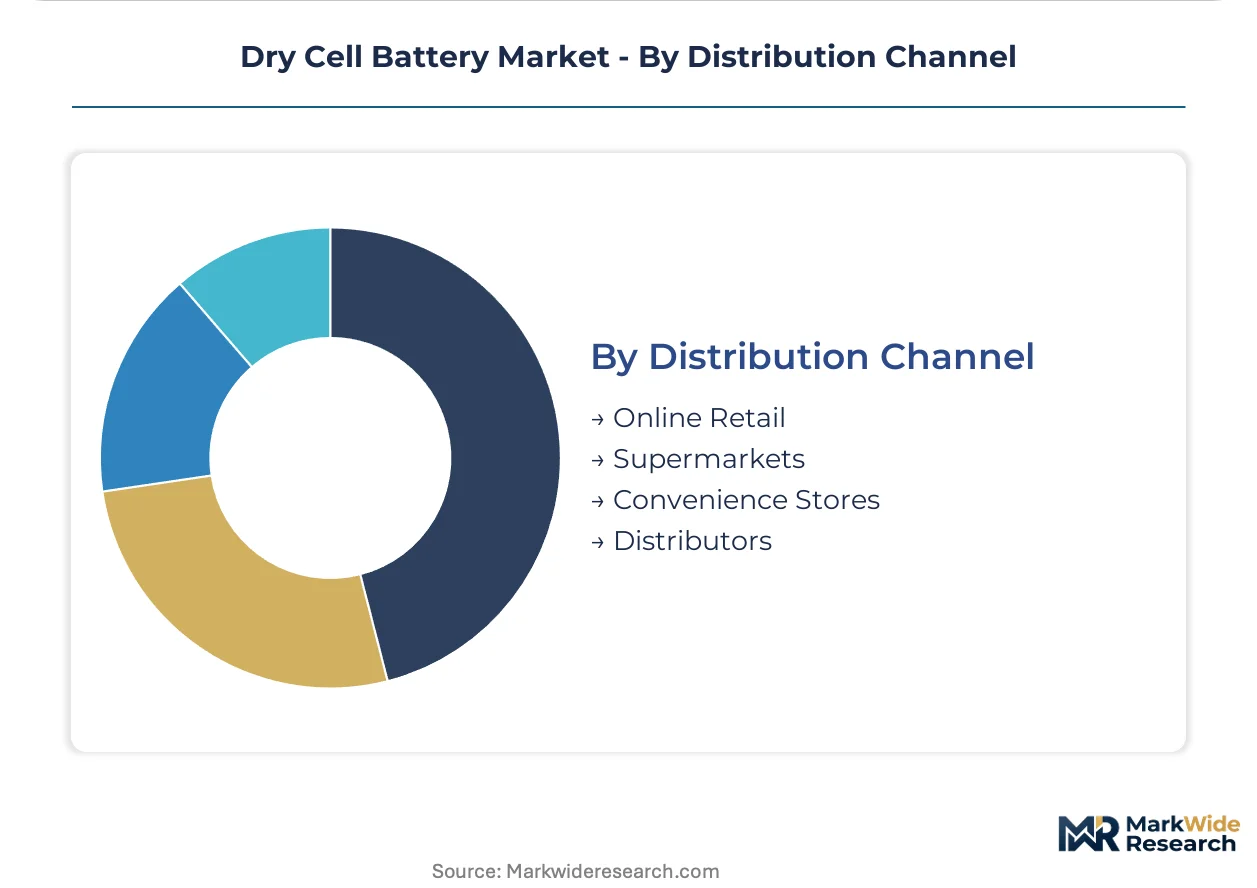
- Online Retail:Subscription replenishment and bulk purchasing concentrate in Amazon and specialized industrial supply platforms, capturing planned replacement demand with lower per-unit logistics costs.
- Supermarkets:Impulse-driven alkaline purchases during routine shopping trips sustain high-margin single-pack and multi-pack offerings in front-of-store displays.
- Convenience Stores:Emergency replacement for depleted cells commands significant price premiums on small-format offerings in travel and urban convenience locations.
- Distributors:Industrial and medical device manufacturers source through authorized distributors providing lot traceability, regulatory documentation, and technical qualification support.
Supermarkets retain the highest footfall volume, with online retail expanding fastest on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting alkaline cell production toward jurisdictions with lower compliance documentation burdens, while India's rural electrification gaps and China's industrial sensor networks sustain divergent demand pools for zinc-carbon and lithium primary formats.
United States
Medical device manufacturers in Minneapolis and Boston corridors specify lithium primary cells for implantable cardiac monitors under FDA quality system regulations. EPA hazardous waste classifications govern end-of-life collection logistics for retailers operating take-back programs. The Southeast manufacturing belt around Atlanta hosts contract packaging operations serving mass-market alkaline distribution.
Germany
Industrial IoT sensor network operators in the Ruhr Valley consolidate procurement through managed service contracts bundling hardware with regulatory documentation. ECHA's REACH enforcement accelerates substitution toward mercury-free formulations across alkaline supply chains. Bavaria's medical technology cluster around Munich standardizes on qualified cell suppliers during device design phases.
China
GB standards and SAMR dimensional requirements set baselines for cells entering industrial supply chains serving domestic electronics manufacturing. The Yangtze River Delta around Shanghai hosts contract manufacturers producing zinc-carbon cells for price-sensitive export markets. Shenzhen's hardware ecosystem integrates lithium primary cells into asset tracking devices for cold-chain logistics.
India
Rural electrification gaps in Tier-2 and Tier-3 cities sustain bulk consumption of zinc-carbon cells for flashlights and basic radios under BIS certification requirements. Maharashtra's consumer electronics distribution hubs channel alkaline volume through modern trade formats penetrating beyond metro centers. Tamil Nadu's medical device manufacturing corridor qualifies imported lithium cells for cardiac monitoring equipment.
Japan
METI energy efficiency standards and JIS safety requirements shape procurement specifications for primary cells in precision electronics applications. The Kansai industrial zone around Osaka maintains specialized production of high-reliability lithium formats for automotive under-hood deployment. Tokyo-based trading houses coordinate regional sourcing for Southeast Asian medical device assemblers.
Dry Cell Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with alkaline replacement cycles concentrating buyer power in retail channels while industrial IoT procurement favors technical qualification over brand equity. The structure tiers into premium branded players, private-label converters, and specialized lithium primary producers. Strategic moves center on backward integration into separator materials and geographic expansion through qualified Asian contract manufacturing partnerships.
Among diversified electronics conglomerates, Panasonic and Fujitsu occupy positions spanning consumer alkaline through industrial lithium primary formats. Energizer Holdings exemplifies the branded specialist archetype with retail shelf dominance in North American mass-market channels. These three entities represent distinct competitive postures: integrated conglomerate diversification, pure-play brand equity leverage, and chemistry-specific technical positioning.
| Leading Market Players |
|---|
| Duracell (Berkshire Hathaway) |
| Fujitsu |
| Energizer Holdings |
| Tenpower |
| Rayovac |
| Panasonic |
| Eveready Industries |
| GP Batteries |
| Tadiran Batteries Ltd |
| Others |
Pricing and Supply Chain Analysis
Zinc LME spot pricing volatility cascades through anode material procurement into three distinct battery tiers, with premium alkaline cells absorbing cost swings through brand equity while zinc-carbon producers serving rural India compress margins to maintain volume positioning against rechargeable substitution.
Pricing Analysis
Distributor margins of 15-25 percent separate contract OEM pricing from retail shelf rates across alkaline and lithium primary segments. Three-tier pricing structure across premium, standard, and economy levels reflects separator quality grades and mercury-free certification status under REACH thresholds. Cost compression in zinc-carbon tiers is intensifying because anode material swings erase already-thin producer margins. Household spot purchasers exhibit highest price sensitivity, while medical device OEMs locked into FDA-qualified supplier relationships show lowest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale medical device and industrial sensor demand, while mass-market alkaline flows through distributor-retailer stacks. Manufacturing concentrates in China, India, and Indonesia for zinc-carbon cells, with Japan and South Korea anchoring lithium primary production. Supply chains draw from manganese dioxide cathode feedstock, zinc anode sheet, and polypropylene separator membrane imports. Single-source vulnerability concentrates in electrolyte additive formulations subject to ECHA pre-market notification delays. Distribution runs through authorized industrial distributors providing lot traceability for medical qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU compliance documentation burdens and India's BIS certification efficiency creates 12-18 month product launch differentials, rewarding manufacturers with qualified Asian contract manufacturing partnerships.
For Market Incumbents: Lock in separator material backward integration to defend alkaline margins against zinc price volatility and private-label encroachment. Secure multi-year OEM qualification contracts with cardiac monitoring device manufacturers before lithium iron disulfide chemistry displaces alkaline in premium medical segments. Prioritize mercury-free formulation R&D to preempt REACH threshold tightening. For New Entrants and Emerging Players: Rural electrification procurement officers in India's Tier-3 cities represent an underserved buyer archetype with concentrated volume and limited brand loyalty. White-space exists in subscription-based fleet refresh programs for German industrial IoT sensor networks, where regulatory documentation bundling creates service differentiation. Enter through specialized distributors capable of integrating inventory management with EU Battery Regulation compliance paperwork. For Investors and Strategic Acquirers: Consolidation pressure builds where qualified cell suppliers face acquisition by diversified electronics conglomerates seeking medical device OEM lock-in. Long-term viability hinges on chemistry diversification beyond alkaline into lithium primary formats serving decade-lifespan IoT deployments. Target acquisition archetype: mid-cap lithium primary specialists with FDA master files and existing cardiac monitor qualifications. Monitor ECHA cadmium threshold enforcement announcements as inflection signal for accelerated mercury-free formulation substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Separator Materials | Captive polypropylene supply insulates margins from specialty polymer price swings. |
| Mercury-Free Formulation Certification | REACH pre-market notification clearance accelerates EU medical device OEM access. |
| Subscription Fleet Management Launch | German industrial sensor operators bundle hardware refresh with regulatory documentation. |
| Asian Contract Manufacturing Partnership | BIS-qualified Indian production sidesteps EU Battery Regulation documentation burdens. |
| Lithium Iron Disulfide Product Line Extension | Cold-weather performance captures cardiac monitoring and cold-chain logistics specification. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with cell manufacturing plant managers, medical device procurement leads at GPOs, industrial sensor network operators, and distributor channel heads informed demand-side assumptions. Secondary sources include ECHA REACH substance restriction databases, FDA 510(k) filings for battery-powered devices, BIS certification registries, and customs trade data for zinc and manganese dioxide flows. Bottom-up cell volume modeling triangulated against top-down replacement cycle frequency estimates.
Rate-of-change decomposition separates volume growth from pricing mix effects across the analysis window. Segmentation dimensions modeled include chemistry type, application end-use, and procurement contract structure. CAGRs derived from replacement cycle frequency projections, device penetration curves, and chemistry substitution elasticities. Industry-specific inputs encompass cardiac monitor implantation rates, industrial IoT sensor deployment pipelines, and rural electrification grid extension timelines.
Underlying measurement precision varies by segment; medical device and industrial IoT procurement carry tighter precision than household retail spot purchasing. Forecasts reflect assumptions regarding REACH enforcement intensity, zinc price volatility persistence, and rechargeable substitution rates in consumer electronics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Global Battery Market
Batteries
Two Wheeler Lead Acid Batteries Market
Batteries
Aluminium-Sulfur Battery Market
Batteries
Southeast Asia Battery Market
Batteries
Inverter Battery Market
Batteries
South Europe Battery Market
Batteries
FORTELION Battery Module Market
Batteries
Italy Rechargeable Battery Market
Batteries
South America Rechargeable Battery Market
Batteries
India Electric Vehicle Battery Electrolyte Market
Batteries
Battery Cases Market
Batteries
Forklift Battery Charger Market
Batteries
Sodium-Air Battery Market
Batteries
Nickel-Metal Hydride (Ni-MH) Battery Market
Batteries
Global Solar Battery Charger Market
Batteries
Asia-Pacific Consumer Battery Market