
 North America Irrigation Valves Market | 2026-2036
North America Irrigation Valves Market Size, Share, and Industry Trends Forecast 2026-2036
North America Irrigation Valves Market Insights
Buyer concentration among large-scale agricultural cooperatives is decoupling from the historical fragmentation that characterized the distributor-led channel. Nelson Irrigation leverages its product specialization in pressure-regulated emitters to sustain premium positioning in drip-intensive growing regions. Toro Company anchors its North American footprint through backward integration into flow-control manufacturing, while Rain Bird competes on brand strength across municipal and golf course verticals.
North America irrigation valves are mechanical or electromechanical flow-control devices engineered from brass, PVC, or ductile iron, typically rated for pressures between 20 and 150 psi, designed to regulate water distribution across pressurized irrigation networks. Their primary commercial purpose is to enable precise volumetric allocation while minimizing losses from backflow, pressure surge, and leakage across agricultural and landscaped environments. Ball valves occupy the largest installed base due to their quarter-turn reliability and lower maintenance burden in surface installations, while electric actuation represents the fastest-expanding technology segment as growers retrofit manual systems for remote telemetry integration. Drip installation configurations command margin concentration because they require higher-precision pressure regulation and filtration pairing than conventional sprinkler layouts.
The EPA enforces water-efficiency standards that directly shape product certification requirements and restrict non-compliant valve imports into the United States, while Health Canada and PMRA coordinate cross-border agricultural chemical runoff rules that influence irrigation infrastructure design in shared watersheds. USDA conservation programs provide cost-share incentives that accelerate replacement cycles for inefficient mechanical systems. Stakeholders must monitor how state-level groundwater withdrawal permitting in California and Texas reshapes capacity planning for electric-actuated valve deployments.
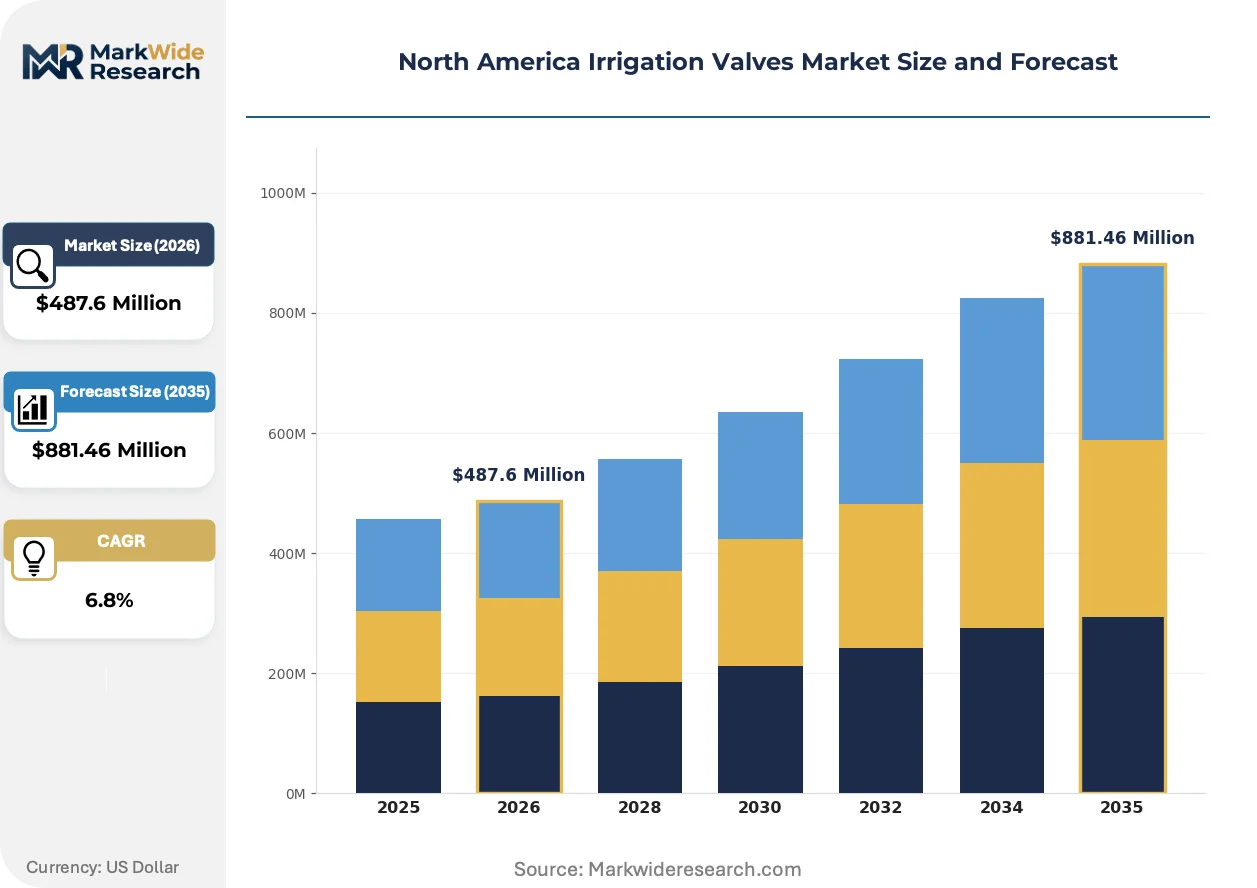
Market Dynamics
Precision agriculture adoption is decoupling from commodity pricing cycles, compelling large-scale row-crop operators to deploy electric-actuated valve systems regardless of grain market volatility. EPA water-use efficiency mandates under the Clean Water Act are accelerating infrastructure replacement timelines across California's Central Valley and the Texas High Plains corridor.
Growth Catalysts
- EPA Clean Water Act mandates:Federal water-efficiency standards are compelling infrastructure upgrades among agricultural operators in water-stressed watersheds.
- USDA conservation cost-share programs:Financial incentives are compressing replacement cycles for inefficient mechanical valve systems across the Corn Belt.
- Remote telemetry integration:Electric actuation technology is enabling precision volumetric control in drip-intensive growing regions.
Market Restraints
- Brass and ductile iron input volatility:Foundry-grade metal price swings are compressing margin stability for valve manufacturers.
- California groundwater withdrawal permitting:State-level allocation restrictions are constraining capacity planning for new electric-actuated deployments.
- Manual valve residual base:Low-cost quarter-turn ball valves continue to dominate surface installation retrofits, limiting premium product penetration.
Strategic Opportunities
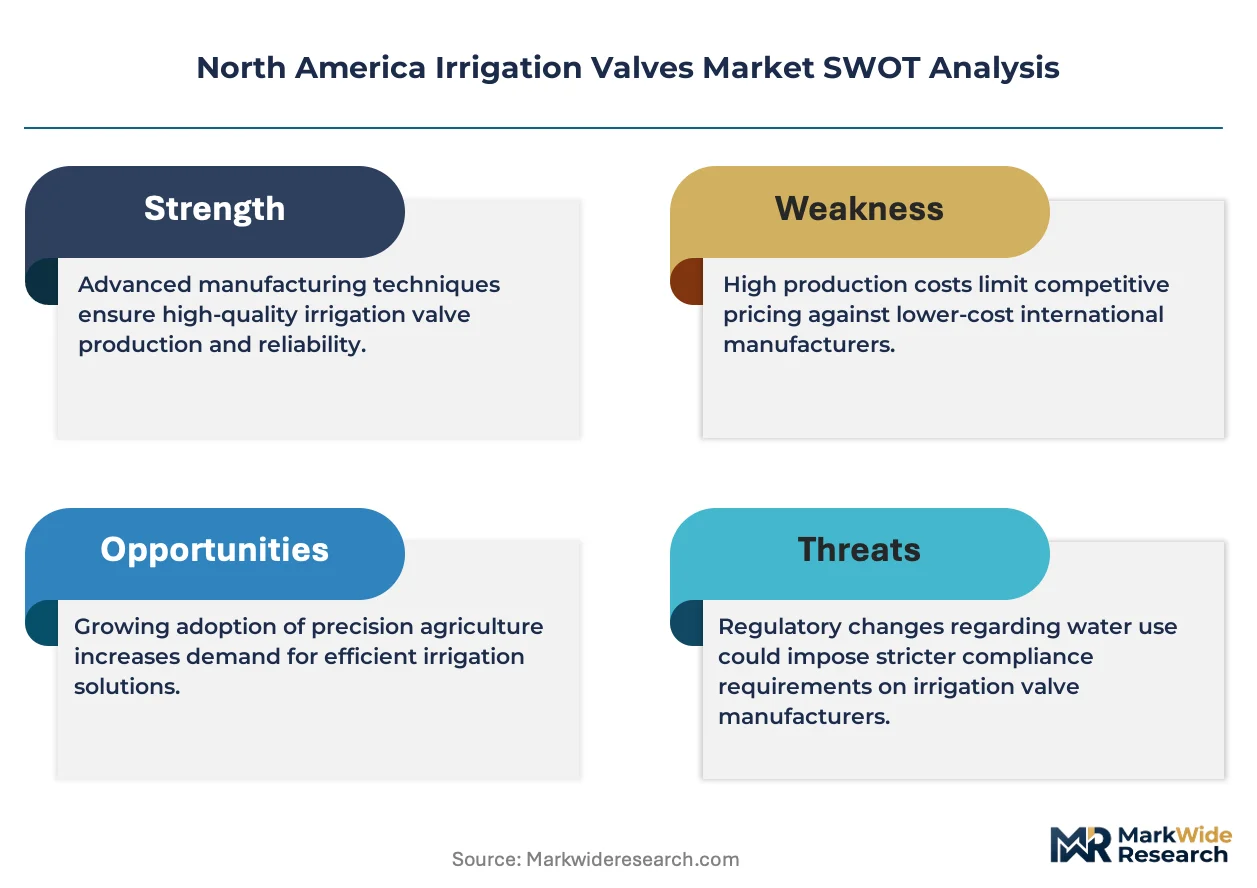
- Texas High Plains corridor expansion:Ogallala Aquifer depletion is driving demand for pressure-regulated precision systems among cotton and grain producers.
- Health Canada-PMRA cross-border coordination:Harmonized agricultural chemical runoff rules are creating specification pull-through for integrated filtration-valve systems in shared Great Lakes watersheds.
- Municipal and golf course verticals:Landscape irrigation specifications are migrating toward smart-actuation platforms with embedded flow sensors.
Industry Challenges
- Electromechanical technician scarcity:Specialized skill gaps in actuator diagnostics and telemetry integration are extending commissioning timelines.
- Legacy mechanical system interoperability:Retrofit complexity with existing PVC network infrastructure is raising total project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Irrigation Valves Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gate, Globe, Ball, Check Technology: Manual, Electric, Hydraulic, Pneumatic End User: Agriculture, Landscape, Golf Courses, Municipal Installation: Surface, Subsurface, Drip, Sprinkler |
| Companies Covered | Ace Pump Corporation, Nelson Irrigation, Netafim USA, Hunter Industries, Toro Company, Rain Bird, Bermad CS Ltd, Fluidra S.A. (Capex), Rivulis Irrigation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Irrigation Valves Market Trends and Innovations
Valve technology is converging with digital agriculture platforms, compressing the gap between flow-control hardware and farm management software. Three developments are reshaping competitive positioning across the North American installed base.
Smart valve controllers with embedded pressure transducers and wireless telemetry modules are unifying flow regulation with real-time soil-moisture feedback loops. Large-scale agricultural cooperatives in California and Texas are deploying these systems at accelerating pace. The technology is unifying previously siloed irrigation decisions into centralized farm management platforms, compressing the addressable market for standalone mechanical valves.
EPA water-efficiency certification requirements under the WaterSense program are tightening performance thresholds for backflow prevention and pressure regulation. Manufacturers must now submit third-party test data for every valve configuration destined for federal procurement or state rebate eligibility. Agricultural distributors in the Central Valley are restructuring inventory toward pre-certified SKUs, marginalizing non-compliant import alternatives.
Cooperative procurement consortia are consolidating purchasing authority among multi-farm operations, displacing traditional distributor-led channel fragmentation. These buying groups now specify integrated valve-filter-actuator packages rather than component sourcing. The pattern is most visible among almond and pistachio growers in California's San Joaquin Valley, where water cost pressures have compressed switching cycles to sub-five-year intervals.
North America Irrigation Valves Market Segmentation
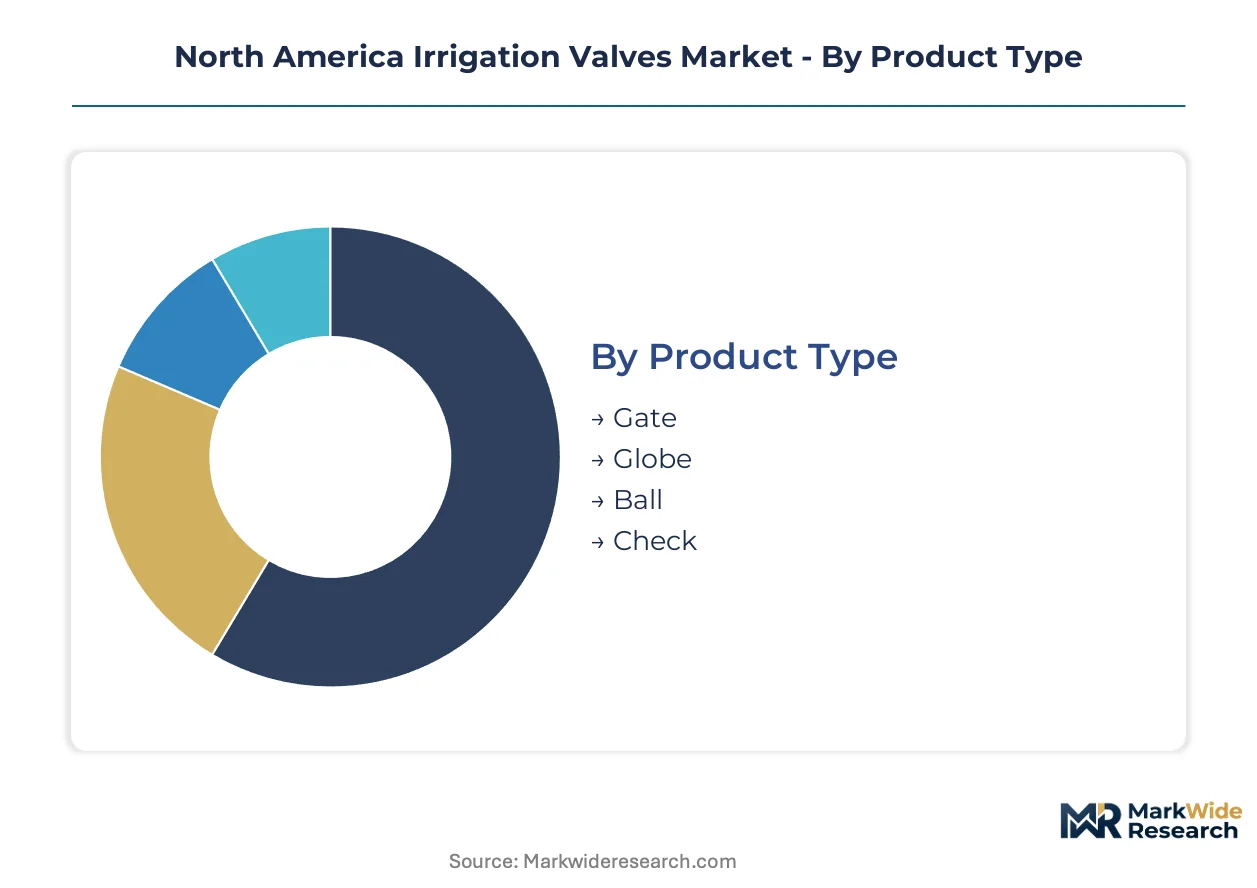
Segmentation in the North America irrigation valves market reveals how replacement cycles, regulatory compliance tiers, and precision agriculture adoption reshape procurement patterns across distinct hardware configurations and control technologies.
Product Type:
Upgrade cycles vary sharply by valve geometry, with pressure-regulation demands and maintenance burdens driving differential replacement timelines across California's Central Valley and Texas High Plains corridors.
- Ball:Quarter-turn brass or PVC construction rated for 20-150 psi service dominates surface installations across row-crop operations. Demand concentrates in Texas cotton districts where mechanical reliability and minimal maintenance burden override precision requirements.
- Gate:Linear-motion cast iron or ductile iron bodies engineered for full-port, low-pressure-drop operation anchor flood-irrigation retrofits in California's San Joaquin Valley. EPA water-efficiency mandates are accelerating displacement of legacy gate valves with backflow-compliant configurations.
- Globe:Throttling-optimized brass or stainless steel trim enables precise flow modulation in pressure-sensitive drip laterals.
- Check:Spring-loaded or swing-disc configurations prevent backflow contamination in municipal and golf course distribution networks.
Ball valves sit at the top of the volume ranking, with gate valves climbing the fastest as flood-to-drip conversions accelerate.
Technology:
Control modality segmentation tracks the capital-intensity gradient separating commodity mechanical hardware from telemetry-integrated electromechanical systems.
- Electric:Actuator-equipped valves with 24VAC solenoid or DC motor drives integrate with farm management software for remote volumetric scheduling. Large-scale agricultural cooperatives in California and Texas are deploying these systems at accelerating pace regardless of grain price volatility.
- Manual:Handwheel or lever-operated quarter-turn mechanisms retain dominance in surface retrofits where labor availability and upfront capital constraints limit automation penetration.
- Hydraulic:Pressure-piloted actuation leverages existing line pressure for valve control in remote installations lacking electrical infrastructure.
- Pneumatic:Compressed-air actuation serves specialized greenhouse and nursery applications requiring rapid cycling response.
Manual technology retains volume leadership across the installed base, while electric actuation is expanding most quickly as precision agriculture adoption decouples from commodity cycles.
End User:
Customer-type segmentation exposes diverging specification standards between agricultural efficiency mandates and landscape aesthetic requirements.
- Agriculture:Large-scale row-crop operators and cooperative consortia specify integrated valve-filter-actuator packages with USDA cost-share eligibility. Procurement concentrates among almond and pistachio growers in California where water cost pressures compress replacement cycles.
- Municipal:Public works departments enforce EPA WaterSense certification and backflow prevention standards in park and streetscape irrigation networks.
- Landscape:Commercial property managers and residential developers prioritize smart-actuation platforms with embedded flow sensors for water-budget compliance.
- Golf Courses:Superintendents demand pressure-regulated distribution with turf-specific zoning capabilities across fairway and green complexes.
Agriculture commands the dominant volume position, with municipal applications gaining share fastest as EPA infrastructure mandates tighten.
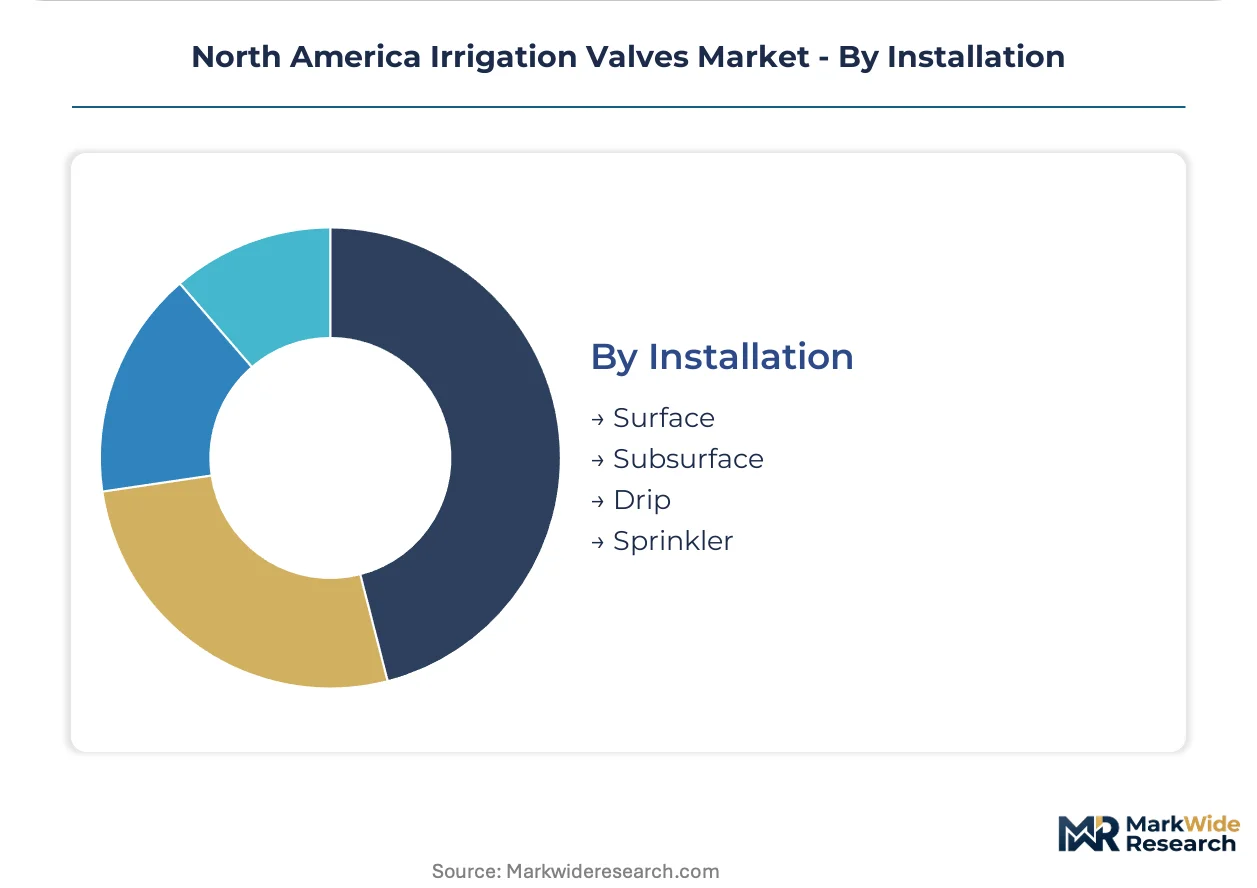
Installation:
Configuration segmentation maps hardware requirements to distribution method complexity, from simple surface lateral feeds to precision subsurface drip networks.
- Drip:Pressure-compensating valve and filtration pairings enable uniform emitter discharge across variable topography. Margin concentration here exceeds conventional layouts due to specification precision and filtration integration requirements in California's Central Valley.
- Sprinkler:Impact and gear-driven rotary systems utilize standard brass ball valves for lateral isolation and zone control in alfalfa and grain operations.
- Surface:Above-grade PVC or brass valve assemblies serve flood and furrow irrigation with minimal burial depth requirements.
- Subsurface:Buried valve configurations with integrated air-vacuum relief prevent soil ingestion and root intrusion in subsurface drip installations.
Sprinkler installations retain volume leadership, with drip configurations climbing the fastest as water-stressed regions mandate efficiency upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's agricultural water management operates under tighter federal coordination than the fragmented state-level governance dominating the United States, while Mexico's northern irrigation districts increasingly mirror Texas infrastructure standards as cross-border water treaties tighten operational alignment.
United States
California's Central Valley and the Texas High Plains corridor concentrate electric-actuated valve deployments driven by groundwater depletion pressures. EPA WaterSense certification mandates under the Clean Water Act restrict federal procurement to pre-certified valve configurations. Fresno County almond cooperatives and Lubbock County cotton operations are compressing replacement cycles below five years as water cost pressures intensify.
Canada
Prairie Provinces irrigation districts in Alberta and Saskatchewan are expanding pressurized system coverage for canola and pulse production. Health Canada and PMRA coordinate cross-border agricultural chemical runoff rules with EPA standards, harmonizing valve specification requirements in Great Lakes watersheds. Southern Ontario greenhouse clusters near Leamington are adopting pneumatic-actuated valves for rapid-cycling nursery applications.
Mexico
Northern border states of Chihuahua and Sonora are retrofitting flood-irrigation infrastructure with pressure-regulated drip systems for vegetable export production. CONAGUA groundwater permitting restrictions in the Colorado River basin are accelerating electric valve adoption among large-scale tomato and pepper growers. Mexicali Valley operations are integrating telemetry-enabled flow control to comply with Minute 323 treaty water accounting requirements.
North America Irrigation Valves Market Competitive Landscape
United States producers anchor the premium tier through backward integration into flow-control manufacturing; Israeli and Spanish specialists hold positions in precision emitter and filtration-integrated systems. The vendor base concentrates among three strategic tiers: diversified irrigation equipment conglomerates with captive valve production, standalone valve specialists focused on pressure-regulation technology, and import-dependent distributors serving cost-sensitive retrofits. Competitive moves center on portfolio diversification into smart-actuation platforms and geographic expansion through cooperative procurement consortia penetration.
Within the diversified equipment tier, Toro Company and Rain Bird exemplify scale-driven manufacturers with integrated flow-control operations spanning agricultural and landscape verticals. Nelson Irrigation occupies a specialist position in pressure-regulated emitter systems for drip-intensive growing regions. These three US-based entities represent contrasting archetypes: Toro Company demonstrates backward integration depth, Rain Bird illustrates brand strength across municipal specifications, and Nelson Irrigation exemplifies product specialization in high-margin precision agriculture niches.
| Leading Market Players |
|---|
| Ace Pump Corporation |
| Nelson Irrigation |
| Netafim USA |
| Hunter Industries |
| Toro Company |
| Rain Bird |
| Bermad CS Ltd |
| Fluidra S.A. (Capex) |
| Rivulis Irrigation |
| Others |
Pricing and Supply Chain Analysis
Cooperative procurement consortia in California's Central Valley are consolidating purchasing authority among multi-farm operations, forcing suppliers to restructure inventory toward pre-certified EPA WaterSense SKUs and compressing margins on non-compliant import alternatives.
Pricing Analysis
Capacity additions in Texas and California are reshaping price floors for electric-actuated valve systems as domestic manufacturers expand flow-control manufacturing footprints. Three-tier pricing structure across premium, standard, and economy levels separates telemetry-integrated systems from mechanical retrofits and PVC commodity valves. Cost compression in the manual valve tier is intensifying because brass and ductile iron input volatility squeezes foundry-grade metal margins. Agricultural cooperatives exhibit highest price sensitivity due to water cost pressures, while municipal golf course specifications show lowest sensitivity given aesthetic compliance mandates.
Supply Chain Analysis
Brass and ductile iron supply rests on domestic foundries in Ohio and Pennsylvania, with PVC resin sourcing anchored in Gulf Coast petrochemical corridors. Raw material dependencies span foundry-grade copper alloys, injection-molding thermoplastics, and solenoid actuator components from Mexico and China. Single-source vulnerability concentrates in precision pressure-transducer supply for smart valve controllers. Distribution runs through agricultural equipment dealerships and irrigation specialist distributors serving California and Texas corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America irrigation valves market operates as a regulatory compounder, with EPA Clean Water Act mandates under the WaterSense program creating durable demand for certified infrastructure upgrades across water-stressed watersheds.
For Market Incumbents: Lock in cooperative procurement consortia relationships across California almond and pistachio growing regions before channel consolidation displaces traditional distributor-led fragmentation. Prioritize captive supply of pressure-regulated emitter systems to defend margin position against Israeli and Spanish precision agriculture specialists. Secure EPA pre-certification for integrated valve-filter-actuator packages to maintain specification authority in federal cost-share programs. For New Entrants and Emerging Players: Direct-to-farm digital sales channels bypass entrenched distributor relationships in the Texas High Plains corridor where Ogallala Aquifer depletion accelerates electric valve adoption. Target cotton and grain operations in Lubbock County with telemetry-as-a-service bundling rather than capital-heavy hardware sales. Pursue white-label manufacturing partnerships with established flow-control producers to penetrate USDA conservation program eligibility lists. For Investors and Strategic Acquirers: Asymmetric upside sits with standalone valve specialists possessing pressure-regulation technology depth in drip-intensive growing regions. Long-term viability hinges on five-to-ten-year water scarcity trajectories across the Colorado River basin and Great Lakes watersheds. Watch for California groundwater withdrawal permitting decisions as the inflection indicator for electric-actuated deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flow-Control Manufacturing | Toro Company's captive production anchors North American cost competitiveness against import alternatives. |
| EPA WaterSense Certification Investment | Pre-certified SKU portfolios secure federal procurement eligibility and state rebate program access. |
| Telemetry Platform Integration | Smart valve controllers with embedded pressure transducers unify hardware with farm management software ecosystems. |
| Cooperative Procurement Consortia Penetration | Multi-farm buying groups in California's San Joaquin Valley displace traditional distributor channel fragmentation. |
| Cross-Border Supply Chain Localization | Mexico-based actuator assembly reduces tariff exposure and aligns with Minute 323 treaty compliance requirements. |
Research Methodology
Multiple input streams — structured interviews with irrigation equipment distributors, technical consultations with agricultural cooperative procurement managers, and regulatory filings with EPA WaterSense certification databases — were reconciled against customs trade data for brass and PVC valve imports, SEC 10-K disclosures from diversified equipment manufacturers, and USDA conservation program participation records. Primary fieldwork engaged plant engineers at Central Valley almond processing facilities, aftermarket service heads at Texas cotton gin operations, and municipal public works directors in Arizona and Colorado. Bottom-up unit economics for electric-actuated valve deployments were triangulated against top-down market sizing from agricultural census irrigation infrastructure surveys.
Historical replacement cycle patterns for mechanical versus electromechanical systems were cross-referenced against panel input from large-scale agricultural cooperatives regarding telemetry adoption intentions across the projection horizon. Segmentation modeling spanned valve geometry, control technology, end-user vertical, and installation configuration dimensions. CAGRs were derived from installed base growth rates and efficiency-mandated replacement acceleration. Forecast inputs incorporated EPA enforcement trajectory assumptions and state-level groundwater permitting restrictiveness in California and Texas.
The model assumes a particular technology adoption path; alternative pathways for hydraulic and pneumatic actuation in remote installations lacking electrical infrastructure would alter the outlook. Forecasts reflect assumptions regarding EPA WaterSense certification expansion and USDA cost-share program continuity. A small set of named triggers — California Sustainable Groundwater Management Act implementation timing, brass foundry capacity utilization swings, and cross-border water treaty renegotiation — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Fluid Handling Systems Market
Valves
Industrial Valves Market
Valves
Refrigeration Valves Market
Valves
Sand Control System Market
Valves
Butterfly Valves Market
Valves
Subsea Valves Market
Valves
Rupture Discs Market
Valves
Pipeline Equipment Market
Valves
Degassing Valves Market
Valves
Three Way Ball Valve Market
Valves
Aerospace Valves Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
China Explosion-Proof Equipment Market
Valves
Stainless Steel Valve Tag Market
Valves
Cryogenic Valve Market
Valves
Magnetic Coupler Market