
 South Africa Battery Market | 2026-2036
South Africa Battery Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Battery Market Analytics
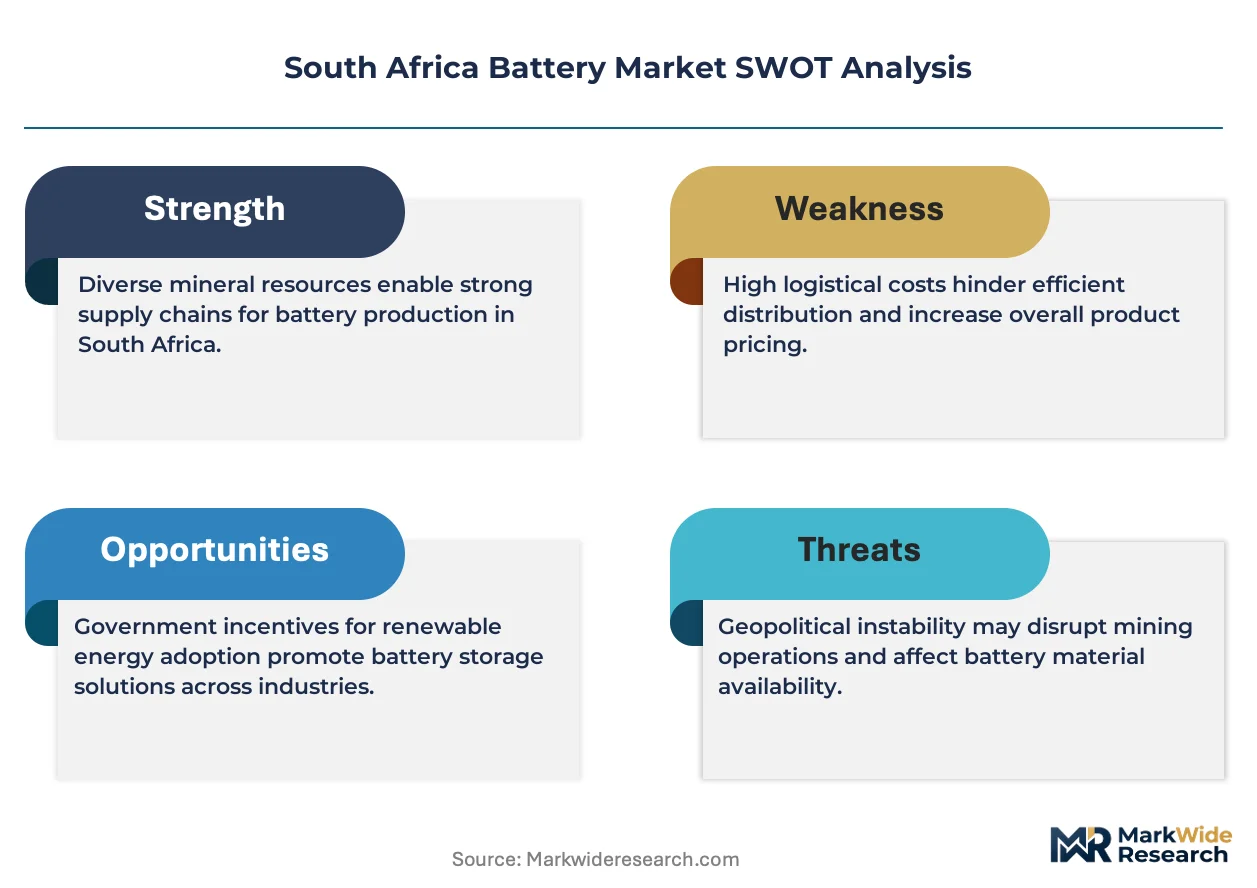
IRP procurement mandates is hardening the cost-of-entry calculus for new battery suppliers seeking utility-scale contracts. Exide Technologies leverages its established lead-acid manufacturing footprint to sustain industrial aftermarket dominance. BlueNova Energy specializes in lithium-iron-phosphate systems for commercial and residential solar-hybrid installations. Freedom Won anchors the premium residential segment with locally assembled energy storage units.
A battery electrochemically stores and releases electrical energy through reversible redox reactions, with lithium-ion cells typically achieving 150-250 Wh/kg energy density and cycle lives exceeding 3,000 deep discharges. These devices serve as critical enablers for grid stabilization, motive power, and backup electricity across industrial and consumer domains. Lead-acid technology still occupies the largest installed base in automotive starter and industrial standby roles, while lithium-ion chemistry captures the fastest growth in renewable energy storage applications where longer cycle life justifies higher upfront capital. The rechargeable technology segment dominates current manufacturing volumes, though solid-state architectures represent the emerging margin pool for next-generation product development.
South Africa's National Energy Regulator (NERSA) enforces grid connection standards that directly shape battery inverter and storage system certification requirements for behind-the-meter installations. The South African Bureau of Standards (SIS) maintains compulsory specifications for lead-acid batteries used in vehicle and stationary applications, while the Department of Mineral Resources and Energy (DMRE) governs procurement frameworks under the Integrated Resource Plan that mandate storage co-location with new renewable capacity. Stakeholders must monitor how NERSA's evolving wheeling regulations reshape the economics of commercial-scale battery arbitrage between industrial consumers and municipal distributors.
Market Dynamics
The Integrated Resource Plan's storage-linked procurement mandates are compressing contract timelines and hardening technical specifications for battery suppliers targeting South African utility-scale projects.
Growth Catalysts
- IRP Storage Mandates:The Department of Mineral Resources and Energy requires co-located battery storage with new renewable capacity, creating guaranteed offtake for grid-scale lithium-ion systems.
- Northern Cape Mining Electrification:Off-grid lithium-ion deployments at remote extraction sites are displacing diesel gensets, driven by fuel logistics costs and carbon reduction targets.
- Gauteng Industrial Corridor Load Shedding Response:Manufacturing and data center operators in Johannesburg and Pretoria are procuring behind-the-meter battery systems to ensure operational continuity during grid instability.
Market Restraints
- Lithium Carbonate Price Volatility:Input cost swings for cathode active materials compress margin predictability for domestic pack assemblers lacking long-term offtake agreements.
- East Asian Cell Supply Concentration:South African integrators remain dependent on imported cylindrical and prismatic cells from concentrated East Asian manufacturing hubs, exposing projects to shipping bottlenecks.
- NERSA Certification Timelines:Grid connection standards for battery inverters create extended approval cycles that delay commercial commissioning and revenue recognition.
Strategic Opportunities
- Eastern Cape Renewable Zones:Coega and adjacent port infrastructure offer underutilized land and logistics access for battery assembly facilities serving export markets into Sub-Saharan Africa.
- Solar-Plus-Storage Hybrid Procurement:Commercial and industrial buyers are bundling photovoltaic and battery installations, creating integrated project pipelines that favor turnkey system providers.
- Wheeling Regulation Evolution:NERSA's developing frameworks for private power trading between industrial consumers and municipal distributors enable new arbitrage revenue streams for distributed storage assets.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Domestic universities produce limited graduates with battery-specific expertise in thermal management, cell characterization, and system integration.
- Lead-Acid Recycling Infrastructure Gaps:Reverse logistics for end-of-life automotive and industrial batteries remain fragmented, complicating environmental compliance for established suppliers.
- Legacy System Integration Complexity:Retrofitting battery storage into existing diesel-dependent microgrids at mining and remote industrial sites requires custom control architecture and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Battery Market |
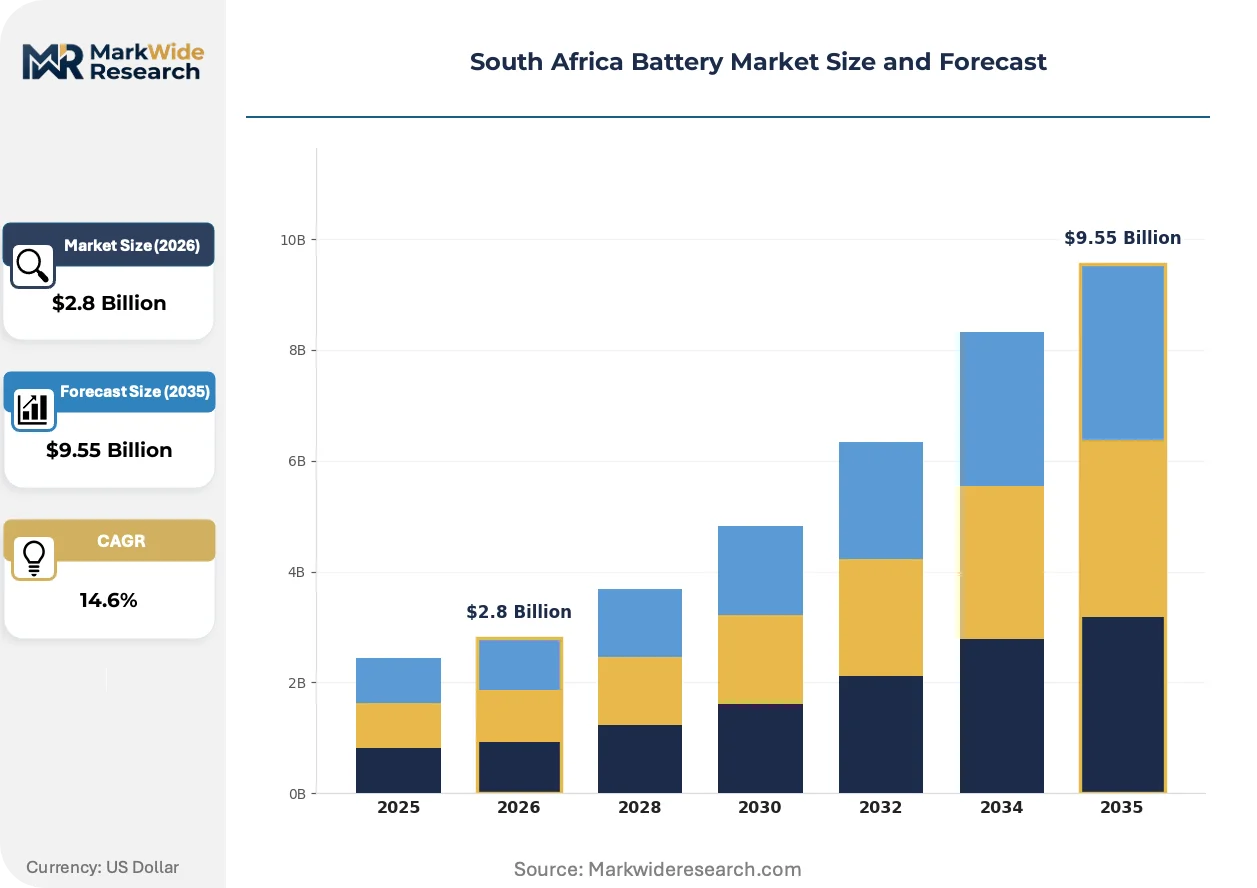
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Flow Application: Electric Vehicles, Renewable Energy Storage, Uninterruptible Power Supply, Consumer Electronics End User: Residential, Commercial, Industrial, Automotive Technology: Rechargeable, Solid-state, Thermal, Hybrid |
| Companies Covered | Exide Technologies, Eveready, BlueNova Energy, Deltec Power Solutions, Solar MD, Freedom Won, Duracell Inc, Energizer Holdings Inc, Hubble Lithium, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Battery Market Evolving Landscape
Lithium-iron-phosphate chemistry is reshaping competitive positioning across South Africa's stationary storage segment, while regulatory pressure on procurement transparency and buyer behavior around energy security are creating parallel transformation vectors.
Lithium-iron-phosphate cells achieve superior thermal stability and cycle life compared to nickel-manganese-cobalt alternatives, making them the default choice for commercial solar-hybrid installations. Mining operators and industrial facilities in the Northern Cape and Gauteng are specifying LFP exclusively for multi-megawatt-hour projects. This chemistry is overtaking nickel-based alternatives in utility-scale tenders, compressing the addressable market for higher energy-density formulations that cannot demonstrate equivalent safety certification under South African Bureau of Standards testing protocols.
The Department of Mineral Resources and Energy's Bid Window framework under the Integrated Resource Plan now mandates disclosed storage duration and round-trip efficiency metrics for all awarded projects. This transparency requirement is disqualifying suppliers lacking independent testing documentation and forcing technology providers to invest in domestic certification partnerships. Grid-scale developers targeting Northern Cape and Western Cape renewable zones are responding by pre-qualifying only battery systems with existing South African Bureau of Standards compliance records.
Industrial buyers are consolidating procurement authority from site-level engineers to centralized energy management teams with capital allocation authority. This shift is compressing vendor evaluation cycles and favoring suppliers offering performance guarantees and long-term service contracts over equipment-only transactions. The concentration is most visible in Gauteng's manufacturing corridor, where Johannesburg-based procurement functions now direct battery investments across multi-site corporate portfolios rather than delegating to individual facility managers.
South Africa Battery Market Segmentation
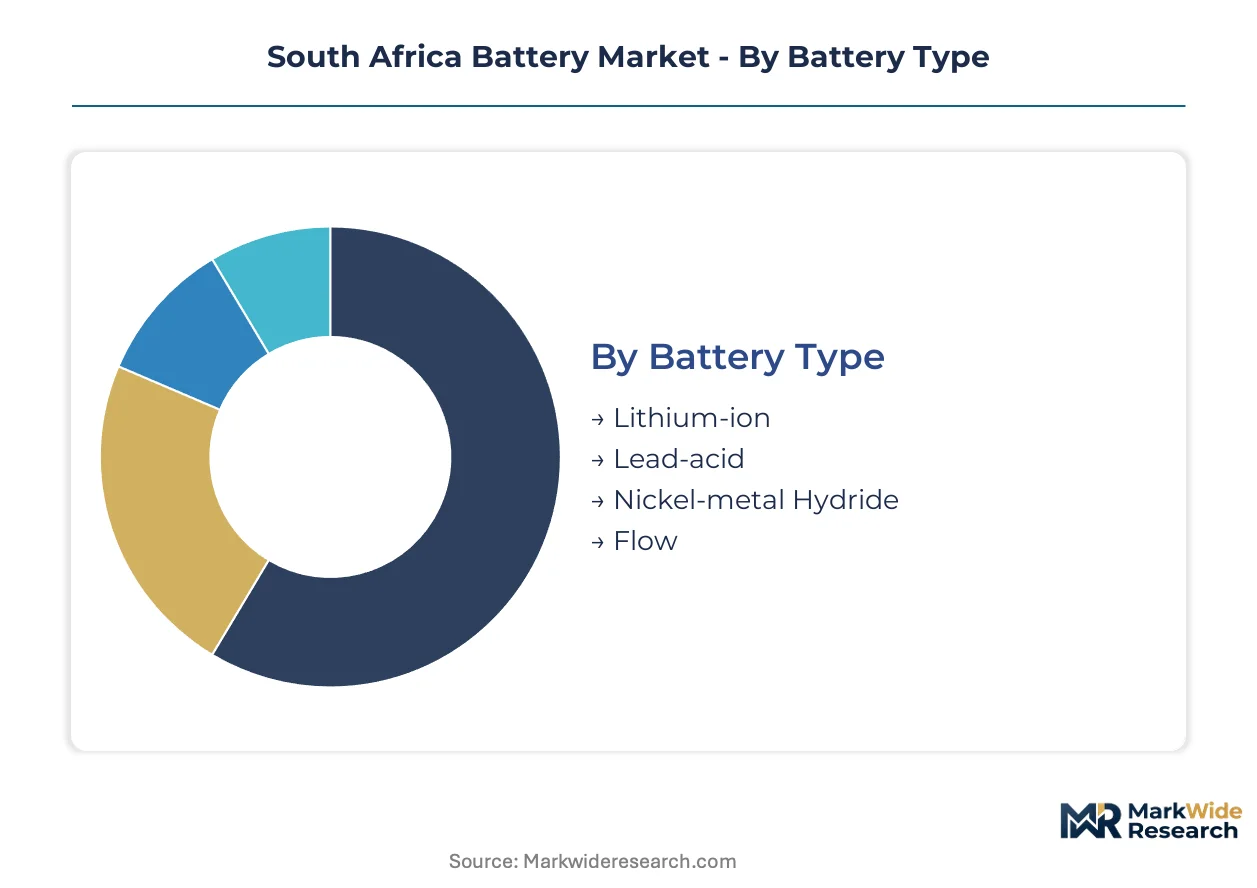
Battery demand across South Africa fragments along electrochemical chemistry, integration depth, and buyer sophistication. Each segmentation axis reveals distinct procurement patterns shaped by NERSA regulations, mining electrification timelines, and Gauteng industrial load-shedding response.
Battery Type:
Standalone battery systems dominate utility-scale and mining deployments, while embedded cells power automotive and consumer electronics manufacturing.
- Lithium-ion:Lithium-iron-phosphate and nickel-manganese-cobalt cells achieve 150-250 Wh/kg energy density with cycle lives exceeding 3,000 discharges. Northern Cape mining operators specify these exclusively for off-grid microgrids displacing diesel gensets, driven by fuel logistics costs and DMRE carbon reduction mandates.
- Lead-acid:Flooded and valve-regulated designs deliver lower energy density but maintain cost advantages in automotive starter and industrial standby roles. Exide Technologies sustains aftermarket dominance through its established manufacturing footprint serving Gauteng's vehicle assembly plants and mining equipment fleets.
- Nickel-metal Hydride:Hybrid electric vehicle battery packs retain niche presence in Toyota's local assembly operations.
- Flow:Vanadium redox systems offer extended duration storage for utility-scale renewable co-location projects in the Western Cape.
Volume placements concentrate in Lead-acid; the faster expansion belongs to Lithium-ion.
Application:
Procurement authority is shifting from site engineers to centralized energy teams, reshaping how each application category captures capital allocation.
- Electric Vehicles:Battery electric and plug-in hybrid platforms require high-discharge-rate cell configurations with thermal management systems. BMW and Volkswagen's local manufacturing facilities in the Eastern Cape are integrating domestic pack assembly to qualify for automotive production incentives.
- Renewable Energy Storage:Grid-scale lithium-ion systems co-located with solar and wind capacity must demonstrate South African Bureau of Standards certification under DMRE Bid Window mandates. Western Cape and Northern Cape renewable zones are hardening technical specifications that disqualify suppliers lacking independent testing documentation.
- Uninterruptible Power Supply:Data centers and financial institutions in Johannesburg's Sandton district specify lithium-iron-phosphate for behind-the-meter continuity during NERSA-mandated load shedding.
- Consumer Electronics:Smartphone and laptop cells flow through import channels with minimal domestic value addition.
Revenue concentration sits with Renewable Energy Storage; steepest expansion trajectory runs through Electric Vehicles.
End User:
Capital deployment scale and technical sophistication vary sharply across buyer categories, with industrial purchasers commanding longest contract durations.
- Residential:Solar-hybrid installations with 5-20 kWh lithium-iron-phosphate systems are climbing fastest in Johannesburg's northern suburbs and Cape Town's Atlantic seaboard, driven by municipal tariff escalation and load-shedding frequency.
- Commercial:Retail chains and office complexes procure 100-500 kWh systems through turnkey providers offering performance guarantees and long-term service contracts.
- Industrial:Mining houses and manufacturing groups in Gauteng's corridor specify multi-megawatt-hour installations with custom control architecture for diesel microgrid retrofit.
- Automotive:Original equipment manufacturers source starter batteries and traction packs through qualified supplier programs with stringent SIS compliance requirements.
Contract value peaks in Industrial; residential installations are gaining share fastest.
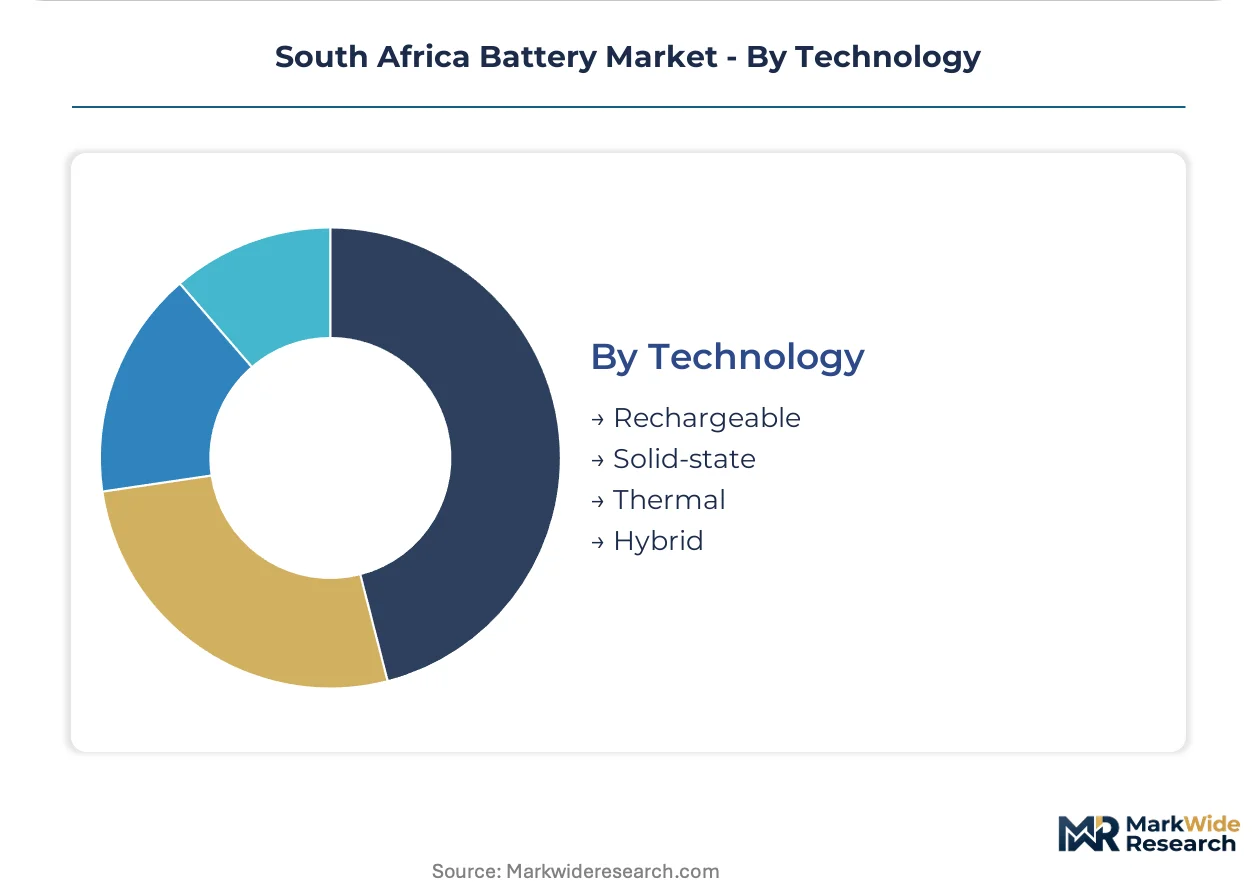
Technology:
Maturity curves and margin profiles diverge sharply, with incumbent chemistries defending volume while emerging architectures capture development premiums.
- Rechargeable:Lithium-ion and lead-acid dominate current manufacturing volumes across all end-use categories, with established recycling infrastructure for lead and developing reverse logistics for lithium.
- Solid-state:Ceramic electrolyte architectures promise enhanced safety and energy density for next-generation electric vehicle platforms, though commercial deployment remains pre-qualification.
- Thermal:Molten salt and phase-change systems serve concentrated solar power plants in the Northern Cape with multi-hour discharge capability.
- Hybrid:Supercapacitor-battery combinations address high-power applications in mining equipment requiring rapid charge acceptance.
Installed base concentrates in Rechargeable; Solid-state holds the emerging margin pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Coega Special Economic Zone in the Eastern Cape is emerging as a battery assembly hub, leveraging port infrastructure and underutilized industrial land to serve Sub-Saharan African export markets.
Gauteng
Johannesburg and Pretoria anchor the country's densest battery demand cluster. Manufacturing and data center operators procure behind-the-meter lithium-iron-phosphate systems to ensure continuity during NERSA-mandated load shedding. The provincial industrial corridor concentrates procurement authority within centralized energy management teams.
Western Cape
Grid-scale renewable co-location projects drive utility-scale storage procurement. The Department of Mineral Resources and Energy's Bid Window framework mandates disclosed storage duration metrics that disqualify suppliers lacking South African Bureau of Standards certification. Cape Town's Atlantic seaboard residential segment climbs fastest for solar-hybrid installations.
Northern Cape
Remote mining electrification displaces diesel gensets with off-grid lithium-ion microgrids. Fuel logistics costs and DMRE carbon reduction targets accelerate deployments at extraction sites. The province's concentrated solar power plants deploy molten salt thermal storage with multi-hour discharge capability.
Eastern Cape
Automotive manufacturing incentives attract BMW and Volkswagen local pack assembly operations. The Coega IDZ offers logistics access for battery assembly facilities targeting export markets. Port infrastructure supports incoming cell supply chains from East Asian manufacturing hubs.
KwaZulu-Natal
Durban's manufacturing base sustains industrial standby battery demand for port logistics and chemical processing operations. The province's automotive supplier network sources starter batteries through qualified supplier programs with stringent SIS compliance requirements.
South Africa Battery Market Competitive Landscape
Gauteng-based producers anchor the industrial aftermarket tier; Eastern Cape specialists hold the automotive integration vector. Market structure fragments across established lead-acid manufacturers, lithium-ion system integrators, and emerging solar-hybrid providers. Three archetypes dominate: legacy industrial suppliers defending aftermarket service contracts, renewable-focused system integrators capturing solar-plus-storage bundles, and premium residential specialists offering performance guarantees. Competitive moves concentrate on certification partnerships with NERSA and SABS, plus geographic expansion into Sub-Saharan African export markets.
Among established industrial suppliers, Exide Technologies and Eveready occupy positions defending lead-acid dominance in automotive starter and mining equipment applications. BlueNova Energy and Freedom Won exemplify the lithium-ion system integration archetype, with Freedom Won anchoring premium residential positioning through locally assembled units. Hubble Lithium represents the emerging specialist tier targeting commercial and industrial solar-hybrid configurations.
| Leading Market Players |
|---|
| Exide Technologies |
| Eveready |
| BlueNova Energy |
| Deltec Power Solutions |
| Solar MD |
| Freedom Won |
| Duracell Inc |
| Energizer Holdings Inc |
| Hubble Lithium |
| Others |
Value Network & Pricing Analysis
Lithium carbonate cathode active materials flow from concentrated East Asian processing hubs through tiered pricing structures that penalize South African pack assemblers lacking long-term offtake agreements. Procurement officers at Gauteng industrial facilities and Northern Cape mining operations face compressed margins when spot market volatility disrupts contract negotiations.
Pricing Analysis
Lead-time premiums for cylindrical and prismatic cells arriving through Durban port infrastructure separate urgent procurement from scheduled inventory builds. Three-tier pricing structure across premium certified, standard import, and economy spot tiers reflects NERSA certification status and South African Bureau of Standards compliance documentation. Price differentiation hinges on thermal management system integration and cycle life guarantees. Cost compression in the standard tier is intensifying because East Asian cell manufacturers are prioritizing contracted volumes over spot sales. Mining procurement teams demonstrate lowest price sensitivity due to diesel displacement economics, while residential solar-hybrid buyers in Johannesburg's northern suburbs negotiate hardest on upfront capital.
Supply Chain Analysis
Single-source vulnerability sits with cylindrical cell supply from concentrated manufacturing hubs in China, South Korea, and Japan. Raw material dependencies span lithium spodumene concentrate from Western Australia, cobalt hydroxide from the Democratic Republic of Congo, and nickel sulfate from Indonesian processing facilities. Supply chain risk centers on shipping bottlenecks through the Suez Canal route affecting Durban port delivery schedules. Distribution runs through Coega IDZ assembly facilities for domestic integration and direct-to-project logistics for utility-scale deployments in Northern Cape renewable zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's battery market sits in a technology-transition phase where lithium-iron-phosphate chemistry systematically displaces lead-acid dominance across stationary storage applications.
For Market Incumbents: Extend certification partnerships with NERSA and South African Bureau of Standards to defend utility-scale procurement eligibility against emerging system integrators. Anchor aftermarket service contracts for Gauteng mining equipment fleets while building backward integration into lithium-iron-phosphate pack assembly at Coega IDZ facilities. The threat of DMRE Bid Window disqualification for non-compliant suppliers creates urgency around documentation investment. For New Entrants and Emerging Players: The price-point gap between Freedom Won's premium residential positioning and unbranded import tiers opens white-space capture for mid-market solar-hybrid configurations. Target Eastern Cape automotive supplier networks with qualified supplier program pre-qualification. The most penetrable segment sits with commercial and industrial buyers in Durban's manufacturing corridor seeking performance-guaranteed turnkey installations without premium branding. For Investors and Strategic Acquirers: NERSA's evolving wheeling regulation publication is the leading indicator that distributed storage arbitrage economics are approaching viability for portfolio-scale deployment. Acquisition targets should display existing SABS certification records and established relationships with DMRE Bid Window developers. Long-term viability across the projection horizon favors integrators with captive port logistics access and domestic assembly footprint.| Strategic Initiative | Industry Significance |
|---|---|
| SABS Certification Investment | Unlocks DMRE Bid Window eligibility for utility-scale renewable co-location projects. |
| Coega IDZ Assembly Footprint | Secures port logistics access for incoming East Asian cell supply chains. |
| Long-term Lithium Carbonate Offtake | Insulates pack assemblers from cathode active material spot price volatility. |
| Wheeling Regulation Partnership | Positions distributed storage assets for municipal distributor arbitrage revenue. |
| Mining Microgrid Retrofit Specialization | Captures diesel displacement demand across Northern Cape extraction sites. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this South Africa battery market assessment. Primary interviews with DMRE procurement officers, NERSA grid connection specialists, EPC contractors at Northern Cape renewable zones, and energy management directors at Gauteng manufacturing groups combined with secondary validation from SABS certification databases and port authority import manifests. Bottom-up cell shipment tracking and top-down renewable capacity installation data were triangulated to construct market size estimates.
Data-stream reconciliation across electrochemical chemistry, application category, and end-user segmentation dimensions produced volume and value outputs across the analysis window. Modeled segments included lithium-ion, lead-acid, and flow battery chemistries; electric vehicle, renewable energy storage, and uninterruptible power supply applications; and residential, commercial, and industrial end-user categories. CAGRs were derived from installation run-rate trending and procurement pipeline aggregation. Forecast inputs incorporated DMRE Bid Window award timelines and mining electrification capex commitments.
Inputs from NERSA regulatory publications and DMRE procurement announcements were available through the study window; gaps in confidential contract pricing introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding wheeling regulation implementation pace and lithium carbonate price normalization. Specific risks that could revise projections include extended SABS certification delays and Suez Canal shipping disruptions affecting cell import schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
South America Consumer Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Semi-Solid Flow Battery Market
Batteries
Global Coke Oven Batteries Market
Batteries
Taiwan Battery Market
Batteries
North America Consumer Battery Market
Batteries
Lead Acid Battery Market
Batteries
Inverter Battery Market
Batteries
Electric Battery Market
Batteries
Battery Separators Market
Batteries
Global Solar Battery Charger Market
Batteries
Coin Cell Lithium Batteries Market
Batteries
Iron Salt Battery Market
Batteries
Global Zinc Air Batteries Market
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
Portable Battery Market