
 South America Battery Cell Market | 2026-2036
South America Battery Cell Market Size, Share, and Industry Trends Forecast 2026-2036
South America Battery Cell Market Analytics
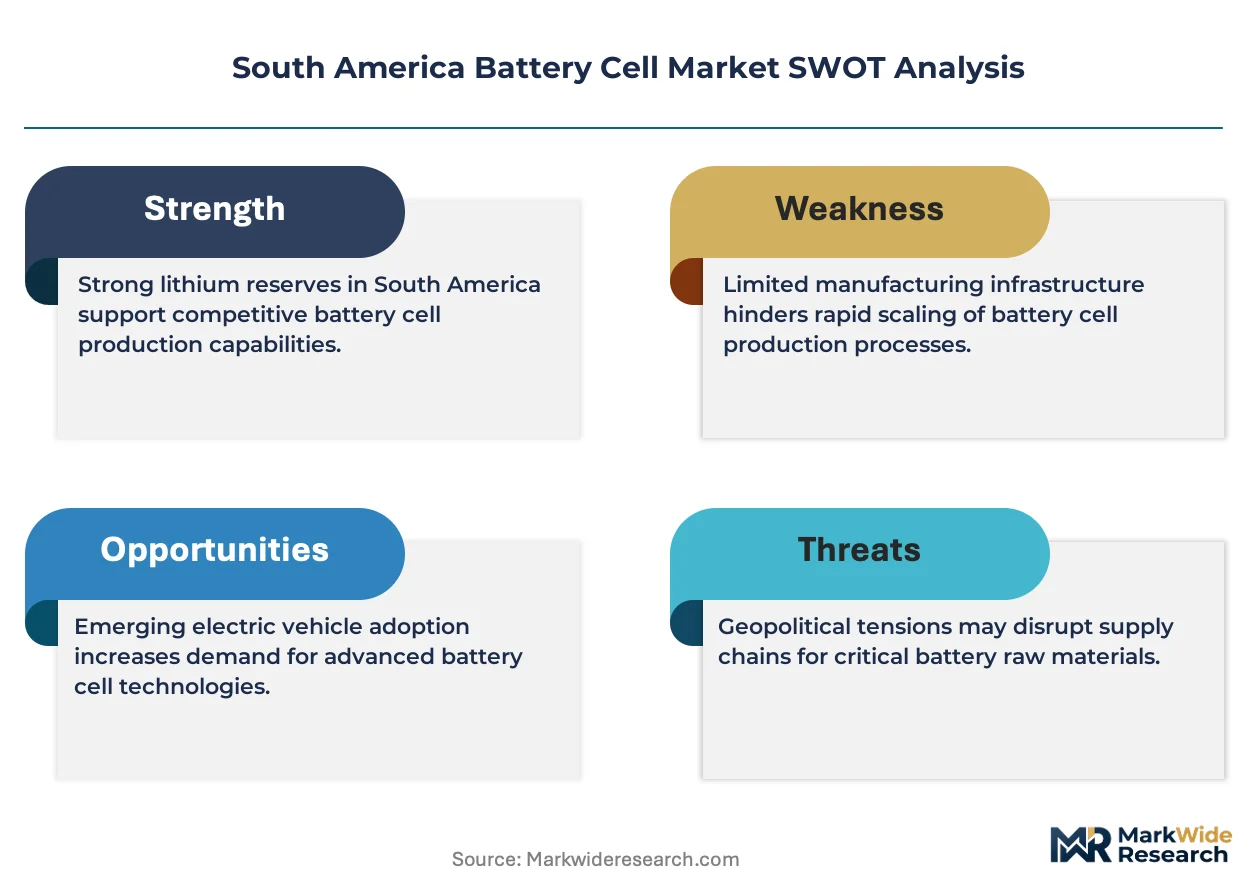
Brazilian lithium refining infrastructure is pivoting toward cathode precursor production to reduce import dependency. BYD Co. Ltd leverages its integrated cell-to-pack manufacturing footprint in the Campinas technology cluster. Contemporary Amperex Technology Co. Limited anchors regional supply through binding offtake agreements with Brazilian energy storage developers. Samsung SDI competes on high-nickel chemistry specialization for tropical climate performance.
A battery cell is an electrochemical device comprising an anode, cathode, separator, and electrolyte that converts stored chemical energy into electrical energy through reversible redox reactions, with nominal voltages ranging from 3.2V for lithium iron phosphate to 4.2V for nickel manganese cobalt variants. These cells serve as the foundational energy storage unit in electric vehicles, grid-scale storage installations, and portable electronics across South American industrial and consumer markets. Lithium-ion chemistry dominates installed capacity due to energy density advantages, while sodium-ion technology is gaining traction for stationary storage applications where weight constraints matter less. Automotive applications command the largest revenue pool, though renewable energy pairing with solar and wind farms represents the fastest-expanding demand segment as Chilean and Colombian utilities procure buffer capacity.
Brazil's ANEEL mandates grid-connected storage compliance standards, while INMETRO certification governs cell safety and cycle life claims for consumer-facing products. Argentina's Secretaría de Energía enforces local content thresholds for renewable project financing, directly shaping procurement decisions by battery integrators. Stakeholders must monitor how evolving MERCOSUR technical regulations on hazardous material transport and end-of-life cell recycling reshape cross-border supply chain economics and manufacturing location choices.
Market Dynamics
ANEEL's grid-connected storage compliance standards are forcing Brazilian utilities to accelerate procurement timelines, compressing the traditional equipment qualification cycle and reshaping supplier qualification criteria across the regional value chain.
Growth Catalysts
- ANEEL Storage Mandates:Brazil's grid compliance standards obligate utilities to install buffer capacity, creating guaranteed procurement pipelines for lithium-ion integrators serving the southeastern manufacturing corridor.
- Electric Bus Fleets:Santiago and São Paulo municipal operators are scaling lithium-ion pack orders as diesel replacement deadlines harden, anchoring demand for high-cycle-life cell chemistries.
- Inova Energia Program:BNDES financing redirects supply chains toward domestic assembly, incentivizing cathode precursor production within Brazilian borders.
Market Restraints
- Lithium Carbonate Volatility:Input cost swings for lithium hydroxide and carbonate feedstocks compress cell manufacturer margins, particularly for producers without captive mining offtake.
- Import Dependency:Cathode active material supply concentrates in East Asian refining hubs, exposing Brazilian assemblers to shipping cost spikes and currency fluctuation risk.
- Thermal Management Limits:High-nickel NMC cells face accelerated degradation in Amazon basin humidity, restricting deployment geography for certain chemistry formulations.
Strategic Opportunities
- Colombian Utility Storage:Grid operators in the Andean region are procuring buffer capacity for solar-wind pairing, creating first-mover positioning for integrators with local certification.
- Sodium-Ion Stationary Applications:Weight-tolerant grid storage and rural microgrids are adopting sodium-ion cells, opening chemistry diversification paths beyond lithium dependence.
- Argentine Local Content Thresholds:Secretaría de Energía mandates for renewable project financing create captive demand for regionally assembled battery systems.
Industry Challenges
- INMETRO Certification Timelines:Cell safety and cycle life validation protocols extend product launch schedules, delaying revenue recognition for new chemistry introductions.
- MERCOSUR Hazardous Transport Harmonization:Cross-border regulatory misalignment on end-of-life cell movement creates compliance friction for multi-country operators.
- Electrolyte Formulation Talent Scarcity:Specialized electrochemists capable of tropical-climate electrolyte optimization remain concentrated in legacy automotive markets outside the region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Battery Cell Market |
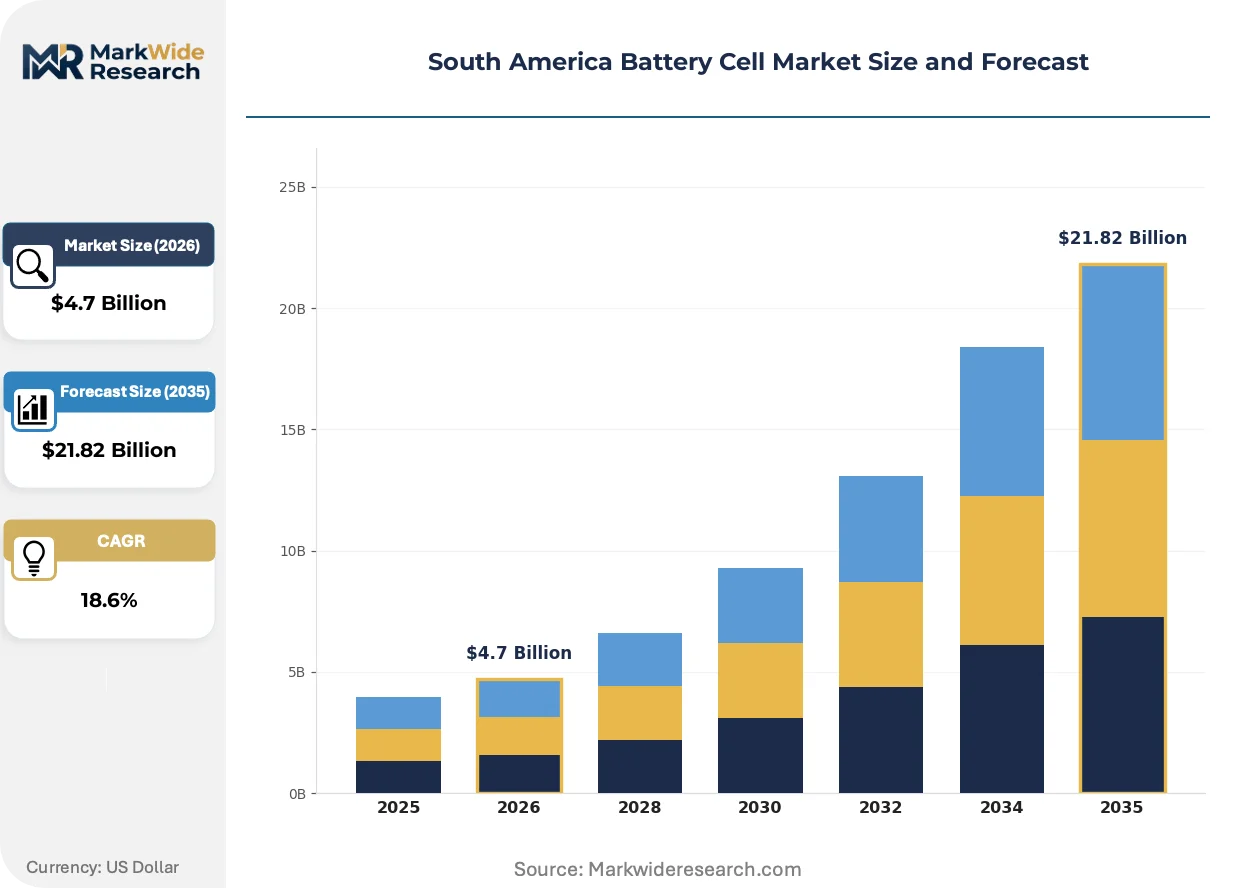
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel Cadmium, Lead Acid, Sodium-ion Application: Consumer Electronics, Automotive, Renewable Energy, Industrial Equipment End User: Retail, Manufacturing, Telecommunications, Healthcare Technology: Solid State, Lithium Polymer, Flow Battery, Nickel Metal Hydride |
| Companies Covered | BYD Co. Ltd, Contemporary Amperex Technology Co. Limited, Samsung SDI, LG Energy Solution, Panasonic Corporation, EnerSys, Duracell Inc., Saft Groupe SA, Enel S.p.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Battery Cell Market Evolving Landscape
Cell-to-pack architectures and solid-state prototyping are compressing conventional module assembly steps, while regulatory pressure on supply chain provenance is accelerating traceability technology deployment across the Andean and Atlantic corridors.
Sodium-ion chemistry is decentralizing stationary storage procurement decisions. The technology eliminates cobalt and nickel feedstock exposure, enabling Colombian and Chilean utilities to source cells without hard currency import exposure. Regional integrators are qualifying sodium-ion systems for solar-buffer installations where energy density penalties matter less than capital cost stability.
Brazil's INMETRO certification framework is tightening cycle life disclosure requirements for consumer-facing products. Cell manufacturers must now submit third-party validated degradation curves, raising documentation costs but filtering substandard imports. The mandate most affects portable power and residential storage segments, where warranty claims previously outpaced actual performance.
Utility procurement committees are consolidating supplier relationships around binding offtake structures rather than spot purchasing. Chilean and Colombian grid operators now favor multi-year volume commitments with price adjustment clauses, displacing the project-by-project tendering that dominated early storage deployments. This concentration is most visible in transmission-connected solar farms, where EPC contractors bundle cell supply into turnkey construction contracts.
South America Battery Cell Market Segmentation
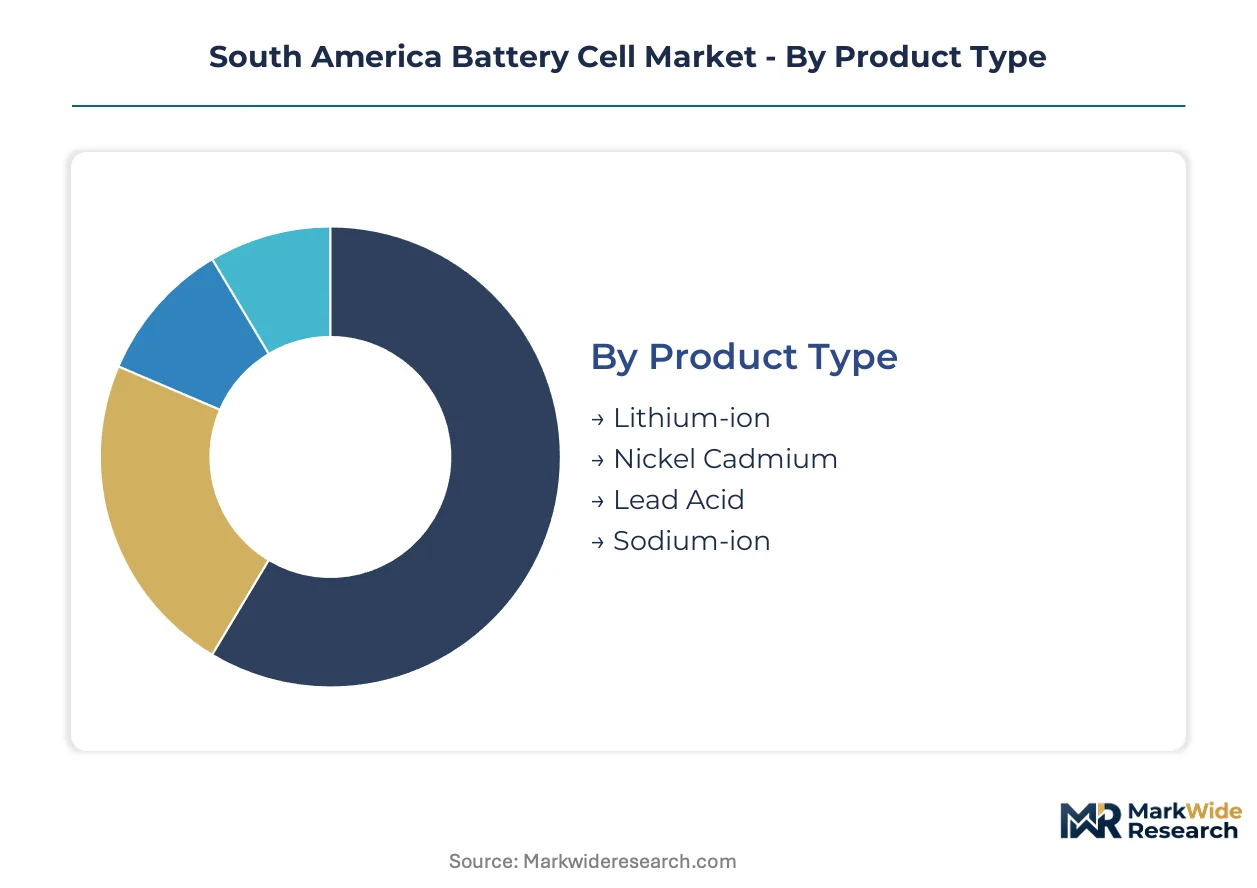
Battery cell procurement patterns across South America diverge sharply by chemistry maturity and application requirements. Segment boundaries reflect how ANEEL mandates, electric bus fleet specifications, and renewable energy pairing needs reshape supplier priorities across the southeastern manufacturing corridor.
Product Type:
Lithium-ion chemistry commands revenue concentration due to energy density advantages in mobility applications, while sodium-ion gains traction where weight constraints relax.
- Lithium-ion:Reversible intercalation chemistry delivers 150-300 Wh/kg energy density with 3.2-4.2V nominal outputs. Santiago and São Paulo electric bus operators specify NMC and LFP variants for high-cycle-life duty. ANEEL grid mandates anchor procurement volume for utility-scale installations.
- Sodium-ion:Prussian white cathode chemistry eliminates cobalt and nickel feedstock exposure, trading 30-40% energy density penalty for capital cost stability. Colombian utility solar-buffer installations adopt this chemistry fastest as hard currency import exposure diminishes procurement risk.
- Lead Acid:Mature flooded and VRLA architectures persist in telecommunications backup and rural microgrids where capital constraints override cycle life requirements.
- Nickel Cadmium:Sintered plate construction survives in extreme temperature industrial applications where memory effect tolerance exceeds replacement cost sensitivity.
Mature deployment sits with Lead Acid. Newer deployment is concentrated in Sodium-ion.
Application:
End-use demand splits between mobility mandates with hard deadlines and renewable pairing with volume scaling timelines.
- Automotive:Cell-to-pack architectures compress module assembly steps for São Paulo and Santiago bus fleet electrification. BNDES Inova Energia financing redirects procurement toward Brazilian-assembled packs.
- Renewable Energy:Transmission-connected solar farms in Chile and Colombia bundle cell supply into EPC turnkey contracts with multi-year offtake structures.
- Consumer Electronics:INMETRO certification requirements tighten cycle life disclosure for portable power segments, raising documentation costs for importers.
- Industrial Equipment:Forklift and material handling electrification concentrates in Minas Gerais manufacturing zones with captive fleet conversion programs.
Volume leadership rests with Automotive. Steepest expansion trajectory belongs to Renewable Energy.
End User:
Procurement authority concentrates differently across sectors with varying technical specification capabilities and financing access.
- Manufacturing:Southeast Brazilian industrial corridors specify high-nickel NMC cells for captive fleet electrification and process power backup.
- Telecommunications:Tower operators in Amazon basin states prioritize thermal-tolerant chemistries given humidity degradation risks.
- Retail:Consumer-facing channels face INMETRO warranty claim scrutiny, filtering substandard imports through third-party validation requirements.
- Healthcare:Uninterruptible power systems for medical equipment demand validated cycle life curves under tighter reliability protocols.
Contract scale peaks with Manufacturing. Certification complexity weighs heaviest on Retail.
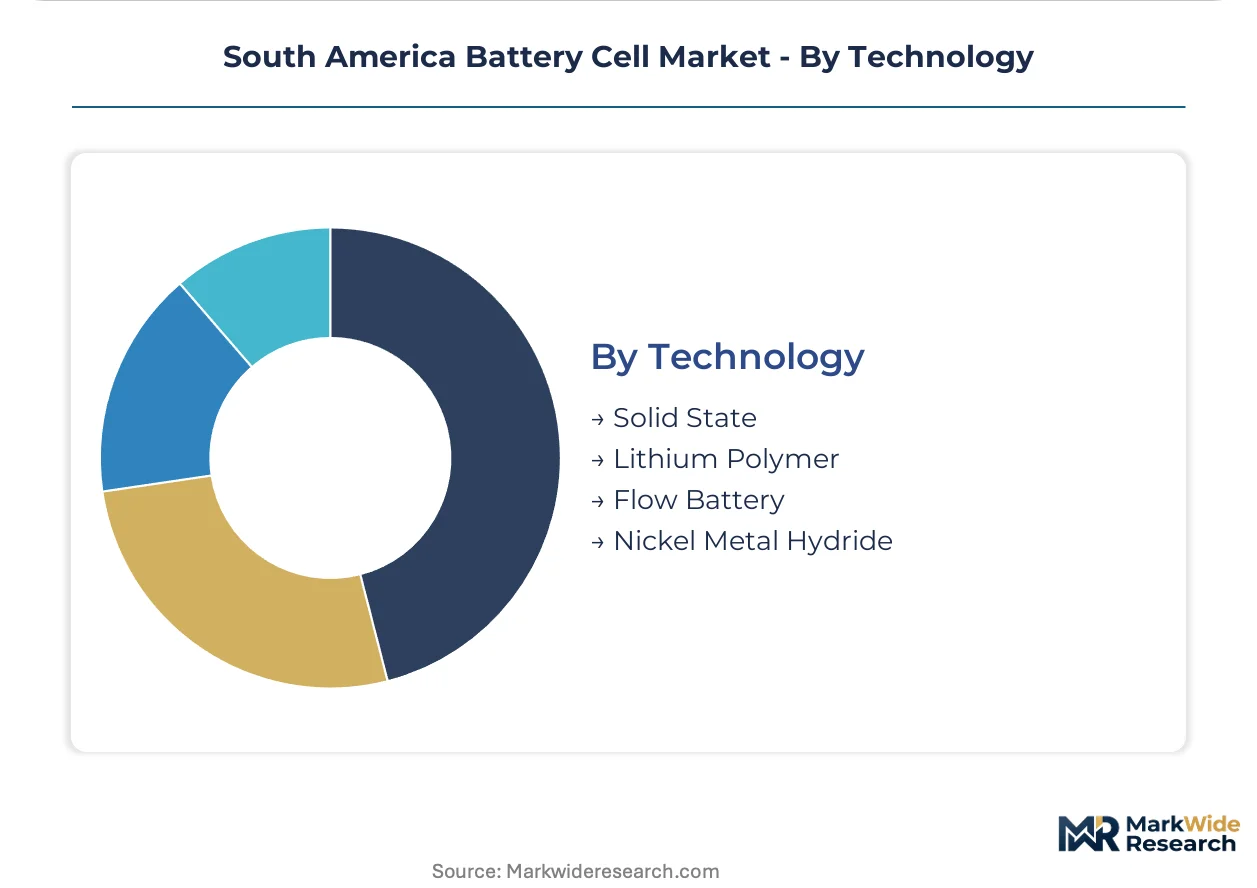
Technology:
Cell architecture evolution compresses conventional assembly while electrolyte formulation advances address tropical climate performance limits.
- Lithium Polymer:Pouch cell construction enables flexible form factors for consumer electronics and drone applications across Brazilian retail channels.
- Solid State:Ceramic electrolyte prototyping targets 400+ Wh/kg density for next-generation electric bus range extension, though manufacturing scale remains pre-commercial.
- Flow Battery:Vanadium redox systems serve grid-scale duration storage in Chilean transmission-connected solar farms where discharge duration exceeds lithium economics.
- Nickel Metal Hydride:Rare earth hydride chemistry retains niche in hybrid vehicle auxiliary power where proven supply chains outweigh lithium conversion costs.
Commercial maturity clusters with Lithium Polymer. Development investment concentrates on Solid State.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lithium Triangle spanning Chile, Argentina, and Bolivia anchors South American battery cell demand through brine extraction and downstream processing ambitions.
Brazil
São Paulo electric bus fleets and Minas Gerais industrial corridors drive lithium-ion procurement volume. ANEEL grid-connected storage compliance standards obligate utilities to install buffer capacity, compressing equipment qualification cycles. The southeastern manufacturing belt concentrates cathode precursor assembly plants seeking BNDES Inova Energia financing.
Chile
Atacama Desert lithium brine operations feed regional cathode material supply chains. Transmission-connected solar farms in the northern regions bundle cell supply into EPC turnkey contracts with multi-year offtake structures. The national mining regulator enforces environmental compliance standards for extraction licensees.
Argentina
Jujuy and Salta provinces host lithium carbonate refineries pivoting toward battery-grade hydroxide production. Secretaría de Energía local content thresholds for renewable project financing shape procurement decisions by battery integrators. Cauchari-Olaroz complex anchors industrial clustering for upstream material processing.
Colombia
Andean grid operators procure buffer capacity for solar-wind pairing, creating first-mover positioning for certified integrators. The national mining agency regulates lithium exploration concessions in the eastern plains. Bogotá-based utilities consolidate supplier relationships around binding multi-year volume commitments.
Peru
Amazon basin telecommunications tower operators prioritize thermal-tolerant chemistries for backup power in high-humidity zones. The Ministry of Energy and Mines oversees grid interconnection standards for remote microgrids. Lima industrial zones concentrate material handling fleet electrification programs.
South America Battery Cell Market Competitive Landscape
Global majors compete with regional champions across technology licensing and local assembly partnerships. The market structure tiers between integrated cell-to-pack manufacturers, chemistry specialists, and regional system integrators. Three archetypes dominate: East Asian giants with captive raw material offtake, European industrial battery incumbents, and Latin American assemblers leveraging domestic content rules. Capacity expansion and strategic partnerships constitute the dominant competitive moves reshaping positioning.
Among East Asian integrated manufacturers, BYD Co. Ltd and Contemporary Amperex Technology Co. Limited occupy positions exemplifying vertical control from mineral processing through pack assembly. Samsung SDI represents the chemistry specialization archetype, with high-nickel formulation expertise serving tropical climate requirements. These three entities anchor the competitive framework through distinct strategic postures: manufacturing integration, supply chain control, and climate-adapted product development.
| Leading Market Players |
|---|
| BYD Co. Ltd |
| Contemporary Amperex Technology Co. Limited |
| Samsung SDI |
| LG Energy Solution |
| Panasonic Corporation |
| EnerSys |
| Duracell Inc. |
| Saft Groupe SA |
| Enel S.p.A. |
| Others |
Value Network & Pricing Analysis
Lithium carbonate price volatility cascades through South American battery cell supply chains, compressing margins for Brazilian assemblers without captive mining offtake while amplifying procurement risk premiums for Colombian and Chilean utility buyers.
Pricing Analysis
Warranty bundling separates premium-tier suppliers from unbundled commodity sellers across the Andean corridor. Three-tier pricing structure across premium, standard, and economy levels reflects INMETRO certification grade and cycle life validation depth. Cost compression in the standard tier intensifies because Argentine local content mandates force integrators to absorb documentation overhead. Municipal electric bus operators in São Paulo and Santiago exhibit lowest price sensitivity given hard electrification deadlines, while rural microgrid developers in Peru's Amazon basin face acute capital constraints.
Supply Chain Analysis
INMETRO and ANEEL certification gates filter substandard imports before Brazilian assembly plants can qualify for BNDES financing. Cathode active material supply concentrates in China, South Korea, and Japan, exposing regional assemblers to shipping cost spikes and currency fluctuation risk. Raw material dependencies center on lithium hydroxide, nickel sulfate, and cobalt feedstocks. Single-source vulnerability persists for high-purity electrolyte formulations optimized for tropical humidity. Distribution runs through EPC contractors bundling cell supply into turnkey transmission-connected solar farm contracts across Chile and Colombia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American battery cell procurement is consolidating around binding multi-year offtake structures, squeezing spot-market-dependent assemblers unable to secure ANEEL qualification or BNDES financing access.
For Market Incumbents: Anticipate sodium-ion chemistry displacement in Colombian and Chilean utility solar-buffer installations by qualifying Prussian white cathode systems before lithium-dependent competitors lock in volume. Secure captive lithium carbonate offtake from Cauchari-Olaroz or Atacama brine operations to insulate margin compression from East Asian refining hub volatility. Reinforce certification investment in INMETRO third-party validation capabilities to filter substandard imports and defend positioning in consumer-facing segments. For New Entrants and Emerging Players: EPC contractors serving transmission-connected solar farms in Colombia's Andean region represent the most penetrable channel partner type for first-mover sodium-ion system qualification. Target Bogotá-based utilities consolidating procurement around multi-year volume commitments with price adjustment clauses. Pursue Argentine renewable project developers facing Secretaría de Energía local content thresholds as captive demand anchors for regionally assembled battery systems. For Investors and Strategic Acquirers: Distressed-cycle entries favor Brazilian cathode precursor producers in Minas Gerais and São Paulo states with BNDES Inova Energia financing access and existing INMETRO certification infrastructure. Long-term viability hinges on backward integration into lithium refining or forward integration into utility-scale EPC bundling. Monitor ANEEL grid-connected storage mandate enforcement intensity as the inflection signal distinguishing guaranteed procurement pipelines from speculative capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Capacity Buildout | Brazilian domestic assembly qualifies for BNDES Inova Energia financing redirection. |
| Sodium-Ion Chemistry Qualification | Colombian utilities adopt Prussian white systems to eliminate hard currency import exposure. |
| Binding Offtake Agreement Structuring | Chilean transmission-connected solar farms consolidate procurement around multi-year volume commitments. |
| INMETRO Certification Investment | Third-party validated degradation curves filter substandard imports from consumer-facing channels. |
| Lithium Brine Backward Integration | Atacama and Cauchari-Olaroz upstream control insulates margin compression from carbonate volatility. |
Research Methodology
Document review covered ANEEL regulatory filings, INMETRO certification databases, BNDES financing disclosure records, and MERCOSUR hazardous transport harmonization drafts, complemented by interviews with utility procurement officers at Chilean and Colombian grid operators, EPC contractors bundling cell supply into turnkey solar farm contracts, cathode precursor plant managers in Brazil's southeastern corridor, and electrochemistry R&D directors at sodium-ion qualification programs. Secondary validation drew from customs trade data, national mining agency extraction reports, and renewable project development databases. Bottom-up cell shipment tracking and top-down utility capex triangulation anchored volume estimates.
Installed capacity and revenue projections across the analysis window reflect segmentation by chemistry type, application end-use, and national regulatory framework. The modeling framework incorporated electric bus fleet electrification deadlines in Santiago and São Paulo, ANEEL grid-connected storage compliance phase-in curves, and Secretaría de Energía local content threshold enforcement patterns. CAGRs were derived from equipment qualification timeline compression and binding offtake structure displacement of spot purchasing.
Caveats apply where lithium carbonate price volatility, MERCOSUR hazardous transport regulatory misalignment, or electrolyte formulation talent scarcity could materially shift the outlook. A model refresh is warranted upon material change in ANEEL mandate enforcement intensity or BNDES Inova Energia financing availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Tubular Batteries Market
Batteries
Drone Lithium Battery Charger Market
Batteries
Asia-Pacific NMC Battery Pack Market
Batteries
Europe Battery Cell Market
Batteries
Battery Anode Materials Market
Batteries
Europe SLI Battery Market
Batteries
Aluminum Wire Battery Market
Batteries
Primary Lithium Battery Market
Batteries
FORTELION Battery Module Market
Batteries
Italy Rechargeable Battery Market
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
Battery Simulator Market
Batteries
Thin Film and Printed Battery Market
Batteries
Rechargeable Coin Cell Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
Water-Based Zinc-Ion Battery Market