
 Radial Lithium-Ion Capacitor Market | 2026-2036
Radial Lithium-Ion Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Radial Lithium-Ion Capacitor Market Insights
Modular cell packaging is realigning how industrial buyers configure energy storage subsystems. TAIYO YUDEN leverages its ceramic capacitor heritage to dominate radial form-factor miniaturization for consumer electronics. VINATech Co., Ltd. anchors high-volume production of lithium-ion capacitors for Korean automotive Tier 1s. Murata Manufacturing Co., Ltd. differentiates through in-house electrode material development, sustaining margin pools in premium industrial grades.
A radial lithium-ion capacitor combines activated carbon cathodes with pre-doped graphite anodes in a cylindrical can with radial lead terminals, achieving energy densities of 10-15 Wh/kg while retaining supercapacitor-level cycle stability above 100,000 charge events. Its primary purpose bridges the gap between aluminum electrolytic capacitors and lithium-ion batteries in pulse-power and backup applications. High-temperature capacitors lead product-type margins due to aerospace and downhole drilling certifications, while supercapacitors represent the fastest-growing category as grid-scale renewable integration expands. Automotive applications concentrate procurement volume, though industrial equipment commands superior pricing through customized thermal management specifications.
FCC equipment authorization rules govern radial capacitor integration into US telecommunications infrastructure, while Japan's METI enacts battery recycling mandates that reshape end-of-life liability for manufacturers. The EU Battery Regulation's carbon footprint disclosure requirements are forcing electrode supply chain documentation upgrades. Stakeholders must monitor how China's GB standards for electrochemical capacitors evolve against IEC baseline specifications to determine certification strategy for dual-market access.
Market Dynamics
Automotive electrification programs in Germany and Japan are accelerating procurement of hybrid energy storage systems, forcing capacitor manufacturers to recalibrate capacity allocation toward certified automotive grades.
Growth Catalysts
- EU Battery Regulation carbon footprint disclosure:The EU Battery Regulation's carbon footprint disclosure requirements are forcing electrode supply chain documentation upgrades, creating competitive advantage for suppliers with traceable material sourcing.
- Hybrid energy storage systems:Automotive electrification programs in Germany and Japan are accelerating procurement of radial lithium-ion capacitors for regenerative braking and start-stop applications.
- East Asian manufacturing clusters:Demand concentrates in East Asian manufacturing clusters, with South Korea and Japan expanding radial cell capacity for industrial OEMs seeking localized supply security.
Market Restraints
- Graphite anode material cost volatility:Pre-doped graphite anode costs fluctuate with battery-grade graphite demand, compressing margins for mid-tier radial cell producers.
- South Korean supply concentration:High-volume production concentrates among Korean automotive Tier 1 suppliers, creating single-source vulnerability for European industrial buyers.
- Aluminum electrolytic capacitor substitution:Mature aluminum electrolytic technology retains cost advantage in low-temperature, non-cycling backup applications below 85°C.
Strategic Opportunities
- Grid-scale renewable integration:Supercapacitors represent expansion opportunity as grid operators seek fast-response frequency regulation assets for solar and wind intermittency management.
- Downhole drilling thermal management:High-temperature capacitors lead product-type margins due to aerospace and downhole drilling certifications, with customized thermal specifications commanding superior pricing.
- Japan METI battery recycling mandates:METI's battery recycling mandates reshape end-of-life liability frameworks, creating first-mover advantage for manufacturers with closed-loop material recovery systems.
Industry Challenges
- Dual certification complexity:China's GB standards for electrochemical capacitors evolve against IEC baseline specifications, forcing manufacturers to maintain parallel testing protocols for dual-market access.
- Electrode material IP disputes:In-house electrode material development faces patent thickets around activated carbon cathode formulations and pre-doping processes.
- Legacy thermal management integration:Industrial equipment buyers require customized thermal management specifications, extending qualification timelines and engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radial Lithium-Ion Capacitor Market |
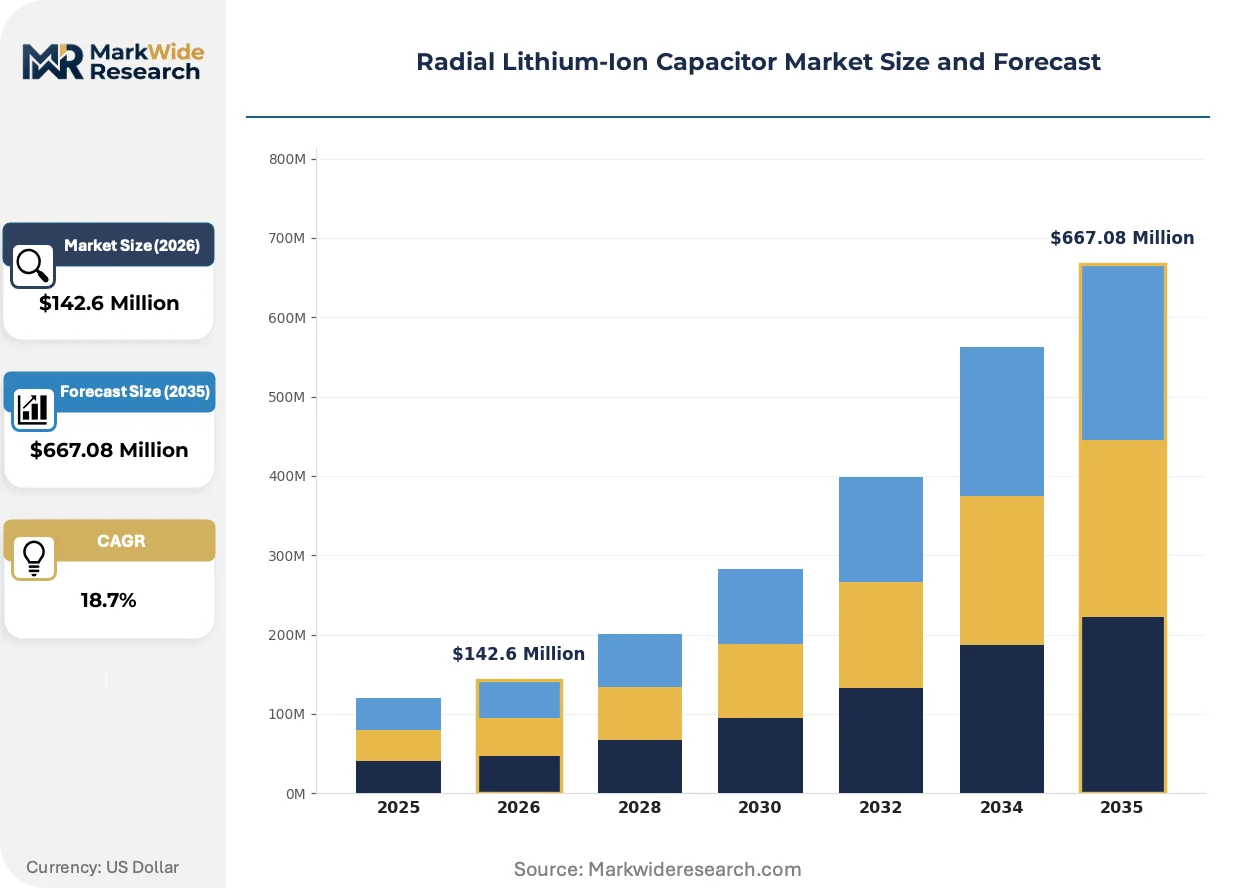
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $667.08 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Capacitors, High-Temperature Capacitors, Polymer Capacitors, Supercapacitors Application: Consumer Electronics, Renewable Energy, Automotive, Industrial Equipment End User: Manufacturers, OEMs, Distributors, Research Institutions Technology: Electrochemical Technology, Hybrid Technology, Printed Technology, Others |
| Companies Covered | LICAP Technologies, Inc., TAIYO YUDEN, JSR Micro NV, VINATech Co., Ltd., Electro Standards Laboratories, Socomec Group, Murata Manufacturing Co., Ltd., YUNASKO Ltd, Spel Technologies Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radial Lithium-Ion Capacitor Market Trends and Innovations
Modular cell packaging is realigning how industrial buyers configure energy storage subsystems, with radial form-factor miniaturization enabling denser subsystem integration.
Pre-doped graphite anode technology is converging with activated carbon cathode manufacturing processes to bridge the energy density gap between aluminum electrolytic capacitors and lithium-ion batteries. Aerospace and downhole drilling OEMs are adopting these hybrid cells at accelerated qualification paces for pulse-power applications above 100,000 cycle requirements. The convergence is compressing the addressable market for pure supercapacitors in medium-duration backup applications.
China's MIIT battery safety standards are tightening cell certification requirements for electrochemical capacitors used in telecommunications infrastructure. The industrial consequence forces manufacturers to upgrade separator materials and electrolyte formulations to pass nail penetration and overcharge abuse tests. Premium industrial grades face the steepest compliance cost increases, with Japanese suppliers accelerating IEC 62368-1 pre-certification to maintain cross-border market access.
Industrial equipment buyers are consolidating vendor qualification lists around suppliers with in-house electrode material development capabilities. Long-term supply agreements are displacing spot purchasing for automotive and grid-scale applications, with buyers demanding documented carbon footprint data from anode and cathode precursor suppliers. This consolidation pattern is most visible in German automotive electrification programs, where Tier 1s are reducing qualified supplier pools from twelve to four radial cell sources.
Radial Lithium-Ion Capacitor Market Segmentation
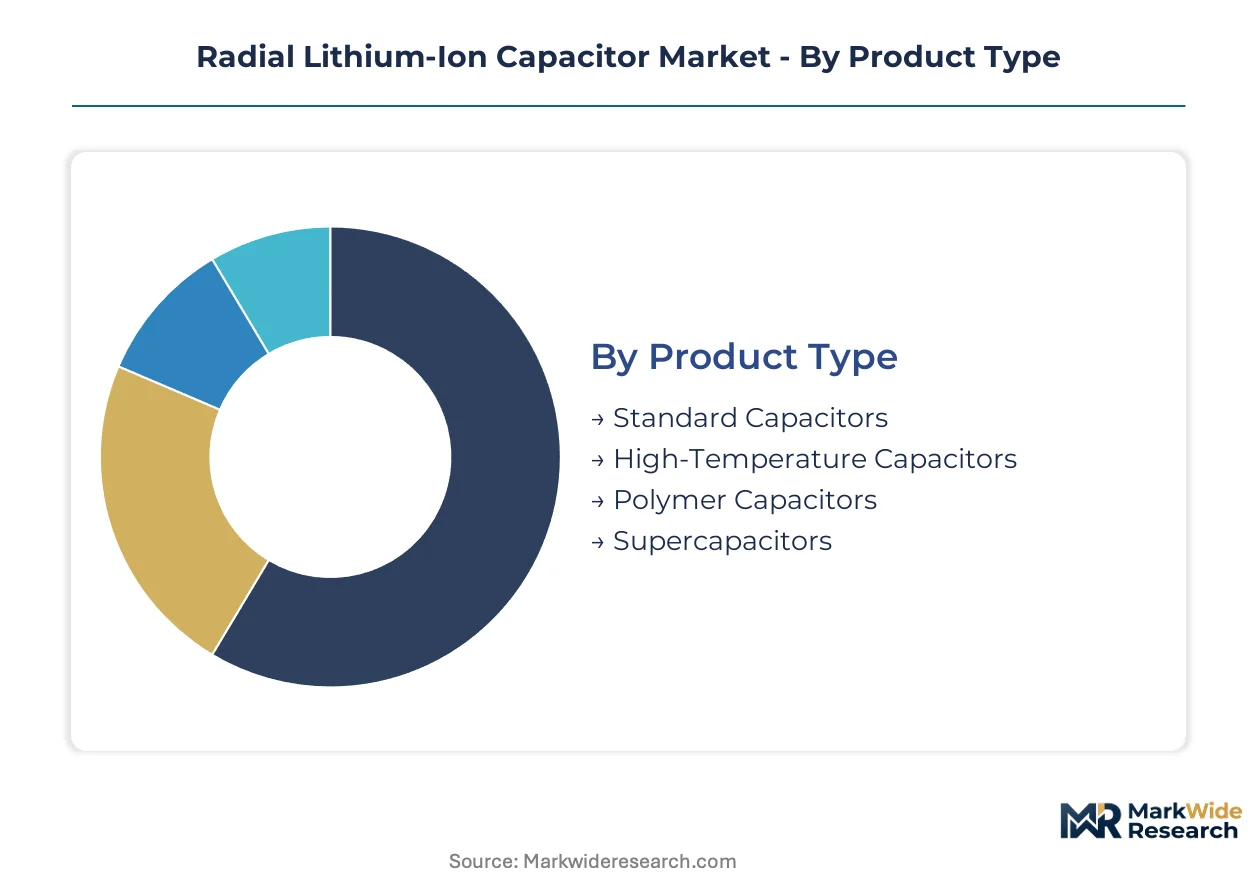
Radial lithium-ion capacitor procurement splits sharply between commodity-grade volume plays and certified premium tiers. Buyers configure subsystems differently across automotive pulse-power, industrial backup, and grid-frequency regulation use cases.
Product Type:
Volume concentrates in standard cylindrical cans, while premium margins pool in thermally certified grades.
- High-Temperature Capacitors:Aerospace and downhole drilling OEMs specify these for sustained operation above 125°C. Customized thermal management specifications command superior pricing through extended qualification timelines.
- Supercapacitors:Grid operators in Germany and Japan procure these for fast-response frequency regulation assets. Solar and wind intermittency management is expanding addressable demand fastest among all product tiers.
- Standard Capacitors:Consumer electronics and automotive start-stop systems drive procurement volume in East Asian manufacturing clusters.
- Polymer Capacitors:Solid-state electrolyte formulations target medical and telecommunications infrastructure requiring extended calendar life.
Today's leader: High-Temperature Capacitors. Tomorrow's challenger: Supercapacitors.
Application:
Automotive electrification absorbs the highest unit volumes, though industrial equipment retains pricing power through specification customization.
- Automotive:Regenerative braking and start-stop systems in German and Japanese electrification programs dominate procurement tonnage. Tier 1 suppliers are consolidating qualified vendor pools from twelve to four radial cell sources.
- Industrial Equipment:Pulse-power machinery and uninterruptible power systems specify radial form factors for cycling durability above 100,000 charge events.
- Consumer Electronics:Miniaturization demands from TAIYO YUDEN's ceramic capacitor heritage drive radial lead terminal density in portable devices.
- Renewable Energy:Grid-scale solar and wind integration creates procurement for frequency regulation and ramp-rate control assets.
Automotive commands volume. Industrial commands margin. Renewable energy is climbing the fastest.
End User:
Direct procurement from manufacturers is displacing distributor channels in automotive and grid-scale applications.
- OEMs:Korean automotive Tier 1s and German industrial machinery builders source directly for supply security and carbon footprint documentation.
- Manufacturers:In-house electrode material development capabilities determine vendor list inclusion for premium industrial grades.
- Distributors:Spot purchasing persists in consumer electronics and small-scale industrial replacement markets.
- Research Institutions:Downhole drilling and aerospace qualification programs fund pre-commercial cell testing for extreme environment specifications.
OEMs set terms today. Manufacturers with captive electrode technology will reshape supplier relationships tomorrow.
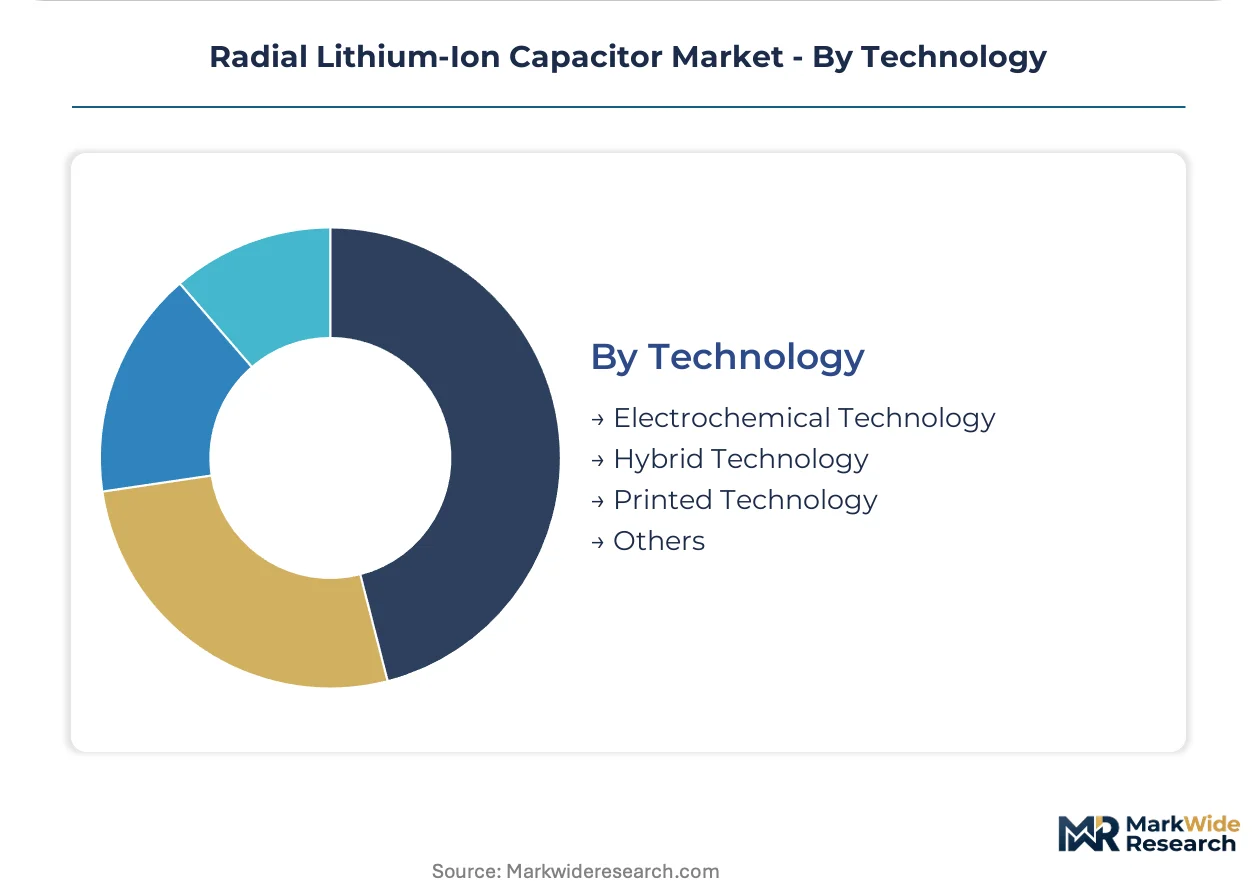
Technology:
Hybrid architectures are compressing the addressable market for pure electrochemical implementations.
- Hybrid Technology:Pre-doped graphite anodes converging with activated carbon cathodes bridge the energy density gap between aluminum electrolytics and lithium-ion batteries. This is expanding most quickly across aerospace and pulse-power applications.
- Electrochemical Technology:Established activated carbon cathode formulations serve cost-sensitive backup applications below 85°C.
- Printed Technology:Additive manufacturing approaches target flexible electronics and conformal wearable device integration.
- Others:Solid-state and quasi-solid electrolyte research programs address MIIT nail penetration and overcharge abuse test requirements.
Hybrid Technology leads commercial traction. Printed Technology represents the steepest expansion trajectory for next-form-factor applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radial lithium-ion capacitor manufacturing originated in Japan's electronics corridor during the 1990s, with Japanese and South Korean firms subsequently scaling production for automotive and industrial applications. German industrial electrification programs and Chinese telecommunications infrastructure build-outs now drive procurement volume expansion.
Germany
Automotive Tier 1 suppliers in Stuttgart and Munich procure hybrid energy storage systems for regenerative braking and start-stop applications. The EU Battery Regulation's carbon footprint disclosure requirements force electrode supply chain documentation upgrades. Industrial machinery builders in Baden-Württemberg consolidate qualified vendor pools from twelve to four radial cell sources.
Japan
Electronics manufacturers in the Kanto region leverage ceramic capacitor heritage to dominate radial form-factor miniaturization for consumer devices. METI battery recycling mandates reshape end-of-life liability frameworks for manufacturers with closed-loop material recovery systems. Nagoya-based automotive suppliers accelerate qualification paces for pulse-power applications above 100,000 cycle requirements.
South Korea
Automotive electrification programs in Seoul and Busan drive high-volume production for Korean automotive Tier 1 suppliers. MFDS-aligned safety standards influence electrochemical capacitor certification protocols for telecommunications infrastructure. Gyeonggi-do manufacturing clusters expand radial cell capacity for industrial OEMs seeking localized supply security.
China
Telecommunications infrastructure deployment in Shenzhen and Beijing absorbs standard cylindrical cans for base station backup systems. MIIT battery safety standards tighten cell certification requirements, forcing separator material and electrolyte formulation upgrades. Yangtze River Delta electronics manufacturers face steepest compliance cost increases for nail penetration and overcharge abuse tests.
United States
Grid operators in California and Texas procure supercapacitors for fast-response frequency regulation assets managing solar and wind intermittency. FCC equipment authorization rules govern radial capacitor integration into telecommunications infrastructure. Aerospace OEMs in the Pacific Northwest specify high-temperature grades for sustained operation above 125°C.
Radial Lithium-Ion Capacitor Market Competitive Landscape
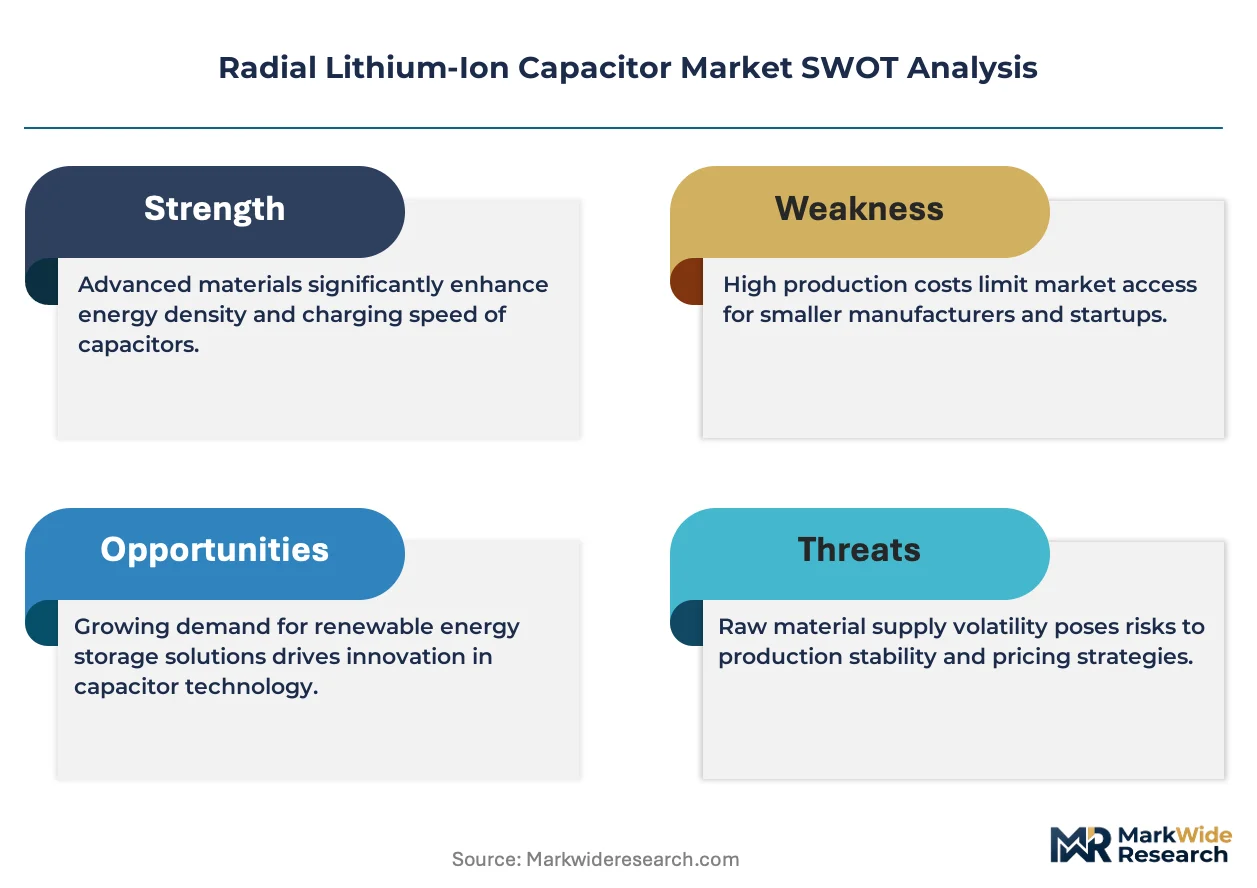
Premium-margin players sit above commodity-margin players across certification-grade and thermal-performance dimensions. The vendor base stratifies into three tiers: integrated electrode developers capturing margin in premium industrial grades, high-volume fabricators serving automotive procurement programs, and specialized miniaturization houses addressing consumer electronics density requirements. Dominant competitive moves include in-house electrode material development and capacity expansion toward certified automotive grades.
Among Japanese electronics conglomerates, TAIYO YUDEN and Murata Manufacturing Co., Ltd. occupy positions shaped by ceramic component heritage and in-house material development capabilities. South Korea's VINATech Co., Ltd. exemplifies the high-volume fabrication archetype serving automotive Tier 1 procurement. Together these three anchors represent distinct competitive vectors: miniaturization expertise, captive electrode technology, and scale-driven automotive supply.
| Leading Market Players |
|---|
| LICAP Technologies, Inc. |
| TAIYO YUDEN |
| JSR Micro NV |
| VINATech Co., Ltd. |
| Electro Standards Laboratories |
| Socomec Group |
| Murata Manufacturing Co., Ltd. |
| YUNASKO Ltd |
| Spel Technologies Pvt Ltd |
| Others |
Pricing and Supply Chain Analysis
German automotive Tier 1 consolidation of qualified vendor pools from twelve to four radial cell sources is forcing mid-tier manufacturers to absorb certification costs or exit premium tiers, compressing margins while elevating pricing power for electrode-integrated incumbents.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified high-temperature grades from automotive start-stop volumes and consumer electronics spot purchases. Price differentiation hinges on thermal certification tier and carbon footprint documentation depth. Cost compression in standard cylindrical cans is intensifying because battery-grade graphite demand fluctuations feed into pre-doped anode input costs. Automotive procurement teams exhibit lowest price sensitivity due to supply security priorities, while consumer electronics buyers drive hardest bargain on unit economics.
Supply Chain Analysis
Pre-doped graphite anode supply rests on Japanese specialty carbon producers and Chinese battery-grade refiners, with activated carbon cathode precursors drawing from South Korean and Southeast Asian chemical processors. Separator materials and electrolyte formulations hinge on Japanese and German specialty chemical houses. Single-source vulnerability concentrates in Korean automotive Tier 1 supplier networks, exposing European industrial buyers to allocation risk during capacity crunches. Distribution runs through direct long-term agreements for automotive and grid-scale procurement, with distributor channels persisting only in consumer electronics replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as automotive electrification programs in Germany and Japan generate durable procurement pipelines for hybrid energy storage systems across multiple product generations.
For Market Incumbents: Lock in electrode material supply through backward integration into pre-doped graphite processing or captive activated carbon precursor partnerships. Accelerate IEC 62368-1 and MIIT safety pre-certification to defend against emerging Chinese suppliers with cost-advantaged standard grades. Carbon footprint documentation capabilities will determine vendor list retention as EU Battery Regulation enforcement tightens. For New Entrants and Emerging Players: EU Battery Regulation carbon footprint disclosure requirements in Germany open a window for electrode traceability specialists to penetrate automotive Tier 2 supplier tiers. Target grid-scale renewable integration in the United States and Japan where fast-response frequency regulation asset procurement outpaces established supplier capacity. Lead with documented supply chain transparency as primary go-to-market wedge against incumbent opacity. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing in-house electrode development and existing aerospace thermal certifications. Five-to-ten-year viability favors manufacturers with closed-loop material recovery systems aligned to Japan METI recycling mandates. Watch Korean automotive Tier 1 supplier consolidation announcements as inflection signal for sector margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electrode Material Backward Integration | Captive pre-doped graphite supply secures margin pools in premium industrial grades against input volatility. |
| Dual Certification Investment | Parallel IEC and GB standards compliance unlocks cross-border access to German automotive and Chinese telecom infrastructure. |
| High-Temperature Grade Capacity Expansion | Aerospace and downhole drilling thermal certifications command superior pricing through extended qualification barriers. |
| Closed-Loop Recovery System Deployment | Japan METI recycling mandates reshape liability frameworks for manufacturers with end-of-life material capture. |
| Grid-Scale Supercapacitor Partnership | Fast-response frequency regulation assets in California and Texas renewable integration outpace current supply capacity. |
Research Methodology
Direct dialogue with automotive Tier 1 procurement directors, industrial equipment maintenance engineers, electrode material R&D leads, and grid operator planning officers grounded qualitative findings in operational reality. Secondary validation drew from MIIT battery safety standard filings, EU Battery Regulation implementation guidance, FERC interconnection queue data, and customs trade records for graphite and activated carbon precursor flows. Bottom-up cell production estimates triangulated against top-down automotive electrification program procurement forecasts.
Segmented outputs across product type, application, end user, and technology dimensions calibrated penetration rates over the projection horizon. CAGRs derived from regression against automotive production schedules, renewable capacity addition trajectories, and industrial capital expenditure cycles. Electrode material cost curves and certification timeline assumptions shaped margin trajectory modeling for premium versus commodity tiers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under graphite supply disruption or accelerated aluminum electrolytic substitution in low-temperature backup applications. A small set of named triggers warrants ongoing watch: Korean Tier 1 supplier consolidation announcements, China GB standards divergence from IEC baselines, and German industrial machinery vendor pool reduction completion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
Lithium-Air Battery Market
Lithium-ion Battery
Automotive Cylindrical Lithium Batteries Market
Lithium-ion Battery
Germany SLI Battery Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
South America Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
EV SOLID State Battery Market
Lithium-ion Battery
Lithium-Ion Battery Packs Market
Lithium-ion Battery
Lithium Battery Wet Separator Market