
 3D-Printed Battery Market | 2026-2036
3D-Printed Battery Market Size, Share, and Industry Trends Forecast 2026-2036
3D-Printed Battery Market Analysis
OEM-direct procurement channels for 3D-printed battery cells is narrowing as tier-one suppliers consolidate qualification programs. Sakuu Corporation leverages its multi-material deposition platform to anchor high-throughput solid-state production. Blackstone Resources AG competes through in-house electrode printing and Swiss-based process control. Stratasys Ltd. extends its polymer expertise into battery housing integration, occupying a niche between cell makers and pack assemblers.
3D-printed batteries are electrochemical energy devices fabricated through additive manufacturing, enabling precise control over electrode architecture with layer resolutions below 100 microns and customizable form factors unattainable through conventional winding or stacking. Their primary purpose is to deliver optimized energy density and thermal management for space-constrained or shape-critical applications. Solid-state chemistry leads product type development due to inherent safety advantages and compatibility with dry printing processes, while electric vehicles represents the fastest-growing application as OEMs pursue pack-level volumetric efficiency. Fused deposition modeling dominates technology adoption for prototyping cycles, though selective laser sintering captures margin pools in production-grade ceramic electrolyte processing.
FDA, EPA, and NHTSA frameworks in the United States govern cell safety testing, chemical exposure limits, and automotive crashworthiness respectively, with NHTSA's emerging battery integrity standards directly shaping design validation timelines for EV applications. The EU Battery Regulation and REACH compliance requirements are forcing material disclosure and recycled content quotas that favor closed-loop 3D printing feedstock systems. Stakeholders must monitor how solid-state qualification protocols evolve across jurisdictions, as regulatory convergence or divergence will determine whether multi-country certification costs erode the format-flexibility advantage that additive manufacturing promises.
Market Dynamics
OEM-direct procurement channels for 3D-printed battery cells are narrowing as tier-one suppliers consolidate qualification programs. Solid-state chemistry compatibility with dry printing processes is compressing traditional cell manufacturing timelines.
Growth Catalysts
- EU Battery Regulation:Tightening traceability and recyclability rules favor closed-loop 3D printing feedstock systems over conventional electrode production.
- Electric vehicle pack architecture:Space-constrained automotive designs demand customizable form factors unattainable through winding or stacking processes.
- Selective laser sintering:Production-grade ceramic electrolyte processing captures margin pools previously reserved for conventional solid-state manufacturing.
Market Restraints
- High-purity ceramic powder supply:Concentration of specialty material suppliers in East Asia creates input cost volatility and single-source risk.
- Multi-material deposition complexity:Technical limitations in controlling interfacial adhesion between active materials and current collectors at sub-100-micron resolutions constrain yield rates.
- NHTSA battery integrity standards:Emerging automotive crashworthiness requirements extend design validation timelines and compress development budgets.
Strategic Opportunities
- California EV startup ecosystem:Underpenetrated demand from venture-backed automotive entrants seeking rapid prototyping partnerships without legacy tooling investments.
- China GB standards convergence:Regulatory tailwind from harmonized national standards enabling single-qualification access to the world's largest electric vehicle market.
- Fused deposition modeling and thermal management:Technology convergence between polymer housing integration and cell architecture is creating new pack-level design service revenue streams.
Industry Challenges
- Electrochemistry-additive manufacturing hybrid expertise:Talent scarcity at the intersection of battery science and process engineering extends hiring cycles and inflates compensation benchmarks.
- Solid-state qualification protocols:Certification timeline fragmentation across FDA, EPA, and NHTSA jurisdictions forces redundant testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D-Printed Battery Market |
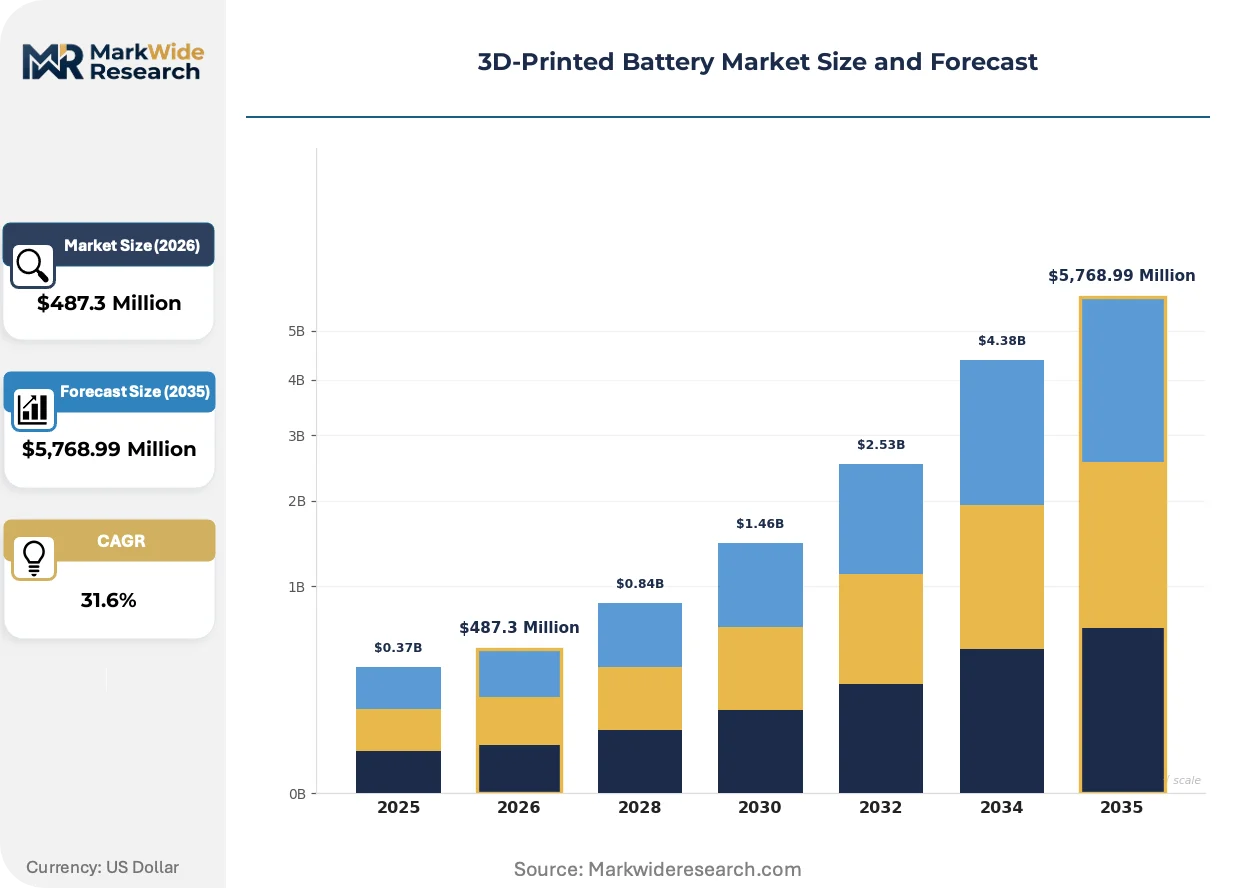
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $5,768.99 Million |
| CAGR (2026 – 2036) | 31.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Solid-state, NiMH, Lead-acid End User: Consumer Electronics, Automotive OEMs, Industrial Equipment, Renewable Energy Technology: Fused Deposition Modeling, Selective Laser Sintering, Stereolithography, Binder Jetting Application: Energy Storage, Electric Vehicles, Wearable Devices, Power Tools |
| Companies Covered | Sakuu Corporation, Blackstone Resources AG, Neware Technology Limited, Enicon Energy and Infrastructure Co., Stratasys Ltd., KeraCel, American Elements, Photocentric Ltd., Materialise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D-Printed Battery Market Emerging Trajectories
Dry electrode printing is virtualizing conventional slurry-based manufacturing, compressing capital requirements and enabling rapid form-factor iteration for automotive and medical device applications.
Multi-material deposition platforms are virtualizing the boundary between cell fabrication and pack assembly, allowing simultaneous printing of active layers, solid electrolytes, and structural housings in single build cycles. Automotive OEMs in Germany and South Korea are piloting these systems for next-generation electric vehicle architectures. The technology is virtualizing traditional tiered supplier relationships by bringing cell production in-house or co-locating it with pack assembly.
REACH compliance requirements are forcing material disclosure and recycled content quotas that reshape feedstock sourcing strategies. Battery manufacturers must now document full chemical lifecycles from raw material extraction through end-of-life recovery. European cell producers are responding by integrating closed-loop powder recovery systems directly into printing operations.
Buyer concentration among tier-one automotive suppliers is compressing vendor qualification timelines and demanding outcome-based performance guarantees rather than component specifications. Cell producers must now warranty pack-level energy density and cycle life. This shift is most visible in Germany's automotive corridor, where OEMs are consolidating supplier panels and requiring direct printing partnerships rather than arm's-length component purchases.
3D-Printed Battery Market Segmentation
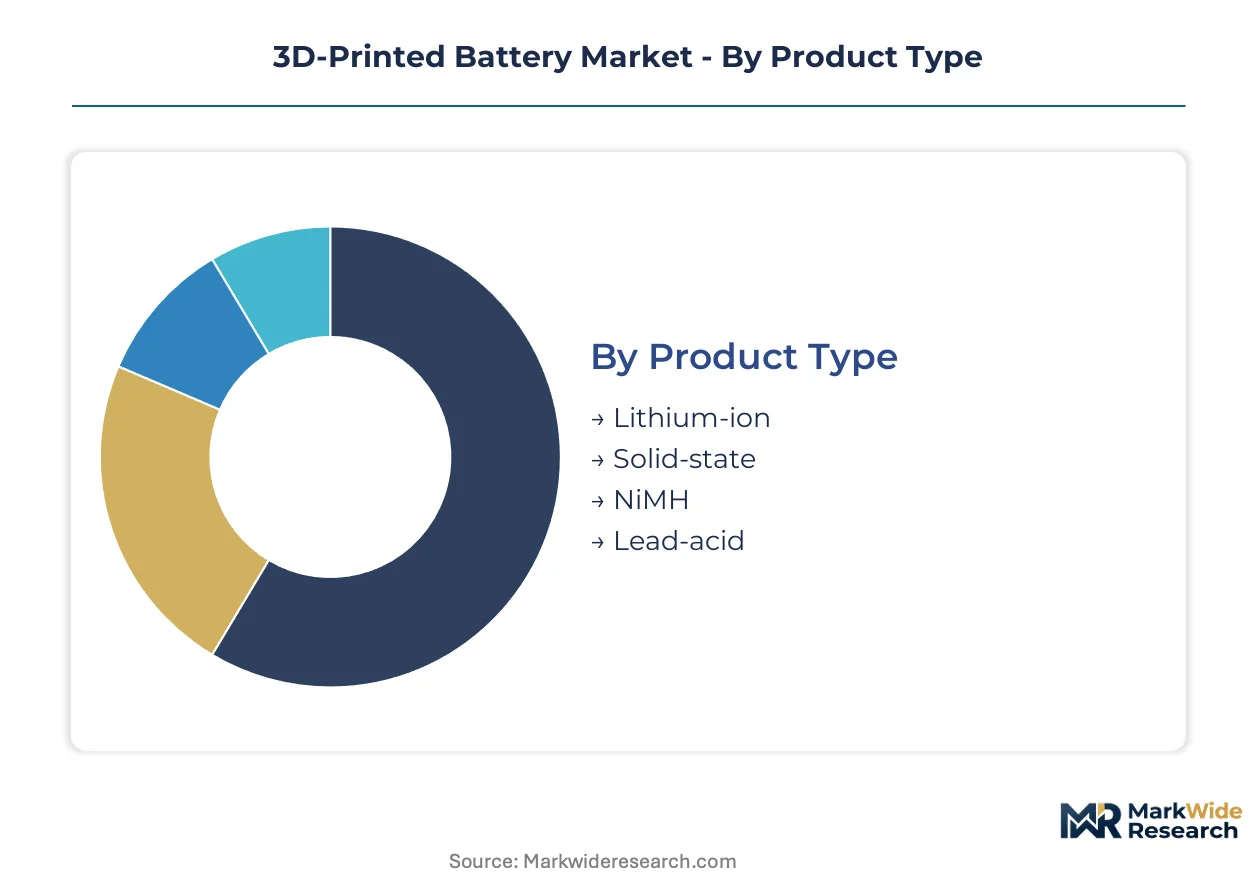
Segmentation in 3D-printed batteries reveals how additive manufacturing intersects with divergent performance requirements across chemistry types, end-use specifications, and build technologies. Each dimension carries distinct qualification barriers and margin structures that reshape supplier positioning.
Product Type:
Cost tier stratification separates commodity-compatible formats from premium solid-state architectures demanding specialized feedstock and controlled atmosphere processing.
- Solid-state:Ceramic or glass-ceramic electrolytes fabricated through dry deposition eliminate flammable liquid components. Automotive OEMs in Germany's corridor specify these for next-generation pack architectures requiring inherent thermal stability.
- Lithium-ion:Conventional intercalation chemistry adapted for additive manufacturing through slurry reformulation and precision layer stacking. Consumer electronics manufacturers in South Korea's electronics belt drive demand for customized form factors in smartphones and tablets.
- NiMH:Nickel-metal hydride systems suit industrial applications tolerating lower energy density in exchange for proven recyclability and supply chain familiarity.
- Lead-acid:Mature chemistry repurposed for prototyping and backup power applications where additive manufacturing enables rapid geometric iteration without tooling investment.
Solid-state commands the established base. The steepest expansion runs through lithium-ion as consumer electronics manufacturers accelerate custom-form-factor programs.
End User:
Application context determines whether customers prioritize rapid prototyping cycles, production-scale qualification, or pack-level integration services.
- Automotive OEMs:Vehicle manufacturers specify pack-level volumetric efficiency and crashworthiness validation under NHTSA emerging standards. California's EV startup ecosystem sources these for rapid architecture iteration without legacy tooling.
- Consumer Electronics:Device manufacturers demand sub-millimeter layer precision for space-constrained wearables and handheld products. South Korean electronics producers concentrate procurement for smartphone and tablet battery programs.
- Industrial Equipment:Forklift, robotics, and stationary power applications favor proven cycle life over energy density optimization.
- Renewable Energy:Grid-scale and residential storage systems utilize 3D printing for geometric customization in containerized or building-integrated installations.
Automotive OEMs anchor current revenue concentration. Consumer electronics represents the fastest-growing trajectory as device form factors fragment.
Technology:
Build method selection constrains achievable resolution, material compatibility, and throughput economics for each application tier.
- Selective Laser Sintering:Laser fusion of ceramic and metallic powders enables production-grade solid electrolyte processing with sub-100-micron feature control. REACH compliance requirements in Europe favor this for closed-loop powder recovery integration.
- Fused Deposition Modeling:Thermoplastic extrusion dominates prototyping cycles for polymer-integrated cell housings and thermal management structures. California EV startups leverage this for rapid design validation without capital-intensive tooling.
- Stereolithography:Photopolymerization suits micro-scale energy devices and medical applications requiring biocompatible resin formulations.
- Binder Jetting:Liquid binding of powder beds offers throughput advantages for larger-format electrodes where surface finish tolerances relax.
Selective laser sintering captures premium margin pools. Fused deposition modeling is expanding most quickly as prototyping demand accelerates across automotive and electronics verticals.
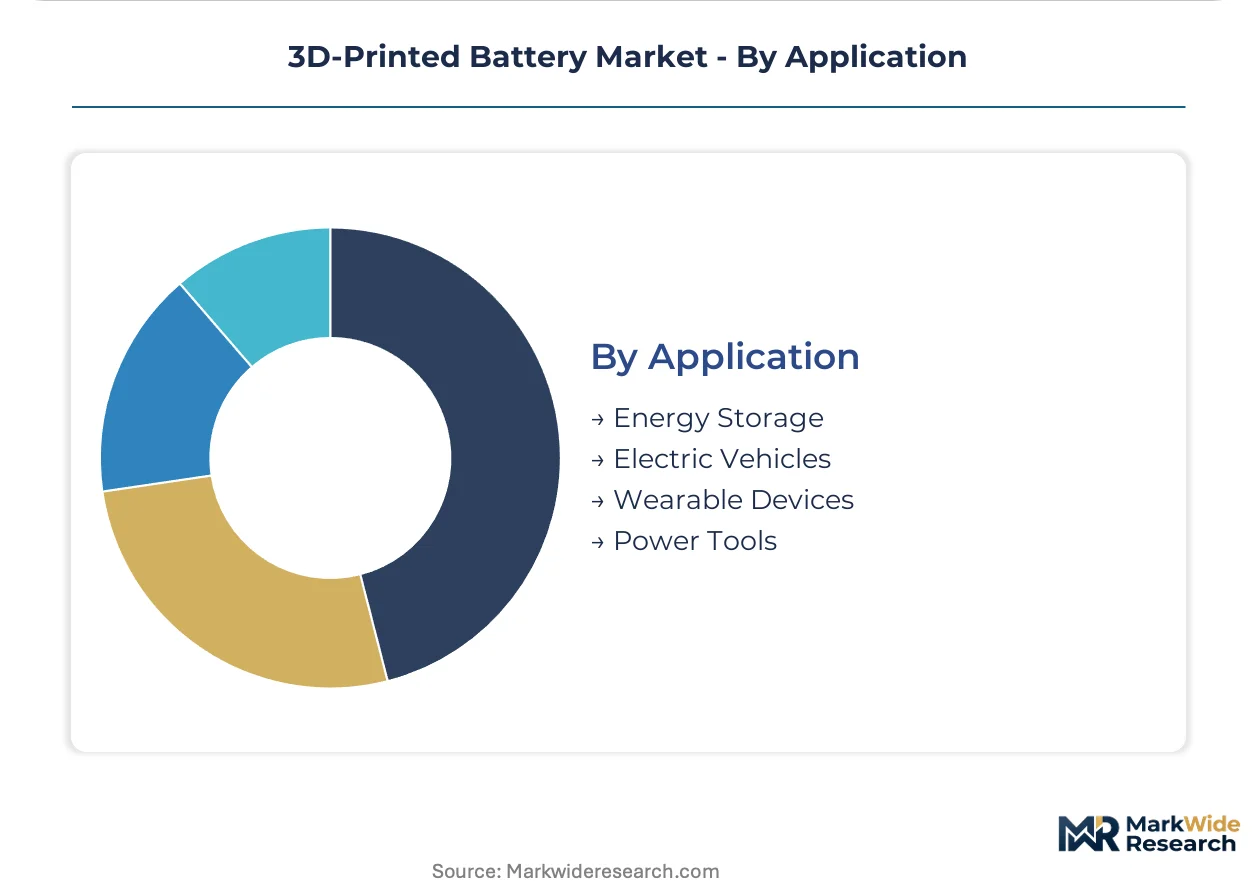
Application:
Volume scale and performance certification requirements fragment across stationary, mobility, and portable power contexts.
- Electric Vehicles:Automotive traction batteries demand pack-level energy density warranties and thermal runaway containment validated under emerging NHTSA integrity standards. Germany's automotive corridor concentrates qualification programs for next-generation architectures.
- Wearable Devices:Medical and consumer wearables require biocompatible materials and flexible form factors unattainable through conventional winding. FDA frameworks govern cell safety testing for implantable and skin-contact applications.
- Energy Storage:Grid and residential systems prioritize cycle life economics over volumetric density.
- Power Tools:Cordless equipment manufacturers specify high-discharge capability in ruggedized geometries.
Electric vehicles command the established base. Wearable devices are climbing the fastest as medical device manufacturers adopt patient-specific battery geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Battery Regulation traceability mandates and China's GB standards harmonization are redrawing qualification pathways across major production zones. National subsidy programs for solid-state R&D in Germany, South Korea, and the United States are accelerating pilot line deployments. Industrial clusters in Bavaria, Gyeonggi-do, and California's Bay Area concentrate tier-one automotive partnerships.
Germany
BMW and Volkswagen procurement teams specify custom-form-factor cells for next-generation pack architectures. REACH compliance requirements force material disclosure quotas that favor closed-loop powder recovery systems. Bavaria's automotive corridor anchors qualification programs for multi-material deposition platforms serving premium EV segments.
United States
NHTSA's emerging battery integrity standards reshape design validation timelines for automotive applications. California's EV startup ecosystem sources rapid prototyping partnerships without legacy tooling investments. The Bay Area concentrates venture-backed entrants pursuing solid-state pilot production.
China
GB standards convergence creates regulatory tailwinds for single-qualification market access. MIIT directives on dual carbon goals accelerate dry electrode printing adoption across state-backed battery consortia. The Yangtze River Delta hosts concentrated ceramic powder supplier networks for solid-state feedstock production.
South Korea
Samsung SDI and LG Energy Solution procurement patterns drive demand for sub-millimeter layer precision in consumer electronics. MFDS frameworks govern biocompatible material qualifications for wearable medical devices. Gyeonggi-do's electronics belt concentrates smartphone and tablet battery customization programs.
3D-Printed Battery Market Vendor Landscape
On the supply side, the industry is consolidating around multi-material deposition specialists and in-house electrode fabricators. Tier-one automotive suppliers narrow vendor qualification programs, compressing procurement channels for cell producers. Two strategic archetypes dominate: platform-technology licensors controlling dry printing IP, and integrated manufacturers capturing margin pools through captive powder processing. Dominant competitive moves include strategic partnerships with automotive OEMs for co-located pilot production and technology licensing agreements for selective laser sintering ceramic electrolyte systems.
Among the named fabricators, Sakuu Corporation anchors the multi-material deposition archetype through its high-throughput solid-state platform. Blackstone Resources AG occupies a position within the integrated manufacturing tier, leveraging Swiss-based process control for electrode printing operations. Stratasys Ltd. represents the polymer-to-battery convergence vector, extending additive manufacturing expertise into thermal management and housing integration services.
| Leading Market Players |
|---|
| Sakuu Corporation |
| Blackstone Resources AG |
| Neware Technology Limited |
| Enicon Energy and Infrastructure Co. |
| Stratasys Ltd. |
| KeraCel |
| American Elements |
| Photocentric Ltd. |
| Materialise |
| Others |
Supply Flow & Price Mechanics
East Asia's concentration of high-purity ceramic powder suppliers anchors input cost volatility that cascades into tier-one automotive qualification timelines. Contract manufacturers serving solid-state cell producers capture margin pools through captive powder processing agreements, while OEM-direct procurement channels compress pricing power at the pack-integration tier.
Pricing Analysis
Volume-discount tiering structures separate prototype-batch pricing from multi-year automotive offtake contracts. Three-tier pricing stratifies across solid-state premium cells, lithium-ion standard formats, and lead-acid economy prototypes. Price differentiation hinges on NHTSA certification grade and REACH-compliant material disclosure depth. Pricing pressure stems from tier-one supplier consolidation demanding outcome-based performance guarantees rather than component specifications. Consumer electronics manufacturers in South Korea exhibit highest price sensitivity due to fragmented device form factors, while German automotive OEMs prioritize thermal stability over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates among Swiss-based process control specialists and Bavarian pilot-line operators serving multi-material deposition platforms. Geographic supply clusters in China, South Korea, and Germany feed ceramic electrolyte production. Raw material dependencies center on lithium carbonate, nickel sulfate, and specialty ceramic binders. Single-source vulnerability runs through East Asian high-purity powder networks concentrated in the Yangtze River Delta. Distribution runs through tier-one automotive supplier panels narrowing vendor qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pack-level thermal management services and closed-loop powder recovery subscriptions expand faster than hardware sales as European REACH compliance mandates deepen recurring revenue attachment. After-sales performance warranties now outpace cell unit economics in margin contribution.
For Market Incumbents: Harden qualification timelines against emerging dry-electrode printing entrants by consolidating captive ceramic powder processing in Bavaria. Deepen backward integration into solid-state electrolyte feedstock production to defend margin pools from tier-one supplier consolidation. Invest in NHTSA pre-certification testing infrastructure before emerging battery integrity standards extend validation cycles.
For New Entrants and Emerging Players: California's venture-backed EV startup ecosystem represents the most penetrable entry point for rapid prototyping partnerships without legacy tooling investments. Medical wearable applications requiring FDA-compliant biocompatible geometries offer white-space expansion as patient-specific battery demand climbs. Lead with fused deposition modeling thermal management integration services rather than competing head-to-head on cell chemistry.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed additive manufacturing platform licensors holding dry-printing IP portfolios. Five-to-ten-year viability hinges on regulatory convergence across NHTSA, FDA, and EPA jurisdictions reducing multi-certification cost burdens. Monitor solid-state qualification protocol harmonization between EU Battery Regulation and China's GB standards as the inflection signal for platform-technology valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Process Licensing | Technology transfer agreements with German automotive OEMs compress slurry-based manufacturing capital requirements. |
| Multi-Material Deposition Scale-Up | Pilot line deployments in California's Bay Area anchor co-located cell and pack production partnerships. |
| Ceramic Powder Recovery Integration | Closed-loop systems meeting REACH quotas secure European automotive qualification programs. |
| Solid-State Certification Pre-Investment | Early NHTSA testing infrastructure locks in design validation timelines before standards finalize. |
| Consumer Electronics Customization Programs | Sub-millimeter precision partnerships with South Korean device manufacturers capture wearable battery white space. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with solid-state R&D directors, tier-one automotive procurement leads, additive manufacturing platform engineers, and REACH compliance officers; and secondary validation through SEC filings, EU Battery Regulation implementation documents, NHTSA docket records, and ceramic powder trade flow databases. Bottom-up cell production capacity estimates triangulated against top-down automotive pack demand projections across the analysis window.
Forecast inputs incorporated chemistry-type adoption curves, build-technology throughput economics, and regional regulatory convergence timelines. Segmentation dimensions modeled include product type chemistry tiers, end-user application contexts, build technology resolution classes, and automotive certification grade clusters. CAGRs derived from installed base growth rates and replacement cycle acceleration across electric vehicle and consumer electronics verticals. Solid-state pilot line deployment schedules and dry electrode printing yield improvements informed scenario-weighted projections.
Stress conditions across ceramic powder supply disruptions, NHTSA certification timeline extensions, and REACH recycled content quota acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization and technology yield maturation. Quarterly review of tier-one automotive supplier panel consolidation and solid-state qualification protocol convergence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Nickel-Metal Hydride (Ni-MH) Battery Market
Batteries
United Kingdom Rechargeable Battery Market
Batteries
South Europe Battery Market
Batteries
Wireless Power Bank Market
Batteries
North Africa Battery Market
Batteries
Grid-Scale Battery Market
Batteries
America SLI Battery Market
Batteries
48 Volt Battery System Market
Batteries
Europe Industrial Battery Market
Batteries
Submarine Batteries Market
Batteries
VRLA Batteries Market
Batteries
All-In-One Solar Storage Battery Market
Batteries
Asia Power Tool Batteries Market
Batteries
France Rechargeable Battery Market
Batteries
Smart Battery Charger Market
Batteries
Industrial Backup Battery Market