
 United Kingdom SLI Battery Market | 2026-2036
United Kingdom SLI Battery Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom SLI Battery Market Insights
Qualified battery technician shortages across the Midlands and Northern England is reorganizing service capacity at national distributors. Clarios leverages its pan-European supply footprint to sustain aftermarket coverage throughout Britain. GS Yuasa Corporation anchors its position through specialized marine and industrial applications where cold-cranking performance requirements exceed standard thresholds. Johnson Controls International plc competes on manufacturing scale, operating high-throughput plants that feed both OEM assembly lines and independent retail channels.
A United Kingdom SLI Battery is a starting, lighting, and ignition power unit engineered to deliver short-duration high-current bursts, typically constructed with lead-acid chemistry using pasted flat-plate or tubular positive electrodes and sulfuric acid electrolyte, designed to crank internal combustion engines and stabilize vehicle electrical loads during transient demand spikes. Lead-Acid chemistry still dominates installed base volumes across British fleets, though Lithium-Ion configurations are capturing share in premium start-stop applications where weight reduction and cycle durability justify higher unit costs. The Maintenance-Free technology segment leads replacement demand among commercial automotive end users seeking reduced service interval labor, while Start-Stop systems represent the fastest-growing technology category as OEMs comply with CO2 reduction commitments.
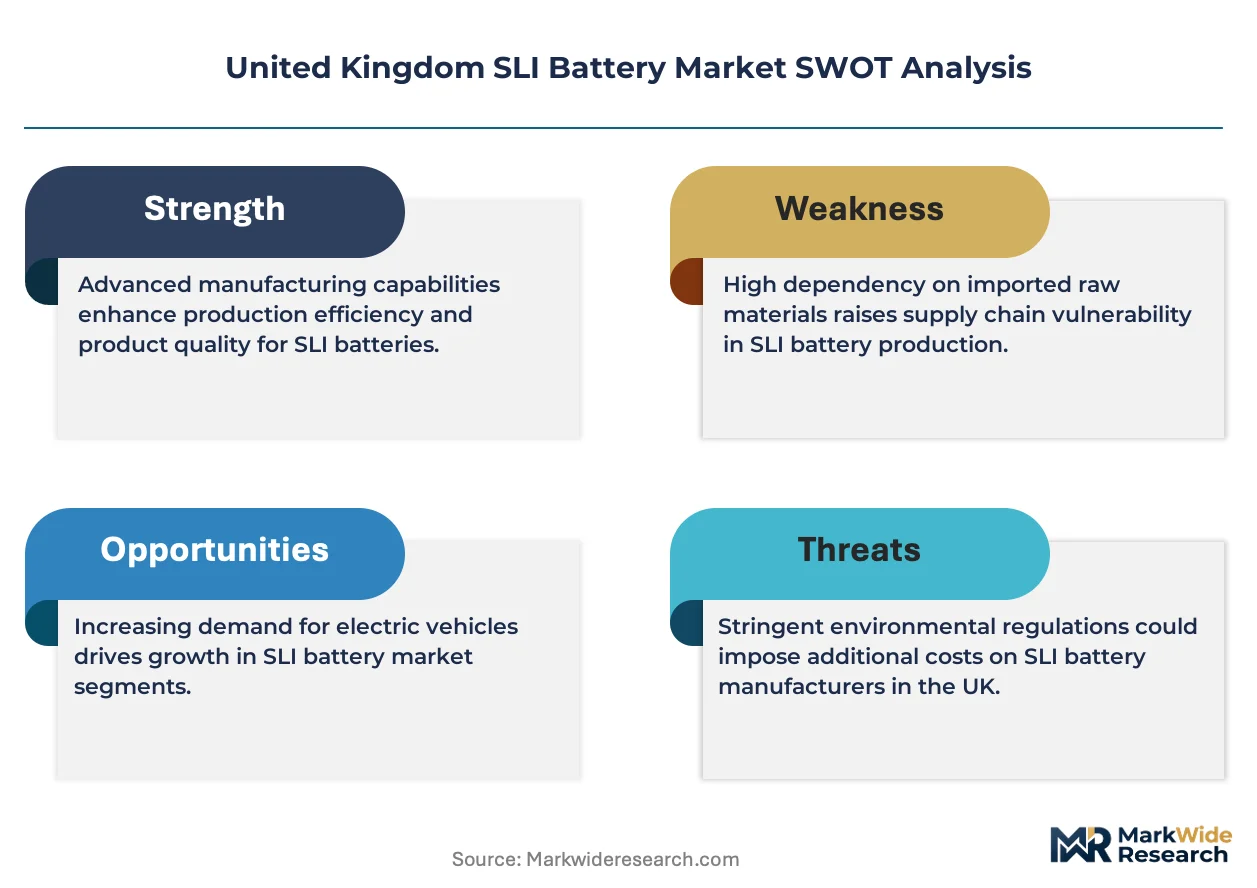
The UK's Waste Batteries and Accumulators Regulations enforce producer responsibility frameworks that shape collection infrastructure and recycling economics for lead-acid SLI units sold domestically. BSI standards for battery safety and performance, alongside Environment Agency enforcement of hazardous waste protocols, define product compliance thresholds for manufacturers and importers. Stakeholders must monitor how post-Brexit divergence from EU Battery Regulation alignment affects certification reciprocity and cross-border supply chain access for SLI products entering Northern Ireland.
Market Dynamics
The United Kingdom SLI Battery Market is restructuring around the Waste Batteries and Accumulators Regulations, which mandate producer responsibility for collection and recycling infrastructure while tightening material recovery thresholds for lead-acid units sold domestically.
Growth Catalysts
- Fleet electrification schedules:Commercial vehicle operators across England and Scotland are accelerating SLI replacement cycles to maintain cold-cranking reliability in aging diesel and hybrid powertrains.
- BSI performance standards:Enhanced safety and durability certifications under British Standards Institution protocols are elevating replacement demand for maintenance-free sealed units in automotive workshops.
- Marine service clusters:Scotland's offshore vessel maintenance hubs generate concentrated demand for heavy-duty SLI configurations engineered for extreme temperature cycling.
Market Restraints
- Lead price volatility:Raw material input costs for lead-acid chemistry fluctuate with global smelter capacity, compressing margin stability for domestic assemblers.
- Substitution by lithium-ion:Premium start-stop applications in passenger vehicles increasingly specify lithium-ion alternatives where weight reduction justifies unit cost premiums.
- Post-Brexit certification friction:Divergence between UKCA marking requirements and retained EU Battery Regulation alignment creates compliance duplication for Northern Ireland supply routes.
Strategic Opportunities
- Closed-loop recycling infrastructure:The Waste Batteries Regulations create mandated collection volume pools that reward domestic recyclers with secured feedstock access.
- Start-stop system penetration:OEM CO2 reduction commitments are expanding the addressable market for enhanced flooded battery and absorbed glass mat technologies.
- Workshop channel consolidation:Independent garage networks across the Midlands seek direct distributor relationships that bypass traditional motor factor intermediaries.
Industry Challenges
- Qualified technician scarcity:Battery system diagnostics and safe handling certification gaps across Northern England constrain service throughput at national distributors.
- Legacy fleet interoperability:Maintenance-free sealed designs require workshop equipment upgrades that smaller independent operators defer due to capital intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom SLI Battery Market |
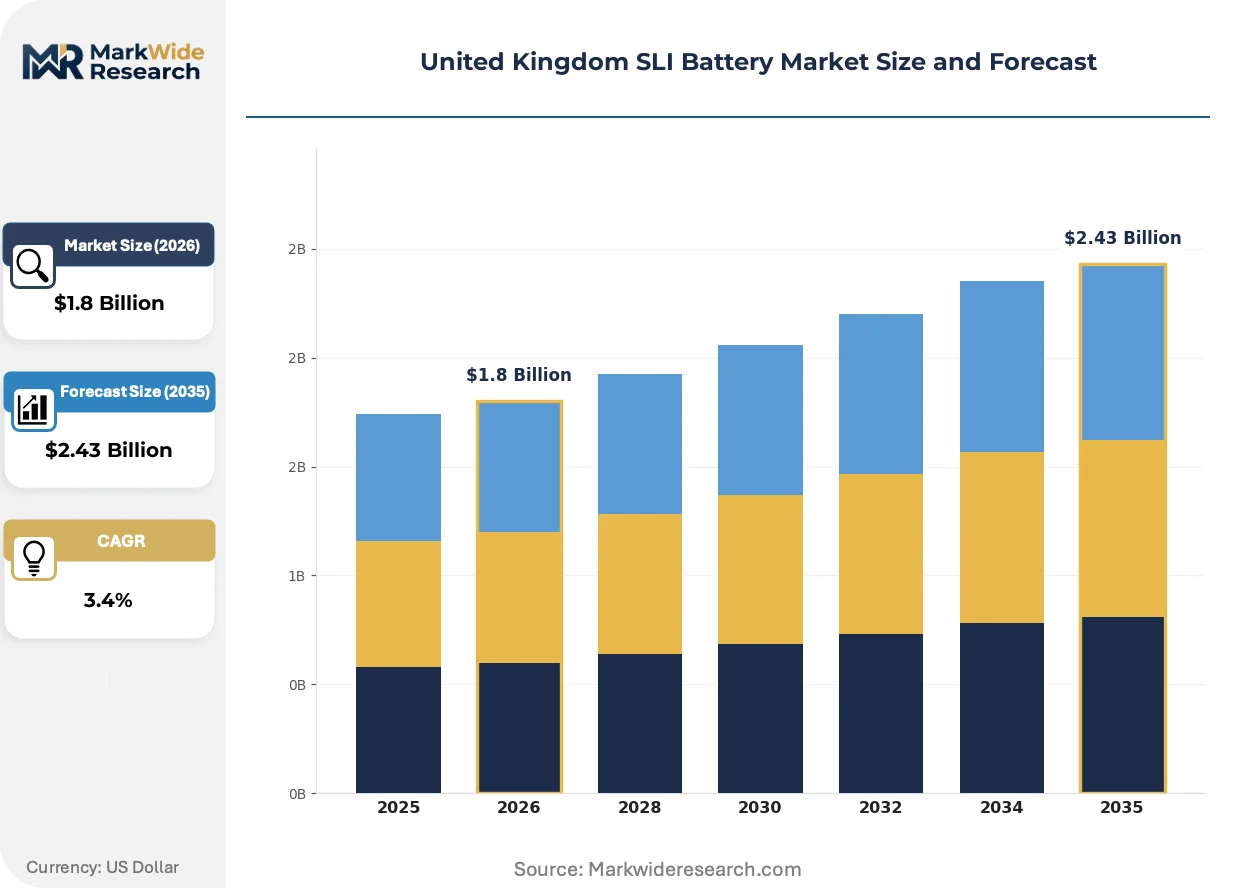
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
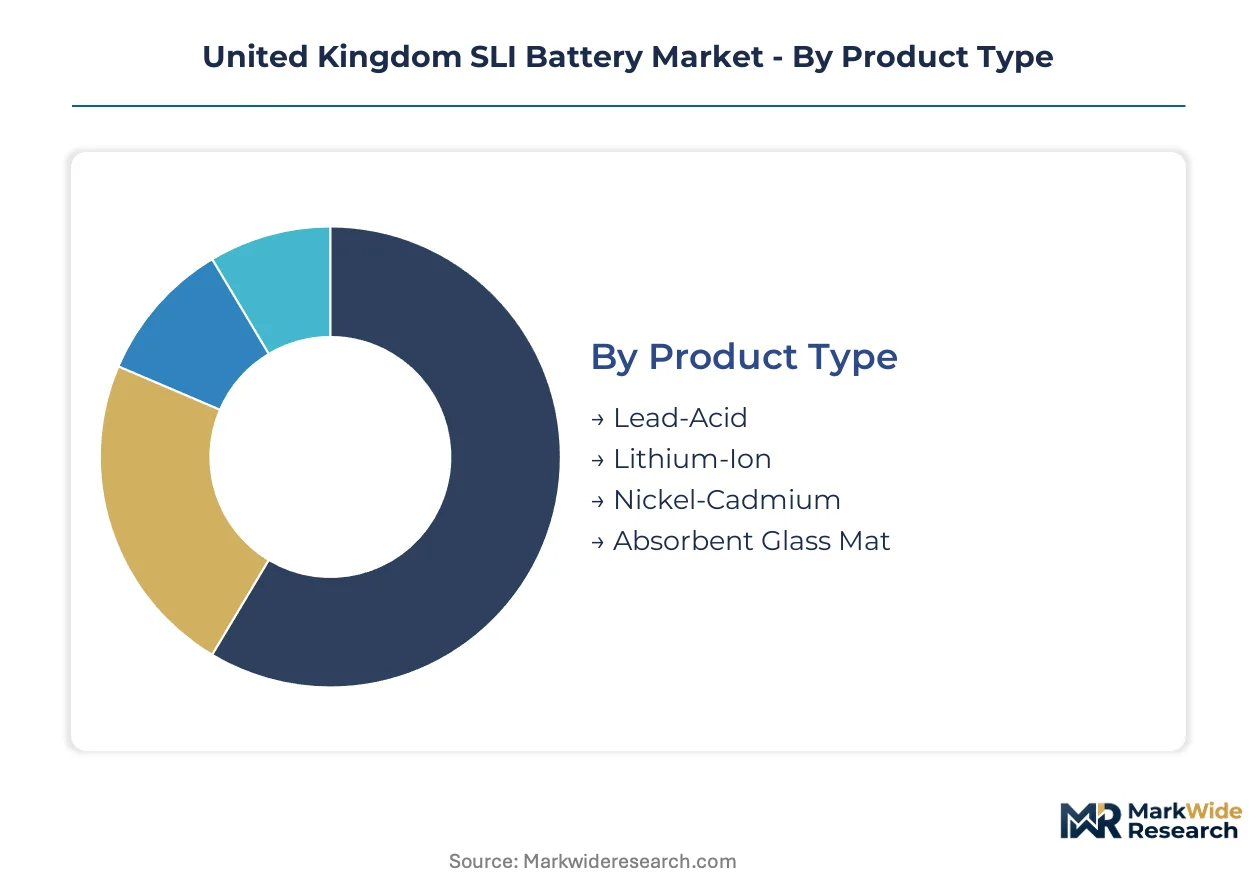
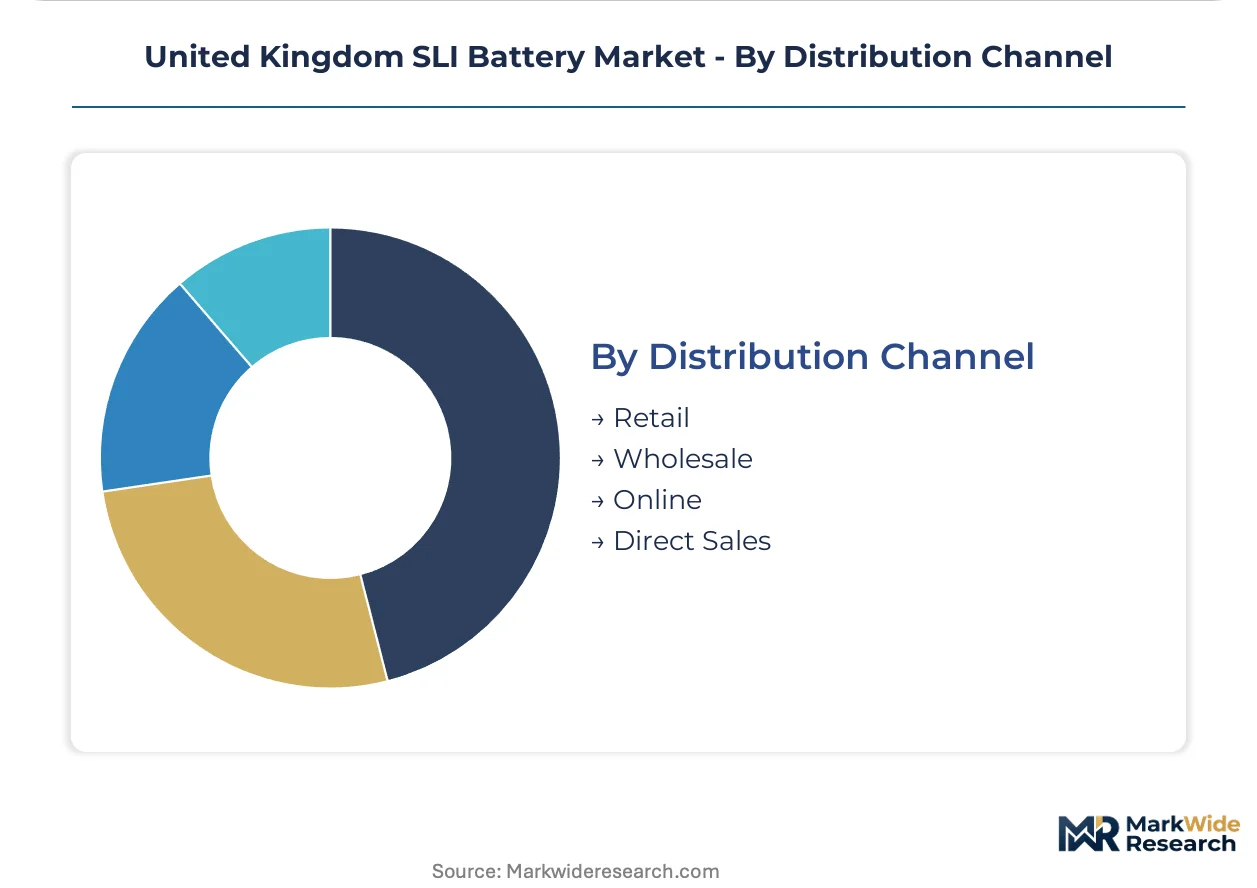
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Absorbent Glass Mat End User: Automotive, Marine, Industrial, Off-Grid Technology: Start-Stop, Conventional, Hybrid, Maintenance-Free Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Exide Technologies, Clarios, GS Yuasa Corporation, Johnson Controls International plc, EnerSys, VARTA AG, Hoppecke Batteries GmbH & Co. KG, FIAMM Energy Technology S.p.A., Banner GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom SLI Battery Market Trends and Innovations
Active material formulations and recycling process chemistry are the primary vectors of technical change reshaping competitive positioning and cost structures across British SLI supply chains.
Absorbed glass mat separator technology is decomposing the traditional flooded lead-acid architecture in start-stop applications. Premium passenger vehicle OEMs specify AGM configurations for enhanced cycle durability. This shift is decomposing aftermarket pricing power for conventional flat-plate producers.
The UK's Waste Batteries and Accumulators Regulations are tightening producer responsibility thresholds for collection and material recovery. Domestic distributors must fund or operate reverse logistics infrastructure. Northern Ireland-based suppliers face particular complexity navigating dual UK-EU compliance obligations.
Workshop procurement patterns favor consolidated distributor relationships over fragmented motor factor purchasing. Large independent garage groups negotiate direct supply agreements with pan-European battery manufacturers. This concentration is most visible across England's automotive manufacturing corridors where fleet density supports volume commitments.
United Kingdom SLI Battery Market Segmentation
SLI battery procurement patterns across Britain diverge sharply by application stress and duty cycle requirements. Fleet operators, marine service providers, and industrial maintenance teams each specify distinct performance thresholds that reshape supplier priorities and channel economics.
Product Type:
Lithium-Ion chemistry exerts the strongest substitution pressure on legacy lead-acid architectures, particularly where weight reduction and cycle durability command premium positioning.
- Lead-Acid:Pasted flat-plate or tubular positive electrodes with sulfuric acid electrolyte deliver short-duration high-current bursts for internal combustion engine cranking. England's automotive manufacturing corridors and Scotland's marine service clusters maintain concentrated demand for flooded and sealed variants where cold-cranking reliability outweighs unit weight concerns.
- Lithium-Ion:Lithium iron phosphate or lithium manganese oxide cathodes paired with graphite anodes enable deep discharge tolerance and rapid recharge capability. Premium start-stop applications in passenger vehicles specify these configurations where CO2 reduction commitments justify higher acquisition costs against fuel efficiency gains.
- Nickel-Cadmium:Pocket-plate or sintered electrode designs tolerate extreme temperature cycling with minimal electrolyte maintenance. Offshore vessel operators in Aberdeen and Peterhead specify these for emergency backup systems where operational continuity overrides capital expenditure.
- Absorbent Glass Mat:Electrolyte suspended in microfiber glass separators enables vibration resistance and position-independent installation. Enhanced flooded battery architectures serve start-stop systems across Birmingham fleet workshops seeking reduced service interval labor.
Lead-Acid anchors the volume base while Lithium-Ion gains share at the steepest rate.
End User:
Customer procurement scale determines margin structure, with national fleet contracts commanding pricing leverage unavailable to fragmented independent operators.
- Automotive:Passenger car, light commercial vehicle, and heavy-duty truck applications dominate replacement schedules across Britain. Midlands-based fleet operators accelerate SLI replacement cycles to maintain warranty compliance and minimize roadside failure incidents during winter demand peaks.
- Marine:Deep-cycle and dual-purpose configurations serve offshore supply vessels, fishing fleets, and leisure craft. Scotland's marine service clusters generate concentrated demand for heavy-duty units engineered to withstand salt corrosion and engine compartment temperature extremes.
- Industrial:Forklift, material handling, and stationary backup power applications specify thick-plate deep-cycle designs. Manufacturing corridors around Manchester and Leeds procure maintenance-free sealed units to reduce facility labor overhead.
- Off-Grid:Remote telecommunications, renewable energy storage, and rural standby power installations require extended reserve capacity. Welsh and Scottish Highlands deployments favor robust construction tolerant of infrequent charging cycles and ambient temperature variation.
Automotive commands the revenue concentration while Marine delivers the highest margin per unit.
Technology:
Technology selection tracks OEM platform architecture, with start-stop system penetration directly tied to vehicle CO2 compliance certification requirements.
- Start-Stop:Enhanced flooded battery or absorbed glass mat configurations tolerate frequent micro-cycling without capacity degradation. OEM assembly lines serving the British market specify these technologies to meet corporate average fuel economy thresholds.
- Conventional:Standard flooded lead-acid designs with removable cell caps dominate legacy fleet replacement demand. Independent garages across Northern England stock these for older vehicle parc where simplified installation procedures reduce technician time allocation.
- Hybrid:Dual-battery architectures combining SLI functions with limited traction support serve mild-hybrid powertrains. Premium passenger vehicle segments in London and Southeast England specify these where 48V electrical systems enable torque assist.
- Maintenance-Free:Sealed calcium-calcium or calcium-silver grid alloys minimize water consumption and terminal corrosion. Commercial automotive end users prioritize these to eliminate scheduled electrolyte inspection intervals across distributed vehicle populations.
Conventional technology retains the largest installed base while Start-Stop expands most quickly.
Distribution Channel:
Channel selection reflects purchase urgency and technical support requirements, with emergency replacement favoring physical proximity over cost minimization.
- Retail:Motor factor branches and automotive parts superstores serve walk-in trade and small independent workshops. High street presence across England's urban centers enables same-day availability for breakdown recovery operations.
- Wholesale:Regional distributors supply volume commitments to multi-site garage groups and fleet maintenance depots. Consolidated procurement through Midlands distribution hubs reduces per-unit logistics overhead for national operators.
- Online:E-commerce platforms and manufacturer-direct portals capture price-sensitive planned replacement demand. Workshop channel consolidation drives larger independent garage groups toward direct distributor relationships that bypass traditional intermediaries.
- Direct Sales:Manufacturer field representatives negotiate frame contracts with national fleet operators and OEM service networks. Clarios and GS Yuasa leverage pan-European supply footprints to sustain aftermarket coverage through dedicated account management.
Wholesale channels handle the transaction volume while Direct Sales capture the strategic account relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SLI battery consumption patterns across Britain diverge sharply between England's dense automotive corridors and Scotland's dispersed marine service networks, with each geography imposing distinct cold-cranking reliability specifications and replacement cycle rhythms.
England
Midlands-based fleet operators and Birmingham workshop clusters drive concentrated demand for maintenance-free sealed units, with commercial vehicle replacement cycles accelerating to maintain warranty compliance. The Environment Agency enforces hazardous waste protocols that shape collection infrastructure economics. Manchester and Leeds manufacturing corridors procure thick-plate designs for material handling fleets seeking reduced facility labor overhead.
Scotland
Aberdeen and Peterhead offshore vessel maintenance hubs generate specialized demand for heavy-duty configurations engineered to withstand salt corrosion and engine compartment temperature extremes. The Scottish Environment Protection Agency administers producer responsibility frameworks aligned with UK Waste Batteries Regulations. Marine service clusters favor nickel-cadmium pocket-plate designs for emergency backup systems where operational continuity overrides capital expenditure.
Wales
Remote telecommunications and rural standby power installations across Welsh highlands require extended reserve capacity tolerant of infrequent charging cycles. Natural Resources Wales oversees hazardous waste permitting for battery recycling facilities serving dispersed populations. Cardiff and Newport distribution nodes handle consolidated procurement for off-grid renewable energy storage deployments.
Northern Ireland
Dual UK-EU compliance obligations create certification friction for suppliers serving Belfast automotive workshops and Londonderry industrial maintenance depots. The Northern Ireland Environment Agency implements retained EU Battery Regulation alignment alongside UKCA marking requirements. Cross-border supply routes from Republic of Ireland distributors complicate reverse logistics for lead-acid collection pools.
North England
Independent garage networks across Yorkshire and Lancashire seek direct distributor relationships that bypass traditional motor factor intermediaries, though qualified battery technician shortages constrain service throughput. HSE regional enforcement shapes workshop safety certification for battery handling procedures. Newcastle and Sheffield fleet maintenance depots negotiate frame contracts with pan-European manufacturers for volume commitment pricing.
United Kingdom SLI Battery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the United Kingdom SLI Battery Market consolidating around manufacturers commanding pan-European supply footprints and dedicated recycling infrastructure. Tier-one participants compete on manufacturing scale and aftermarket coverage density, while mid-tier specialists anchor positions in marine, industrial, and premium start-stop applications. Strategic moves concentrate on backward integration into lead smelting capacity and direct distributor relationships with consolidated independent garage groups.
Within the integrated multinational tier, Clarios and Johnson Controls International plc exemplify scale-driven positioning through high-throughput manufacturing and dedicated account management with national fleet operators. GS Yuasa Corporation occupies a specialist position, with its corporate structure suggesting concentrated expertise in advanced battery chemistries for demanding duty cycles. Hoppecke Batteries GmbH & Co. KG represents the German-engineered industrial specialist archetype, while VARTA AG anchors premium-tier positioning in start-stop and enhanced flooded battery technologies.
| Leading Market Players |
|---|
| Exide Technologies |
| Clarios |
| GS Yuasa Corporation |
| Johnson Controls International plc |
| EnerSys |
| VARTA AG |
| Hoppecke Batteries GmbH & Co. KG |
| FIAMM Energy Technology S.p.A. |
| Banner GmbH |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion substitution into premium start-stop applications simultaneously redraws supply geography toward East Asian cell manufacturers and compresses pricing power for legacy lead-acid producers serving Britain's automotive corridors. This chemistry shift feeds back into distributor procurement patterns, with volume commitments increasingly tied to dual-source requirements that buffer against raw material volatility in lead smelting.
Pricing Analysis
Contract structures in the United Kingdom SLI Battery Market stratify across long-term offtake agreements with national fleet operators, spot purchasing by independent garages, and project-based frames for marine and industrial installations. Price differentiation rests on certification grade under BSI standards and volume scale commitments, with maintenance-free sealed units commanding premiums over conventional flooded designs. Cost compression in economy-tier flooded batteries is intensifying because qualified technician shortages constrain service throughput at distributors. Fleet operators exhibit the lowest price sensitivity due to warranty compliance requirements, while independent garages in Northern England prioritize unit cost minimization over after-sales bundling.
Supply Chain Analysis
Inventory strategy preferences across British distributors favor just-in-time replenishment for high-turnover automotive SKUs, while strategic stockpiling dominates for heavy-duty marine configurations with extended procurement lead times. Geographic supply concentration draws from Germany, Poland, and China for finished battery units, with lead feedstock sourcing anchored in domestic smelting capacity supplemented by Spanish and Italian secondary recovery. Raw material dependencies rest on lead bullion, polypropylene casing resin, and sulfuric acid electrolyte. Single-source vulnerability concentrates in AGM separator supply from specialized European manufacturers. Distribution runs through consolidated regional hubs in the Midlands that feed both motor factor branches and direct-to-workshop channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom SLI Battery Market fragments across chemistry transitions, creating specialist niches where technical certification and reverse logistics capabilities outcompete scale. Start-stop system proliferation and Waste Batteries Regulations compliance obligations are spawning demand-side micro-segments underserved by integrated multinationals.
For Market Incumbents: Compound aftermarket coverage density through backward integration into lead smelting capacity and captive recycling infrastructure. Secure frame contracts with consolidated independent garage groups across England's automotive corridors to preempt distributor disintermediation. Lithium-ion substitution in passenger vehicles threatens volume erosion in premium segments; counter by anchoring maintenance-free sealed unit dominance in commercial fleets where cold-cranking reliability specifications resist chemistry migration.
For New Entrants and Emerging Players: Qualified battery technician training and certification services represent a service-layer gap where incumbents under-serve Northern England's independent garage networks. Penetrate Scotland's marine service clusters through specialized nickel-cadmium and deep-cycle configurations engineered for offshore vessel duty cycles. A go-to-market angle anchored in Environment Agency hazardous waste handling accreditation differentiates against generalist distributors lacking technical compliance depth.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed automotive aftermarket platforms seeking battery verticals to complement existing parts distribution. The five-to-ten year viability window favors recyclers with secured collection pool access under producer responsibility frameworks. Acquisition targets should demonstrate dual UK-EU compliance capability for Northern Ireland supply route optionality. Watch lithium-ion penetration rates in mild-hybrid 48V architectures as the inflection signal for lead-acid demand trajectory revision.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Smelting | Captive feedstock supply insulates margin stability against London Metal Exchange price volatility. |
| AGM Technology Licensing Agreement | Absorbed glass mat separator know-how transfer accelerates start-stop system qualification with Birmingham OEM assembly lines. |
| Recycling Infrastructure Joint Venture | Domestic collection pool consolidation secures Waste Batteries Regulations compliance cost recovery. |
| Direct-to-Workshop Channel Expansion | Bypassing motor factor intermediaries captures pricing power from consolidated garage group procurement. |
| Marine Certification Program Investment | Scottish Environment Protection Agency accreditation opens Aberdeen offshore vessel maintenance hub access. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with battery manufacturer sales directors, fleet procurement managers, automotive workshop owners, and Environment Agency hazardous waste officers; and secondary validation against BSI standards documentation, UK trade customs records, SEC filings of listed battery producers, and Waste Batteries Regulations enforcement data. Triangulation between bottom-up channel volume estimates and top-down OEM production data anchored market sizing integrity.
Across the analysis window, the forecasting framework modeled chemistry transitions, technology penetration curves, and regional demand clustering. Segmentation dimensions included product type, end-user vertical, technology architecture, and distribution channel configuration. CAGRs derived from regression analysis of replacement cycle frequencies, vehicle parc aging, and regulatory compliance cost trajectories. Industry-specific inputs incorporated lead price volatility indices and start-stop system adoption rates in British passenger vehicle registrations.
Material uncertainties — abrupt lithium-ion cost parity achievement, post-Brexit regulatory divergence acceleration, or lead smelter capacity disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding technician training pipeline recovery and fleet electrification pacing. Revision becomes warranted when lithium-ion penetration in mild-hybrid applications crosses thresholds that fundamentally restructure lead-acid replacement demand elasticity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Elastic Battery Binders Market
Batteries
Power-Sports Batteries Market
Batteries
48 Volt Battery System Market
Batteries
North Africa Battery Market
Batteries
Norway Rechargeable Battery Market
Batteries
Nimh Battery Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Advanced Batteries Market
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Sodium Nickel Chloride Battery Market
Batteries
India Alkaline Battery Market
Batteries
PERC Battery Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Taiwan Battery Market