
 Iron-Chromium Flow Battery Market | 2026-2036
Iron-Chromium Flow Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Iron-Chromium Flow Battery Market Insights
Modular containerized packaging is shifting buyer choice toward plug-and-deploy configurations that slash installation timelines and site preparation costs. ESS Inc. leverages its all-iron electrolyte architecture to eliminate cross-contamination risks and simplify supply chains. Sumitomo Electric Industries anchors Asian utility relationships through decades of power electronics integration. ViZn Energy Systems differentiates via zinc-iron hybrid designs that compete for commercial and industrial microgrid contracts.
An iron-chromium flow battery stores electrochemical energy in separate tanks of iron and chromium electrolyte solutions, pumped through a membrane-separated cell stack where redox reactions enable reversible charge and discharge cycles lasting 6–12 hours at ambient temperatures. Grid-scale batteries dominate capital deployment as utilities prioritize multi-megawatt installations for renewable firming and transmission deferral. Frequency regulation applications sustain premium pricing due to sub-second response requirements and ancillary service revenue streams. Stationary batteries for commercial and industrial end users represent an expanding margin pool where behind-the-meter peak shaving contracts shorten payback periods.
China's MIIT enforces GB standards for battery energy storage system safety and grid compatibility, while the EPA and FERC in the United States shape environmental permitting and wholesale market participation rules that determine project economics. The EU Green Deal and F-Gas Regulation constrain competing vanadium flow chemistries, indirectly expanding addressable share for iron-chromium systems. Stakeholders must monitor evolving capacity market designs and electrolyte recycling mandates that will determine long-term cost structures and geographic manufacturing placement.
Market Dynamics
Utility-scale renewable integration is forcing procurement teams to prioritize long-duration storage chemistries that deliver 6–12 hour discharge cycles without thermal runaway risks. China's updated GB standards and the EU's F-Gas Regulation are simultaneously constraining vanadium alternatives and accelerating iron-chromium qualification timelines.
Growth Catalysts
- MIIT Grid Standards:China's revised battery energy storage system safety mandates eliminate competing chemistries that fail thermal stability tests, opening procurement windows for iron-chromium systems in provincial grid tenders.
- Transmission Deferral Economics:Utilities in Germany and the United States are deploying multi-megawatt installations to delay substation upgrades, creating bankable revenue streams for 20-year asset contracts.
- Iron Electrolyte Abundance:Supply security concerns around vanadium concentrates are redirecting cathode material procurement toward domestically sourced iron salts that bypass concentrated mining jurisdictions.
Market Restraints
- Membrane Cost Concentration:Perfluorinated ion exchange membranes remain concentrated among Japanese and US specialty chemical suppliers, exposing stack manufacturers to input price volatility and allocation risk.
- Round-Trip Efficiency Gap:Iron-chromium systems operate at 75–80% efficiency versus 85%+ for lithium-ion, compressing ancillary service revenue margins in frequency regulation markets where every percentage point determines dispatch priority.
- Electrolyte Volume Requirements:Energy density limitations demand 3–4x larger tank footprints than comparable lithium installations, restricting urban substation retrofits and elevating land acquisition costs in dense markets.
Strategic Opportunities
- Behind-the-Meter C&I Contracts:Commercial and industrial microgrids in California and Texas are negotiating peak-shaving agreements that monetize 4–8 hour discharge profiles through demand charge avoidance.
- EU F-Gas Regulatory Tailwind:The phasedown of sulfur hexafluoride and perfluorocarbon manufacturing is disqualifying vanadium flow batteries with fluorinated membrane stacks from Green Deal-aligned tenders.
- Hybrid Renewable-Storage PPAs:Solar-plus-storage and wind-plus-storage power purchase agreements in India and Australia are incorporating iron-chromium duration guarantees that lithium configurations cannot match.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Flow battery stack design and membrane-electrode assembly optimization require specialized expertise concentrated among a handful of academic programs and incumbent research labs.
- Extended Certification Cycles:UL 9540 and IEC 62933-5-2 testing protocols for multi-hour duration systems stretch 18–24 months, delaying revenue recognition and compressing project IRRs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron-Chromium Flow Battery Market |
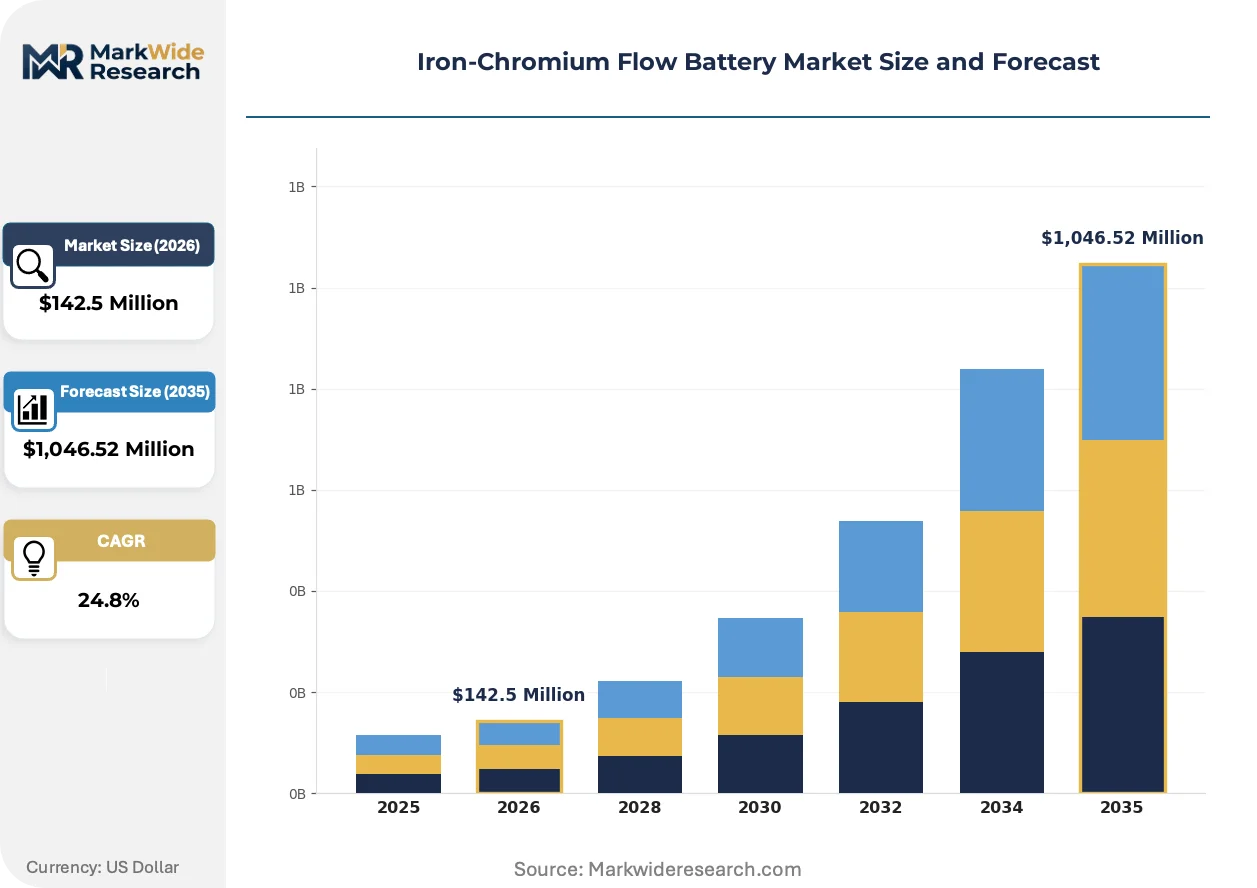
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $1,046.52 Million |
| CAGR (2026 – 2036) | 24.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Batteries, Portable Batteries, Grid-Scale Batteries, Backup Power Systems Application: Renewable Energy Storage, Uninterruptible Power Supply, Peak Shaving, Frequency Regulation End User: Utilities, Commercial, Industrial, Residential Technology: Electrolyte Flow, Energy Management Systems, Power Conversion, Control Systems |
| Companies Covered | ViZn Energy Systems, ESS Inc., Sumitomo Electric Industries, Primus Power, UniEnergy Technologies, Schmid Group, Lockheed Martin, VoltStorage GmbH, JenaBatteries GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron-Chromium Flow Battery Market Trends and Innovations
Containerized system architecture is compressing installation timelines from months to weeks. Electrolyte formulation advances are addressing chromium crossover degradation. Procurement teams are restructuring vendor relationships around performance guarantees rather than equipment transfers.
Membrane-less cell stack architecture is unifying the functions of ion transport and reactant separation within single-component electrodes. German and Chinese utilities are piloting these configurations in 100kW demonstration units. This convergence is unifying previously separate supply chains for membranes, bipolar plates, and electrode substrates into integrated manufacturing lines.
The EU F-Gas Regulation is banning perfluorinated compounds in battery manufacturing inputs from 2030. Flow battery manufacturers are reformulating electrolyte additives and membrane materials to maintain conductivity without fluorinated polymers. Grid-scale tenders in Spain and Italy are already excluding non-compliant chemistries from eligibility.
Power purchase agreement structures are migrating from equipment procurement to energy-as-a-service contracts where vendors retain ownership and charge availability fees. Industrial offtakers in mining and data center verticals are adopting these arrangements to bypass balance-sheet treatment of battery assets. This shift is most visible in Australian and South African markets where currency volatility discourages capital-intensive ownership models.
Iron-Chromium Flow Battery Market Segmentation
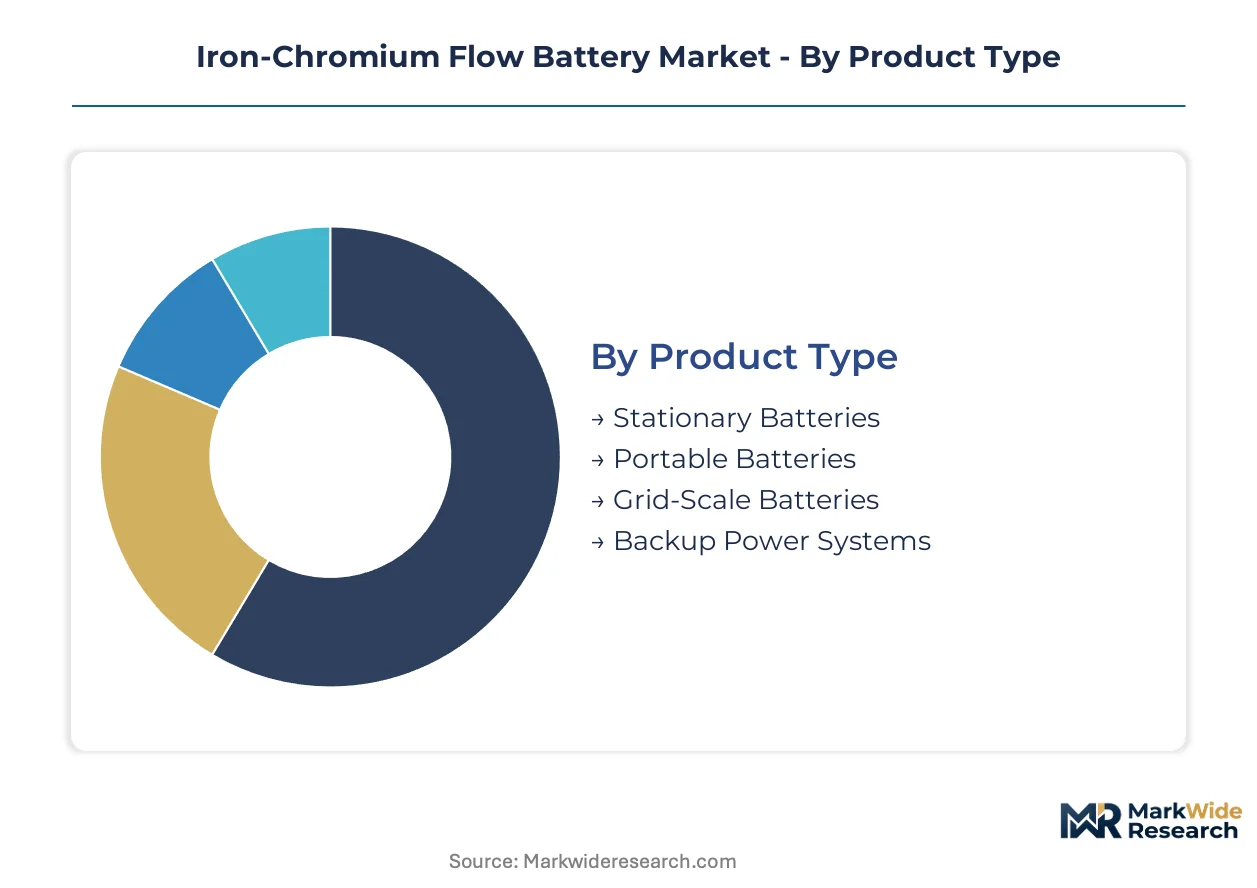
Iron-chromium flow battery deployments fragment across four distinct dimensions, each carrying unique certification burdens and procurement workflows. Understanding these splits reveals where capital concentrates and which technical specifications determine vendor selection.
Product Type:
UL 9540 and IEC 62933-5-2 certifications apply differentially across product categories, with grid-scale installations facing the most exhaustive fire safety and grid interconnection testing protocols.
- Grid-Scale Batteries:Multi-megawatt containerized systems dominate capital deployment in utility tenders across China, Germany, and the United States. MIIT's revised GB standards and FERC Order 841 compliance requirements stretch certification timelines to 18-24 months, compressing project IRRs but creating durable competitive moats for qualified suppliers.
- Stationary Batteries:Behind-the-meter commercial and industrial installations in California and Texas negotiate 4-8 hour discharge contracts through demand charge avoidance structures. These systems bypass some transmission-level interconnection studies but still require IEEE 1547 compliance for distributed energy resource integration.
- Backup Power Systems:Critical infrastructure deployments in data centers and hospitals prioritize black-start capability and islanding resilience.
- Portable Batteries:Modular skid-mounted units serve temporary construction loads and remote mining operations with rapid redeployment flexibility.
Grid-Scale Batteries sits at the top of the volume ranking, with Stationary Batteries climbing the fastest.
Application:
Revenue model differentiation separates applications by contract structure and dispatch priority in wholesale markets.
- Renewable Energy Storage:Solar-plus-storage and wind-plus-storage PPAs in India and Australia incorporate iron-chromium duration guarantees that lithium configurations cannot match. These contracts monetize 6-12 hour discharge profiles through firming obligations and renewable energy credit stacking.
- Frequency Regulation:Sub-second response requirements in PJM and CAISO ancillary service markets sustain premium pricing despite round-trip efficiency gaps versus lithium-ion. Every percentage point of efficiency determines dispatch priority and revenue capture.
- Peak Shaving:Commercial offtakers in mining and data center verticals adopt energy-as-a-service contracts to bypass balance-sheet treatment of battery assets.
- Uninterruptible Power Supply:Mission-critical loads in healthcare and financial services demand instantaneous transfer and voltage regulation.
Renewable Energy Storage commands the largest installed base, while Peak Shaving gains share fastest in deregulated retail markets.
End User:
Procurement sophistication and counterparty risk profiles vary sharply across customer categories.
- Utilities:State-owned grid operators in China and municipal utilities in Germany drive multi-megawatt tenders with 20-year asset contracts. These buyers demand performance guarantees, liquidated damages clauses, and long-term electrolyte supply commitments.
- Industrial:Mining operations in Australia and South Africa adopt energy-as-a-service arrangements to circumvent currency volatility and capital intensity. Currency hedging through vendor-retained ownership models accelerates procurement decisions.
- Commercial:Data center operators and retail chains negotiate behind-the-meter peak shaving with shorter payback thresholds.
- Residential:Single-family and multi-family installations remain marginal due to footprint requirements and land constraints in dense markets.
Utilities anchor procurement volume, with Industrial expanding most quickly through mining and heavy manufacturing verticals.
Technology:
Supply chain concentration and intellectual property intensity differentiate technology stack components.
- Electrolyte Flow:Iron and chromium salt formulations determine system longevity and degradation rates. Advances in chromium crossover suppression are extending stack life and reducing maintenance intervals in German and Chinese pilot installations.
- Power Conversion:Inverter and power electronics integration from established industrial suppliers determines round-trip efficiency and grid code compliance. Japanese and Korean power semiconductor manufacturers anchor this subsegment.
- Energy Management Systems:Software platforms optimize dispatch against wholesale price signals and renewable generation forecasts.
- Control Systems:Battery management units monitor stack health, electrolyte levels, and thermal conditions.
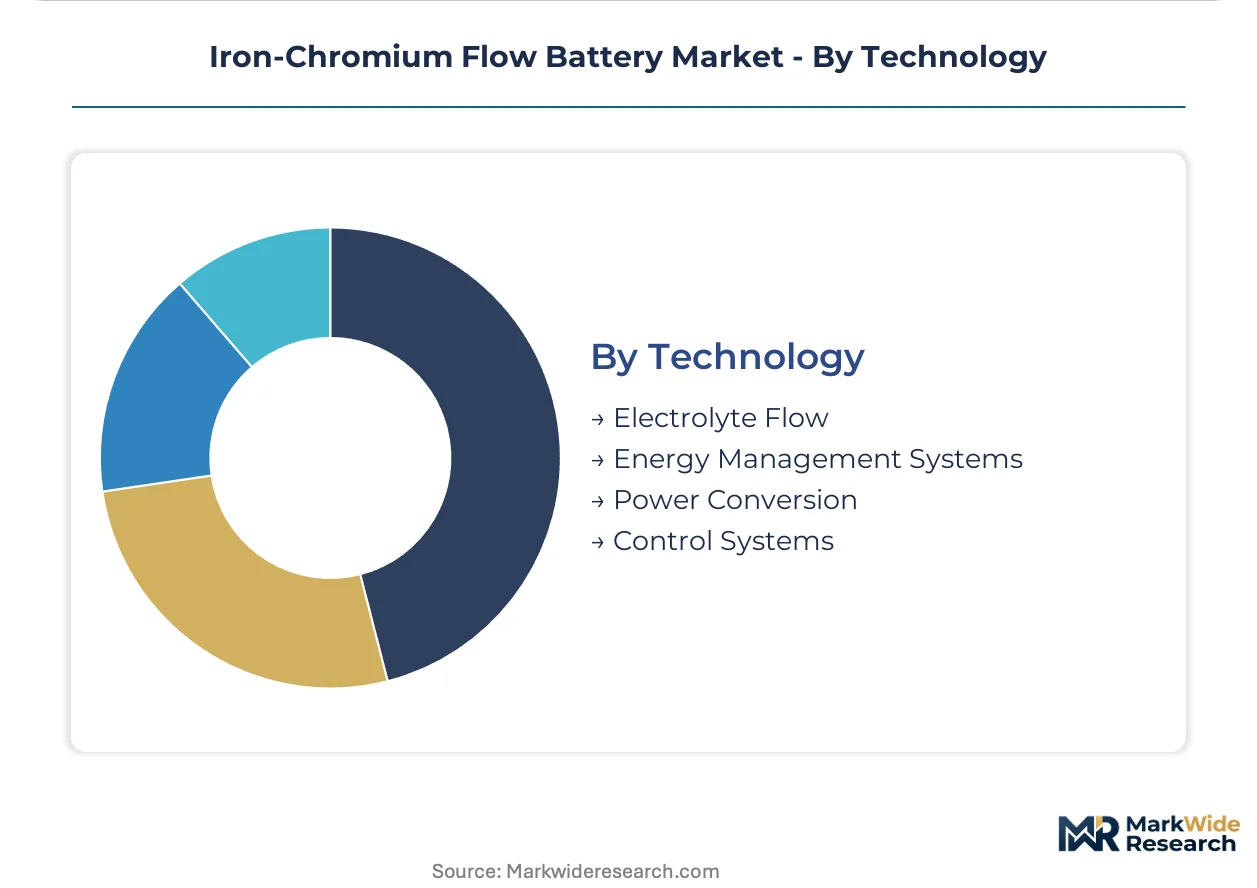
Electrolyte Flow represents the largest value pool, with Power Conversion gaining importance as efficiency margins tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron-chromium flow battery technology achieved commercial scale in Japan during the 1980s through demonstration projects led by state-backed research consortia. Deployment patterns now concentrate in jurisdictions with aggressive renewable integration mandates and domestic electrolyte sourcing capabilities.
China
Provincial grid operators in Shandong and Gansu provinces are tendering 100MW-plus storage installations to accommodate wind curtailment reduction targets. MIIT's updated GB standards for battery energy storage system safety have disqualified several competing chemistries from state procurement lists. The Zhangjiakou renewable energy demonstration zone hosts multiple iron-chromium pilot installations serving 2022 Winter Olympics legacy microgrids.
United States
Texas ERCOT market participants and California IOUs are procuring long-duration systems to address duck curve ramping constraints and transmission congestion. FERC Order 841 compliance requirements enable wholesale market participation for storage assets, improving project financeability. Greater Houston and Silicon Valley clusters host engineering talent pools developing next-generation stack architectures.
Germany
Transmission system operators TenneT and 50Hertz are deploying grid-scale batteries to defer substation upgrades in northern wind corridors. The EU F-Gas Regulation's 2030 phaseout of perfluorinated compounds is disqualifying vanadium alternatives with fluorinated membrane stacks. Industrial Ruhr and Bavarian manufacturing belts concentrate electrolyte formulation R&D partnerships between chemical conglomerates and stack integrators.
India
Solar Energy Corporation of India tenders incorporate 6-hour duration requirements that favor flow chemistries over lithium-ion configurations. Ministry of Power guidelines mandate domestic content thresholds for battery energy storage projects under the National Electricity Policy. Gujarat and Rajasthan renewable energy zones are emerging as testbeds for solar-plus-storage PPAs with iron-chromium duration guarantees.
Australia
Mining operations in Western Australia and Queensland are adopting energy-as-a-service contracts to circumvent currency volatility and capital intensity constraints. The Australian Energy Market Commission's wholesale demand response mechanism creates revenue streams for behind-the-meter peak shaving installations. Pilbara iron ore hubs and Hunter Valley coal transition zones concentrate early commercial deployments.
Iron-Chromium Flow Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across electrolyte formulation sophistication and membrane-electrode assembly integration depth. The vendor base separates into three functional tiers: integrated system architects controlling full stack design, component specialists supplying membranes or power electronics, and project developers assembling third-party subsystems. Strategic archetypes include chemistry-agnostic platform builders, iron-electrolyte purists, and hybrid metal innovators. Capacity expansion and strategic partnerships dominate competitive moves as firms secure electrolyte supply commitments and utility offtake agreements.
Within the integrated system tier, ESS Inc. and Sumitomo Electric Industries exemplify divergent geographic anchoring strategies. ESS Inc. occupies a position among North American chemistry specialists leveraging all-iron electrolyte architectures. Sumitomo Electric Industries anchors Asian utility relationships through power electronics integration heritage. ViZn Energy Systems represents the hybrid-metal innovation vector competing for commercial and industrial microgrid contracts.
| Leading Market Players |
|---|
| ViZn Energy Systems |
| ESS Inc. |
| Sumitomo Electric Industries |
| Primus Power |
| UniEnergy Technologies |
| Schmid Group |
| Lockheed Martin |
| VoltStorage GmbH |
| JenaBatteries GmbH |
| Others |
Pricing and Supply Chain Analysis
Iron sulfate spot prices on the Dalian Commodity Exchange cascade through electrolyte formulation costs into three distinct procurement tiers across Chinese, German, and United States utility tenders. Buyers with captive iron salt processing capabilities capture margin compression that flows downstream to membrane-dependent stack integrators facing Japanese supplier concentration.
Pricing Analysis
Project-based long-term offtake contracting dominates utility-scale procurement, with pricing stratifying across premium certified, standard compliant, and economy pilot tiers. Price differentiation hinges on UL 9540 certification status and 20-year performance guarantee coverage. Cost compression in economy-tier systems is intensifying because of membrane price volatility from concentrated Japanese suppliers. Industrial mining offtakers in Australia exhibit highest price sensitivity due to currency hedging requirements, while German transmission operators demonstrate lowest sensitivity given transmission deferral value capture.
Supply Chain Analysis
Perfluorinated ion exchange membrane supply rests on Japanese and United States specialty chemical producers, creating single-source vulnerability for stack manufacturers. Iron and chromium salt feedstocks draw from domestic chemical processing in China, Germany, and the United States. Supply chain risk centers on fluorinated polymer regulatory restrictions under the EU F-Gas Regulation. Distribution runs through integrated system architects controlling full stack design rather than component spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The iron-chromium flow battery market functions as a geographic-arbitrage play between China's MIIT-compliant procurement premiums and Germany's F-Gas regulatory displacement of vanadium alternatives. Electrolyte sourcing cost differentials exceed 15% across these jurisdictions.
For Market Incumbents: Deploy captive electrolyte formulation capacity to defend margin position against vanadium flow battery price erosion in European tenders. Sumitomo Electric Industries and ESS Inc. should accelerate backward integration into iron salt processing to offset membrane cost volatility. Secure long-term utility offtake agreements before F-Gas Regulation phaseout accelerates competitive entry.
For New Entrants and Emerging Players: Digital-channel route through energy-as-a-service platforms offers lowest customer acquisition friction in Australian mining and South African heavy industrial verticals. White-space concentration sits with behind-the-meter commercial and industrial microgrids in Texas ERCOT and California IOU territories. Target 4-8 hour discharge contract structures where lithium-ion duration guarantees fail.
For Investors and Strategic Acquirers: Asymmetric upside sits with membrane-electrode assembly specialists possessing fluorine-free formulation intellectual property. Long-term viability across the projection horizon favors integrated system architects with utility relationship depth and electrolyte supply security. Watch MIIT procurement list updates and F-Gas Regulation enforcement timing as inflection indicators for capacity deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Supply Security | Captive iron salt processing in China and Germany insulates margins from commodity volatility. |
| Membrane-Free Stack Development | German and Chinese pilot installations validate convergence of ion transport and reactant separation. |
| Energy-as-a-Service Contracting | Australian mining operations bypass currency volatility through vendor-retained ownership models. |
| F-Gas Regulatory Compliance | EU 2030 fluorinated compound phaseout disqualifies vanadium alternatives from Green Deal tenders. |
| Hybrid Renewable-Storage PPAs | Indian and Australian solar-plus-storage contracts incorporate iron-chromium duration guarantees. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down electrolyte supply tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Triangulation across stakeholder inputs and regulatory filing analysis ensures cross-verified demand and supply estimates.
Input-output matrices map electrolyte volume requirements against installed capacity projections across product type, application, end user, and technology segmentation dimensions. CAGRs derive from regression analysis of historical deployment patterns and policy-triggered step changes in procurement velocity. Key forecast inputs include MIIT tender announcement timelines and F-Gas Regulation enforcement milestones.
The model assumes a particular technology adoption path; alternative pathways for membrane-less cell stack architecture would alter the outlook for fluorinated polymer demand. Forecasts reflect assumptions around certification cycle durations and electrolyte recycling mandate implementation. A small set of triggers—MIIT procurement list revisions, F-Gas Regulation phaseout acceleration, and chromium crossover suppression breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
All-In-One Solar Storage Battery Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Alkaline Secondary Battery Market
Batteries
Smart Battery Charger Market
Batteries
Lithium-Based Battery Charger Market
Batteries
Nickel Cadmium Battery Market
Batteries
Power Tool Batteries Market
Batteries
Battery Swapping Market
Batteries
Primary Lithium Battery Market
Batteries
Tubular Batteries Market
Batteries
Indonesia Battery Market
Batteries
Portable Battery Market
Batteries
North America Battery Market
Batteries
Global Cylindrical Lithium Battery Pack Market
Batteries
Europe Industrial Battery Market