
 Iron Casting Market | 2026-2036
Iron Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Iron Casting Market Intelligence
ASTM A536-grade ductile iron specifications is reorganizing procurement criteria across heavy-duty automotive and construction equipment supply chains. Waupaca Foundry leverages its captive melt capacity to anchor long-term contracts with Detroit-area OEMs. Grede Holdings LLC specializes in complex drivetrain castings, while Georg Fischer Ltd. controls premium infrastructure-grade production across European water and energy networks.
Iron casting is the process of pouring molten ferrous alloy—typically containing 2-4% carbon and 1-3% silicon—into molds to produce engineered components with tensile strengths ranging from 20,000 to 120,000 psi depending on grade and heat treatment. Ductile iron dominates value generation due to its superior strength-to-weight ratio in crankshafts and suspension arms. Sand casting anchors volume across engine blocks and brake drums, though investment casting captures margin in aerospace-adjacent precision components where surface finish tolerances tighten.
EPA emissions mandates and NHTSA fuel-economy standards are forcing OEMs to source lighter, higher-strength ferrous substitutes for steel forgings in powertrain assemblies. India's BIS certification requirements for construction-grade castings and China's GB standards for automotive safety components are reshaping export qualification protocols. Stakeholders must track how dual carbon goals in Beijing and Delhi recast energy-intensive foundry operations before committing to multi-year capacity expansions.
Market Dynamics
EPA emissions mandates and NHTSA fuel-economy standards are forcing automotive OEMs to source lighter, higher-strength ferrous substitutes for steel forgings in powertrain assemblies, restructuring procurement criteria across heavy-duty vehicle supply chains.
Growth Catalysts
- Automotive lightweighting mandates:EPA Tier 3 and NHTSA CAFE standards tighten annually, compelling Detroit-area OEMs to replace steel forgings with ASTM A536-grade ductile iron in crankshafts and suspension arms.
- Infrastructure-grade water network replacement:European utilities under EU Green Deal decarbonization timelines are procuring ductile iron pipe for aging water distribution systems.
- Construction equipment localization:India's PLI scheme for heavy machinery manufacturing is pulling foundry capacity toward domestic BIS-certified casting production for excavator and loader OEMs.
Market Restraints
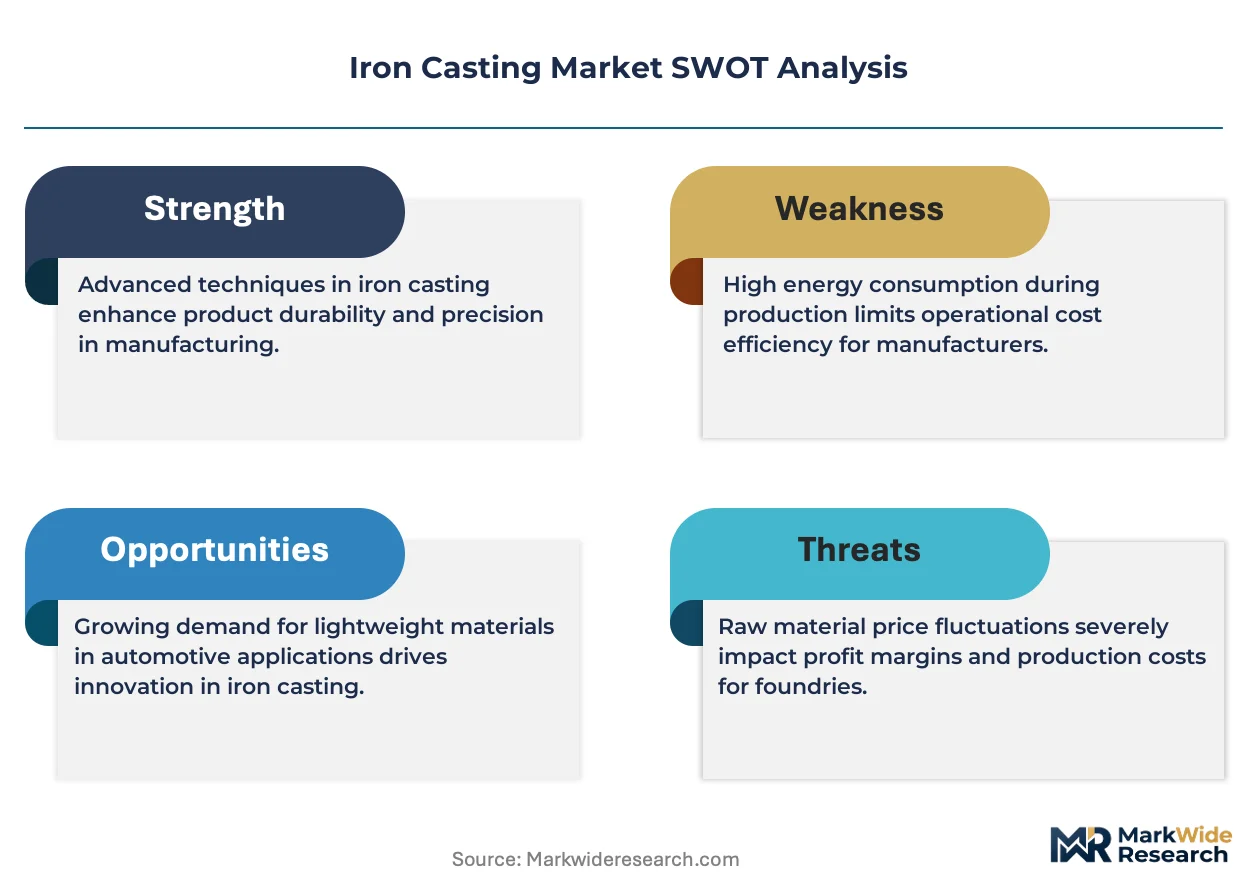
- Scrap metal price volatility:Ferrous scrap input costs swing with Turkish and Vietnamese export demand, compressing margin predictability for merchant foundries without captive melt.
- Supply concentration in premium grades:European water infrastructure casting capacity clusters in Austria and Switzerland, creating bottleneck risk for large-diameter pipe orders.
- Aluminum substitution in passenger vehicle powertrains:EV manufacturers specify aluminum motor housings and structural nodes, displacing iron castings in battery-electric platforms.
Strategic Opportunities
- India's domestic construction equipment boom:BIS certification requirements for construction-grade castings are reshaping export qualification protocols, favoring local foundry investment over import dependency.
- Dual carbon policy tailwinds:China's MEE enforcement of dual carbon goals is accelerating electric arc furnace retrofits, opening efficiency gaps for early movers in Shanxi and Hebei clusters.
- Aerospace-adjacent precision casting:Investment casting for turbine housings and thermal management components is capturing margin where surface finish tolerances tighten below 50 microns.
Industry Challenges
- Patternmaking and coremaking skill scarcity:Master crafts capable of complex sand core assembly for engine block water jackets are retiring faster than apprenticeship pipelines refill.
- Capex intensity of emissions compliance:Baghouse filtration and thermal oxidizer installations for EPA Maximum Achievable Control Technology standards require multi-year payback periods.
- Cross-border certification timeline friction:India's BIS and China's GB standards for automotive safety components impose parallel testing regimes that delay export market entry by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron Casting Market |
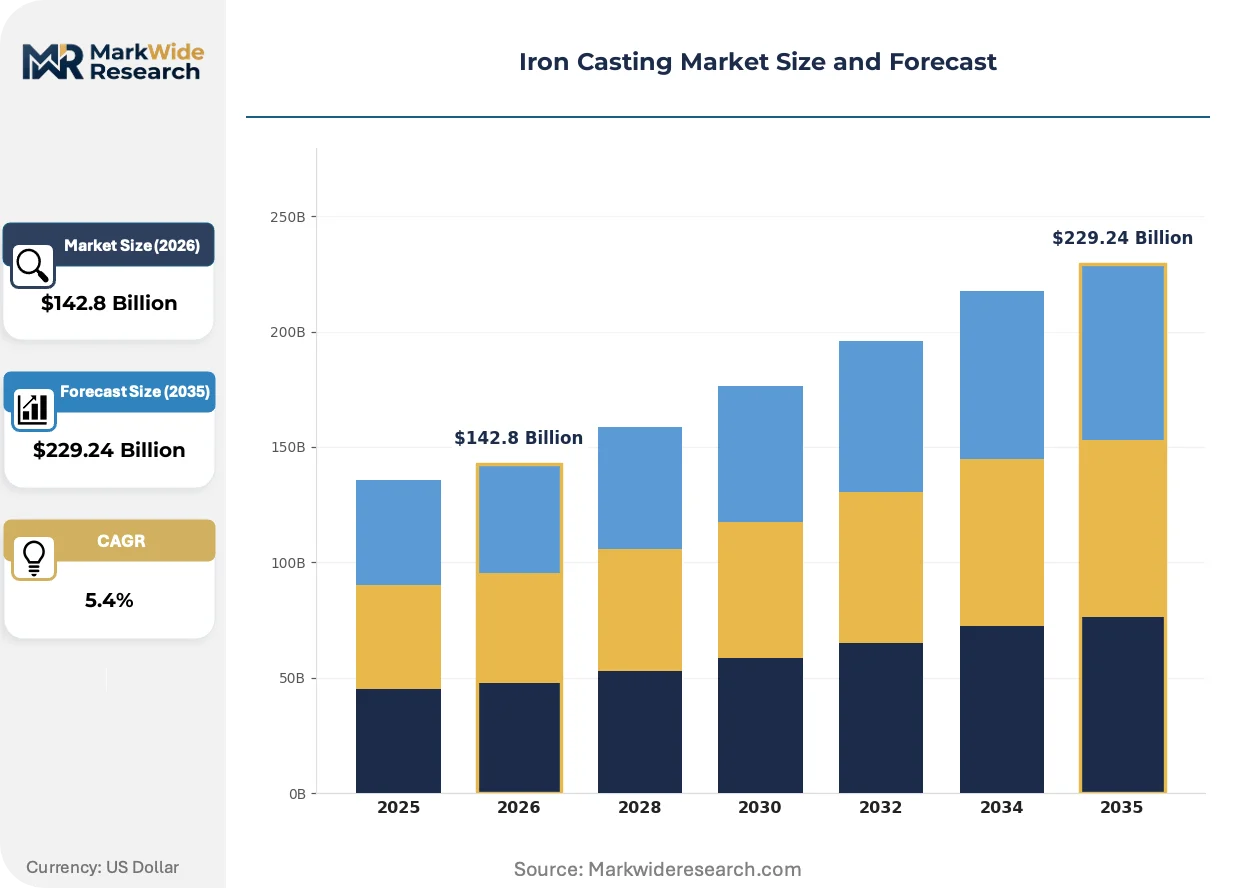
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $229.24 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gray Iron, Ductile Iron, White Iron, Malleable Iron Application: Automotive, Construction, Marine, Industrial Machinery Technology: Sand Casting, Investment Casting, Die Casting, Process Casting End User: Manufacturers, OEMs, Foundries, Repair Services |
| Companies Covered | Waupaca Foundry, Grede Holdings LLC, Proterial Ltd., Bharat Forge Limited, Georg Fischer Ltd., Hitachi Metals Ltd., Grupo Industrial Saltillo, Neenah Foundry Company, Tupy S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron Casting Market Strategic Shifts & Innovations
Digital process control and alternative molding media are compressing lead times while regulatory pressure on embodied carbon forces foundries to reengineer melt shop energy profiles.
3D-printed sand molds and cores are supplanting traditional pattern-based tooling for low-volume and prototype castings. Automotive powertrain engineers at Detroit-area OEMs now specify printed sand for crankshaft prototypes with 48-hour turnaround versus six-week pattern lead times. This compression is collapsing the traditional prototype-to-production timeline and enabling late-stage design changes without tooling sunk costs.
REACH restrictions on crystalline silica exposure are mandating wet scrubbing and enclosed molding lines across European foundries. The industrial consequence is accelerated capital deployment in automated no-bake and vacuum molding systems. Water infrastructure casting specialists in Austria and Germany are responding by consolidating production in greenfield facilities with integrated silica monitoring and closed-loop sand reclamation.
Automotive OEMs now bundle long-term casting supply with design-for-manufacturing engineering services, displacing transactional spot purchasing. Tier-1 suppliers to Ford and GM are absorbing upfront tooling investment in exchange for 7-10 year volume commitments. This behavior is most visible in Michigan and Ohio, where captive melt capacity anchors multi-year contracts for transmission case and differential housing programs.
Iron Casting Market Segmentation
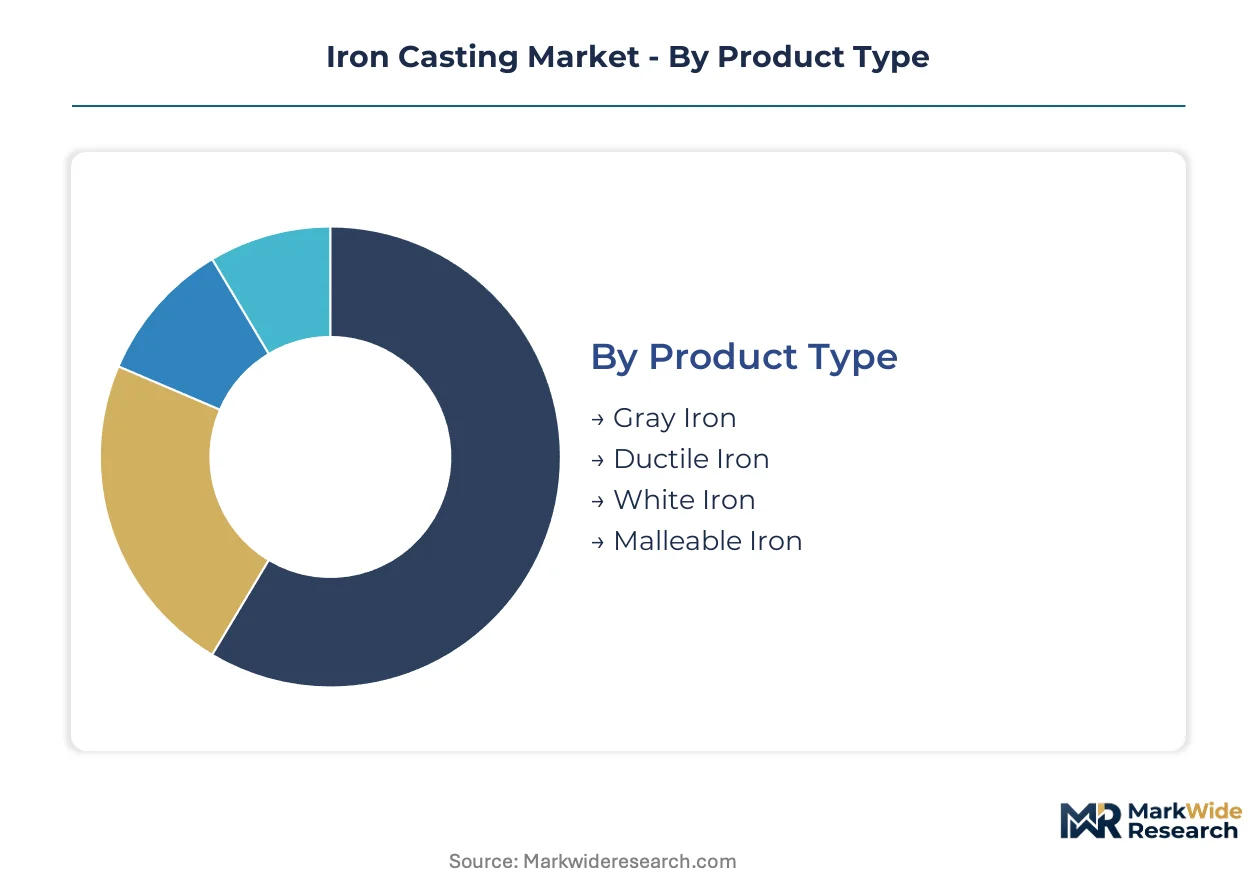
Iron casting procurement patterns diverge sharply between domestic infrastructure replacement cycles and export-driven automotive programs. Understanding these segment boundaries clarifies where capacity investments align with policy tailwinds versus commodity exposure.
Product Type:
Ductile iron dominates export-led automotive contracts, while gray iron anchors domestic construction and municipal water networks. White iron and malleable iron serve narrower industrial niches with concentrated geographic demand.
- Gray Iron:Contains flake graphite microstructures with tensile strengths of 20,000-40,000 psi, specified for engine blocks and brake rotors where vibration damping matters. Demand clusters in India's domestic construction equipment sector under BIS certification mandates, though aluminum substitution in passenger vehicles constrains growth in Detroit-area OEM sourcing.
- Ductile Iron:Spheroidal graphite morphology delivers 60,000-120,000 psi tensile strength with superior fatigue resistance. ASTM A536-grade specifications now govern crankshaft and suspension arm procurement for EPA Tier 3 compliance, with European water utilities specifying the grade for Green Deal-mandated pipe replacement programs.
- White Iron:Carbide-rich structure provides extreme abrasion resistance for mining and cement mill liners. Demand concentrates in Australian and South African mineral processing clusters.
- Malleable Iron:Annealed microstructure offers ductility in thin-section fittings and hardware. Serves plumbing and electrical conduit manufacturers in legacy North American and European building stock renovation.
Gray iron commands the established base. The steepest expansion runs through ductile iron.
Application:
Cost tier stratification separates precision-machined automotive components from rough-cast construction hardware. Marine and industrial machinery occupy intermediate positions with specialized certification requirements.
- Automotive:Powertrain castings—engine blocks, transmission cases, differential housings—face NHTSA CAFE-driven lightweighting mandates. Detroit-area OEMs now bundle 7-10 year volume commitments with design-for-manufacturing engineering services, favoring foundries with captive melt capacity.
- Construction:Excavator booms, loader buckets, and compaction equipment frames drive demand in India's PLI-supported heavy machinery localization. BIS certification requirements reshape export qualification protocols, pulling capacity toward domestic foundry investment.
- Marine:Propeller hubs, stern frames, and engine bedplates require Lloyd's Register or DNV GL classification society approval. Demand clusters in South Korean and Chinese shipbuilding centers.
- Industrial Machinery:Pump housings, valve bodies, and compressor frames serve process industries with extended replacement cycles. European chemical and energy sectors specify EN-GJS grades for corrosion-resistant applications.
Automotive applications concentrate margin in long-term contracts. Construction equipment offers the fastest volume climb among application segments.
Technology:
Volume scale separates high-output sand casting from margin-capturing investment casting. Die casting and process casting occupy intermediate positions with distinct capital intensity profiles.
- Sand Casting:Green sand and no-bake systems produce 70%+ of global iron casting tonnage. 3D-printed sand molds now compress prototype-to-production timelines from six weeks to 48 hours for Detroit-area powertrain programs.
- Investment Casting:Ceramic shell processes achieve surface finishes below 50 microns for turbine housings and thermal management components. Aerospace-adjacent precision applications command premium pricing with exacting tolerances.
- Die Casting:High-pressure metal injection suits thin-walled automotive structural nodes. Limited adoption in ferrous grades due to tooling wear and cycle time constraints.
- Process Casting:Centrifugal and continuous casting methods produce pipes and cylinders with directional solidification control. European water infrastructure specialists in Austria and Germany deploy these for large-diameter ductile iron pipe.
Sand casting holds the volume base. Investment casting delivers the steepest margin expansion trajectory.
End User:
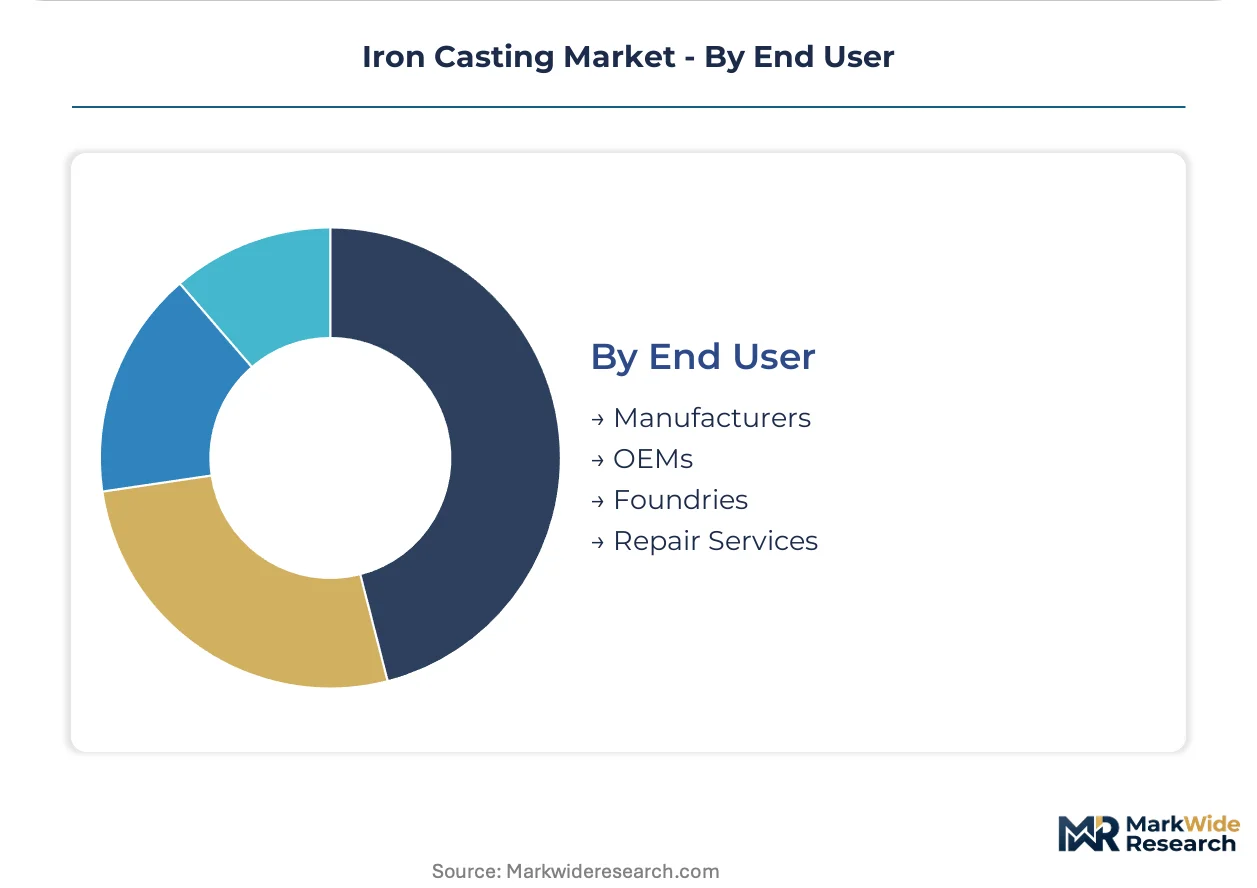
Customer type determines contract structure, with OEMs demanding engineering integration and foundries trading margin for volume certainty.
- Manufacturers:Tier-1 and Tier-2 component suppliers absorb upfront tooling investment in exchange for multi-year program commitments. Michigan and Ohio clusters show this behavior most visibly.
- OEMs:Ford, GM, and construction equipment majors now specify ASTM A536-grade ductile iron with bundled design services. Procurement criteria reorganize around lightweighting compliance rather than spot pricing.
- Foundries:Merchant operations without captive melt face scrap price volatility from Turkish and Vietnamese export demand swings. Captive melt operators anchor regional supply security.
- Repair Services:Aftermarket replacement castings for aging infrastructure and legacy equipment. European water network maintenance drives steady demand for compatible fitting geometries.
OEMs dictate specification evolution. Foundries face the steepest margin pressure from input cost volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity clusters in three distinct geographies with divergent regulatory pressures and end-use specializations. Each concentration serves different demand vectors shaped by local industrial policy and infrastructure investment cycles.
United States
Detroit-area OEMs drive procurement of ASTM A536-grade ductile iron for powertrain lightweighting under NHTSA CAFE standards. EPA Tier 3 emissions mandates tighten annually, forcing foundries to invest in baghouse filtration and thermal oxidizer systems. Michigan and Ohio foundry clusters anchor long-term supply contracts with captive melt capacity securing multi-year program commitments.
Germany
European water utilities under EU Green Deal timelines procure ductile iron pipe for aging distribution network replacement. REACH restrictions on crystalline silica exposure mandate wet scrubbing and enclosed molding lines across foundry operations. Bavarian and Baden-Württemberg facilities consolidate production in greenfield sites with integrated silica monitoring and closed-loop sand reclamation.
China
Domestic construction equipment manufacturers in Shanxi and Hebei provinces expand sourcing from local foundries as export qualification protocols tighten. MEE enforcement of dual carbon goals accelerates electric arc furnace retrofits across northern industrial clusters. GB standards for automotive safety components reshape procurement criteria for crankshaft and suspension arm programs.
India
PLI scheme incentives for heavy machinery manufacturing pull foundry capacity toward domestic BIS-certified casting production. Construction equipment OEMs localize excavator and loader component sourcing under import substitution pressure. Gujarat and Maharashtra foundry clusters capture expanding demand from domestic infrastructure equipment manufacturers.
Japan
Precision casting for aerospace-adjacent turbine housings and thermal management components commands premium pricing with sub-50 micron surface finish tolerances. METI industrial policy supports advanced materials R&D in Nagoya and Osaka manufacturing corridors. JIS standards govern export qualification for automotive safety-critical castings serving regional OEM supply chains.
Iron Casting Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the iron casting sector. The market structure fragments between integrated foundry operators with captive melt capacity and merchant producers exposed to scrap price volatility. Three strategic archetypes dominate: automotive-focused ductile iron specialists with design-for-manufacturing capabilities, infrastructure-grade water network casting producers with process casting expertise, and precision investment casting operators serving aerospace-adjacent applications. Competitive moves concentrate on geographic expansion to follow OEM localization programs and backward integration into scrap processing to stabilize input costs.
Among North American foundry operators, Waupaca Foundry and Grede Holdings LLC exemplify the integrated automotive supply archetype, while Georg Fischer Ltd. represents European infrastructure-grade specialization. These three entities anchor distinct competitive vectors shaped by regional regulatory environments and end-use concentration, with each occupying positions that reflect their geographic origin and implied scale of operations.
| Leading Market Players |
|---|
| Waupaca Foundry |
| Grede Holdings LLC |
| Proterial Ltd. |
| Bharat Forge Limited |
| Georg Fischer Ltd. |
| Hitachi Metals Ltd. |
| Grupo Industrial Saltillo |
| Neenah Foundry Company |
| Tupy S.A. |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts with bundled design-for-manufacturing services lock in both supply access and price visibility for Detroit-area OEMs, insulating captive melt foundries from Turkish and Vietnamese scrap export volatility while exposing merchant operators to margin compression.
Pricing Analysis
EPA Tier 3 and NHTSA CAFE standards dictate the pricing tier structure across automotive powertrain procurement. Three-tier pricing structure across premium, standard, and economy levels separates ASTM A536-grade ductile iron specifications from gray iron commodity grades and white iron abrasion-resistant alloys. Cost compression in standard-grade gray iron is intensifying because aluminum substitution in passenger vehicle powertrains displaces volume. Tier-1 suppliers absorbing upfront tooling investment exhibit the lowest price sensitivity, while merchant foundries without captive melt face acute margin pressure from ferrous scrap input swings.
Supply Chain Analysis
Pattern and core inventory lead times have collapsed from six weeks to 48 hours where 3D-printed sand tooling supplants traditional patternmaking. Supply concentrates in China, India, and the United States for automotive and construction equipment castings. Raw material dependencies center on ferrous scrap, nodularizing alloys, and silica sand for mold media. Single-source vulnerability clusters in European water infrastructure casting capacity across Austria and Switzerland. Distribution runs through Tier-1 supplier networks with 7-10 year program commitments rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EPA emissions mandates and BIS certification requirements creates defensive moats for foundries with pre-qualified capacity, as switching costs for OEMs escalate with bundled engineering services and multi-year tooling investments.
For Market Incumbents: Consolidate captive melt capacity in Michigan and Ohio to anchor Detroit-area OEM contracts against aluminum substitution threats. Deepen backward integration into scrap processing to stabilize input costs against Turkish export demand swings. Prioritize ASTM A536-grade certification maintenance as EPA Tier 3 standards tighten annually. For New Entrants and Emerging Players: Design-for-manufacturing engineering services represent a service-layer gap where incumbents under-serve mid-tier construction equipment OEMs in India's PLI-supported localization programs. Target Gujarat and Maharashtra foundry clusters for BIS-certified ductile iron capacity serving domestic excavator and loader manufacturers. Lead with 48-hour prototype turnaround using 3D-printed sand tooling to displace six-week pattern lead times. For Investors and Strategic Acquirers: Capital is best deployed toward foundry operators with captive melt capacity and pre-qualified automotive safety component certifications. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale. Watch electric arc furnace retrofit momentum in Shanxi and Hebei provinces as an inflection indicator for cost-competitive low-carbon casting supply.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Melt Capacity Expansion | Insulates margin from Turkish and Vietnamese ferrous scrap export volatility. |
| 3D-Printed Sand Tooling Adoption | Compresses prototype-to-production timelines from six weeks to 48 hours for Detroit OEMs. |
| Electric Arc Furnace Retrofit | Aligns Shanxi and Hebei foundries with MEE dual carbon enforcement timelines. |
| BIS Certification Investment | Unlocks PLI scheme procurement from domestic construction equipment OEMs in India. |
| Long-Term Supply Agreement | Bundles design-for-manufacturing services with 7-10 year volume commitments from Tier-1 suppliers. |
Research Approach
A spread of perspectives from foundry operations managers, OEM procurement directors, Tier-1 supplier engineering leads, and construction equipment manufacturing heads converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from SEC 10-K filings, customs and trade data, EPA regulatory dockets, and BIS certification registries. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling from automotive production databases and infrastructure investment trackers.
Segmentation dimensions modeled include product type, application, technology, end user, and regional regulatory cluster across the analysis window. CAGRs were derived from trend extrapolation of lightweighting mandate intensity, infrastructure replacement cycles, and localization policy enforcement. Forecast inputs incorporated ferrous scrap price correlation models and electric arc furnace adoption curves in northern China industrial clusters.
Material uncertainties — scrap metal export demand swings, aluminum substitution acceleration in EV platforms, and dual carbon policy enforcement variability — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and OEM procurement behavior continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Galvanized Steel Market
Metals
High Purity Aluminium Market
Metals
Metal Injection Molding (Mim) Powders Market
Metals
Arc Ferrite Magnet Market
Metals
North America Metal Finishing Market
Metals
Refined Nickel Market
Metals
Carbotanium Market
Metals
Cobalt Market
Metals
Ferrosilicon Magnesium Market
Metals
Steel Wire Market
Metals
Russia Metal Fabrication Market
Metals
Powder Metallurgy Market
Metals
Wear Steel Plate Market
Metals
TMCP Steel Market
Metals
Monel Alloy Market
Metals
Global Copper Market