
 High Purity Aluminium Market | 2026-2036
High Purity Aluminium Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Aluminium Market Intelligence
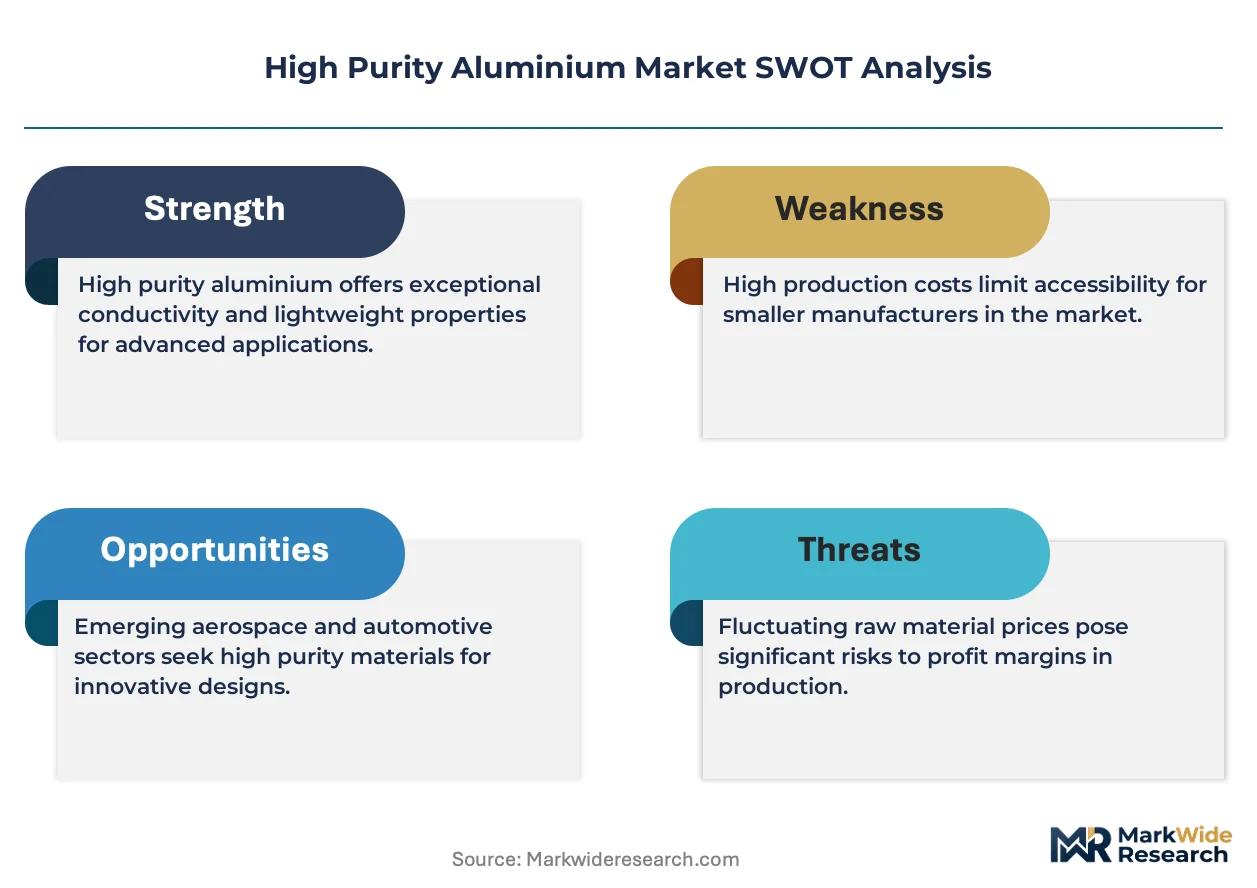
REACH compliance is pivoting the cost-of-entry calculus for European suppliers of ultra-high-purity aluminium. Hindalco Industries leverages backward integration into bauxite refining to secure feedstock purity at source. Norsk Hydro ASA anchors its position through hydropower-smelting synergies that yield low-carbon 4N6 ingots. Sumitomo Chemical Co. Ltd differentiates via proprietary zone-refining capabilities that push purity beyond 6N for semiconductor clients.
High purity aluminium denotes metal refined to 99.999% (5N) or greater, produced through electrolytic refining, zone melting, or tri-iodide decomposition to eliminate iron, silicon, and copper contaminants below parts-per-billion thresholds. Its primary purpose centres on thin-film deposition in semiconductor wafer fabrication, where sputtering target integrity determines chip yield. The electronics application commands the deepest margin pools due to qualification barriers and long-term supply agreements with foundries. Semiconductor manufacturing as an end user absorbs the fastest volume growth, while metallurgical-grade product types remain mature with cyclical pricing tied to primary aluminium benchmarks.
The US EPA and China's MEE enforce divergent emissions frameworks that shape smelter economics and cross-border metal flows. ISO 9001 and ASTM B479 certifications function as de facto market-access filters for aerospace and electronics buyers respectively. Stakeholders must monitor how dual carbon mandates in China and the EU Green Deal's embedded-carbon border adjustments reconfigure the locational advantage of low-emission refining assets.
Market Dynamics
Semiconductor foundries are consolidating sputtering target supply chains around qualified 5N+ aluminium sources, compressing qualification timelines and locking in multi-year offtake agreements that reshape competitive access.
Growth Catalysts
- Chip self-sufficiency mandates:China's dual carbon goals and domestic semiconductor subsidies are accelerating captive refining investments in the Yangtze River Delta electronics cluster.
- EU Green Deal embedded-carbon border adjustments:Low-emission hydropower-smelted 4N6 ingots from Nordic sources now command preferential access to European semiconductor fabs.
- Zone refining advancement:Proprietary tri-iodide decomposition methods are pushing commercial purity beyond 6N for advanced node lithography equipment.
Market Restraints
- Feedstock purity bottlenecks:Bauxite ore quality degradation in Guinea and Australia is forcing additional pre-refining stages that inflate energy costs.
- Single-source supply risk:Zone refining capacity concentrates among three Japanese and German equipment specialists, creating chokepoints for 6N expansion.
- Fluorinated process restrictions:EPA emissions limits on perfluorocarbon byproducts from electrolytic cells are constraining US smelter output flexibility.
Strategic Opportunities
- India PLI scheme for semiconductors:Domestic fabs under construction in Gujarat and Karnataka will require local 4N5 aluminium qualification by 2027.
- Copper interconnect substitution:Advanced packaging's return to aluminium metallization for cost-sensitive memory chips opens volume tiers below leading-edge logic.
- Blockchain traceability platforms:EU REACH Article 33 compliance is creating paid software layers that vertically integrated refiners can monetize as certification services.
Industry Challenges
- Plasma spectroscopy technician scarcity:ICP-MS analysis for parts-per-billion contamination verification requires specialized training pipelines that universities have not scaled.
- Foundry qualification timelines:TSMC and Samsung's 18-month sputtering target validation cycles freeze out new entrants regardless of purity performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Aluminium Market |
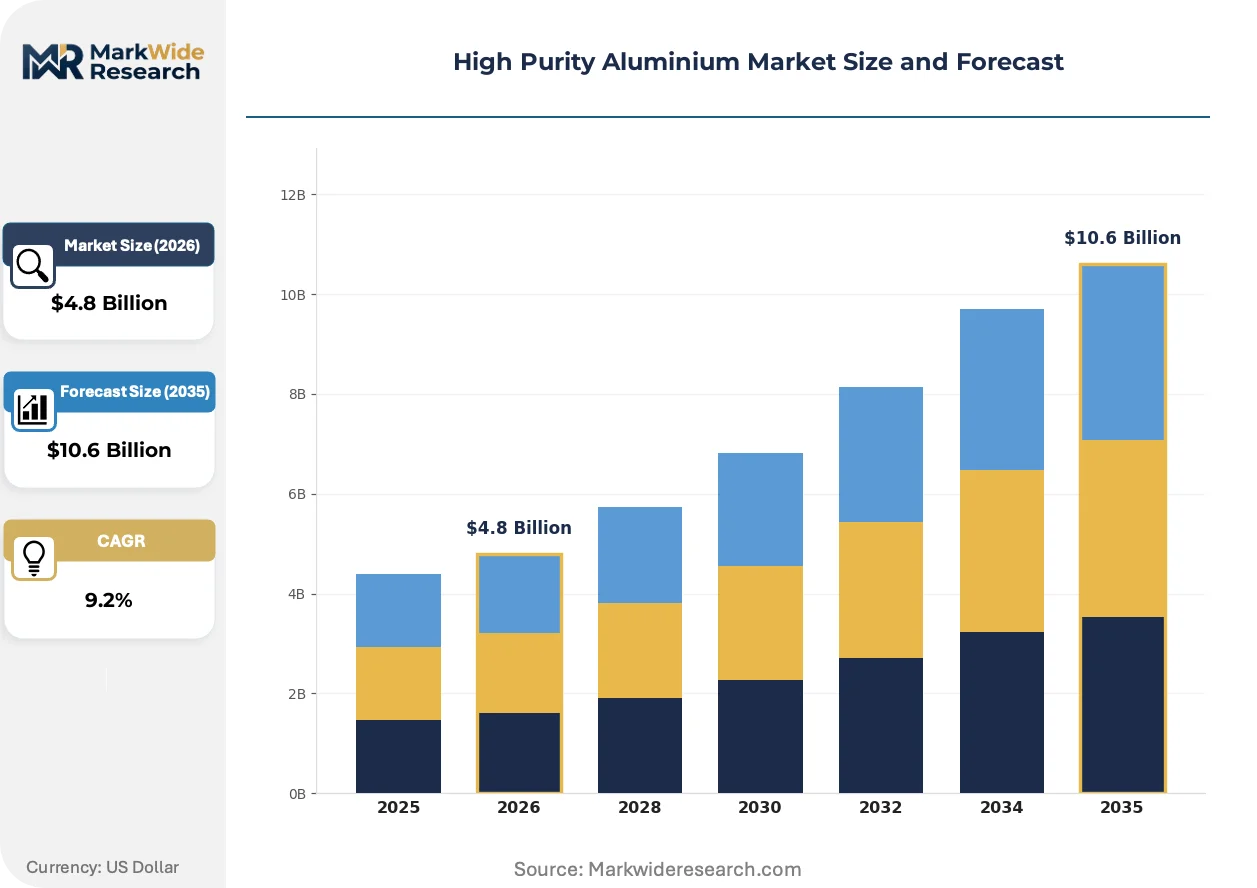
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallurgical, Chemical, Aerospace, Electronics Application: Automotive Components, Semiconductor Manufacturing, Battery Production, Aerospace Structures End User: Manufacturers, OEMs, Research Institutions, Industrial Clients Delivery Mode: Bulk Supply, Customized Packages, On-Demand Delivery, Standard Gases |
| Companies Covered | Hindalco Industries, Aluminum Corporation of China Limited, Alcoa Corporation, Sumitomo Chemical Co. Ltd, Nippon Light Metal Holdings Co. Ltd, Rio Tinto, United Company RUSAL, China Hongqiao Group Limited, Norsk Hydro ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Aluminium Market Strategic Shifts & Innovations
Electrolytic cell automation and regulatory carbon accounting are converging to redefine how purity grades are certified, priced, and traded across semiconductor supply chains.
Sensor-integrated Hall-Héroult cells are automating real-time bath chemistry adjustments that maintain 99.999% purity without manual sampling. Norsk Hydro and Chalco are deploying these retrofits at smelters serving electronics customers. The technology is automating labor-intensive pot-tending roles while compressing batch-to-batch variability that previously required downstream zone refining correction.
EU REACH Annex XVII restrictions on persistent organic pollutants are forcing refiners to document contaminant provenance back to bauxite mine tailings. ECHA compliance audits now require third-party verification of silicon and iron content at each process stage. German and French aerospace buyers are extending these traceability requirements to 4N6 stock for satellite applications, creating a two-tier certification market.
Long-term offtake contracts are displacing spot market purchases for 5N+ grades. Taiwan Semiconductor Manufacturing and Intel have shifted procurement toward five-year supply agreements with fixed purity escalation clauses. This pattern is most pronounced in the Hsinchu Science Park cluster, where foundries seek insulation from aluminium price volatility and concentrate supplier audits on fewer qualified refiners.
High Purity Aluminium Market Segmentation
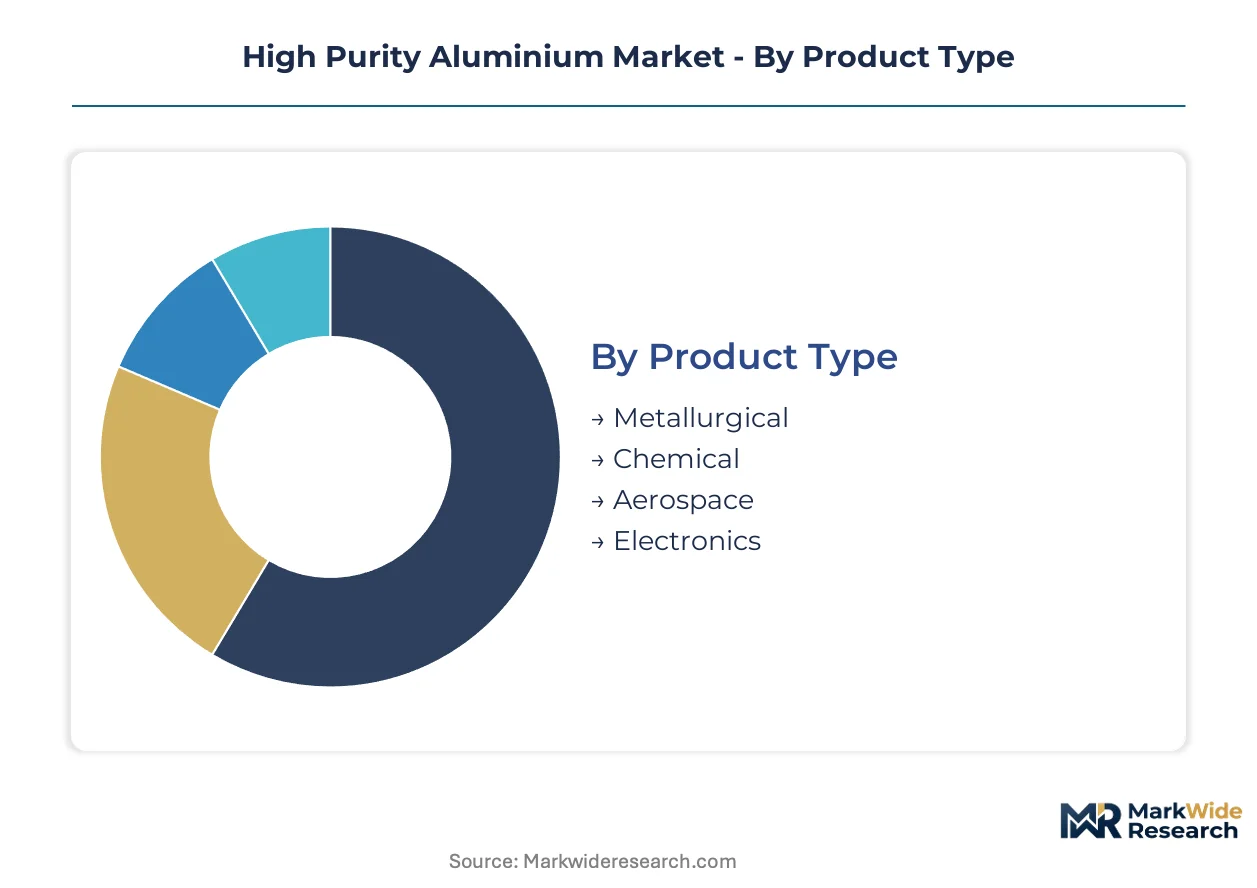
High purity aluminium segmentation reflects divergent purity thresholds, qualification barriers, and margin architectures across electronics, aerospace, and industrial end uses. Each category channels distinct technical specifications, delivery modalities, and customer procurement behaviors that shape supplier positioning.
Product Type:
Customization intensity varies sharply across this category, from standardized metallurgical grades to specification-locked electronics grades requiring foundry qualification.
- Electronics:Refined to 5N or 6N purity through zone melting or tri-iodide decomposition for sputtering target applications. Demand concentrates in Taiwan's Hsinchu Science Park and China's Yangtze River Delta, where TSMC and SMIC enforce 18-month qualification timelines that freeze out unqualified suppliers.
- Aerospace:4N6 ingots certified to ASTM B479 for satellite structural components and cryogenic tanks. German and French buyers now extend EU REACH traceability requirements to stock provenance documentation, creating a two-tier certification market that Nordic hydropower smelters exploit for preferential access.
- Metallurgical:Cyclical pricing tied to LME primary aluminium benchmarks serves commodity alloying applications with minimal purity premiums.
- Chemical:Intermediate purity grades for catalyst substrates and specialty chemical synthesis, where batch consistency outweighs extreme purity thresholds.
Most installed capacity flows through Metallurgical. Expansion is steepest in Electronics.
Application:
Volume concentration versus value capture splits this category, with semiconductor manufacturing commanding premium pricing while automotive and battery applications scale through cost-engineered grades.
- Semiconductor Manufacturing:Sputtering targets for wafer metallization require 5N+ purity with iron and copper contaminants below parts-per-billion. Intel and Samsung have shifted procurement toward five-year offtake agreements with fixed purity escalation clauses, compressing spot market liquidity.
- Battery Production:Aluminium foil for lithium-ion cell current collectors uses 4N5 grades where thickness uniformity and surface cleanliness determine cell performance. China's CATL and BYD are qualifying domestic 4N5 sources to reduce import dependency.
- Automotive Components:Heat exchangers and structural castings consume 4N grades with less stringent traceability than electronics or aerospace.
- Aerospace Structures:Cryogenic fuel tanks and satellite frameworks demand 4N6 certification with full batch documentation for ECHA compliance audits.
Semiconductor Manufacturing captures the highest purity premiums. Battery Production is climbing the fastest as EV cell capacity scales.
End User:
Procurement sophistication and qualification authority distinguish this category, from price-sensitive industrial buyers to specification-owning OEMs.
- OEMs:Semiconductor foundries and aerospace primes dictate purity specifications, qualification protocols, and audit schedules. TSMC's supplier consolidation around qualified 5N+ sources has reduced its active aluminium refiner panel by half over the past qualification cycle.
- Manufacturers:Tier-two component producers purchase certified stock under OEM-directed supplier lists, limiting direct refiner relationships.
- Research Institutions:Small-lot 6N purchases for materials science and physics applications, with limited price elasticity but irregular volume.
- Industrial Clients:Process chemical and general alloying buyers prioritize availability and freight economics over purity documentation.
OEMs control specification authority. Manufacturers handle the greatest transaction volume.
Delivery Mode:
Supply chain configuration and inventory risk allocation differentiate this category, from long-term contract bulk to agile on-demand fulfillment.
- Customized Packages:Foundry-specific ingot dimensions, surface finishes, and contamination-sealed packaging for direct sputtering target fabrication. Norsk Hydro and Chalco have automated Hall-Héroult cell retrofits to reduce batch-to-batch variability that previously required downstream correction.
- Bulk Supply:Multi-tonne annual contracts with fixed purity tiers and indexed pricing for qualified aerospace and electronics buyers.
- On-Demand Delivery:Emergency replenishment for qualified suppliers facing production disruptions, commanding 30-50% premiums over contract rates.
- Standard Gases:Tri-methyl aluminium and other organometallic precursors delivered in sealed cylinder systems for chemical vapor deposition tools.
Bulk Supply anchors contractual relationships. Customized Packages is gaining share fastest as foundries consolidate supplier panels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized plasma spectroscopy technicians concentrate in Taiwan's Hsinchu Science Park and China's Yangtze River Delta, anchoring the two dominant semiconductor manufacturing clusters driving 5N+ aluminium qualification demand.
China
Domestic foundry subsidies under the dual carbon framework accelerate captive refining investments. MEE emissions enforcement tightens traceability documentation for bauxite-to-ingot supply chains. The Yangtze River Delta electronics cluster hosts expanding zone refining capacity serving SMIC and Hua Hong Semiconductor.
United States
Intel's domestic fab expansion under the CHIPS Act drives long-term offtake negotiations for 4N6 and 5N grades. EPA perfluorocarbon emissions limits constrain electrolytic cell output flexibility at legacy smelters. Arizona's semiconductor corridor attracts Nordic hydropower aluminium suppliers seeking low-carbon qualification.
Germany
Aerospace primes extend EU REACH Article 33 traceability requirements to satellite-grade 4N6 stock. ECHA compliance audits now mandate third-party verification at each process stage. Bavaria's precision engineering cluster sources certified ingots for cryogenic tank fabrication.
Japan
Tri-iodide decomposition specialists maintain chokehold on 6N zone refining equipment supply. METI industrial policy prioritizes domestic sputtering target material security. Kyushu's materials science corridor houses concentrated zone melting expertise for advanced node lithography.
India
PLI scheme semiconductor fabs under construction in Gujarat and Karnataka require local 4N5 aluminium qualification by 2027. BIS standards development lags behind foundry specifications, creating certification gaps. The Delhi-NCR research corridor trains ICP-MS technicians for contamination verification protocols.
High Purity Aluminium Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered purity grades. The vendor base stratifies between integrated aluminium majors with captive smelting assets and specialized refiners with proprietary zone melting capabilities. Three archetypes dominate: hydropower-smelting Nordic producers, bauxite-integrated Indian-Chinese conglomerates, and Japanese-German zone refining equipment specialists. Capacity expansion and backward integration into bauxite refining constitute the primary competitive vectors as feedstock purity bottlenecks intensify.
Among integrated producers, Hindalco Industries leverages upstream bauxite control to secure feedstock purity at source. Norsk Hydro ASA anchors the low-carbon tier through hydropower-smelting synergies yielding 4N6 ingots. Sumitomo Chemical Co. Ltd occupies the ultra-high-purity position via proprietary zone-refining capabilities pushing beyond 6N for semiconductor clients.
| Leading Market Players |
|---|
| Hindalco Industries |
| Aluminum Corporation of China Limited |
| Alcoa Corporation |
| Sumitomo Chemical Co. Ltd |
| Nippon Light Metal Holdings Co. Ltd |
| Rio Tinto |
| United Company RUSAL |
| China Hongqiao Group Limited |
| Norsk Hydro ASA |
| Others |
Cost & Logistics Intelligence
TSMC and Samsung's five-year offtake agreements with fixed purity escalation clauses are compressing spot market liquidity and forcing suppliers to absorb volatility through contract structures rather than price premiums. This procurement consolidation concentrates pricing power among qualified 5N+ refiners while locking out speculative spot players.
Pricing Analysis
Certification-bundled versus unbundled service splits dominate transaction structures. Electronics-grade 5N aluminium carries ISO 9001 and foundry-specific qualification costs embedded in long-term contracts, while metallurgical grades trade on LME-indexed spot terms. Price differentiation rests on purity tier and carbon intensity documentation, with Nordic hydropower-smelted 4N6 commanding premiums over coal-intensive alternatives. Cost compression in 4N5 battery foil is intensifying as China's CATL and BYD qualify domestic sources. Industrial alloying buyers exhibit highest price sensitivity; semiconductor foundries show least.
Supply Chain Analysis
Dual-sourcing mandates from Intel and Taiwan Semiconductor require qualified refiners to maintain redundant production lines across geographies. Supply concentrates in China, Norway, and Japan, with bauxite feedstock drawing from Guinea and Australian mines vulnerable to quality degradation. Zone refining equipment and tri-iodide precursor chemicals rest on Japanese-German specialist chokepoints. Single-source vulnerability in 6N capacity creates qualification bottlenecks. Distribution runs through direct mill-to-foundry bulk contracts with customized packaging for sputtering target fabrication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high purity aluminium market reads as a late-cycle quality story, with semiconductor foundries shifting procurement toward 6N grades for advanced node lithography equipment and away from commoditized 4N alternatives.
For Market Incumbents: Anticipate feedstock purity bottlenecks by securing bauxite mine equity or offtake rights in Guinea and Australia before ore quality degradation accelerates. Invest in Hall-Héroult cell automation retrofits to reduce batch-to-batch variability that currently requires downstream zone refining correction, defending margin position against emerging Chinese captive refiners. For New Entrants and Emerging Players: Battery foil manufacturers represent an underserved buyer archetype seeking qualified 4N5 domestic sources in India and Southeast Asia. Target Gujarat and Karnataka fab corridors ahead of 2027 qualification deadlines, positioning as local alternatives to Chinese imports. Lead with ICP-MS contamination verification capabilities and BIS certification pre-clearance. For Investors and Strategic Acquirers: Asymmetric upside sits with zone refining equipment specialists and tri-iodide decomposition technology holders, given 6N capacity expansion constraints. Five-to-ten year viability favors assets with proprietary purification IP and existing foundry qualification relationships. Watch for Intel and Samsung dual-sourcing mandate expansions as inflection signal for qualified supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Refining | Hindalco-style mine equity secures feedstock purity before electrolytic smelting stages. |
| Hydropower Smelting Capacity Expansion | Nordic low-carbon 4N6 ingots qualify for EU Green Deal border adjustment preferences. |
| Zone Refining Technology Licensing | Japanese-German equipment specialists monetize 6N purity chokehold through royalty structures. |
| Long-term Foundry Offtake Agreements | TSMC-style five-year contracts with purity escalation clauses lock in volume visibility. |
| Blockchain Traceability Platform Deployment | EU REACH Article 33 compliance creates paid certification service layers for integrated refiners. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged electrolytic smelter operations managers, semiconductor foundry procurement directors, aerospace prime materials engineers, and ICP-MS laboratory technicians. Secondary validation drew from SEC 10-K filings of listed aluminium producers, ECHA REACH registration databases, customs trade flow records, and ASTM certification registries. Bottom-up capacity modeling and top-down demand segmentation were triangulated against foundry capital expenditure disclosures.
Segment-weighting approaches distributed value and volume across purity tiers, end-use applications, and regional production clusters. The analytical framework modeled electronics, aerospace, metallurgical, and chemical product types against semiconductor manufacturing, battery production, automotive, and aerospace structures demand verticals. CAGRs were derived from regression analysis of historical qualification timelines and projected foundry capacity additions. Forecast inputs incorporated bauxite ore quality degradation curves and EPA perfluorocarbon emissions enforcement trajectories.
Underlying measurement precision varies by segment; semiconductor-grade 5N+ volumes carry tighter precision than metallurgical commodity flows given consolidated customer transparency. Forecasts reflect assumptions on foundry qualification timeline compression, dual carbon policy enforcement intensity, and zone refining equipment capacity expansion. Deviation in Chinese domestic fab subsidy disbursement timing or EU embedded-carbon border adjustment implementation scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Japan Aluminium Powder Market
Metals
Steel Long Products Market
Metals
Aluminium Rolled Products Market
Metals
Lithium Tungstate Market
Metals
Global Copper Cathode Market
Metals
Global Flat Carbon Steel Market
Metals
Copper and Copper Alloy Foil Market
Metals
Titanium Mill Products Market
Metals
Steel Drums Market
Metals
Global Copper Sputtering Target Market
Metals
Steel Wire Market
Metals
Metal Injection Molding (MIM) Parts Market
Metals
Galvanizing Market
Metals
Global High Purity Titanium Powder Market
Metals
United States Aluminum Extrusion Market
Metals
Aluminium Powder Market