
 Steel Wire Market | 2026-2036
Steel Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Wire Market Intelligence
The basis for price differentiation between premium and commodity steel wire is shifting from simple tensile strength to advanced material properties like fatigue resistance and specific coatings. ArcelorMittal leverages its global production footprint to serve large-scale construction projects with standardized products. In contrast, Bridon-Bekaert Ropes Group specializes in high-performance ropes for demanding applications in mining and marine environments. Nippon Steel Corporation competes on material innovation for the automotive sector.
Steel wire is a metallic filament produced by drawing hot-rolled steel rods through dies to reduce their diameter. The process imparts specific mechanical properties, including high tensile strength, with final products often featuring coatings like zinc for galvanization. These wires serve critical functions in applications requiring structural support, fastening, and force transmission. The construction application segment remains the largest volume consumer, utilizing heavy gauge galvanized and cold drawn wires, while stainless steel wire for automotive components represents a higher-margin category.
Global product standards are governed by ISO specifications, ensuring interchangeability and quality benchmarks for international trade. In Europe, the REACH regulation restricts the use of certain chemicals in coatings and surface treatments. Concurrently, in the United States, OSHA standards dictate the safe use of wire ropes in lifting and hoisting applications. Supplier selection will increasingly hinge on the ability to provide documented compliance with diverging regional environmental and safety mandates.
Market Dynamics
The central dynamic shaping the steel wire market is the bifurcation of demand between high-volume, standardized products for construction and high-performance, specialized wires for advanced manufacturing, particularly for automotive and renewable energy applications.
Growth Catalysts
- Renewable Energy Infrastructure:Government mandates for wind and solar power expansion drive demand for high-strength galvanized steel wire in power transmission cables and structural supports for wind turbines.
- Automotive Lightweighting:The automotive industry's shift to electric vehicles and lighter components requires advanced high-strength steel wires for tire cords, suspension springs, and seating structures.
- Urbanization in Emerging Economies:Continued infrastructure and residential construction projects in countries like India and Brazil absorb large volumes of steel wire for concrete reinforcement, fencing, and general construction use.
Market Restraints
- Input Cost Volatility:Fluctuations in the global prices of essential raw materials, specifically high-grade iron ore, coking coal, and zinc for galvanization, create margin pressure and pricing instability for wire producers.
- Substitution from Synthetics:High-performance synthetic fibers, such as aramid and UHMWPE, present a substitution threat in niche, high-value applications like marine and offshore mooring lines where weight and corrosion are critical.
- Environmental Compliance Costs:Adherence to stringent environmental regulations, including the EU's REACH directive on chemical usage in coatings, increases operational costs and requires significant investment in compliant production processes.
Strategic Opportunities
- Smart Wire Development:Integrating fiber optics or micro-sensors into wire ropes creates opportunities for structural health monitoring in critical infrastructure like bridges and dams, offering new service-based revenue models.
- Advanced Medical Wires:The growing demand for minimally invasive surgical procedures presents an opportunity for fine-gauge stainless steel and nitinol wires used in catheters, guidewires, and endoscopic instruments.
- Extreme Environment Coatings:Developing novel polymer or duplex coating systems that provide superior corrosion and fatigue resistance opens access to high-margin applications in offshore oil, gas, and wind energy sectors.
Industry Challenges
- Diverging Compliance Mandates:Manufacturers face the operational challenge of managing and documenting compliance with a fragmented landscape of regional safety standards, such as OSHA rules for wire ropes in the United States.
- High-Cost Process Upgrades:Modernizing production facilities with advanced drawing, heat treatment, and coating lines to meet the specifications for next-generation automotive and aerospace wires requires substantial capital investment.
- Metallurgical Skills Gap:A shortage of experienced metallurgists and material scientists capable of developing and commercializing new steel alloys and specialized coatings hinders product innovation and qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Wire Market |
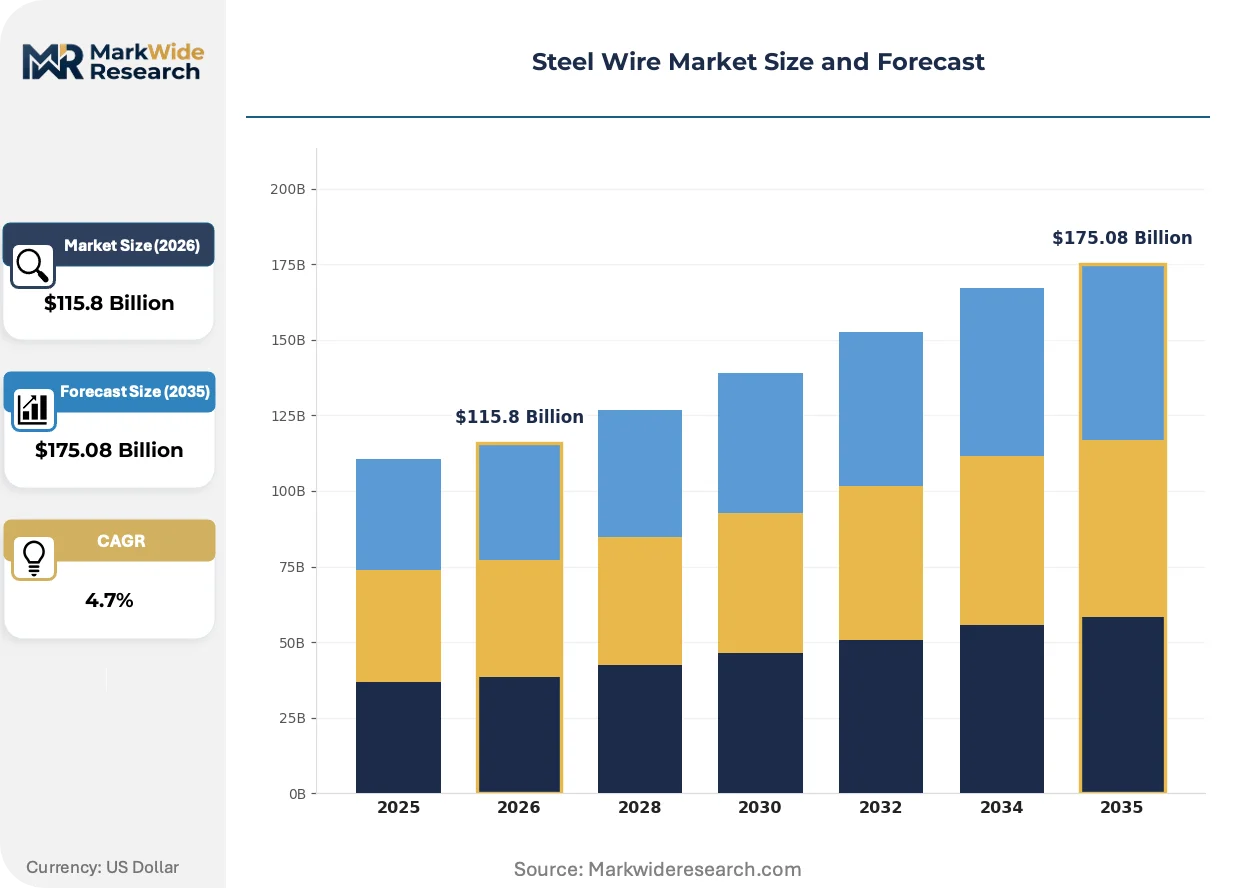
| Market Size in 2026 | $115.8 Billion |
| Market Size in 2035 | $175.08 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Drawn Wire, Hot Rolled Wire, Galvanized Wire, Stainless Steel Wire Application: Construction, Automotive Components, Agriculture Equipment, Industrial Machinery End User: Manufacturers, Construction Firms, OEMs, Retailers Wire Gauge: Light Gauge, Medium Gauge, Heavy Gauge, Specialty Wire |
| Companies Covered | ArcelorMittal, Bridon-Bekaert Ropes Group, Nippon Steel Corporation, JFE Steel Corporation, Kobe Steel, HBIS Group, WireCo WorldGroup, Heico Companies, Insteel Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Wire Market Strategic Shifts & Innovations
Material science advancements are transforming steel wire from a simple structural commodity into a sophisticated, engineered component. This evolution is driven by the convergence of new coating technologies, digitalization, and stringent performance demands from end-users in high-tech sectors.
Digital sensor technology enables the creation of "smart ropes" that provide real-time data on tension, wear, and potential failure points. Mining, crane, and port operators are early adopters, seeking to minimize downtime and improve safety. This technology is integrating predictive maintenance capabilities directly into the wire itself, transforming the value proposition from a simple replacement part to a data-generating asset that enhances operational uptime.
China's "dual carbon" policy framework is compelling a fundamental shift in steel production methods. The policy incentivizes a transition from blast furnace production to electric arc furnace (EAF) processes, which rely heavily on recycled steel scrap. This directly impacts the consistency of raw material feedstock for wire manufacturers across Asia, forcing investment in new quality control systems and process adjustments to manage feedstock variability.
Lifecycle cost analysis is supplanting traditional procurement metrics based purely on initial price per ton. This shift disrupts the business model of commodity distributors, creating an advantage for manufacturers who can provide documented performance data on fatigue life and corrosion resistance. The trend is most visible in procurement for critical infrastructure and offshore energy projects in North America and Europe, where total cost of ownership is paramount.
Steel Wire Market Segmentation
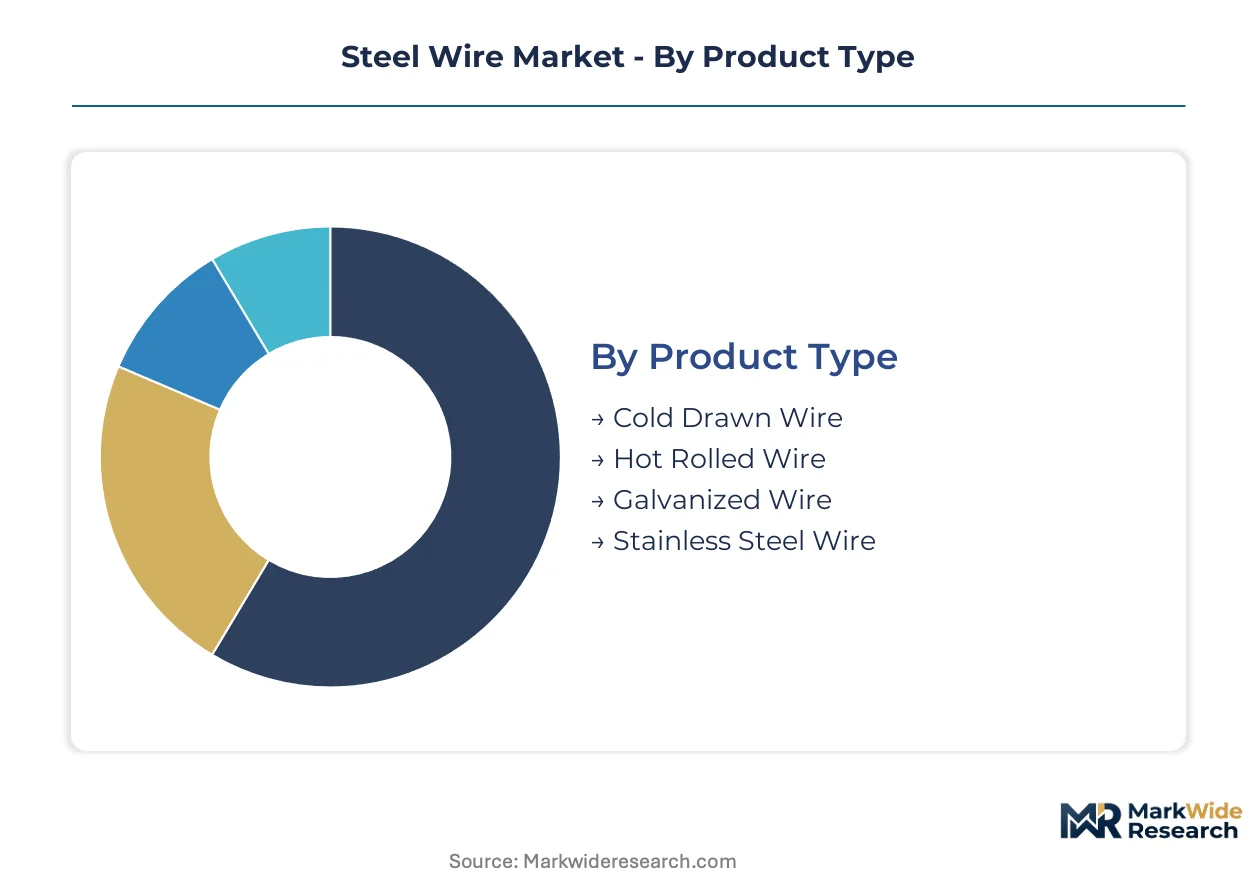
The steel wire market's segmentation reflects the diverse technical specifications and end-use requirements that dictate product selection. Understanding these distinct categories allows manufacturers to tailor production, optimize supply chains, and address specific customer needs across various industries. Each segment presents unique performance criteria and market dynamics influencing pricing and competitive positioning.
Product Type:
Buyers of steel wire in this segment prioritize specific material properties and surface treatments essential for their intended applications.
- Cold Drawn Wire:This wire type undergoes cold working processes to enhance its tensile strength and improve surface finish, making it suitable for applications requiring precision and high mechanical properties. Demand concentrates in the automotive sector for springs and fasteners, driven by lightweighting initiatives.
- Hot Rolled Wire:Produced by rolling steel at high temperatures, this wire offers good ductility and formability, serving as an intermediate product for further processing or for less demanding structural applications. Infrastructure development in China absorbs significant volumes for rebar and general construction.
- Galvanized Wire:Coated with a layer of zinc, this wire provides superior corrosion resistance, making it ideal for outdoor and marine environments. Construction and agriculture sectors drive demand for fencing, mesh, and structural components due to its extended lifespan.
- Stainless Steel Wire:Composed of steel alloys with chromium, this wire offers excellent corrosion resistance and aesthetic appeal for high-value applications. The automotive sector utilizes it for high-performance components, requiring material innovation.
Volume sits with Galvanized Wire; growth tilts toward Stainless Steel Wire.
Application:
The application segment highlights how end-use requirements dictate wire specifications and performance attributes.
- Construction:This segment utilizes a wide range of steel wires, including heavy gauge galvanized and cold drawn wires, for concrete reinforcement, structural support, and fencing. Urbanization in emerging economies like India drives consistent high-volume demand.
- Automotive Components:This application demands high-strength steel wires for critical parts such as tire cords, suspension springs, and seating structures. The shift to electric vehicles and lightweighting initiatives provides a key impetus for advanced wire solutions.
- Agriculture Equipment:Steel wire finds use in various agricultural applications, including baling wire, trellising, and fencing for livestock containment. Durability and corrosion resistance are key performance requirements in this sector.
- Industrial Machinery:This segment uses specialized steel wires for springs, cables, and various mechanical components within manufacturing and processing equipment. Precision and fatigue resistance are critical for machine longevity.
Construction remains the dominant application, while Automotive Components exhibit the steepest expansion trajectory.
End User:
Customer type significantly influences procurement channels and order volumes for steel wire products.
- Manufacturers:These entities integrate steel wire as a raw material into their finished products, ranging from automotive parts to consumer goods. Their purchasing decisions are driven by consistent supply and specific technical specifications.
- Construction Firms:These companies procure steel wire for large-scale infrastructure and building projects, prioritizing bulk quantities and adherence to structural integrity standards. They require reliable delivery schedules for project timelines.
- OEMs:Original Equipment Manufacturers require highly specialized and consistent quality steel wire for integration into their complex machinery and vehicles. Compliance with global product standards like ISO specifications is paramount.
- Retailers:These channels distribute steel wire products to smaller contractors, DIY enthusiasts, and local businesses for general purpose and repair applications. Product availability and competitive pricing are important for this segment.
Manufacturers represent the largest consumer base, with OEMs driving demand for specialized wire solutions.
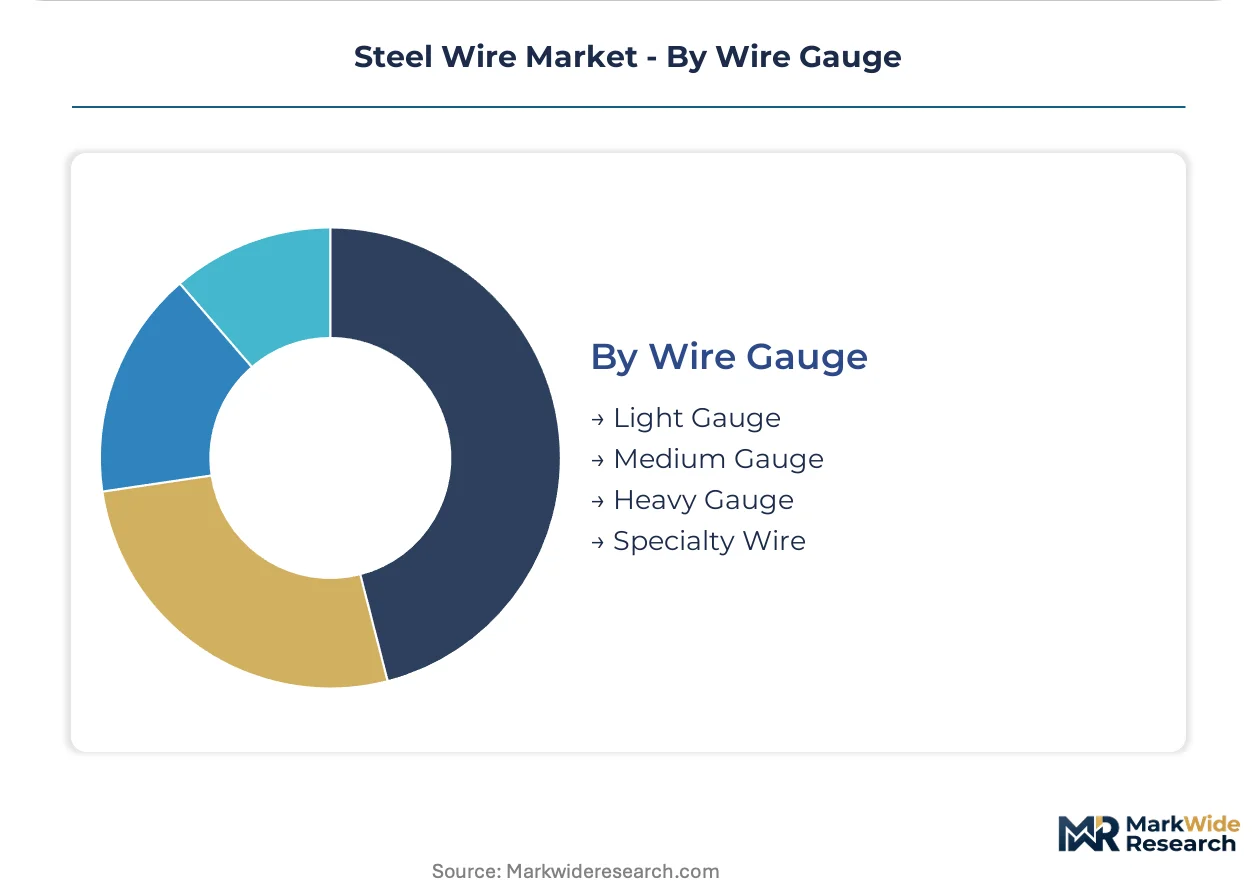
Wire Gauge:
Wire gauge segmentation reflects the diverse structural and mechanical demands across various industries.
- Light Gauge:These fine wires are used in applications requiring flexibility and precision, such as in mesh, small springs, and certain electronic components. Medical devices increasingly utilize these for guidewires and catheters.
- Medium Gauge:This versatile category of wire serves a broad range of applications, including general construction, fencing, and various industrial fasteners. Balancing strength and workability is crucial for this segment.
- Heavy Gauge:Characterized by larger diameters, these wires provide substantial structural support and load-bearing capabilities for heavy construction and infrastructure projects. Power transmission cables and bridge components rely on heavy gauge wires.
- Specialty Wire:This segment encompasses wires engineered for unique performance attributes, such as extreme temperature resistance, specific electrical conductivity, or advanced fatigue resistance. Offshore oil and gas applications often require these custom solutions.
Heavy Gauge wires command significant volume, but Specialty Wire categories are gaining share fastest due to advanced requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta region, a major industrial hub in China, drives significant steel wire consumption for its vast infrastructure projects. This region exemplifies the impact of China's "dual carbon" policy, which reshapes steel production methods. Manufacturers here increasingly integrate recycled steel scrap into electric arc furnace processes.
United States
Demand for advanced steel wire in the United States stems from automotive lightweighting initiatives and renewable energy infrastructure. OSHA standards govern the safe use of wire ropes in lifting applications, influencing product specifications for industrial users. Major automotive manufacturing clusters in the Midwest, such as Detroit, require specialized high-strength wires for vehicle components.
Germany
Germany's robust automotive and industrial machinery sectors create substantial demand for high-performance steel wires. The EU's REACH regulation dictates chemical usage in coatings and surface treatments, impacting production processes for German manufacturers. The Ruhr Valley industrial region, a traditional steel hub, continues to innovate in material science for specialized wire applications.
India
India's rapid urbanization and extensive infrastructure development projects absorb large volumes of steel wire for construction and power transmission. Government policies supporting domestic manufacturing, such as the PLI scheme for certain industries, can influence local wire production. Industrial zones in Maharashtra, particularly around Pune, drive demand for wires used in automotive and general engineering sectors.
Japan
Japan's automotive sector, a global leader in innovation, requires advanced steel wires for lighter and stronger components. JIS standards ensure stringent quality benchmarks for steel products, including wire, used across various Japanese industries. Steel manufacturers in the Kansai region, including Kobe Steel, focus on material innovation for high-value applications.
Steel Wire Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the bifurcated steel wire market. This market structure features global integrated steelmakers, specialized wire manufacturers, and regional distributors. Strategic archetypes include large-scale commodity suppliers and niche high-performance solution providers. Dominant competitive moves involve M&A for technology acquisition and capacity expansion to meet volume demand.
Integrated steelmakers like ArcelorMittal leverage their global production footprint to serve large-scale construction projects with standardized products. Nippon Steel Corporation exemplifies a focus on material innovation, particularly for the automotive sector, driving advancements in high-strength alloys. Bridon-Bekaert Ropes Group sits within the specialized segment, offering high-performance ropes for demanding applications in mining and marine environments.
| Leading Market Players |
|---|
| ArcelorMittal |
| Bridon-Bekaert Ropes Group |
| Nippon Steel Corporation |
| JFE Steel Corporation |
| Kobe Steel |
| HBIS Group |
| WireCo WorldGroup |
| Heico Companies |
| Insteel Industries |
| Others |
Cost & Logistics Intelligence
Experienced metallurgists in regions like the Ruhr Valley drive higher pricing tiers for specialized steel wires, reflecting the labor-cost differentials inherent in advanced material development. This expertise influences the premium customers pay for performance-critical products.
Pricing Analysis
Lifecycle cost analysis anchors pricing in the steel wire market, shifting from initial price per ton to total cost of ownership. Performance data on fatigue life and corrosion resistance drive price differentiation, particularly for critical infrastructure projects. Pricing softness emerges in commodity grades due to high-volume competition and input cost volatility. Construction firms exhibit higher price sensitivity for bulk orders, while OEMs prioritize documented performance for specialized wire solutions.
Supply Chain Analysis
China's "dual carbon" policy mandates reshape steel wire sourcing, pushing manufacturers to integrate recycled steel scrap into electric arc furnace processes. Key supply concentrations exist in China, Germany, and Japan, drawing heavily on high-grade iron ore, coking coal, and zinc. Input cost volatility presents a significant structural risk for wire producers. Distribution runs through a bifurcated model, serving large manufacturers directly and smaller contractors via retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The steel wire market increasingly operates as a cost-of-compliance story, where adherence to regulations like the EU's REACH directive establishes a significant barrier-to-entry moat for compliant manufacturers. This regulatory environment favors players with robust investment in compliant production processes.
For Market Incumbents:Deploy advanced coating technologies to counter substitution threats from high-performance synthetic fibers in niche applications. Incumbents must invest in upgrading production facilities with advanced drawing and heat treatment lines to meet next-generation automotive specifications. Strategic M&A for technology acquisition can consolidate market share against smaller, specialized entrants. This mitigates margin pressure from commodity price fluctuations.
For New Entrants and Emerging Players:OSHA standards in the United States open a window for new entrants specializing in smart wire ropes for lifting applications, offering enhanced safety and predictive maintenance. Focus on developing advanced medical wires for minimally invasive surgical procedures, targeting the fine-gauge stainless steel segment. A go-to-market strategy emphasizing documented compliance and lifecycle cost benefits can penetrate critical infrastructure projects in North America.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized wire manufacturers given the accelerating demand for high-performance materials in electric vehicles and renewable energy. Long-term viability spans the next decade, driven by ongoing infrastructure modernization and automotive lightweighting. Acquisition targets should be asset-light designers with strong IP in advanced coatings or smart wire technologies. The signal to watch is the increasing adoption rate of smart ropes in mining and port operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses high-volume demand for construction and power transmission projects. |
| R&D Investment | Develops advanced coatings for superior corrosion and fatigue resistance in offshore energy. |
| Technology Acquisition | Integrates micro-sensors into wire ropes for real-time structural health monitoring. |
| Certification Investment | Ensures documented compliance with diverging regional environmental and safety mandates. |
| Geographic Diversification | Mitigates supply chain risks and accesses new markets in urbanization initiatives. |
Research Approach
ISO specifications, REACH regulations, and OSHA standards formed the secondary backbone for this analysis, providing foundational data on product quality and regulatory compliance. Primary interviews with automotive engineers, construction firm procurement managers, and specialized wire manufacturers complemented this, offering qualitative market insights. This approach integrated bottom-up market sizing with top-down validation to ensure data accuracy. Customs and trade data further informed regional trade flows.
Historical trendline analysis established growth trajectories for various steel wire product types and applications across the analysis window. The analytical framework modeled market dynamics by product type, application, end-user, and wire gauge. Compound annual growth rates derived from supply-demand imbalances and technological adoption rates. Forecast inputs included electric vehicle production forecasts and infrastructure development spending.
Caveats apply where unforeseen shifts in raw material prices or geopolitical trade policies could materially shift the outlook. Forecasts reflect assumptions on regulatory stability and sustained end-user demand. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Metallurgical Coal Market
Metals
Beryllium Copper Plate Market
Metals
Stainless Steel 400 Series Market
Metals
Clutch Spring Wires Market
Metals
Copper Chromium Black Market
Metals
Stainless Steel Foil Market
Metals
Galvanized Steel Coil Market
Metals
Aluminium Conductors Market
Metals
Electrolytic Iron Market
Metals
Europe Metal Casting Market
Metals
Ore Metals Market
Metals
North America Metal Casting Market
Metals
Silver Enamel Market
Metals
Metal Forging Market
Metals
Heat-Treated Steel Plates Market
Metals
Qatar Metalworking Market