
 Ferrosilicon Magnesium Market | 2026-2036
Ferrosilicon Magnesium Market Size, Share, and Industry Trends Forecast 2026-2036
Ferrosilicon Magnesium Market Analytics
The capital-intensity divergence between integrated smelters and merchant alloy producers is unwinding competitive stability in ferrosilicon magnesium supply. Elkem ASA leverages captive quartzite mines and hydroelectric power in Norway to sustain cost leadership across European nodular grades. FerroGlobe competes through multi-continent furnace operations that span Spain, South Africa, and the United States. Henan Hexing anchors volume position within China's Henan province through proximity to coking coal and steel mill demand clusters.
Ferrosilicon magnesium denotes an iron-silicon-magnesium master alloy typically containing 3-10% magnesium, 44-48% silicon, and balance iron, produced via submerged arc furnace smelting with subsequent ladle injection or cored wire embedding for controlled magnesium recovery. Its primary commercial purpose centers on nodularizing molten cast iron to produce spheroidal graphite structures that deliver tensile strength exceeding 400 MPa in finished components. Nodular ferrosilicon commands the dominant value share among product types due to irreplaceable performance in wind turbine hubs and crankshaft applications where flake graphite structures would fail catastrophically. Automotive components represent the fastest-expanding application segment as OEMs substitute forged steel with ductile iron to reduce unsprung mass in electric vehicle chassis systems.
China's MIIT enforces GB 28666 energy consumption limits that disqualify smaller ferroalloy furnaces below 25 MVA, while India's BIS certification mandates chemical uniformity testing under IS 1559 for all imported nodular grades. REACH registration requirements in Europe compel alloy importers to disclose full substance toxicity profiles, elevating compliance costs for non-European suppliers. Stakeholders must monitor divergence between China's dual carbon goals and India's PLI scheme for specialty steel to anticipate which regulatory trajectory will reshape alloy specification premiums.
Market Dynamics
Capital-intensity divergence between integrated smelters and merchant alloy producers is unwinding competitive stability in ferrosilicon magnesium supply, as captive power and raw material access separate cost leaders from price-takers.
Growth Catalysts
- Automotive lightweighting mandates:OEM procurement of ductile iron crankshafts and suspension nodes is displacing forged steel in electric vehicle chassis systems to reduce unsprung mass.
- India's PLI scheme for specialty steel:Domestic foundry clusters in Gujarat and Maharashtra are expanding nodular ferrosilicon consumption to feed automotive supply chain localization requirements.
- Wind turbine hub specifications:Irreplaceable performance of spheroidal graphite structures in 8MW+ turbine castings is concentrating alloy demand among tier-1 wind OEMs.
Market Restraints
- Quartzite supply concentration:Premium silica deposits cluster in Norway, South Africa, and China's Henan province, exposing non-integrated producers to raw material bottlenecks.
- Energy cost volatility:Submerged arc furnace operations consume 4,500-6,500 kWh per metric ton, making European smelters vulnerable to natural gas price spikes.
- REACH compliance friction:ECHA registration requirements compel alloy importers to disclose full substance toxicity profiles, elevating compliance costs for non-European suppliers.
Strategic Opportunities
- Underpenetrated Southeast Asian foundry base:Vietnam and Indonesia lack domestic nodular alloy production, creating import substitution potential for integrated producers.
- Cored wire embedding convergence:Ladle metallurgy automation combining cored wire injection with real-time thermal imaging is enabling precision magnesium recovery rates above 92%.
- China's dual carbon goals:MIIT enforcement of GB 28666 energy consumption limits is disqualifying subscale furnaces below 25 MVA, consolidating market share among compliant producers.
Industry Challenges
- Furnace metallurgist scarcity:Submerged arc smelting expertise requires 8-12 year apprenticeship cycles, constraining expansion timelines for new market entrants.
- BIS certification timelines:India's IS 1559 chemical uniformity testing mandates 90-120 day approval windows for imported nodular grades, delaying spot market responsiveness.
- Legacy ladle injection integration:Foundries operating conventional magnesium treatment stations face retrofit capex burdens to accommodate cored wire compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferrosilicon Magnesium Market |
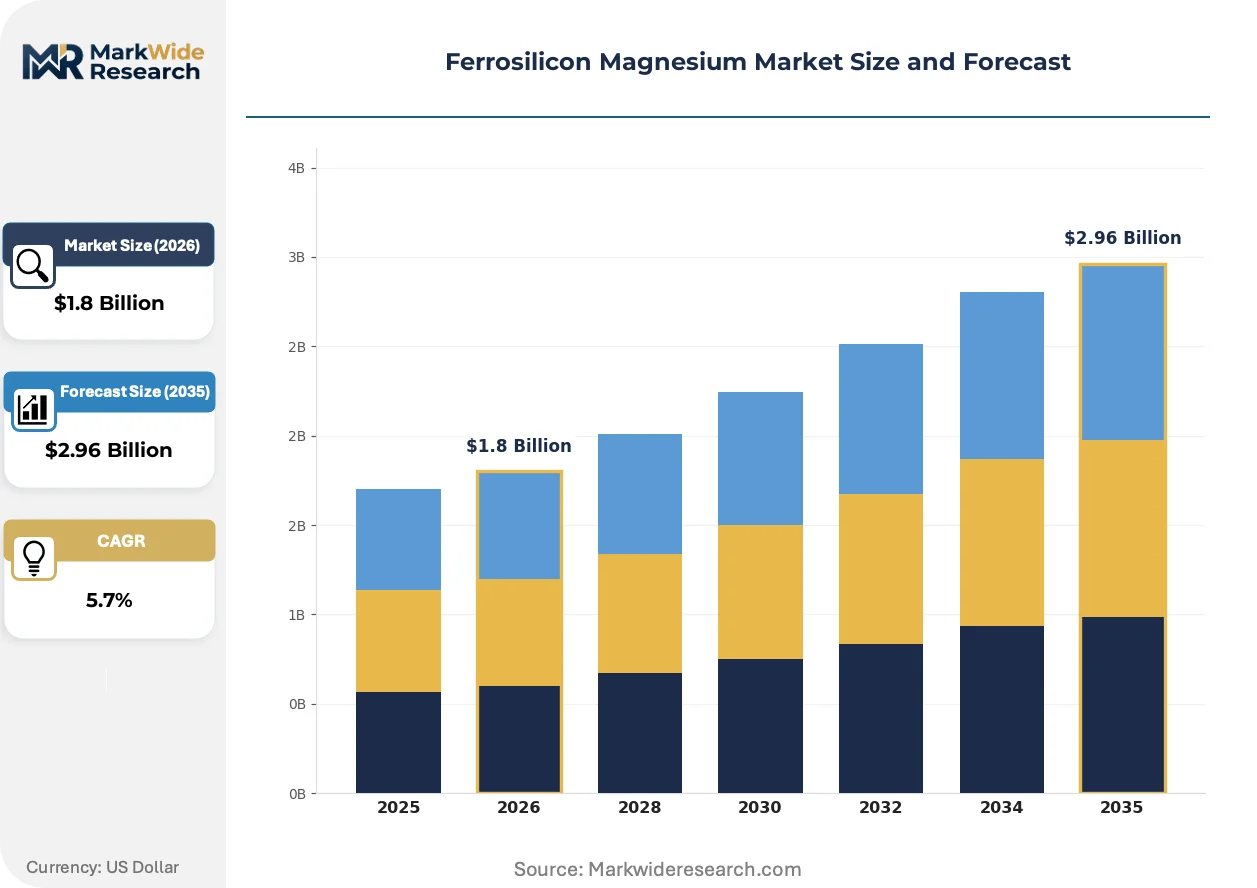
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
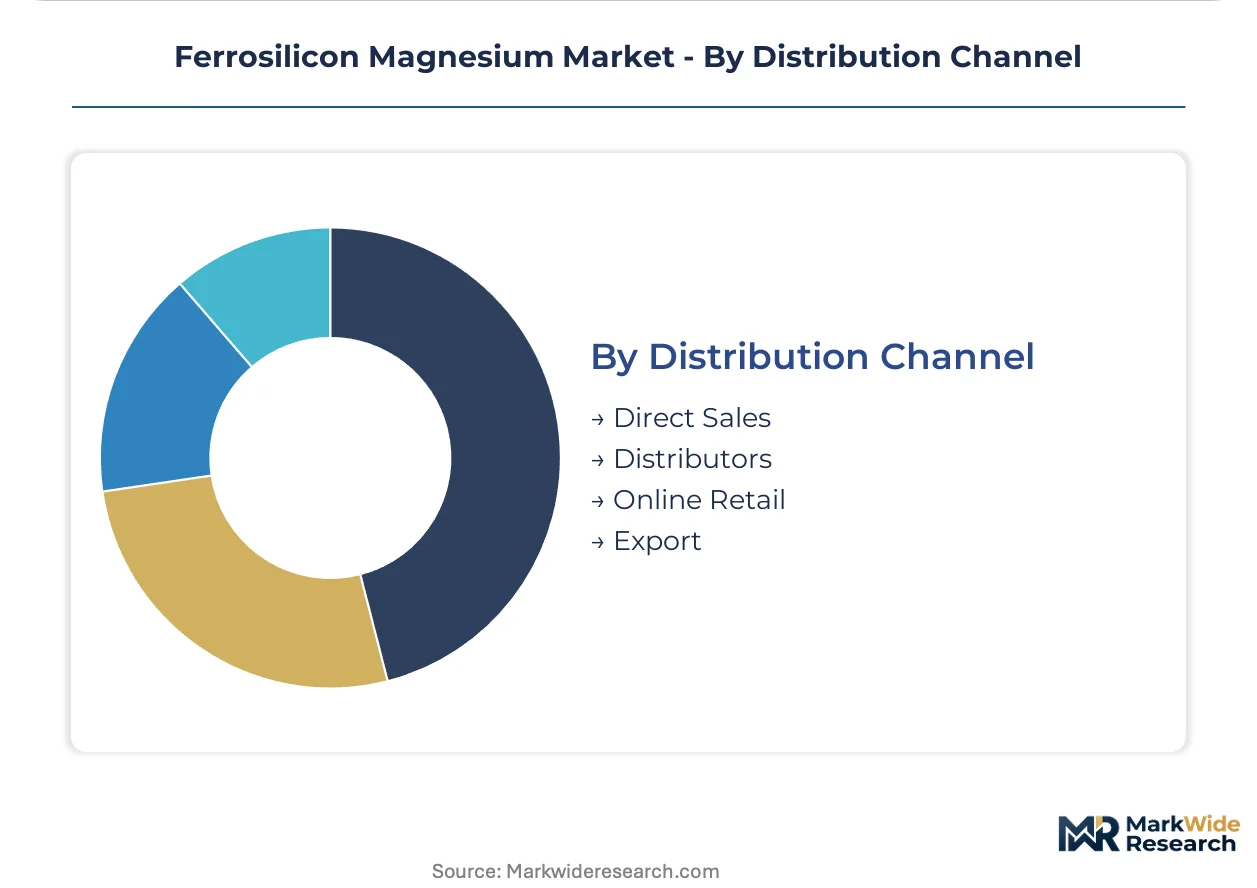
| Segmentation | Product Type: Standard Ferrosilicon, Nodular Ferrosilicon, Calcium Ferrosilicon, Aluminum Ferrosilicon Application: Steel Production, Foundry, Chemical Manufacturing, Automotive Components End User: Metal Fabricators, Foundries, Automotive OEMs, Construction Industry Distribution Channel: Direct Sales, Distributors, Online Retail, Export |
| Companies Covered | All Minmetal International, Henan Hexing, FerroGlobe, Ferro Alloys Corporation, Eshtehard Alloys, Elkem ASA, Hickman Williams & Co, Prithvi Group, M & M Alloys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferrosilicon Magnesium Market Evolving Landscape
Active process intensification and regulatory specification tightening are compressing batch-to-batch variability tolerances while expanding alloy customization requirements across end-use verticals.
Cored wire embedding technology is miniaturizing treatment station footprints while improving magnesium recovery precision. Tier-1 automotive foundries in Germany and Japan are retrofitting ladle systems with 13mm and 16mm cored wire injectors to achieve ±0.02% magnesium variance. This technology is miniaturizing the physical infrastructure required for nodularization, enabling smaller batch operations without quality degradation.
China's MIIT GB 28666 energy consumption limits are disqualifying smaller ferroalloy furnaces below 25 MVA from operating licenses. The regulation compresses supply-side fragmentation by forcing technical upgrades or exit among subscale producers. Merchant alloy importers into Europe face elevated compliance documentation burdens under parallel REACH registration timelines.
Direct mill procurement contracts are displacing distributor-mediated spot purchases among volume automotive foundries. Tier-1 suppliers in India's western industrial corridor now negotiate annual nodular ferrosilicon offtake agreements with Elkem and FerroGlobe, bypassing traditional alloy traders. This concentration is visible across Gujarat and Maharashtra foundry clusters feeding Maruti Suzuki and Tata Motors supply chains.
Ferrosilicon Magnesium Market Segmentation
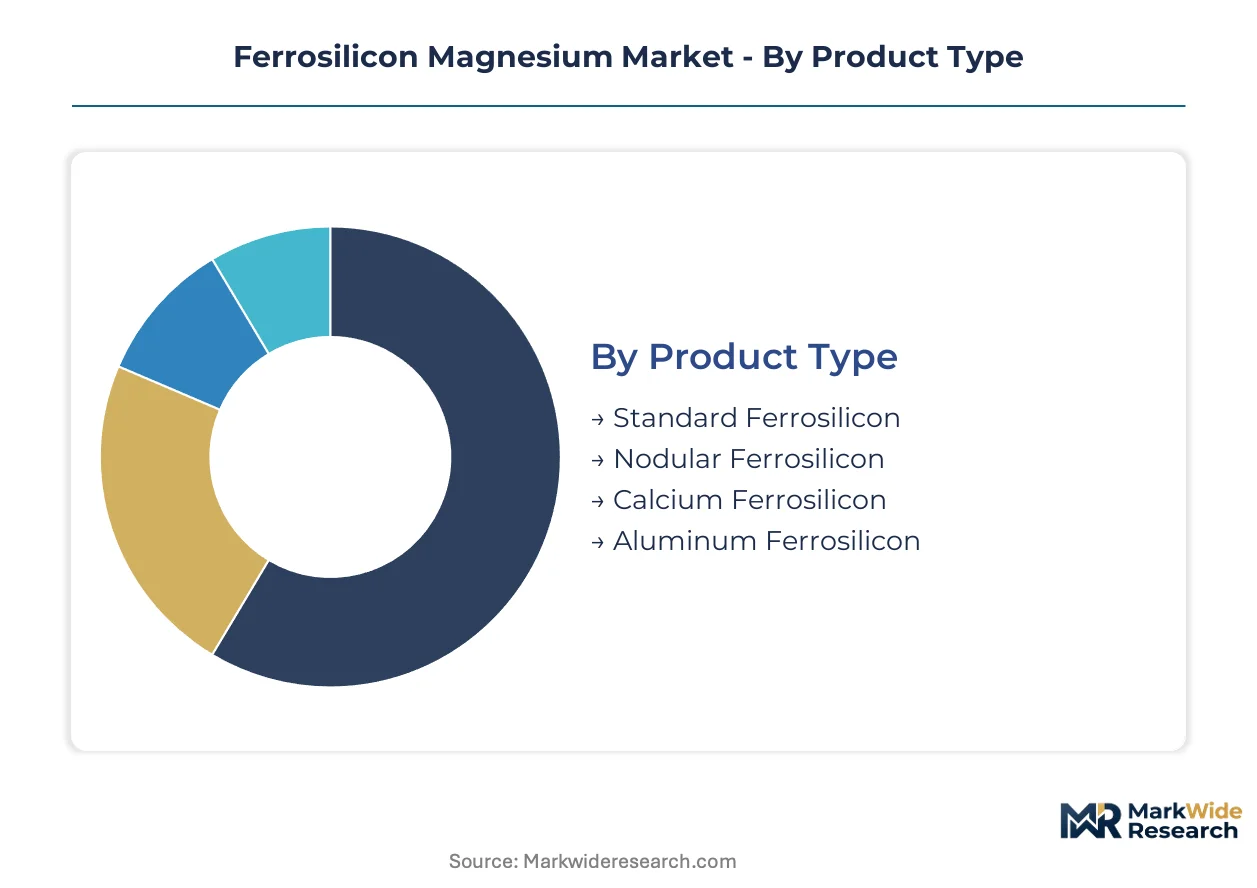
Channel configuration in ferrosilicon magnesium supply varies sharply by segment maturity. Direct mill procurement dominates high-volume nodular grades, while distributor networks retain relevance for spot purchases and smaller foundry accounts.
Product Type:
Nodular ferrosilicon flows predominantly through direct sales channels to tier-1 automotive foundries, while standard grades circulate via distributor networks serving fragmented metal fabricators.
- Nodular Ferrosilicon:Contains 3-10% magnesium with 44-48% silicon content, engineered for spheroidal graphite formation in ductile iron. Demand concentrates in Germany and Japan where tier-1 automotive foundries specify ±0.02% magnesium variance for crankshaft and suspension node applications. Wind turbine hub manufacturers in Denmark and Spain source exclusively through annual offtake agreements.
- Standard Ferrosilicon:Baseline iron-silicon alloy without magnesium addition, used primarily for steel deoxidation. Procurement in India's Gujarat and Maharashtra foundry clusters feeds Maruti Suzuki and Tata Motors supply chains under BIS IS 1559 certification requirements.
- Calcium Ferrosilicon:Calcium-bearing variant for desulfurization applications in ladle metallurgy.
- Aluminum Ferrosilicon:Aluminum-modified grade for specialized steel alloying where residual aluminum control matters.
Nodular ferrosilicon dominates installed base. Standard ferrosilicon is where expansion concentrates in emerging foundry economies.
Application:
Cost tier stratification separates premium specification grades from commodity alloy flows, with automotive and wind energy commanding price premiums over steel production.
- Automotive Components:Ductile iron crankshafts, suspension nodes, and powertrain castings where OEM lightweighting mandates displace forged steel. Electric vehicle chassis systems in Germany and Japan drive specification tightening for unsprung mass reduction.
- Steel Production:Deoxidation and alloying in integrated steel mills, primarily standard ferrosilicon grades. China's Henan province steel clusters anchor volume consumption through proximity to coking coal and ferroalloy production.
- Foundry:General-purpose casting operations across tier-2 and tier-3 metal fabricators.
- Chemical Manufacturing:Niche applications in silicon-based chemical synthesis.
Steel production anchors volume throughput. Automotive components are climbing the fastest on specification premiums.
End User:
Customer type determines contract structure, with automotive OEMs demanding multi-year supply agreements while construction industry buyers transact on spot markets.
- Automotive OEMs:Direct procurement of nodular ferrosilicon for captive foundry operations and tier-1 supplier networks. India's western industrial corridor foundries in Gujarat and Maharashtra localize supply chains under the PLI scheme for specialty steel.
- Foundries:Independent casting operations serving diversified industrial demand across construction, agriculture, and general machinery.
- Metal Fabricators:Secondary steel processors and job shops with fragmented, price-sensitive purchasing patterns.
- Construction Industry:Infrastructure and building material applications with cyclical demand profiles.
Foundries dominate installed base. Automotive OEMs are gaining share fastest on vertical integration trends.
Distribution Channel:
Geography shapes channel viability, with direct sales penetrating mature markets while export channels serve Southeast Asian underpenetrated foundry bases.
- Direct Sales:Annual offtake agreements between integrated producers and volume automotive foundries. Elkem and FerroGlobe bypass traditional alloy traders in European and Indian markets, compressing distributor margins.
- Distributors:Regional stockists serving spot market demand from smaller foundries and metal fabricators with irregular consumption patterns.
- Export:Cross-border shipments to Vietnam and Indonesia where domestic nodular alloy production remains absent.
- Online Retail:Emerging platform-based procurement for standardized grades in fragmented buyer segments.
Direct sales dominate value capture. Export channels are where expansion concentrates for integrated producers seeking geographic diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes ferrosilicon magnesium primarily for steel deoxidation in integrated mill complexes, while India and Germany deploy the alloy almost exclusively for automotive nodularization, creating divergent specification demands across geographies.
China
Henan province steel clusters anchor volume consumption through proximity to coking coal and ferroalloy production infrastructure. MIIT enforces GB 28666 energy consumption limits that disqualify furnaces below 25 MVA, consolidating supply among compliant smelters. The Yangtze River Delta and Shandong Peninsula foundry bases are upgrading to cored wire systems for precision magnesium recovery.
India
Automotive OEM procurement for ductile iron crankshafts and EV chassis components is accelerating in Gujarat and Maharashtra foundry clusters. BIS mandates IS 1559 chemical uniformity testing with 90-120 day approval windows for imported nodular grades. The PLI scheme for specialty steel is localizing supply chains feeding Maruti Suzuki and Tata Motors operations.
Germany
Tier-1 automotive foundries specify ±0.02% magnesium variance for powertrain castings in electric vehicle platforms. REACH registration requirements compel full substance toxicity disclosure from alloy importers, elevating compliance costs for non-European suppliers. The Ruhr industrial corridor and Bavarian automotive belt concentrate demand among precision casting operations.
United States
Wind turbine hub manufacturers in the Great Plains region source nodular ferrosilicon through annual offtake agreements for 8MW+ turbine castings. EPA emissions standards and OSHA workplace exposure limits shape furnace operation protocols. The Midwest foundry belt spanning Ohio, Michigan, and Indiana feeds automotive and agricultural equipment supply chains.
Norway
Captive quartzite mines and hydroelectric power infrastructure sustain cost leadership in European nodular grade production. ECHA REACH compliance documentation burdens favor domestic suppliers over merchant alloy importers. The Mo i Rana industrial region concentrates submerged arc furnace capacity serving Nordic and Continental European demand.
Ferrosilicon Magnesium Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in ferrosilicon magnesium supply, with captive raw material access and energy infrastructure separating cost leaders from price-takers. Merchant producers without quartzite mine ownership or dedicated power arrangements face persistent margin compression. Two strategic archetypes dominate: Nordic-integrated smelters with hydroelectric advantage and Chinese provincial champions with coking coal proximity. Competitive moves center on backward integration into quartzite mining and multi-continent furnace placement to hedge energy cost volatility.
Among integrated Nordic producers, Elkem ASA exemplifies the captive-resource archetype through Norwegian hydroelectric and quartzite integration. FerroGlobe occupies a position spanning furnace operations across Spain, South Africa, and the United States, representing geographic diversification strategy. Henan Hexing anchors volume positioning within China's Henan province, sitting within the provincial champion tier with proximity to steel mill demand clusters.
| Leading Market Players |
|---|
| All Minmetal International |
| Henan Hexing |
| FerroGlobe |
| Ferro Alloys Corporation |
| Eshtehard Alloys |
| Elkem ASA |
| Hickman Williams & Co |
| Prithvi Group |
| M & M Alloys |
| Others |
Value Network & Pricing Analysis
Ductile iron substitution for forged steel in electric vehicle chassis systems simultaneously redraws procurement geography toward India's western industrial corridor and compresses margin tolerance among merchant alloy producers lacking captive quartzite access. This substitution dynamic concentrates pricing power with integrated smelters while fragmenting spot market liquidity.
Pricing Analysis
Long-term offtake agreements between tier-1 automotive foundries and integrated producers now dominate nodular grade procurement, displacing distributor-mediated spot purchases. Three-tier pricing structure across premium, standard, and economy levels separates specification-tightened automotive grades from steel mill deoxidation alloys. Cost compression in standard grades is intensifying because China's MIIT GB 28666 enforcement is consolidating supply among compliant smelters. Metal fabricators and tier-3 foundries exhibit highest price sensitivity, while wind turbine OEMs accept premium positioning for 8MW+ hub specifications.
Supply Chain Analysis
Quartzite deposit concentration in Norway, South Africa, and China's Henan province creates raw material chokepoints that tether non-integrated producers to volatile input costs. Submerged arc furnace operations draw from premium silica, metallurgical-grade magnesium, and coking coal feedstocks. Single-source vulnerability runs through Norway's hydroelectric-dependent smelters exposed to European natural gas price spillovers. Distribution runs through direct mill procurement channels in mature markets and export channels serving Vietnam and Indonesia's underpenetrated foundry bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ferrosilicon magnesium supply is fragmenting into specification-differentiated tiers as automotive OEMs impose ±0.02% magnesium variance requirements that smaller foundries cannot meet, creating service and technology niches between volume leaders and commodity merchants.
For Market Incumbents: Shield margin position by deepening backward integration into captive quartzite mining and securing multi-year power purchase agreements with Nordic hydroelectric utilities. The priority threat is cored wire embedding technology convergence that favors precision metallurgy capabilities over scale. Incumbents should accelerate ladle automation partnerships with tier-1 automotive foundries to lock in specification premiums before merchant competitors achieve comparable magnesium recovery rates. For New Entrants and Emerging Players: Technical apprenticeship gaps in submerged arc furnace operation represent a service-layer gap where incumbents under-serve mid-tier foundries needing operational support. Southeast Asian import substitution in Vietnam and Indonesia offers the most penetrable geography, with cored wire embedding system retrofits providing a differentiated go-to-market angle against conventional ladle injection suppliers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated resource owners over merchant traders. Long-term viability across the projection horizon rests on captive energy infrastructure and quartzite reserve access. Acquisition targets should display Nordic or Chinese provincial positioning with compliant furnace scale above 25 MVA. The signal to watch is BIS certification timeline compression in India, which would accelerate import substitution and reward early compliant capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartzite Mining | Captive silica supply secures cost leadership against Norwegian and South African deposit holders. |
| Cored Wire Embedding Technology Deployment | Precision magnesium recovery above 92% meets tier-1 automotive foundry specifications in Germany and Japan. |
| Long-term Supply Agreement with Wind OEMs | Annual offtake contracts for 8MW+ turbine hubs reduce spot market exposure and stabilize furnace utilization. |
| Capacity Expansion in India's Western Corridor | Gujarat and Maharashtra proximity feeds Maruti Suzuki and Tata Motors supply chains under PLI localization. |
| Green Manufacturing Transition | Hydroelectric-powered smelting aligns with EU Green Deal and REACH compliance requirements for European market access. |
Research Methodology
The analysis maps nodular ferrosilicon, standard ferrosilicon, calcium ferrosilicon, and aluminum-modified grades, each validated through submerged arc furnace operators, automotive foundry procurement directors, wind turbine OEM metallurgists, and alloy distribution channel managers. Primary interviews with these stakeholders combined with secondary validation from customs trade data, MIIT GB standard filings, BIS IS 1559 certification records, and ECHA REACH registration disclosures. Bottom-up capacity modeling and top-down demand triangulation from automotive production and wind installation forecasts ensured cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled magnesium content tiers, end-use verticals, distribution channel configurations, and regional production hub clusters. CAGRs were derived from segment-level demand elasticity analysis and furnace capacity utilization trajectories. Key inputs included electric vehicle platform rollout schedules and wind turbine hub casting specifications.
Underlying assumptions cover MIIT enforcement continuity, BIS certification timeline stability, and REACH registration cost trajectories, with deviation risk concentrated in energy price volatility and quartzite export restriction policies. Practitioners should keep alternative scenarios live as China's dual carbon goal implementation pace and India's PLI scheme expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Copper Powder Market
Metals
Expanded Metal Foils Market
Metals
Ultrafine Tungsten Wire for Medical Applications Market
Metals
Titanium Sponge Market
Metals
Platinum Market
Metals
Stainless Steel Sheet Market
Metals
Global Flat Steel Market
Metals
Global Galvanized Steel Wire Market
Metals
GCC Metal Forging Market
Metals
Steel Drums and Ibcs Market
Metals
Barium Market
Metals
Global Electrolytic Copper Foil Market
Metals
Global Brazing Consumable Market
Metals
Aluminum Welding Wires Market
Metals
Reconditioned Steel Drums Market
Metals
Steel Casting Market