
 Coolant Filtration Systems Market | 2026-2036
Coolant Filtration Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Coolant Filtration Systems Market Insights
Aerospace fabrication is expanding its share of coolant filtration procurement as titanium and nickel-alloy machining intensifies. Mayfran International leverages its conveyor-integrated filtration architecture to dominate large-scale metalworking installations. Barnes International sustains a broad geographic footprint across North American machine shop networks. PRAB specializes in magnetic and vacuum filtration systems for high-volume chip management.
Coolant filtration systems remove particulate matter, tramp oil, and biological contaminants from metalworking fluids through mechanical separation, magnetic extraction, or membrane-based processes, typically achieving particle retention down to 10-25 microns depending on filter media configuration. These systems extend fluid life, reduce disposal costs, and maintain dimensional tolerances in precision machining operations. Vacuum filtration occupies the largest installed base across OEM workshops due to its continuous operation and minimal operator intervention. Crossflow filtration is gaining traction among contract manufacturers processing aerospace superalloys where fine particulate loads challenge conventional media. Magnetic filters lead replacement demand in heavy roughing operations at tooling centers generating high ferrous chip volumes.
EPA effluent limitation guidelines govern discharge of metalworking fluids into municipal wastewater systems, compelling machine shops toward zero-liquid-discharge configurations. REACH restrictions on boron and formaldehyde-releasing biocides are reformulating coolant chemistry and accelerating filtration system upgrades across European precision engineering firms. OSHA metalworking fluid standards mandate exposure controls that filtration systems help achieve through tramp oil removal and microbial suppression. Stakeholders must evaluate filtration technology roadmaps against evolving chemical compliance thresholds rather than treating equipment procurement as a standalone capital decision.
Market Dynamics
Closed-loop coolant architectures are displacing open-sump configurations across precision manufacturing, driven by EPA effluent guidelines and REACH chemical restrictions that mandate zero-liquid-discharge compliance and biocide-free fluid formulations.
Growth Catalysts
- EPA Effluent Limitation Guidelines:US machine shops face discharge restrictions into municipal wastewater systems, compelling capital deployment toward vacuum and membrane filtration configurations that enable water reuse.
- Aerospace superalloy machining:Titanium and nickel-alloy fabrication generates fine particulate loads that overwhelm conventional media, pulling demand toward crossflow filtration systems capable of sub-10-micron retention.
- Germany's precision manufacturing belt:Stuttgart and Aachen tooling centers concentrate procurement of advanced magnetic and vacuum systems for automotive powertrain operations.
Market Restraints
- Stainless steel and rare-earth magnet costs:Input price volatility for filter housings and magnetic drum assemblies compresses margin structures for system integrators serving mid-tier machine shops.
- European supply concentration:Advanced membrane media production clusters in Germany and Switzerland, creating sourcing vulnerability for North American OEMs seeking crossflow configurations.
- Tramp oil separation limits:Conventional coalescer technology struggles with emulsified synthetic coolants, forcing premature fluid disposal despite filtration investment.
Strategic Opportunities
- India's precision engineering corridor:Bangalore and Pune contract manufacturers remain underpenetrated by closed-loop systems, presenting first-mover advantage for vacuum filtration deployments.
- IoT-enabled condition monitoring:Sensor-integrated filtration units are converging with predictive maintenance platforms, creating subscription revenue streams beyond equipment sales.
- EU Green Deal industrial transition:Carbon border adjustment mechanisms incentivize European metalworkers to reduce fluid waste volumes through upgraded filtration infrastructure.
Industry Challenges
- Fluid chemistry requalification:REACH-mandated removal of boron and formaldehyde-releasing biocides requires machine shops to recalibrate filtration parameters for reformulated coolants.
- Retrofit integration complexity:Legacy CNC machining centers lack standardized plumbing interfaces, extending installation timelines and requiring custom engineering for closed-loop conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coolant Filtration Systems Market |
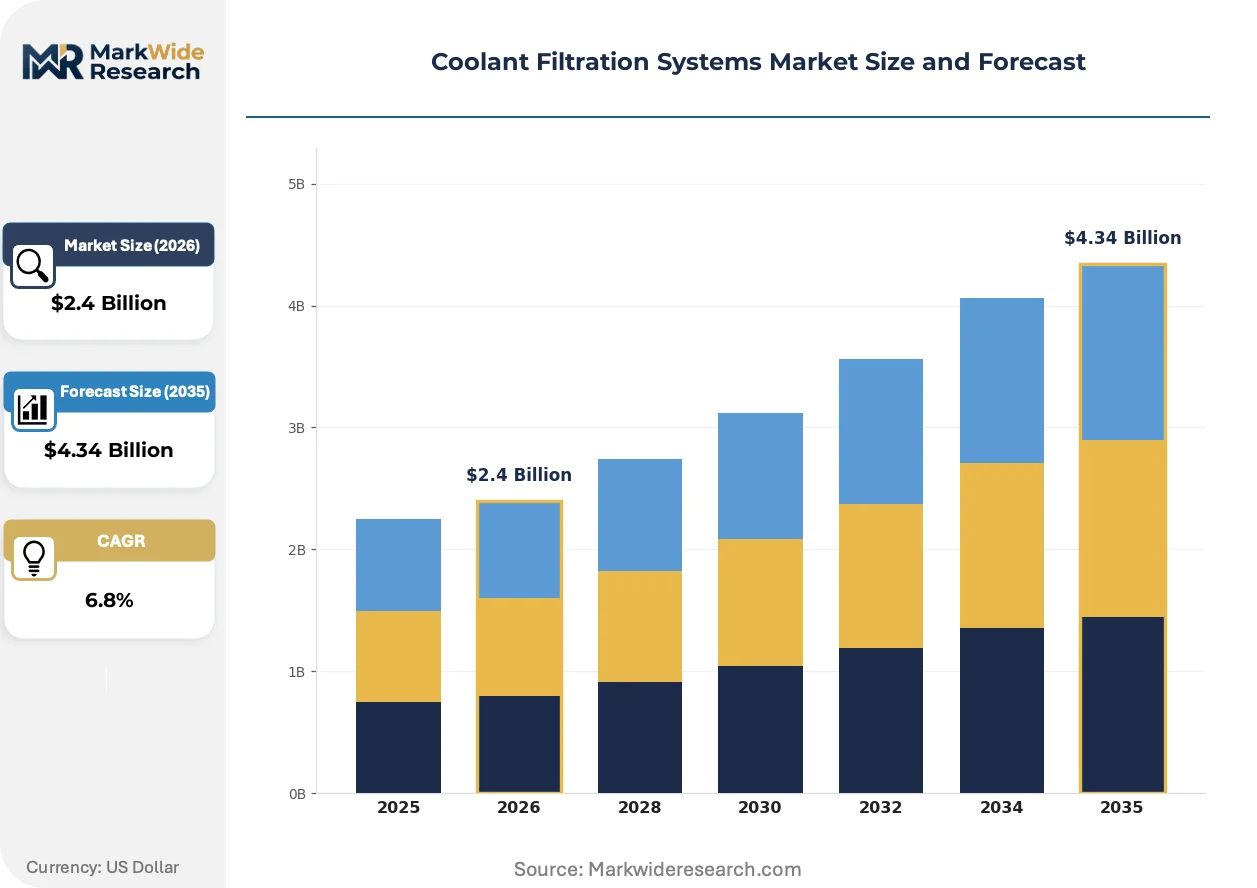
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Filters, Centrifugal Separators, Magnetic Filters, Cartridge Filters, Bag Filters Technology: Spin-on Filtration, Crossflow Filtration, Depth Filtration, Screen Filtration, Electrostatic Filtration Application: Metalworking, Electronics Manufacturing, Textile Processing, Aerospace Fabrication, Food Processing End User: Machine Shops, Precision Engineering Firms, OEM Workshops, Tooling Centers, Contract Manufacturers |
| Companies Covered | Mayfran International, Noritake, Losma, EdjeTech, MP Systems, Boll & Kirch Filterbau GmbH, Barnes International, PRAB, Oberlin Filter Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coolant Filtration Systems Market Trends and Innovations
Membrane technology and intelligent monitoring systems are restructuring competitive advantage in coolant filtration, compressing the gap between fluid maintenance and precision machining outcomes.
Crossflow ceramic membrane systems are integrating continuous backpulse cleaning with automated flux recovery, extending membrane life beyond three years in aerospace titanium machining operations. Tier-1 suppliers in Germany and Japan are adopting these configurations to maintain dimensional tolerances on nickel-alloy turbine components. The technology is integrating real-time particle counting feedback loops that trigger media replacement before tolerance drift occurs.
REACH restrictions on boron and biocide chemistries are forcing reformulation of metalworking fluids across European precision engineering firms. Machine shops must now verify filtration efficacy against microbial contamination without relying on traditional preservative additives. German automotive suppliers are responding by specifying vacuum filtration with ultraviolet sterilization modules to meet ECHA compliance thresholds.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance contracts into componentized offerings. North American machine shop networks now procure filter media, sensor modules, and technical support through separate channels rather than single-source agreements. This pattern is most visible in Michigan and Ohio automotive tooling corridors where independent service providers compete against OEM filtration specialists.
Coolant Filtration Systems Market Segmentation
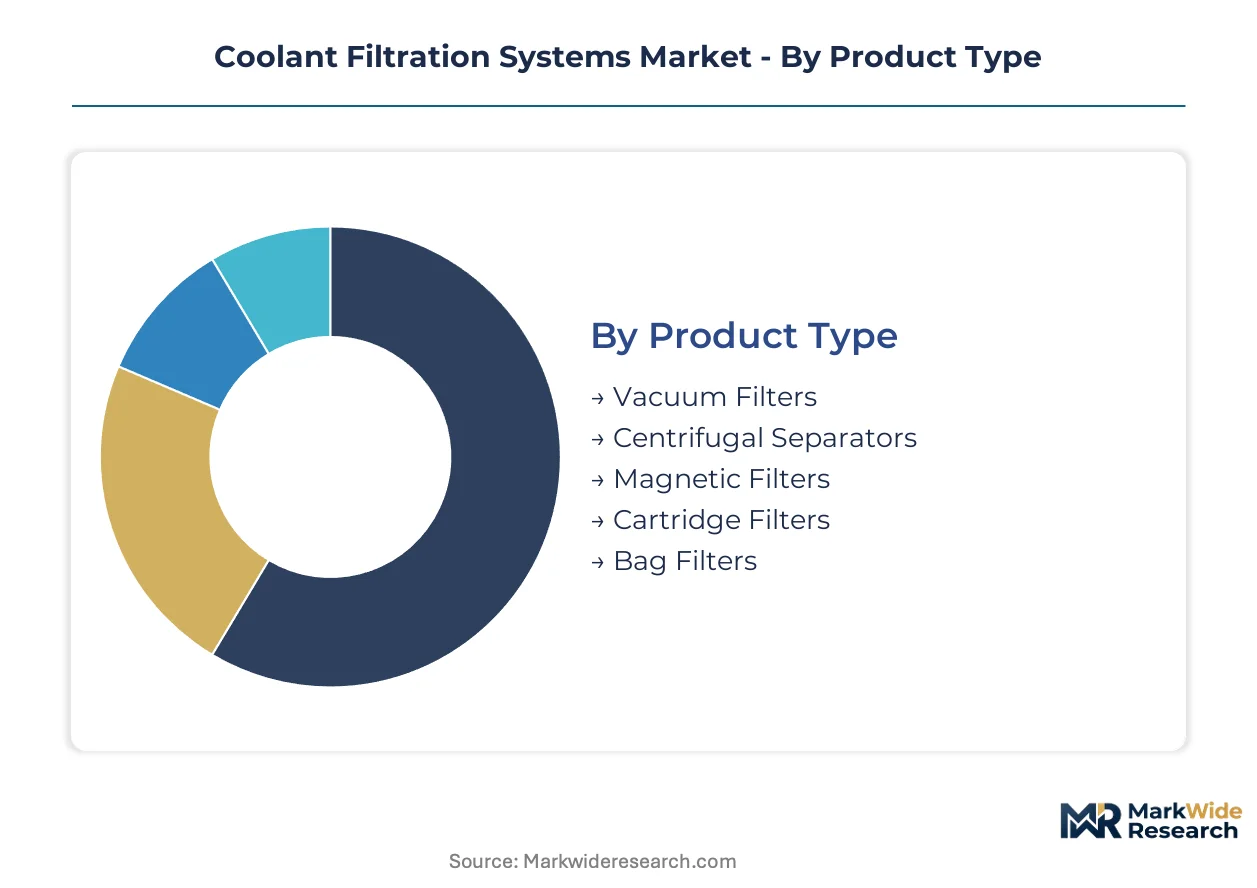
Coolant filtration procurement varies sharply by operational scale, fluid chemistry, and regulatory exposure. Buyers select configurations based on chip load characteristics, coolant formulation constraints, and discharge compliance thresholds rather than generic performance metrics.
Product Type:
Machine shops differentiate procurement by chip volume, ferrous content, and automation requirements.
- Vacuum Filters:Continuous belt-driven systems separate solids from water-based coolants through gravity-assisted vacuum suction, achieving 20-25 micron retention. OEM workshops across Germany's Stuttgart corridor deploy these for uninterrupted automotive powertrain machining.
- Magnetic Filters:Rare-earth drum assemblies extract ferrous particulate without consumable media, handling high-volume roughing operations. Tooling centers generating substantial cast iron chip loads specify these for minimal operator intervention and near-zero media costs.
- Centrifugal Separators:High-G-force spinning removes fine non-ferrous solids and tramp oil through density differentiation, suited for mixed-alloy environments.
- Cartridge Filters:Disposable pleated media provide point-of-use protection for individual CNC machines in low-volume precision engineering settings.
- Bag Filters:Simplex or duplex housings with polypropylene felt capture coarse debris in entry-level metalworking operations prioritizing capital efficiency.
Vacuum filtration leads volumes today; magnetic systems are gaining share fastest among heavy roughing specialists.
Technology:
Retention precision and membrane durability separate premium deployments from standard configurations.
- Crossflow Filtration:Tangential flow across ceramic or polymeric membranes maintains flux rates through continuous scouring action, achieving sub-10-micron retention. Aerospace fabrication of titanium and nickel-alloys in Japan and Germany drives specification for superalloy machining where fine particulate loads overwhelm conventional media.
- Spin-on Filtration:Threaded canister designs integrate pump, motor, and filter element in compact footprints for individual machine retrofit. North American machine shop networks favor these for legacy CNC upgrades where plumbing modifications face space constraints.
- Depth Filtration:Graded-density media trap particles throughout matrix thickness rather than surface alone, extending service intervals in high-load grinding applications.
- Screen Filtration:Wedge-wire or mesh elements provide coarse pre-filtration protecting downstream fine media from abrasive wear in heavy stock removal.
- Electrostatic Filtration:Charged collection surfaces attract sub-micron particles and colloidal contaminants without pressure drop, addressing synthetic coolant emulsion stability challenges.
Spin-on configurations dominate installed base; crossflow systems are expanding most quickly among aerospace contract manufacturers.
Application:
Fluid chemistry and contamination profiles dictate filtration architecture selection across verticals.
- Metalworking:Water-soluble and straight-oil coolants carrying metallic fines, tramp oil, and biological contamination require multi-stage separation. EPA effluent guidelines and REACH chemical restrictions are accelerating closed-loop system deployment across US and European precision manufacturing.
- Aerospace Fabrication:Titanium and nickel-alloy machining generates fine, abrasive particulate that compromises dimensional tolerances. Crossflow ceramic membrane systems with automated backpulse cleaning extend fluid life beyond three years in turbine component operations.
- Electronics Manufacturing:Deionized water and semi-aqueous cleaning fluids demand particulate and ionic contamination control for circuit board fabrication.
- Textile Processing:Synthetic fiber lubricants and sizing agents require oil-water separation and suspended solids removal in continuous filament operations.
- Food Processing:Vegetable oil filtration for frying applications and washdown compliance separates this segment through sanitary design requirements.
Metalworking anchors current demand; aerospace fabrication is climbing the fastest as superalloy machining intensifies.
End User:
Capital intensity and technical staffing determine system complexity tolerance across buyer types.
- OEM Workshops:Captive machining operations at automotive and aerospace manufacturers specify centralized vacuum filtration with automated chip handling. These facilities prioritize uptime guarantees and integration with production scheduling systems over unit capital cost.
- Contract Manufacturers:Job shops serving multiple industries face variable coolant chemistries and batch-size fluctuations. IoT-enabled condition monitoring with subscription-based maintenance contracts is penetrating this segment fastest as equipment financing flexibility outweighs ownership preferences.
- Machine Shops:Independent operators with limited technical staff favor plug-and-play spin-on or bag filter configurations minimizing maintenance complexity.
- Precision Engineering Firms:High-mix, low-volume producers of medical and optical components specify point-of-use cartridge protection for tight tolerance assurance.
- Tooling Centers:Cutting tool manufacturers generating concentrated ferrous chip streams leverage magnetic filtration for media-free operation.
OEM workshops lead capital deployment; contract manufacturers are expanding filtration investment most rapidly through service-based procurement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating coolant filtration procurement toward jurisdictions where REACH compliance costs and EPA enforcement intensity create divergent operating economics. Germany and the United States currently absorb premium-system deployment, while India's precision engineering corridor offers arbitrage opportunities for standardized vacuum configurations.
United States
Automotive powertrain machining across Michigan and Ohio drives vacuum filtration deployment for continuous automotive production. EPA effluent limitation guidelines compel zero-liquid-discharge retrofits across Great Lakes machine shop networks. Detroit-area tooling centers concentrate procurement of conveyor-integrated systems for high-volume cast iron processing.
Germany
Stuttgart and Aachen precision manufacturing clusters specify crossflow ceramic membranes for nickel-alloy turbine component machining. REACH restrictions on boron and formaldehyde-releasing biocides mandate ultraviolet sterilization modules in automotive supplier workshops. Bavarian medical device fabricators deploy point-of-use cartridge protection for tight tolerance assurance.
Japan
Aerospace superalloy machining in Nagoya and Tokyo industrial corridors pulls demand toward automated backpulse cleaning systems. METI industrial efficiency standards incentivize fluid life extension through membrane-based closed-loop architectures. Chubu region contract manufacturers are integrating IoT-enabled condition monitoring for predictive maintenance contracts.
India
Bangalore and Pune contract manufacturers remain underpenetrated by closed-loop systems, presenting first-mover deployment opportunities for vacuum filtration. Central Pollution Control Board wastewater discharge norms are tightening across Maharashtra and Karnataka precision engineering zones. Gujarat machine tool builders are sourcing magnetic filtration for cast iron roughing operations serving domestic automotive OEMs.
China
Yangtze River Delta machine tool manufacturers face MEE environmental compliance deadlines for metalworking fluid discharge. Shanghai and Suzhou precision machining parks are retrofitting legacy CNC centers with spin-on filtration for legacy equipment compatibility. Dual carbon goals are accelerating closed-loop coolant adoption among state-owned automotive component suppliers.
Coolant Filtration Systems Market Competitive Landscape
Technology licensing dominates the current landscape as membrane specialists partner with established metalworking equipment OEMs. The vendor base clusters around three strategic archetypes: conveyor-integrated system builders, magnetic filtration specialists, and membrane technology licensors. Consolidation pressure is mounting among mid-tier bag and cartridge filter suppliers facing input cost volatility. Geographic expansion and portfolio diversification represent the two dominant competitive vectors as European players seek North American machine shop networks and vacuum specialists add crossflow capabilities.
Within the conveyor-integrated tier, Mayfran International and Barnes International occupy positions exemplifying large-scale metalworking installation architecture. Magnetic and vacuum filtration specialists include PRAB, which sits within the high-volume chip management archetype serving heavy roughing operations. Among precision membrane providers, Noritake and Losma represent ceramic and polymeric media expertise respectively, with Boll & Kirch Filterbau GmbH anchoring German-engineered pressure filtration systems for industrial fluid processing.
| Leading Market Players |
|---|
| Mayfran International |
| Noritake |
| Losma |
| EdjeTech |
| MP Systems |
| Boll & Kirch Filterbau GmbH |
| Barnes International |
| PRAB |
| Oberlin Filter Company |
| Others |
Pricing and Supply Chain Analysis
OEM workshops in Germany's Stuttgart automotive corridor anchor procurement volumes and enforce three-tier pricing stratification across premium crossflow membranes, standard vacuum configurations, and economy bag-filter alternatives. Their specification power compresses distributor margins while rewarding direct-channel relationships with certified system integrators.
Pricing Analysis
Distributor markups of 18-22 percentage points separate authorized channel pricing from direct-to-OEM contract rates, with volume scale and REACH certification tier driving the steepest price differentiation. Pricing pressure stems from stainless steel and rare-earth magnet cost volatility eroding integrator margins on magnetic drum assemblies. Contract manufacturers in India's precision engineering corridor exhibit highest price sensitivity due to limited technical staffing and financing constraints, whereas Japanese aerospace fabricators prioritize sub-10-micron retention performance over unit economics.
Supply Chain Analysis
Filter media refurbishment and magnetic drum remanufacturing flows create reverse-logistics revenue streams for German and Swiss membrane specialists serving European precision engineering firms. Ceramic membrane production concentrates in Germany and Japan, drawing from rare-earth oxide deposits and precision-machined stainless steel housings sourced from domestic metalworking clusters. Single-source vulnerability in advanced polymeric membrane feedstock exposes North American OEMs to transatlantic logistics chokepoints. Distribution runs through authorized system integrators with captive installation and aftermarket service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coolant filtration has matured into a late-cycle quality story as aerospace superalloy machining specifications displace commodity bag-filter procurement across precision manufacturing. Buyers now specify fluid life extension and dimensional tolerance assurance as primary selection criteria rather than capital cost minimization.
For Market Incumbents: Extend crossflow membrane service life guarantees beyond three years through automated backpulse cleaning integration, defending against emerging IoT-native entrants offering predictive maintenance subscriptions. Backward integration into rare-earth magnet recycling secures input cost stability for magnetic filtration specialists facing commodity volatility. Certification investment in EPA zero-liquid-discharge validation and REACH biocide-free compliance creates switching costs for captive OEM relationships. For New Entrants and Emerging Players: Capture Bangalore and Pune contract manufacturers through vacuum filtration deployments with equipment-financing structures that convert capital expenditure into operational expenditure. India's precision engineering corridor remains underpenetrated by closed-loop architectures due to legacy open-sump infrastructure. A sensor-integrated condition monitoring go-to-market angle bypasses incumbent maintenance-contract lock-in. For Investors and Strategic Acquirers: Metalworking equipment OEMs are the most active acquirers in this space, seeking filtration technology to bundle with machining center sales and capture aftermarket service revenue. Long-term viability hinges on membrane durability differentiation and regulatory compliance automation rather than commodity hardware scale. Watch for EPA effluent guideline enforcement intensity and REACH chemical restriction expansion as inflection signals for upgrade-cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Crossflow ceramic specialists partner with conveyor-integrated system builders to access aerospace superalloy machining specifications in Germany and Japan. |
| IoT-Enabled Condition Monitoring | Sensor-integrated filtration units converge with predictive maintenance platforms, creating subscription revenue streams beyond equipment sales for contract manufacturers. |
| REACH Compliance Certification | Ultraviolet sterilization module integration enables European automotive suppliers to meet ECHA biocide-free thresholds without reformulation risk. |
| Geographic Expansion into India | Vacuum filtration first-mover deployments in Bangalore and Pune exploit tightening Central Pollution Control Board discharge norms across Maharashtra and Karnataka. |
| After-Sales Service Unbundling | Componentized procurement of filter media, sensor modules, and technical support fragments traditional equipment-plus-maintenance contracts in Michigan and Ohio automotive corridors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with plant engineers, OEM procurement teams, aftermarket service heads, and filtration system integrators with secondary validation against EPA effluent limitation guidelines, ECHA REACH substance restrictions, customs trade data for filter media imports, and SEC filings from metalworking equipment OEMs. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from production capacity and replacement cycle analysis.
Comparable-period anchoring linked projection assumptions to historical reference periods across the analysis window, with segmentation dimensions spanning product type, retention technology, application vertical, and end-user capital intensity. CAGRs derived from regression analysis of installed base growth, replacement demand patterns, and regulatory compliance upgrade cycles. Industry-specific forecast inputs incorporated aerospace superalloy machining intensity indices and automotive powertrain production schedules.
Regulatory enforcement variance, raw material cost volatility, and membrane technology substitution rates are the dominant revision risks to projection assumptions. Practitioners should monitor EPA guideline implementation timelines, rare-earth magnet price movements, and crossflow ceramic membrane durability claims for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Europe Industrial Air Filtration Market
Filters
Industrial Air Filtration Market
Filters
Global Cartridge Filters Market
Filters
Round Plate Filter Press Market
Filters
Color Filter Glass Market
Filters
North America Gas Filtration Media Market
Filters
Global Tangential Flow Filtration Market
Filters
Ceramic Filters Market
Filters
Global Lamella Clarifier Market
Filters
Global Pleated Filters Market
Filters
Filter Paper Market
Filters
Nonwoven Air Conditioning Filter Market
Filters
Global Depth Filtration Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Filter Media Market
Filters
Drum Filters Market