
 North America Iron Casting Market | 2026-2036
North America Iron Casting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Iron Casting Market Intelligence
The Occupational Safety and Health Administration's (OSHA) final rule on respirable crystalline silica is decoupling foundry viability from simple production scale, elevating the importance of capital investment in dust control. Waupaca Foundry Inc leverages its multi-plant scale to absorb these compliance costs. Grede Holdings LLC specializes in complex, high-value ductile iron components for automotive and industrial markets. Metal Technologies Inc positions itself through advanced process automation and metallurgical expertise.
Iron casting is a manufacturing process where molten iron is poured into a mold to create a solidified part of a desired shape. The process often utilizes sand-based molds and can produce components with high compressive strength and vibration damping qualities, essential for heavy machinery. Ductile iron continues to gain share over gray iron in applications requiring higher tensile strength and fatigue resistance. While the automotive end-user segment remains the largest consumer, construction applications for pipe and fittings represent a stable, high-volume base.
Foundry operations in North America are shaped by environmental and safety regulations. The US Environmental Protection Agency (EPA) enforces strict air quality standards, impacting technology choices. Concurrently, OSHA's rules on silica exposure mandate significant capital investment in dust mitigation systems for foundries. Successfully managing these compliance costs while innovating in higher-strength, lightweighted ductile iron will be critical for market share.
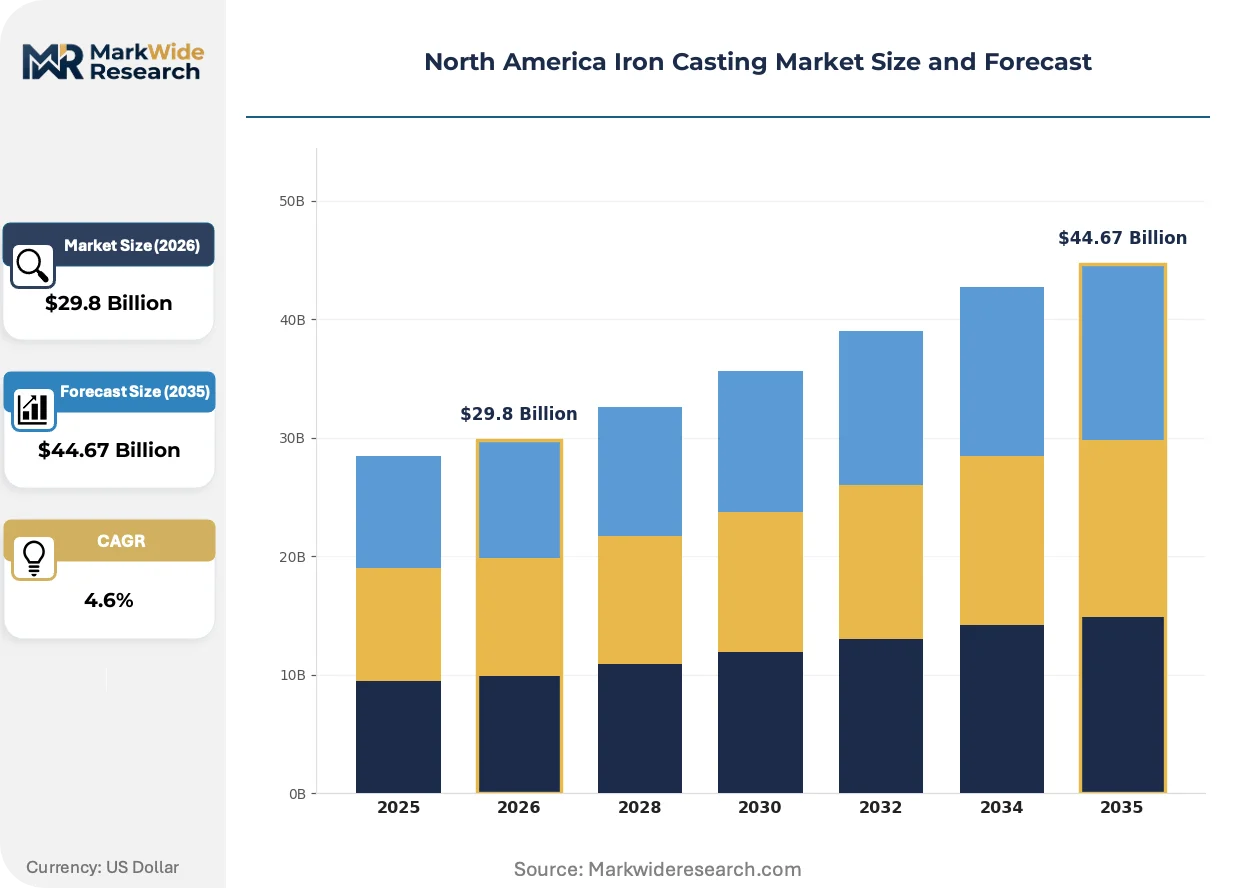
Market Dynamics
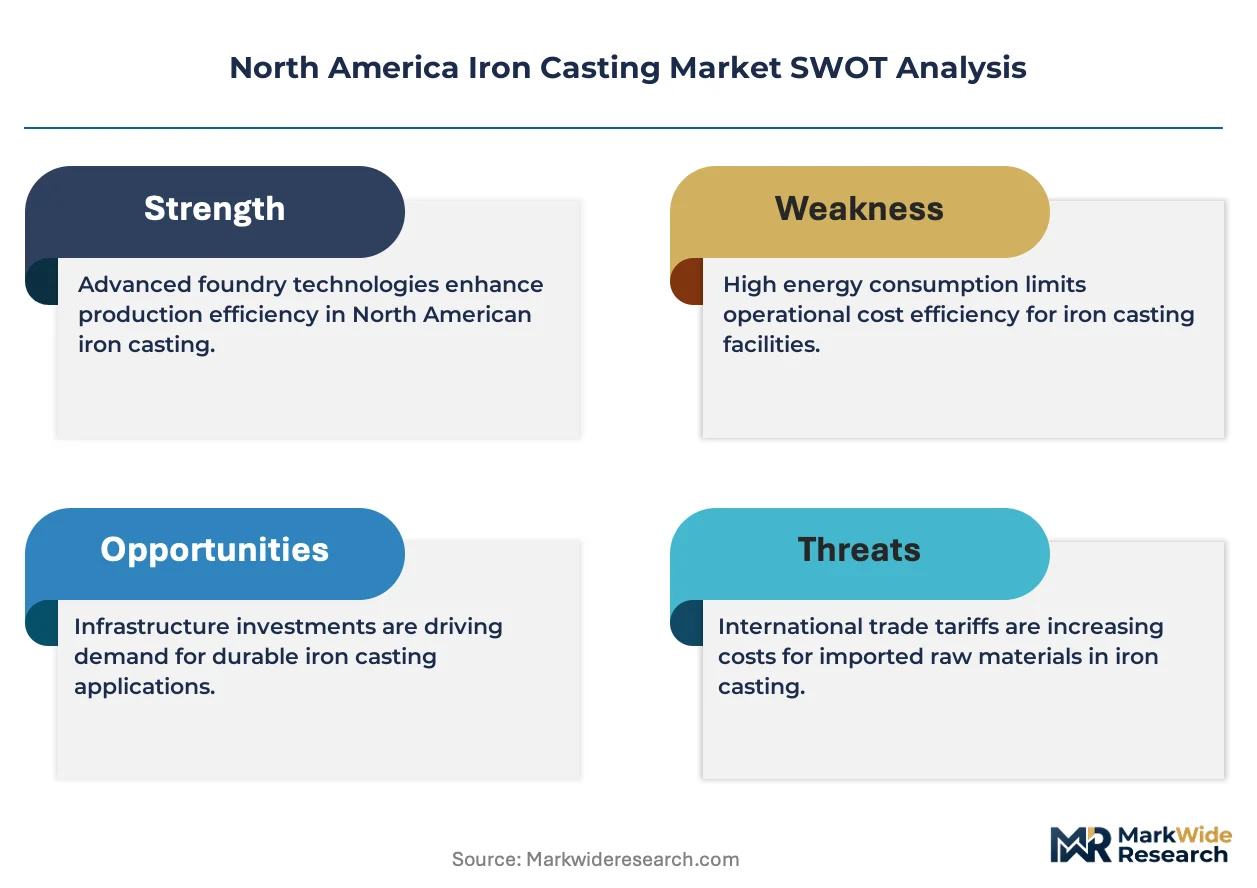
The North America iron casting market is defined by the tension between stringent environmental regulations and the automotive sector's demand for higher-performance materials. Compliance costs, especially those mandated by OSHA, are forcing consolidation and rewarding capital-intensive foundries capable of technological investment.
Growth Catalysts
- Automotive Sector Demand:The US Environmental Protection Agency's emission standards for heavy-duty vehicles require complex engine components, driving significant demand for advanced, durable cast iron parts with high heat and pressure tolerance.
- Material Superiority:Ductile iron continues to displace gray iron in high-fatigue applications due to its superior tensile strength and elongation properties, expanding its use in automotive suspensions and industrial machinery.
- Infrastructure Investment:Stable, high-volume demand for iron pipes and fittings is sustained by public and private investment in water and wastewater infrastructure renewal projects across the United States and Canada.
Market Restraints
- Raw Material Volatility:Foundry profitability is directly exposed to price fluctuations in essential inputs like scrap iron, pig iron, and metallurgical coke, making cost management a persistent structural challenge for operators.
- Substitution from Aluminum:In automotive applications where weight reduction is the primary design goal, cast iron faces a persistent substitution threat from lighter materials like cast aluminum, especially for non-structural components.
- Regulatory Capital Burden:The significant capital expenditure required to comply with OSHA's final rule on respirable crystalline silica acts as a major financial barrier, particularly for smaller, independent foundries.
Strategic Opportunities
- Lightweighting Innovation:Developing advanced, thin-walled ductile iron castings and austempered ductile iron (ADI) presents an opportunity to compete with aluminum on weight while offering superior strength and lower cost.
- Renewable Energy Components:The expanding wind energy sector offers a new market for large, complex castings, including turbine hubs, gearbox housings, and base frames, which require the strength and durability of iron.
- Supply Chain Onshoring:Foundries can capitalize on the trend of North American OEMs near-shoring their supply chains to mitigate geopolitical risks and shorten lead times, recapturing business from overseas competitors.
Industry Challenges
- Skilled Labor Scarcity:A critical shortage of skilled foundry workers, including metallurgists, patternmakers, and maintenance technicians, constrains production capacity and slows the adoption of new manufacturing technologies.
- Modernization Capital Needs:The high cost of upgrading or replacing aging foundry equipment with modern, automated systems is a significant challenge that impacts efficiency, quality, and environmental compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Iron Casting Market |
| Market Size in 2026 | $29.8 Billion |
| Market Size in 2035 | $44.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gray Iron, Ductile Iron, White Iron, Malleable Iron End User: Automotive, Construction, Machinery, Aerospace Technology: Sand Casting, Investment Casting, Die Casting, Centrifugal Casting Application: Heavy Equipment, Pipe & Fittings, Engine Components, Industrial Machinery |
| Companies Covered | Decatur Foundry Inc, OSCO Industries Inc, Waupaca Foundry Inc, Metal Technologies Inc, Grede Holdings LLC, Cadillac Casting Inc, Fusium Inc, Neenah Foundry, Calmet Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Iron Casting Market Strategic Shifts & Innovations
Material science advancements and process automation are central to foundry evolution in North America. Foundries are adapting to produce higher-strength, lighter-weight components while navigating an increasingly complex regulatory environment that dictates technology choices and investment priorities.
Austempered Ductile Iron (ADI) is a high-performance material created via a specialized heat treatment, offering an exceptional strength-to-weight ratio. Automotive manufacturers are adopting ADI for critical powertrain and chassis components to reduce vehicle mass without compromising on durability or fatigue life. This advanced material innovation is electrifying the competitive dynamic between iron castings and alternative materials like forged steel and aluminum alloys.
The US Environmental Protection Agency's (EPA) air quality standards for industrial facilities directly influence foundry operations and technology. These rules mandate investments in advanced emission control systems for melting, pouring, and sand handling processes, increasing the capital intensity of the business. Consequently, foundries in heavily industrialized regions like Ohio and Michigan are prioritizing technologies that both improve efficiency and ensure compliance.
A clear behavioral shift is occurring as original equipment manufacturers move toward more collaborative, long-term supply partnerships. Instead of purely transactional, cost-based sourcing, procurement teams in the automotive and heavy equipment sectors are prioritizing suppliers with proven metallurgical expertise and design-for-manufacturing capabilities. This trend is most visible in the development of complex, safety-critical components for next-generation vehicles.
North America Iron Casting Market Segmentation
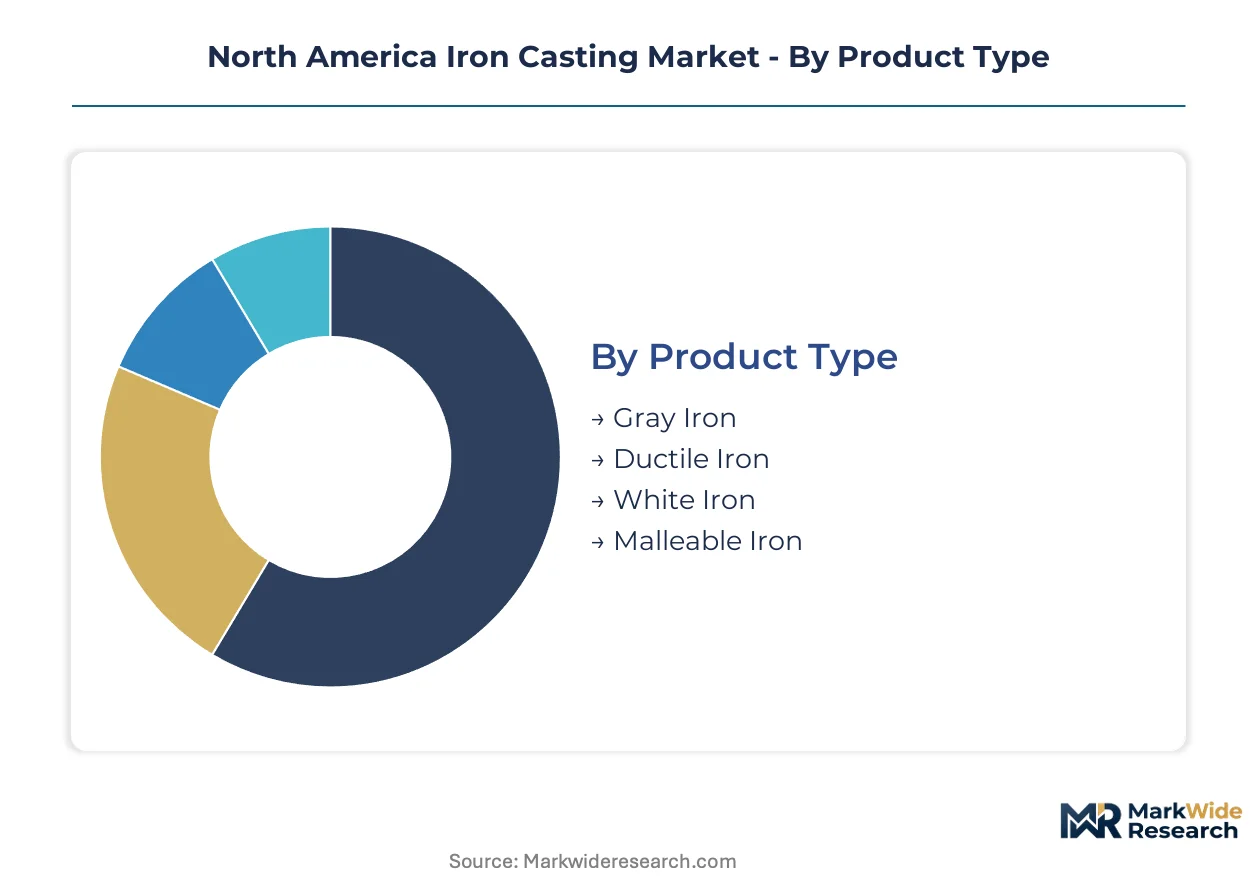
The North America iron casting market segments reflect diverse material properties, end-user requirements, and manufacturing processes. Understanding these distinct segments reveals where capital investment and technological innovation are most critical for foundries. Each segment responds differently to regulatory pressures and material performance demands.
Product Type:
The market's product type segmentation highlights the tension between high-volume, cost-effective solutions and premium, performance-driven materials.
- Ductile Iron:This material features spherical graphite nodules, providing superior tensile strength, ductility, and fatigue resistance compared to gray iron. Demand is concentrating in automotive suspensions and industrial machinery, driven by the need for enhanced durability and vibration damping qualities.
- Gray Iron:Characterized by flake graphite, gray iron offers excellent compressive strength, vibration damping, and machinability, making it cost-effective for many applications. Demand remains stable in construction applications for pipe and fittings, supported by a consistent, high-volume base in infrastructure projects across the United States.
- White Iron:This iron casting type contains carbide structures, offering extreme hardness and abrasion resistance. White iron is primarily utilized in wear-resistant applications like grinding mill liners and shot blasting nozzles.
- Malleable Iron:Produced by heat-treating white iron, malleable iron exhibits increased ductility and shock resistance. It finds specific applications in agricultural equipment, railway components, and electrical fittings requiring toughness.
Today's leader: Gray Iron. Tomorrow's challenger: Ductile Iron.
End User:
End-user segments reveal the varied applications and performance expectations driving demand for iron castings across North America.
- Automotive:This segment consumes iron castings for complex engine components, brake parts, and chassis elements, requiring high heat and pressure tolerance. Demand from heavy-duty vehicles in the US is driven by the Environmental Protection Agency's stringent emission standards, necessitating advanced, durable parts.
- Construction:The construction sector utilizes iron castings for pipes, fittings, manhole covers, and structural components within buildings and infrastructure. Demand is sustained by public and private investment in water and wastewater infrastructure renewal projects throughout the United States and Canada.
- Machinery:Industrial, agricultural, and heavy machinery sectors demand robust iron castings for frames, housings, and functional components. These applications require materials with high compressive strength and vibration damping characteristics for demanding operational environments.
- Aerospace:Specialized, high-strength iron castings are used in certain aerospace applications for specific structural or engine components where durability and thermal stability are critical.
The automotive sector continues its dominance, while infrastructure projects provide a stable base.
Technology:
This segment focuses on the manufacturing processes employed, reflecting differences in precision, volume capabilities, and tooling costs.
- Sand Casting:This widely used process involves pouring molten iron into molds made from sand, producing components with high compressive strength. Sand casting remains the most versatile and cost-effective method for large volume production across various industries due to its lower tooling costs.
- Investment Casting:Also known as lost-wax casting, this process uses ceramic shell molds to achieve high dimensional accuracy and intricate geometries. Demand for investment casting is driven by the need for complex, critical components with minimal machining requirements in specialized applications.
- Die Casting:This high-pressure casting method forces molten metal into reusable metal dies, suitable for high-volume production of smaller, uniform parts. Die casting offers excellent surface finish and dimensional consistency for specific component types.
- Centrifugal Casting:Molten iron is poured into a rapidly rotating mold, creating dense, uniform components with superior metallurgical integrity. This technology primarily produces cylindrical components like pipes, liners, and bushings.
Sand casting remains the workhorse, with investment casting offering precision for specialized needs.
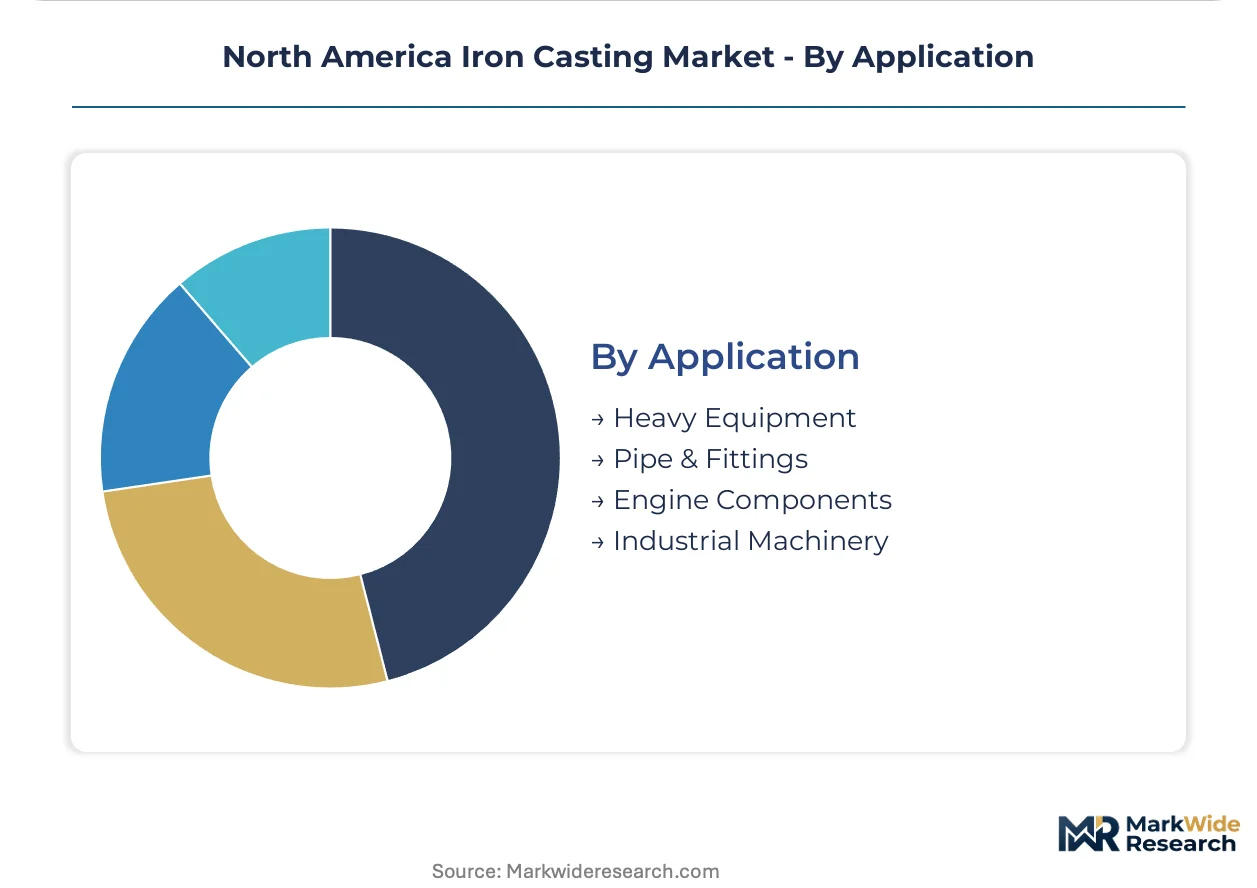
Application:
Application segmentation highlights the functional roles iron castings fulfill across various industries, emphasizing performance requirements.
- Engine Components:This segment includes cylinder blocks, cylinder heads, crankshafts, and exhaust manifolds, requiring high heat and pressure tolerance. Demand from heavy-duty vehicles is driven by stringent US Environmental Protection Agency emission standards, necessitating durable and high-performance cast iron parts.
- Pipe & Fittings:Iron castings are essential for water and wastewater pipelines, drainage systems, and municipal infrastructure. This application represents a stable, high-volume market sustained by ongoing public and private investment in infrastructure renewal across North America.
- Heavy Equipment:Cast iron parts are crucial for construction equipment, agricultural machinery, and mining vehicles, providing structural integrity and wear resistance. These applications demand robust, high-strength castings capable of withstanding harsh operating conditions.
- Industrial Machinery:This segment encompasses castings used in manufacturing, processing, and power generation equipment, including machine frames, gearboxes, and pump housings. These components require high compressive strength and vibration damping qualities for reliable operation.
Demand for engine components reflects regulatory pressures, while infrastructure needs stabilize pipe and fittings applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America iron casting industry historically scaled in the US Midwest, particularly in states like Ohio and Michigan, forming a foundational supply chain for industrial and automotive sectors. These regions developed expertise in producing durable components for heavy machinery and vehicles. Early foundries established critical production capabilities, supporting the continent's industrial growth.
United States
United States demand for iron castings is significantly driven by the automotive sector's need for complex engine components and robust infrastructure projects. The US Environmental Protection Agency (EPA) enforces stringent emission standards for heavy-duty vehicles, necessitating advanced, durable cast iron parts with high heat and pressure tolerance. Foundries in the US Midwest, especially in Ohio and Michigan, are central to the supply chain for these critical components, focusing on innovation and compliance with OSHA's silica rule.
Canada
Canadian iron casting demand benefits from stable infrastructure investment in water and wastewater projects, alongside requirements from its industrial machinery sector for heavy equipment parts. Health Canada's occupational safety regulations, including those for respirable crystalline silica exposure, influence foundry operations and capital investment across the provinces. Ontario's manufacturing corridor, particularly around Windsor and Toronto, supports automotive and industrial casting production, adapting to evolving material specifications.
Mexico
Mexico's iron casting market is propelled by its expanding automotive manufacturing base, which requires durable components for both domestic assembly and export. The Secretariat of Environment and Natural Resources (SEMARNAT) sets environmental standards for industrial facilities, impacting foundry technology choices and investment in emission control systems. The Bajío region, including states like Guanajuato and Querétaro, has emerged as a significant hub for automotive component casting, attracting foreign direct investment.
North America Iron Casting Market Key Industry Players
The competitive structure tilts toward capital-intensive foundries capable of significant technological investment, driven by stringent environmental and safety regulations. Consolidation is forcing smaller, independent foundries to either invest heavily or exit the market, favoring larger players. Strategic archetypes include multi-plant scale operators, specialized high-value component producers, and those leveraging advanced process automation. Dominant competitive moves involve substantial capital expenditure in dust mitigation systems and continuous innovation in higher-strength, lightweighted ductile iron.
Specialists in complex, high-value ductile iron components include Grede Holdings LLC, which focuses on automotive and industrial markets, providing critical parts requiring superior tensile strength. Waupaca Foundry Inc exemplifies the multi-plant scale archetype, leveraging its extensive operations to absorb significant compliance costs associated with new environmental and safety regulations. Metal Technologies Inc positions itself through advanced process automation and metallurgical expertise, catering to diverse industrial requirements with precision castings. These companies collectively navigate regulatory pressures while driving material science advancements in the North America iron casting market.
| Leading Market Players |
|---|
| Decatur Foundry Inc |
| OSCO Industries Inc |
| Waupaca Foundry Inc |
| Metal Technologies Inc |
| Grede Holdings LLC |
| Cadillac Casting Inc |
| Fusium Inc |
| Neenah Foundry |
| Calmet Inc |
| Others |
Cost & Logistics Intelligence
Captive supply arrangements anchor pricing power for large automotive OEMs, as in-house foundry capabilities secure consistent material flow and cost control. This integration strategy mitigates raw material volatility and strengthens supply positions for critical engine components.
Pricing Analysis
Bundled service models, combining casting with machining and finishing, command premium pricing in the North America iron casting market. Pricing stratifies across premium, standard, and economy tiers based on metallurgical complexity and certification level for critical automotive parts. Cost compression in standard gray iron castings stems from intense competition among regional foundries. Automotive OEMs are generally less price-sensitive for high-performance ductile iron components, while construction sector buyers prioritize cost-effectiveness for pipe and fittings.
Supply Chain Analysis
Domestic-content mandates, particularly within the US automotive sector, reshape sourcing patterns for iron castings across North America. The supply base concentrates in the US Midwest, Ontario, and Mexico's Bajío region, drawing from essential inputs like scrap iron, pig iron, and metallurgical coke. Raw material volatility presents a persistent structural risk, impacting foundry profitability. Distribution runs through direct sales channels to OEMs and industrial buyers, complemented by regional distributors for smaller volume orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America iron casting market presents a margin-expansion story, driven by the premiumization of high-strength ductile iron components. Innovation in lightweighting and advanced materials enables foundries to capture higher value in automotive and industrial applications.
For Market Incumbents: Deepen capital investment in advanced dust mitigation systems to comply with OSHA's silica rule, consolidating market share against smaller foundries. Expand R&D into Austempered Ductile Iron (ADI) to counter substitution from aluminum in lightweighting applications. Strategic partnerships with automotive OEMs for complex engine components will secure long-term demand. This vertical integration secures demand against material substitution threats.
For New Entrants and Emerging Players: Capture opportunities in renewable energy components, targeting wind turbine hubs and gearbox housings. Focus on specialized, high-value investment casting for niche aerospace applications requiring intricate geometries. The construction sector, particularly for pipe and fittings in infrastructure renewal projects, offers a stable, penetrable segment. A go-to-market angle emphasizing rapid prototyping and metallurgical customization can differentiate offerings.
For Investors and Strategic Acquirers: Roll-up economics work for multi-plant foundry operators because stringent regulatory compliance costs favor scale and capital intensity. The long-term viability for iron casting remains strong over the next 5-10 years, particularly with sustained infrastructure investment and automotive demand. Acquisition targets should be mid-sized foundries specializing in ductile iron or advanced process automation. A critical signal to watch is the pace of skilled labor development, indicating future production capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capital Investment in Dust Mitigation | Compliance with OSHA's silica rule ensures operational continuity and reinforces market leadership for large foundries. |
| Austempered Ductile Iron (ADI) Development | This material science advancement allows iron castings to compete with aluminum in automotive lightweighting applications. |
| Supply Chain Onshoring Initiatives | North American OEMs benefit from reduced lead times and mitigated geopolitical risks for critical components. |
| Skilled Workforce Development Programs | Addressing the scarcity of metallurgists and patternmakers supports production capacity and technological adoption. |
| Advanced Process Automation Adoption | Modern automated systems enhance efficiency, improve casting quality, and ensure environmental compliance for foundries. |
Research Approach
Multiple input streams — primary interviews, proprietary databases, and industry reports — were reconciled for a robust market perspective. Field interviews with foundry owners, metallurgists, and automotive procurement leads provided granular insights. Secondary validation drew from US EPA publications, OSHA compliance documents, and automotive production statistics. Bottom-up data collection and top-down market sizing ensured comprehensive triangulation.
Data-stream reconciliation formed the analytical framework across the analysis window, integrating volume and value outputs. Market segmentation dimensions modeled included product type, end-user, technology, application, and regional regulatory impact. Compound Annual Growth Rates were derived from historical trends and projected demand forecasts. US Environmental Protection Agency emission standards for heavy-duty vehicles served as a key forecast input.
Raw material volatility, regulatory shifts, and technological advancements are the dominant revision risks for market forecasts. These projections reflect current assumptions regarding economic conditions and industry dynamics. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Copper and Copper Alloy Foil Market
Metals
Aluminium Rolled Products Market
Metals
Global Hot Rolled Coil Steel Market
Metals
Metal Recycling Market
Metals
Medium Carbon Steel Market
Metals
Electrolytic Iron Market
Metals
Medical Metal Tubing Market
Metals
Global Electrolytic Copper Foil Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
Finished Steel Products Market
Metals
Steel Casting Market
Metals
Europe Aluminium Wire Rod Market
Metals
Rubidium Market
Metals
Aluminum Scrap Recycling Market
Metals
Steel Ingots Market