
 Refined Nickel Market | 2026-2036
Refined Nickel Market Size, Share, and Industry Trends Forecast 2026-2036
Refined Nickel Market Outlook
Battery-grade nickel is bifurcating the refined nickel landscape as cathode specifications tighten above 99.9% purity thresholds. Norilsk Nickel leverages its Siberian mining complex to sustain high-grade electrolytic output for European battery supply chains. Vale anchors its position through integrated laterite-to-matte operations in New Caledonia and Indonesia. Jinchuan Group dominates domestic Chinese supply while extending capacity into cobalt-nickel intermediates for ternary precursor makers.
Refined nickel denotes metal purified to minimum 99.8% Ni content through electrolytic refining or carbonyl vapor metallurgy, with battery-grade material exceeding 99.95% to minimize cobalt and copper impurities in lithium-ion cathodes. Electrolytic nickel leads volume output due to entrenched stainless steel demand, while carbonyl nickel commands premium pricing in electronics and aerospace superalloys where particle morphology controls sintering performance. Battery production represents the fastest-growing application segment as nickel-intensive chemistries displace cobalt in NMC 811 and NCA formulations.
Indonesia's Ministry of Energy and Mineral Resources enforces downstream beneficiation rules requiring in-country refining of nickel ore exports, while China's MEE implements dual carbon targets that cap energy intensity at smelters. The EU's proposed Critical Raw Materials Act classifies refined nickel as a strategic dependency, triggering stockpile obligations and domestic processing incentives. Stakeholders must monitor how Indonesia's export duty escalations and Europe's carbon border adjustments reshape arbitrage flows between Asian refining hubs and Atlantic basin consumers.
Market Dynamics
Battery-grade purity mandates are splitting the refined nickel value chain, forcing stainless steel producers to compete for electrolytic output against cathode material makers while Indonesia's downstream mandates lock ore supply within national borders.
Growth Catalysts
- Indonesia's downstream beneficiation rules:The Ministry of Energy and Mineral Resources requires in-country refining, converting raw ore exports into captive matte and MHP feedstock for integrated HPAL operations.
- High-purity cathode specifications:Battery manufacturers now reject nickel below 99.95% purity, redirecting smelter investment toward carbonyl and advanced electrolytic circuits capable of cobalt and copper exclusion.
- HPAL-to-refinery integration:Pressure acid leach plants in Morowali Industrial Park are co-locating with electrowinning facilities, collapsing transport costs and intermediate handling losses.
Market Restraints
- Laterite ore energy intensity:RKEF smelting consumes 40-50 MWh per tonne of nickel contained, exposing producers to power price volatility and carbon border adjustment liabilities.
- Sulfide deposit depletion:High-grade concentrates from Russian and Canadian underground mines face declining head grades, tightening feedstock for traditional electrolytic refineries.
- Intermediate product substitution:Battery makers increasingly source nickel sulfate directly from HPAL operators, bypassing refined metal conversion and compressing demand for LME-deliverable cathode.
Strategic Opportunities
- EU Critical Raw Materials Act stockpiles:The strategic dependency classification triggers member state obligations to hold 90 days of refined nickel consumption, creating guaranteed offtake for Atlantic basin producers.
- Aerospace superalloy particle demand:Carbonyl nickel's controlled morphology enables single-crystal turbine blade casting, with jet engine OEMs seeking long-term supply contracts outside Chinese processing.
- Scrap closed-loop refining:End-of-life battery black mass and stainless steel scrap are emerging as alternative feedstocks for hydrometallurgical circuits in Europe and North America.
Industry Challenges
- Hydrometallurgical engineering scarcity:HPAL design and commissioning expertise concentrates among a handful of engineering firms, delaying project timelines and inflating capital costs for new entrants.
- Dual carbon compliance verification:China's MEE energy intensity caps and emerging EU carbon border adjustments require parallel certification systems, multiplying audit burdens for exporters.
- Legacy stainless steel contract renegotiation:Long-term offtake agreements signed before battery demand surges now constrain refinery flexibility to redirect output toward premium cathode markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refined Nickel Market |
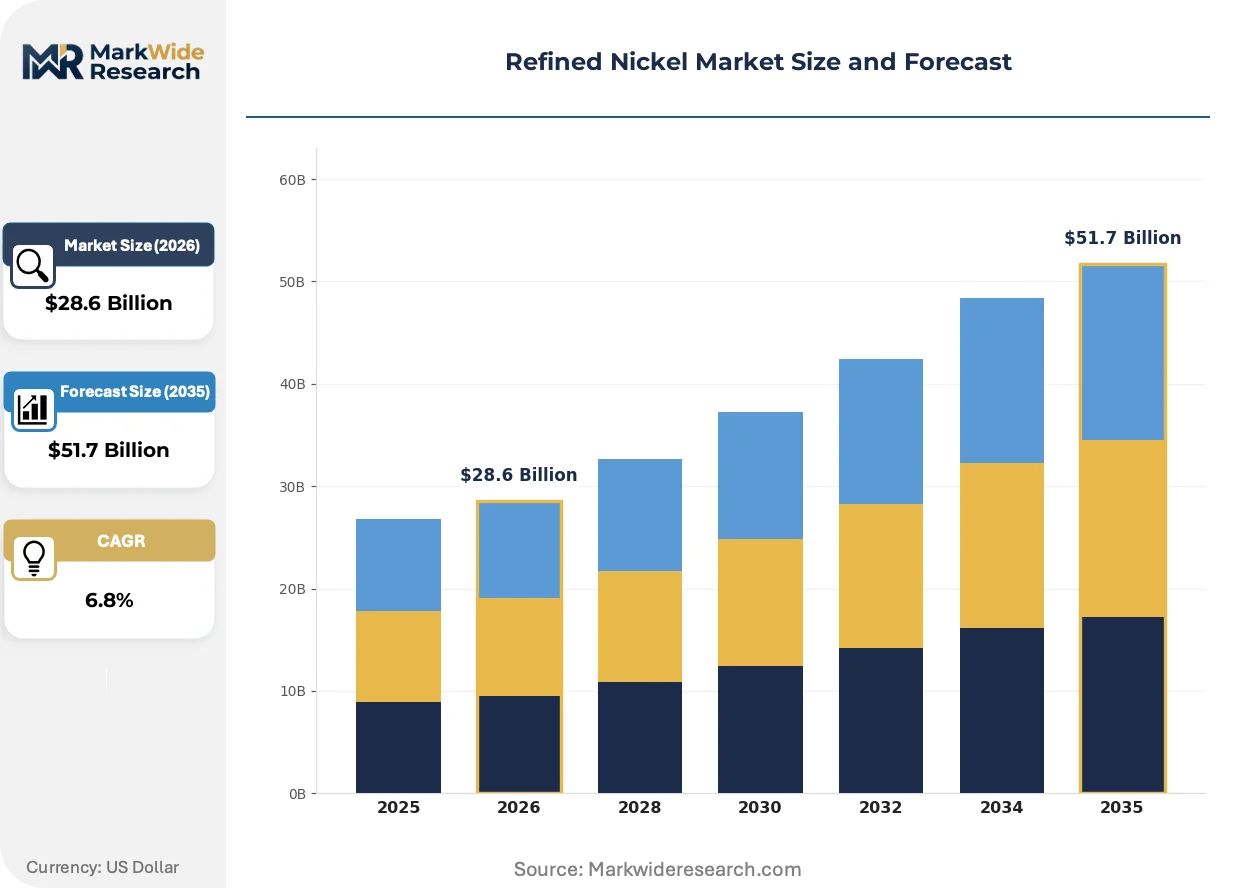
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolytic Nickel, Carbonyl Nickel, Nickel Alloy, Nickel Pigment End User: Battery Manufacturers, Stainless Steel Producers, Aerospace, Electronics Application: Battery Production, Coating, Electrical Components, Alloys Distribution Channel: Direct Sales, E-Commerce, Distributors, Wholesalers |
| Companies Covered | Jinchuan Group, Global Ferronickel, Norilsk Nickel, BHP, Vale, Zhejiang Huayou Cobalt, Nickel Asia, First Quantum Minerals, Glencore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refined Nickel Market Strategic Shifts
Refining technology is pivoting from pyrometallurgical dominance toward hydrometallurgical precision, driven by feedstock degradation and end-use purity divergence. Process innovation now centers on impurity rejection efficiency rather than volume throughput.
High-pressure acid leach (HPAL) circuits are decomposing the traditional matte-smelting-refining sequence by producing mixed hydroxide precipitate (MHP) directly from laterite ore. Battery precursor makers in South Korea and Japan are commissioning dedicated MHP offtake agreements, bypassing LME warehouse metal entirely. This direct feedstock pathway is compressing arbitrage margins for merchant refined nickel traders while locking ore-to-cathode supply relationships.
China's Ministry of Ecology and Environment (MEE) dual carbon targets now cap smelter energy intensity per tonne of nickel output, forcing RKEF operators to retrofit with waste-heat recovery or abandon production. The policy is accelerating capacity consolidation in Shandong and Jiangsu provinces while pushing investment toward Indonesian coke-fired and hydropower-backed operations. European stainless steel mills are responding by sourcing from Indonesian integrated complexes to preempt carbon border adjustment costs.
Cathode makers are consolidating procurement through direct equity stakes in upstream refining assets rather than spot market purchases. POSCO and LG Chem have acquired minority positions in Indonesian HPAL projects, securing dedicated nickel sulfate streams. This captive supply model is most visible in binding offtake structures linking Morowali Industrial Park output to South Korean precursor plants, displacing traditional merchant metal distributors from the battery supply chain.
Refined Nickel Market Segmentation
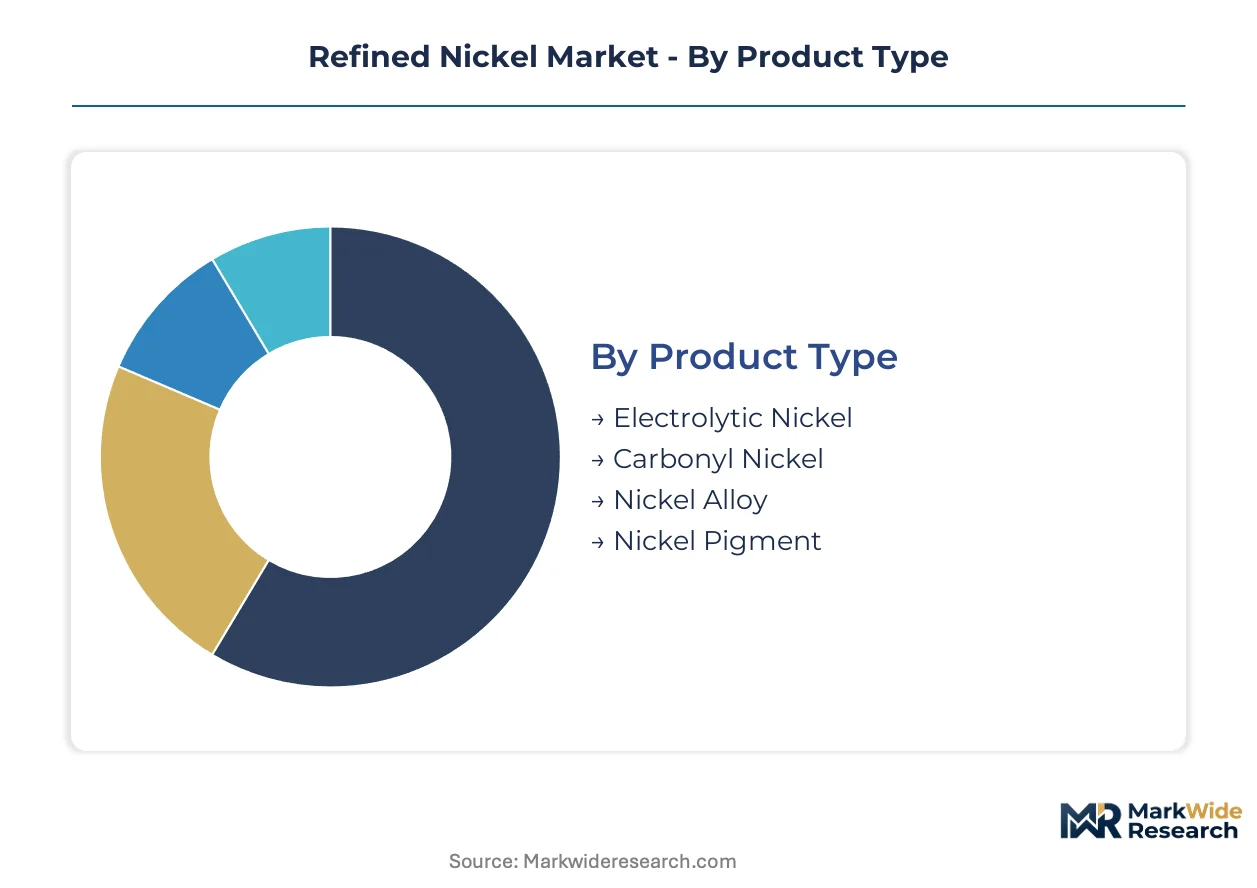
Purity thresholds and cathode specifications are fragmenting demand across product grades, while Indonesia's downstream mandates are reshaping how refined nickel reaches end-users. Segmentation reveals where battery-grade premiums override traditional stainless steel offtake.
Product Type:
Electrolytic nickel dominates domestic consumption in stainless steel hubs, while carbonyl nickel serves export-led aerospace and electronics supply chains.
- Electrolytic Nickel:Refined through electrowinning to minimum 99.8% purity, this grade sustains stainless steel mills in China and Indonesia. Demand concentrates in Shandong province where long-term contracts constrain flexibility to redirect output toward battery cathode markets.
- Carbonyl Nickel:Produced via vapor metallurgy with controlled particle morphology, this premium grade commands pricing multiples for single-crystal turbine blade casting. Procurement concentrates with jet engine OEMs seeking supply security outside Chinese processing jurisdictions.
- Nickel Alloy:Intermediate products combining refined nickel with chromium and molybdenum for corrosion-resistant applications.
- Nickel Pigment:Powdered forms for ceramic and coating applications with lower purity tolerances.
Electrolytic nickel holds the largest share; momentum sits with carbonyl nickel as aerospace OEMs diversify supply sources.
End User:
Cost tiers separate battery manufacturers paying purity premiums from stainless steel producers locked into legacy contract structures.
- Battery Manufacturers:Cathode makers now reject material below 99.95% purity, forcing direct equity stakes in Indonesian HPAL projects. Procurement concentrates through binding offtake agreements linking Morowali Industrial Park output to South Korean precursor plants.
- Stainless Steel Producers:Mills in Jiangsu and Fujian provinces consume electrolytic nickel under long-term agreements signed before battery demand surges. These contracts constrain refinery flexibility to capture premium cathode pricing.
- Aerospace:Superalloy foundries requiring carbonyl nickel with precise particle size distribution for turbine casting.
- Electronics:Connector and component manufacturers sourcing high-purity grades for corrosion resistance.
Stainless steel producers represent the largest volume base; battery manufacturers are climbing the fastest as NMC 811 chemistries displace cobalt.
Application:
Volume concentration favors mature coating and alloy segments, while customer type divergence splits procurement between spot buyers and captive supply chains.
- Battery Production:Nickel sulfate derived from HPAL mixed hydroxide precipitate now bypasses traditional refined metal conversion. Battery makers source directly from integrated complexes, compressing demand for LME-deliverable cathode.
- Coating:Electroplating applications in automotive and construction consume standard electrolytic grades through established distributor networks.
- Electrical Components:Connector manufacturers requiring high-purity nickel for conductivity and oxidation resistance.
- Alloys:Nickel-copper and nickel-chromium formulations for chemical processing equipment and marine applications.
Coating and alloys hold the largest combined share; battery production is gaining share fastest as precursor integration accelerates.
Distribution Channel:
Supply concentration dictates channel selection, with integrated producers favoring direct relationships and merchant refiners relying on distributor networks.
- Direct Sales:Integrated HPAL-to-refinery complexes in Indonesia's Morowali Industrial Park ship nickel sulfate directly to battery precursor plants. This captive supply model displaces traditional metal traders from the cathode supply chain.
- Distributors:Merchant refined nickel for stainless steel mills moves through regional distributors with warehouse operations in Rotterdam, Singapore, and Shanghai.
- E-Commerce:Limited to specialty nickel powders and small-laboratory quantities through chemical supply platforms.
- Wholesalers:Bulk electrolytic nickel for non-battery industrial applications.
Distributors hold the largest share; direct sales are expanding most quickly as battery makers consolidate upstream equity positions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
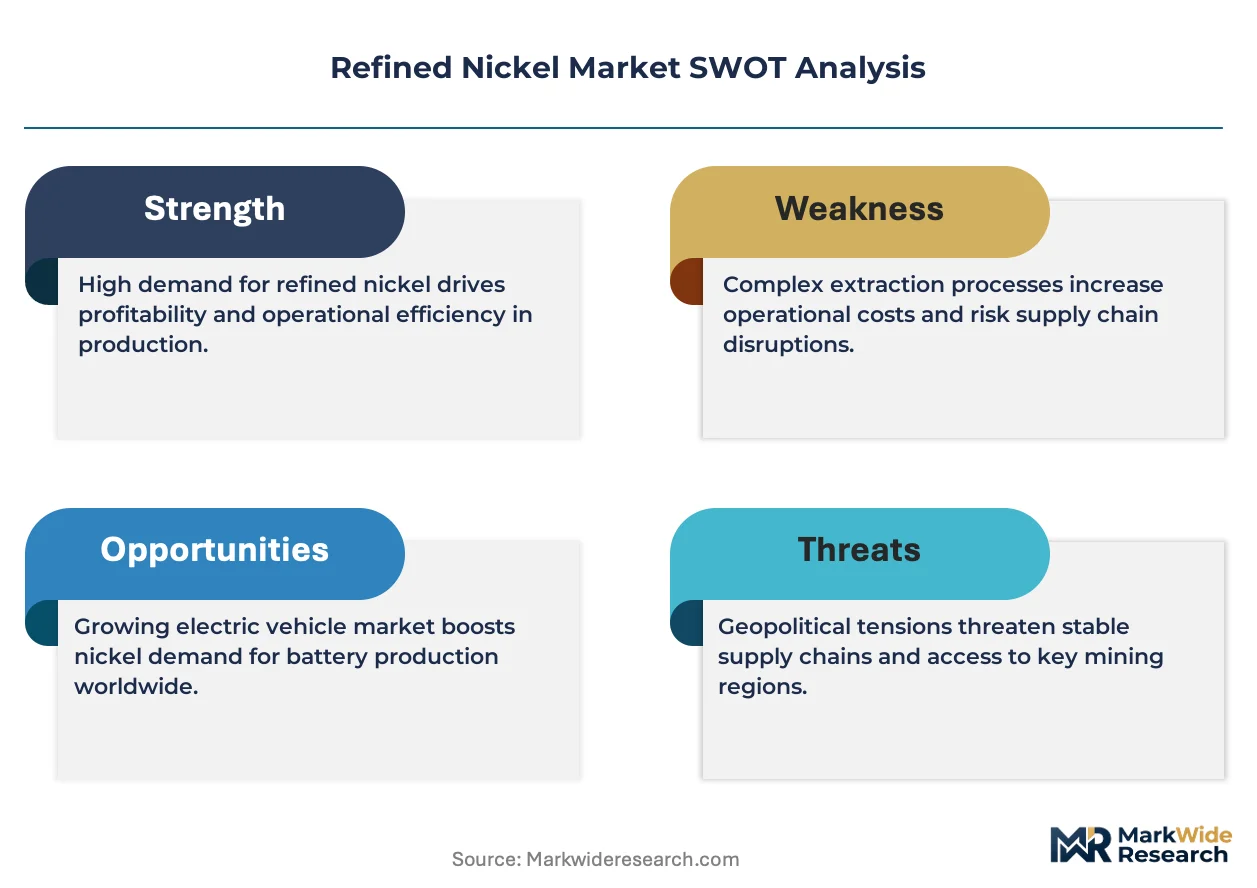
Refined nickel supply chains concentrate in jurisdictions with integrated laterite processing and low-cost energy access. Indonesia's downstream mandates have redirected investment flows from traditional sulfide refining centers toward Southeast Asian industrial parks.
Indonesia
Morowali Industrial Park hosts integrated HPAL-to-refinery complexes serving battery precursor makers. The Ministry of Energy and Mineral Resources enforces beneficiation rules requiring in-country refining of nickel ore exports. Weda Bay and Obi Island clusters are expanding carbonyl nickel capacity for aerospace superalloy applications.
China
Jinchuan Group anchors domestic electrolytic output while Shandong province stainless steel mills consume legacy contract volumes. The MEE dual carbon targets cap smelter energy intensity per tonne of nickel output. Jiangsu and Fujian provinces face capacity consolidation as producers retrofit waste-heat recovery systems or relocate to Indonesian operations.
Russia
Norilsk Nickel leverages Siberian mining complexes to sustain high-grade electrolytic output for European battery supply chains. The country's national mining regulator oversees emission standards across Arctic smelting operations. Polar division concentrators supply feedstock for carbonyl nickel production targeting turbine blade casting markets.
Canada
Sudbury Basin and Voisey's Bay deposits feed traditional electrolytic refineries facing declining head grades. Health Canada and provincial environmental agencies regulate sulfur dioxide emissions from pyrometallurgical circuits. Quebec and Ontario hydrometallurgical pilot plants are testing black mass recovery from end-of-life batteries.
Australia
First Quantum Minerals and BHP operate laterite and sulfide mines with limited domestic refining capacity. The country's national resources regulator oversees tailings management for pressure acid leach projects. Western Australia nickel sulfate plants are commissioning direct offtake agreements with South Korean cathode makers, bypassing LME metal conversion.
Refined Nickel Market Competitive Environment
Concentration sits with integrated mining-to-refining conglomerates and specialized battery material suppliers. The market structure divides between sulfide-based electrolytic producers with legacy stainless steel contracts and laterite-integrated operators capturing battery-grade premiums. Two strategic archetypes dominate: diversified miners with downstream refining assets and pure-play battery material specialists with HPAL equity stakes. Competitive moves center on upstream acquisition of Indonesian processing capacity and long-term offtake binding with precursor manufacturers.
Within the diversified mining tier, Vale and BHP exemplify integrated laterite-to-matte operators with New Caledonian and Australian upstream positions. Norilsk Nickel occupies a position as the sulfide-based electrolytic specialist serving European aerospace and battery supply chains. Jinchuan Group anchors the state-backed refinery archetype with domestic Chinese dominance and Indonesian expansion into cobalt-nickel intermediates.
| Leading Market Players |
|---|
| Jinchuan Group |
| Global Ferronickel |
| Norilsk Nickel |
| BHP |
| Vale |
| Zhejiang Huayou Cobalt |
| Nickel Asia |
| First Quantum Minerals |
| Glencore |
| Others |
Value Chain & Pricing Dynamics
Nickel sulfate from HPAL circuits displacing LME-deliverable cathode simultaneously concentrates supply geography in Indonesia's industrial parks and collapses arbitrage margins that once sustained merchant trading economics. Battery makers now capture refining premiums through direct equity stakes, while stainless steel mills absorb residual electrolytic volumes under legacy contract structures.
Pricing Analysis
Indonesia's downstream beneficiation rules dictate the pricing tier structure across the refined nickel landscape. Battery-grade material exceeding 99.95% purity commands substantial premiums over standard electrolytic grades, with differentiation driven by cobalt exclusion capability and carbon intensity certification. Cost compression in standard electrolytic tiers is intensifying because Chinese stainless steel mills face MEE energy intensity caps and carbon border adjustment exposure. Stainless steel producers locked into long-term offtake agreements exhibit highest price sensitivity, while aerospace OEMs sourcing carbonyl nickel outside Chinese jurisdictions show least sensitivity due to supply security premiums.
Supply Chain Analysis
Inventory cycles for mixed hydroxide precipitate now run shorter than traditional cathode warehouse stocks, reflecting just-in-time precursor integration. Geographic concentration centers on Indonesia, China, and Russia as primary supply nodes. Raw material flows draw from laterite ore deposits in Sulawesi and Halmahera, Siberian sulfide concentrates, and recycled black mass from European collection networks. Single-source vulnerability concentrates in HPAL engineering expertise held by a handful of commissioning firms. Distribution runs through direct sales from Morowali Industrial Park to South Korean precursor plants, bypassing Rotterdam and Singapore warehouse networks that historically served stainless steel mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among battery precursor makers with captive Indonesian equity positions, fragmenting procurement influence previously held by stainless steel conglomerates.
For Market Incumbents: Fortify position by retrofitting RKEF smelters with waste-heat recovery to meet MEE dual carbon caps, while securing long-term offtake binding with aerospace OEMs seeking non-Chinese carbonyl nickel. Threat substitution from HPAL-to-sulfate direct pathways demands upstream control over Indonesian processing capacity as the priority defensive lever. For New Entrants and Emerging Players: EU Critical Raw Materials Act stockpile certification offers a fast-track entry mechanism into Atlantic basin supply chains with guaranteed offtake volumes. White-space targets include scrap closed-loop refining in North America and carbonyl nickel capacity expansion for turbine blade casting. The most penetrable segment sits with European superalloy foundries diversifying from Russian supply. Go-to-market positioning should emphasize carbon intensity transparency and single-source traceability. For Investors and Strategic Acquirers: Capital is best deployed toward hydrometallurgical engineering specialists with proven HPAL commissioning track records and binding offtake structures with Korean precursor makers. Long-term viability over the next decade hinges on positioning upstream of battery supply chain consolidation. The acquisition target archetype combines Indonesian processing licenses with operational hydrometallurgical assets. The signal to monitor is EU carbon border adjustment implementation timing, which would reprice Indonesian coal-backed output against hydropower-integrated alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| HPAL-to-Refinery Integration | Morowali Industrial Park complexes collapse transport costs and intermediate handling losses for battery precursor supply. |
| Carbonyl Nickel Capacity Expansion | Weda Bay and Obi Island clusters target aerospace superalloy demand outside Chinese processing jurisdictions. |
| Scrap Closed-Loop Refining | Quebec and Ontario pilot plants test black mass recovery from end-of-life batteries as alternative feedstock. |
| EU Stockpile Certification | Member state obligations under the Critical Raw Materials Act create guaranteed offtake for Atlantic basin producers. |
| Dual Carbon Compliance Investment | Shandong and Jiangsu retrofit programs respond to MEE energy intensity caps and preempt carbon border costs. |
Study Parameters
Two parallel data streams informed the analysis: primary engagement with HPAL project developers, battery precursor procurement leads, stainless steel mill planners, and aerospace superalloy foundry managers; alongside secondary validation through Indonesian Ministry of Energy and Mineral Resources filings, Chinese MEE enforcement notices, EU Critical Raw Materials Act documentation, and LME warehouse stock reports. Bottom-up triangulation across refinery capacity announcements and top-down reconciliation against cathode demand projections anchored volume estimates.
Across the analysis window, the forecasting framework modeled segmentation across purity grade tiers, end-use applications spanning battery production to aerospace, and regional production clusters. CAGRs were derived from supply-demand balance modeling incorporating HPAL commissioning timelines and RKEF capacity consolidation patterns. Key inputs included laterite ore grade degradation curves, energy intensity compliance costs under dual carbon targets, and precursor integration rates bypassing refined metal conversion.
Underlying assumptions cover HPAL project execution timelines and EU carbon border adjustment implementation scope, with deviation risk concentrated in Indonesian export duty escalations and engineering firm capacity constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Titanium Mill Products Market
Metals
Osmium Market
Metals
North America Aluminium Powder Market
Metals
Reconditioned Steel Drums Market
Metals
Galvanizing Market
Metals
Galvanized Steel Market
Metals
North America and Europe Metal Powder Market
Metals
Europe Aluminium Cans Market
Metals
Copper Clad Aluminum Wire Market
Metals
Aluminum Flat Products Market
Metals
Global Hot Rolled Coil Steel Market
Metals
Liquid Metal Thermal Pad Market
Metals
Aluminum Sheet Market
Metals
Iron and Steel Market
Metals
Copper and Copper Alloy Scrap and Recycling Market
Metals
Platinum Group Metals Market