
 Global Copper Market | 2026-2036
Global Copper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Copper Market Analysis
Buyer concentration among electric vehicle manufacturers and renewable energy developers is realigning contract structures toward long-term offtake agreements. BHP leverages its Olympic Dam and Escondida assets to sustain volume commitments to Asian battery producers. Codelco anchors Chilean state-backed supply through direct government partnerships. Freeport-McMoRan competes on Grasberg and North American mine output with integrated smelting positions.
Copper is a ductile, thermally conductive base metal with 99.99% purity cathode specifications and electrolytic refining as the dominant purification process, serving as the backbone of electrical conductivity across power generation and transmission systems. Copper cathodes dominate margin pools given their role as the exchange-traded benchmark and feedstock for downstream wire and rod production. Copper wire leads volume throughput in the application dimension due to grid modernization and building electrification, while copper alloys capture premium pricing in heat exchangers and specialized electrical equipment where corrosion resistance commands specification premiums.
The US EPA enforces air quality standards for smelter emissions that elevate capital costs for new North American refining capacity, while China's MEE implements dual carbon goals that constrain coal-powered smelting expansion and redirect investment toward hydropower-fed Chilean operations. The EU REACH framework and RoHS directives restrict hazardous substance content in electrical applications, shaping alloy formulations and import compliance requirements. Stakeholders must monitor permitting timelines for Chilean and Peruvian greenfield projects against smelter bottleneck constraints to calibrate procurement and inventory strategies.
Market Dynamics
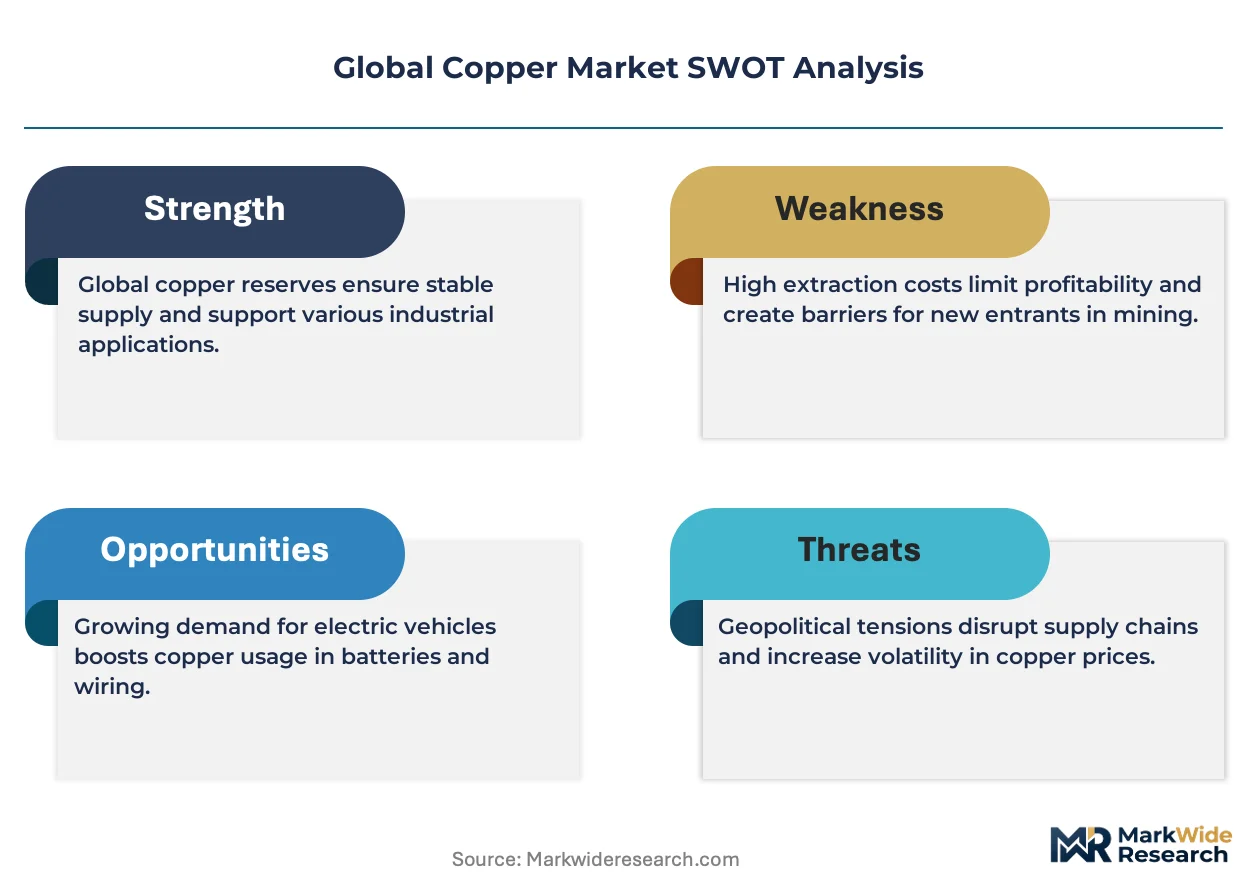
Electrification mandates across transportation and power grids are compressing copper procurement cycles, forcing smelters and fabricators to recalibrate inventory positions against volatile cathode premiums and concentrate supply bottlenecks.
Growth Catalysts
- Renewable energy buildout:Offshore wind and solar photovoltaic installations require copper-intensive cabling and transformer infrastructure. Grid interconnection backlogs in Germany and Spain are accelerating cathode offtake commitments.
- EU F-Gas Regulation:Stricter emission standards for industrial cooling are redirecting heat exchanger demand toward copper-nickel alloys with superior thermal conductivity and leak resistance.
- China's dual carbon goals:Coal-powered smelting curbs under MEE directives are channeling investment toward hydropower-fed Chilean refining capacity, tightening cathode availability for Asian wire rod producers.
Market Restraints
- Concentrate supply concentration:Chile's mining belt and Peru's Andean corridor control over half of mined copper output, exposing cathode pricing to labor stoppages and water access disputes.
- Aluminum substitution in power cabling:Transmission utilities in cost-sensitive markets are specifying aluminum conductors for overhead lines, compressing copper volume in long-distance grid segments.
- US EPA air quality enforcement:Smelter emission standards elevate capital requirements for new North American refining capacity, limiting greenfield project viability.
Strategic Opportunities
- Direct cathode-to-rod integration:Battery manufacturers in South Korea and Japan are negotiating tolling arrangements that bypass traditional merchant market premiums.
- Scrap circularity infrastructure:Urban mining networks in Belgium and the Netherlands are capturing end-of-life electrical equipment for secondary cathode production.
- Submarine cable specification:Interconnector projects linking Norway, the United Kingdom, and Germany are specifying high-purity oxygen-free copper for subsea transmission corridors.
Industry Challenges
- Metallurgical engineering scarcity:Solvent extraction and electrowinning expertise is concentrating among retiring specialists, constraining operational ramp-ups at greenfield leaching operations.
- Permitting timeline compression:Chilean environmental impact assessments for mine expansions are extending beyond historical baselines, delaying concentrate supply additions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Copper Market |
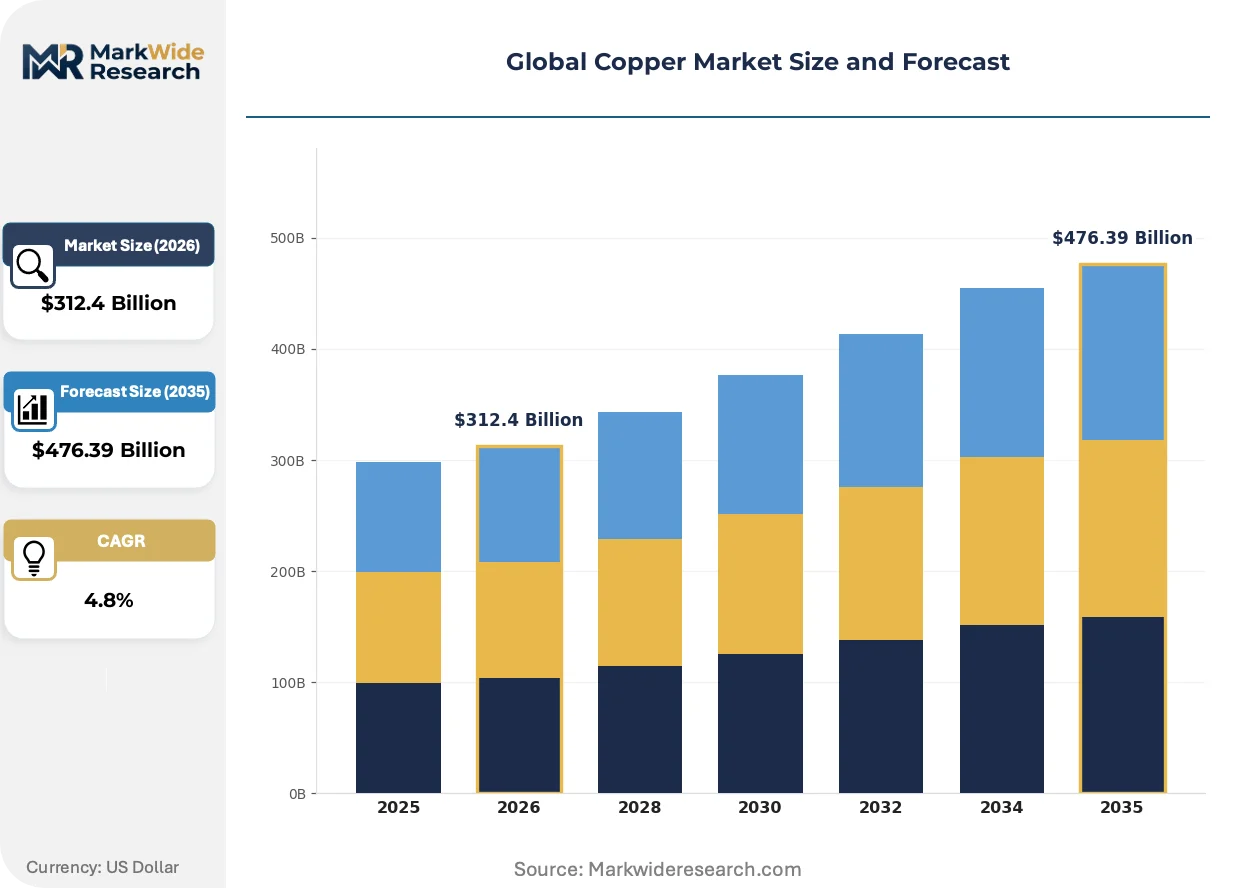
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $476.39 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Cathodes, Copper Wire, Copper Rod, Copper Alloys End Use Industry: Construction, Electronics, Transportation, Renewable Energy Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Application: Wiring, Plumbing, Electrical Equipment, Heat Exchangers |
| Companies Covered | Freeport-McMoRan, BHP, Codelco, Zijin Mining, Southern Copper, Glencore, Anglo American, KGHM Polska Miedź, Antofagasta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Copper Market Emerging Trajectories
Process intensification and digitalization are reshaping how copper moves from concentrate to fabricated product, with automation and predictive analytics compressing working capital cycles across the value chain.
Direct solvent extraction with modular skids is expanding into smaller-scale leaching operations previously served by conventional tankhouse circuits. Junior miners in Zambia and the Democratic Republic of Congo are deploying containerized SX-EW units to bypass capital-intensive permanent infrastructure. This distributed refining architecture is compressing concentrate transport costs and enabling cathode production closer to remote oxide ore bodies.
The EU REACH framework and RoHS directives are restricting hazardous substance thresholds in electrical and electronic equipment, forcing alloy reformulations and import documentation overhauls. Copper fabricators serving European appliance manufacturers must certify lead-free and cadmium-free specifications across supply tiers. Wire and cable producers are responding by segregating production lines and implementing batch-level traceability systems.
Long-term offtake contracting is displacing spot market cathode purchases among electric vehicle battery producers and renewable energy developers. Asian automotive OEMs are negotiating five- to seven-year supply agreements directly with Chilean state mining enterprises, bypassing traditional merchant trading houses. This procurement model shift is most visible in South Korean and Japanese battery supply chains, where cathode price volatility threatens cell cost targets.
Global Copper Market Segmentation
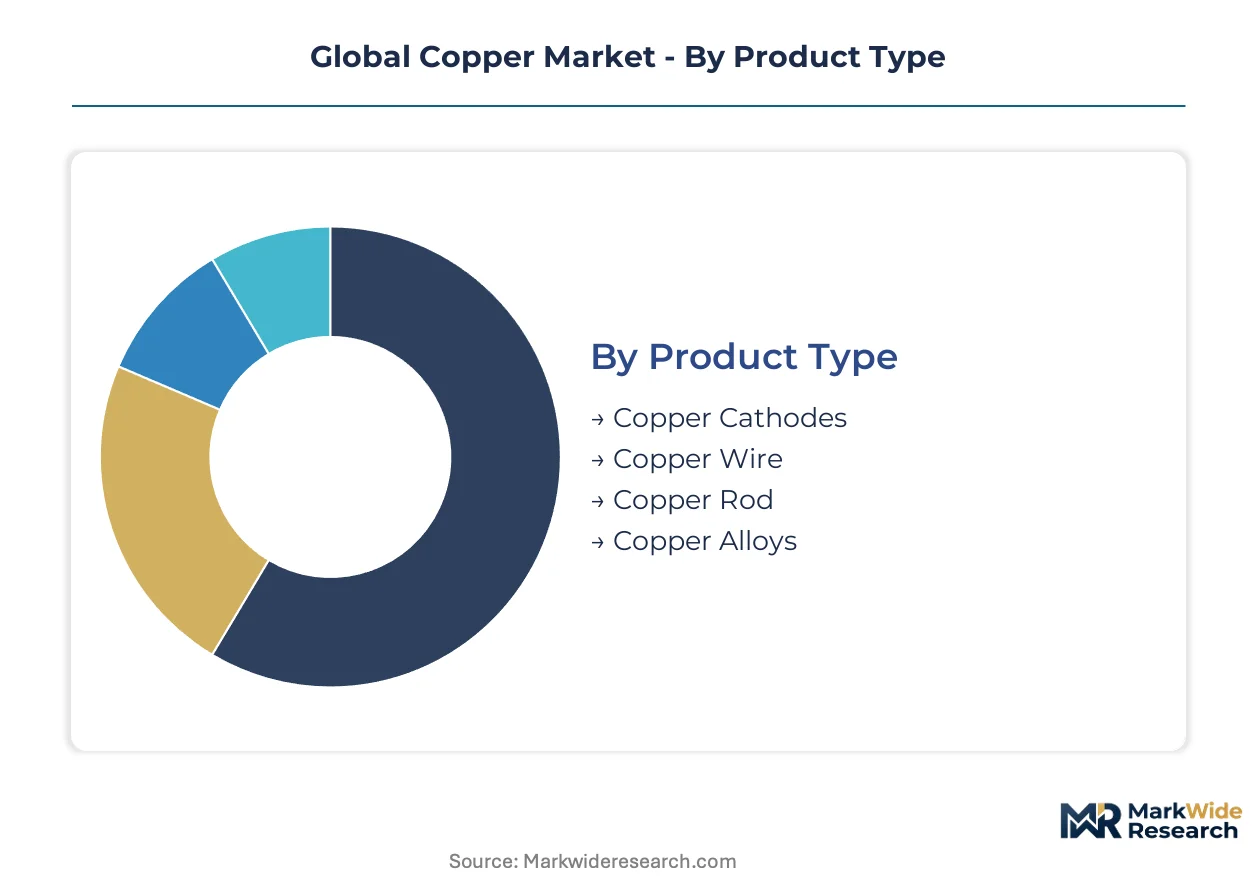
Copper market segmentation reveals how purity grades, fabrication stages, and conductivity specifications create divergent margin structures across the value chain. Buyers prioritize cathode benchmark pricing, alloy performance premiums, or wire gauge tolerances depending on their downstream integration depth.
Product Type:
Buyers differentiate by metal purity requirements and downstream processing intensity, with exchange-traded cathodes commanding distinct procurement workflows from custom alloy formulations.
- Copper Cathodes:Electrolytically refined to 99.99% purity, these LME-deliverable ingots serve as the pricing benchmark and feedstock for rod and wire production. Demand concentrates among Asian wire rod producers facing smelter bottlenecks under China's MEE coal-powered curbs.
- Copper Wire:Drawn from continuous cast rod, this segment spans power transmission cables to magnet wire for electric vehicle motors. Grid interconnection backlogs in Germany and Spain are accelerating offtake commitments from utilities.
- Copper Rod:Continuous cast and rolled feedstock for downstream drawing operations. South Korean battery manufacturers negotiate direct tolling arrangements to bypass merchant market premiums.
- Copper Alloys:Brass, bronze, and copper-nickel formulations for corrosion-resistant applications. EU F-Gas Regulation redirects heat exchanger demand toward copper-nickel grades with superior thermal conductivity.
Volume sits with Copper Cathodes; growth tilts toward Copper Alloys.
End Use Industry:
Industry verticals separate by project scale, certification burden, and long-term contracting appetite, with infrastructure developers locking in multi-year supply against spot volatility.
- Construction:Building electrification and HVAC systems drive wire and tubing consumption. Urban mining networks in Belgium and the Netherlands are capturing end-of-life electrical equipment for secondary feedstock.
- Electronics:Printed circuit boards and semiconductor packaging require high-purity oxygen-free copper. Japanese automotive OEMs negotiate five- to seven-year supply agreements directly with Chilean state mining enterprises.
- Transportation:Electric vehicle battery manufacturers and charging infrastructure deploy copper-intensive busbars and cabling. Asian battery producers are displacing spot market purchases with long-term offtake contracts.
- Renewable Energy:Offshore wind turbines and solar photovoltaic installations require transformer and cabling infrastructure. Submarine interconnectors linking Norway, the United Kingdom, and Germany specify high-purity grades for subsea corridors.
Construction holds installed base dominance; Renewable Energy climbs the fastest.
Distribution Channel:
Channel selection tracks order size predictability and technical service requirements, with integrated manufacturers bypassing intermediaries while project developers rely on distributor inventory buffers.
- Direct Sales:Long-term offtake agreements between miners, smelters, and large fabricators. Chilean state mining enterprises anchor volume through direct government partnerships with Asian battery supply chains.
- Distributors:Regional inventory positioning for construction contractors and small fabricators. Stocking locations in Rotterdam and Singapore buffer lead time volatility for European and Southeast Asian wire rod mills.
- Online Sales:Digital platforms for standardized copper products and scrap trading. Containerized SX-EW units in Zambia and the Democratic Republic of Congo enable cathode production closer to remote oxide ore bodies.
- Retail:Small-quantity sales to electricians and maintenance contractors. Segregated production lines and batch-level traceability systems respond to EU REACH documentation requirements.
Direct Sales capture contract value; Online Sales expand most quickly.
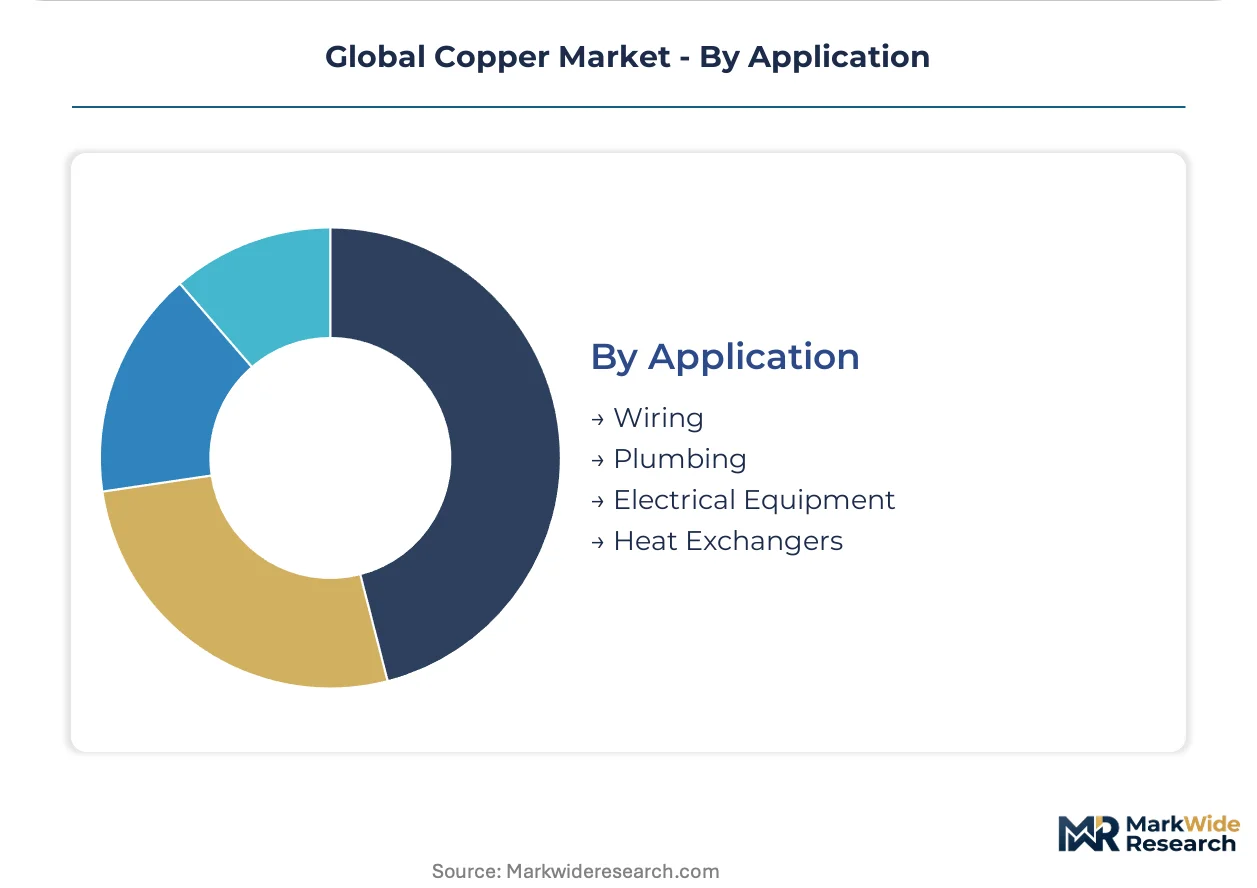
Application:
Application segments diverge by regulatory exposure, with electrical installations facing REACH and RoHS compliance while plumbing encounters lead-free alloy mandates.
- Wiring:Power transmission and building electrical systems comprise the largest throughput category. Grid modernization across Germany and Spain compresses procurement cycles for cathode and rod producers.
- Plumbing:Potable water tubing and fittings require lead-free alloy certifications. US EPA air quality enforcement elevates capital requirements for new North American refining capacity serving this segment.
- Electrical Equipment:Transformers, switchgear, and motors specify conductivity and fatigue resistance. Labor stoppages and water access disputes in Chile's mining belt and Peru's Andean corridor expose pricing to supply interruptions.
- Heat Exchangers:HVAC and industrial cooling systems leverage copper-nickel thermal performance. Stricter EU F-Gas Regulation redirects specification toward alloys with superior leak resistance.
Wiring dominates volume throughput; Heat Exchangers command specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's Atacama Desert and Peru's Andean copper corridor anchor mined concentrate supply, while Chinese smelting capacity and European fabrication demand reshape trade flows across three continents.
Chile
State mining enterprises and private operators extract from the Atacama and central mining belt. Stricter water access regulations under environmental courts constrain tailings dam expansions. Antofagasta and Escondida operations near Calama face permitting delays extending project timelines.
Peru
The Andean copper corridor supplies concentrate to Asian smelters under long-term offtake structures. Community consultation mandates from the Ministry of Energy and Mines slow greenfield approvals. Cerro Verde and Las Bambas clusters in Arequipa and Apurímac encounter periodic logistics disruptions from port access disputes.
China
Wire rod mills and cathode consumers absorb imported concentrate despite MEE coal-powered smelting curbs. Dual carbon goals redirect investment toward hydropower-fed Chilean refining partnerships. Jiangxi and Anhui provinces concentrate secondary smelting capacity for scrap circularity.
Germany
Grid interconnection backlogs accelerate cathode commitments from utilities modernizing transmission infrastructure. EU REACH and RoHS directives enforce hazardous substance thresholds on electrical equipment imports. Hamburg and Duisburg harbor zones stockpile rod inventory for European wire mills.
United States
EPA air quality standards elevate capital barriers for new smelter construction, preserving reliance on imported cathode. Arizona and Utah mining operations feed concentrate to limited domestic refining capacity. Electric vehicle battery producers in the Midwest negotiate direct cathode supply bypassing merchant markets.
Global Copper Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular leaching and scrap circularity positions. The vendor base concentrates among integrated miners with captive smelting assets and state-backed enterprises with direct government partnerships. Two strategic archetypes dominate: scale-driven concentrators controlling Andean ore bodies, and technology licensors deploying containerized SX-EW units. Competitive moves center on long-term offtake contracting with Asian battery manufacturers and backward integration into rod and wire fabrication.
Among diversified mining conglomerates, BHP and Glencore exemplify scale-driven concentrators with integrated smelting positions across multiple geographies. Codelco anchors the state-backed archetype through direct Chilean government partnerships. Freeport-McMoRan occupies a position spanning both concentrator and technology licensing vectors with Grasberg and North American assets. These three represent divergent responses to cathode premium volatility and concentrate supply bottlenecks.
| Leading Market Players |
|---|
| Freeport-McMoRan |
| BHP |
| Codelco |
| Zijin Mining |
| Southern Copper |
| Glencore |
| Anglo American |
| KGHM Polska Miedź |
| Antofagasta |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in Chile and Peru anchor concentrate supply, translating geological endowment into pricing power through long-term offtake structures that bypass spot volatility. State mining enterprises leverage direct government partnerships to secure volume commitments from Asian battery manufacturers, compressing merchant market participation and elevating cathode premium capture for integrated operators.
Pricing Analysis
Volume throughput concentrates in standard-grade cathodes while margin capture tilts toward high-purity oxygen-free grades for submarine interconnectors. Three-tier pricing structure across premium, standard, and economy levels separates LME-deliverable cathodes from custom alloy formulations and scrap-derived secondary material. Cost compression in wire rod is intensifying because Chinese MEE coal-powered smelting curbs are tightening cathode availability for Asian mills. Electric vehicle battery manufacturers exhibit lowest price sensitivity due to cell cost targets, while construction contractors face acute pressure from aluminum substitution in overhead transmission lines.
Supply Chain Analysis
Single-source vulnerability sits with Chile's Atacama mining belt and Peru's Andean corridor, which together feed the majority of global concentrate throughput. The supply chain draws from sulfuric acid for leaching operations, metallurgical coal for smelting energy, and specialized solvent extraction reagents for electrowinning circuits. Regulatory restriction from US EPA air quality standards elevates capital barriers for new North American refining capacity, preserving import dependence. Distribution runs through Rotterdam and Singapore harbor zones stocking rod inventory for European and Southeast Asian wire mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained fundamentals prop pricing across the forecast horizon, with permitting timeline compression in Chilean mine expansions representing the binding capacity bottleneck preventing demand absorption.
For Market Incumbents: Cement long-term offtake structures with Asian battery manufacturers before modular SX-EW entrants capture remote oxide deposits in Zambia and the Democratic Republic of Congo. Prioritize backward integration into continuous cast rod production to bypass merchant market premiums and defend margin position against tolling arrangement displacement. For New Entrants and Emerging Players: Battery-grade copper-nickel alloy fabricators serving EU heat exchanger OEMs face limited incumbent specialization, creating white-space opportunity for certification-ready producers. Target containerized SX-EW deployment near remote oxide ore bodies to compress concentrate transport costs and establish cathode production proximity to African mining corridors. For Investors and Strategic Acquirers: Chilean environmental court rulings on water access permits are the leading indicator that concentrate supply additions will lag demand growth across the projection horizon. Position for five-to-ten year viability in hydropower-fed refining assets with direct government partnerships, monitoring MEE policy enforcement in China as the signal for Asian smelter bottleneck duration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Asian battery manufacturers bypass merchant markets through direct Chilean state mining partnerships. |
| Backward Integration | South Korean rod producers capture cathode-to-wire margin through tolling arrangements with miners. |
| Green Manufacturing Transition | Hydropower-fed Chilean refining capacity attracts investment diverted from coal-powered Chinese smelting. |
| Capacity Expansion | Antofagasta and Escondida face permitting delays from environmental court water access rulings near Calama. |
| Joint Venture | Belgian and Dutch urban mining networks partner with fabricators for secondary cathode production from end-of-life equipment. |
Methodological Framework
Trade databases, SEC filings from diversified mining conglomerates, and Chilean environmental court records formed the secondary backbone, cross-referenced with primary interviews across smelter operations directors, cathode procurement leads at Asian wire rod mills, and regulatory affairs specialists at state mining enterprises. Bottom-up concentrate supply modeling and top-down demand segmentation from renewable energy project pipelines were triangulated to calibrate volume forecasts.
Historical trendline analysis of cathode premium volatility and concentrate treatment charges informed the analytical framework across the analysis window. Segmentation dimensions modeled include product purity grade, end-use industry vertical, and distribution channel structure, with CAGRs derived from project-level renewable energy buildout pipelines and electric vehicle battery capacity announcements. Forecast inputs incorporated MEE enforcement intensity projections and EU F-Gas Regulation implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chilean permitting timeline resolution and Chinese dual carbon goal enforcement consistency. Forecasts reflect documented assumptions regarding concentrate supply addition schedules and substitution elasticity in power transmission applications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Powders Pastes and Flakes Market
Metals
Aluminium Conductors Market
Metals
United States Metal Casting Market
Metals
Global Duplex Stainless Steel Market
Metals
Copper Powder Market
Metals
Silico Manganese Market
Metals
Nickel Sulfate Market
Metals
Lithium Tungstate Market
Metals
Qatar Metalworking Market
Metals
Niobium Oxide Market
Metals
Silver Cyanide Market
Metals
Rubidium Market
Metals
Pump Casing Materials Market
Metals
Global Flat Carbon Steel Market
Metals
Vietnam Aluminum Market
Metals
Palladium Market