
 Metal Injection Molding (Mim) Powders Market | 2026-2036
Metal Injection Molding (Mim) Powders Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Injection Molding (Mim) Powders Market Analytics
Maintenance-linked powder replenishment contracts are pivoting how MIM suppliers monetize long-term customer relationships. Höganäs AB leverages its Scandinavian raw material base to sustain consistent feedstock quality across medical and automotive programs. GKN Powder Metallurgy anchors European aerospace demand through captive powder-to-part integration. Indo-MIM dominates Asian supply chains with localized spherical powder production.
Metal injection molding powders are finely atomized metallic feedstocks, typically 2-22 microns in particle size, formulated with thermoplastic binders for injection into complex molds before thermal debinding and sintering. Stainless steel variants lead material type volumes due to corrosion resistance requirements in surgical instruments and firearm components, while spherical powder forms command premium positioning for aerospace turbine blade applications where flowability and packing density directly determine final part integrity. Medical devices and consumer electronics represent the fastest-expanding application channels, driven by miniaturization trends that conventional machining cannot satisfy.
FDA 21 CFR Part 820 quality system regulations and EU MDR conformity requirements shape medical-grade powder specifications, forcing suppliers to maintain batch-level traceability and biocompatibility documentation. REACH substance restrictions and evolving ECHA guidance on nickel compound classifications are elevating compliance costs for European powder blenders. Stakeholders must monitor how binding agent chemistry evolves under tightening EPA volatile organic compound rules and whether China's GB standard harmonization opens or constrains export pathways for Western powder producers.
Market Dynamics
Flight-weight miniaturization in aerospace turbine systems is compressing tolerance requirements for spherical MIM powders, forcing atomization technology upgrades across European and Asian supply bases.
Growth Catalysts
- EU MDR conformity pathways:Batch-level traceability mandates for implantable devices are pulling medical-grade stainless steel powders through certified supply chains in Germany and Switzerland.
- Titanium aluminide adoption:Next-generation aerospace engine programs are specifying gamma-TiAl powders for turbine blade applications above 800°C operating temperatures.
- Stuttgart precision engineering cluster:Concentrated demand from firearm component manufacturers is sustaining high-volume stainless steel powder throughput with minimal logistics friction.
Market Restraints
- Nickel price volatility:316L and 17-4PH stainless steel formulations face margin compression when London Metal Exchange nickel contracts spike above historical baselines.
- Spherical powder supply concentration:Plasma atomization capacity clusters among three specialized producers, creating single-source vulnerability for aerospace-qualified feedstock.
- Gas atomization energy intensity:Argon consumption per kilogram of fine powder constrains cost competitiveness against machined alternatives in consumer electronics brackets.
Strategic Opportunities
- India's orthopedic implant localization:CDSCO manufacturing-linked incentives are creating captive demand for surgical-grade 316L powder with domestic atomization partnerships.
- Copper-tungsten thermal management:5G base station heat spreader applications are opening volume channels for bimetallic MIM formulations previously limited to defense programs.
- Japan METI carbon-neutral manufacturing roadmap:Hydrogen-reduced atomization pilot programs offer regulatory preference and procurement priority for qualifying powder suppliers.
Industry Challenges
- Debinding furnace throughput bottlenecks:Thermal processing capacity expansion requires 18-24 month lead times for catalytic and solvent debinding line commissioning.
- ISO 22068 sintering density certification:Medical device auditors are demanding particle-size-distribution documentation that legacy quality systems cannot generate without IT infrastructure overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Injection Molding (Mim) Powders Market |
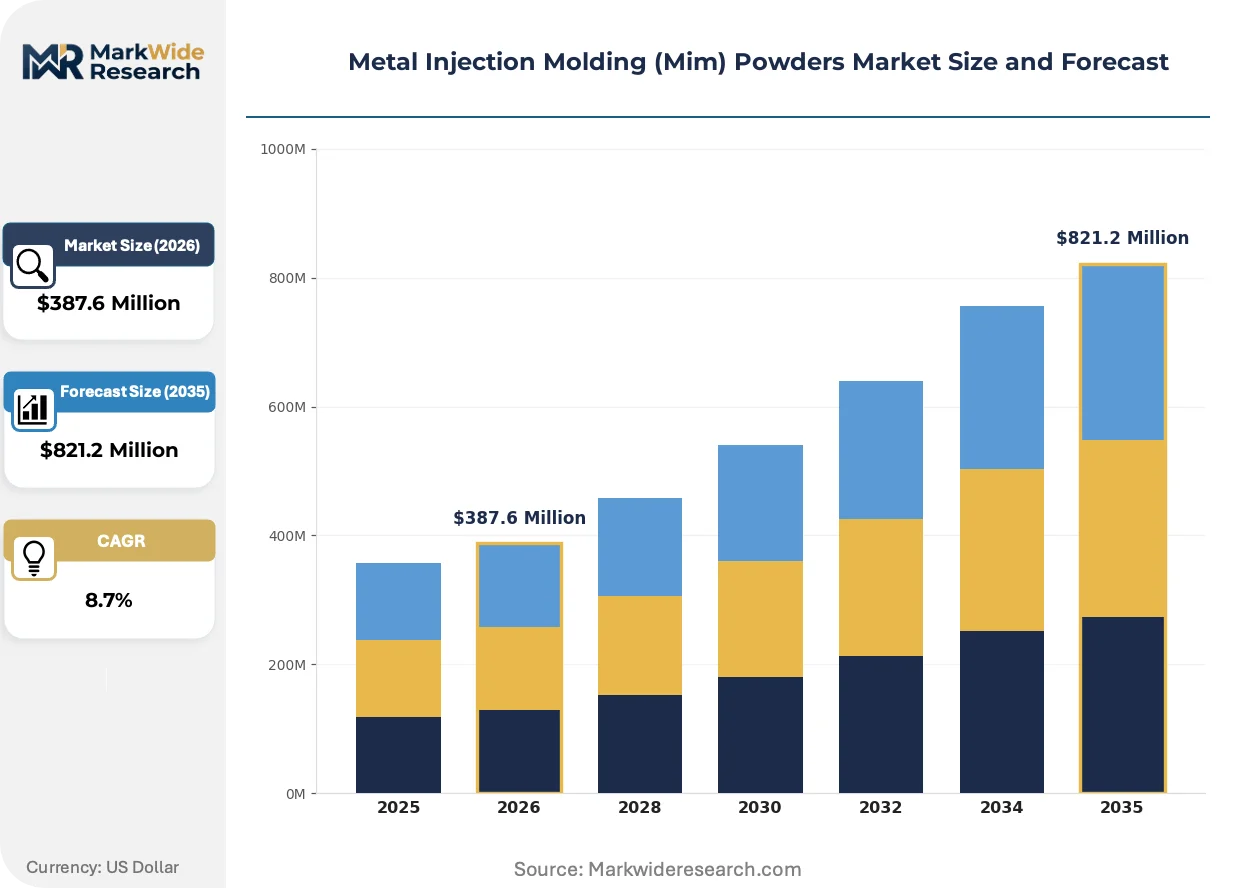
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Stainless Steel, Tungsten, Iron, Nickel Application Type: Aerospace, Automotive, Consumer Electronics, Medical Devices Form: Powdered Pre-Alloyed, Blended, Coated, Spherical End User: Manufacturers, OEMs, Prototyping Services, Tier-1 Suppliers |
| Companies Covered | GKN Powder Metallurgy, Höganäs AB, Indo-MIM, Dynacast, Form Technologies, Schunk Group, FineMIM, BASF SE, Carpenter Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Injection Molding (Mim) Powders Market Evolving Landscape
Atomization control systems and binder chemistry platforms are converging to enable geometries previously unreachable through conventional powder metallurgy or subtractive methods.
Plasma rotating electrode process (PREP) technology is expanding into aerospace turbine blade programs requiring defect-free spherical morphology below 45 microns. Rolls-Royce and Safran procurement specifications now mandate PREP-derived Ti-6Al-4V for high-cycle fatigue applications. This is expanding into medical hip implant femoral heads where alpha-case elimination justifies 40% powder cost premiums over gas-atomized alternatives.
REACH Annex XVII nickel compound restrictions are forcing reformulation of 17-4PH variants for European consumer electronics hinges. ECHA substance evaluation timelines are compressing supplier response windows to 18 months for compliance dossier submission. Medical device powder blenders in Germany and Switzerland are responding with nitrogen-atomized 316L variants that reduce nickel surface availability below migration test thresholds.
Buyer consolidation among contract manufacturers is compressing powder supplier qualification cycles from 24 months to 14 months. Indo-MIM and its tier-one competitors are unbundling technical service from powder pricing, shifting revenue toward application engineering retainers. This pattern is most visible in Singapore and Penang electronics manufacturing corridors where MIM houses now specify powder lots with matched thermal expansion coefficients for multi-material assemblies.
Metal Injection Molding (Mim) Powders Market Segmentation
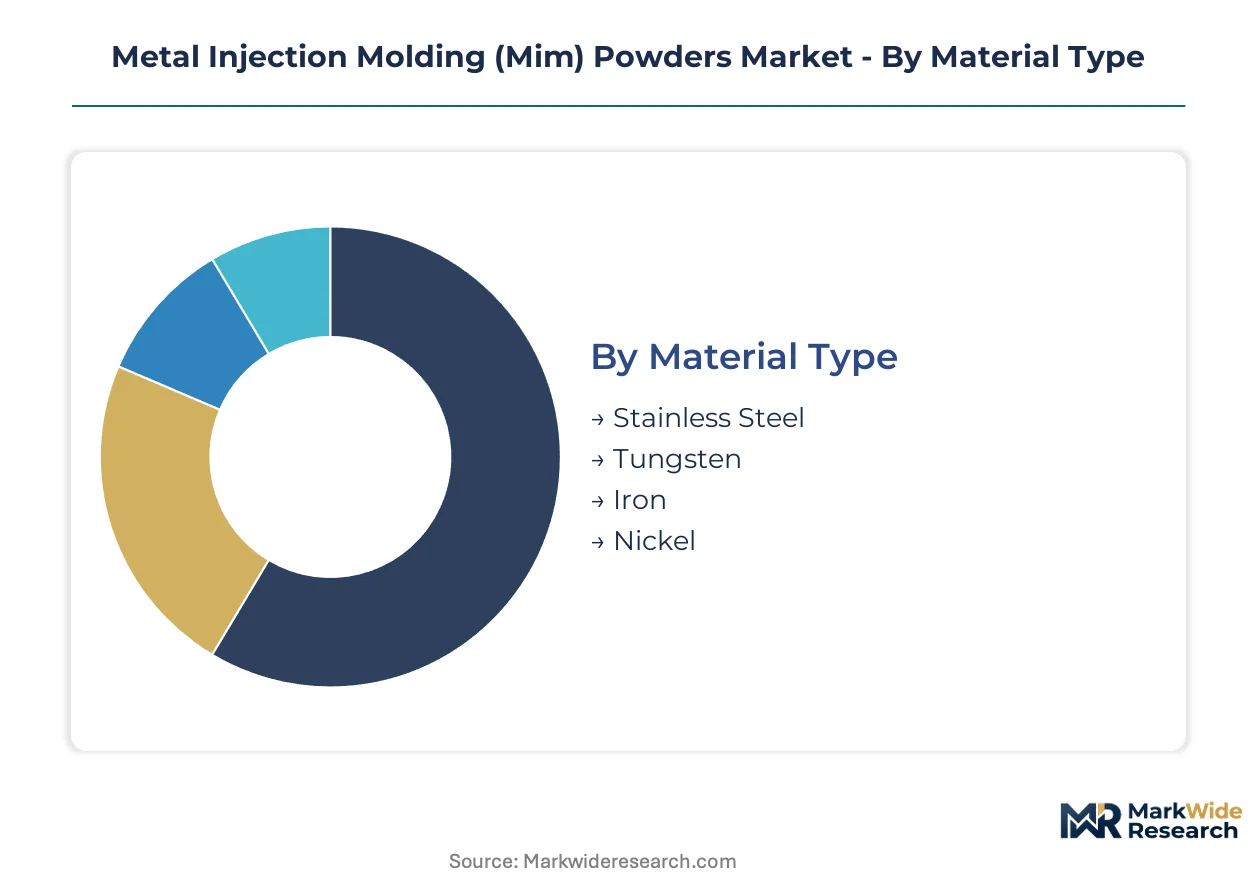
Material chemistry and particle morphology dictate pricing tiers and qualification barriers in MIM powder procurement. Aerospace turbine programs and medical implant manufacturers drive specification divergence that fragments supply contracts across atomization technologies.
Material Type:
Stainless steel formulations concentrate procurement volumes through corrosion-resistant specifications for surgical instruments and firearm components. Tungsten variants serve defense and radiation shielding applications where density requirements exclude lighter alternatives.
- Stainless Steel:316L and 17-4PH grades dominate surgical instrument and consumer electronics hinge production. REACH Annex XVII nickel migration thresholds are forcing nitrogen-atomized variants in Germany and Switzerland to reduce surface nickel availability below detection limits.
- Tungsten:Heavy alloy formulations achieve 17.5-18.5 g/cm³ density for kinetic energy penetrators and collimator shields. US Department of Defense procurement through the Defense Logistics Agency sustains dedicated atomization capacity in Pennsylvania and Ohio.
- Iron:Low-alloy ferrous powders serve automotive lock components and power tool gears where corrosion resistance requirements permit cost-minimized formulations.
- Nickel:Inconel and Monel variants target chemical processing hardware and marine fasteners requiring chloride stress-corrosion resistance beyond stainless capabilities.
Today's leader: Stainless Steel. Tomorrow's challenger: Tungsten.
Application Type:
End-use qualification cycles stretch from 14 months for consumer electronics to 36 months for implantable medical devices. Aerospace turbine blade programs now mandate PREP-derived powders that command 40% premiums over gas-atomized alternatives.
- Aerospace:Gamma-TiAl and Ti-6Al-4V specifications for turbine blades above 800°C operating temperatures. Rolls-Royce and Safran procurement mandates PREP morphology below 45 microns for high-cycle fatigue resistance.
- Medical Devices:FDA 21 CFR Part 820 quality system regulations and EU MDR batch-level traceability requirements shape 316L powder specifications for hip implant femoral heads and surgical stapler components.
- Automotive:Turbocharger wastegate arms and fuel injection nozzles specify 17-4PH for temperature resistance up to 315°C with HRC 40 hardness post-sintering.
- Consumer Electronics:Miniaturized hinges and connector housings for foldable smartphones drive volume demand for 316L with tight particle size distribution around 10 microns.
Medical Devices expand most quickly as orthopedic implant localization accelerates in India and Southeast Asia.
Form:
Particle geometry determines flowability, packing density, and final part integrity in complex mold filling. Spherical morphology commands structural premiums while blended formulations serve cost-sensitive high-volume applications.
- Spherical:Plasma atomization and PREP processes yield 45-micron-and-below powders with Hausner ratios below 1.25 for aerospace turbine blade applications where defect-free morphology justifies feedstock cost premiums.
- Powdered Pre-Alloyed:Homogeneous chemistry distribution eliminates segregation risks in medical implant sintering where ISO 22068 density certification requires consistent particle composition.
- Blended:Elemental powder mixing permits custom alloy development for prototyping services and short-run specialty components without dedicated atomization campaigns.
- Coated:Polymer or metallic surface treatments enhance flowability and oxidation resistance during thermal debinding cycles in high-humidity manufacturing environments.
Spherical forms gain share fastest as aerospace qualification standards tighten.
End User:
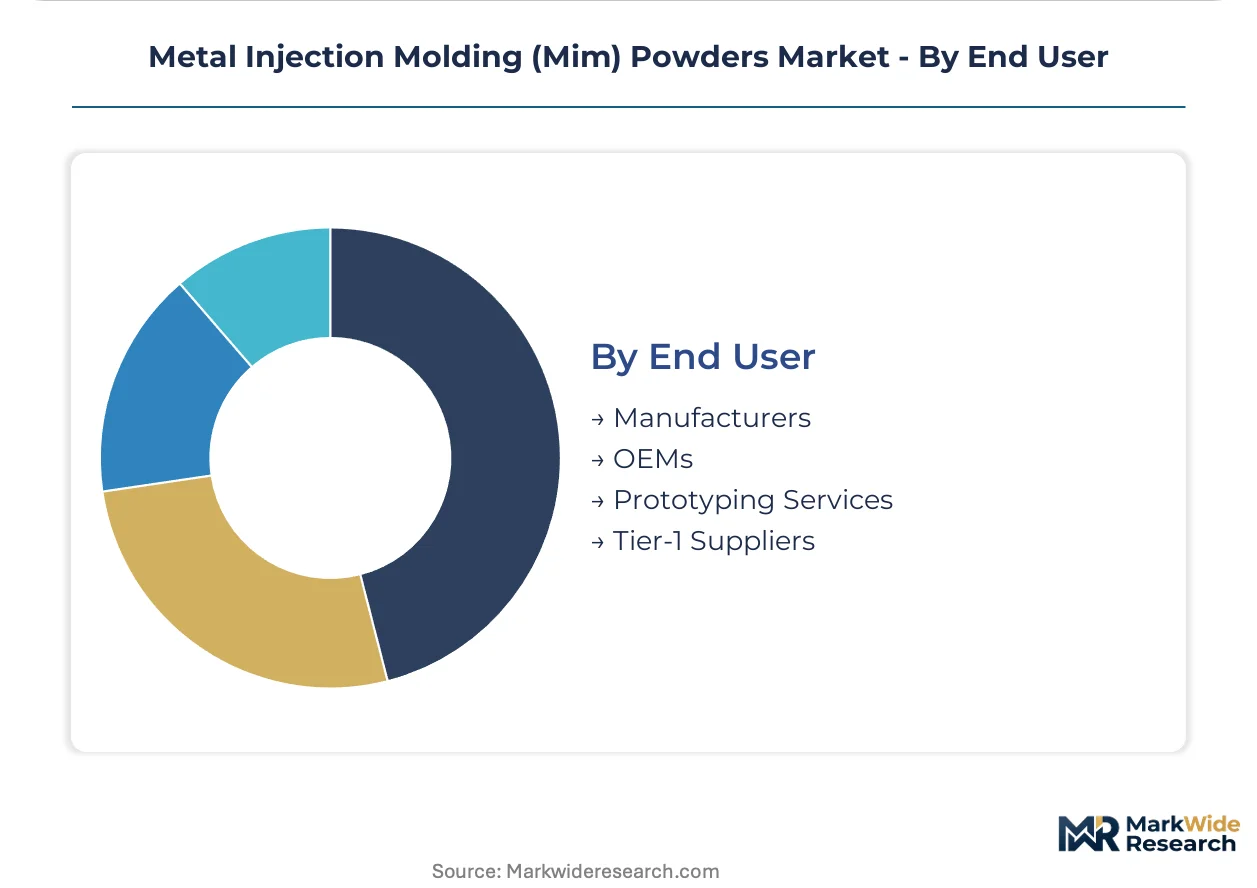
Buyer consolidation among contract manufacturers compresses supplier qualification cycles and shifts procurement toward application engineering partnerships. Tier-1 suppliers increasingly specify matched thermal expansion coefficients for multi-material assemblies.
- Tier-1 Suppliers:Singapore and Penang electronics manufacturing corridors drive specification of powder lots with coefficient-matching for stainless steel-ceramic hybrid assemblies in smartphone camera modules.
- Manufacturers:Captive MIM operations at Indo-MIM and GKN Powder Metallurgy anchor volume demand through powder-to-part integration that internalizes margin capture.
- OEMs:Original equipment manufacturers in Stuttgart's precision engineering cluster sustain high-throughput stainless steel procurement with minimal logistics friction through regional atomization partnerships.
- Prototyping Services:Rapid qualification requirements favor blended powder formulations and shortened debinding cycles for design iteration support before production tooling commitment.
Tier-1 Suppliers lead current procurement volumes. Prototyping Services present the steepest expansion trajectory as product development cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates aerospace-grade spherical powder demand while India scales domestic atomization for orthopedic implants, revealing divergent regional specialization patterns across the MIM powder value chain.
Germany
Stuttgart's precision engineering corridor sustains high-volume 316L and 17-4PH throughput for firearm components and surgical instruments. ECHA REACH Annex XVII nickel compound restrictions force nitrogen-atomized variants that reduce surface nickel availability below migration thresholds. Munich anchors medical-grade powder qualification through Swissmedic-aligned batch traceability systems serving EU MDR implantable device pathways.
United States
Defense Logistics Agency procurement sustains dedicated tungsten heavy alloy atomization capacity in Pennsylvania and Ohio for kinetic energy penetrators. FDA 21 CFR Part 820 quality system regulations shape surgical-grade stainless steel specifications for domestic hip implant manufacturers. The Pacific Northwest hosts plasma atomization R&D clusters addressing PREP-derived Ti-6Al-4V fatigue requirements for next-generation turbine programs.
China
GB standard harmonization efforts determine export pathway viability for Western powder producers accessing domestic MIM houses. MIIT industrial policy directs spherical powder capacity expansion toward consumer electronics hinge miniaturization for foldable smartphone programs. The Yangtze River Delta concentrates blended powder formulation services for rapid prototyping cycles serving regional contract manufacturers.
India
CDSCO manufacturing-linked incentives create captive demand for surgical-grade 316L powder with domestic atomization partnerships accelerating orthopedic implant localization. BIS certification requirements for medical device feedstocks compress supplier qualification timelines from 24 months toward 14-month benchmarks. Maharashtra and Gujarat host emerging powder-to-part integration facilities capturing margin previously exported to European toll processors.
Japan
METI carbon-neutral manufacturing roadmap elevates hydrogen-reduced atomization pilot programs toward regulatory preference and procurement priority status. PMDA medical device quality standards align with ISO 22068 sintering density certification requirements for domestic hip implant femoral head production. Nagoya's precision manufacturing belt sustains PREP technology adoption for aerospace turbine blade programs requiring defect-free spherical morphology below 45 microns.
Metal Injection Molding (Mim) Powders Market Competitive Landscape
Top-tier vendors anchor aerospace and medical qualification tiers, while mid-scale specialists occupy regional automotive and consumer electronics niches. The vendor base stratifies across atomization technology ownership, with plasma and PREP capability holders commanding structural premiums over gas-atomized commodity suppliers. Three archetypes dominate: captive powder-to-part integrators, independent feedstock specialists with multi-industry certification, and regional toll processors serving prototyping services. Competitive dynamics center on qualification cycle compression and backward integration into raw material sourcing.
Among European-anchored suppliers, Höganäs AB and GKN Powder Metallurgy exemplify divergent strategic positioning within premium-tier supply chains. Höganäs leverages Scandinavian raw material access for consistent feedstock quality across medical and automotive programs, while GKN anchors European aerospace demand through captive powder-to-part integration. Indo-MIM represents the Asia-Pacific scale archetype, dominating regional supply chains through localized spherical powder production and compressed qualification timelines for Singapore and Penang electronics manufacturing corridors.
| Leading Market Players |
|---|
| GKN Powder Metallurgy |
| Höganäs AB |
| Indo-MIM |
| Dynacast |
| Form Technologies |
| Schunk Group |
| FineMIM |
| BASF SE |
| Carpenter Technology Corporation |
| Others |
Value Network & Pricing Analysis
Rolls-Royce and Safran procurement mandates for PREP-derived Ti-6Al-4V powders below 45 microns are forcing atomization capacity investments among European and Asian suppliers, compressing margins on gas-atomized alternatives while elevating structural premiums for spherical morphology specialists.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for standard-grade stainless steel powders while premium-tier PREP and plasma-atomized feedstocks maintain insulation through aerospace qualification barriers. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade batch-traceable powders from automotive commodity grades and blended prototyping formulations. Cost compression in consumer electronics brackets is intensifying because Indo-MIM and regional competitors are unbundling technical service from powder pricing. Tier-1 suppliers in Singapore and Penang electronics corridors show lowest price sensitivity due to coefficient-matching specifications, while prototyping services remain most price-sensitive.
Supply Chain Analysis
Single-source vulnerability sits with plasma atomization capacity concentrated among three specialized producers serving aerospace turbine blade programs. Germany, China, and India anchor spherical powder supply, with Stuttgart's precision engineering cluster and the Yangtze River Delta serving distinct end-use tiers. Feedstock draws from Scandinavian ore bases, argon gas supply contracts, and nickel exchange positions. Tariff exposure on Chinese-origin powders threatens Western medical device supply chains. Distribution runs through captive powder-to-part integrators, regional toll processors, and direct qualification partnerships with tier-1 contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with orthopedic implant localization in India and Southeast Asia providing durable volume expansion that transcends cyclical industrial demand swings.
For Market Incumbents: Extend qualification cycle compression capabilities to defend against emerging Indian atomization partnerships capturing CDSCO-linked surgical-grade contracts. Deepen backward integration into Scandinavian raw material sourcing to sustain feedstock consistency across REACH-compliant medical programs. Invest in hydrogen-reduced atomization pilots ahead of Japan METI carbon-neutral procurement preferences. For New Entrants and Emerging Players: Capture copper-tungsten thermal management formulations for 5G base station heat spreaders, a bimetallic segment previously restricted to defense programs with minimal incumbent saturation. Target India's orthopedic implant localization wave through BIS-certified 316L powder partnerships with Maharashtra and Gujarat powder-to-part facilities. Lead with application engineering retainers rather than commodity powder pricing to bypass established supplier qualification barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists owning PREP or plasma atomization technology in geographies with aerospace manufacturing expansion. The 5-10 year viability window favors feedstock producers with multi-industry certification spanning FDA 21 CFR Part 820 and EU MDR pathways. Watch for ECHA substance evaluation timelines compressing supplier response windows as inflection indicator for consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Höganäs AB leverages Scandinavian ore access to sustain feedstock consistency across REACH-regulated medical programs. |
| PREP Technology Capacity Expansion | Defect-free spherical morphology below 45 microns commands 40% premiums for Rolls-Royce and Safran turbine specifications. |
| Domestic Atomization Partnership Formation | CDSCO manufacturing-linked incentives in India accelerate orthopedic implant localization away from European toll processors. |
| Hydrogen-Reduced Atomization Pilot Programs | Japan METI carbon-neutral roadmap offers regulatory preference and procurement priority for qualifying powder suppliers. |
| Application Engineering Retainer Unbundling | Singapore and Penang tier-1 suppliers now specify powder lots with matched thermal expansion coefficients for multi-material assemblies. |
Research Methodology
Direct dialogue with atomization plant managers, biomedical engineers at hip implant manufacturers, procurement leads at tier-1 electronics contract manufacturers, and regulatory affairs specialists at notified bodies grounded the qualitative foundation. Secondary validation drew from FDA 510(k) filings, ECHA REACH dossier submissions, CDSCO manufacturing incentive notifications, and SEC filings of publicly traded powder metallurgy firms. Bottom-up demand modeling across application segments triangulated against top-down supply capacity assessments.
Segment-level outputs across material type, particle morphology, end-use qualification tier, and regional regulatory cluster were generated through the projection horizon. CAGRs were derived from regression analysis of historical procurement volumes against aerospace program ramps and medical device localization trends. Industry-specific forecast inputs incorporated EU MDR batch-traceability implementation timelines and GB standard harmonization progress for Chinese market access.
Plasma atomization capacity bottlenecks, ECHA nickel compound reclassification timelines, and aerospace program delay risks are the dominant revision risks to the analytical envelope. Forecasts reflect documented assumptions regarding qualification cycle compression rates and regional localization policy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
7075 T6 Aluminum Market
Metals
Stainless Steel 400 Series Market
Metals
Aluminum Extrusion Market
Metals
Finished Steel Products Market
Metals
Pump Casing Materials Market
Metals
Amorphous Metal Cores Market
Metals
Cold Drawn Wire Market
Metals
Aluminum Fluoride Market
Metals
Global Bronze Market
Metals
Zinc Dust Market
Metals
US Ferrochrome Market
Metals
Aluminium Powder Market
Metals
Copper and Copper Alloy Scrap and Recycling Market
Metals
Tin Chloride Market
Metals
Niobium Oxide Market
Metals
Global Metal and Metal Manufactured Products Market