
 Cobalt Market | 2026-2036
Cobalt Market Size, Share, and Industry Trends Forecast 2026-2036
Cobalt Market Intelligence
ISO 14001 environmental management certification is bifurcating the cobalt supply base between qualified industrial suppliers and artisanal operators excluded from formal procurement channels. Glencore leverages its integrated mining-trading infrastructure across Central African Copperbelt assets. CMOC Group dominates Tenke Fungurume output, the largest cobalt-producing mine globally. Vale S.A. anchors its position through nickel-cobalt byproduct streams from Canadian and Brazilian operations.
Cobalt is a hard, lustrous transition metal with atomic number 27, typically extracted as a byproduct of copper and nickel mining and refined into salts, metal, or powder for high-temperature stability applications. Its primary commercial purpose centers on imparting thermal resistance and electrochemical performance in aerospace turbine blades and lithium-ion battery cathodes. Cobalt sulfate leads product type demand because battery cathode manufacturers specify this salt for precursor synthesis, while cobalt metal retains premium pricing in superalloy applications where purity thresholds exceed battery-grade material. The automotive batteries end-use segment commands the fastest expansion trajectory, whereas pigment applications in ceramics represent a mature, price-sensitive consumption pool with thinner margins.
The US SEC climate disclosure rules, the EU Battery Regulation's due diligence mandates, and China's MIIT new energy vehicle credit system collectively reshape cobalt sourcing transparency and end-use qualification. These frameworks compel producers to document chain-of-custody from mine to cathode plant, effectively raising compliance costs for non-integrated traders. Stakeholders must monitor how Congolese mining code revisions and downstream recycling mandates in multiple jurisdictions alter feedstock availability and long-term contract structures.
Market Dynamics
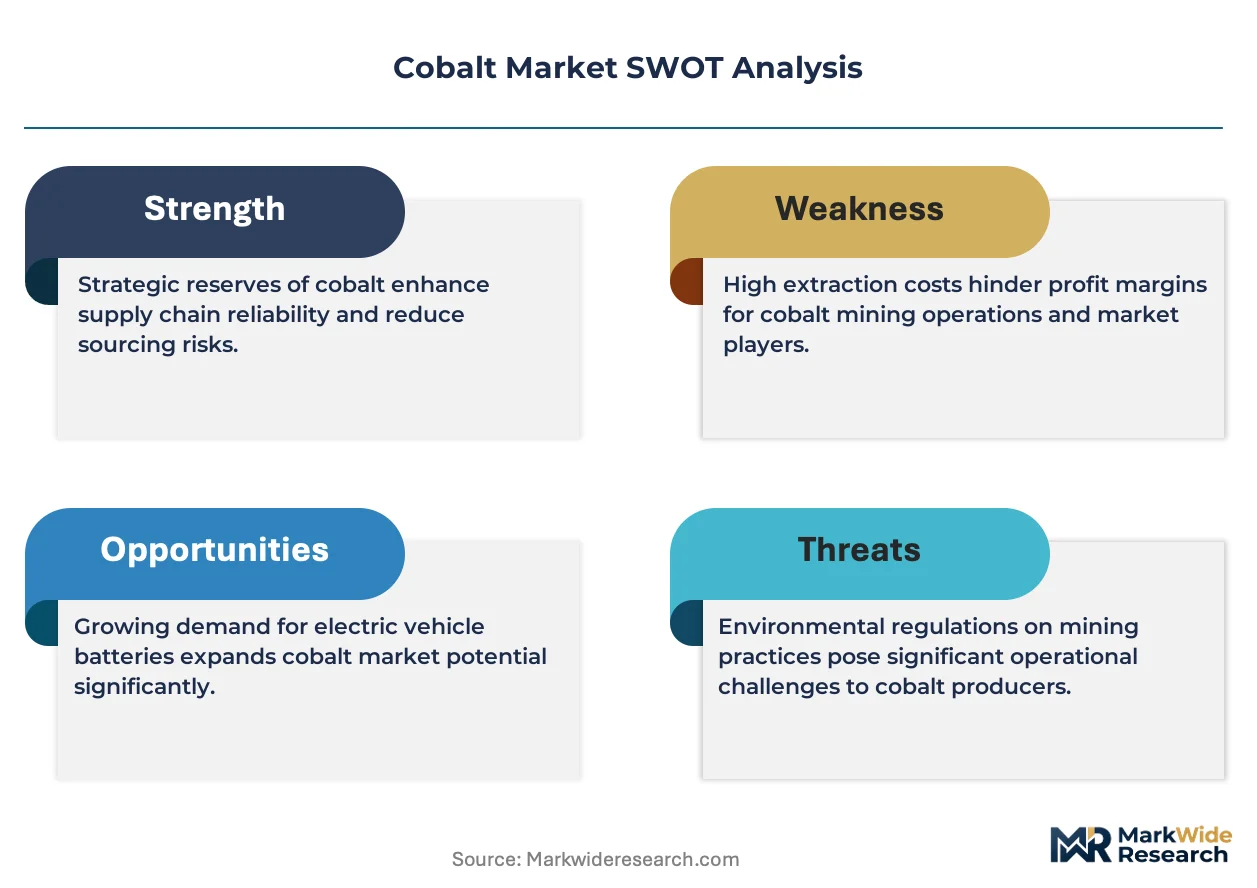
High-nickel cathode chemistry migration is compressing cobalt intensity per kilowatt-hour while absolute battery demand expansion sustains volume pull, creating a structural tension between unit economics and feedstock security.
Growth Catalysts
- EU Battery Regulation due diligence mandates:The regulation's chain-of-custody disclosure requirements are filtering artisanal supply from formal procurement channels, consolidating demand around certified industrial producers.
- China's MIIT new energy vehicle credit system:Domestic OEMs are accelerating cobalt sulfate offtake to secure cathode precursor qualification under tightening domestic content rules.
- Superalloy thermal stability specifications:Aerospace turbine blade manufacturers are specifying higher-purity cobalt metal for next-generation engine platforms operating at elevated temperatures.
Market Restraints
- Congolese mining code fiscal terms:Royalty escalations and profit-sharing revisions at the Tenke Fungurume complex are elevating all-in cost structures for integrated miners.
- Lithium iron phosphate substitution:Battery cell producers are qualifying cobalt-free cathode chemistries for entry-range electric vehicle segments, compressing addressable demand.
- ISO 14001 certification scarcity:Environmental management system gaps across Central African Copperbelt artisanal operations are excluding substantial feedstock volumes from battery-grade supply pools.
Strategic Opportunities
- Indonesian nickel-cobalt laterite integration:Hydrometallurgical processing investments are creating captive cobalt hydroxide supply for precursor plants serving Korean and Japanese cathode manufacturers.
- Closed-loop battery recycling mandates:China's GB standards on recycled content minimums are stimulating secondary cobalt sulfate capacity expansion to displace mined feedstock.
- Solid-state electrolyte convergence:Sulfide-based solid-state battery architectures are specifying cobalt-rich cathode interfaces for ionic conductivity optimization.
Industry Challenges
- Metallurgical assay standardization:Discrepancies between Chinese GB and ASTM testing protocols for cobalt sulfate purity are delaying qualification timelines for cross-border shipments.
- Artisanal mining formalization capex:Upgrading creuseur operations to meet OECD due diligence guidance requires capital deployment that informal cooperatives cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cobalt Market |
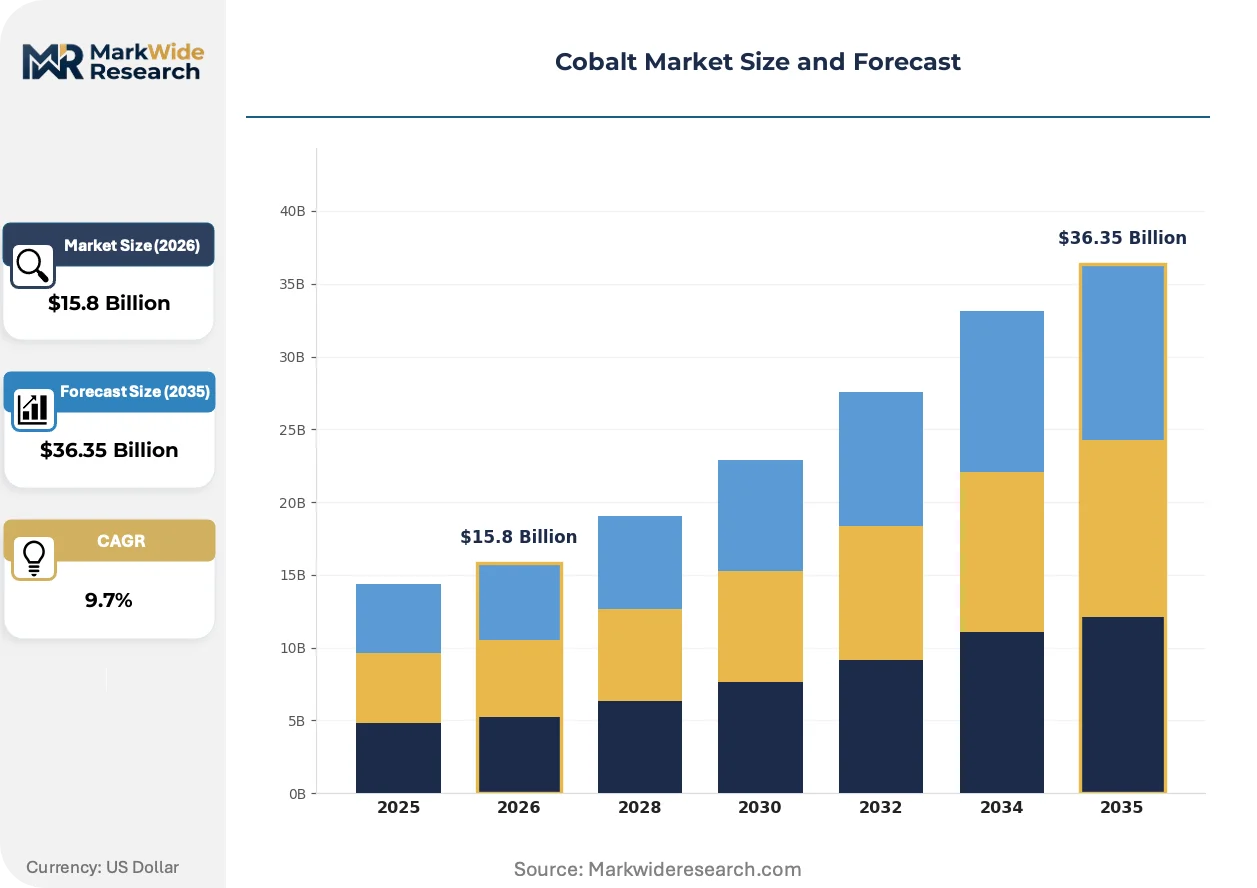
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $36.35 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cobalt Hydroxide, Cobalt Sulfate, Cobalt Carbonate, Cobalt Metal End Use Industry: Electronics, Aerospace, Automotive Batteries, Renewable Energy Application: Catalyst, Pigment, Superalloys, Magnetic Materials Form: Powder, Granule, Sheet, Alloy |
| Companies Covered | Vale S.A., Freeport-McMoRan, Glencore, Sherritt International, Wheaton Precious Metals, BHP Group, CMOC Group, Talon Metals, Rio Tinto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cobalt Market Strategic Shifts & Innovations
Process metallurgy and regulatory architecture are jointly restructuring how cobalt moves from ore to cathode, with chemistry innovation and compliance technology converging to redefine competitive positioning.
Direct solvent extraction flowsheets are decomposing the traditional leaching-precipitation-solvent extraction sequence for cobalt-copper separation. Glencore's Kamoto Copper Company and CMOC's Tenke Fungurume operations are piloting circuits that bypass intermediate hydroxide precipitation. This technology is decomposing working capital requirements and reagent consumption benchmarks across Central African refining infrastructure.
REACH authorization requirements for cobalt metal and compounds are tightening downstream user obligations across EU battery and aerospace supply chains. ECHA's 2023 inclusion of cobalt salts on the candidate list is forcing cathode manufacturers to document substitution feasibility or secure authorization for continued use. German and French precursor plants are accelerating supply chain mapping to pre-empt authorization bottlenecks.
Automotive OEMs are consolidating cathode procurement under long-term offtake agreements with integrated miners, displacing spot-market traders from high-volume battery-grade transactions. Tesla, BMW, and Volkswagen Group are negotiating direct cobalt sulfate supply from Glencore and CMOC with embedded price collars. This pattern is most pronounced in European and North American electric vehicle programs where ESG disclosure requirements demand named-source transparency.
Cobalt Market Segmentation
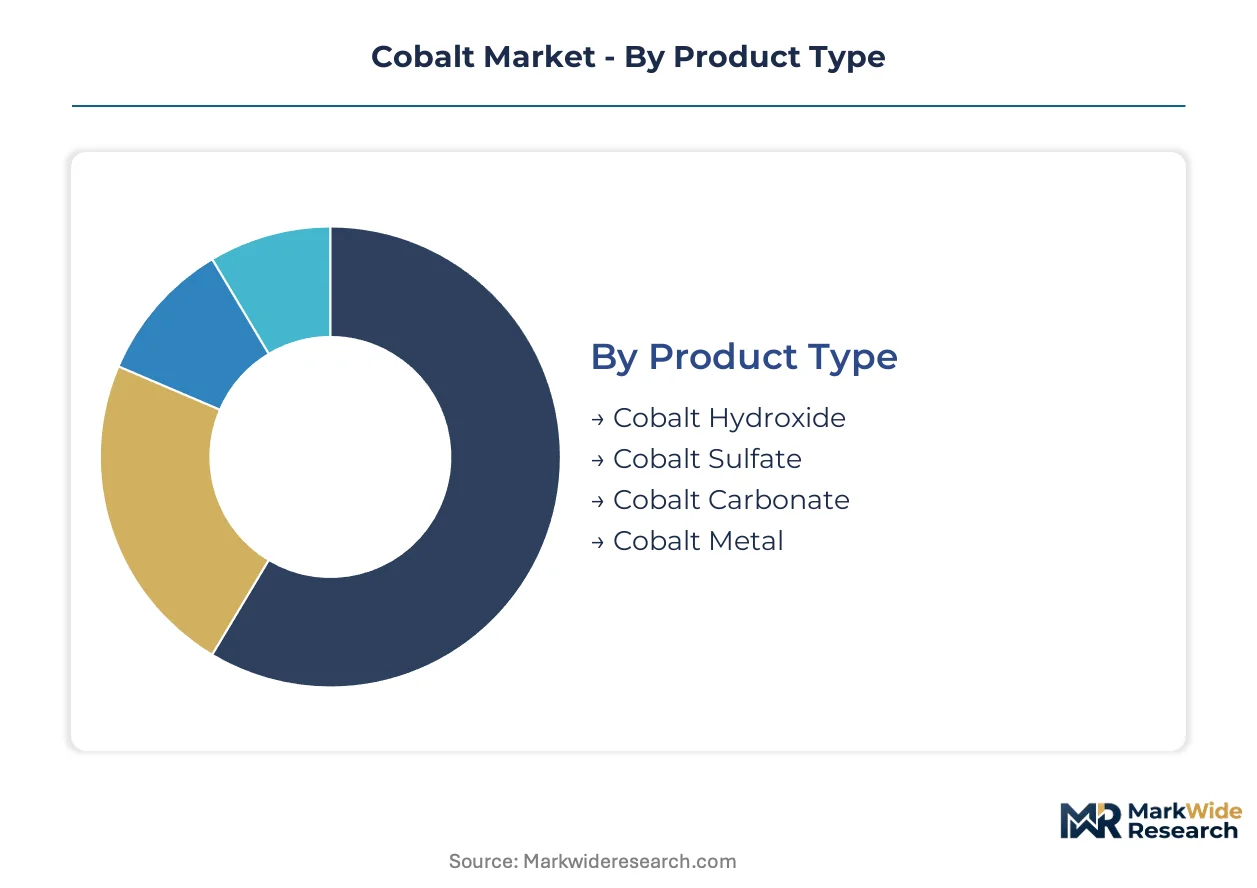
Cobalt's commercial value hinges on chemical form and purity grade, with battery-grade specifications diverging sharply from aerospace and industrial applications. Segmentation reveals how regulatory frameworks and end-use qualification standards partition the supply base into discrete procurement channels with incompatible certification requirements.
Product Type:
REACH authorization and China's GB standards on recycled content are bifurcating product qualification pathways, with battery-grade salts facing stricter chain-of-custody documentation than metal or industrial compounds.
- Cobalt Sulfate:This hexahydrate salt dominates cathode precursor synthesis for high-nickel lithium-ion batteries, with purity thresholds typically exceeding 20.5% cobalt content. Demand concentrates in Chinese precursor plants supplying Korean and Japanese cathode manufacturers, driven by EU Battery Regulation due diligence mandates that exclude uncertified feedstock.
- Cobalt Metal:Electrowon or broken cathode forms serve superalloy and aerospace turbine blade specifications requiring 99.3%+ purity. Procurement clusters around US and European aerospace primes, constrained by ECHA candidate list inclusion that forces substitution feasibility documentation.
- Cobalt Hydroxide:Intermediate feedstock for sulfate and metal refining routes across Central African Copperbelt operations.
- Cobalt Carbonate:Ceramic pigment and catalyst applications with lower purity tolerances than battery-grade specifications.
Cobalt sulfate handles the majority of throughput; cobalt metal is the fastest mover on share as aerospace thermal stability specifications tighten.
End Use Industry:
Cost tier differentiation separates premium qualification requirements from price-sensitive volume applications.
- Automotive Batteries:High-nickel cathode chemistries specify cobalt sulfate for energy density and thermal runaway prevention. Korean cell producers and Chinese OEMs anchor procurement volume, though lithium iron phosphate substitution compresses addressable demand in entry-range electric vehicle segments.
- Aerospace:Single-crystal superalloy turbine blades mandate cobalt metal for creep resistance at elevated operating temperatures. US and European engine manufacturers dominate offtake, with next-generation platform specifications driving purity threshold escalation.
- Electronics:Portable device batteries and magnetic components with moderate cobalt intensity per unit.
- Renewable Energy:Stationary storage applications where lithium iron phosphate chemistry displacement limits cobalt penetration.
Automotive batteries commands the steepest expansion trajectory; aerospace maintains premium pricing power through specification lock-in.
Application:
Volume concentration favors battery and superalloy offtake over mature, price-sensitive consumption pools.
- Superalloys:Nickel-cobalt-chromium formulations for gas turbine hot-section components requiring oxidation resistance above 1000°C. Demand clusters at GE Aerospace, Pratt & Whitney, and Rolls-Royce supply chains, with qualification timelines exceeding 24 months for new material sources.
- Catalyst:Petroleum refining hydrodesulfurization and chemical synthesis applications. Chinese and US Gulf Coast refiners anchor consumption, though platinum group metal substitution pressures long-term share.
- Pigment:Ceramic and glass colorants with thinning margins as Chinese oversupply compresses pricing.
- Magnetic Materials:Samarium-cobalt permanent magnets for high-temperature motor applications with limited volume growth.
Superalloys retains the highest margin structure; catalyst applications face substitution headwinds from alternative metal systems.
Form:
Supply chain configuration directly links physical form to downstream processing economics and transportation cost structures.
- Powder:Atomized or reduced metal powders for additive manufacturing and powder metallurgy applications. German and US aerospace suppliers drive specification development, with spherical morphology requirements for electron beam melting processes.
- Alloy:Master alloys and welding consumables for superalloy foundry feedstock. European and Japanese precision casting operations concentrate demand.
- Granule:Intermediate sizing for chemical processing and catalyst manufacturing.
- Sheet:Rolled products for limited specialty applications with minimal volume contribution.
Powder captures the fastest share gains from additive manufacturing qualification; alloy forms maintain stable superalloy foundry throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Battery Regulation's chain-of-custody mandates are redirecting procurement flows toward jurisdictions with established certification infrastructure. National governments are deploying industrial policy to capture refining value and secure precursor supply for domestic battery manufacturing.
Democratic Republic of Congo
Artisanal mining cooperatives in Lualaba and Haut-Katanga provinces feed hydroxide concentrate to Chinese refineries. The country's mining code revisions impose royalty escalations on copper-cobalt byproduct streams. Kolwezi and Lubumbashi anchor the Copperbelt extraction cluster where CMOC and Glencore operate integrated assets.
China
Domestic OEMs accelerate cobalt sulfate offtake to secure MIIT new energy vehicle credit qualification. GB standards on recycled content minimums stimulate secondary cobalt sulfate capacity expansion. The Yangtze River Delta precursor plant cluster in Zhejiang and Jiangsu provinces processes hydroxide feedstock into cathode-grade salts for Korean and Japanese cell manufacturers.
Indonesia
Hydrometallurgical investments at nickel-cobalt laterite operations create captive hydroxide supply for precursor plants. The government's downstream beneficiation policies mandate domestic refining of critical mineral exports. Morowali Industrial Park in Central Sulawesi concentrates HPAL processing capacity serving Korean cathode manufacturer demand.
Finland
EU Battery Regulation due diligence requirements filter procurement toward OECD-compliant industrial suppliers. The Finnish Minerals Group anchors state-backed critical raw material processing infrastructure. Kokkola refinery operations supply battery-grade cobalt chemicals to European precursor plants under REACH authorization frameworks.
Canada
Nickel-cobalt byproduct streams from Ontario and Quebec hard-rock mining anchor North American superalloy metal supply. Federal critical minerals strategy funding supports cobalt sulfate refining project development. The Sudbury Basin and Abitibi-Témiscamingue region concentrate primary extraction capacity with downstream links to US aerospace supply chains.
Cobalt Market Key Industry Players
Player mix skews toward integrated mining-trading conglomerates with Central African Copperbelt asset control. Consolidation around vertically positioned operators with captive feedstock and refining infrastructure has displaced spot-market traders from high-volume battery-grade transactions. Two strategic archetypes dominate: diversified mining majors with nickel-cobalt byproduct streams and Copperbelt-focused copper-cobalt integrated producers. Competitive moves concentrate on long-term offtake anchoring with automotive OEMs and hydrometallurgical circuit upgrades to bypass intermediate hydroxide precipitation.
Among diversified mining majors, Vale S.A. and BHP Group occupy positions anchored by nickel-cobalt byproduct extraction from Canadian and Australian operations. Within the Copperbelt-integrated tier, Glencore and CMOC Group exemplify asset-heavy configurations with mining-trading infrastructure spanning extraction, concentrate marketing, and downstream chemical production. These archetypes represent alternative pathways to cathode precursor qualification under tightening chain-of-custody disclosure regimes.
| Leading Market Players |
|---|
| Vale S.A. |
| Freeport-McMoRan |
| Glencore |
| Sherritt International |
| Wheaton Precious Metals |
| BHP Group |
| CMOC Group |
| Talon Metals |
| Rio Tinto |
| Others |
Cost & Logistics Intelligence
Lithium iron phosphate chemistry migration simultaneously redraws procurement geography toward Indonesian nickel-cobalt laterite operations and compresses cobalt sulfate premiums in entry-range electric vehicle segments. This substitution dynamic severs the historical link between absolute battery demand growth and cobalt intensity, forcing suppliers to recalibrate pricing power around aerospace superalloy qualification rather than volume cathode offtake.
Pricing Analysis
Long-term offtake contracts with embedded London Metal Exchange indexation dominate cobalt sulfate transactions between integrated miners and automotive OEMs. Price differentiation rests on chain-of-custody certification tier and volume commitment scale, with EU Battery Regulation-compliant material commanding substantial premiums over uncertified hydroxide feedstock. Cost compression in battery-grade salts is intensifying because Indonesian HPAL output expands captive supply for Korean precursor plants. Entry-range electric vehicle cathode buyers exhibit highest price sensitivity, whereas aerospace turbine blade manufacturers accept premium cobalt metal pricing for 99.3%+ purity specifications.
Supply Chain Analysis
Inbound logistics costs from Dar es Salaam and Durban ports constrain Central African Copperbelt concentrate movements to Chinese refineries, with container availability volatility amplifying working capital requirements across the trade lane. Supply concentrates in the Democratic Republic of Congo for mined feedstock, China for refining capacity, and Indonesia for emerging nickel-cobalt laterite processing. The supply chain draws from copper-cobalt byproduct streams, nickel-cobalt laterite ore, and secondary battery recycling feedstock. Single-source vulnerability around Tenke Fungurume output concentration presents structural risk. Distribution runs through long-term offtake agreements with named-source disclosure rather than spot-market trader intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified cobalt sulfate supply with embedded chain-of-custody documentation represents the scarcest capability layer in this market, separating formal procurement channels from excluded artisanal volumes. Closing this certification gap demands capital deployment and technical assistance that informal cooperatives cannot access independently.
For Market Incumbents: Consolidate control over OECD-compliant feedstock streams through direct investment in Congolese mining code-compliant operations. CMOC and Glencore anchor positions by deepening backward integration into precursor plant partnerships with Korean cathode manufacturers. Lithium iron phosphate substitution in entry-range segments threatens volume-based revenue models, making aerospace superalloy qualification the priority defensive lever. Prioritize hydrometallurgical circuit upgrades that bypass intermediate hydroxide precipitation to defend processing margin structures. For New Entrants and Emerging Players: ISO 14001 certification fast-track programs offer the most penetrable entry point into European automotive battery supply chains excluded from incumbent long-term offtake structures. Target Finnish and Canadian refining jurisdictions where EU Battery Regulation and US SEC climate disclosure rules concentrate demand for compliant material. Indonesia's Morowali Industrial Park presents geographic white space for HPAL investments serving Japanese cathode manufacturer demand. Pursue joint venture structures with state-backed critical minerals infrastructure to overcome capital intensity barriers. For Investors and Strategic Acquirers: The market sits at a supply-fragmentation phase that favors vertically integrated operators with captive Central African assets and downstream chemical production. Long-term viability hinges on positioning ahead of solid-state battery chemistry convergence, where cobalt-rich cathode interfaces retain specification lock-in. Acquisition targets should screen for OECD due diligence compliance infrastructure and existing automotive OEM offtake relationships. Watch Indonesian nickel-cobalt laterite integration pace as the inflection signal for hydroxide pricing power transfer.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Captures margin migration from hydroxide to sulfate as Korean cathode manufacturers consolidate supply. |
| Long-term Offtake Agreement with Named-Source Disclosure | Satisfies EU Battery Regulation chain-of-custody mandates for BMW and Volkswagen Group procurement. |
| HPAL Circuit Investment at Indonesian Laterite Operations | Creates captive cobalt hydroxide supply independent of Central African Copperbelt concentrate flows. |
| ISO 14001 Certification Program for Artisanal Cooperatives | Expands qualified feedstock pool under OECD due diligence guidance for formal procurement channels. |
| Closed-loop Battery Recycling Capacity Expansion | Aligns with China's GB standards on recycled content minimums displacing mined cobalt sulfate. |
Research Approach
A standing panel of mine site engineers, cathode precursor plant procurement leads, aerospace turbine blade metallurgists, and EU regulatory compliance officers provided ongoing calibration across primary interview rounds. This practitioner input combined with customs trade data, SEC 10-K filings from diversified mining majors, ECHA REACH authorization databases, and MIIT new energy vehicle credit system disclosures. Bottom-up mine-level production estimates and top-down cathode demand modeling were triangulated to validate volume assumptions.
Consistency checks against external benchmarks verified that modeled outputs aligned with observed long-term offtake announcement patterns and refinery capacity utilization rates across the projection horizon. Segmentation dimensions included product type, end-use industry, application, and regional regulatory cluster. CAGRs were derived from slope-intercept fitting of annual volume trajectories. Industry-specific forecast inputs incorporated high-nickel cathode chemistry migration rates and solid-state battery architecture development timelines.
Underlying assumptions cover sustained electric vehicle penetration, OECD due diligence guidance enforcement, and REACH authorization pathway stability, with deviation risk concentrated in Congolese mining code fiscal revisions and lithium iron phosphate substitution acceleration. Forecasts reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Galvanized Steel Wire Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
Flat-Rolled Stainless Steel Market
Metals
Aluminum Extrusion Market
Metals
Steel Wire Market
Metals
North America Aluminum Casting Market
Metals
Global Tantalum Market
Metals
Global Stretch Spring Wire Market
Metals
Aluminum Slugs Market
Metals
GCC Aluminium Powder Market
Metals
Brazil Aluminum Market
Metals
Metal Finishing Market
Metals
Trivalent Chromium Finishing Market
Metals
Silver Cyanide Market
Metals
Aluminum Fluoride Market
Metals
US Metal Fabrication Market