
 Wear Steel Plate Market | 2026-2036
Wear Steel Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Wear Steel Plate Market Insights
The gap between premium quenched-and-tempered grades and commodity overlay products is hardening as mining majors tighten performance specifications while construction buyers prioritize cost. SSAB leverages its proprietary hardening process to dominate the premium tier in Nordic supply chains. ArcelorMittal sustains broad geographic coverage through integrated mills in Europe and Brazil. Bisalloy anchors the Asia-Pacific mid-market with specialized quenched plate for Australian quarry operations.
Wear steel plate denotes abrasion-resistant flat-rolled steel engineered with elevated carbon, chromium, and boron content, typically heat-treated to Brinell hardness ratings exceeding 400 HBW for protection against gouging and sliding wear in aggressive material-handling environments. Quenched and tempered grades command the deepest margin pools due to through-thickness hardness uniformity demanded by OEM crusher manufacturers. Hardfaced and overlay variants capture fastest volume growth in aftermarket refurbishment, where end users weld deposit layers onto degraded base structures rather than replacing entire fabrications. The thickness dimension stratifies sharply: 20 mm plate dominates mining truck body applications, while 6 mm and 10 mm gauges concentrate in agricultural implement and shredder housing segments.
ISO 15614 welding procedure standards and ASTM A514/A517 specifications govern fabrication compatibility and base material qualification, while China's SAMR enforces GB/T 24186 abrasion test protocols that filter out inconsistent suppliers. The EU's F-Gas Regulation indirectly pressures mining equipment OEMs to extend machinery service life, amplifying demand for durable wear components. Stakeholders must monitor how carbon border adjustments and evolving scrap-recycling rules reshape the cost structure of quenched plate versus overlay alternatives.
Market Dynamics
Mining equipment operators in Western Australia's Pilbara district are compressing replacement cycles for truck body liners, forcing suppliers to align production schedules with unplanned refurbishment demand rather than predictable OEM build programs.
Growth Catalysts
- EU F-Gas Regulation:Extended machinery service-life mandates amplify demand for durable wear components in European mining fleets.
- Overlay welding adoption:Australian quarry operators expand hardfaced plate procurement for bucket-lip refurbishment versus full replacement.
- China's GB/T 24186 tightening:SAMR enforcement of hardness consistency protocols filters inconsistent suppliers, consolidating qualified vendor pools.
Market Restraints
- Alloy input volatility:Chromium and boron price swings compress margins on quenched-and-tempered grades.
- Nordic supply concentration:Premium hardening capacity clusters in Scandinavia, creating geographic vulnerability.
- Overlay substitution threat:Hardfaced deposits on degraded base structures displace new plate fabrication in aftermarket channels.
Strategic Opportunities
- Brazilian iron ore expansion:Vale's Carajás operations drive demand for 20 mm truck body plate in South America.
- Digital thickness monitoring:IoT-enabled wear sensors create predictive replacement service models for fleet operators.
- India's PLI scheme:Domestic steel capability incentives attract overlay equipment investment for local refurbishment capacity.
Industry Challenges
- Welding procedure qualification:ISO 15614 certification timelines delay new grade qualification for OEM crusher manufacturers.
- Scrap-recycling rule adaptation:Evolving carbon border adjustments complicate cost modeling for quenched plate versus overlay alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wear Steel Plate Market |
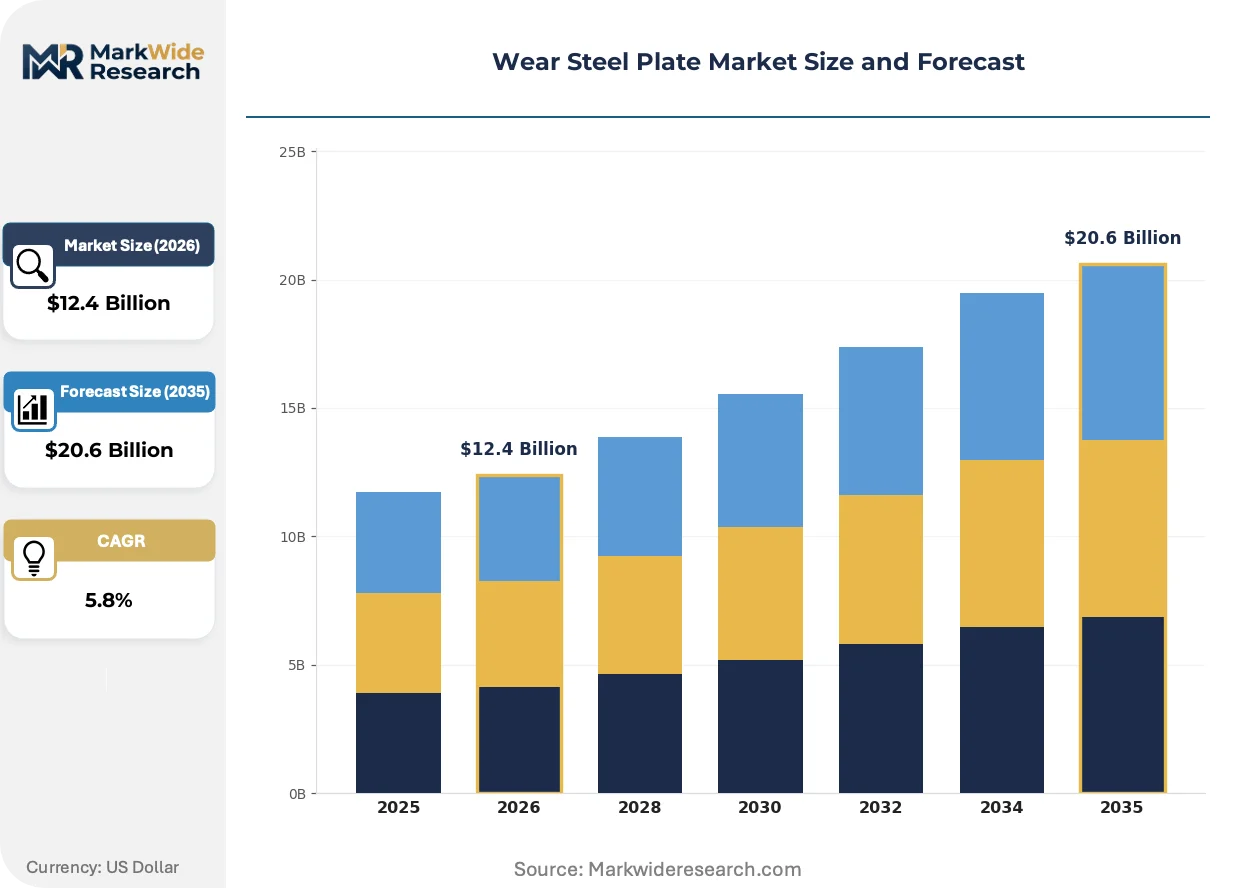
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quenched, Tempered, Hardfaced, Overlay Industry Vertical: Mining, Construction, Agriculture, Heavy Equipment Application: Excavators, Crushers, Dump Trucks, Shredders Thickness: 6 mm, 10 mm, 12 mm, 20 mm |
| Companies Covered | SSAB, ArcelorMittal, ThyssenKrupp, JFE, Dillinger, Nippon Steel, Bisalloy, Baosteel Group, ANSTEEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wear Steel Plate Market Trends and Innovations
Process integration between plate production and downstream fabrication is compressing lead times while regulatory pressure on embodied carbon reshapes material selection criteria across heavy equipment supply chains.
Direct quenching technology is unifying heat treatment and rolling operations into continuous lines. SSAB and JFE Steel deploy this process to achieve through-thickness hardness uniformity without separate reheating. Mining truck OEMs specify these grades for body liner contracts, compressing the traditional premium-commodity price spread.
China's SAMR is tightening GB/T 24186 abrasion test protocols to eliminate hardness variation in imported plate. Domestic mills must recalibrate quenching systems to meet batch consistency thresholds. Australian mining procurement teams now require mill test certificates verifying compliance before contract award.
Fleet operators are bundling wear plate supply with refurbishment service contracts rather than purchasing material separately. Komatsu and Caterpillar dealers capture this shift through integrated bucket rebuild programs. Western Australia's Pilbara contractors lead this transition, prioritizing equipment availability over unit material cost.
Wear Steel Plate Market Segmentation
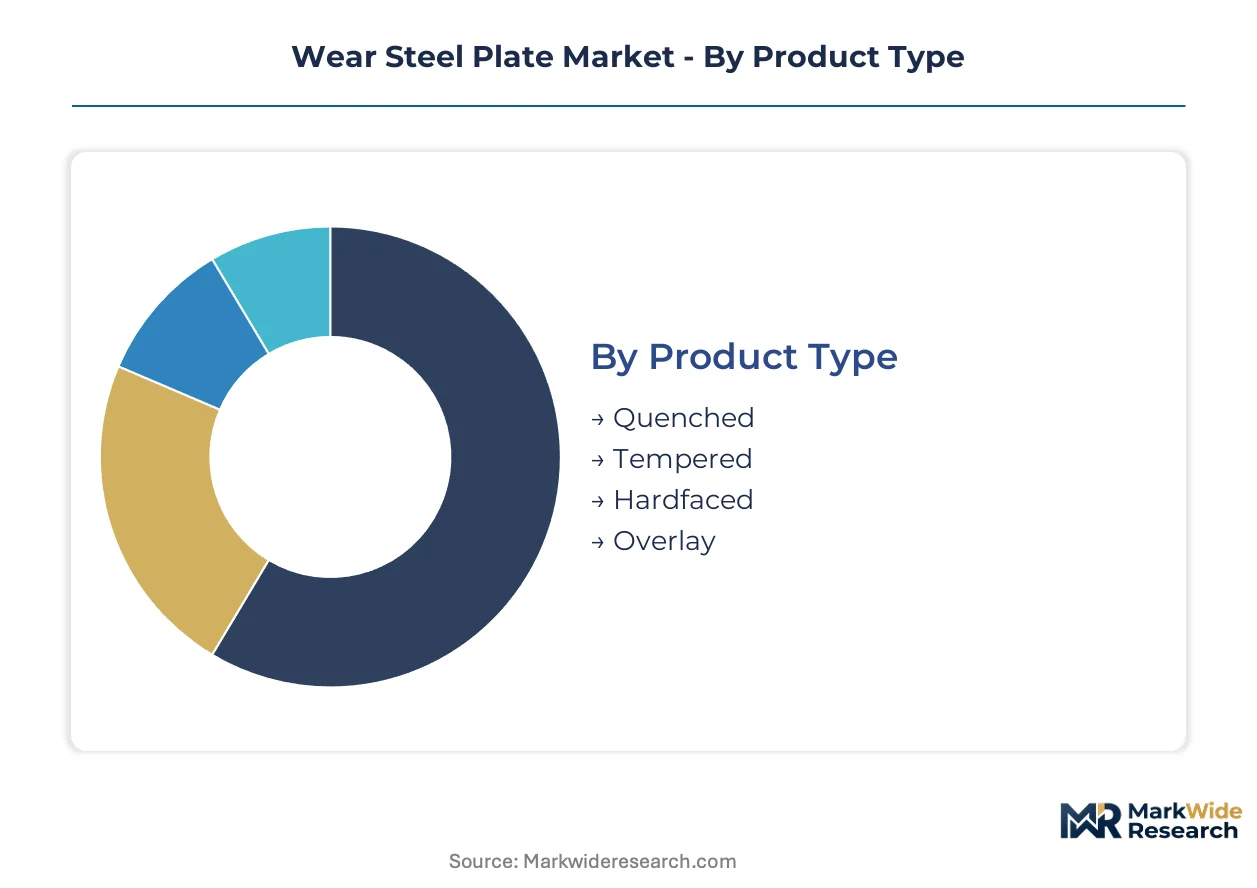
Wear steel plate procurement splits sharply between premium heat-treated grades for OEM builds and cost-optimized overlay products for aftermarket refurbishment. Thickness and hardness specifications vary dramatically across mining truck bodies, agricultural implements, and crushing equipment, creating distinct margin pools that suppliers must navigate simultaneously.
Product Type:
Volume concentrates in overlay and hardfaced variants, while premium margins pool in quenched-and-tempered grades with through-thickness hardness uniformity.
- Quenched:Rapid cooling from austenitizing temperature produces martensitic microstructures exceeding 400 HBW surface hardness. Mining truck OEMs in Western Australia's Pilbara district specify these grades for body liner contracts due to predictable wear patterns under high-impact iron ore loading.
- Tempered:Controlled reheating after quenching optimizes toughness-to-hardness ratios for applications requiring resistance to cracking under cyclic stress. Crusher manufacturers demand these grades for jaw and cone crusher liners where fracture would trigger catastrophic downtime.
- Hardfaced:Weld-deposited alloy layers on mild steel substrates deliver abrasion resistance at 40-60% lower material cost than solid quenched plate.
- Overlay:Factory-applied chromium carbide deposits create composite plates with extreme surface hardness for bucket lip and chute applications.
Today's leader: Quenched grades. Tomorrow's challenger: Overlay variants expanding most quickly in Australian refurbishment channels.
Industry Vertical:
Application severity and equipment utilization rates separate mining's premium specifications from agriculture's cost-driven purchasing patterns.
- Mining:24/7 equipment operation in Pilbara iron ore and Brazil's Carajás district drives replacement cycles measured in months, not years. Specifications demand Brinell consistency across entire plate surfaces to prevent premature localized failure.
- Construction:Intermittent equipment use and mixed-material handling create demand for mid-tier tempered grades balancing abrasion resistance with weldability for field fabrication.
- Agriculture:Soil abrasion and crop residue handling dominate wear mechanisms for tillage implements and harvester components.
- Heavy Equipment:General material handling applications span forklift attachments to conveyor systems with moderate wear intensity.
Mining commands the steepest premium tier. Agriculture anchors volume at compressed margins.
Application:
Impact severity and material abrasiveness stratify specifications from high-energy crushing to moderate sliding wear.
- Excavators:Bucket lips and side cutters encounter gouging abrasion from rock and ore, driving demand for overlay products that can be field-rebuilt multiple times.
- Crushers:Jaw plates, cone mantles, and impactor bars require through-hardened quenched grades with hardness uniformity to prevent uneven wear profiles that reduce crushing efficiency.
- Dump Trucks:Body liners protect structural steel from sliding abrasion during ore transport and impact damage during loading.
- Shredders:Rotor knives and anvil plates in metal and waste recycling face high-temperature wear from friction and impact.
Crushers lock in premium pricing. Excavators drive overlay volume expansion.
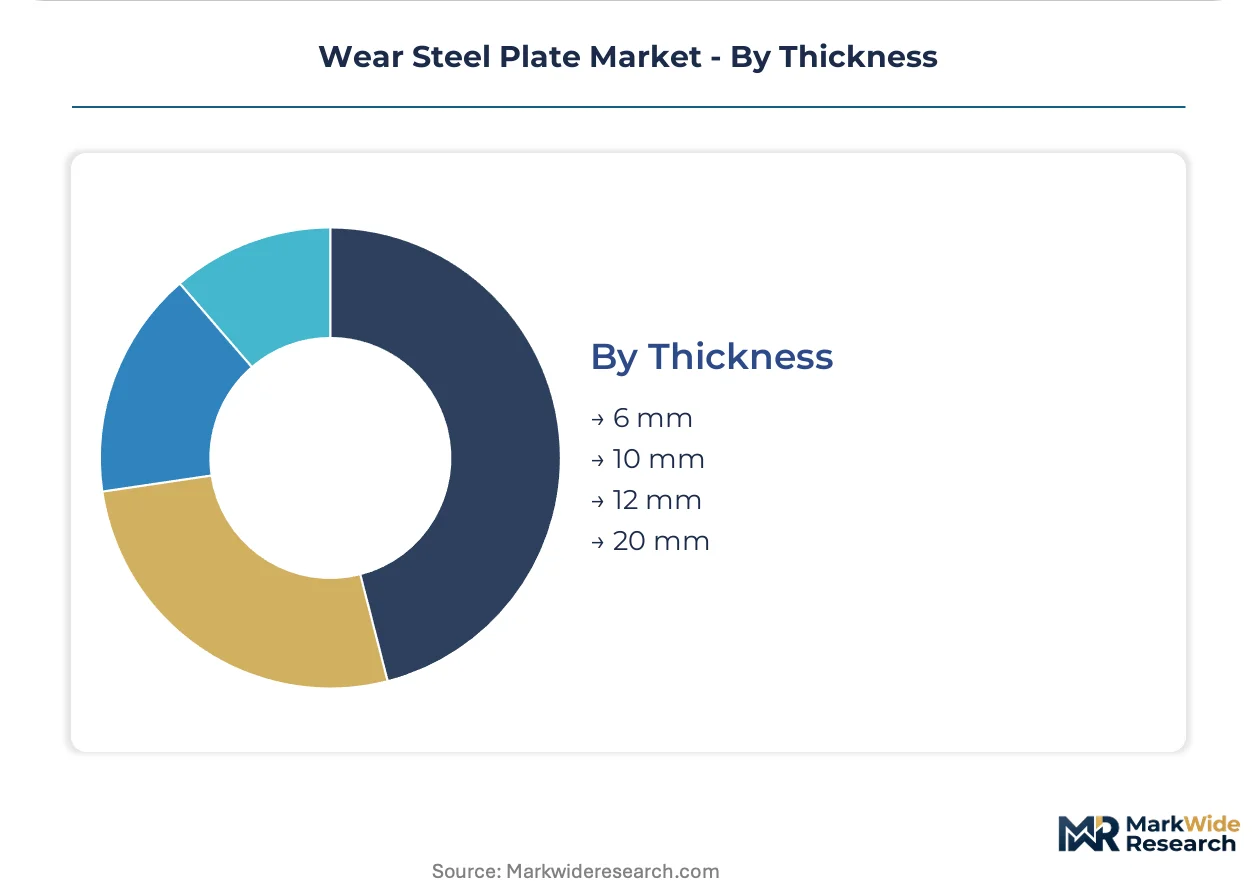
Thickness:
Structural load requirements and wear life targets create sharp stratification between heavy mining applications and lighter agricultural uses.
- 6 mm:Agricultural tillage points, shredder housings, and light-duty chute linings where weight minimization matters. Australian grain handling operations specify this gauge for conveyor skirt boards.
- 10 mm:General-purpose chutes, hopper liners, and medium-duty excavator bucket floors balancing wear life with fabricability.
- 12 mm:Transition thickness for heavy chutes and crusher feed boxes requiring extended service intervals without excessive weight.
- 20 mm:Mining truck body liners in Pilbara haul fleets and primary crusher dump pockets where impact energy and material volume demand maximum sectional strength.
20 mm dominates mining revenue. 6 mm and 10 mm aggregate highest unit volumes across diversified end-uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized metallurgical engineers concentrate in Australia's Pilbara district, Sweden's steel belt, and Germany's Ruhr industrial corridor, anchoring regional capability clusters that shape procurement patterns and technical specifications.
Australia
Mining operators in Western Australia's Pilbara iron ore district compress replacement cycles for truck body liners and bucket lips. The country's national resources regulator enforces equipment safety standards that mandate documented material traceability for critical wear components. Perth-based procurement teams now require mill test certificates verifying GB/T 24186 hardness consistency before contract award to Chinese suppliers.
China
Domestic steel mills recalibrate quenching systems to meet SAMR's tightened batch consistency thresholds under GB/T 24186 protocols. The Ministry of Ecology and Environment's dual carbon goals pressure producers to optimize energy-intensive heat treatment operations. Shanghai and Tangshan industrial clusters filter inconsistent suppliers from qualified vendor pools serving Australian mining procurement teams.
Sweden
SSAB's proprietary direct quenching technology anchors premium-grade production for Nordic mining equipment supply chains. The country's national environmental agency enforces stringent emissions standards on steel production that favor continuous heat treatment integration. Oxelösund and Luleå production facilities dominate European quenched-and-tempered plate supply for crusher OEM specifications.
Brazil
Vale's Carajás iron ore expansion drives demand for 20 mm truck body plate specifications in South American mining fleets. The country's national mining regulator enforces tailings dam safety standards that extend to material handling equipment durability requirements. Belo Horizonte equipment dealers bundle wear plate supply with refurbishment service contracts for fleet operators.
Germany
Construction machinery OEMs in Baden-Württemberg specify mid-tier tempered grades balancing abrasion resistance with field weldability. The EU F-Gas Regulation's extended machinery service-life mandates amplify demand for durable wear components in European mining fleets. Duisburg and Dortmund fabrication clusters process imported quenched plate for crusher liner applications serving Central European quarry operations.
Wear Steel Plate Market Competitive Landscape
Capital-heavy integrated mills compete with specialized quenching specialists and overlay fabrication shops across distinct capability tiers. The vendor base stratifies sharply between premium through-hardened producers, mid-market regional suppliers, and cost-driven hardfacing operations. Three archetypes dominate: Nordic technology leaders with proprietary heat treatment, Asian integrated mills with scale advantages, and Australian regional specialists with refurbishment service integration. Competitive moves center on direct quenching technology licensing and predictive maintenance service bundling.
Among Nordic-based metallurgical specialists, SSAB exemplifies the premium-tier archetype through proprietary process control. ArcelorMittal occupies a position spanning multiple capability levels through geographically distributed integrated capacity. Bisalloy represents the regional specialist model with Australian quarry market anchoring. These three names illustrate how competitive positioning fragments across technology leadership, scale breadth, and service integration vectors.
| Leading Market Players |
|---|
| SSAB |
| ArcelorMittal |
| ThyssenKrupp |
| JFE |
| Dillinger |
| Nippon Steel |
| Bisalloy |
| Baosteel Group |
| ANSTEEL |
| Others |
Pricing and Supply Chain Analysis
Mining fleet operators in Western Australia's Pilbara district concentrate procurement volumes through bundled service contracts rather than spot material purchases, compressing the traditional premium-commodity price spread across heat-treated grades. This buyer concentration shifts pricing power toward suppliers with integrated refurbishment capabilities.
Pricing Analysis
Bundled service contracts versus unbundled material-only transactions define the dominant pricing split. Three-tier pricing structure across premium quenched grades, standard tempered products, and economy overlay levels separates OEM crusher manufacturers from aftermarket refurbishment channels. Pricing pressure stems from chromium and boron alloy input volatility squeezing margins on through-hardened grades. Construction buyers exhibit highest price sensitivity, while mining majors prioritize hardness consistency over unit cost.
Supply Chain Analysis
Regional distribution centers in Perth, Duisburg, and Shanghai anchor hub-and-spoke patterns for plate delivery to fabrication clusters. Supply concentrates in Sweden, Germany, and China for premium heat treatment capacity, with Australia and Brazil hosting downstream refurbishment operations. Production draws from iron ore, chromium, and boron feedstocks vulnerable to commodity price swings. Single-source vulnerability in Nordic hardening technology creates geographic risk concentration. Distribution runs through mill-direct contracts for OEMs and dealer networks for aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wear steel plate procurement is shifting toward margin expansion as direct quenching technology reduces energy-intensive reheating costs while mining specifications harden premium-tier requirements.
For Market Incumbents: Hedge against overlay substitution by securing proprietary hardening technology licenses before Chinese mills achieve GB/T 24186 consistency thresholds. Backward integration into chromium carbide welding consumables defends service bundling margins against independent hardfacing shops. Capacity expansion in Brazilian distribution networks captures Vale's Carajás truck body plate demand. For New Entrants and Emerging Players: IoT-enabled wear thickness monitoring offers a technology-first wedge into predictive replacement service models. Australian quarry contractors present the most penetrable white-space target given their compressed replacement cycles and limited incumbent service integration. Partner with Komatsu or Caterpillar dealers for integrated bucket rebuild program access. For Investors and Strategic Acquirers: Mining equipment OEMs are the most active acquirer in this space, seeking captive wear component supply. Long-term viability hinges on quenching technology differentiation rather than commodity overlay volume. Watch for SAMR decertification events filtering Chinese suppliers from Australian procurement pools as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Quenching Technology Licensing | SSAB and JFE Steel deploy continuous heat treatment lines that unify rolling and hardening operations. |
| Refurbishment Service Integration | Komatsu and Caterpillar dealers bundle wear plate supply with predictive maintenance contracts. |
| GB/T 24186 Compliance Investment | Chinese mills recalibrate batch consistency to meet Australian mining procurement certificate requirements. |
| Brazilian Distribution Expansion | Vale's Carajás iron ore operations drive 20 mm truck body plate specifications in South American fleets. |
| Overlay Welding Capacity Buildout | Hardfaced deposits on degraded base structures displace new plate fabrication in aftermarket channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with maintenance directors at Pilbara mining operations, OEM procurement teams at crusher manufacturers, aftermarket service heads at equipment dealers, and technical R&D directors at steel mills informed demand-side dynamics. Secondary validation drew from customs trade data, SEC filings of listed steel producers, ISO 15614 welding procedure registries, and SAMR GB/T 24186 compliance notices. Bottom-up volume estimates triangulated against top-down steel industry capacity assessments.
Comparable historical periods anchored the projection horizon across product type, thickness specification, industry vertical, and regional production hub dimensions. CAGRs derived from regression analysis of replacement cycle compression rates and overlay adoption curves. Hardness consistency thresholds under tightening Chinese protocols and fleet operator service bundling preferences served as key forecast inputs.
The model holds under stable alloy input pricing and continued mining equipment utilization rates; deviation in chromium volatility or Chinese export permit restrictions would shift volume projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Oxygen-Free Copper Market
Metals
Chrome Metal Powder Market
Metals
Global Nickel Alloy Welding Consumables Market
Metals
Global Copper Market
Metals
Metallic Rope Cords Market
Metals
Global Ultra-Low Alpha Metal Market
Metals
Ore Metals Market
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market
Metals
High Carbon Bearing Steel Market
Metals
Silver Powder and Flakes Market
Metals
Electrolytic Manganese Metal Market
Metals
Steel Ingots Market
Metals
Molybdenum Market
Metals
Global High Purity Titanium Powder Market
Metals
High Purity Base Metals Market
Metals
Titanium Mill Products Market