
 France Engineering Plastics Market | 2026-2036
France Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
France Engineering Plastics Market Insights
Aftermarket recycling and recompounding of engineering-grade polymers is reshaping margin distribution across the France engineering plastics value chain. Arkema leverages its vertically integrated specialty polyamide production to capture premium positions in high-performance applications. Solvay sustains technology leadership through fluoropolymer and sulfone polymer expertise for aerospace and healthcare segments. BASF SE anchors its competitive position with Ultramid polyamide compounds serving automotive OEMs in the Grand Est region.
Engineering plastics encompass thermoplastic polymers engineered to withstand mechanical loads, thermal stress, and chemical exposure beyond commodity plastic capabilities, typically exhibiting tensile strengths exceeding 40 MPa and continuous service temperatures above 100°C for structural reliability in demanding industrial environments. Polyamide dominates volume consumption in France due to its fatigue resistance and compatibility with glass-fiber reinforcement for under-hood automotive applications. Polycarbonate captures premium pricing in electrical and electronics housing where optical clarity and flame retardancy converge. Polyoxymethylene competes intensively in precision mechanical parts for consumer goods, though margin compression from Asian imports constrains domestic producers.
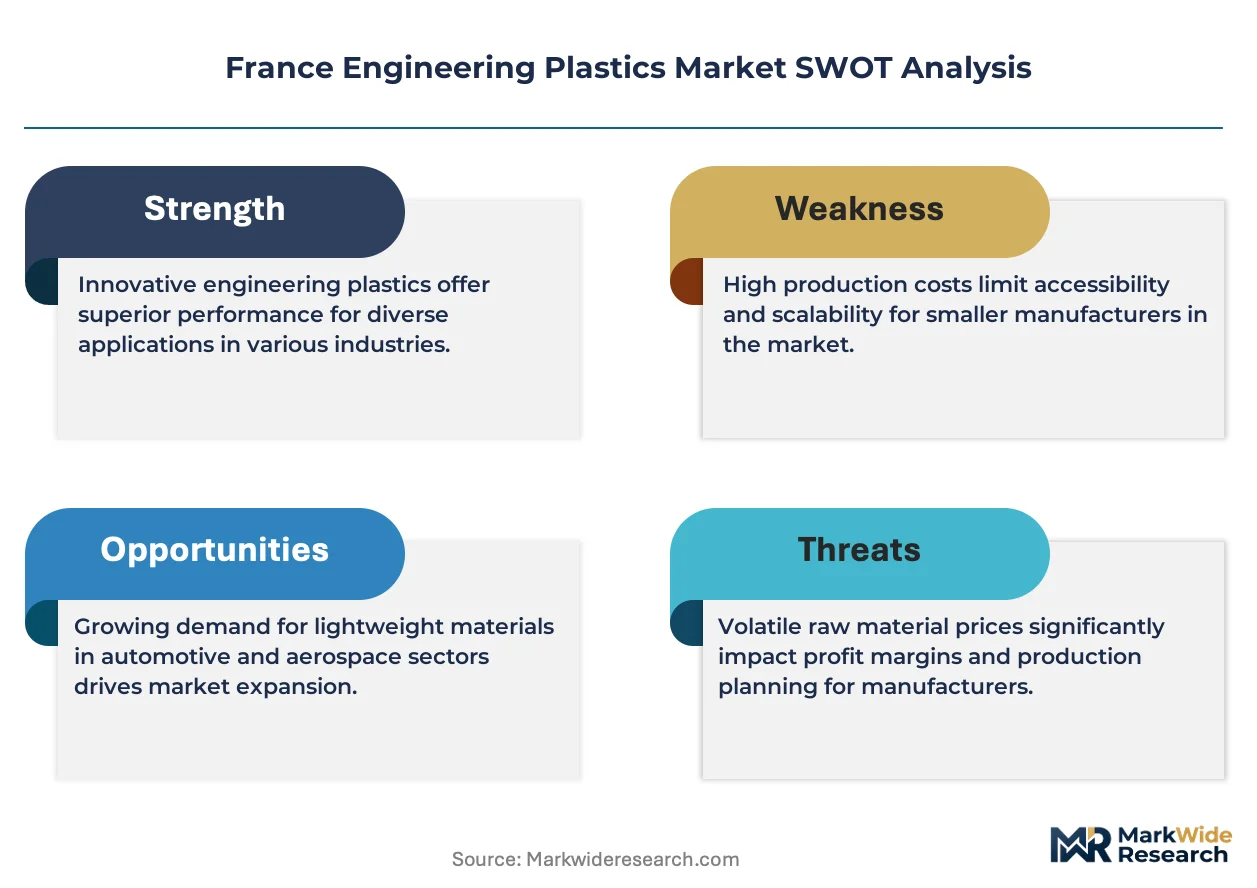
REACH registration requirements and the EU Green Deal's carbon border adjustments are tightening material traceability and recyclability standards for engineering plastics sold into French manufacturing channels. ANSM guidelines for medical-grade polymers and ECHA restrictions on per- and polyfluoroalkyl substances further narrow the approved substance lists for healthcare and food-contact applications. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in mechanical recycling infrastructure or partner with specialized recompounders to maintain market access under tightening circular economy mandates.
Market Dynamics
REACH registration deadlines and EU Green Deal carbon border adjustments are forcing French compounders to requalify entire product portfolios, accelerating substitution of virgin feedstocks with mechanically recycled engineering-grade polymers across automotive and electrical supply chains.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in the Grand Est region are specifying glass-fiber reinforced polyamide for battery housings and structural under-hood components to meet fleet CO₂ reduction targets.
- ECHA restrictions on PFAS:Per- and polyfluoroalkyl substance phaseouts are redirecting aerospace and healthcare procurement toward sulfone and polyaryletherketone alternatives with established safety dossiers.
- Rhône-Alpes industrial clustering:Concentrated specialty chemical infrastructure enables rapid prototyping and just-in-time compounding for precision mechanical parts serving medical device manufacturers.
Market Restraints
- Caprolactam price volatility:Polyamide feedstock costs fluctuate with benzene and ammonia input markets, compressing margin visibility for domestic compounders serving price-sensitive automotive tiers.
- Asian POM import penetration:Polyoxymethylene resin from integrated producers in East Asia arrives at French ports at 15-20% below domestic production cost, crowding indigenous capacity.
- REACH data gap requirements:Substance information obligations for novel polymer additives extend registration timelines by 18-24 months, freezing formulation innovation for smaller compounders.
Strategic Opportunities
- Medical-grade polymer localization:ANSM guidance on implantable device biocompatibility creates demand for sulfone and polyetherimide compounds produced under ISO 13485 certification within French territory.
- Recompounding infrastructure gaps:Mechanical recycling of post-industrial polyamide and polycarbonate scrap remains underdeveloped in the Greater Paris manufacturing belt, offering first-mover positions for integrated recyclers.
- Hydrogen economy material specifications:Pressure vessel and fuel cell component standards are converging on high-barrier polyamide and fluoropolymer systems for Rhône-Alpes energy equipment suppliers.
Industry Challenges
- Polymer characterization expertise scarcity:Compounders struggle to recruit spectroscopy and rheology specialists capable of validating recycled-content grades for automotive OEM qualification protocols.
- Legacy injection molding asset retrofit costs:Processing equipment designed for virgin resins requires screw, barrel, and hot-runner modifications to handle moisture-sensitive recycled polyamide without degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Engineering Plastics Market |
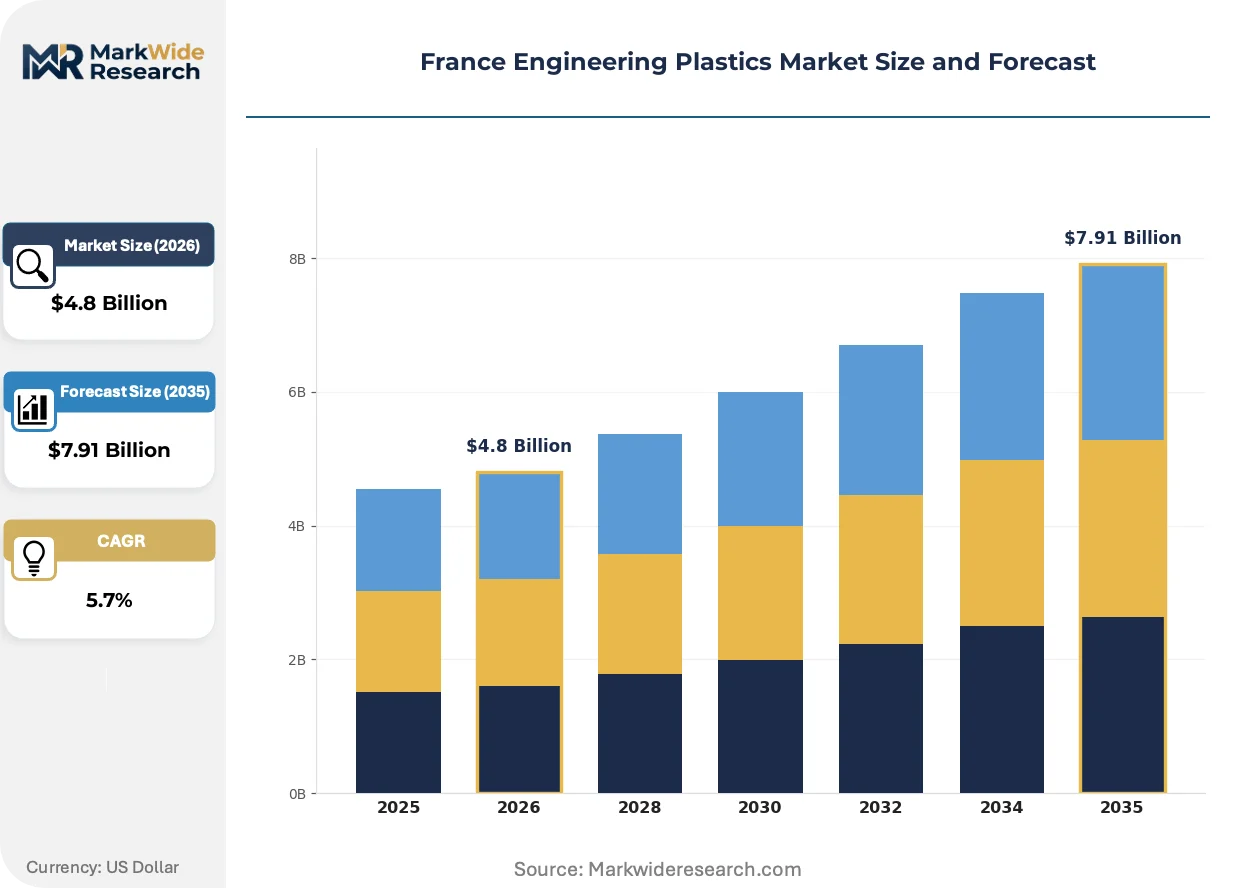
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Polyamide, Polyethylene Terephthalate, Polyoxymethylene End User: Aerospace, Automotive OEMs, Electrical & Electronics, Consumer Goods Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers Application: Structural Components, Insulating Parts, Housing, Mechanical Parts |
| Companies Covered | Arkema, Solvay, BASF SE, Covestro AG, Celanese Corporation, Domo Chemicals, DuPont, SABIC, INEOS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Engineering Plastics Market Trends and Innovations
Bio-based feedstock integration and closed-loop recycling systems are redefining material qualification pathways for French engineering plastics suppliers, with regulatory pressure and OEM sustainability targets converging on mass-balance certification schemes.
Hybrid polyamide-polyphenylene sulfide compounds are hybridizing thermal performance profiles for electric powertrain applications. Tier-1 suppliers in the Grand Est region are qualifying these materials for inverter housings and high-voltage connectors. This convergence is hybridizing the traditional segmentation between commodity polyamides and premium high-performance polymers, compressing intermediate price tiers.
EU Green Deal carbon border adjustment mechanisms are tightening documentation requirements for imported polymer feedstocks. French compounders must now verify embedded emissions across upstream naphtha and caprolactam supply chains. Medical device and food-contact segments face the steepest compliance burdens, driving domestic sourcing preferences for ANSM-registered materials.
Automotive OEMs are consolidating qualified supplier lists around vertically integrated compounders with in-house recycling capabilities. Tier-2 and tier-3 processors in the Greater Paris belt are losing access to specification-controlled applications. This concentration is most visible in battery electric vehicle programs, where Renault and Stellantis procurement teams mandate cradle-to-gate carbon footprint disclosures.
France Engineering Plastics Market Segmentation
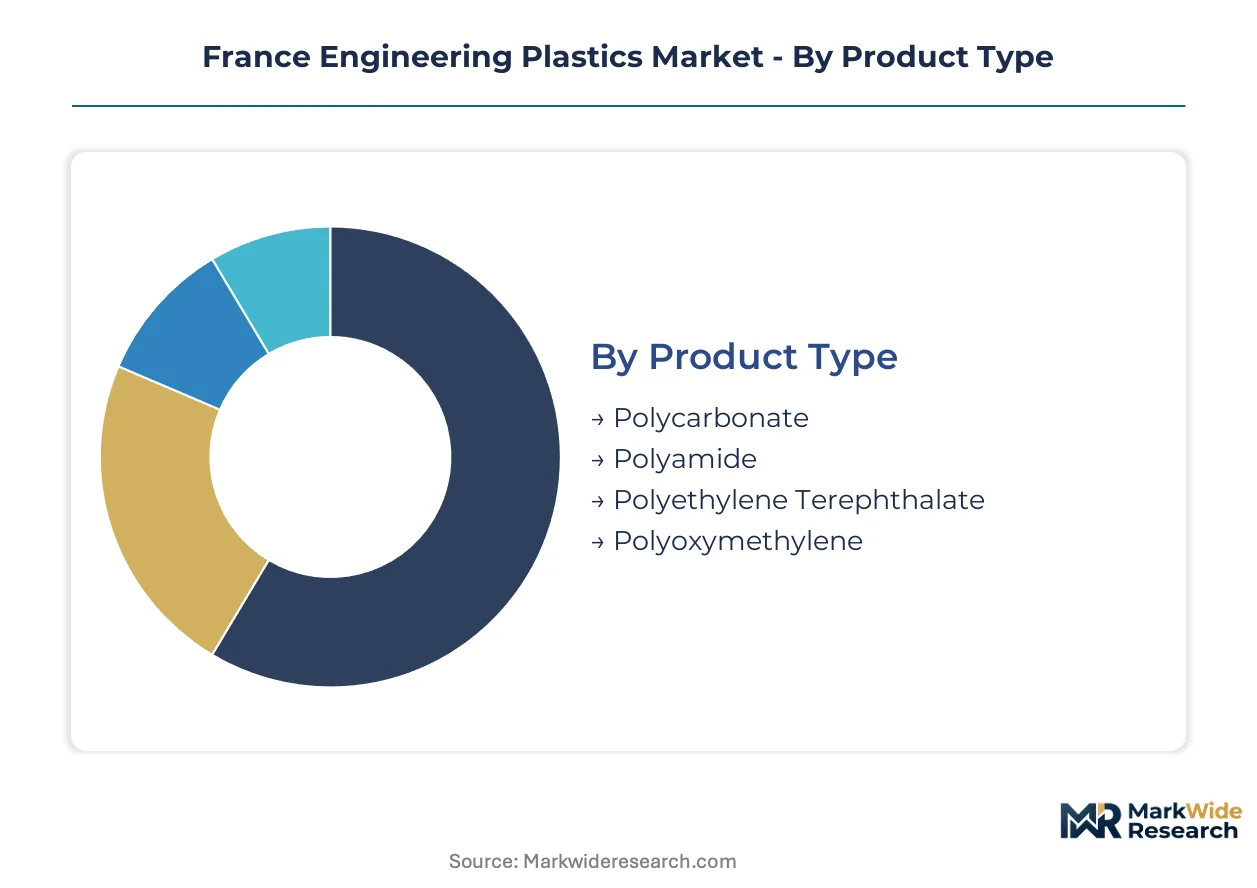
Engineering plastics demand in France fragments across performance tiers and supply chain configurations. Each segment carries distinct technical qualification requirements and margin profiles that reshape competitive positioning for compounders and distributors.
Product Type:
After-sales service intensity varies sharply across polymer chemistries, with high-performance grades requiring dedicated technical support for molding parameter optimization and failure analysis.
- Polyamide:Glass-fiber reinforced grades dominate fatigue-critical under-hood automotive applications. Rhône-Alpes compounders supply battery housing specifications for Stellantis and Renault electric platforms under stringent thermal cycling protocols.
- Polycarbonate:Optical clarity combined with inherent flame retardancy positions this resin for electrical housing and medical device transparency requirements. Greater Paris electronics manufacturers specify V-0 rated grades for server chassis and diagnostic equipment enclosures.
- Polyoxymethylene:Precision mechanical properties serve consumer goods and automotive fuel system components, though Asian import pressure constrains domestic recompounding margins.
- Polyethylene Terephthalate:Engineering-grade crystalline PET targets electrical insulating films and industrial fiber applications with dimensional stability requirements.
By volume, Polyamide leads. By growth pace, Polycarbonate is ahead.
End User:
Cost tier stratification separates specification-controlled aerospace procurement from price-sensitive consumer goods molding.
- Automotive OEMs:Lightweighting mandates drive glass-fiber polyamide adoption for structural components. Grand Est region battery electric vehicle programs require cradle-to-gate carbon footprint documentation from qualified compounders.
- Aerospace:Sulfone and fluoropolymer systems serve cabin interior and fuel system applications under EASA flame-smoke-toxicity standards. Solvay's Saint-Fons facility anchors domestic supply security for tier-1 aerostructures.
- Electrical & Electronics:Miniaturization trends push polycarbonate and polyamide into connector housings and circuit breaker components across Île-de-France industrial zones.
- Consumer Goods:Polyoxymethylene precision gears and sliding components face margin compression from integrated Asian producers serving appliance manufacturers.
Automotive OEMs command the largest volume share. Aerospace delivers the steepest expansion trajectory.
Distribution Channel:
Customer type segmentation separates multinational compounders with direct OEM relationships from regional distributors serving tier-2 processors.
- Direct Sales:Arkema and BASF SE maintain technical service teams embedded at major automotive and aerospace manufacturing sites for just-in-time compound delivery.
- Distributors:Regional specialists stock standard grades for Greater Paris injection molders requiring rapid lot-size flexibility without minimum order constraints.
- Wholesalers:Volume aggregation serves mid-tier processors in Lyon and Marseille industrial corridors with consolidated freight economics.
- Online Retail:Emerging channel targets prototype shops and research institutions requiring kilogram-scale samples with expedited fulfillment.
Direct Sales captures the premium tier. Distributors are gaining share fastest among small-batch processors.
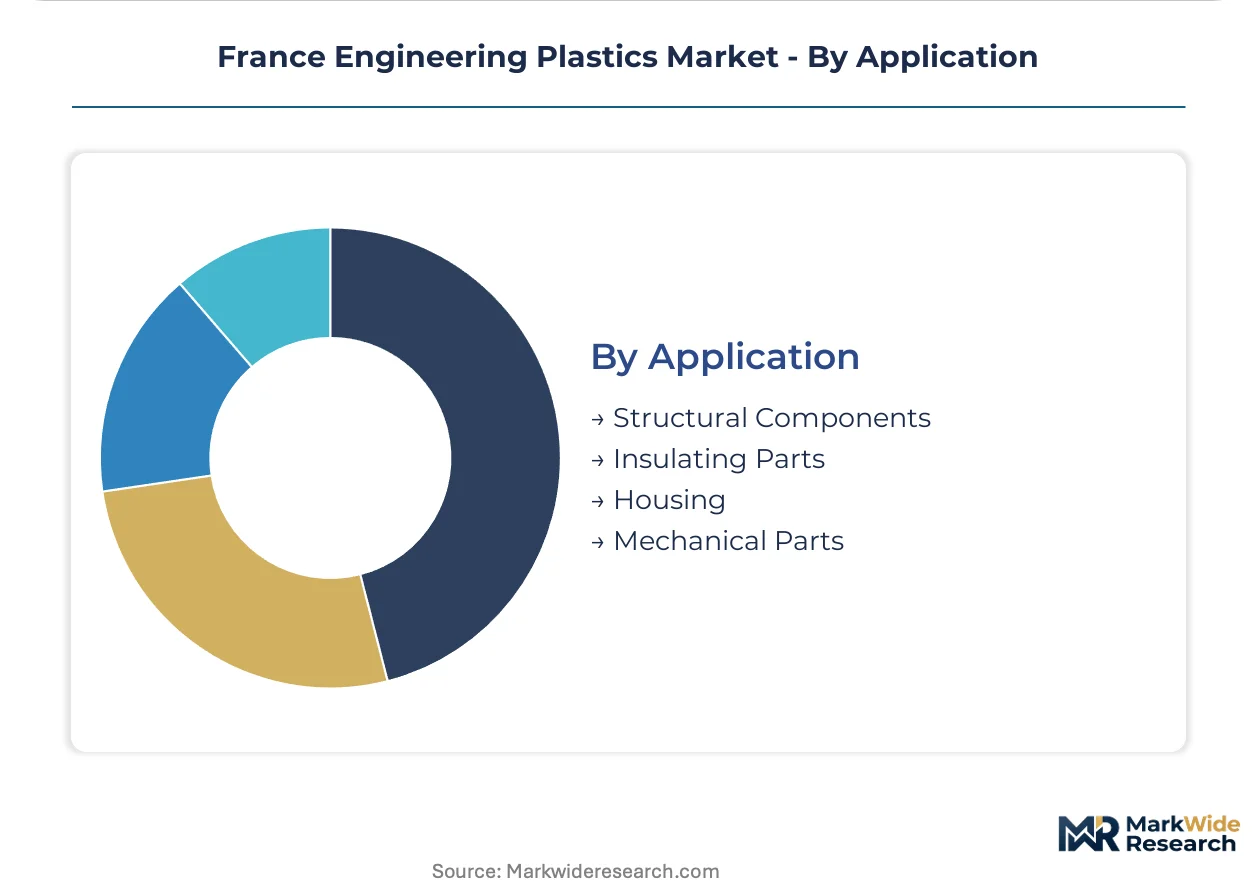
Application:
Application maturity determines qualification timeline intensity, with structural components requiring 18-24 month OEM validation cycles.
- Structural Components:Load-bearing polyamide and composite systems replace metal castings in automotive chassis and aerospace brackets. REACH carbon footprint documentation is mandatory for qualified supplier status.
- Housing:Polycarbonate enclosures for electrical and medical equipment combine aesthetic surface quality with IEC flame retardancy ratings.
- Mechanical Parts:Wear-resistant polyoxymethylene gears and bearings serve precision motion systems with tight dimensional tolerance requirements.
- Insulating Parts:Electrical grade polyamide and PET films separate high-voltage conductors in power distribution and electric powertrain architectures.
Structural Components leads by revenue concentration. Insulating Parts is expanding most quickly on electrification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's engineering plastics consumption patterns diverge from neighboring Germany and Italy, with automotive electrification driving polyamide demand while aerospace procurement concentrates fluoropolymer and sulfone grades in distinct supply corridors.
Île-de-France
Electrical and electronics manufacturing clusters in the Greater Paris belt specify flame-retardant polycarbonate for server chassis and diagnostic enclosures. ANSM medical device regulations tighten biocompatibility documentation for implantable-grade polymers sourced by Saint-Denis medical technology firms. Research institutions in Saclay accelerate prototyping cycles for next-generation insulating compounds.
Auvergne-Rhône-Alpes
Battery electric vehicle programs at Stellantis and Renault facilities drive glass-fiber reinforced polyamide consumption for thermal management housings. EU Green Deal carbon border adjustments force requalification of imported caprolactam feedstocks at Lyon-area compounders. The Grenoble-Saint-Étienne corridor anchors specialty polymer R&D for hydrogen pressure vessel applications.
Grand Est
Automotive OEM lightweighting mandates specify structural polyamide components to meet fleet CO₂ reduction targets under French energy transition law. REACH registration deadlines compress formulation timelines for Strasbourg-area compounders serving tier-1 suppliers. The Mulhouse-Belfort manufacturing zone concentrates precision molding capacity for under-hood applications.
Provence-Alpes-Côte d'Azur
Aerospace tier-1 procurement of sulfone and fluoropolymer systems supports cabin interior and fuel system programs under EASA flame-smoke-toxicity standards. Solvay's Saint-Fons facility maintains supply security for Airbus and Safran aerostructures. Marseille port logistics handle specialty resin imports for Mediterranean industrial corridors.
Hauts-de-France
Post-industrial polyamide and polycarbonate scrap accumulation from historic textile and automotive supply chains creates recompounding infrastructure opportunities. Extended producer responsibility frameworks under French circular economy law mandate recycling rate targets. Lille-Roubaix industrial zones lack integrated mechanical recycling capacity relative to feedstock availability.
France Engineering Plastics Market Competitive Landscape
Capability concentration sits with integrated specialty polymer producers; scale advantage sits with diversified chemical conglomerates with European compounding networks. The France engineering plastics market structures around three tiers: vertically integrated resin producers controlling feedstock-to-compound value chains; regional compounders with automotive OEM qualification status; and import-dependent distributors serving price-sensitive processors. Dominant competitive moves include backward integration into recycled feedstock sourcing and strategic partnerships with hydrogen economy equipment suppliers.
Within the integrated specialty tier, Arkema S.A. exemplifies European resin-to-compound control, while Solvay S.A. occupies a position anchored in high-performance fluoropolymer and sulfone expertise. BASF SE represents the diversified chemical conglomerate archetype with Ultramid polyamide compound production serving Grand Est automotive programs. These three companies collectively illustrate the capability-scale spectrum defining competitive positioning in French engineering plastics channels.
| Leading Market Players |
|---|
| Arkema |
| Solvay |
| BASF SE |
| Covestro AG |
| Celanese Corporation |
| Domo Chemicals |
| DuPont |
| SABIC |
| INEOS |
| Others |
Pricing and Supply Chain Analysis
Undercapacity at European caprolactam producers is compressing margin visibility for French polyamide compounders while simultaneously elevating pricing leverage for integrated resin producers with captive feedstock supply. This utilization squeeze propagates through automotive supply chains as OEMs absorb pass-through costs or accept formulation switches to recycled-content grades.
Pricing Analysis
Long-term offtake contracts dominate procurement between Grand Est automotive OEMs and qualified compounders, insulating volume commitments from benzene price spikes while spot transactions govern distributor channels serving prototype shops. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade sulfone compounds under ISO 13485 certification from commodity polyamide grades and Asian-imported polyoxymethylene. Cost compression in precision mechanical tiers is intensifying because integrated East Asian producers deliver at 15-20% below domestic production economics. Tier-2 processors in the Greater Paris belt exhibit acute price sensitivity, whereas aerospace procurement at Solvay's Saint-Fons facility prioritizes supply security over unit cost.
Supply Chain Analysis
Upstream caprolactam and benzene feedstocks draw from integrated petrochemical complexes in Belgium, Germany, and the Netherlands, with naphtha cracking economics tethered to natural gas pricing at Rotterdam and Antwerp hubs. Polymer additive packages rest on specialty chemical production concentrated in the Rhône-Alpes corridor and imported masterbatch formulations from Switzerland. Single-source vulnerability permeates medical-grade sulfone supply where ANSM-registered alternatives remain limited. Distribution runs through Arkema and BASF SE technical service teams embedded at OEM manufacturing sites, with regional distributors filling lot-size flexibility gaps for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's engineering plastics market sits in early-cycle expansion as battery electric vehicle programs accelerate polyamide qualification timelines beyond historical automotive adoption curves. Electrification mandates and REACH carbon border adjustments are displacing virgin feedstock procurement with mechanically recycled alternatives.
For Market Incumbents: Build certification moats around ANSM-registered medical-grade polymer production to defend against emerging recompounders with recycled-content portfolios. Invest in backward integration into post-industrial scrap sourcing within Hauts-de-France textile corridors. Secure long-term offtake agreements with Rhône-Alpes hydrogen equipment suppliers before pressure vessel specifications crystallize.
For New Entrants and Emerging Players: Mechanical recycling infrastructure gaps in the Greater Paris manufacturing belt represent the most penetrable entry point for integrated recompounders with spectroscopy validation capabilities. Medical-grade sulfone localization under ISO 13485 certification offers white-space capture as Solvay concentrates on fluoropolymer aerospace applications. Partner with tier-2 automotive processors losing qualified supplier status to secure toll-compounding arrangements.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated compounders with in-house recycling capabilities and automotive OEM qualification status. The five-to-ten-year viability window favors assets with established REACH registration dossiers and carbon footprint documentation systems. Watch for inflection when ECHA publishes definitive PFAS restriction timelines redirecting aerospace procurement toward sulfone alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock | Captures margin from post-industrial polyamide scrap accumulation in Hauts-de-France textile corridors. |
| Medical-Grade Polymer Localization | Addresses ANSM biocompatibility requirements for implantable devices under tightening EU MDR enforcement. |
| Long-term Supply Agreement with Hydrogen Equipment Suppliers | Positions compounders for high-barrier polyamide specifications in Rhône-Alpes pressure vessel programs. |
| Joint Venture with Automotive Tier-1 Suppliers | Accelerates cradle-to-gate carbon footprint documentation for Stellantis and Renault battery platforms. |
| Green Manufacturing Transition | Aligns production with EU Green Deal carbon border adjustment mechanisms affecting caprolactam imports. |
Research Methodology
Cross-validation between plant manager interviews at Lyon-area compounders and customs trade data anchors the qualitative findings on import penetration dynamics. Primary discussions with procurement leads at Grand Est automotive OEMs, distribution channel partners in Marseille industrial corridors, and technical R&D directors at specialty polymer producers informed supply chain configuration analysis. Secondary validation drew from Cefic sector reports, SEC 10-K filings of multinational chemical conglomerates, and ANSM regulatory guidance documents. Bottom-up volume modeling triangulated against top-down macroeconomic absorption rates.
Calibration against historical polyamide consumption patterns and automotive production forecasts shaped the analytical framework across the analysis window. Segmentation dimensions modeled include performance grade tier, end-use industry vertical, regional production hub within France, and certification status under REACH and ANSM protocols. CAGRs derived from regression analysis of feedstock price elasticity and substitution coefficients between virgin and recycled engineering plastics. Industry-specific inputs incorporated battery electric vehicle platform rollout schedules and ECHA restriction timeline scenarios.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, benzene pricing volatility, or REACH registration enforcement intensity would shift the trajectory. Forecasts reflect underlying assumptions about polymer characterization expertise availability and mechanical recycling infrastructure buildout rates. Cross-checking against IHS Markit vehicle registration data and Cefic polymer trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Australia Engineering Plastics Market
Polymers & Resins
Global Furan Resins Market
Polymers & Resins
EVA Foam Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Polyimide and Imide Polymers Market
Polymers & Resins
Asia-Pacific Flooring Resins Market
Polymers & Resins
Ammonium Polyphosphate (Phase II) Market
Polymers & Resins
Renewable PVDF Market
Polymers & Resins
North America and Europe Phenolic Resin Market
Polymers & Resins
Polyglycerol Market
Polymers & Resins
Nylon 4-6 Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Polyurethane (PU) Foam Market