
 Carbotanium Market | 2026-2036
Carbotanium Market Size, Share, and Industry Trends Forecast 2026-2036
Carbotanium Market Outlook
Direct sales channels between raw material suppliers and aerospace primes is rewriting procurement economics for advanced composites. Toray Industries leverages its carbon fiber precursor dominance to sustain pricing power across Japanese and US supply chains. Hexcel Corporation anchors North American aerospace qualified material status through decades of Boeing and Lockheed Martin program integration. SGL Carbon SE competes via specialized carbon-carbon and carbon fiber product lines serving European automotive and industrial applications.
Carbotanium denotes hybrid material systems combining carbon fiber reinforced polymers with titanium alloy substrates, typically fabricated through resin transfer molding or automated fiber placement followed by diffusion bonding at temperatures exceeding 800°C to achieve specific strength ratios exceeding conventional aluminum alloys by factors of three to five. The aerospace application segment leads current value generation due to airframe weight reduction mandates and fuel efficiency targets, while automotive OEMs represent the fastest-growing demand pool as Horacio Pagani S.P.A. and Rolls-Royce Motor Cars validate structural performance in limited-production chassis. Composite product types command margin concentration due to processing complexity and qualification barriers, whereas titanium alloy feedstock remains volume-constrained by sponge supply and mill product capacity.
FAA airworthiness standards and EU REACH chemical registration frameworks govern material qualification timelines and substance restrictions across US and European supply chains. EASA certification requirements for primary aircraft structures extend testing protocols and documentation burdens, effectively filtering market access to pre-qualified suppliers. Stakeholders must monitor evolving MEE environmental compliance in China and emerging dual carbon goals that may redirect titanium sponge and carbon fiber capacity toward domestic aerospace programs.
Market Dynamics
Diffusion bonding automation at temperatures exceeding 800°C is compressing fabrication timelines and requalifying supplier tiers across aerospace and automotive supply chains.
Growth Catalysts
- FAA Airworthiness Directives:Lightweight material mandates for commercial airframes accelerate qualified supplier procurement cycles in the United States.
- EU Green Deal:Carbon intensity targets for aviation fuel consumption drive airframe weight reduction programs across European manufacturing clusters.
- Resin Transfer Molding:Automated fiber placement hybridization reduces labor content and improves repeatability for titanium-carbon hybrid structures.
Market Restraints
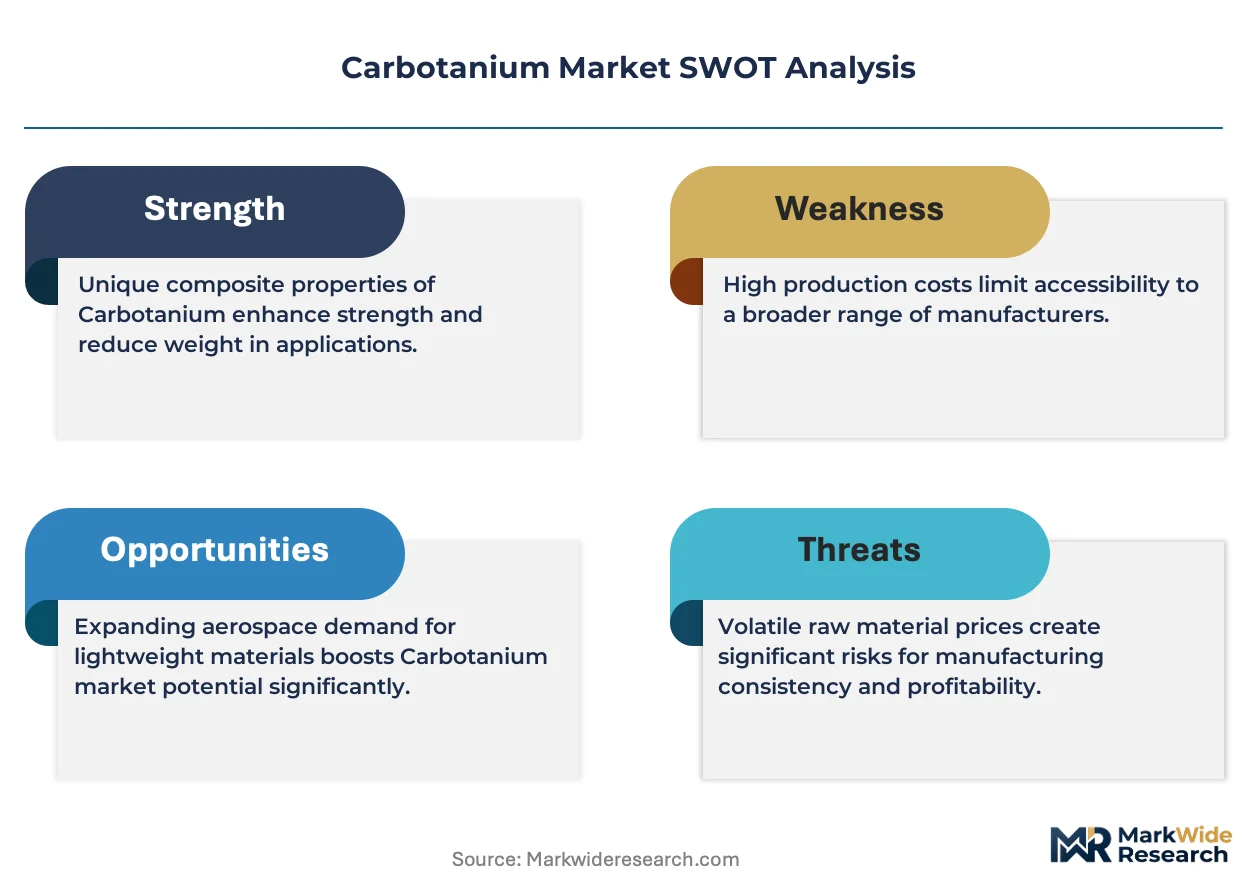
- Titanium Sponge Concentration:Mill product capacity constraints in Russia and China expose feedstock supply chains to export control volatility.
- EASA Certification Timelines:Extended testing protocols for primary aircraft structures filter market access to pre-qualified incumbents with decade-long qualification records.
- Aluminum-Lithium Alloys:Third-generation Al-Li systems compete for wing and fuselage applications where carbotanium cost premiums face procurement scrutiny.
Strategic Opportunities
- Urban Air Mobility:Electric vertical take-off and landing airframe programs in Germany and Italy validate structural performance for high-volume production scaling.
- EU REACH Chemical Registration:Streamlined substance authorization pathways for qualified aerospace materials reduce compliance burdens for European tier-one suppliers.
- Automated Fiber Placement:Convergence with in-situ thermoplastic consolidation enables out-of-autoclave processing for cost-sensitive automotive chassis applications.
Industry Challenges
- Diffusion Bonding Expertise:Process engineers capable of 800°C titanium-carbon interface control remain concentrated at a handful of European and Japanese research institutes.
- Dual-Use Export Controls:ITAR and EU dual-use regulation complexity fragments qualified supplier networks for defense-aerospace crossover programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbotanium Market |
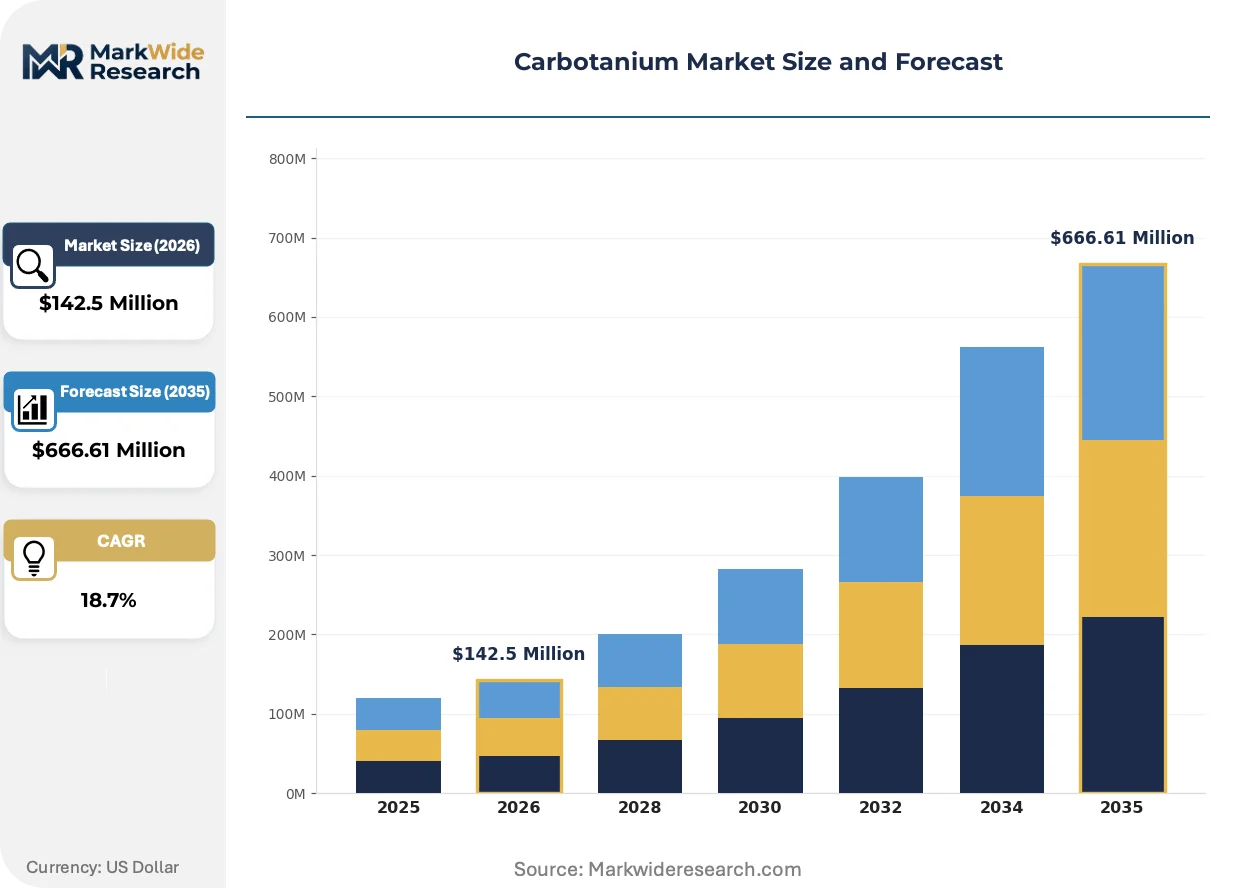
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $666.61 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber, Titanium Alloy, Composite, Others Application: Aerospace, Automotive OEMs, Defense, Sports Equipment End User: Manufacturers, R&D Institutes, Government Agencies, Aerospace Companies Distribution Channel: Direct Sales, Online Retail, Distributors, Third-party Dealers |
| Companies Covered | Horacio Pagani S.P.A., Rolls-Royce Motor Cars, Boeing, Carbotanium Ltd., Arevo Labs, Hyperganic Materials, Toray Industries, Hexcel Corporation, SGL Carbon SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbotanium Market Strategic Shifts
Digital thread integration across material qualification and airworthiness certification is compressing program development cycles and rewiring supplier-buyer information flows.
Automated fiber placement with in-situ consolidation is virtualizing traditional autoclave curing for large titanium-carbon hybrid structures. Boeing and Airbus tier-one suppliers in Japan and Italy adopt these systems for wing spar and fuselage frame production. The technology is virtualizing capital-intensive thermal processing infrastructure and enabling geographic decoupling of fabrication from final assembly.
EU REACH chemical registration frameworks are tightening substance restriction timelines for epoxy resin systems and hardener packages used in aerospace prepregs. ECHA authorization requirements now extend to bisphenol derivatives and certain amine curing agents. European composite formulators respond by accelerating bio-based epoxy development and qualifying alternative hardener chemistries through EASA parallel certification tracks.
Direct material supplier relationships with aerospace primes are displacing distributor-mediated procurement for qualified carbotanium feedstock. Tier-one airframers in the United States and Germany now negotiate multi-year carbon fiber and titanium mill product agreements bypassing traditional composite distributors. This pattern concentrates most visibly in Seattle and Toulouse manufacturing corridors where Boeing and Airbus maintain captive engineering integration teams.
Carbotanium Market Segmentation
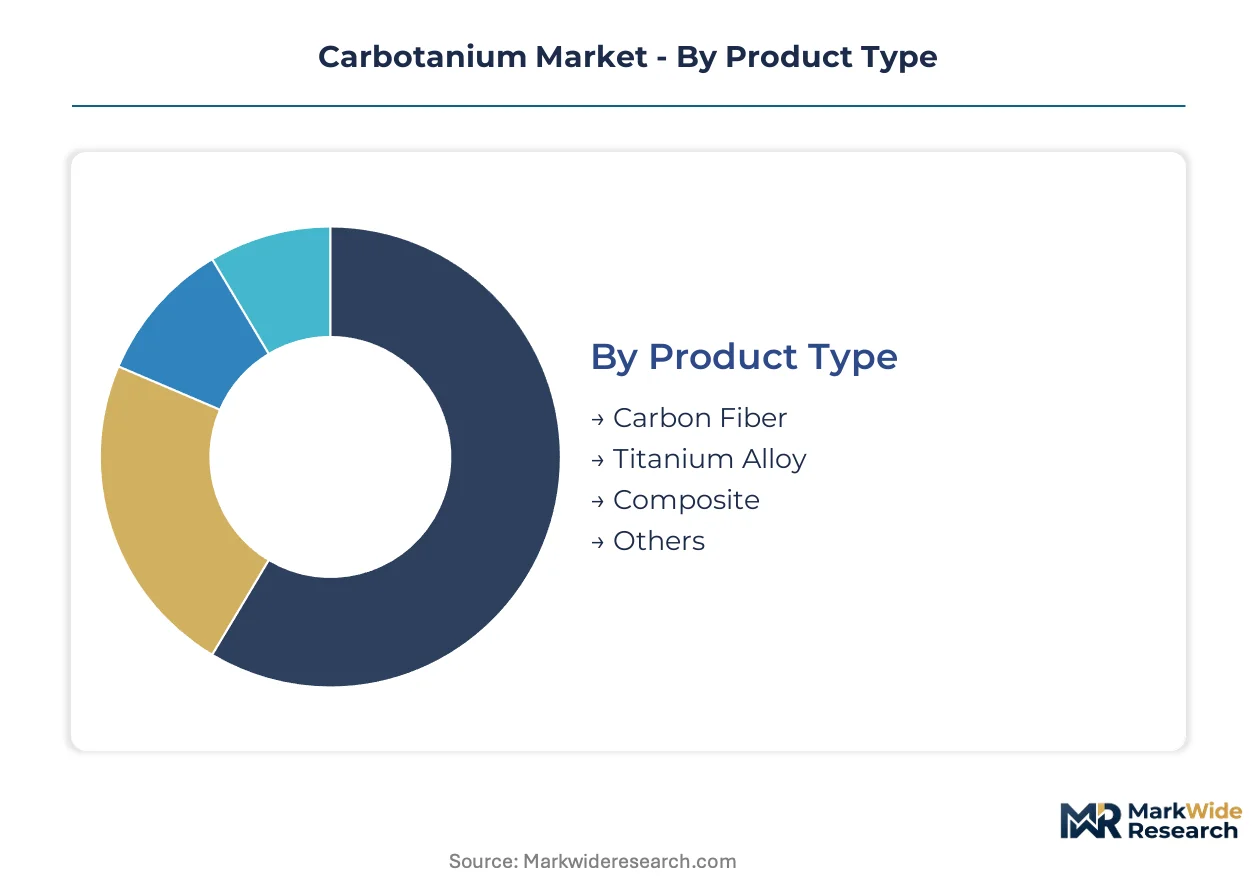
Carbotanium procurement economics vary sharply across product hierarchies and end-use qualifications. Aerospace primes negotiate multi-year direct agreements for qualified feedstock, while automotive channels fragment across tiered distributor networks with divergent certification burdens.
Product Type:
Cost tier stratification separates aerospace-qualified composites from industrial-grade titanium mill products and commodity carbon fiber precursors.
- Carbon Fiber:PAN-based and pitch-based precursors supply the reinforcing phase for hybrid laminates, with aerospace-grade tow specifications commanding qualification premiums from Boeing and Airbus supply chains in Japan and the United States. Toray Industries and Hexcel Corporation anchor precursor supply through vertical integration into polymerization and carbonization stages.
- Titanium Alloy:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr mill products form the metallic substrate layer, with sponge-to-rotor supply chains concentrated in Russia and China exposing procurement to export control volatility. Mill product capacity constraints amplify lead times for diffusion bonding-qualified plate and foil gauges.
- Composite:Hybrid carbotanium laminates fabricated through resin transfer molding or automated fiber placement command margin concentration due to processing complexity and airworthiness qualification barriers. Horacio Pagani S.P.A. validates structural performance in limited-production automotive chassis.
- Others:Specialized interlayers and surface preparation chemistries complete the material system stack.
Composite holds installed capacity. Carbon Fiber is rotating up the share rankings.
Application:
Application scope spans weight-critical airframe structures through performance automotive chassis to defense armor systems with divergent qualification timelines.
- Aerospace:Wing spars, fuselage frames, and control surfaces drive qualified material procurement from Boeing and Airbus tier-one suppliers in Seattle and Toulouse corridors. FAA airworthiness directives and EASA certification requirements extend testing protocols, filtering market access to pre-qualified incumbents.
- Automotive OEMs:Limited-production supercar chassis from Rolls-Royce Motor Cars and specialty manufacturers in Germany and Italy validate structural performance for high-volume production scaling. Urban air mobility programs in these same manufacturing clusters are expanding the addressable demand pool.
- Defense:Armor and structural applications face ITAR and EU dual-use regulation complexity that fragments qualified supplier networks.
- Sports Equipment:High-performance bicycles and racing components represent a price-sensitive niche with reduced qualification overhead.
Aerospace holds installed capacity. Automotive OEMs are expanding most quickly.
End User:
Customer type determines procurement modality, with captive engineering integration teams at aerospace primes displacing traditional distributor relationships.
- Manufacturers:Tier-one airframers and automotive OEMs negotiate direct multi-year agreements for qualified feedstock, bypassing composite distributors in Seattle, Toulouse, and Stuttgart manufacturing corridors.
- R&D Institutes:European and Japanese research institutes concentrate process engineering expertise for 800°C titanium-carbon interface control.
- Government Agencies:Defense procurement programs face dual-use export control fragmentation across ITAR and EU regulatory frameworks.
- Aerospace Companies:Boeing and Airbus maintain captive engineering integration teams that rewire supplier-buyer information flows through digital thread integration.
Manufacturers hold installed capacity. R&D Institutes are rotating up the share rankings.
Distribution Channel:
Channel configuration tracks qualification tier, with direct sales dominating aerospace and distributor networks serving price-sensitive segments.
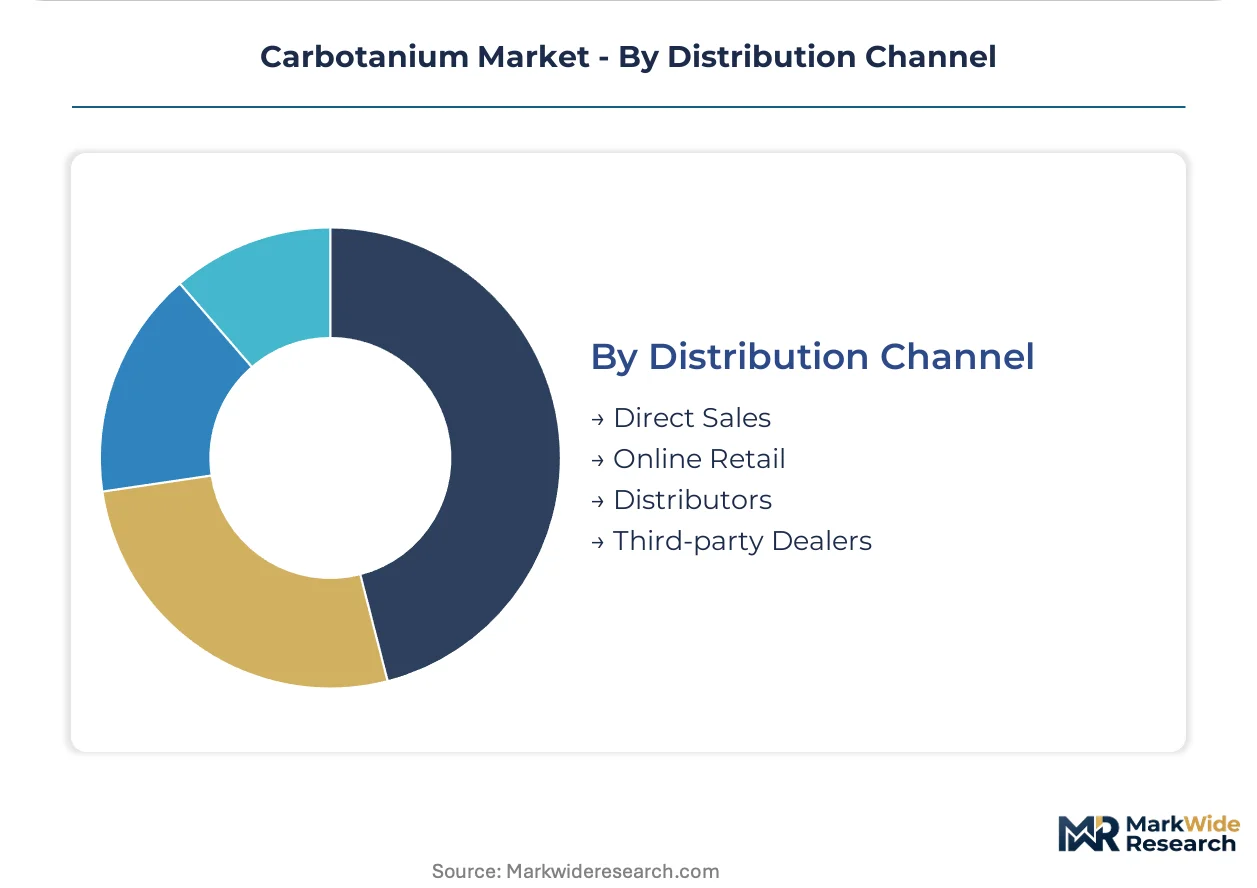
- Direct Sales:Raw material suppliers negotiate multi-year carbon fiber and titanium mill product agreements directly with aerospace primes, concentrating procurement economics in qualified supply chains.
- Distributors:Traditional composite distributors serve industrial and sports equipment segments where airworthiness qualification is absent.
- Online Retail:Limited to commodity carbon fiber fabrics and small-format titanium products without aerospace certification.
- Third-party Dealers:Regional intermediaries serve automotive aftermarket and specialty fabrication shops.
Direct Sales holds installed capacity. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and German supply chains where qualified material status commands decade-long premiums, while Chinese and Russian titanium sponge sources face export control volatility that compresses margins for downstream fabricators.
United States
Boeing and Lockheed Martin procurement drives qualified composite demand through Seattle and Southern California manufacturing corridors. FAA airworthiness directives on lightweight materials accelerate certification timelines for domestic tier-one suppliers. Diffusion bonding expertise clusters at MIT and Georgia Tech research institutes alongside Hexcel Corporation's Utah carbon fiber operations.
Germany
Automotive supercar OEMs in Stuttgart and Munich validate carbotanium chassis for limited-production scaling. EU REACH chemical registration frameworks govern epoxy resin systems and hardener packages through ECHA authorization requirements. Urban air mobility programs in Bavaria and Baden-Württemberg expand structural performance testing for electric vertical take-off applications.
Japan
Toray Industries anchors PAN-based precursor supply through vertical integration into polymerization and carbonization stages. METI industrial policy supports automated fiber placement hybridization for aerospace-qualified laminates. Nagoya and Tokyo manufacturing clusters concentrate process engineering expertise for 800°C titanium-carbon interface control.
Italy
Horacio Pagani S.P.A. validates hybrid composite performance in limited-production automotive chassis from Modena facilities. EASA certification requirements extend testing protocols for primary aircraft structures, filtering market access to pre-qualified incumbents. Emilia-Romagna's motor valley co-locates aerospace tier-one suppliers with specialty automotive fabricators.
China
Dual carbon goals redirect titanium sponge and carbon fiber capacity toward domestic aerospace programs under MEE environmental compliance monitoring. Mill product constraints expose procurement to export control volatility from concentrated sponge-to-rotor supply chains. Xi'an and Chengdu manufacturing bases develop diffusion bonding capabilities for military-aircraft crossover applications.
Carbotanium Market Competitive Environment
Integrated material suppliers and specialized hybrid fabricators split the market between upstream precursor dominance and downstream qualification barriers. Japanese and North American incumbents consolidate around carbon fiber precursor supply, while European specialists compete via carbon-carbon and titanium alloy product lines. Three archetypes define competitive positioning: vertically integrated chemical conglomerates, aerospace-qualified composite formulators, and automotive-anchored hybrid specialists. Capacity expansion and direct sales channel development constitute the dominant competitive moves as distributors lose share to prime-direct procurement.
Among aerospace-qualified composite suppliers, Toray Industries and Hexcel Corporation exemplify the precursor-integrated archetype, while SGL Carbon SE occupies a position within the European specialty tier. These three anchors represent divergent geographic and structural strategies—Japanese chemical conglomerate, US public corporation, and German SE-format entity—each sitting within distinct regulatory and customer relationship frameworks.
| Leading Market Players |
|---|
| Horacio Pagani S.P.A. |
| Rolls-Royce Motor Cars |
| Boeing |
| Carbotanium Ltd. |
| Arevo Labs |
| Hyperganic Materials |
| Toray Industries |
| Hexcel Corporation |
| SGL Carbon SE |
| Others |
Value Chain & Pricing Dynamics
Nagoya manufacturing clusters concentrate PAN-based precursor capacity and 800°C diffusion bonding expertise, anchoring pricing power for aerospace-qualified laminates. Toray Industries' backward integration into polymerization stages sustains margin capture across Japanese and US supply chains, while downstream fabricators face cost compression from titanium sponge volatility.
Pricing Analysis
Configured-to-order pricing for EASA-certified hybrid laminates commands spreads exceeding standard industrial titanium mill products by qualification premiums. Three-tier pricing structure across aerospace-qualified, automotive-performance, and industrial-grade levels separates Boeing tier-one suppliers from Horacio Pagani S.P.A. chassis fabricators from commodity carbon fiber distributors. Cost compression in automotive-performance tiers is intensifying because Rolls-Royce Motor Cars procurement scales toward limited-production volumes. Aerospace primes exhibit least price sensitivity due to fuel efficiency mandates, while sports equipment distributors face acute margin pressure from spot-market carbon fiber sourcing.
Supply Chain Analysis
ITAR and EU dual-use regulation complexity fragments qualified supplier networks, limiting defense-aerospace crossover flows. Geographic supply concentration centers on Japan for PAN-based precursors, Russia and China for titanium sponge-to-rotor capacity, and Germany for carbon-carbon specialty products. Raw material dependencies draw from aerospace-grade carbon fiber tow, Ti-6Al-4V mill plate, and epoxy resin systems governed by ECHA authorization. Single-source vulnerability in sponge supply chains amplifies lead time risk for diffusion bonding-qualified gauges. Distribution runs through direct sales channels for aerospace primes and tiered distributor networks for automotive and industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbotanium procurement is shifting toward platform-economics dynamics as digital thread integration rewrites supplier-buyer information flows and captive engineering teams at Boeing and Airbus consolidate multi-year direct agreements.
For Market Incumbents: Harden qualification barriers by deepening EASA parallel certification tracks for bio-based epoxy alternatives ahead of REACH substance restrictions. Anchor capacity addition in Utah and Nagoya manufacturing corridors to defend against emerging automated fiber placement specialists. Lockheed Martin program integration records constitute the core defensive asset against new entrants lacking decade-long airworthiness documentation.
For New Entrants and Emerging Players: Urban air mobility programs in Bavaria and Baden-Württemberg represent underpenetrated demand pools where electric vertical take-off airframe procurement lacks incumbent supplier relationships. Target automotive chassis applications for high-volume production scaling as Horacio Pagani S.P.A. validates structural performance benchmarks. Pursue joint development agreements with R&D institutes concentrating 800°C titanium-carbon interface expertise.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with non-core carbon fiber precursor divisions lacking aerospace qualification pathways. Five-to-ten year viability hinges on diffusion bonding automation adoption compressing fabrication timelines. Watch for ITAR restriction easing on dual-use titanium-carbon technologies as the inflection signal for defense-aerospace crossover valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Scale-Up | Hexcel Corporation adoption virtualizes autoclave curing for Boeing wing spar production. |
| Backward Integration into Precursor Supply | Toray Industries polymerization control sustains pricing power across Japanese supply chains. |
| EASA Parallel Certification Investment | Bio-based epoxy qualification reduces REACH compliance burdens for European tier-one suppliers. |
| Urban Air Mobility Partnership | German eVTOL programs validate structural performance for high-volume automotive scaling. |
| Direct Sales Channel Development | Multi-year agreements with Seattle and Toulouse corridors displace composite distributors. |
Study Parameters
The analysis maps carbon fiber precursor supply, titanium alloy mill products, hybrid composite fabrication, and end-use qualification tiers, each validated through procurement directors at aerospace primes, plant managers at carbonization facilities, EASA certification engineers, and automotive platform development leads. Primary interview data triangulates against customs records for titanium sponge trade flows, FAA airworthiness directive filings, ECHA substance authorization databases, and SEC 10-K disclosures from qualified material suppliers. Bottom-up segment sizing and top-down macroeconomic anchoring cross-validate volume and value estimates.
Assumption-sets held feedstock capacity expansion in Japan and US corridors fixed while varying REACH authorization timelines and dual-use export control stringency across the projection horizon. Segmentation dimensions modeled include product type hierarchy, application qualification tier, end-user procurement modality, and geographic manufacturing cluster. CAGRs derive from diffusion bonding automation adoption curves and urban air mobility program scaling assumptions. Industry-specific inputs incorporate Boeing and Airbus order backlogs, titanium sponge inventory cycles, and EASA certification queue depths.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed sponge producers or automated fiber placement equipment vendors would shift outcomes. Material shifts in FAA lightweight material mandate timing or EU Green Deal carbon intensity enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
North America Metal Finishing Market
Metals
North America Iron Casting Market
Metals
High Carbon Bearing Steel Market
Metals
Beryllium Copper for Telecommunication Market
Metals
Europe Metal Casting Market
Metals
Steel Casting Market
Metals
Palladium Market
Metals
Heat-Treated Steel Plates Market
Metals
Global Welding Powder Market
Metals
GCC Metal Forging Market
Metals
Zinc Plating Market
Metals
Global Aluminum Extruded Products Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
Transition Metals Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Global Stretch Spring Wire Market