
 TMCP Steel Market | 2026-2036
TMCP Steel Market Size, Share, and Industry Trends Forecast 2026-2036
TMCP Steel Market Insights
Accelerated cooling control systems is reconfiguring how TMCP steel plates achieve specified yield strengths without heavy alloy additions. ArcelorMittal leverages its European R&D network to refine direct-quench process parameters for offshore grades. Nippon Steel Corporation anchors Japanese shipyard supply through dedicated plate mills in Nagoya and Kimitsu. POSCO dominates Korean line pipe production with in-house slab-to-plate integration at Pohang.
Thermo-mechanical controlled process steel refers to plate and structural products manufactured through integrated controlled rolling and accelerated cooling to achieve high strength-to-weight ratios with leaner chemistry than normalized or quenched-and-tempered alternatives. Typical yield strengths range from 355 MPa to 960 MPa depending on cooling rate and reduction schedule, serving applications where weldability and toughness at low temperatures are mandatory. Structural steel occupies the largest volume share as infrastructure projects specify TMCP plates for welded bridge girders and building frames. Automotive grade steel represents the fastest-expanding category as OEMs adopt higher-strength chassis components to meet crash standards without weight penalties. Offshore steel commands premium pricing due to supplementary through-thickness testing and Z-direction property requirements for platform leg nodes.
API specifications for sour service line pipe, EN 10025-4 thermomechanical rolled weldable fine grain steels, and ISO 19902 fixed offshore structure standards collectively define the compliance baseline for mill qualification and end-user procurement. China's SAMR enforces GB/T 1591 updates that mandate lower carbon equivalents for seismic zones, effectively filtering out older open-heat-treatment capacity. Japan's METI coordinates national projects linking steelmakers to shipbuilders through JIS G 3106 SM570Y grade specifications. Stakeholders must track how hydrogen pipeline design codes under development at ISO and ASME incorporate TMCP steel fracture resistance criteria for pressurized hydrogen transport.
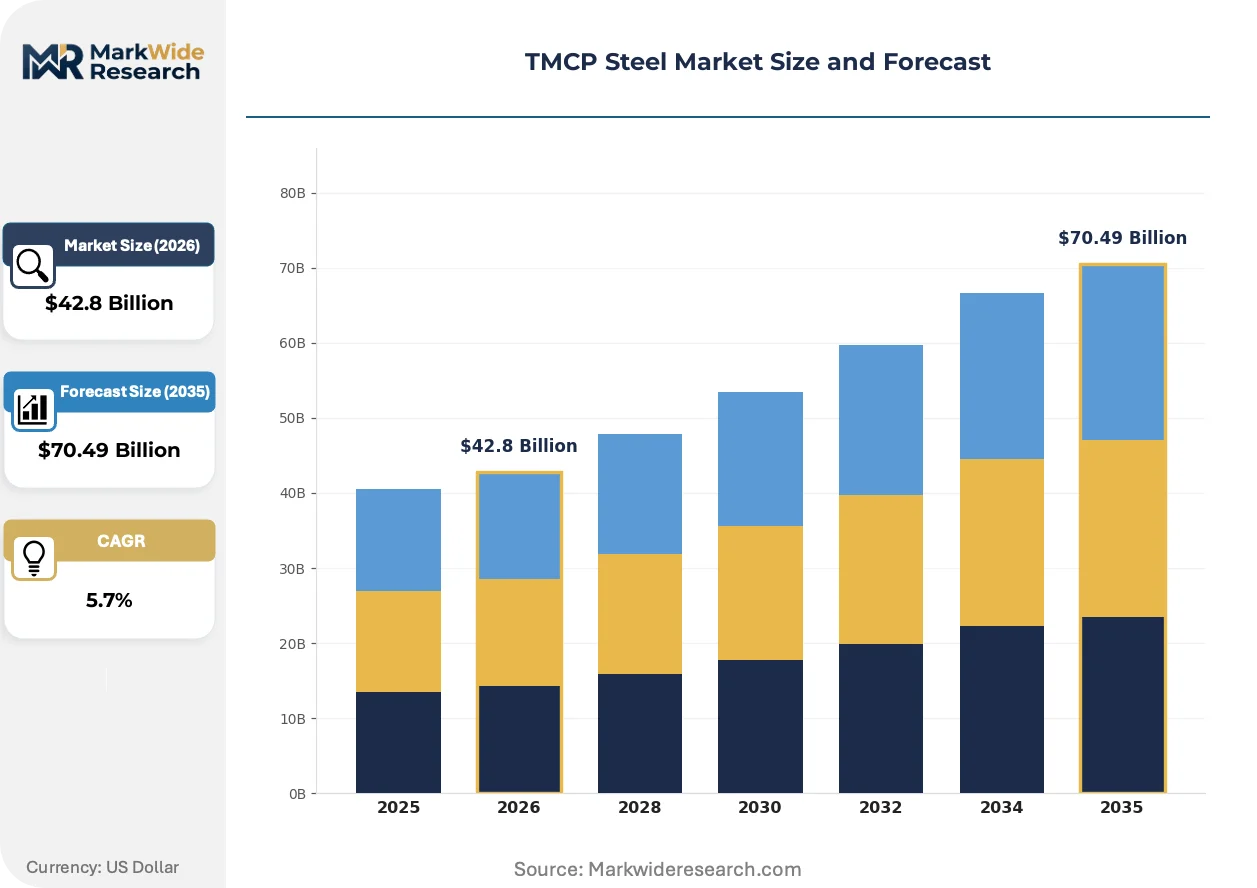
Market Dynamics
Accelerated cooling control systems are compressing alloy requirements across TMCP steel production, forcing mills to reconfigure rolling schedules and chemistry protocols to meet tighter carbon-equivalent mandates from classification societies and seismic codes.
Growth Catalysts
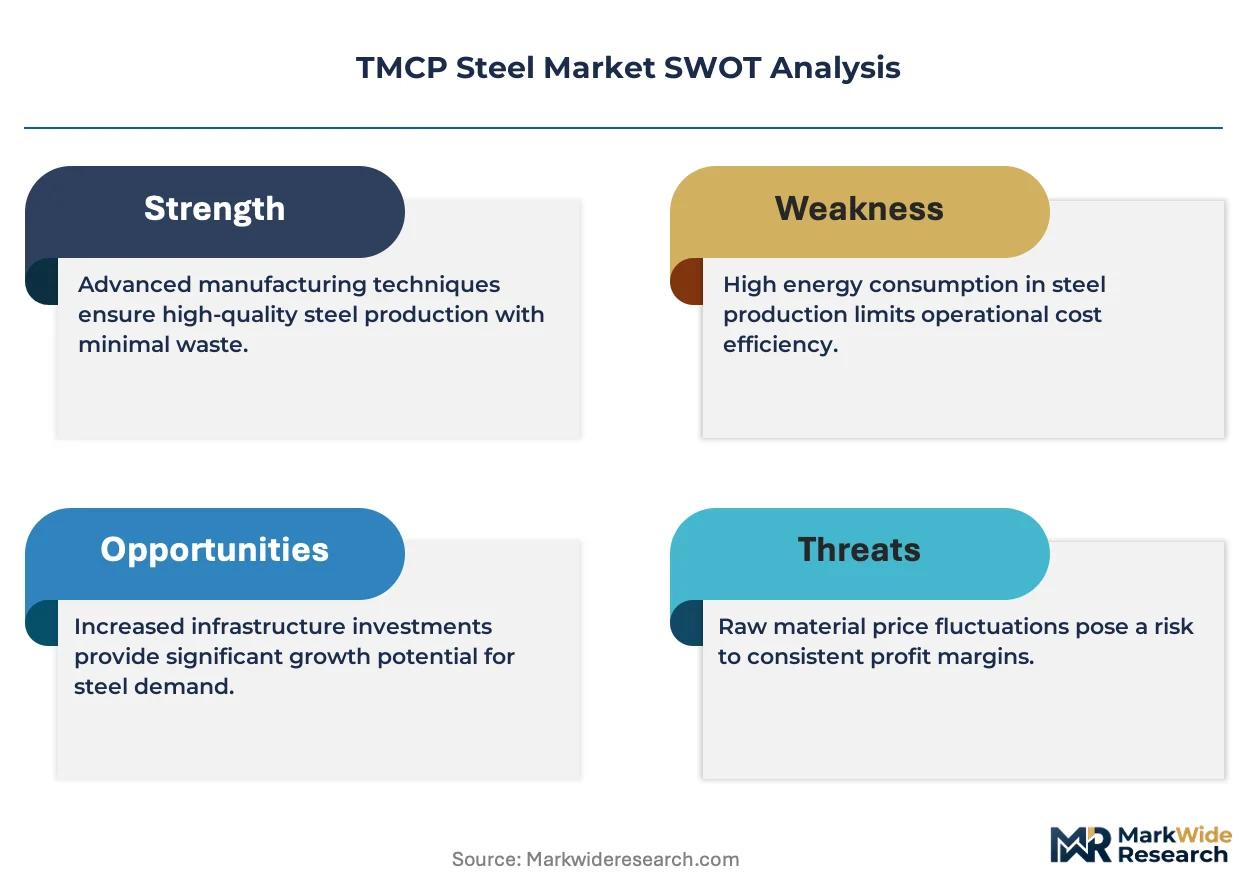
- Seismic code tightening:China's SAMR-enforced GB/T 1591 updates mandate lower carbon equivalents for bridge steels in earthquake zones, pulling demand toward accelerated cooling-capable mills.
- Hydrogen transport infrastructure:ISO and ASME pipeline design codes under development are incorporating TMCP fracture resistance criteria for pressurized hydrogen, opening new specification categories.
- East Asian shipbuilding:South Korean and Japanese shipyards are expanding high-tensile TMCP plate orders to satisfy classification society rules for lighter hull structures.
Market Restraints
- Scrap volatility:Electric arc furnace feedstock costs fluctuate with ferrous scrap export restrictions from major supplying nations, compressing margin predictability for plate producers.
- Equipment concentration:Accelerated cooling system manufacturing concentrates among a narrow supplier base in Germany and Japan, creating bottleneck risk for mill expansion timelines.
- Normalized steel substitution:Quenched-and-tempered alternatives retain specification grandfathering in legacy offshore platform contracts, slowing TMCP penetration in brownfield projects.
Strategic Opportunities
- Indian infrastructure buildout:The country's Dedicated Freight Corridor and bullet train projects specify high-strength weldable plate, creating import substitution potential for domestic TMCP capacity.
- Automotive chassis lightweighting:OEM crash standard compliance without weight penalties is pulling TMCP grades into passenger vehicle frame components previously served by conventional HSLA steels.
- EU Green Deal carbon accounting:The framework's embodied carbon tracking rewards lean-chemistry TMCP against alloy-intensive alternatives, creating specification preference in public procurement.
Industry Challenges
- Metallurgical control talent:Accelerated cooling parameter optimization requires process engineers with combined thermal modeling and phase transformation expertise, a skill set scarce outside established East Asian mill clusters.
- Through-thickness certification timelines:Z-direction property testing for offshore grades adds 6-8 weeks to qualification cycles, compressing responsiveness to spot demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TMCP Steel Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $70.49 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Steel, High Strength Plates, Line Pipe Steel, Automotive Grade Steel, Offshore Steel Application: Shipbuilding, Bridge Construction, Heavy Machinery, Oil & Gas Pipelines, Construction Equipment Technology: Accelerated Cooling, Controlled Rolling, Controlled Cooling, Quenching & Tempering, Thermo-Mechanically Treated End User: Shipyards, Bridge Builders, Machinery Manufacturers, Pipeline Operators, Construction Firms |
| Companies Covered | ArcelorMittal, Nippon Steel Corporation, Hyundai Steel, Baosteel Co. Ltd., POSCO, JFE Steel, Nucor, SSAB AB, Victor Steel Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TMCP Steel Market Trends and Innovations
Digital process control is reconfiguring how TMCP steel achieves mechanical properties, with real-time thermal mapping and predictive metallurgy displacing empirical rolling schedules across integrated mills.
Direct-quench processing is virtualizing traditional normalized plate production by integrating controlled rolling with inline accelerated cooling to achieve equivalent yield strengths without separate heat treatment. Offshore fabricators in the North Sea are adopting these grades for platform leg nodes to compress project schedules. The technology is virtualizing the normalized plate supply chain by collapsing heat treatment logistics into single-pass mill operations.
Japan's METI coordinates national R&D consortia linking Nippon Steel to shipbuilders through updated JIS G 3106 SM570Y grade specifications. The ministry's framework mandates fracture toughness verification at sub-zero temperatures for Arctic route vessels. Korean yards are responding by pre-qualifying enhanced TMCP plates for ice-class hull structures ahead of formal classification society rule changes.
Buyers are consolidating procurement around slab-to-plate integrated suppliers capable of certificate-of-origin traceability for carbon intensity claims. European bridge contractors now specify mill-specific environmental product declarations alongside mechanical property compliance. German fabricators serving the offshore wind sector are driving this consolidation, rejecting traders without direct mill relationships.
TMCP Steel Market Segmentation
TMCP steel specifications diverge sharply across end-use requirements, with yield strength targets, carbon-equivalent limits, and through-thickness property testing creating distinct procurement categories. Mills configure rolling schedules and cooling parameters differently for each segment, generating specialized supply chains that rarely overlap.
Product Type:
The use-case spectrum spans infrastructure load-bearing members through energy transport systems, with each product category demanding unique metallurgical control protocols.
- Structural Steel:Bridge girders and building frames specify TMCP plates at 355-460 MPa yield strength with lean carbon equivalents for field weldability. China's SAMR-enforced GB/T 1591 updates for seismic zones are pulling demand toward accelerated cooling-capable mills in East Asian coastal clusters.
- High Strength Plates:Heavy equipment booms and crane structures require 500-690 MPa grades with controlled toughness at sub-zero temperatures. Korean and Japanese fabricators dominate procurement, leveraging integrated slab-to-plate supply chains at Pohang and Nagoya.
- Line Pipe Steel:API 5L specifications for sour service mandate hydrogen-induced cracking resistance through calcium treatment and controlled sulfur levels.
- Automotive Grade Steel:OEM chassis components specify 600-800 MPa grades with bake-hardening compatibility for crash management systems.
- Offshore Steel:Platform leg nodes require Z-direction property certification and through-thickness tensile testing per ISO 19902.
Established volume favors Structural Steel; emerging adoption favors Automotive Grade Steel.
Application:
Cost tier differentiation separates specification-heavy energy projects from standardized civil engineering procurement.
- Shipbuilding:Classification society rules for lighter hull structures are expanding orders for high-tensile TMCP plates at 355-550 MPa. South Korean yards at Ulsan and Geoje anchor demand, with Japanese builders at Nagasaki and Kure specifying enhanced toughness for Arctic route vessels.
- Bridge Construction:Seismic-resistant designs specify 345-485 MPa grades with low yield-to-tensile ratios for ductility. China's tightening GB standards for seismic zones are compressing supplier qualification to mills with inline accelerated cooling.
- Heavy Machinery:Mining equipment frames and crane structures demand 690-960 MPa grades with guaranteed Charpy impact values at minus 40 degrees Celsius.
- Oil & Gas Pipelines:Sour service environments require calcium-treated, low-sulfur chemistries with HIC testing per NACE TM0284.
- Construction Equipment:Excavator booms and loader arms specify 500-700 MPa grades with controlled hardness for wear resistance.
Procurement scale concentrates in Shipbuilding; specification complexity peaks in Oil & Gas Pipelines.
Technology:
Volume distribution reflects capital intensity, with accelerated cooling systems requiring 40-60 million dollar investments per installation.
- Accelerated Cooling:Inline water-cooling systems achieve 15-30 degrees Celsius per second cooling rates, enabling 500-960 MPa yield strengths without heavy alloy additions. POSCO's Pohang works and Nippon Steel's Kimitsu mill anchor regional supply capability for this dominant production method.
- Controlled Rolling:Integrated deformation and temperature management in the austenite regime refines grain structure for 355-500 MPa grades. Older mill configurations without inline cooling still deploy this approach for standardized structural applications.
- Controlled Cooling:Air and mist cooling systems on runout tables provide moderate cooling rates for intermediate strength grades with lower capital requirements.
- Quenching & Tempering:Separate heat treatment cycles achieve ultra-high strengths above 960 MPa for specialized mining and defense applications.
- Thermo-Mechanically Treated:Combined deformation and phase transformation protocols optimize microstructure for specific toughness requirements.
Installed base favors Accelerated Cooling; retrofit potential sits with Controlled Rolling.
End User:
Customer maturity determines specification precision, with integrated energy companies driving the tightest metallurgical tolerances.
- Shipyards:Korean and Japanese builders specify JIS G 3106 SM570Y and equivalent high-tensile grades with fracture toughness verification at minus 60 degrees Celsius for ice-class vessels.
- Bridge Builders:Chinese contractors under GB/T 1591 mandate lower carbon equivalents for welded connections in seismic zones.
- Machinery Manufacturers:Caterpillar and Komatsu specify 690-960 MPa plates with guaranteed through-thickness properties for boom and frame weldments.
- Pipeline Operators:TC Energy and similar operators enforce API 5L supplementary requirements for sour service and offshore laying.
- Construction Firms:European contractors now require environmental product declarations alongside mechanical property compliance for public procurement under EU Green Deal frameworks.
Specification sophistication peaks with Pipeline Operators; volume scale concentrates with Shipyards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese mills dominate high-grade TMCP plate exports to South Korean shipyards, while Chinese producers supply seismic-resistant structural grades across domestic infrastructure corridors. Trade flows concentrate along East Asian coastal manufacturing belts where integrated steelworks share port infrastructure with end-users.
China
Bridge construction and high-speed rail projects drive TMCP plate consumption in seismic zones. SAMR-enforced GB/T 1591 updates mandate lower carbon equivalents for welded connections, filtering demand toward mills with inline accelerated cooling. Yangtze River Delta steelworks in Shanghai and Jiangsu province are retrofitting controlled rolling lines to meet tightened chemistry protocols.
Japan
Shipbuilders at Nagasaki and Kure specify enhanced toughness grades for Arctic route vessels. METI coordinates national R&D consortia linking Nippon Steel to yards through updated JIS G 3106 SM570Y specifications. Chubu region mills around Nagoya anchor supply chains for ice-class hull structures ahead of formal classification society rule changes.
South Korea
Ulsan and Geoje shipyards expand high-tensile TMCP plate orders for lighter hull structures under classification society rules. Hyundai Steel and POSCO maintain captive slab-to-plate integration at Pohang and Dangjin. Korean yards are pre-qualifying enhanced plates for ice-class applications before regulatory mandates take effect.
Germany
Offshore wind fabricators in the North Sea drive demand for direct-quench processed grades that compress project schedules. EU Green Deal carbon accounting rewards lean-chemistry TMCP against alloy-intensive alternatives in public procurement. Ruhr region mills and northern ports form a procurement cluster demanding mill-specific environmental product declarations.
India
The Dedicated Freight Corridor and bullet train projects specify high-strength weldable plate for bridge girders and track infrastructure. BIS standards for seismic-resistant structural steels are tightening, creating import substitution potential for domestic TMCP capacity. Western Maharashtra and Gujarat coastal zones are emerging as fabrication hubs for infrastructure steel demand.
TMCP Steel Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure defined by integrated mill capacity and end-user certification relationships. Consolidation concentrates among East Asian producers with captive slab supply and inline accelerated cooling systems. Two strategic archetypes dominate: integrated coastal mills with port-adjacent plate facilities, and regional specialists serving infrastructure contractors with customized rolling schedules. Capacity expansion and backward integration into raw material control represent the dominant competitive vectors.
Within the integrated mill tier, ArcelorMittal and Nippon Steel Corporation exemplify channel-controlling positions through R&D networks and dedicated plate mill configurations. POSCO anchors Korean supply capability through in-house slab-to-plate integration. These producers occupy positions where certificate-of-origin traceability and carbon intensity claims determine procurement access for European bridge contractors and offshore wind fabricators.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel Corporation |
| Hyundai Steel |
| Baosteel Co. Ltd. |
| POSCO |
| JFE Steel |
| Nucor |
| SSAB AB |
| Victor Steel Co. |
| Others |
Pricing and Supply Chain Analysis
East Asian port-to-port freight corridors between Pohang, Nagoya, and Shanghai anchor cost dynamics that compress margins for traders while amplifying pricing power for integrated mills with captive berth access. Carbon-equivalent certification tiers and slab-origin traceability now separate premium contract tiers from spot-market material, with EU Green Deal procurement rules rewarding mills that control upstream emissions data.
Pricing Analysis
Cost-plus contracts indexed to ferrous scrap export benchmarks from Japan and Germany dominate long-term offtake agreements between Korean shipyards and integrated plate mills. Price differentiation hinges on Z-direction certification grade and mill-specific environmental product declarations, with offshore wind fabricators paying premiums for direct-quench grades that eliminate normalized heat treatment. Pricing pressure intensifies in standardized structural segments as Chinese mills retrofit older controlled rolling lines to meet GB/T 1591 seismic mandates. Bridge contractors in seismic zones show highest price sensitivity due to public procurement budget constraints, while Arctic-class shipyards absorb premiums for sub-zero toughness verification.
Supply Chain Analysis
Export control regimes limiting accelerated cooling system technology from Germany and Japan constrain mill expansion timelines outside established East Asian clusters. Supply concentrates in South Korea, Japan, and China, where POSCO, Nippon Steel, and Baosteel control captive slab-to-plate integration. Production draws from iron ore pellet feedstock and ferrous scrap, with electric arc furnace operators exposed to volatile export restrictions from major supplying nations. Single-source vulnerability concentrates in specialized cooling equipment manufacturing, where a narrow German-Japanese supplier base creates bottleneck risk. Distribution runs through mill-direct relationships with shipbuilders and bridge contractors, bypassing traders lacking certificate-of-origin traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Normalized and quenched-and-tempered alternatives retain specification grandfathering in legacy offshore contracts, forcing TMCP incumbents to defend substitution pressure through certification investment and schedule compression.
For Market Incumbents: Pre-empt quenched-and-tempered substitution in brownfield offshore platforms by accelerating direct-quench qualification timelines and embedding fracture resistance data into classification society pre-approvals. Backward integration into captive slab supply secures carbon intensity traceability for EU Green Deal procurement access. Certification investment in hydrogen pipeline fracture resistance criteria positions mills ahead of ISO and ASME code finalization. For New Entrants and Emerging Players: Indian infrastructure corridors for Dedicated Freight Corridor and bullet train projects represent the most penetrable entry point, with BIS seismic standard tightening creating import substitution demand that domestic TMCP capacity cannot yet satisfy. Automotive chassis lightweighting in European OEM supply chains offers secondary white-space, with bake-hardening compatible grades displacing conventional HSLA steels. Go-to-market leverage rests on pre-qualifying with German fabricators serving North Sea offshore wind, who reject traders without direct mill relationships. For Investors and Strategic Acquirers: Accelerated cooling system manufacturers with phase transformation modeling software capabilities present the most defensible acquisition archetype, given metallurgical control talent scarcity outside East Asian mill clusters. Long-term viability frames around hydrogen transport infrastructure buildout and Arctic shipping route expansion, with fracture resistance verification at sub-zero temperatures as the durable capability moat. Monitor classification society rule changes for ice-class hull structures as the inflection signal, with Korean and Japanese yards pre-qualifying enhanced grades ahead of formal mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Accelerated Cooling Retrofit | Enables GB/T 1591 compliance for Chinese mills serving seismic-zone bridge projects. |
| Direct-Quench Qualification | Compresses project schedules for North Sea offshore wind fabricators demanding normalized plate alternatives. |
| Hydrogen Pipeline Certification | Positions mills ahead of ISO and ASME fracture resistance criteria for pressurized hydrogen transport. |
| Slab-to-Plate Integration | Secures carbon intensity traceability for EU Green Deal public procurement preference. |
| Ice-Class Pre-Qualification | Captures Korean and Japanese shipbuilder demand ahead of formal classification society rule changes. |
Research Methodology
Operator-level perspectives from plate mill process engineers, shipyard procurement directors, bridge contractor technical specifications leads, and offshore wind fabricator metallurgists anchored the qualitative base. Secondary validation drew from JIS G 3106 specification updates, SAMR GB/T 1591 enforcement notices, API 5L supplementary requirement filings, and classification society rule change proposals. Customs data on ferrous scrap trade flows and environmental product declaration registries supplied quantitative cross-checks. Bottom-up capacity modeling and top-down demand segmentation were triangulated against disclosed mill utilization rates.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling across product type, application technology, and end-user sophistication tiers. CAGRs were derived from rolling schedule capacity expansion announcements, regulatory mandate timelines, and substitution elasticity assumptions between TMCP and normalized alternatives. Industry-specific forecast inputs incorporated hydrogen pipeline code development velocity and Arctic shipping route ice-class vessel order backlogs.
Practitioners should monitor classification society rule finalization, SAMR enforcement intensity on carbon equivalent limits, and ferrous scrap export restriction announcements for early signals of forecast deviation. Material shifts in hydrogen transport infrastructure investment commitments or ice-class hull specification adoption rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Huntite Market
Metals
Titanium Mill Products Market
Metals
Ruthenium Market
Metals
Tinplate Market
Metals
Global Brass Rods Market
Metals
Copper Wire Market
Metals
Niobium Market
Metals
Silver Sulphate Market
Metals
Carbon Steel Market
Metals
Battery Metals Market
Metals
Aluminum Hot Rolling Mill Market
Metals
United States Metal Casting Market
Metals
High-End Copper Foil Market
Metals
Zinc Dust Market
Metals
High Purity Boron Market
Metals
Ferro Aluminum Market