
 Arc Ferrite Magnet Market | 2026-2036
Arc Ferrite Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
Arc Ferrite Magnet Market Analysis
China's Zhejiang Province is narrowing the cost-performance gap between arc ferrite and rare-earth alternatives through continuous kiln investments and powder metallurgy automation. DMEGC Magnetics leverages captive strontium ferrite powder production to sustain margin stability across automotive tier-one contracts. BGRIMM Magnetic Materials & Technology Co., Ltd. anchors domestic supply security through its Beijing-based R&D complex and provincial manufacturing bases. Arnold Magnetic Technologies competes in North American specialty applications with precision-ground arc segments for aerospace motor assemblies.
Arc ferrite magnets are sintered ceramic composites of iron oxide and strontium or barium carbonate, formed through powder pressing and high-temperature firing to achieve coercivity values typically exceeding 3,000 Oersted; these curved segments convert electrical to mechanical energy in permanent magnet DC motors and brushless configurations. The electric motors application commands the largest volume share due to ubiquitous deployment in HVAC blowers, power steering units, and appliance drives, while magnetic sensors represent the fastest-expanding use case as industrial automation demands contactless position detection. Ceramic magnets maintain cost leadership in high-volume consumer tiers, though permanent magnet grades capture superior margin pools in automotive and medical device channels where dimensional tolerance and thermal stability requirements intensify.
China's MIIT enforces GB/T 13560 material efficiency standards that restrict heavy-metal content and mandate recycling documentation for ferrite magnet exports, while Japan's METI administers JIS C 2502 performance benchmarks that arc segment producers must satisfy for industrial motor qualification. The EPA in the United States monitors particulate emissions from ferrite calcination and grinding operations, pressuring manufacturers to install baghouse filtration or relocate finishing stages to regulated jurisdictions. Stakeholders must monitor divergence between Asian efficiency mandates and Western environmental compliance timelines when siting new powder-processing capacity.
Market Dynamics
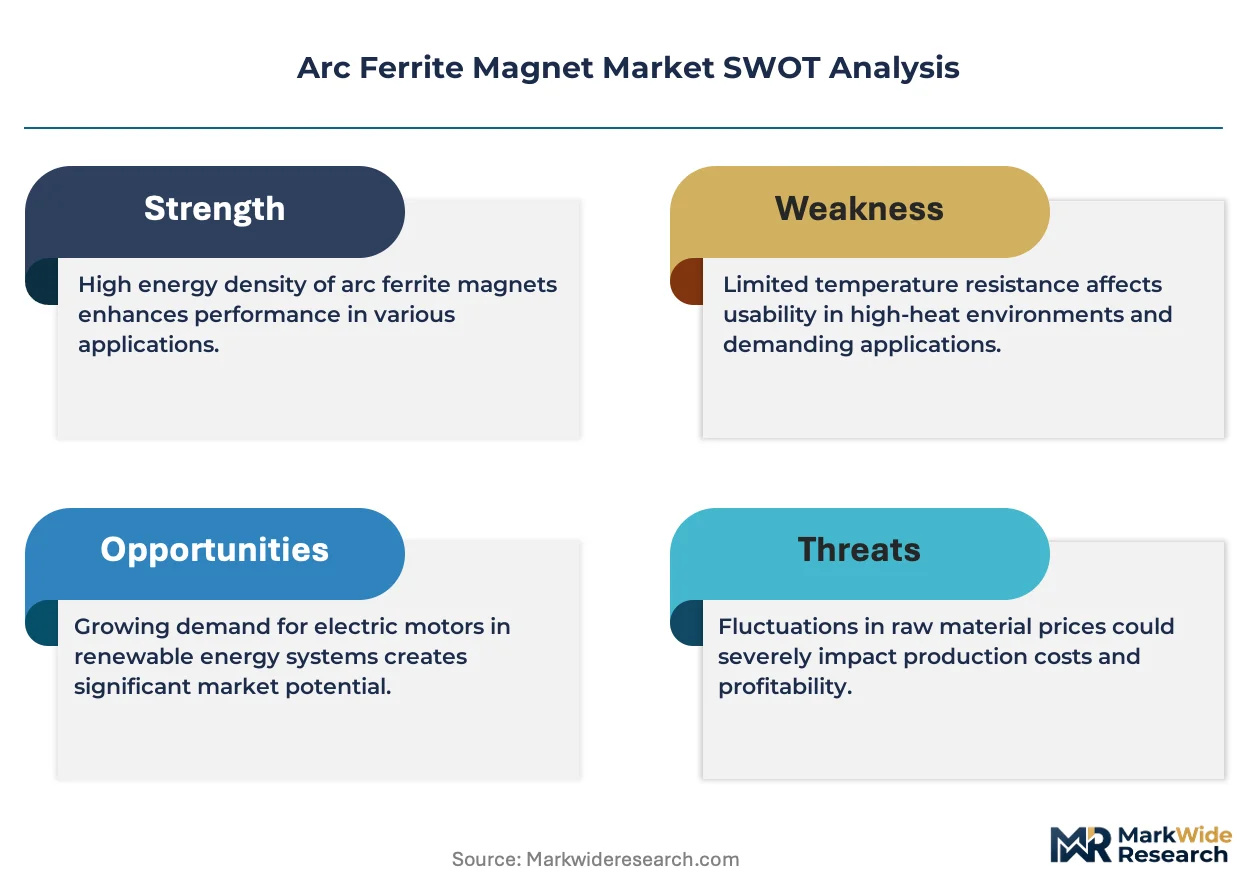
China's MIIT energy-efficiency mandates for electric vehicle motors are tightening material specifications and reshaping supplier qualification criteria across the arc ferrite magnet value chain.
Growth Catalysts
- Automotive electrification programs:Procurement of arc ferrite magnets for traction motor assemblies is accelerating in Germany, Japan, and China as OEMs expand EV production lines.
- GB/T 13560 standards:China's MIIT mandates are pushing ferrite magnet producers to upgrade powder metallurgy automation and kiln efficiency to meet export documentation requirements.
- Industrial automation sensors:Contactless position detection demand is expanding the magnetic sensors application segment faster than traditional motor volumes.
Market Restraints
- Strontium carbonate input volatility:Ferrite magnet cost structures face pressure from mineral supply concentration in Chinese processing corridors.
- Rare-earth substitution threat:Neodymium-iron-boron magnets capture premium automotive and aerospace applications where thermal stability requirements intensify.
- EPA particulate enforcement:US manufacturers must install baghouse filtration or relocate grinding operations to regulated jurisdictions, elevating capital requirements.
Strategic Opportunities
- Medical device precision segments:Dimensional tolerance requirements in brushless surgical motors create margin pools for certified arc segment suppliers.
- HVAC blower motor retrofit cycles:Appliance OEMs in North America are qualifying ferrite alternatives to reduce rare-earth dependency in residential systems.
- Recycling documentation incentives:China's MIIT export protocols reward producers with closed-loop powder recovery systems.
Industry Challenges
- Coercivity engineering talent scarcity:Formulation chemists capable of optimizing iron oxide-strontium ratios above 3,000 Oersted are concentrated in Zhejiang and Beijing corridors.
- Dual certification timelines:Producers must simultaneously satisfy Japan's METI JIS C 2502 benchmarks and China's GB/T 13560 standards to serve tier-one automotive contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arc Ferrite Magnet Market |
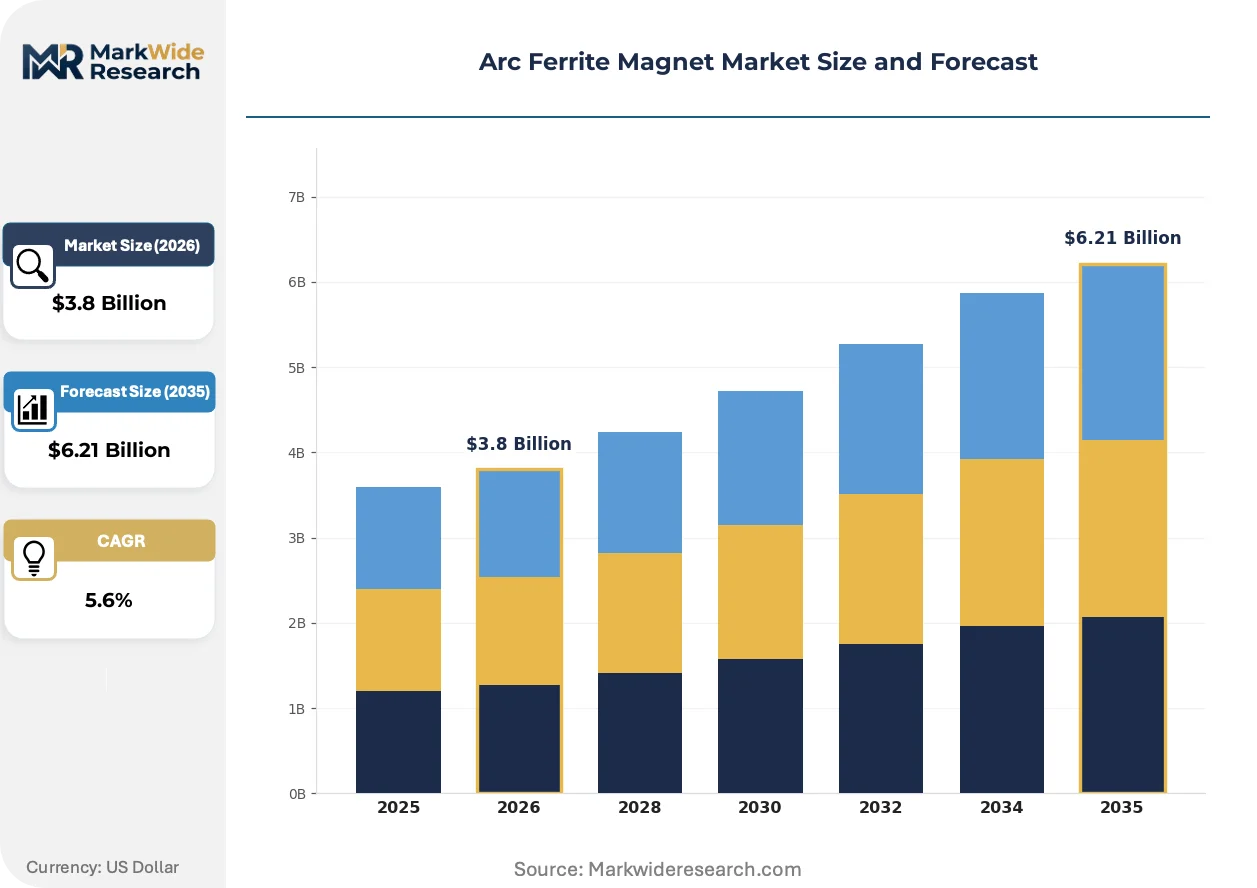
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Magnets, Ceramic Magnets, Ferrite Magnets, Rare Earth Magnets End User: Automotive Industry, Aerospace Sector, Electronics Manufacturers, Home Appliances Application: Magnetic Sensors, Electric Motors, Magnetic Strips, Power Tools Shape: Rectangular, Circular, Custom Shapes, Arc Shapes |
| Companies Covered | DMEGC Magnetics, BGRIMM Magnetic Materials & Technology Co., Ltd., Arnold Magnetic Technologies, Ningbo Vastsky Magnet Co., Ltd., Anhui Earth-Panda Advance Magnetic Material Co., Ltd., Adams Magnetic Products Co., Electron Energy Corporation, Hangzhou Permanent Magnet Group, Hitachi Metals, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arc Ferrite Magnet Market Emerging Trajectories
Continuous kiln investments and powder metallurgy automation are compressing production cycles while regulatory divergence between Asian efficiency mandates and Western environmental compliance is fragmenting capacity siting decisions.
Isotropic-to-anisotropic powder pressing is collapsing the performance gap between economy-grade ferrite segments and mid-tier rare-earth alternatives. Automotive tier-one suppliers in Germany and Japan are adopting these enhanced ceramic formulations for auxiliary motor applications. The technology is collapsing price premiums previously commanded by sintered NdFeB in power steering and HVAC blower assemblies.
Japan's METI JIS C 2502 performance benchmarks are tightening dimensional tolerance specifications for industrial motor qualification. Arc segment producers must now demonstrate thermal stability above 150°C and coercivity degradation rates below 3% per 1,000 hours. Japanese industrial motor OEMs are consolidating supplier panels to those with certified Beijing or Zhejiang R&D facilities.
Buyer concentration among automotive tier-one integrators is compressing supplier qualification cycles from 24 months to 14 months. Direct contracting with powder metallurgy specialists is displacing distributor-mediated procurement in high-volume motor programs. This pattern is most visible in East Asian manufacturing corridors where DMEGC Magnetics and BGRIMM anchor captive supply relationships.
Arc Ferrite Magnet Market Segmentation
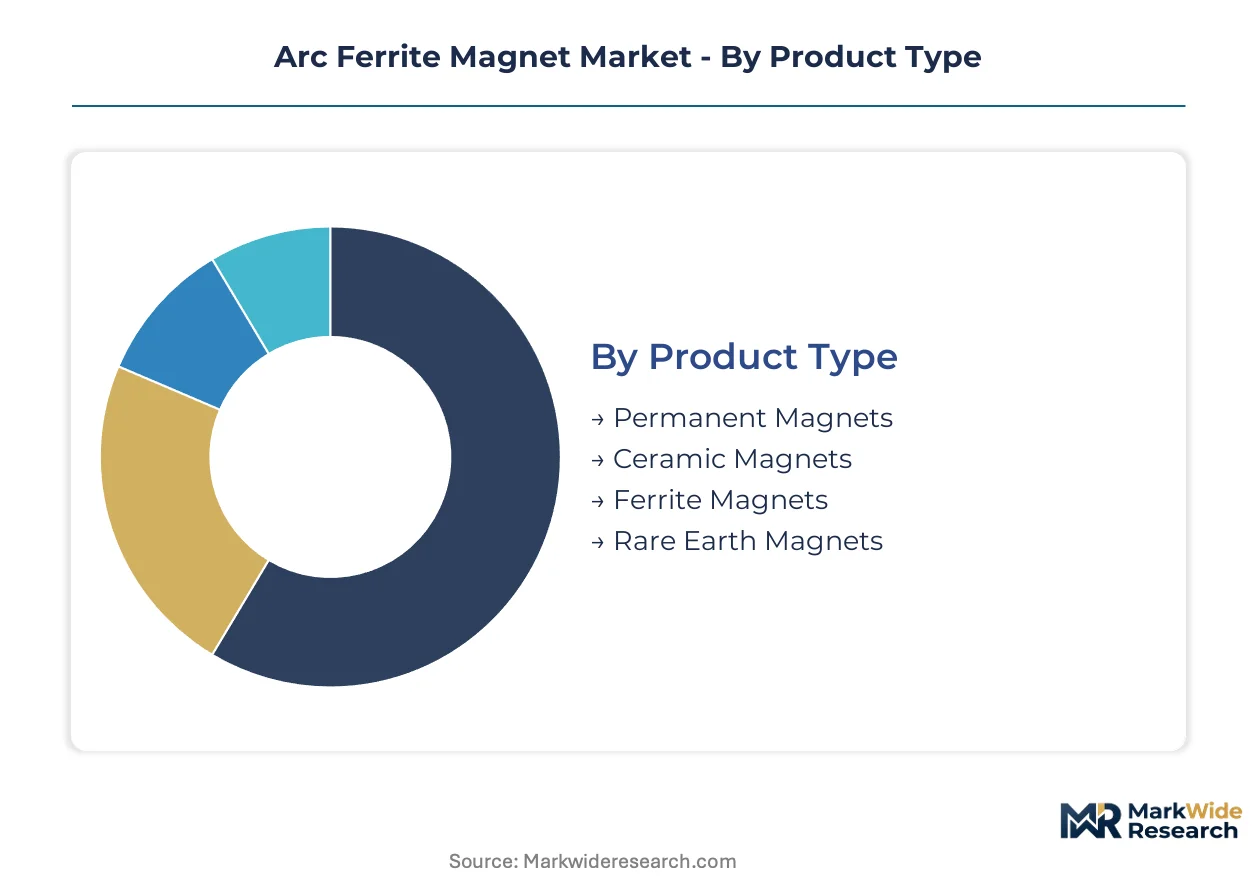
Arc ferrite magnet procurement patterns diverge sharply across product grades, end-use specifications, and geometric tolerances. Suppliers configure powder metallurgy lines and kiln investments to serve distinct margin pools rather than undifferentiated volume.
Product Type:
Cost tier determines raw material sourcing strategy and coercivity engineering intensity across magnet categories.
- Permanent Magnets:Sintered ceramic composites of iron oxide and strontium carbonate achieve coercivity above 3,000 Oersted through high-temperature firing. Automotive traction motor assemblies in Germany and Japan concentrate procurement here as OEMs expand EV production lines.
- Ceramic Magnets:Economy-grade formulations dominate HVAC blowers and appliance drives where thermal stability requirements remain moderate. China's Zhejiang Province anchors global ceramic magnet output through continuous kiln automation.
- Ferrite Magnets:Barium carbonate variants serve cost-sensitive industrial motor retrofits with reduced heavy-metal content per China's MIIT GB/T 13560 export protocols.
- Rare Earth Magnets:Neodymium-iron-boron alternatives capture premium aerospace and medical device applications where dimensional tolerances tighten below 50 microns.
Permanent magnets command the established base. The steepest expansion runs through rare earth magnets.
End User:
Application maturity shapes supplier qualification cycles and certification requirements across customer categories.
- Automotive Industry:Tier-one integrators in Germany, Japan, and China are compressing supplier qualification from 24 months to 14 months for traction motor arc segments. China's MIIT energy-efficiency mandates are tightening material specifications and reshaping supplier panels.
- Aerospace Sector:Precision-ground arc segments for motor assemblies require thermal stability above 150°C and coercivity degradation below 3% per 1,000 hours. Arnold Magnetic Technologies anchors North American supply for this specification tier.
- Electronics Manufacturers:Contactless position detection demand is expanding magnetic sensor volumes faster than traditional motor applications.
- Home Appliances:North American OEMs are qualifying ferrite alternatives to reduce rare-earth dependency in residential HVAC blower systems.
Automotive industry holds the volume anchor. Electronics manufacturers are climbing the fastest.
Application:
Functional performance requirements separate commodity powder grades from certified formulation tiers.
- Magnetic Sensors:Industrial automation demands contactless position detection with isotropic-to-anisotropic powder pressing collapsing performance gaps against mid-tier rare-earth alternatives.
- Electric Motors:Brushless DC configurations in power steering and HVAC blower assemblies consume the largest arc ferrite volumes. Japan's METI JIS C 2502 benchmarks govern qualification for industrial motor contracts.
- Magnetic Strips:Flexible bonded ferrite formulations serve low-coercivity sealing and holding applications with minimal kiln investment.
- Power Tools:High-torque motor segments favor anisotropic pressed segments with strontium ferrite powder from captive production lines.
Electric motors retain the installed base. Magnetic sensors show the steepest upward trajectory.
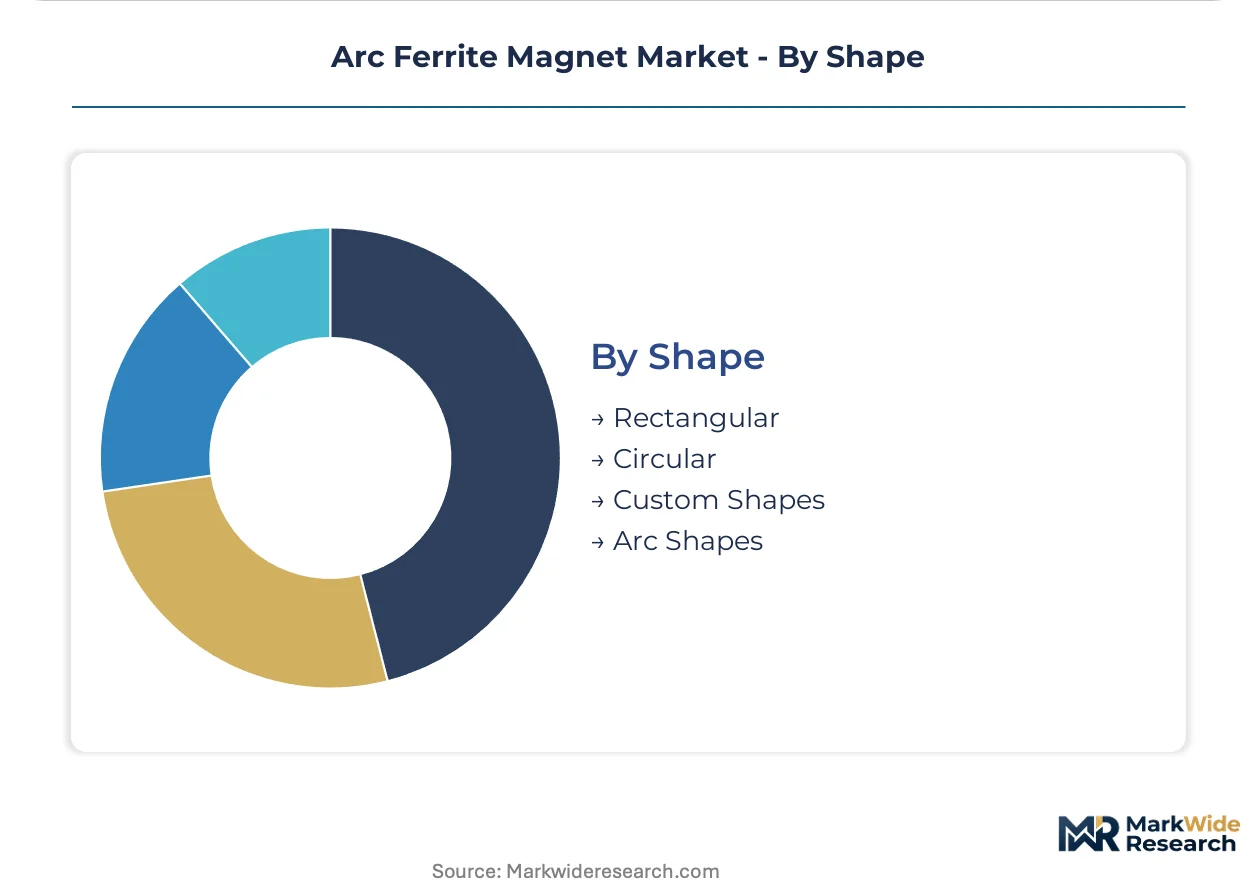
Shape:
Geometric complexity drives grinding automation investment and dimensional tolerance capability.
- Rectangular:Standard block forms serve commodity holding and speaker applications with minimal post-sintering machining.
- Circular:Ring magnets for rotary encoder and pump motor applications require centerless grinding to tight concentricity specifications.
- Custom Shapes:Medical device brushless surgical motors demand dimensional tolerances that create margin pools for certified arc segment suppliers.
- Arc Shapes:Curved segments convert electrical to mechanical energy in permanent magnet DC motors and brushless configurations. DMEGC Magnetics and BGRIMM anchor captive supply relationships for automotive tier-one programs.
Arc shapes dominate motor integration. Custom shapes are gaining share fastest in precision medical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through GB/T 13560 standards that constrain heavy-metal content and mandate recycling documentation for ferrite magnet exports. Automotive electrification programs in Germany and Japan are accelerating procurement of arc ferrite magnets for traction motor assemblies. Industrial clusters in Zhejiang Province and surrounding East Asian manufacturing corridors concentrate powder metallurgy automation and continuous kiln investments.
China
Automotive tier-one integrators and appliance OEMs drive procurement volumes for traction motor and HVAC blower applications. MIIT energy-efficiency mandates tighten material specifications and reshape supplier qualification criteria for export documentation. Zhejiang Province anchors global ceramic magnet output through DMEGC Magnetics and BGRIMM manufacturing bases with captive strontium ferrite powder production.
Germany
EV production line expansions by domestic OEMs accelerate arc ferrite magnet procurement for auxiliary motor applications. KBA vehicle certification protocols indirectly govern motor component material standards through type-approval requirements. Bavaria and Baden-Württemberg industrial corridors host precision grinding facilities serving automotive tier-one contracts with compressed 14-month qualification cycles.
Japan
Industrial motor OEMs and automotive suppliers concentrate demand for high-coercivity arc segments above 3,000 Oersted. METI administers JIS C 2502 performance benchmarks requiring thermal stability above 150°C and coercivity degradation below 3% per 1,000 hours. Kansai and Chubu manufacturing belts consolidate supplier panels to producers with certified Beijing or Zhejiang R&D facilities.
United States
North American appliance OEMs qualify ferrite alternatives to reduce rare-earth dependency in residential HVAC blower systems. EPA monitors particulate emissions from ferrite calcination and grinding operations, pressuring baghouse filtration installation or finishing stage relocation. Midwest industrial corridors and Southeast manufacturing zones concentrate precision-ground arc segment production for aerospace motor assemblies.
South Korea
Electronics manufacturers and automotive suppliers expand magnetic sensor volumes for industrial automation contactless position detection. MFDS and national industrial standards bodies align with JIS C 2502 benchmarks for motor component qualification. Seoul Capital Area and Busan-Ulsan corridors concentrate powder metallurgy automation investments serving domestic and export motor programs.
Arc Ferrite Magnet Market Vendor Landscape
Capability concentration sits with vertically integrated powder metallurgy specialists; scale advantage sits with continuous kiln operators serving high-volume automotive contracts. The vendor base separates into three tiers: captive strontium ferrite producers, precision grinding specialists for aerospace and medical applications, and economy-grade ceramic magnet fabricators. Strategic moves center on backward integration into raw material processing and geographic expansion to satisfy dual certification requirements for Japan's METI and China's MIIT standards.
Among Chinese integrated producers, DMEGC Magnetics and BGRIMM Magnetic Materials & Technology Co., Ltd. occupy positions exemplifying the captive supply archetype through in-house strontium ferrite powder production. Arnold Magnetic Technologies represents the precision-specialist tier, anchoring North American supply for dimensional tolerance-intensive applications. These three entities illustrate the structural divergence between scale-driven ceramic output and certified premium-grade arc segment supply.
| Leading Market Players |
|---|
| DMEGC Magnetics |
| BGRIMM Magnetic Materials & Technology Co., Ltd. |
| Arnold Magnetic Technologies |
| Ningbo Vastsky Magnet Co., Ltd. |
| Anhui Earth-Panda Advance Magnetic Material Co., Ltd. |
| Adams Magnetic Products Co. |
| Electron Energy Corporation |
| Hangzhou Permanent Magnet Group |
| Hitachi Metals, Ltd. |
| Others |
Supply Flow & Price Mechanics
Zhejiang Province's continuous kiln investments and powder metallurgy automation are compressing production cycles and amplifying cost leadership for regional producers serving automotive tier-one contracts. This supply-side efficiency translates into pricing power asymmetries where captive strontium ferrite producers sustain margin stability while non-integrated fabricators face cost compression.
Pricing Analysis
Price spreads between East Asian manufacturing corridors and North American precision grinding facilities reflect divergent cost structures and certification overhead. Pricing stratifies across certified automotive-grade, standard industrial-grade, and economy appliance-grade tiers, with JIS C 2502 and GB/T 13560 compliance levels driving differentiation. Cost compression in ceramic magnet segments is intensifying because China's MIIT recycling documentation mandates elevate compliance spending for export-oriented producers. Appliance OEMs in residential HVAC systems exhibit highest price sensitivity, while aerospace motor assemblies demonstrate lowest sensitivity due to dimensional tolerance requirements.
Supply Chain Analysis
Tariff exposure between Chinese processing corridors and German automotive assembly plants dominates supply chain risk calculations for arc ferrite magnet procurement. Production gravity centers on China, Japan, and Germany, with strontium carbonate, iron oxide, and barium carbonate feeding from mineral processing concentrations in East Asian supply zones. Single-source vulnerability in strontium ferrite powder supply creates consolidation pressure as DMEGC Magnetics and BGRIMM anchor captive production relationships. Distribution runs through direct contracting with automotive tier-one integrators, displacing distributor-mediated procurement in high-volume motor programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes this market as automotive electrification programs and industrial automation sensor demand create specialized niches alongside commodity ceramic magnet supply. Supplier qualification compression from 24 months to 14 months opens entry points for certified specialists.
For Market Incumbents: Entrench through backward integration into strontium ferrite powder production and dual certification investment for Japan's METI JIS C 2502 and China's MIIT GB/T 13560 standards. Neodymium-iron-boron substitution in premium thermal stability applications threatens margin pools; defend through precision grinding automation for aerospace and medical device segments. Capacity addition in Zhejiang Province manufacturing corridors reinforces cost position against emerging economy-grade competitors. For New Entrants and Emerging Players: North American HVAC blower motor retrofit cycles present accessible entry points as appliance OEMs qualify ferrite alternatives to reduce rare-earth dependency. Medical device brushless surgical motors offer the most penetrable precision segment given dimensional tolerance requirements and compressed supplier panels. Pursue direct contracting relationships with tier-one automotive integrators rather than distributor channels to capture qualification cycle efficiencies. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because supplier panel consolidation among automotive tier-one integrators favors scaled producers with certified R&D facilities. Target acquisition archetypes include vertically integrated powder metallurgy specialists with captive strontium ferrite production and dual jurisdiction certification. Watch for MIIT export documentation enforcement intensity as inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strontium Ferrite Powder | DMEGC Magnetics and BGRIMM demonstrate margin stability through captive raw material production. |
| Dual Certification Investment | Simultaneous JIS C 2502 and GB/T 13560 compliance unlocks tier-one automotive contract access. |
| Precision Grinding Automation | Aerospace motor assemblies demand thermal stability above 150°C and sub-50 micron tolerances. |
| Recycling Documentation Systems | China's MIIT export protocols reward producers with closed-loop powder recovery infrastructure. |
| Direct Tier-One Contracting | Compressed 14-month qualification cycles favor suppliers bypassing distributor intermediaries. |
Methodological Framework
Operator-level perspectives from powder metallurgy plant managers, automotive tier-one procurement leads, appliance OEM supply planners, and aerospace motor assembly engineers anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, MIIT GB/T standard filings, METI JIS certification registries, and SEC 10-K disclosures from magnetic materials producers. Bottom-up segment sizing and top-down macro constraint triangulation ensured cross-verification of volume and value estimates.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing around strontium carbonate input volatility and rare-earth substitution elasticity. Segmentation dimensions modeled include product grade tier, end-use industry, geometric tolerance specification, and regional regulatory cluster. CAGRs derived from regression against historical automotive production and appliance shipment data, with electric vehicle motor content per vehicle and industrial automation sensor penetration as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-supported producers or accelerated neodymium-iron-boron cost reduction would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Flat Carbon Steel Market
Metals
316 Stainless Steel Container Market
Metals
Metal Powder Market
Metals
Merchant Bar Quality (MBQ) Steel Market
Metals
Copper Smelting Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
Aluminum Flat Products Market
Metals
Refined Nickel Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Heat-Treated Steel Plates Market
Metals
Aluminum Extrusion Market
Metals
TMCP Steel Market
Metals
Global Copper Cathode Market
Metals
Copper Azoles Market
Metals
Neodymium Market
Metals
Monel Alloy Market