
 Monel Alloy Market | 2026-2036
Monel Alloy Market Size, Share, and Industry Trends Forecast 2026-2036
Monel Alloy Market Foresight
REACH compliance is broadening the cost-of-entry calculus for European-sourced Monel feedstock. Special Metals Corporation anchors North American melt capacity through its integrated Huntington, West Virginia facility. VDM Metals GmbH leverages vacuum induction melting expertise to sustain premium positioning in aerospace-certified grades. Alleima competes on precision-rolled strip for chemical processing OEMs across Scandinavia and Germany.
Monel alloys are nickel-copper solid-solution alloys, typically containing 67% nickel and 30% copper with trace iron and manganese, engineered for exceptional resistance to seawater corrosion, chlorides, and sulfuric acid environments across subsea, chemical, and propulsion systems. Monel 400 dominates volume flows into marine valve and pump castings where decades of service life justify material cost premiums. Monel K-500, precipitation-hardened with aluminum and titanium, captures the fastest-growing share in aerospace landing gear and high-strength fastener applications demanding yield strength above 965 MPa. Sheet and bar forms command the widest fabrication flexibility, while wire specialty from producers like Alloy Wire International serves niche instrumentation and sealing applications with tight chemistry control.
The US EPA, BSEE, and EU REACH framework collectively shape material qualification protocols, with offshore safety case requirements in the North Sea and Gulf of Mexico mandating traceable melt-to-finish documentation for pressure-containing components. China's GB standards and NMPA-equivalent pressure equipment rules add parallel certification burdens for suppliers targeting domestic refinery expansion. Stakeholders must monitor divergence between US and EU hydrogen sulfide testing protocols, as misaligned qualification timelines risk locking fabricators out of dual-market bidding for sour service projects.
Market Dynamics
Offshore safety case mandates from the US BSEE and EU offshore directives are compressing qualification timelines for corrosion-resistant alloys, forcing fabricators to pre-certify material lots before project bidding rather than post-award.
Growth Catalysts
- Subsea infrastructure buildout:Gulf of Mexico and North Sea operators are expanding subsea manifold and tieback projects requiring Monel 400 valve bodies rated for 30-year seawater exposure.
- REACH substance restrictions:The EU ECHA framework is restricting competing cobalt-based alloy feedstocks, redirecting chemical processing OEMs toward nickel-copper alternatives with established safety dossiers.
- Hydrogen sulfide testing alignment:Convergence between US NACE and ISO 15156 sour service protocols is unifying qualification standards, reducing duplicate testing costs for dual-market suppliers.
Market Restraints
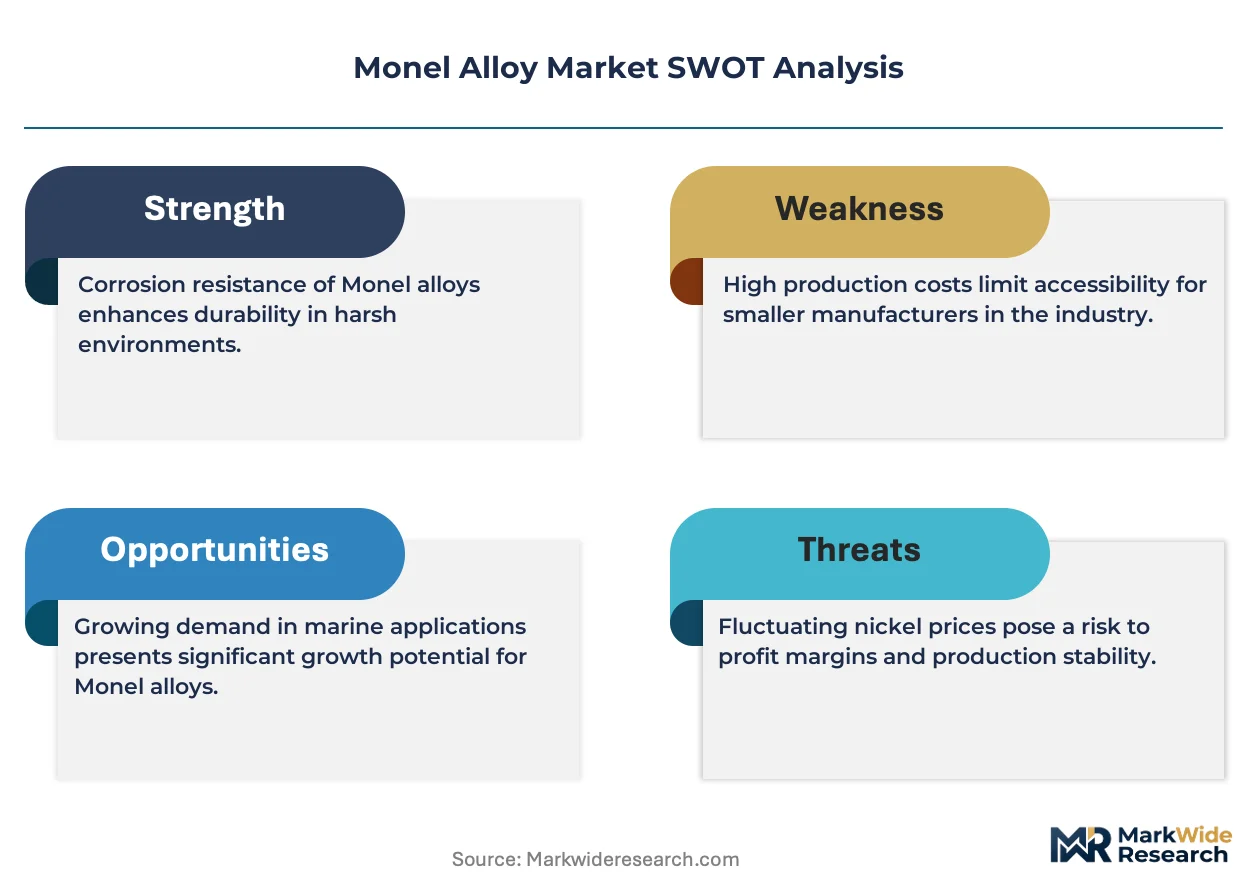
- Nickel price volatility:LME nickel contract swings above 40% annually compress mill margin visibility and deter long-term supply agreements for high-nickel alloys.
- Melt capacity concentration:North American vacuum induction melting is geographically concentrated in Appalachia, creating hurricane and logistics exposure for just-in-time aerospace orders.
- Titanium substitution in fasteners:Ti-6Al-4V aerospace fastener stock is displacing Monel K-500 in non-magnetic applications where weight reduction outweighs corrosion requirements.
Strategic Opportunities
- India refinery expansion:Reliance Industries and Indian Oil are building sour crude processing units requiring chloride-resistant heat exchanger tubing in quantities exceeding domestic stainless supply.
- Green hydrogen electrolyzer manifolds:Alkaline electrolyzer OEMs are testing Monel 400 for high-purity hydrogen handling where embrittlement resistance exceeds 316L stainless capabilities.
- US Inflation Reduction Act domestic content:IRA clean energy manufacturing credits are incentivizing onshore alloy production for offshore wind subsea cable terminations.
Industry Challenges
- Weld procedure qualification backlog:ASME Section IX weld procedure certifications for Monel K-500 thick sections are running 14-18 months, delaying aerospace landing gear contract starts.
- Traceability system fragmentation:Melt-to-finish documentation requirements diverge between US BSEE safety cases and EU PED 2014/68/EU module H, forcing dual IT system investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monel Alloy Market |
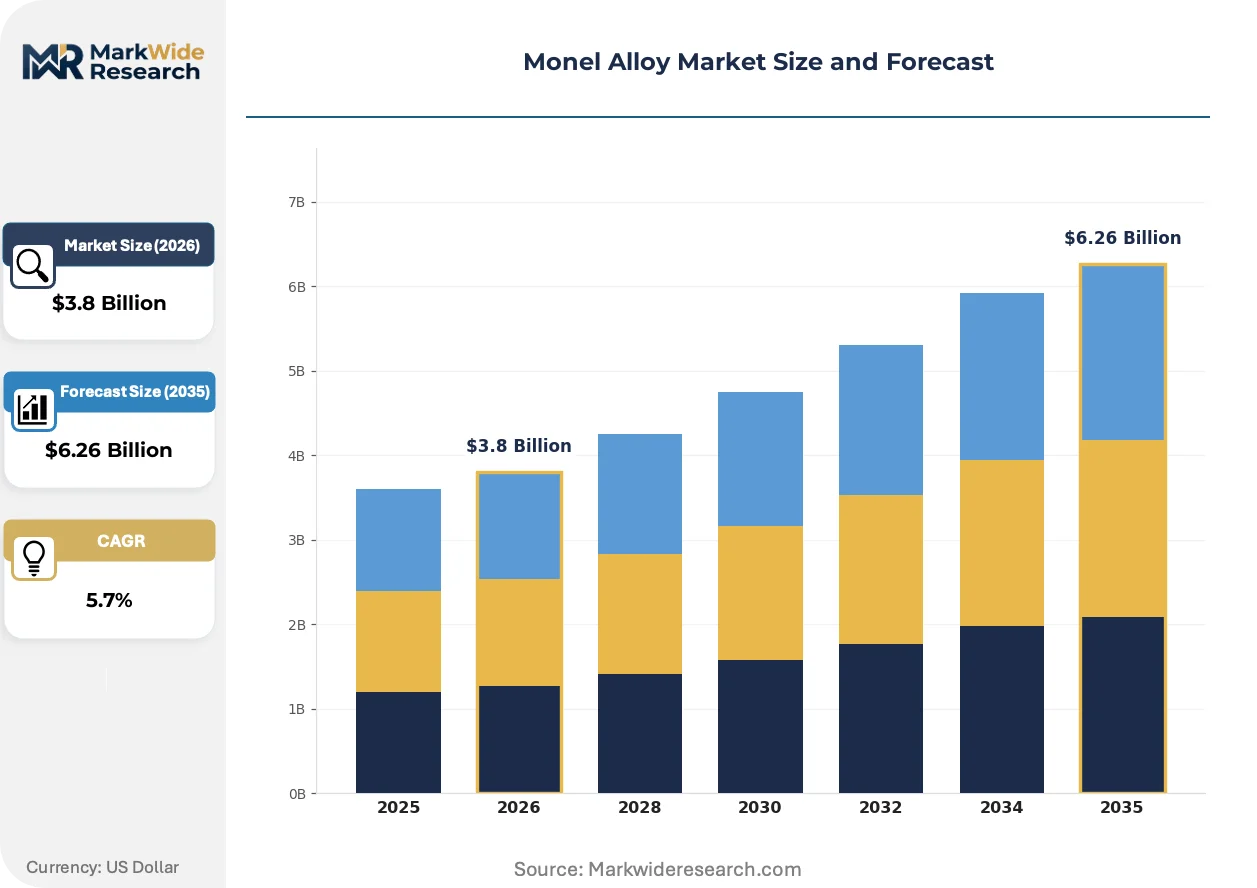
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monel 400, Monel K-500, Monel 404, Monel R-404 Form: Sheet, Bar, Pipe, Wire End User: Aerospace, Marine, Chemical Processing, Oil & Gas Application: Corrosion Resistant Applications, Heat Exchangers, Valves, Pumps |
| Companies Covered | Deutsche Nickel GmbH, Ulbrich Stainless Steels and Special Metals, Special Metals Corporation, Sandmeyer Steel Company, AEETHER, Alleima, Alloy Wire International, Raajratna, VDM Metals GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monel Alloy Market Shifts & Advancements
Additive manufacturing of nickel-copper alloys is crossing from prototyping into qualified production, with powder bed fusion parameters now validated for marine impeller geometries previously machined from solid bar.
Direct metal laser sintering of Monel K-500 is unifying complex lattice structures with precipitation-hardened strength, enabling aerospace OEMs to consolidate multi-part landing gear assemblies into single printed components. Honeywell and Safran are qualifying these parts for non-structural brackets initially, with load-bearing applications following by mid-decade. The technology is compressing lead times from 26-week forging cycles to 72-hour print-to-heat-treat sequences.
EPA methane emission rules under the Clean Air Act are tightening packing and seal specifications for offshore valves, mandating corrosion-resistant alloys in previously carbon-acceptable service. The regulation is forcing operators to replace 20-year-old valve inventories ahead of failure, accelerating replacement demand. Gulf of Mexico fabrication yards are responding by pre-stocking Monel 400 trim sets for standardized API 6A wellhead configurations.
Integrated mill-direct procurement is displacing distributor stocking for high-specification aerospace grades, with OEMs establishing VMI arrangements at Special Metals and VDM to secure heat-lot traceability. Tier-1 fastener manufacturers are bypassing service centers entirely, drawing bar stock against forecasted call-offs. This pattern is most visible in Germany and the US, where landed cost calculations now include customs documentation risk rather than inventory carrying cost alone.
Monel Alloy Market Segmentation
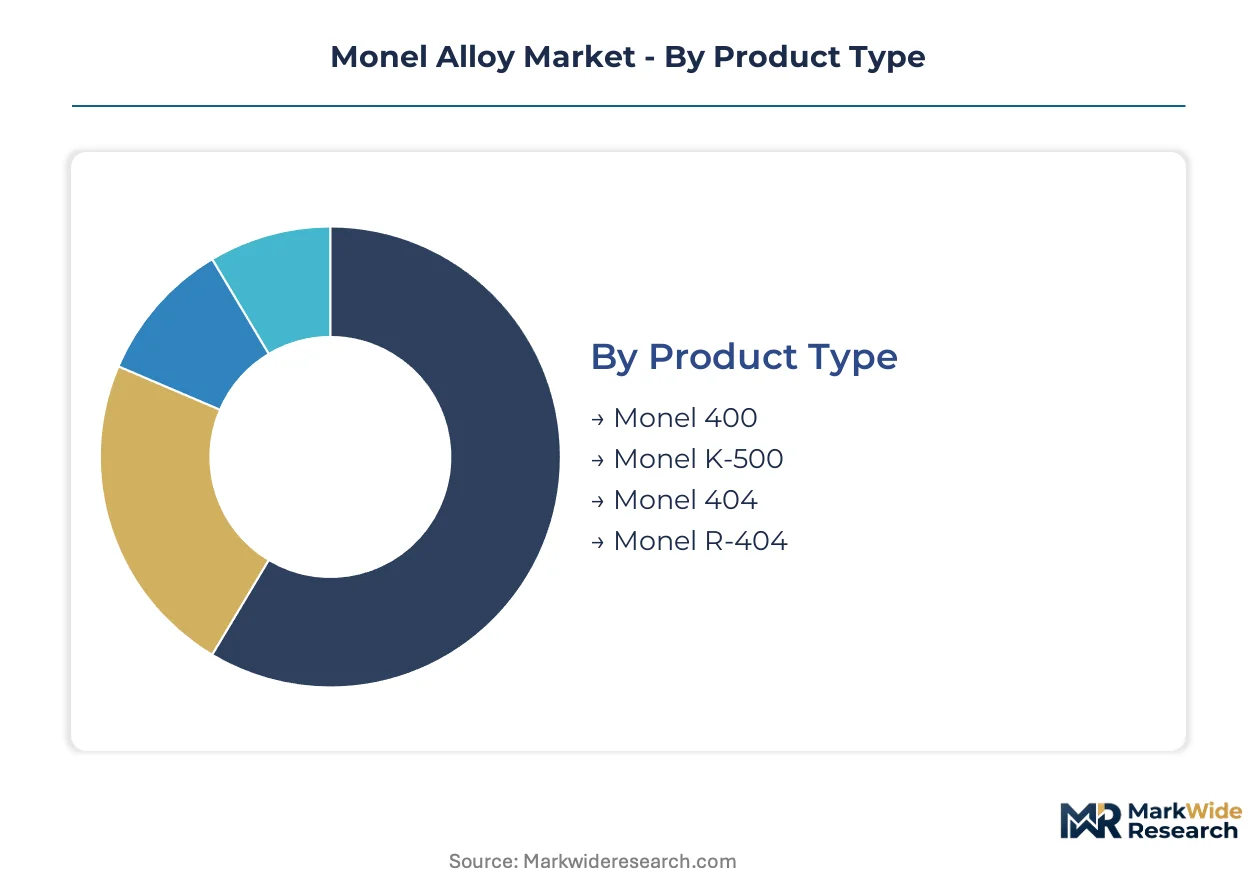
Monel alloy procurement decisions pivot on material grade specifications, form factor constraints, and end-use certification requirements. Fabricators must align feedstock selection with ASME pressure vessel codes, NACE sour service protocols, and aerospace OEM material qualification lists. Each segmentation dimension carries distinct margin profiles and technical barriers that shape supplier positioning.
Product Type:
Capital intensity escalates sharply with alloy complexity, driven by vacuum induction melting capacity requirements and precipitation-hardening process controls.
- Monel 400:The nickel-copper solid-solution baseline contains approximately 67% nickel and 30% copper with minimal iron and manganese traces. Gulf of Mexico subsea valve manufacturers specify this grade for 30-year seawater exposure applications where corrosion resistance outweighs strength requirements. Huntington melt shops dedicate continuous casting lines to this high-volume grade.
- Monel K-500:Aluminum and titanium additions enable precipitation hardening to yield strengths exceeding 965 MPa. Aerospace landing gear OEMs in Germany and the US specify this grade for high-strength fastener applications where Ti-6Al-4V substitution remains incomplete. Vacuum arc remelting capacity constraints limit supplier participation.
- Monel 404:Tailored for specialized brazing applications with controlled chemistry for filler metal compatibility.
- Monel R-404:Modified composition for enhanced machinability in precision instrumentation components.
Monel 400 absorbs the bulk of installed capacity; Monel K-500 is expanding most quickly.
Form:
Processing route selection determines lead time reliability and dimensional tolerance achievement for downstream fabrication.
- Sheet:Cold-rolled strip from Alleima's Sandviken facility serves Scandinavian chemical processing OEMs requiring tight thickness tolerances for heat exchanger plate stacks. Precision rolling investments exceed $50 million per production line.
- Bar:Rotary forged and peeled bar stock dominates aerospace fastener feedstock flows, with VDM Metals supplying German Tier-1 manufacturers under vendor-managed inventory arrangements.
- Pipe:Seamless extruded and drawn tubing serves offshore riser and flowline applications.
- Wire:Fine wire specialty from Alloy Wire International addresses instrumentation and sealing applications with sub-millimeter diameter control.
Sheet and bar command the widest fabrication flexibility; wire specialty sustains premium pricing through chemistry control.
End User:
Customer concentration and certification burden vary dramatically across industrial verticals, reshaping go-to-market economics.
- Aerospace:Landing gear and fastener OEMs impose 18-24 month material qualification cycles with heat-lot traceability mandates. Safran and Honeywell are qualifying additively manufactured Monel K-500 brackets for non-structural applications initially.
- Marine:Shipbuilders and subsea fabricators in the US Gulf Coast cluster specify Monel 400 for seawater-cooled systems and valve trim. EPA and BSEE safety case requirements compress bidding timelines.
- Chemical Processing:REACH-compliant nickel-copper alternatives are displacing restricted cobalt-based alloys in European chlor-alkali plants.
- Oil & Gas:Sour service wellhead components require NACE MR0175/ISO 15156 qualification for hydrogen sulfide exposure.
Aerospace absorbs the longest qualification cycles; chemical processing is redirecting fastest toward nickel-copper alternatives.
Application:
Functional performance requirements dictate alloy grade selection and form factor combination for each use case.
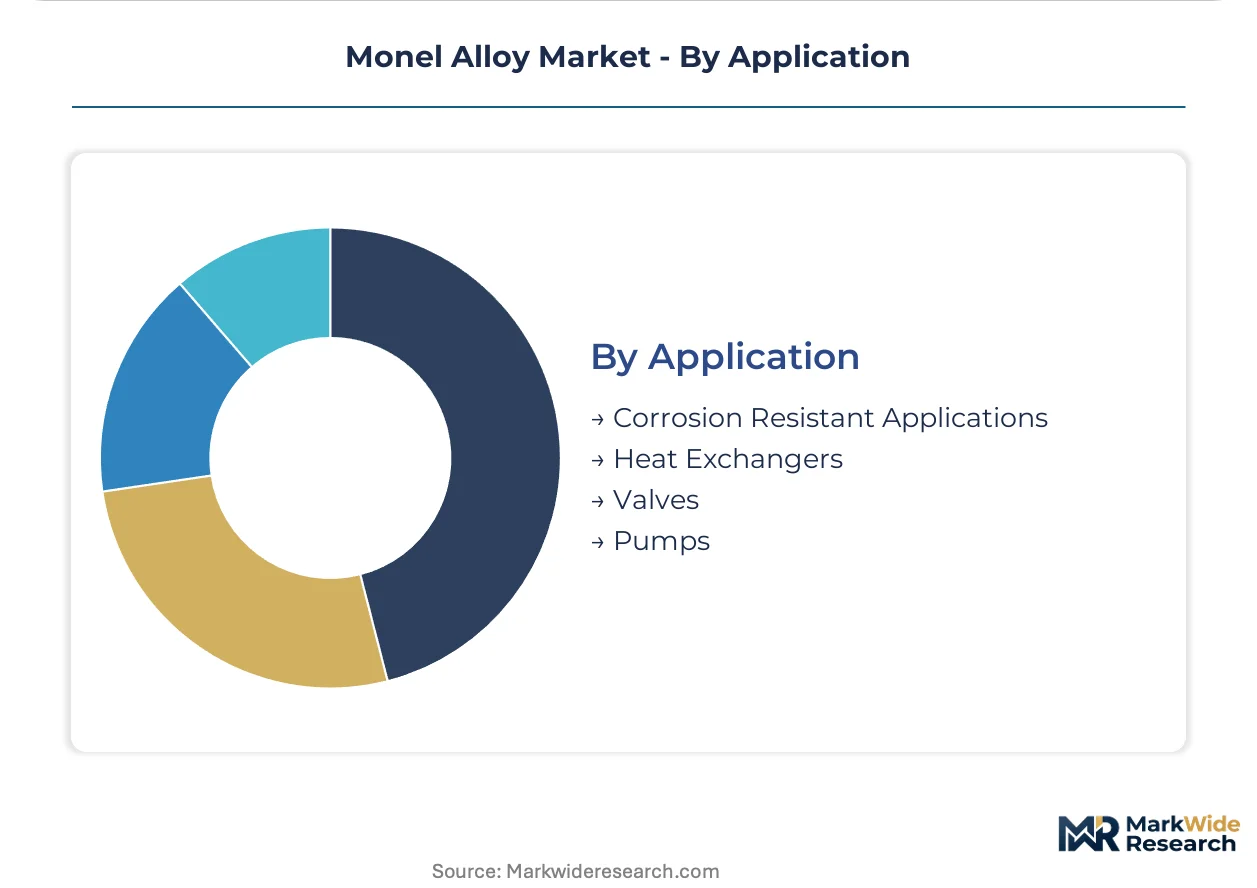
- Corrosion Resistant Applications:Seawater exposure systems in offshore platforms and coastal power plants specify Monel 400 for chloride resistance exceeding 316L stainless capabilities. Replacement demand is accelerating under EPA methane emission rules mandating upgraded valve packing.
- Heat Exchangers:Reliance Industries and Indian Oil are sourcing chloride-resistant tubing for sour crude processing units exceeding domestic stainless supply availability.
- Valves:API 6A wellhead trim sets require traceable melt-to-finish documentation for BSEE safety case compliance.
- Pumps:Subsea manifold pump castings demand 30-year service life justification for material cost premiums.
Corrosion resistant applications anchor volume demand; heat exchangers are climbing the fastest on refinery expansion in India.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast foreign trade zone drives subsea fabrication concentration, attracting vacuum induction melt capacity to Louisiana and Texas port corridors. Special economic zone status in India's Gujarat and Saudi Arabia's Ras Al-Khair are redirecting petrochemical alloy procurement patterns.
United States
BSEE safety case mandates and EPA methane emission rules compress qualification timelines for offshore valve manufacturers. The Inflation Reduction Act domestic content provisions incentivize onshore melt capacity expansion. Houston-Galveston fabrication yards pre-stock Monel 400 trim sets for API 6A wellhead configurations under accelerated replacement schedules.
Germany
REACH substance restrictions on cobalt-based alloys redirect chemical processing OEMs toward nickel-copper alternatives with established safety dossiers. VDM Metals anchors vacuum induction melting expertise for aerospace-certified grades. The Ruhr industrial corridor sustains precision-rolled strip demand from Scandinavian heat exchanger manufacturers.
India
Reliance Industries and Indian Oil refinery expansions exceed domestic stainless supply for sour crude processing units. The country's national petroleum regulator imposes parallel certification burdens for pressure equipment rules. Gujarat's Dahej and Hazira industrial zones concentrate chloride-resistant tubing procurement for new alkylation units.
Saudi Arabia
Sour gas field development in the Eastern Province requires NACE MR0175-qualified alloys for hydrogen sulfide exposure. The national industrial development program prioritizes localized supply chain formation. Ras Al-Khair's metals processing zone attracts toll melting arrangements for regional oilfield service companies.
China
GB standards and NMPA-equivalent pressure equipment rules add certification burdens for domestic refinery expansion projects. Dual carbon goals accelerate scrutiny of high-energy alloy production routes. Shandong's petrochemical clusters source nickel-copper alternatives for chlor-alkali plant retrofits restricted under competing cobalt alloy regulations.
Monel Alloy Market Competitive Landscape
North American producers anchor one tier; European specialists hold premium positioning through aerospace certification depth. The vendor base concentrates around vacuum induction melting capacity with geographic clustering in Appalachia and the Ruhr. Three archetypes dominate: integrated melt-to-finish mills, precision rolling specialists, and wire drawing niche operators. Capacity expansion and vendor-managed inventory arrangements constitute the dominant competitive moves as OEMs bypass distributors for heat-lot traceability.
Among German-based fabricators, Deutsche Nickel GmbH and VDM Metals GmbH exemplify the premium-grade tier with vacuum metallurgy heritage. Special Metals Corporation anchors North American melt capacity through its integrated Huntington facility. Alleima occupies a position bridging Scandinavian precision rolling with chemical processing OEM supply chains. These three represent the geographic and capability spread defining competitive positioning.
| Leading Market Players |
|---|
| Deutsche Nickel GmbH |
| Ulbrich Stainless Steels and Special Metals |
| Special Metals Corporation |
| Sandmeyer Steel Company |
| AEETHER |
| Alleima |
| Alloy Wire International |
| Raajratna |
| VDM Metals GmbH |
| Others |
Supply & Pricing Matrix
Appalachian vacuum induction melting specialists command wage premiums 15-20% above regional manufacturing baselines, compressing margin spreads between aerospace-certified and industrial-grade Monel feedstock tiers. Labor-cost differentials between Huntington melt shops and European precision-rolling facilities amplify pricing stratification across certificate-grade boundaries.
Pricing Analysis
Lead-time premiums dominate transactional pricing, with 26-week forging-cycle aerospace grades commanding 35-40% markups over spot-available industrial bar stock. Three-tier pricing structure separates NACE-qualified sour service material from standard marine grades and uncertified commodity forms. Price differentiation hinges on heat-lot traceability depth and vacuum arc remelting passes. Cost compression in industrial-grade sheet runs through nickel price volatility transmission from LME contract swings. Chemical processing OEMs exhibit highest price sensitivity; aerospace fastener manufacturers accept premiums for qualification continuity.
Supply Chain Analysis
Direct-to-OEM channels handle Tier-1 aerospace demand, with vendor-managed inventory arrangements displacing distributor intermediation for heat-lot traceability. Geographic supply concentrates in the United States, Germany, and Sweden for vacuum metallurgy capacity; China and India draw from toll-melting arrangements for domestic refinery expansion. Raw material dependencies rest on LME nickel cathode, high-purity copper cathode, and titanium sponge for K-500 precipitation hardening. Single-source vulnerability pervades vacuum induction melting capacity in hurricane-exposed Appalachia. Distribution runs through integrated mill-direct procurement for aerospace grades and regional service centers for industrial maintenance flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is reshaping competitive positioning as vacuum induction melting capacity becomes the contested upstream lever for margin defense and aerospace qualification access.
For Market Incumbents: Deepen backward integration into nickel cathode sourcing through long-term offtake arrangements with mining concentrators, insulating margin exposure from LME volatility. Expand Huntington melt capacity ahead of IRA domestic content enforcement for offshore wind subsea cable terminations. Titanium substitution in non-magnetic aerospace fasteners threatens K-500 volume; accelerate additive manufacturing qualification for complex landing gear geometries to defend specialty positioning. For New Entrants and Emerging Players: Begin with toll-melting arrangements at underutilized European vacuum induction facilities, avoiding capital-intensive greenfield capacity investments. Target India's Gujarat refinery corridor for chloride-resistant heat exchanger tubing supply, where Reliance Industries and Indian Oil expansion exceeds domestic stainless availability. Pursue qualification partnerships with Scandinavian chemical processing OEMs displaced from cobalt-based alloys under REACH restrictions. For Investors and Strategic Acquirers: Re-rating potential sits with precision-rolling specialists possessing aerospace certification depth given additive manufacturing parameter validation trends. Long-term viability favors vendors controlling melt-to-finish traceability systems compatible with both BSEE safety cases and EU PED module H requirements. Watch weld procedure qualification backlog duration as inflection signal; compression below 12 months indicates capacity expansion adequacy, extension beyond 18 months signals supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Cathode Supply | Long-term offtake arrangements with mining concentrators hedge LME volatility exposure for Huntington melt shops. |
| Additive Manufacturing Qualification | Honeywell and Safran validation of powder bed fusion Monel K-500 compresses 26-week forging cycles to 72-hour sequences. |
| Vendor-Managed Inventory Expansion | Direct mill-OEM arrangements at Special Metals and VDM eliminate distributor markups while securing heat-lot traceability. |
| REACH-Compliant Safety Dossier Investment | Established nickel-copper toxicology profiles capture chemical processing OEMs displaced from restricted cobalt alloys. |
| Weld Procedure Certification Acceleration | ASME Section IX backlog reduction below 14 months unlocks aerospace landing gear contract starts for K-500 thick sections. |
Research Methodology
Independent corroboration across melt shop production managers, aerospace procurement leads at Tier-1 fastener manufacturers, and chemical processing OEM technical directors underwrites the qualitative findings. Secondary validation draws from BSEE safety case filings, EU ECHA substance restriction updates, SEC 10-K disclosures from publicly traded alloy producers, and customs trade data for nickel-copper alloy flows. Bottom-up capacity assessments at Huntington, Ruhr, and Sandviken facilities triangulate against top-down demand modeling from subsea project backlogs and refinery expansion announcements.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions span alloy grade complexity, form factor processing route, end-use certification burden, and regional regulatory cluster. CAGRs derive from installed capacity utilization trajectories and project pipeline conversion rates. Industry-specific forecast inputs include NACE MR0175 qualification renewal cycles and EPA methane emission rule implementation timelines for valve replacement demand.
Underlying measurement precision varies by segment; aerospace-certified grades carry tighter precision than commodity industrial forms due to visible OEM qualification lists. Forecasts reflect assumptions regarding nickel price regime stability and REACH substance restriction enforcement continuity. Periodic stress-testing of base assumptions is recommended against LME volatility spikes and divergence between US and EU hydrogen sulfide testing protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Zirconium Market
Metals
Global Brazing Consumable Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Russia Metal Fabrication Market
Metals
Aluminium Conductors Market
Metals
316 Stainless Steel Container Market
Metals
Europe Welding Consumables Market
Metals
Metallurgical Coal Market
Metals
Titanium Market
Metals
Heat-Treated Steel Plates Market
Metals
Metal Recycling Market
Metals
Tantalum and Niobium Material Market
Metals
Silver Nitrate Market
Metals
Global Hot Rolled Coil Steel Market
Metals
Aluminum Fluoride Market
Metals
Copper Smelting Market