
 Galvanized Steel Market | 2026-2036
Galvanized Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Galvanized Steel Market Analysis
Chinese integrated steelmakers is consolidating capacity around higher-grade hot-dip galvanizing lines to serve premium automotive and construction accounts. ArcelorMittal leverages its European R&D network to develop zinc-magnesium coating formulations with extended corrosion resistance. POSCO sustains technological leadership through proprietary continuous galvanizing process controls that reduce coating weight variance. NIPPON STEEL CORPORATION anchors its competitive position with specialized automotive exterior panel grades that meet OEM bake-hardening specifications.
Galvanized steel comprises carbon steel substrates coated with zinc through hot-dip or electrogalvanizing processes, typically achieving 40-600 g/m² coating weights that sacrificially protect base metal against atmospheric corrosion for 20-50 years in most environments. The material serves primarily as a cost-effective, low-maintenance structural and aesthetic solution for exposed building envelopes, vehicle bodies, and appliance housings. Flat Products dominate volume flows through construction and automotive channels where coil-fed stamping and roll-forming operations demand uniform gauge and surface quality. Construction Applications absorb the largest share of tonnage, though Automotive Applications command premium pricing for exposed body panels requiring complex forming and weldability. Specialty Products remain a niche margin pool, serving extreme corrosion environments with aluminum-zinc and zinc-aluminum-magnesium alloy coatings that extend service life in marine and agricultural settings.
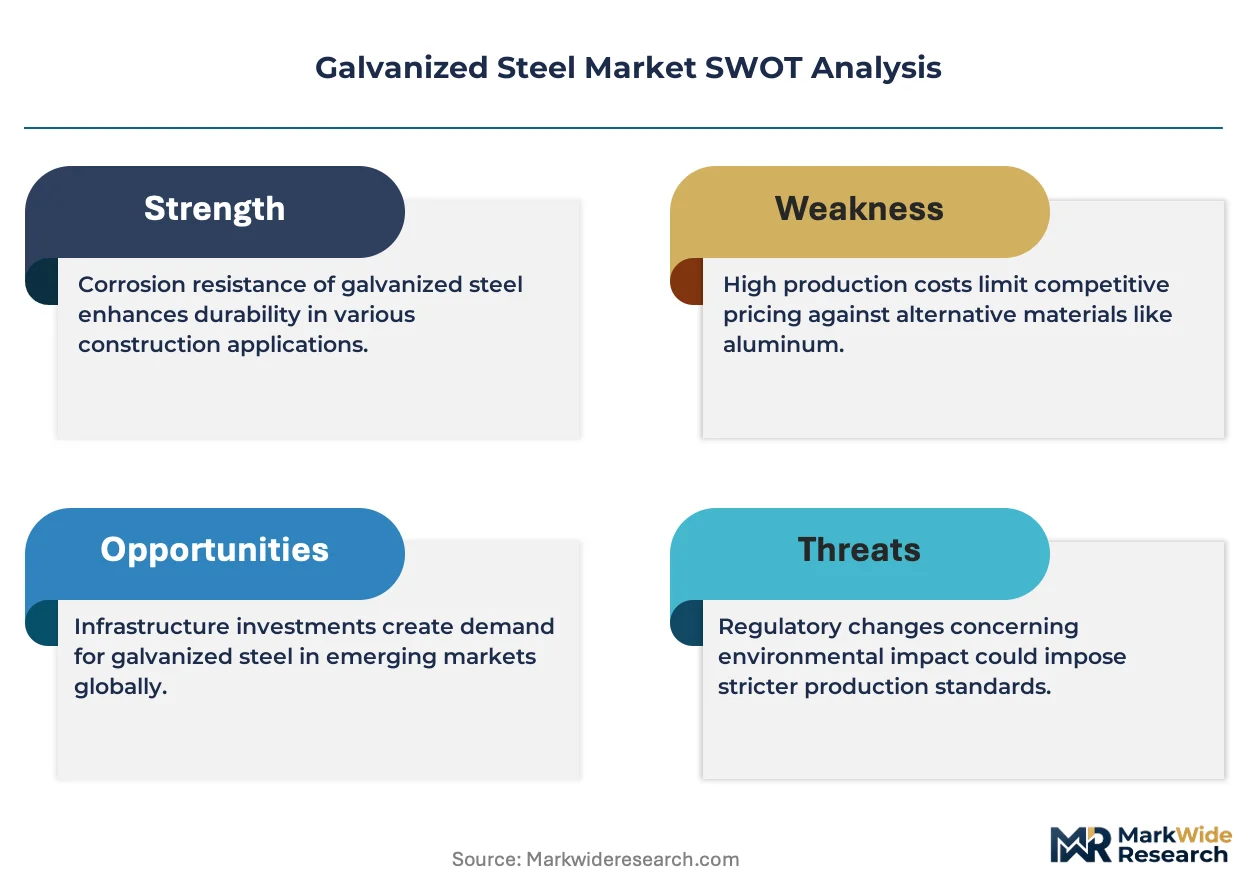
China's MEE enforces stricter zinc fume and wastewater discharge limits that raise compliance costs for smaller galvanizing shops and accelerate capacity migration toward integrated mills with environmental controls. India's BIS mandates IS 277 standards for general purpose galvanized sheets, while CEA building codes increasingly specify corrosion-resistant structural members for coastal and high-humidity zones. The EU's F-Gas Regulation indirectly shapes demand by pressuring HVAC manufacturers toward galvanized heat exchanger designs that eliminate refrigerant-intensive systems. Stakeholders must monitor how carbon border adjustment mechanisms and evolving zinc sourcing transparency requirements reshape cost structures and supplier qualification criteria across key demand centers.
Market Dynamics
China's MEE emissions mandates are compressing galvanizing capacity toward integrated steel mills with captive environmental controls, displacing fragmented job-shop operators unable to absorb compliance retrofit costs.
Growth Catalysts
- India's infrastructure buildout:CEA building codes now mandate corrosion-resistant structural members for coastal zones, pulling tonnage toward road, rail, and affordable housing projects.
- REACH-compliant coating formulations:EU regulatory pressure on hexavalent chromium alternatives is accelerating zinc-magnesium alloy adoption across automotive exterior panels.
- Hot-dip line automation:Advanced process control systems are reducing coating weight variance below 3%, enabling thinner zinc layers that preserve corrosion performance while lowering raw material intensity.
Market Restraints
- Zinc price volatility:Concentrated mining supply from Australia and Peru transmits commodity swings directly into galvanizing cost structures, compressing margins for non-integrated processors.
- Aluminum substitution in lightweighting:Automotive OEMs are specifying aluminum-intensive body-in-white architectures for battery electric vehicles, displacing galvanized steel in closure panels.
- EU F-Gas Regulation friction:HVAC manufacturers face refrigerant system redesign timelines that delay heat exchanger procurement cycles, temporarily freezing galvanized coil orders.
Strategic Opportunities
- India's secondary cities:Tier-2 and Tier-3 urban expansion outside Mumbai and Delhi remains underpenetrated for pre-engineered building systems using roll-formed galvanized sections.
- Zinc-aluminum-magnesium convergence:Coating technologies combining sacrificial zinc protection with aluminum barrier layers are opening marine and agricultural equipment applications previously served by stainless steel.
- Direct mill-to-fabricator channels:Integrated steelmakers are bypassing traditional distributor networks to supply coil directly to construction roll-formers, capturing margin and demand signals.
Industry Challenges
- Skilled furnace operator scarcity:Hot-dip galvanizing requires technicians capable of managing zinc bath chemistry and dross removal, with training pipelines failing to replace retiring workforce cohorts.
- CE marking certification timelines:European construction product regulation compliance now demands 12-18 month testing cycles for new coating formulations, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galvanized Steel Market |
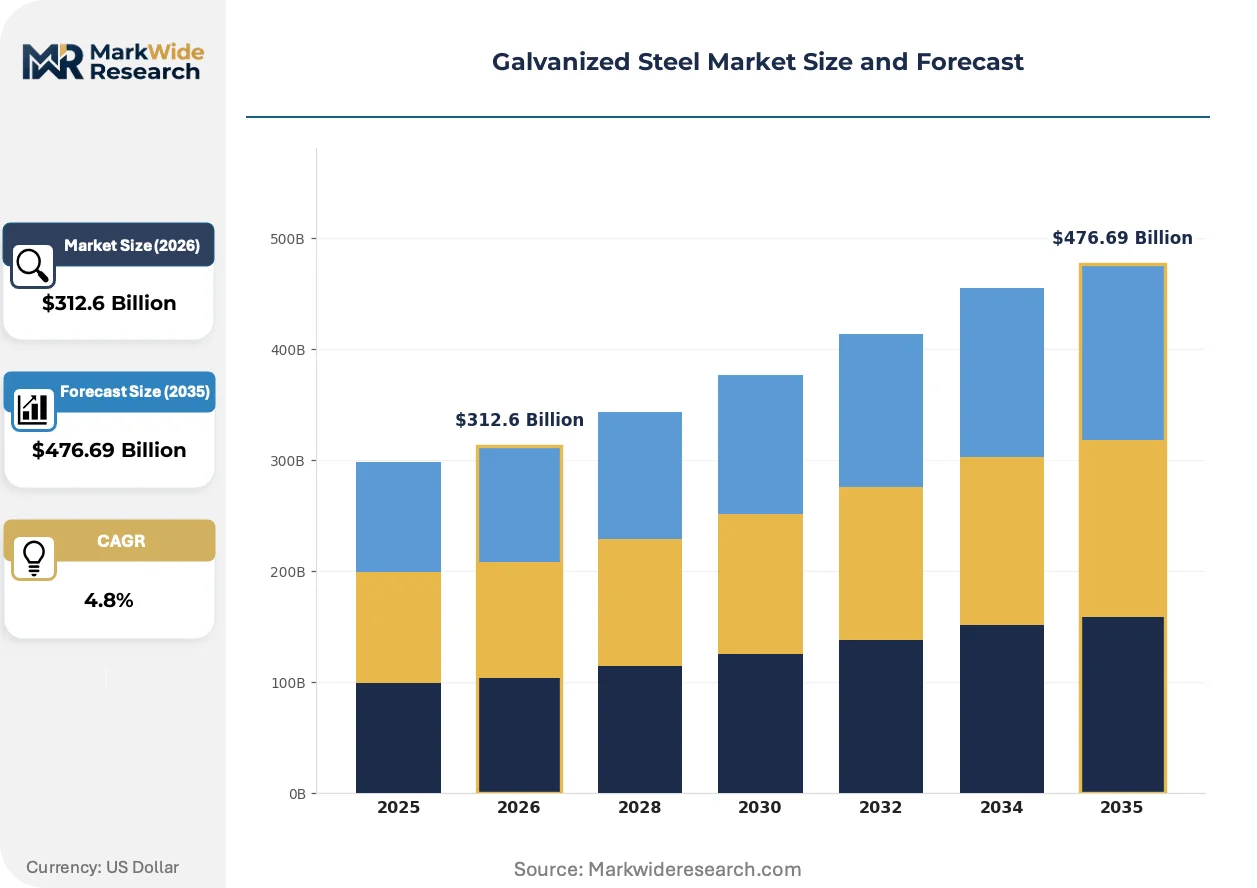
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $476.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Products, Long Products, Coated Products, Specialty Products Application: Construction, Automotive, Appliances, Furniture End User: Manufacturers, Contractors, Distributors, Retailers Distribution Channel: Direct Sales, Online Sales, Wholesale, Retail |
| Companies Covered | POSCO, Ansteel Group, ArcelorMittal, Shagang Group, HBIS Group, NIPPON STEEL CORPORATION, China Baowu Steel Group Corporation Limited, Jianlong Group, Tata Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galvanized Steel Market Emerging Trajectories
Coating chemistry advances and process digitization are compressing the performance gap between commodity galvanizing and premium corrosion-resistant alloys, reshaping how fabricators specify materials across construction and transportation end-uses.
Digital twin process control is integrating continuous galvanizing lines with real-time bath temperature, aluminum content, and air-knife pressure monitoring. Automotive stampers in Germany and Japan are adopting these systems to achieve coating uniformity specifications below 5 g/m² variance. The technology is integrating quality assurance directly into production flow, reducing offline inspection requirements and enabling just-in-time coil release.
China's dual carbon goals are forcing MEE to tighten zinc fume capture and wastewater discharge limits for galvanizing operations. Smaller job shops in Hebei and Shandong provinces face shutdown orders or forced consolidation into mill-adjacent facilities. Construction-grade coil supply is concentrating toward Baowu and Shagang Group integrated lines with captive environmental infrastructure.
Specification-driven procurement now dominates commercial construction in India's coastal states, where CEA mandates corrosion-resistant structural members for high-humidity zones. Fabricators in Gujarat and Tamil Nadu are shifting from lowest-bid commodity purchasing to certified-grade contracts with documented coating weight and adhesion test results. This behavior is most visible in pre-engineered building projects for logistics warehouses, where 20-year structural warranties require traceable mill certification.
Galvanized Steel Market Segmentation
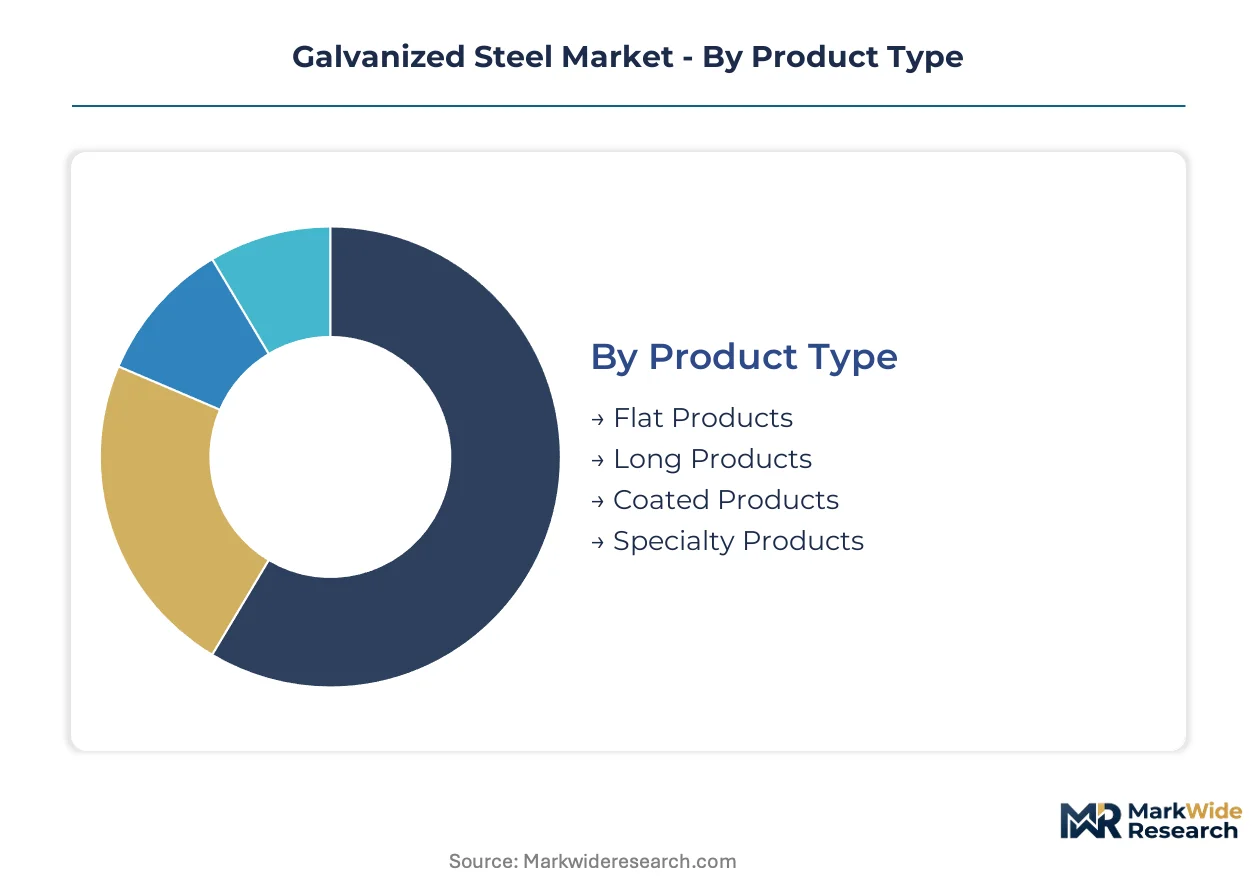
Galvanized steel procurement patterns diverge sharply across product geometries and end-use specifications. Construction roll-formers prioritize coil width consistency and surface quality, while automotive stampers demand bake-hardening grades with precise coating weight control.
Product Type:
Buyers in this category differentiate primarily by forming method and corrosion performance requirements.
- Flat Products:Continuously cast and hot-rolled substrates processed through hot-dip or electrogalvanizing lines achieve uniform zinc coatings from 40-600 g/m². Demand concentrates in India's pre-engineered building sector, where CEA coastal zone mandates pull tonnage toward certified corrosion-resistant grades with documented mill test reports.
- Specialty Products:Aluminum-zinc and zinc-aluminum-magnesium alloy coatings extend service life in marine and agricultural environments through combined barrier and sacrificial protection mechanisms. Japanese and South Korean fabricators specify these grades for livestock equipment and greenhouse structures exposed to high humidity and ammonia corrosion.
- Long Products:Wire rod, rebar, and structural sections receive batch or continuous galvanizing for infrastructure anchoring and fencing applications.
- Coated Products:Pre-painted galvanized coils combine zinc substrate protection with polymer topcoats for architectural cladding and appliance panels.
Flat Products leads volumes today; Specialty Products is gaining share fastest.
Application:
End-use specifications in this category separate commodity structural applications from premium surface-critical grades.
- Construction:Roofing, walling, and structural framing absorb the largest tonnage share, with roll-formed purlins and girts serving industrial warehouses and affordable housing projects. India's tier-2 and tier-3 urban expansion outside Mumbai and Delhi drives demand for pre-engineered building systems using standardized galvanized sections.
- Automotive:Exposed body panels require complex forming grades with bake-hardening capability and weldability specifications that command premium pricing over construction grades. European REACH compliance pressure on hexavalent chromium alternatives accelerates zinc-magnesium alloy adoption for hoods, doors, and fenders.
- Appliances:Refrigerator cabinets, washing machine drums, and HVAC heat exchangers specify galvanized substrates for corrosion resistance and paint adhesion.
- Furniture:Office systems, shelving, and outdoor fixtures use lighter-gauge galvanized tubing and sheet for cost-effective durability.
Construction commands the highest absolute tonnage; Automotive captures the steepest margin expansion trajectory.
End User:
Purchasing scale and technical specification authority distinguish stakeholders in this category.
- Manufacturers:Automotive OEMs and appliance producers negotiate direct mill contracts with coating weight variance specifications below 5 g/m² and traceable batch certification. German and Japanese stampers integrate digital twin process controls into supplier qualification requirements.
- Contractors:Construction fabricators and erectors source through distributor networks or direct mill channels depending on project scale and certification needs.
- Distributors:Steel service centers inventory standard grades for spot purchasing by smaller fabricators and maintenance contractors.
- Retailers:Hardware and building material chains stock light-gauge consumer products for DIY and small repair applications.
Manufacturers dominate premium grade procurement; Contractors represent the largest volume aggregation point.
Distribution Channel:
Channel selection in this category reflects order size, technical support requirements, and inventory carrying cost tolerance.
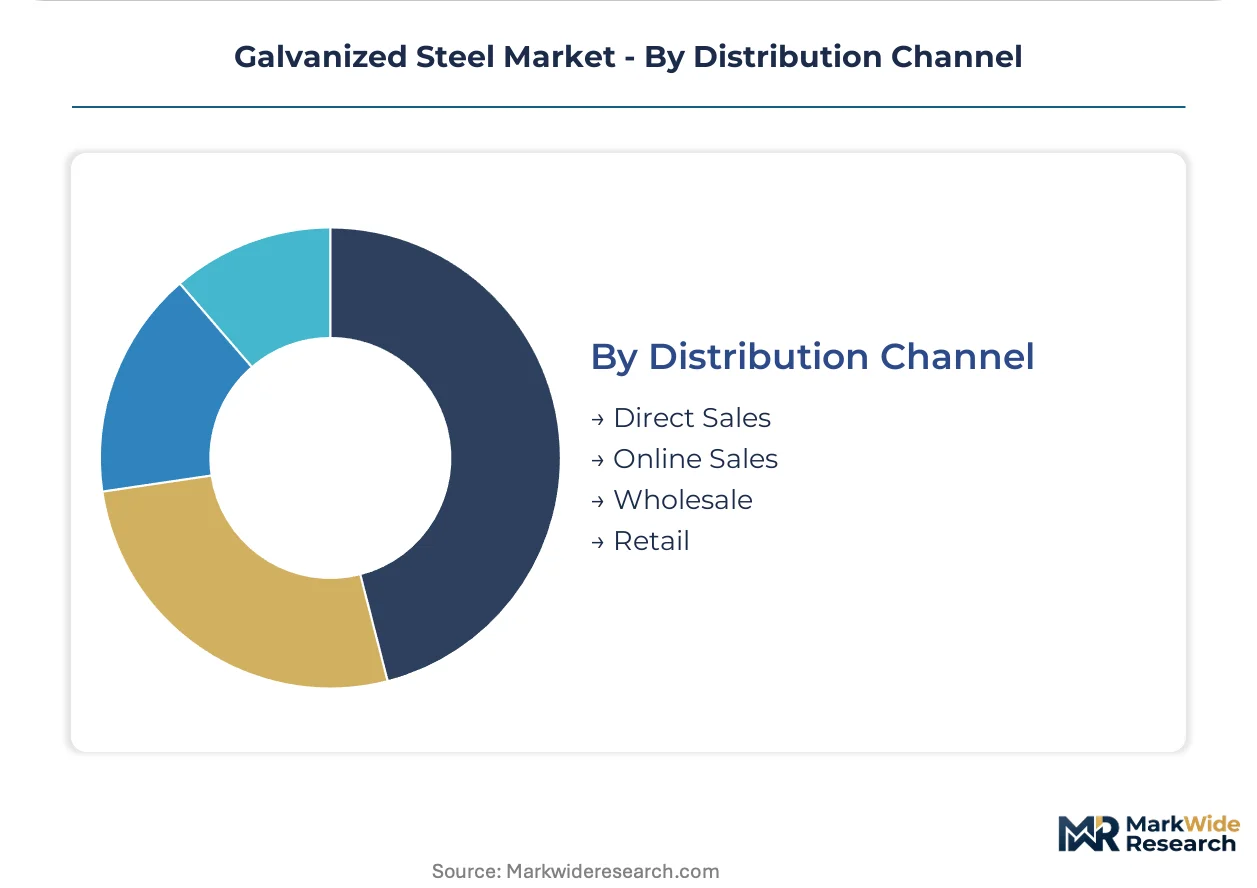
- Direct Sales:Integrated steelmakers bypass traditional distributors to supply coil directly to construction roll-formers and automotive tier-1 stampers, capturing margin and capturing real-time demand signals for production scheduling.
- Wholesale:Steel service centers and regional distributors maintain inventoried coil and slit strip for spot requirements and just-in-time delivery to fabricators.
- Online Sales:Digital platforms facilitate price discovery and small-lot procurement for maintenance, repair, and operations purchasing by smaller contractors.
- Retail:Building material chains and hardware stores stock pre-cut sheets and consumer-format products for residential and light commercial applications.
Direct Sales is expanding most quickly among large-volume accounts; Wholesale retains the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese producers are migrating capacity toward integrated mills with captive environmental controls as MEE enforcement raises compliance costs for smaller operators, creating arbitrage opportunities for mills with in-house pollution management infrastructure.
China
Hebei and Shandong provinces host the dominant hot-dip galvanizing clusters serving construction and automotive stampers. MEE's tightening zinc fume capture mandates are forcing job-shop consolidation into mill-adjacent facilities. Baowu and Shagang Group integrated lines in Shanghai and Jiangsu are absorbing displaced capacity.
India
Gujarat and Tamil Nadu fabricators are shifting from commodity purchasing to certified-grade contracts for pre-engineered building systems. CEA mandates corrosion-resistant structural members for coastal zones. Secondary cities outside Mumbai and Delhi drive demand for standardized galvanized sections in logistics warehouses.
Japan
Automotive exterior panel specifications dominate procurement from Kansai and Chubu industrial corridors. METI-backed R&D networks accelerate zinc-magnesium coating adoption for hood and door applications. Nagoya-area stampers integrate digital twin process controls into supplier qualification requirements.
Germany
Ruhr Valley and Bavarian steel service centers supply coil to construction roll-formers and automotive tier-1 suppliers. REACH compliance pressure on hexavalent chromium alternatives pulls specification toward advanced alloy coatings. KBA vehicle certification timelines shape coating formulation testing cycles.
South Korea
Pohang and Gwangyang industrial complexes anchor continuous galvanizing capacity for export-oriented automotive and shipbuilding accounts. MFDS and METI regulatory alignment enables seamless coil qualification for Japanese and European OEMs. Busan-Ulsan fabricators specialize in marine-grade alloy coatings for offshore equipment.
Galvanized Steel Market Vendor Landscape
Chinese integrated steelmakers anchor one tier; Japanese and South Korean specialists hold premium-grade positions through proprietary process controls. Market structure concentrates around three strategic archetypes: state-backed integrated mills with environmental compliance infrastructure, technology-focused alloy developers serving automotive specifications, and regional construction-grade suppliers competing on logistics proximity. Dominant competitive moves include direct mill-to-fabricator channel bypass and coating chemistry licensing for extended corrosion resistance.
Among East Asian producers, POSCO and NIPPON STEEL CORPORATION exemplify technology-driven positioning through proprietary continuous galvanizing expertise. ArcelorMittal occupies a position bridging European R&D networks with construction-grade scale. Ansteel Group and HBIS Group represent state-backed integrated capacity with captive environmental infrastructure. These anchors illustrate how competitive advantage separates process control precision from commodity volume plays.
| Leading Market Players |
|---|
| POSCO |
| Ansteel Group |
| ArcelorMittal |
| Shagang Group |
| HBIS Group |
| NIPPON STEEL CORPORATION |
| China Baowu Steel Group Corporation Limited |
| Jianlong Group |
| Tata Steel |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between CEA-mandated coastal corrosion-resistant structural members and commodity construction grades splits pricing power and procurement channels across India's galvanized steel market. Premium coil with documented mill test reports commands channel margins through direct mill-to-fabricator relationships, while uncertified commodity tonnage competes on logistics proximity and distributor credit terms.
Pricing Analysis
Distributor margins compress most severely in construction-grade coil where spot purchasing through steel service centers competes with direct mill channels. Three-tier pricing structure across premium automotive exterior panel grades, certified construction specifications, and uncertified commodity sheet reflects coating weight variance tolerances and traceability documentation. Pricing pressure stems from zinc price volatility transmitted through concentrated Australian and Peruvian mining supply, squeezing non-integrated galvanizing operations. Automotive OEMs exhibit lowest price sensitivity due to bake-hardening specification lock-in, while tier-3 construction fabricators in India's secondary cities prioritize landed cost above certification.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive stamper demand through mill-direct coil supply with sub-5 g/m² coating weight variance specifications. Raw material flows draw from zinc concentrate imports through Australia and Peru, hot-rolled substrate from Chinese integrated mills, and alloying aluminum from domestic Indian smelters. Supply chain risk centers on MEE-mandated environmental compliance shutdowns in Hebei and Shandong provinces displacing job-shop galvanizing capacity. Distribution runs through integrated steelmaker direct sales for large accounts, regional steel service centers for construction spot demand, and digital platforms for MRO procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's CEA coastal corrosion mandates and China's MEE emissions enforcement continuously requalify supplier rosters and reshape capacity geography.
For Market Incumbents: To counter aluminum substitution in battery electric vehicle body-in-white architectures, anchor automotive positioning through zinc-magnesium coating R&D partnerships with European REACH-compliant formulators. Deepen backward integration into captive zinc refining to buffer commodity price volatility, while consolidating Hebei and Shandong job-shop capacity into mill-adjacent facilities with MEE-compliant fume capture infrastructure. For New Entrants and Emerging Players: Launch via digital-first procurement platforms targeting India's tier-2 and tier-3 construction fabricators underserved by traditional distributor networks. White-space concentration sits in pre-engineered building systems for logistics warehouses in Gujarat and Tamil Nadu coastal zones where CEA mandates create certified-grade demand without entrenched supplier relationships. Prioritize direct mill partnerships over inventory-heavy distribution models. For Investors and Strategic Acquirers: Asymmetric upside sits with zinc-aluminum-magnesium alloy coating specialists serving marine and agricultural equipment applications previously captured by stainless steel. Long-term viability hinges on environmental compliance infrastructure rather than pure scale, favoring integrated mills with captive pollution controls. Watch MEE enforcement intensity in Shandong province as inflection signal for Chinese capacity consolidation velocity and export availability.| Strategic Initiative | Industry Significance |
|---|---|
| Environmental Compliance Infrastructure Investment | MEE-mandated fume capture systems in Hebei and Shandong determine Chinese capacity survival and export availability. |
| Zinc-Aluminum-Magnesium Coating Development | Alloy formulations extending service life in marine environments displace stainless steel in Japanese and South Korean fabricator specifications. |
| Direct Mill-to-Fabricator Channel Expansion | Bypassing steel service centers captures margin and real-time demand signals from Indian construction roll-formers. |
| Digital Twin Process Control Integration | Real-time bath monitoring enables sub-5 g/m² coating variance required by German and Japanese automotive stampers. |
| Coastal Certification Grade Capacity Addition | CEA-mandated corrosion-resistant structural members for Gujarat and Tamil Nadu create qualified supply scarcity. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hot-dip galvanizing line operators, automotive tier-1 procurement managers, construction roll-former technical directors, and steel service center inventory planners with secondary validation through customs trade data, BIS certification registries, MEE emissions disclosure filings, and SEC 10-K filings of listed steelmakers. Bottom-up coil production estimates triangulated against top-down construction and automotive consumption forecasts.
Segment-weighting applied product type splits across flat, specialty, long, and coated products, application segmentation across construction, automotive, appliance, and furniture end-uses, and end-user categories spanning manufacturers, contractors, distributors, and retailers. CAGRs derived from regression analysis of historical capacity utilization, zinc price elasticity coefficients, and regulatory enforcement intensity proxies across the projection horizon. Forecast inputs incorporated MEE compliance timeline assumptions, CEA building code adoption curves, and REACH substitution rates for hexavalent chromium alternatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated aluminum substitution in electric vehicle architectures or disruptive zinc supply disruptions from Peruvian mining jurisdictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Beryllium Copper for Industrial Equipment Market
Metals
Copper and Copper Alloy Market
Metals
Barium Market
Metals
Iron Ore Market
Metals
Ruthenium Market
Metals
Osmium Market
Metals
Ferrosilicon Market
Metals
Heat-Treated Steel Plates Market
Metals
Nickel Foam Market
Metals
Global Stretch Spring Wire Market
Metals
North America Aluminum Market
Metals
Clutch Spring Wires Market
Metals
Global Brass Rods Market
Metals
Metal Alloys Market
Metals
Platinum Market
Metals
Europe Aluminium Wire Rod Market